
 Global Adaptive Robot Market | 2026-2036
Global Adaptive Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adaptive Robot Market Foresight
Direct-to-factory distribution is reshaping how adaptive robot vendors reach electronics and pharmaceutical producers. ABB leverages its installed base of industrial automation systems to anchor recurring upgrade cycles across European automotive suppliers. FANUC competes through captive servo-motor production that insulates margins from component volatility. NVIDIA positions its Isaac platform as the computational backbone for third-party robot developers seeking simulation-to-reality pipelines.
Adaptive robots integrate machine learning, sensor fusion, and real-time control architectures to modify trajectories and grasp strategies without explicit reprogramming, typically operating with sub-millimeter repeatability in unstructured environments. Their primary commercial purpose is to bridge the gap between rigid automation and manual labor in batch-size-one manufacturing and hazardous settings. Collaborative robots now capture the deepest margin pools as pharmaceutical cleanrooms and aerospace assembly bays prioritize force-limited operation alongside human technicians. Reinforcement learning represents the fastest-advancing technology segment, though computer vision still dominates installed bases due to mature camera-to-actuator latency standards.
The EU AI Act and CE marking under the Machinery Directive constrain market access for systems lacking documented risk-assessment protocols, while OSHA in the United States enforces speed and separation monitoring for collaborative deployments. ISO 10218 and ISO/TS 15066 provide the harmonized safety benchmarks that buyers in Japan and Germany require before procurement approval. Stakeholders must track how regulatory divergence between Brussels and Washington on algorithmic transparency reshapes certification costs and time-to-market for cross-border robot platforms.
Market Dynamics
Reinforcement learning architectures are compressing reprogramming cycles from weeks to hours, forcing vendors to restructure software revenue models around runtime licensing rather than perpetual hardware sales.
Growth Catalysts
- EU AI Act conformity pathways:Documented risk-assessment protocols under Brussels algorithmic transparency rules create procurement preference for certified vendors in German automotive supply chains.
- Pharmaceutical cleanroom deployment:Force-limited collaborative robots capture margin pools as batch-size-one biologics manufacturing displaces rigid fill-finish automation.
- South Korean smart factory mandates:Government-backed K-SMART initiatives accelerate sensor-fusion mobile robot procurement through tax depreciation incentives.
Market Restraints
- Rare-earth magnet supply concentration:Neodymium-dysprosium price volatility from Chinese export quota regimes compresses servo-motor margins for non-integrated assemblers.
- ISO/TS 15066 certification timelines:Force-torque validation protocols add months to collaborative robot time-to-market in Japan and Germany.
- Legacy SCADA integration friction:Proprietary fieldbus architectures in incumbent European automotive plants delay adaptive robot commissioning.
Strategic Opportunities
- Indian electronics assembly underpenetration:PLI scheme subsidies for mobile device manufacturing create first-mover advantage for adaptive gripper vendors establishing local service presence.
- Simulation-to-reality pipelines:NVIDIA Isaac platform adoption by third-party developers collapses physical prototyping costs for unstructured bin-picking applications.
- OSHA speed-and-separation monitoring waivers:United States collaborative deployment permits above-threshold speeds where force-limiting redundancy meets documented risk thresholds.
Industry Challenges
- Reinforcement learning engineer scarcity:Robot behavior optimization requires hybrid robotics-ML talent concentrated in Shenzhen, Munich, and Boston metro clusters.
- CE marking Machinery Directive convergence:Divergent Brussels-Washington algorithmic transparency documentation requirements inflate cross-border platform certification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adaptive Robot Market |
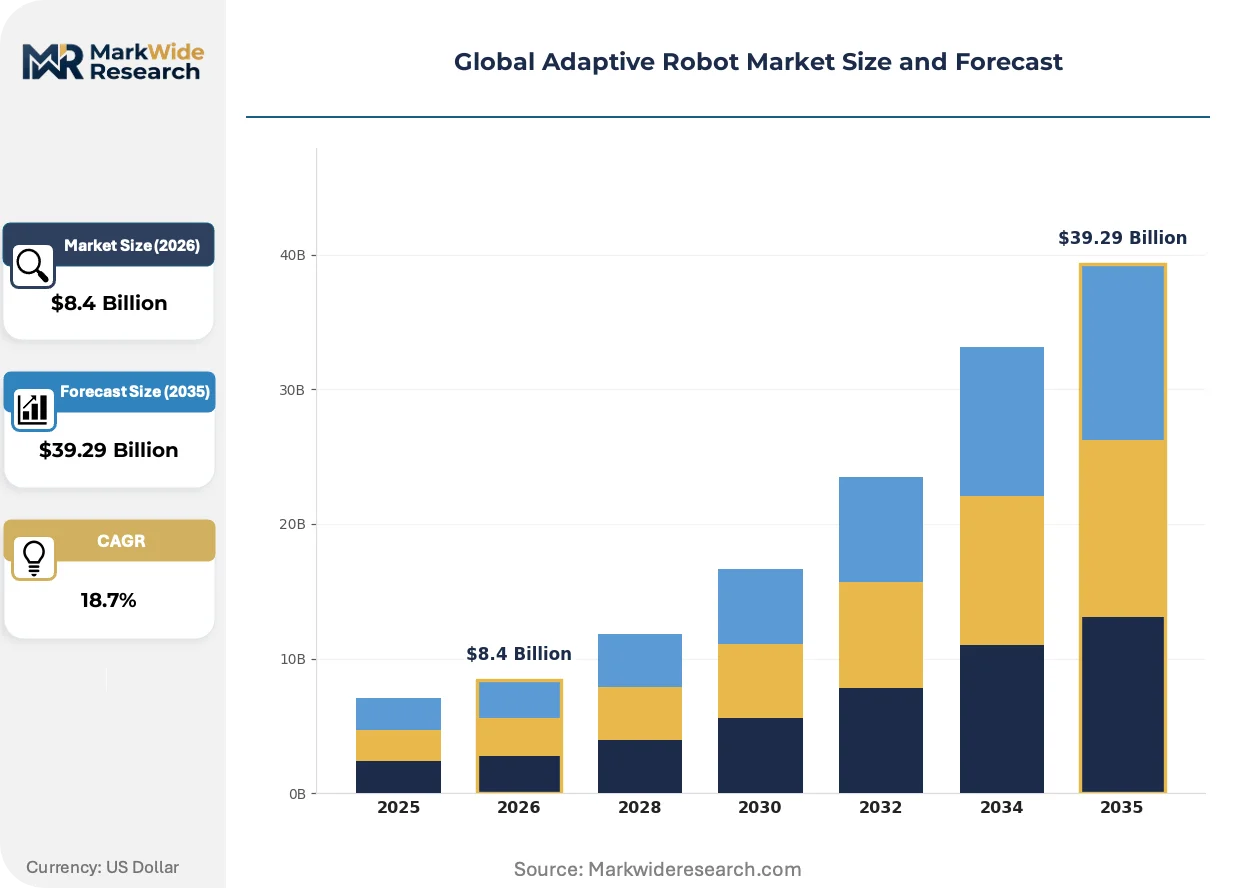
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Robot Type: Collaborative Robots, Mobile Robots, Humanoid Robots, Autonomous Robots Technology: Machine Learning, Computer Vision, Sensor Fusion, Natural Language Processing, Reinforcement Learning Application: Material Handling, Quality Inspection, Assembly Automation, Hazardous Environment Operation End User: Electronics Manufacturing, Pharmaceutical Production, Aerospace Engineering, Food Processing |
| Companies Covered | Boston Dynamics, ABB, KUKA, FANUC, Yaskawa Electric, Universal Robots, Intuitive Surgical, Cyberdyne, NVIDIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adaptive Robot Market Shifts & Advancements
Digital twin technology is collapsing the physical-digital boundary in robot development, compressing validation cycles while regulatory pressure on autonomous decision-making intensifies certification complexity.
Simulation environments for adaptive robots are virtualizing hardware-in-the-loop testing that previously required physical cell construction. Pharmaceutical and aerospace buyers now demand virtual commissioning before purchase authorization. This shift is virtualizing capital allocation from production floors to cloud compute infrastructure, restructuring vendor R&D spend toward software subscriptions.
The EU AI Act risk-classification framework for autonomous industrial systems tightens conformity requirements for high-risk robot categories entering European supply chains. Machinery Directive harmonization with algorithmic accountability rules extends documentation burdens to sensor-fusion mobile platforms. German automotive suppliers and French pharmaceutical contract manufacturers now require third-party algorithmic audits before procurement approval.
After-sales service unbundling from hardware contracts accelerates as buyers demand outcome-based performance guarantees. System integrators in South Korea and Japan now separate maintenance, software updates, and retraining services from initial capital expenditure. Electronics manufacturers in Taiwan and Germany increasingly procure adaptive capabilities through runtime licensing rather than perpetual ownership.
Global Adaptive Robot Market Segmentation
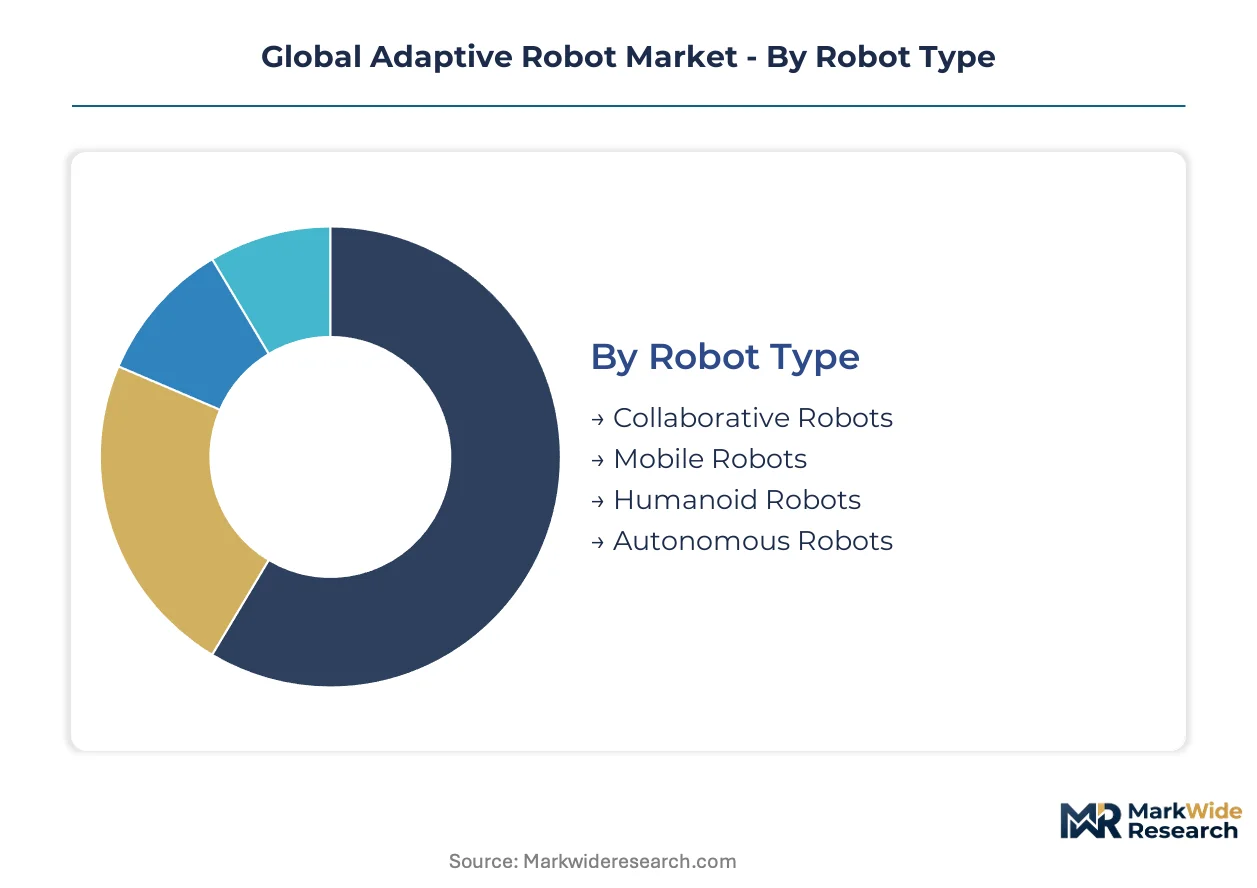
Segmentation reveals how adaptive robot procurement cycles vary dramatically by technical maturity and regulatory exposure. Vendors must align R&D cadence and service models to divergent replacement timelines across robot types, sensor architectures, and end-use environments.
Robot Type:
Replacement cycles compress from seven-year industrial averages to sub-36-month refresh rates for software-heavy platforms, while hardware-centric categories retain longer amortization schedules.
- Collaborative Robots:Force-limited articulated arms with torque-sensing joints enable human-robot workspace sharing without physical guarding. Pharmaceutical cleanrooms in Germany and South Korea now mandate ISO/TS 15066-certified units for batch-size-one biologics filling, compressing vendor validation timelines.
- Mobile Robots:Autonomous mobile platforms fuse LiDAR, vision, and inertial measurement for dynamic path planning in unstructured logistics environments. South Korean smart factory initiatives under K-SMART accelerate fleet deployment through accelerated tax depreciation schedules.
- Humanoid Robots:Bipedal platforms with multi-degree-of-freedom limbs target research institutions and pilot manufacturing trials.
- Autonomous Robots:Self-directed systems with minimal human oversight operate in remote inspection and hazardous material handling.
Collaborative robots anchor the volume base while mobile robots gain share at the steepest rate.
Technology:
Development cost tiers separate mature perception stacks from emerging learning architectures requiring specialized talent pools.
- Machine Learning:Supervised learning pipelines for defect classification and predictive maintenance dominate installed bases with established training data protocols. Electronics manufacturers in Taiwan deploy these systems for PCB solder joint inspection with minimal retraining overhead.
- Computer Vision:Camera-to-actuator latency standards under ISO 10218 enable sub-50-millisecond response times for pick-and-place operations. German automotive suppliers require vision-guided adaptive grippers for mixed-model assembly lines.
- Sensor Fusion:Multi-modal integration of tactile, visual, and proximity sensing enables robust operation in variable lighting.
- Natural Language Processing:Voice-command interfaces reduce programming burden for non-technical operators in small-batch settings.
- Reinforcement Learning:Trial-and-error optimization algorithms compress behavior programming from weeks to hours for unstructured grasp tasks.
Computer vision commands the largest installed footprint while reinforcement learning attracts the most venture-stage engineering investment.
Application:
Margin concentration follows regulatory intensity and failure-cost exposure across manufacturing stages.
- Material Handling:Adaptive grippers with force-torque feedback manage variable-weight payloads in electronics and pharmaceutical distribution centers. OSHA speed-and-separation monitoring waivers in the United States permit above-threshold collaborative speeds where redundant force-limiting systems meet documented risk thresholds.
- Quality Inspection:Machine learning-augmented vision systems detect micron-level defects in semiconductor wafer and aerospace component manufacturing. Japanese METI-funded smart factory programs prioritize inspection automation for export-competitive precision manufacturing.
- Assembly Automation:Force-controlled insertion and fastening operations replace rigid automation in high-mix production.
- Hazardous Environment Operation:Sealed, explosion-protected platforms handle chemical processing and nuclear decommissioning tasks.
Material handling generates the broadest deployment base while quality inspection commands the highest per-unit pricing.
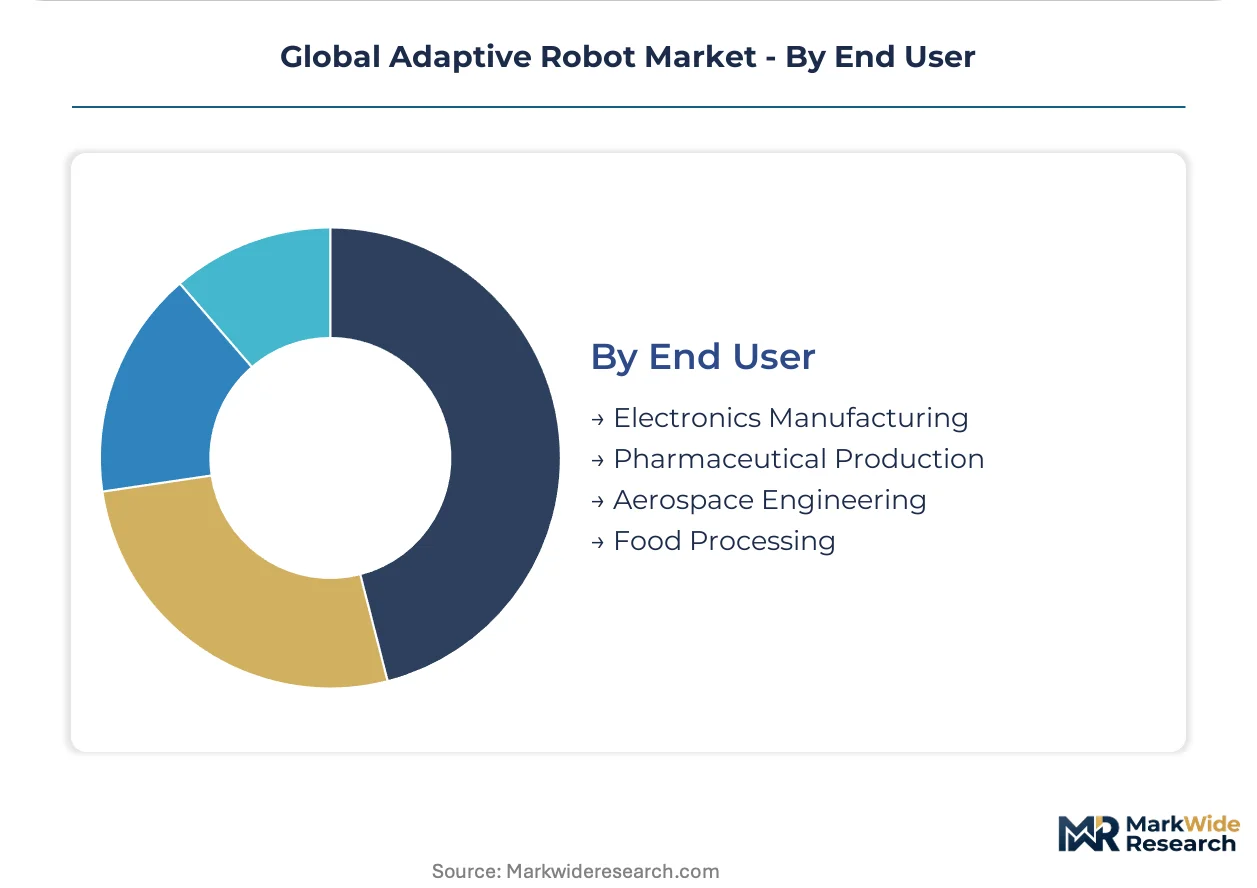
End User:
Procurement sophistication and integration complexity create distinct vendor qualification barriers across verticals.
- Electronics Manufacturing:High-mix, high-speed assembly demands sub-millimeter repeatability with rapid product changeover capabilities. Indian PLI scheme subsidies for mobile device manufacturing create first-mover openings for adaptive gripper vendors establishing local service presence.
- Pharmaceutical Production:FDA and EMA validation requirements for GMP environments force extended qualification protocols for any system touching drug product. French contract manufacturers now require third-party algorithmic audits under EU AI Act conformity pathways.
- Aerospace Engineering:Low-volume, high-precision drilling and fastening operations tolerate longer payback periods for adaptive automation.
- Food Processing:Washdown-rated collaborative systems address labor availability in protein packaging and ready-meal assembly.
Electronics manufacturing provides the deepest volume pool while pharmaceutical production offers the most defensible margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput and the Rhine-Alpine rail corridor position Germany as the logistics backbone for European adaptive robot distribution, while South Korea's K-SMART industrial cloud infrastructure underwrites East Asian procurement velocity.
United States
OSHA speed-and-separation monitoring waivers permit collaborative deployments above standard velocity thresholds where redundant force-limiting systems meet documented risk protocols. FDA validation requirements for pharmaceutical manufacturing systems extend procurement cycles for cleanroom-rated platforms. The Boston metro cluster concentrates reinforcement learning engineering talent for unstructured grasp optimization.
Germany
EU AI Act conformity pathways and Machinery Directive harmonization create procurement preference for certified vendors in automotive supply chains. CE marking under algorithmic transparency rules extends documentation burdens to sensor-fusion mobile platforms. Stuttgart and Munich anchor electronics manufacturing expansion with collaborative robot deployment on mixed-model assembly lines.
Japan
METI-funded smart factory programs prioritize inspection automation for export-competitive precision manufacturing. ISO 10218 and ISO/TS 15066 certification requirements add months to collaborative robot validation timelines before procurement approval. The Nagoya industrial corridor concentrates force-torque sensing joint production for pharmaceutical cleanroom applications.
South Korea
K-SMART government initiatives accelerate sensor-fusion mobile robot procurement through accelerated tax depreciation schedules. MFDS pharmaceutical manufacturing standards drive validation protocols for biologics filling automation. The Busan-Ulsan manufacturing belt concentrates fleet deployment for electronics assembly under government-backed smart factory mandates.
India
PLI scheme subsidies for mobile device manufacturing create first-mover openings for adaptive gripper vendors establishing local service presence. BIS industrial equipment standards shape certification requirements for imported automation platforms. The Karnataka electronics manufacturing cluster near Bangalore drives demand for sub-millimeter repeatability in high-mix assembly environments.
Global Adaptive Robot Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in servo motors, force sensors, and simulation engines. The vendor base stratifies between full-stack automation houses and modular subsystem suppliers. Three archetypes dominate: industrial conglomerates with captive component production, pure-play collaborative robot specialists, and computational platform providers licensing software stacks. Consolidation pressure intensifies through strategic partnerships bridging hardware and AI layers, while geographic expansion into underpenetrated electronics assembly markets accelerates.
Within the industrial conglomerate tier, ABB and FANUC exemplify vertically integrated positioning through in-house production of critical motion control components. NVIDIA occupies a distinct platform-provider position, anchoring the simulation-to-reality pipeline segment for third-party robot developers. These three represent divergent competitive vectors: captive manufacturing, component autonomy, and computational infrastructure licensing.
| Leading Market Players |
|---|
| Boston Dynamics |
| ABB |
| KUKA |
| FANUC |
| Yaskawa Electric |
| Universal Robots |
| Intuitive Surgical |
| Cyberdyne |
| NVIDIA |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine rail corridor's freight cost volatility transmits directly through European adaptive robot distribution networks, amplifying price differentiation between CE-certified premium tiers and standard economy units while compressing margins for non-integrated assemblers exposed to rare-earth magnet supply shocks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates adaptive robot procurement, with ISO/TS 15066 certification and force-torque sensing precision anchoring premium positioning. Price differentiation rests on after-sales service bundling and runtime software licensing versus perpetual hardware ownership. Cost compression in the economy tier is intensifying because Chinese export quota regimes on neodymium-dysprosium feedstocks squeeze servo-motor margins. Electronics manufacturers in Taiwan exhibit highest price sensitivity due to high-mix, high-volume procurement patterns, while pharmaceutical cleanroom operators in Germany tolerate premium pricing for validated GMP compliance.
Supply Chain Analysis
Upstream rare-earth magnet production draws from China, with secondary processing concentration in Japan and Germany for high-grade servo-motor assemblies. Critical component dependencies include neodymium-dysprosium permanent magnets, high-resolution force-torque sensors, and GPU clusters for simulation-to-reality training pipelines. Single-source vulnerability in Chinese rare-earth export licensing creates procurement risk for European and North American robot assemblers lacking backward integration. Distribution runs through direct-to-factory channels for electronics and pharmaceutical producers, with system integrators in South Korea and Japan unbundling after-sales service from hardware contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Adaptive Robot Market is entering a cyclical recovery phase as electronics manufacturing capital expenditure rebounds from inventory destocking, with German automotive supplier automation budgets expanding ahead of EU AI Act enforcement deadlines.
For Market Incumbents: Build switching-cost moats through runtime software licensing architectures that embed proprietary simulation-to-reality training data. Deepen backward integration into force-torque sensor production to insulate margins from component volatility. Anchor recurring revenue streams via outcome-based performance guarantees for pharmaceutical cleanroom deployments, defending against pure-play collaborative robot specialists eroding hardware margins.
For New Entrants and Emerging Players: Build out local service infrastructure in Indian electronics manufacturing clusters near Bangalore, where PLI scheme subsidies accelerate mobile device assembly automation procurement. Target adaptive gripper applications for high-mix PCB assembly with sub-millimeter repeatability requirements. Pursue partnership-based go-to-market models with established system integrators possessing existing FDA and EMA validation relationships.
For Investors and Strategic Acquirers: Simulation-engine specialists with pharmaceutical industry validation credentials represent the most attractive acquisition target archetype. Long-term viability over the next decade hinges on software subscription revenue exceeding hardware sales in vendor income statements. Watch for inflection when NVIDIA Isaac platform adoption rates among third-party developers exceed captive in-house simulation development at major industrial conglomerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Runtime Licensing Architecture Migration | Shifts revenue from hardware sales to recurring software subscriptions across pharmaceutical and electronics deployments. |
| Backward Integration into Force-Torque Sensors | Insulates servo-motor margins from Chinese rare-earth export quota volatility. |
| EU AI Act Conformity Certification | Creates procurement preference barrier for uncertified vendors in German automotive supply chains. |
| Simulation-to-Reality Pipeline Partnership | Collapses physical prototyping costs for unstructured bin-picking applications via NVIDIA Isaac adoption. |
| Indian Electronics Assembly Service Expansion | Captures PLI scheme-driven demand for adaptive grippers in high-mix mobile device manufacturing. |
Research Methodology
A standing panel of plant automation engineers, pharmaceutical manufacturing directors, automotive supplier procurement leads, and collaborative robot system integrators provided ongoing calibration across the study period. Primary interview findings were cross-validated against secondary sources including EU AI Act regulatory filings, FDA medical device and pharmaceutical manufacturing guidance documents, METI smart factory program disclosures, and K-SMART initiative procurement records. Bottom-up unit deployment estimates from end-user interviews were triangulated against top-down vendor shipment data.
Scenario-bracketing around regulatory enforcement intensity, rare-earth supply disruption probability, and reinforcement learning talent availability shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include robot type, technology stack, application environment, and end-user vertical with regional regulatory cluster overlays. CAGRs were derived from installed base growth rates, replacement cycle compression, and average selling price trajectories informed by runtime licensing adoption curves and pharmaceutical validation timeline benchmarks.
Stress conditions across neodymium-dysprosium price volatility bands, EU AI Act documentation requirement stringency, and OSHA collaborative deployment waiver availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding K-SMART subsidy continuity, ISO/TS 15066 harmonization timelines, and electronics manufacturing capital expenditure recovery trajectories. Cross-checking against IEA industrial automation investment surveys and national robotics association deployment statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Global Medical Robotic Systems Market
Robotics and Automation
Telepresence Robotics Market
Robotics and Automation
Laboratory Robotics Market
Robotics and Automation
Automotive Robotic Painting Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Asia-Pacific Data Center Robotics Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Global Delivery Robots Market
Robotics and Automation
Assistive Technology Market
Robotics and Automation
North America Robotics and Automation Actuators Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Global Soft Robotics Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Claytronics Market