
 Claytronics Market | 2026-2036
Claytronics Market Size, Share, and Industry Trends Forecast 2026-2036
Claytronics Market Analysis
A shortage of mechatronics engineers with nanoscale fabrication expertise is redrawing competitive boundaries in claytronics development. Intel Corp leverages its semiconductor process knowledge to anchor advanced catom manufacturing capabilities. Carnegie Mellon University sustains foundational research momentum through its legacy claytronics program and graduate pipeline. Samsung Advanced Institute of Technology competes aggressively in Asia-Pacific programmable matter patents.
Claytronics refers to programmable matter systems composed of sub-millimeter robotic units called catoms that communicate locally and self-assemble into three-dimensional physical forms under software control. These systems operate through electrostatic latching, electromagnetic coupling, or mechanical interlocking at scales between ten and one thousand micrometers, enabling real-time shape transformation for telepresence, adaptive interfaces, and dynamic physical modeling. Nano-robots and programmable matter segments attract the deepest R&D investment due to their centrality in defense and medical visualization roadmaps. AI Integration and Machine Learning technology layers command premium positioning as they determine catom swarm coordination efficiency and real-time morphing fidelity.
The US Army Research Laboratory operates under Department of Defense nano-technology directives that fast-track programmable matter for battlefield simulation and adaptive camouflage. REACH in Europe and corresponding EPA nano-material reporting rules in the United States impose substance characterization burdens that filter out undercapitalized entrants. Stakeholders must monitor how export control expansions around dual-use programmable matter technologies reshape cross-border collaboration models and intellectual property licensing terms.
Market Dynamics
The Claytronics Market is being fundamentally restructured by the scarcity of mechatronics engineers capable of nanoscale fabrication, a constraint that is concentrating competitive advantage among organizations with established semiconductor process expertise and graduate research pipelines.
Growth Catalysts
- US National Nanotechnology Initiative:Federal funding directives are accelerating FDA certification pathways for claytronic surgical simulators and prosthetic interfaces, compressing time-to-market for programmable matter medical devices.
- Defense visualization roadmaps:Department of Defense nano-technology directives are fast-tracking catom swarm development for battlefield simulation and adaptive camouflage applications.
- Electrostatic latching advances:Improved micrometer-scale adhesion mechanisms are enabling real-time shape transformation fidelity required for telepresence and dynamic physical modeling.
Market Restraints
- Sub-millimeter fabrication costs:Precision manufacturing of catoms at ten to one thousand micrometer scales requires capital-intensive cleanroom infrastructure that filters out undercapitalized entrants.
- REACH substance characterization:European nano-material reporting mandates impose documentation burdens that extend certification timelines and raise compliance costs for programmable matter developers.
- Electromagnetic interference limitations:Current electromagnetic coupling methods face signal degradation at dense catom configurations, constraining swarm coordination complexity.
Strategic Opportunities
- German semiconductor clusters:Munich and Dresden research hubs offer untapped partnership potential for catom manufacturing scale-up and process knowledge transfer.
- AI-ML convergence:Machine learning layers for swarm coordination represent premium positioning opportunities as morphing fidelity becomes the primary performance differentiator.
- South Korean patent landscape:Aggressive programmable matter IP filing activity creates licensing and co-development pathways for Western technology holders.
Industry Challenges
- Nanoscale mechatronics talent pipeline:Universities produce insufficient graduates with combined robotics and sub-micron fabrication expertise, forcing firms to compete for a shallow talent pool.
- Dual-use export control complexity:Expanding restrictions on programmable matter technologies are fragmenting cross-border collaboration models and complicating IP licensing structures.
- Multi-physics certification timelines:Claytronic devices must simultaneously satisfy electrical safety, mechanical reliability, and biocompatibility standards, creating extended regulatory review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Claytronics Market |
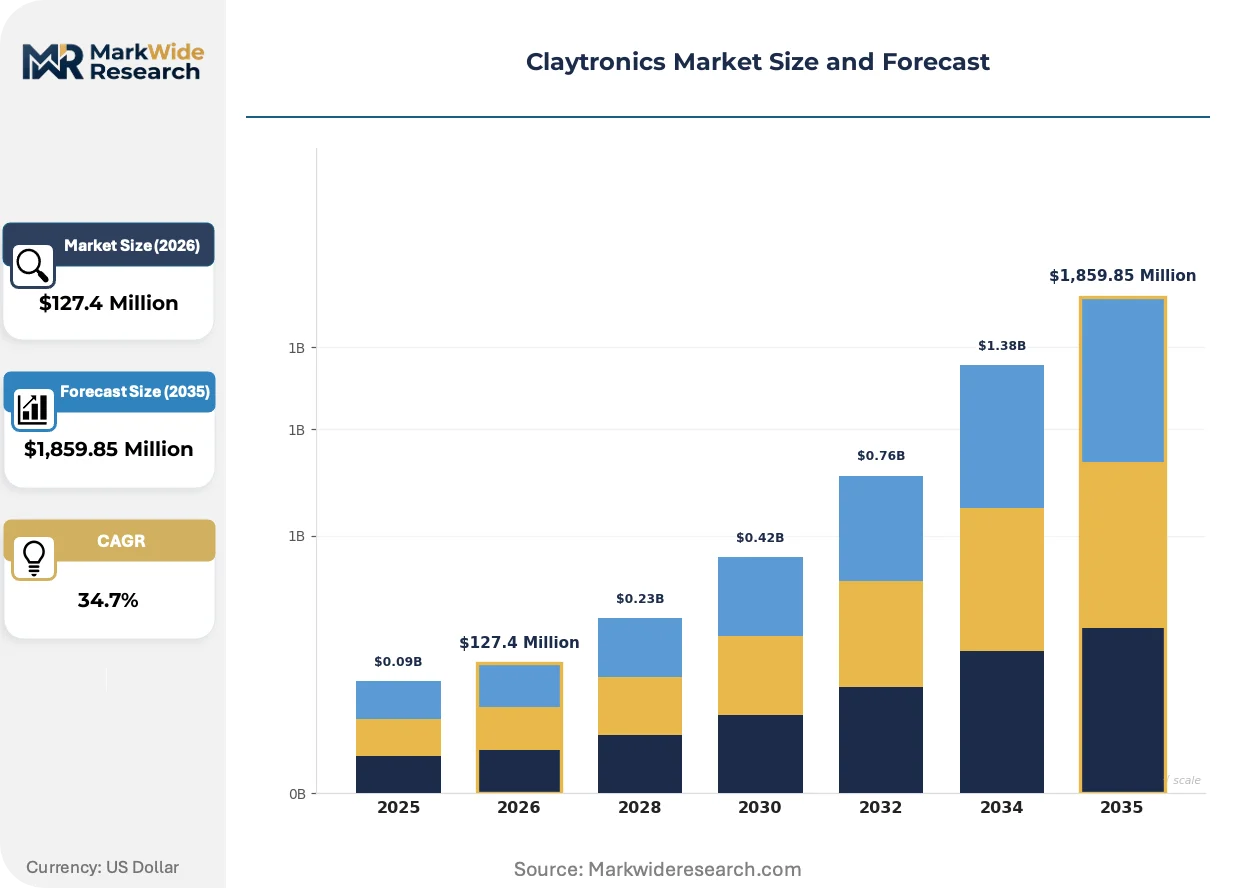
| Market Size in 2026 | $127.4 Million |
| Market Size in 2035 | $1,859.85 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nano-robots, Programmable Matter, Actuators, Sensors Technology: 3D Printing, AI Integration, Robotics, Machine Learning Application: Consumer Electronics, Healthcare Solutions, Education Tools, Entertainment End User: Manufacturers, Researchers, Educational Institutions, Entertainment Industries |
| Companies Covered | Carnegie Mellon University, United States Army Research Laboratory, Intel Corp, SRI International, Claytronics Inc, Claysol Inc, Real Intent, Samsung Advanced Institute of Technology, Claytronics Solutions Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Claytronics Market Emerging Trajectories
Programmable matter systems are undergoing rapid architectural evolution as electrostatic and electromagnetic actuation methods mature, while regulatory frameworks across major economies are crystallizing around nano-material safety protocols.
Electrostatic latching is supplanting mechanical interlocking as the dominant catom adhesion mechanism in next-generation claytronic systems. Medical visualization laboratories in the United States and Germany are adopting electrostatic architectures at accelerating pace for surgical simulation applications. This transition is compressing development cycles for real-time morphing interfaces while raising performance expectations for swarm coordination algorithms.
REACH nano-material characterization requirements are forcing claytronics developers to establish substance-by-substance documentation protocols before market entry. European manufacturers face particular pressure to demonstrate environmental fate and toxicity profiles for sub-millimeter robotic units. Medical device segments targeting CE marking under MDR are responding by integrating compliance teams earlier in product development workflows.
Defense procurement offices are consolidating vendor relationships around programmable matter suppliers with demonstrated dual-use capability. Traditional research equipment distribution channels are losing share to direct contracting models that emphasize security clearance and ITAR compliance. This concentration is most visible in United States Army Research Laboratory funding allocations, where single-source awards now dominate adaptive camouflage development programs.
Claytronics Market Segmentation
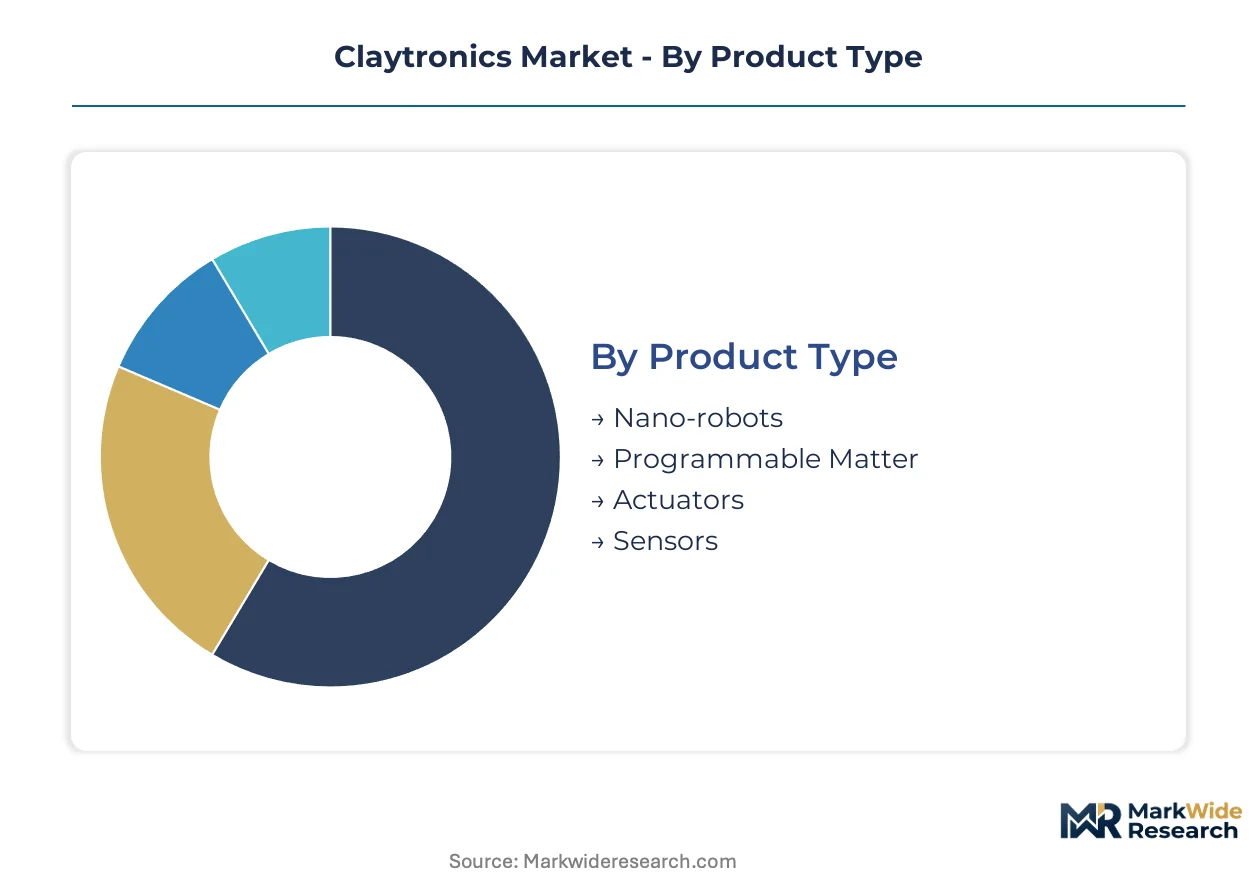
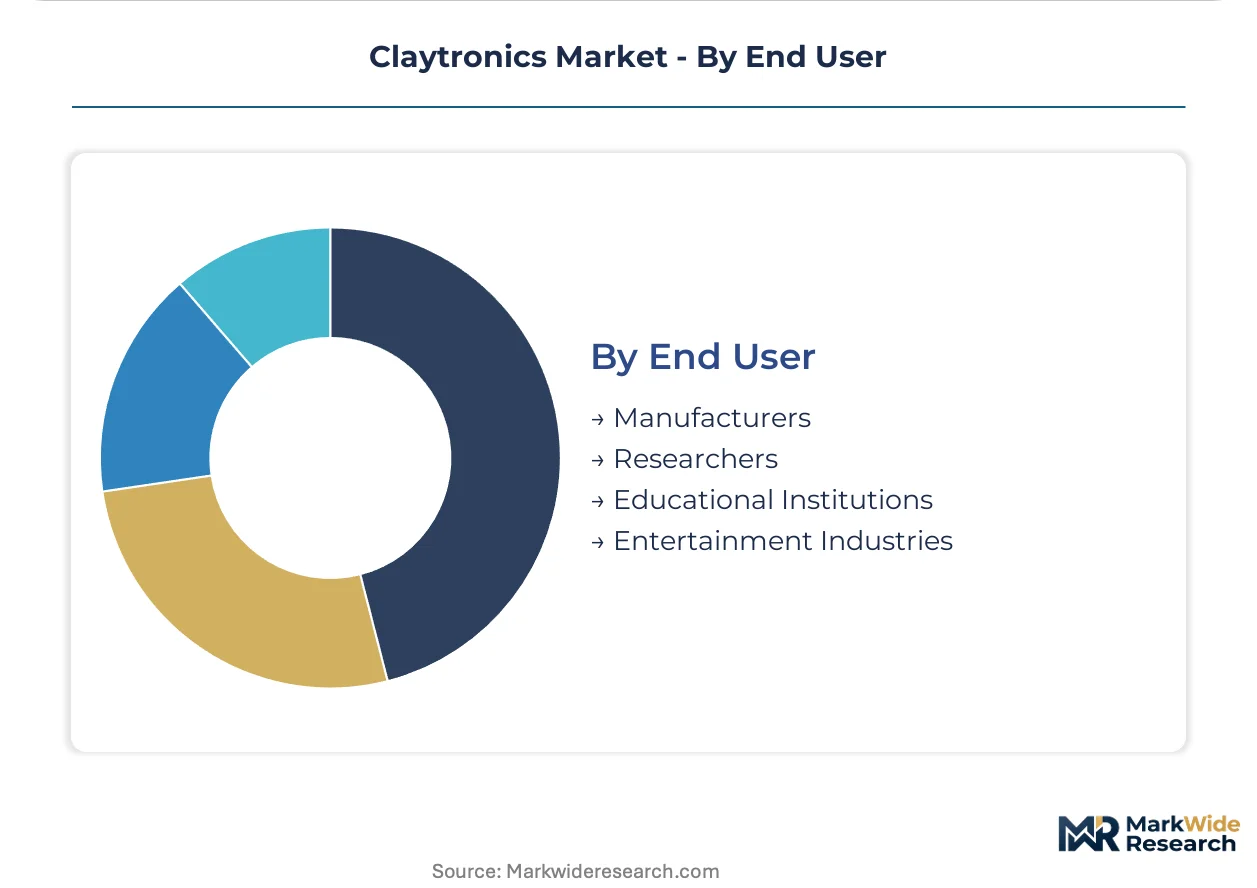
Claytronics market segmentation reveals distinct procurement patterns across defense, medical, and industrial verticals. Each dimension—product architecture, enabling technology, use case, and buyer type—exhibits divergent geographic concentration and certification requirements that reshape competitive positioning.
Product Type:
Domestic procurement dominates programmable matter and actuator segments in the United States and South Korea, while nano-robot systems flow through export-controlled channels to allied defense programs.
- Nano-robots:Sub-millimeter robotic units operate through electrostatic or electromagnetic actuation at scales between ten and one thousand micrometers. United States Army Research Laboratory procurement concentrates demand for battlefield simulation and adaptive camouflage applications, constrained by ITAR export restrictions and dual-use classification protocols.
- Programmable Matter:Self-assembling catom swarms enable real-time three-dimensional shape transformation under software control. German healthcare clusters in Munich and Dresden drive adoption for surgical simulation interfaces, accelerated by FDA-equivalent certification pathways under the EU Medical Device Regulation.
- Actuators:Micrometer-scale motion components require precision cleanroom fabrication infrastructure concentrated in South Korean and Taiwanese semiconductor foundries.
- Sensors:Sub-millimeter detection elements integrate with catom architectures for environmental feedback and swarm coordination.
Programmable matter commands the established base. The steepest expansion runs through nano-robot systems.
Technology:
Cost tier stratification separates capital-intensive 3D printing and robotics infrastructure from software-layer AI and machine learning investments that scale with lower marginal cost.
- 3D Printing:Additive manufacturing at sub-millimeter resolution enables rapid catom prototyping and small-batch production. Carnegie Mellon University research programs anchor United States academic demand, while German Fraunhofer institutes concentrate European industrial adoption.
- AI Integration:Swarm coordination algorithms determine real-time morphing fidelity and telepresence rendering quality. South Korean patent filing activity accelerates fastest in Seoul and Suwon research corridors, driven by Samsung Advanced Institute of Technology programs.
- Robotics:Mechatronics hardware platforms integrate actuation, sensing, and communication in unified catom architectures.
- Machine Learning:Predictive models optimize catom energy consumption and reconfiguration sequencing for extended operational duration.
3D printing retains the installed equipment base. AI integration is climbing the fastest as morphing fidelity becomes the primary performance differentiator.
Application:
Volume concentration skews toward healthcare and consumer electronics, while entertainment applications remain fragmented across experimental deployments.
- Healthcare Solutions:Surgical simulation and prosthetic interface applications command premium pricing due to FDA and EMA certification requirements. United States medical visualization laboratories adopt electrostatic architectures at accelerating pace, compressing development cycles for real-time morphing interfaces.
- Consumer Electronics:Adaptive display and haptic interface applications target mass-market scalability. South Korean electronics conglomerates concentrate manufacturing investment for telepresence and dynamic physical modeling products.
- Education Tools:Programmable matter teaching platforms enable tangible manipulation of abstract concepts in university engineering curricula.
- Entertainment:Immersive experience and physical special effects applications remain experimental with limited commercial deployment.
Healthcare solutions anchor revenue concentration. Consumer electronics is gaining share fastest as manufacturing scale economics improve.
End User:
Customer type determines procurement channel structure, with manufacturers and researchers accessing direct contracting while educational institutions route through equipment distribution.
- Manufacturers:Industrial integrators require production-scale catom supply chains and process knowledge transfer agreements. German semiconductor clusters in Dresden offer untapped partnership potential for manufacturing scale-up.
- Researchers:Academic and government laboratories prioritize experimental flexibility and publication rights over unit economics. United States National Nanotechnology Initiative funding directs procurement toward dual-use capability demonstrations.
- Educational Institutions:University programs emphasize graduate training pipeline development in nanoscale mechatronics engineering.
- Entertainment Industries:Studio and experience design firms prioritize rapid prototyping turnaround and creative customization.
Manufacturers represent the established demand core. Researchers are expanding most quickly as defense and medical visualization roadmaps accelerate funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA certification pathways for claytronic surgical simulators anchor United States demand, while German healthcare clusters and South Korean semiconductor foundries concentrate complementary supply capabilities across three continents.
United States
Defense visualization roadmaps and medical simulation laboratories drive procurement concentration. The US Army Research Laboratory fast-tracks programmable matter under Department of Defense nano-technology directives, filtering vendors through ITAR compliance requirements. Pittsburgh hosts Carnegie Mellon University's foundational claytronics program, sustaining graduate pipeline development for catom swarm coordination.
Germany
Surgical simulation interfaces and prosthetic device development command premium positioning. EMA-equivalent certification under EU Medical Device Regulation accelerates CE marking timelines for electrostatic claytronic architectures. Munich and Dresden semiconductor clusters offer untapped partnership potential for manufacturing scale-up and process knowledge transfer.
South Korea
Consumer electronics adaptive displays and telepresence applications concentrate manufacturing investment. Samsung Advanced Institute of Technology accelerates programmable matter patent filing activity across Seoul and Suwon research corridors. National nano-material frameworks reshape certification pathways for export-bound claytronic components.
Japan
Precision robotics integration and sub-millimeter fabrication expertise attract R&D investment. METI industrial technology roadmaps prioritize programmable matter for next-generation haptic interfaces. Nagoya and Osaka manufacturing belts concentrate cleanroom infrastructure for actuator component production.
United Kingdom
Academic research programs and dual-use technology assessment capabilities shape demand patterns. UK Research and Innovation funding directs programmable matter toward surgical training applications. Cambridge and Oxford nanotechnology clusters maintain active catom swarm development programs.
Claytronics Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with semiconductor process expertise and defense research clearance determining competitive boundaries. University-affiliated research laboratories and corporate advanced technology institutes concentrate foundational IP development, while commercial spin-outs struggle with capital-intensive cleanroom requirements. Two archetypes dominate: legacy academic programs with graduate pipeline control, and diversified technology conglomerates leveraging existing nano-fabrication infrastructure. Strategic moves center on research partnership consolidation and geographic patent filing expansion.
Among United States-based research anchors, Carnegie Mellon University exemplifies the academic archetype with sustained program continuity, while Intel Corp occupies a position within the semiconductor-integrated tier. Samsung Advanced Institute of Technology represents the Asia-Pacific conglomerate model, anchoring regional patent development.
| Leading Market Players |
|---|
| Carnegie Mellon University |
| United States Army Research Laboratory |
| Intel Corp |
| SRI International |
| Claytronics Inc |
| Claysol Inc |
| Real Intent |
| Samsung Advanced Institute of Technology |
| Claytronics Solutions Private Limited |
| Others |
Supply Flow & Price Mechanics
Electrostatic latching mechanisms displacing mechanical interlocking in next-generation catom architectures are simultaneously concentrating component sourcing in South Korean and Taiwanese foundries while compressing per-unit production economics for programmable matter systems. This substitution dynamic redraws supplier power structures across the claytronics value chain as legacy mechanical interlock vendors lose volume leverage.
Pricing Analysis
Price spreads between United States and German procurement markets exceed those observed in semiconductor equipment, reflecting FDA and EMA certification tier differentiation rather than raw manufacturing cost variation. Three-tier pricing structure across ITAR-restricted defense-grade, CE-marked medical-grade, and commercial prototyping tiers dominates transactional models. Cost compression in commercial prototyping segments intensifies as South Korean electronics conglomerates scale adaptive display manufacturing. Defense procurement offices exhibit lowest price sensitivity due to single-source security requirements, while educational institutions face acute budget constraints.
Supply Chain Analysis
Inbound logistics costs through the Port of Busan and Kaohsiung container terminals constrain just-in-time delivery windows for sub-millimeter actuator components bound for European medical device manufacturers. Supply concentrates in South Korea, Taiwan, and Germany for precision cleanroom fabrication infrastructure. Raw material dependencies include photoresist chemicals, rare-earth magnetic powders, and silicon wafer substrates. Single-source vulnerability in electrostatic latching intellectual property creates chokepoint exposure. Distribution runs through direct contracting models for defense and medical verticals, with equipment distributors serving educational and entertainment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Claytronics markets are approaching a platform-economics inflection where catom swarm interoperability standards will determine winner-take-most dynamics, with Carnegie Mellon University's open-architecture research programs accelerating ecosystem consolidation around electrostatic communication protocols.
For Market Incumbents: Consolidate graduate pipeline control through endowed chair positions at Carnegie Mellon University and comparable institutions to secure nanoscale mechatronics talent flows against poaching from Samsung Advanced Institute of Technology. Deepen backward integration into photoresist chemical supply through partnerships with German Fraunhofer institutes, reducing exposure to Taiwan Strait logistics volatility. Certification investment in dual FDA-EMA pathways for surgical simulation interfaces creates switching-cost moats against emerging entrants.
For New Entrants and Emerging Players: Lead with AI-ML swarm coordination software layers rather than capital-intensive catom hardware manufacturing, exploiting lower marginal scaling costs against semiconductor-integrated incumbents. German healthcare clusters in Munich and Dresden represent the most penetrable geography due to EMA-equivalent certification acceleration and untapped manufacturing partnerships. Go-to-market positioning through hospital system pilot programs for surgical training applications bypasses defense procurement channel barriers.
For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors research-laboratory spin-outs with demonstrated dual-use capability and ITAR compliance infrastructure. Long-term viability across the next decade hinges on successful navigation of REACH nano-material characterization requirements and export control expansion. Acquisition target archetypes include university-affiliated programs with graduate pipeline control and electrostatic latching patent portfolios. The signal to watch is Department of Defense single-source award concentration rates for adaptive camouflage development.
| Strategic Initiative | Industry Significance |
|---|---|
| Research Partnership Consolidation | Carnegie Mellon University pipeline agreements secure nanoscale mechatronics talent against Samsung Advanced Institute of Technology competition. |
| Dual-Use Capability Demonstration | United States Army Research Laboratory funding eligibility requires ITAR compliance and security clearance infrastructure. |
| Electrostatic Architecture Transition | FDA certification pathways for surgical simulators compress development cycles for real-time morphing medical interfaces. |
| REACH Compliance Integration | EMA substance characterization protocols force early-stage documentation workflows for European market entry. |
| Patent Filing Geographic Expansion | Seoul and Suwon research corridors accelerate South Korean programmable matter IP development against Western holders. |
Methodological Framework
The analysis maps nano-robot hardware, programmable matter systems, AI-ML coordination software, and electrostatic actuator components, each validated through claytronics research directors, FDA regulatory affairs specialists, defense procurement officers, and hospital biomedical engineering committees. Primary interviews with these stakeholders combined with secondary validation from SEC filings of semiconductor-integrated conglomerates, United States Patent and Trademark Office programmable matter filings, EMA medical device registration databases, and Department of Defense nano-technology directive publications. Bottom-up catom unit economics modeling and top-down defense and healthcare vertical demand aggregation provided triangulation consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product architecture, enabling technology layer, application vertical, and end-user procurement channel, supplemented by regulatory certification tier as an industry-specific dimension. CAGRs derived from historical funding trajectory analysis and patent filing velocity indicators, with electrostatic latching adoption curves and REACH compliance timeline assumptions as key forecast inputs.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EMA MDR frameworks; material policy shifts in nano-material characterization requirements or ITAR export control scope would require re-modeling. Specific risks include electromagnetic interference technical limitations constraining swarm coordination complexity and nanoscale mechatronics graduate pipeline shortfalls. Recalibration cycles align with material shifts in Department of Defense funding allocations and electrostatic architecture adoption rates in medical visualization laboratories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Firefighting Robots Market
Robotics and Automation
Robot Controller, Integrator and Software Market
Robotics and Automation
Painting Robot Market
Robotics and Automation
North America Cloud Robotics Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
AI Assisted Robots Market
Robotics and Automation
Mobile Robot Charging Station Market
Robotics and Automation
Data Center Robotics Market
Robotics and Automation
Asia-Pacific Cloud Robotics Market
Robotics and Automation
Industrial Robot Controllers Market
Robotics and Automation
Robotic Process Automation in BFSI Market
Robotics and Automation
Global Robot Software Market
Robotics and Automation
Europe Logistics Robotics Market
Robotics and Automation
Micro Robots Market
Robotics and Automation
Asia Pacific Industrial Robots Market