
 Automotive Robotic Painting Market | 2026-2036
Automotive Robotic Painting Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Robotic Painting Market Outlook
ISO 9001 quality management certification is reorganizing supplier hierarchies in automotive robotic painting, favoring vendors with documented process control. Dürr AG leverages its captive finishing technology portfolio to anchor European OEM relationships. FANUC CORPORATION dominates Japan-based robotics supply for paint shop automation. ABB competes through integrated vision-guided spray control systems that reduce material waste.
Automotive robotic painting deploys articulated manipulators with six-axis kinematics, electrostatic spray applicators, and real-time film-thickness feedback to deposit basecoat and clearcoat layers with sub-millimeter uniformity across vehicle body panels. Spray robots command the largest installed base among product types due to their direct role in transfer efficiency and finish consistency. OEM end users represent the deepest margin pool as they specify equipment architectures that Tier-1 suppliers must replicate. Vision technology integration is expanding fastest as manufacturers pursue defect detection concurrent with application rather than post-process inspection.
EPA enforces National Emission Standards for Hazardous Air Pollutants that mandate capture and control of paint solvent emissions, directly shaping equipment specifications for enclosed spray booths and vapor recovery. OSHA maintains permissible exposure limits for isocyanates and hexavalent chromium compounds that drive automation substitution for manual spray operations. In Europe, REACH restrictions on chromium-based pigments and the F-Gas Regulation governing solvent-based systems are redirecting formulation and application technology choices. Stakeholders must monitor how evolving substance restrictions and carbon accounting rules will alter capital allocation between solvent-borne, water-borne, and powder coating robotic lines.
Market Dynamics
Electrostatic spray efficiency mandates are compressing equipment replacement cycles as EPA emission thresholds tighten and OEMs face carbon-accounting disclosure requirements for Scope 3 paint-shop emissions.
Growth Catalysts
- REACH substance restrictions:European chromium pigment bans are forcing water-borne coating conversions that require new robotic applicator architectures.
- Electric vehicle OEMs:Battery-electric vehicle manufacturers are specifying precision film-thickness uniformity that only six-axis robotic systems can deliver across composite body panels.
- Real-time vision feedback:Concurrent defect detection during spray application is eliminating post-process inspection stations and reducing rework rates.
Market Restraints
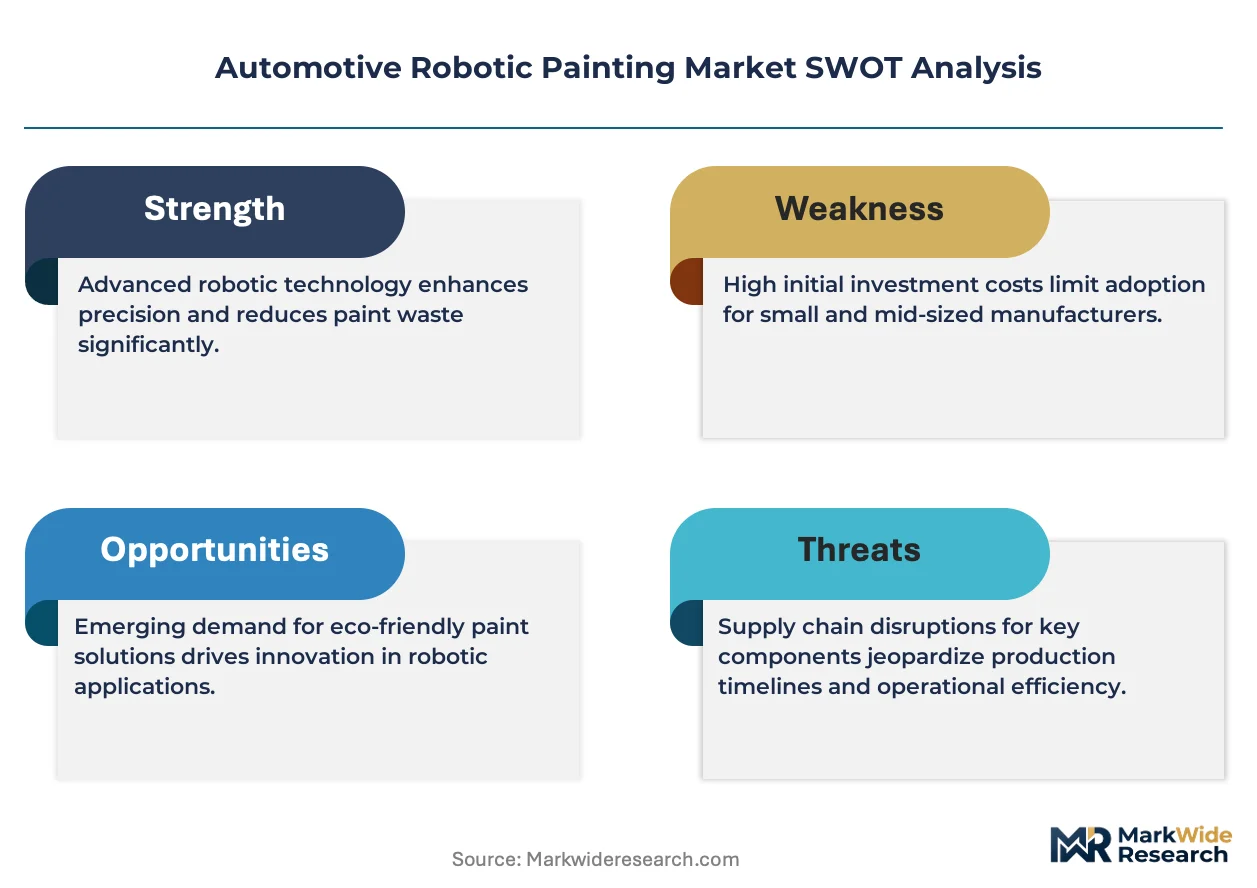
- Servo motor supply concentration:Precision motion control components for articulated manipulators concentrate in Japanese and German supplier bases, creating lead-time vulnerability.
- Hexavalent chromium exposure limits:OSHA permissible exposure thresholds for manual operations are accelerating automation but requiring expensive enclosed booth retrofits.
- Powder coating substitution:Zero-VOC powder formulations are displacing liquid robotic lines in underbody and wheel-arch applications where appearance tolerance permits.
Strategic Opportunities
- India automotive clusters:Tamil Nadu and Gujarat manufacturing corridors lack automated paint capacity relative to projected vehicle output through 2035.
- AI-guided path planning:Machine learning trajectory optimization converging with existing robot kinematics is enabling first-time-right spray patterns without manual teach-point programming.
- CSRD disclosure mandates:European corporate sustainability reporting requirements are creating preference for equipment vendors with documented lifecycle carbon footprints.
Industry Challenges
- Multi-axis programming expertise:Shortage of technicians capable of calibrating electrostatic parameters across complex vehicle geometries is extending commissioning timelines.
- Legacy controller integration:Brownfield paint shops face protocol incompatibility when retrofitting vision-guided systems onto twenty-year-old robot platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Robotic Painting Market |
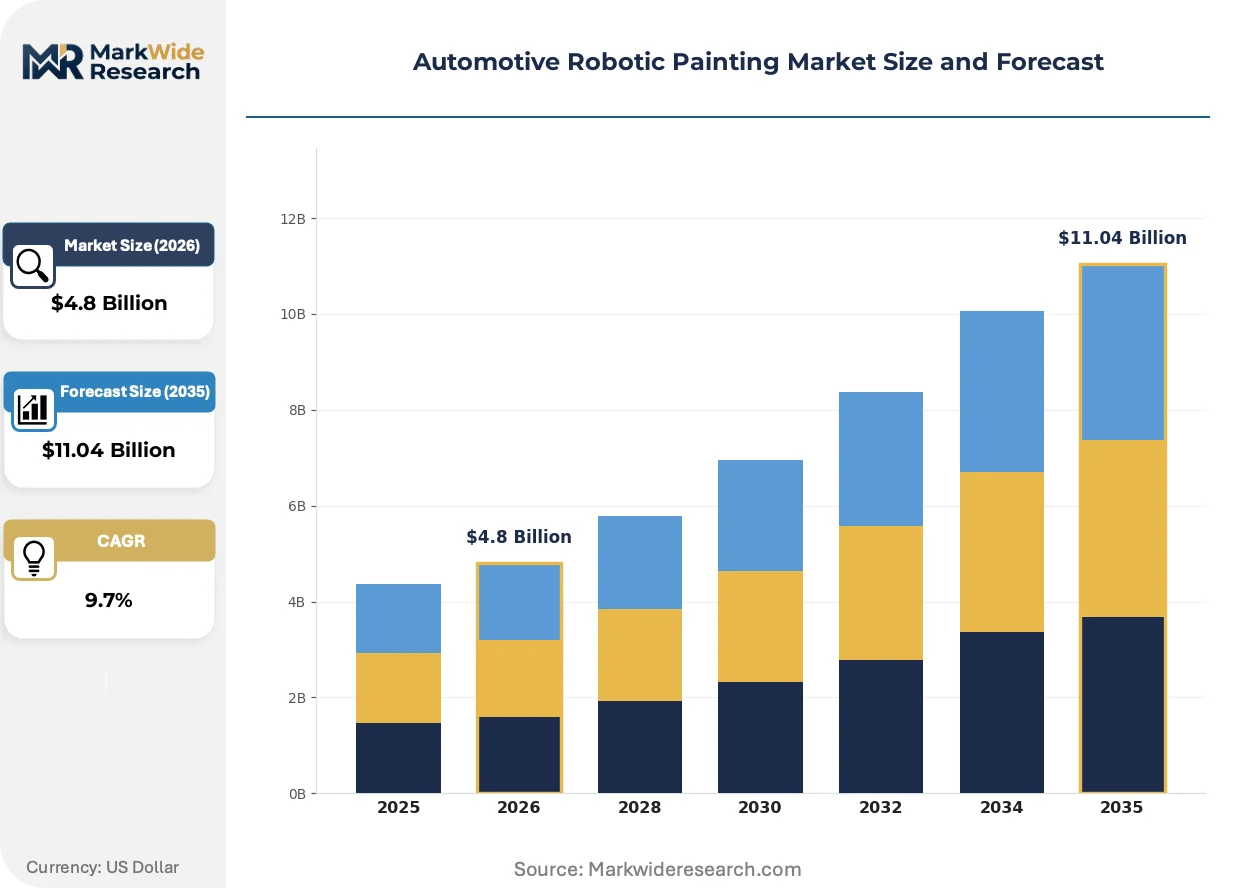
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray Robots, Robotic Arms, Vision Systems, Paint Dispensing Technology End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Manufacturing Plants Installation: On-site, Off-site, Integrated Systems, Standalone Solutions Technology: Artificial Intelligence, Machine Learning, Vision Technology, Automation |
| Companies Covered | Dürr AG, ABB, FANUC CORPORATION, KUKA AG, Yaskawa Electric Corporation, Kawasaki Heavy Industries, Stäubli International AG, Epson Robotics, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Robotic Painting Market Strategic Shifts
Application technology is splitting between premium vision-integrated systems and cost-optimized configurations as regulatory pressure and margin compression operate simultaneously across OEM and supplier tiers.
Electrostatic rotary bell atomizers with integrated current control are bifurcating the installed base. Luxury and electric vehicle manufacturers are adopting high-transfer-efficiency models that reduce material waste by capturing overspray for recirculation. This technology is compressing demand for conventional air-spray robotic stations in mass-market assembly plants where capital constraints dominate procurement decisions.
EPA National Emission Standards for Hazardous Air Pollutants are mandating vapor recovery capture efficiency above ninety-eight percent for major source paint operations. Equipment specifications now require enclosed spray booths with carbon adsorption or thermal oxidation downstream. Tier-1 suppliers serving US-based OEMs are reconfiguring line architectures to accommodate these capture systems, increasing booth footprint and HVAC load.
Buyer contracting is consolidating around equipment-as-service models with throughput-based pricing. Tier-1 automotive suppliers are displacing capital purchase agreements with multi-year contracts where vendors retain ownership and charge per finished vehicle body. This shift is most visible in German automotive manufacturing clusters where Dürr and ABB have established captive service operations adjacent to OEM assembly plants.
Automotive Robotic Painting Market Segmentation
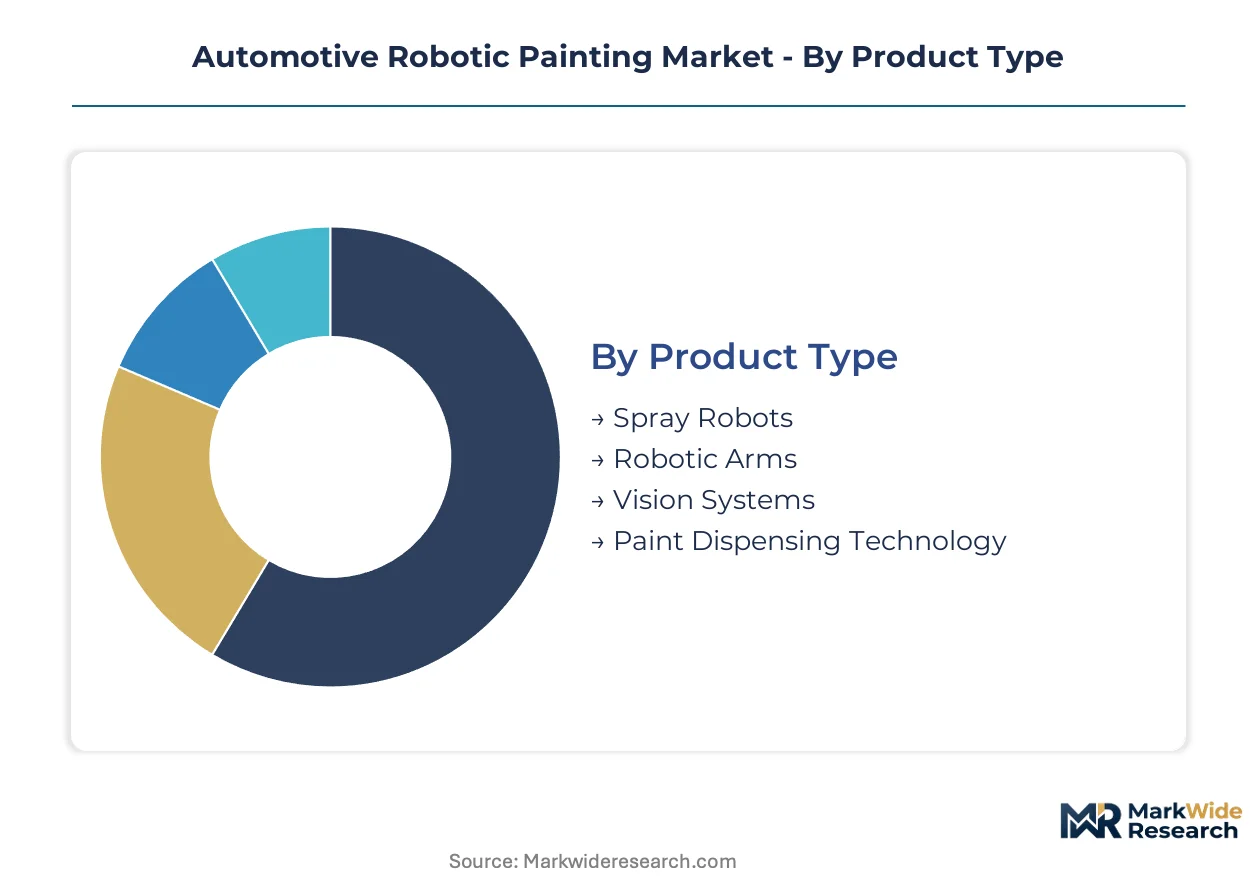
Automotive robotic painting equipment flows through distinct procurement channels depending on segment characteristics. OEMs specify architectures that Tier-1 suppliers must replicate, while aftermarket channels handle retrofits and capacity expansions. Understanding these pathways clarifies where margin pools concentrate and which segments drive replacement cycles.
Product Type:
Spray robots and vision systems move through OEM direct procurement, while paint dispensing technology often channels through Tier-1 system integrators.
- Spray Robots:Articulated six-axis manipulators with electrostatic rotary bell atomizers deposit basecoat and clearcoat layers. Demand concentrates at electric vehicle OEMs in Germany and the United States where EPA emission thresholds mandate enclosed booth configurations with vapor recovery capture efficiency above ninety-eight percent.
- Vision Systems:Real-time film-thickness feedback and concurrent defect detection eliminate post-process inspection stations. Expansion concentrates among battery-electric vehicle manufacturers specifying precision uniformity across composite body panels that manual inspection cannot achieve.
- Robotic Arms:Standard kinematic platforms without integrated spray heads serve ancillary material handling and masking operations.
- Paint Dispensing Technology:Metering systems and color-change modules reduce solvent waste and flush cycles between vehicle variants.
Spray robots dominate installed base. Vision systems are where expansion concentrates.
End User:
Cost tiers separate specification authority from execution risk across the value chain.
- OEMs:Original equipment manufacturers retain architectural control and capture the deepest margin pools through captive engineering standards. German automotive clusters drive precision robotics procurement as manufacturing concentration justifies dedicated automation engineering teams.
- Tier-1 Suppliers:Contract manufacturers replicate OEM-specified equipment architectures under throughput-based service contracts. REACH substance restrictions on chromium pigments are forcing water-borne coating conversions that require new robotic applicator architectures at these facilities.
- Manufacturing Plants:Greenfield assembly sites in India and Southeast Asia represent underpenetrated demand relative to projected vehicle output through the forecast window.
- Aftermarket Providers:Retrofit specialists serve capacity expansions and legacy line upgrades where brownfield integration challenges dominate.
OEMs anchor specification authority. Tier-1 suppliers represent the volume expansion layer.
Installation:
Volume concentration favors integrated configurations where line throughput justifies single-source accountability.
- Integrated Systems:Turnkey paint shop architectures combine spray booths, robots, conveyors, and emission control in unified vendor responsibility. EPA National Emission Standards for Hazardous Air Pollutants mandate carbon adsorption or thermal oxidation downstream, increasing booth footprint and HVAC load.
- On-site:Field-assembled configurations prevail in brownfield expansions where existing infrastructure constrains layout flexibility. OSHA permissible exposure limits for isocyanates and hexavalent chromium compounds accelerate automation substitution requiring expensive enclosed booth retrofits.
- Standalone Solutions:Single-robot cells serve low-volume specialty operations and prototype coating.
- Off-site:Pre-commissioned modular paint shops reduce field installation time for greenfield projects.
Integrated systems command the premium tier. On-site installation carries the brownfield retrofit burden.
Technology:
Maturity gradients separate proven automation from emerging AI applications with unproven scale economics.
- Vision Technology:Concurrent defect detection during spray application reduces rework rates and eliminates dedicated inspection stations. Machine learning trajectory optimization is converging with existing robot kinematics to enable first-time-right spray patterns without manual teach-point programming.
- Automation:Programmable logic controllers and fixed-sequence robotics constitute the installed base majority with established commissioning protocols.
- Artificial Intelligence:AI-guided path planning remains in pilot deployment at luxury and electric vehicle manufacturers with engineering tolerance for algorithmic experimentation.
- Machine Learning:Predictive maintenance models for electrostatic parameter calibration are extending equipment uptime in high-volume operations.
Vision technology is climbing the fastest. Automation retains the volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German automotive exports to global assembly networks, while the Trans-Siberian Railway links Russian energy flows to Asian manufacturing zones. These infrastructure assets position specific countries as demand anchors for precision coating automation.
United States
EPA National Emission Standards for Hazardous Air Pollutants mandate vapor recovery capture efficiency above ninety-eight percent for major source paint operations. OSHA permissible exposure limits for isocyanates accelerate automation substitution in manual spray operations. Detroit-Warren-Dearborn manufacturing corridor concentrates electric vehicle OEM capacity expansions requiring enclosed booth retrofits.
Germany
REACH restrictions on chromium-based pigments redirect formulation choices toward water-borne coating systems requiring new robotic applicator architectures. The F-Gas Regulation governs solvent-based application technology selections across automotive clusters. Stuttgart and Munich manufacturing corridors drive precision robotics procurement as engineering concentration justifies dedicated automation teams.
China
MIIT dual carbon goals compress equipment replacement cycles as carbon-accounting disclosure requirements tighten for Scope 3 paint-shop emissions. GB standards for volatile organic compound limits reshape enclosed spray booth specifications. Yangtze River Delta automotive clusters concentrate battery-electric vehicle manufacturing demanding six-axis robotic uniformity across composite body panels.
Japan
METI industrial policy supports precision motion control component manufacturing for articulated manipulators serving automotive paint automation. JIS standards govern electrostatic spray equipment interoperability. Nagoya-Toyota industrial corridor concentrates Toyota Motor Corporation and supplier ecosystem paint shop automation demand.
India
PLI scheme incentives for automotive manufacturing attract greenfield assembly investments lacking automated paint capacity relative to projected vehicle output. BIS standards for emission control equipment shape enclosed booth specifications. Tamil Nadu and Gujarat manufacturing corridors represent underpenetrated demand for integrated paint shop systems through 2035.
Automotive Robotic Painting Market Competitive Environment
Listed leaders compete with private specialists across technology integration depth, with public companies commanding capital access for multi-year service contracts while private fabricators retain agility in custom retrofit configurations. The vendor base stratifies into three tiers: integrated system architects owning full paint shop responsibility, component specialists supplying electrostatic applicators or vision modules, and regional integrators executing field installation. Dominant competitive moves include equipment-as-service contracting with throughput-based pricing and AI-guided path planning partnerships that reduce manual teach-point programming requirements.
Within the integrated system architect tier, Dürr AG anchors European OEM relationships through captive finishing technology portfolios, while ABB occupies a position exemplifying vision-guided spray control specialization. FANUC CORPORATION represents the Japan-based robotics supply archetype for paint shop automation. These three companies sit within distinct geographic and technological positioning vectors rather than direct product overlap.
| Leading Market Players |
|---|
| Dürr AG |
| ABB |
| FANUC CORPORATION |
| KUKA AG |
| Yaskawa Electric Corporation |
| Kawasaki Heavy Industries |
| Stäubli International AG |
| Epson Robotics |
| Omron Corporation |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day lead times for precision servo motors from Japanese and German suppliers compress pricing flexibility for robotic manipulator manufacturers serving EPA-mandated emission control retrofits. This inventory constraint concentrates margin pressure on Tier-1 system integrators while OEMs with captive engineering teams extract volume discounts through multi-year throughput-based contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates vision-integrated electrostatic systems from conventional air-spray configurations and basic articulated platforms without film-thickness feedback. Price differentiation hinges on ISO 9001 certification status and enclosed booth vapor recovery integration. Pricing pressure stems from REACH-driven water-borne coating conversions requiring new applicator architectures. Tier-1 suppliers exhibit highest price sensitivity due to throughput-based contracting, while luxury electric vehicle OEMs prioritize performance over unit cost.
Supply Chain Analysis
Japan and Germany anchor precision motion control component manufacturing for six-axis articulated manipulators, with South Korea expanding rotary bell atomizer production. Supply chains draw from rare earth magnet suppliers for servo motors, specialized electrostatic generators, and real-time vision sensors. Single-source vulnerability concentrates in high-voltage electrostatic power supply modules. Distribution runs through OEM direct procurement for architectural specification and Tier-1 system integrators for replication deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around German and US-based electric vehicle OEMs with captive automation engineering teams, fragmenting pricing leverage among Tier-1 contract manufacturers locked into throughput-based service agreements.
For Market Incumbents: Shield margin pools by deepening backward integration into electrostatic rotary bell atomizer manufacturing and securing exclusive service operations adjacent to Stuttgart and Munich automotive clusters. Powder coating substitution in underbody applications threatens liquid robotic line revenue. Certification investment in documented lifecycle carbon footprints anchors European CSRD disclosure preference. For New Entrants and Emerging Players: Commissioning expertise scarcity in multi-axis electrostatic parameter calibration offers white-space entry through AI-guided path planning partnerships that eliminate manual teach-point programming. Tamil Nadu and Gujarat manufacturing corridors in India represent the most penetrable geography relative to projected vehicle output. Target aftermarket retrofit specialists facing legacy controller protocol incompatibility as the initial go-to-market channel. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because EPA and OSHA emission thresholds tighten equipment replacement cycles irrespective of automotive production cyclicality. Acquisition targets should exhibit vision technology integration capabilities with established Tier-1 supplier relationships. Monitor F-Gas Regulation enforcement intensity in European automotive clusters as the inflection signal for water-borne coating conversion capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-Service Contracting | Throughput-based pricing shifts capital risk from Tier-1 suppliers to vendors with captive balance sheets. |
| AI-Guided Path Planning Integration | Machine learning trajectory optimization reduces commissioning timelines threatened by technician shortages. |
| Vision Technology Partnership | Concurrent defect detection eliminates post-process inspection stations for battery-electric vehicle manufacturers. |
| Carbon Footprint Documentation | Lifecycle certification anchors vendor preference under European CSRD disclosure mandates. |
| Regional Service Operations | Captive finishing technology portfolios adjacent to OEM assembly plants lock out competitor access. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, paint shop maintenance directors, and electrostatic applicator R&D specialists and refined through secondary validation against SEC 10-K filings, EPA enforcement databases, IHS Markit vehicle production data, and REACH substance restriction updates. Bottom-up equipment shipment analysis triangulated with top-down automotive manufacturing capacity modeling.
Variance decomposition across the projection horizon isolates segment-specific growth contributions from spray robots, vision systems, and integrated paint shop architectures. Modeled dimensions span vehicle propulsion architecture, OEM tier classification, coating formulation type, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and greenfield capacity expansion schedules, with EPA National Emission Standards for Hazardous Air Pollutants and REACH substance restrictions as primary demand timing inputs.
Underlying assumptions cover emission threshold enforcement continuity, servo motor supply lead-time stability, and electric vehicle production trajectory realization, with deviation risk concentrated in powder coating substitution rates and AI path planning scale economics. Recalibration cycles align with material shifts in EPA enforcement intensity and European F-Gas Regulation amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
Global Smart Robots Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Commercial Robotics Market
Robotics and Automation
Global Rescue Robot Market
Robotics and Automation
Gantry Industrial Robots Market
Robotics and Automation
Asia-Pacific Service Robotics Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Medical Service Robots Market
Robotics and Automation
Surgical Robots Market
Robotics and Automation
Asrs and Ruos Market
Robotics and Automation
Asia-Pacific Robotic Process Automation Market
Robotics and Automation
Agriculture Robotics Market
Robotics and Automation
Robotics for NDT Market
Robotics and Automation
Robotics Actuators Market