
 Typhoid Vaccines Market | 2026-2036
Typhoid Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Typhoid Vaccines Market Analytics
mRNA platform refinement is rewriting how typhoid vaccine candidates enter clinical pipelines, shifting development timelines and immunogenicity benchmarks for conjugate formulations. Bharat Biotech anchors South Asian supply through its established Vi polysaccharide manufacturing base. GlaxoSmithKline competes via WHO-prequalified Typbar-TCV distribution networks across endemic zones. Sanofi leverages its injectable delivery expertise to sustain hospital and clinic channel presence in Francophone Africa.
Typhoid vaccines are sterile biological preparations containing purified Vi capsular polysaccharide from Salmonella Typhi, either alone or conjugated to carrier proteins, designed to induce protective antibodies against systemic infection. The ViCPS segment dominates current procurement volumes due to established cold chain compatibility and single-dose administration, while conjugate formulations command premium positioning through extended immunological memory in pediatric populations. Oral Ty21a live-attenuated delivery retains niche deployment in travel health applications where multi-dose compliance remains achievable. Health departments represent the fastest-growing end user channel as national programs transition from outbreak response to routine preventive immunization.
WHO prequalification standards shape manufacturing compliance requirements for suppliers targeting Gavi-eligible countries, while FDA and EMA pathways govern access to travel health segments in North America and Europe. India's CDSCO regulates domestic licensure under the Drugs and Cosmetics Act, with BIS standards applying to cold chain equipment used in last-mile distribution. Stakeholders must monitor conjugate vaccine cost curves against national budget ceilings to determine whether preventive campaigns or targeted outbreak control delivers superior health economic returns.
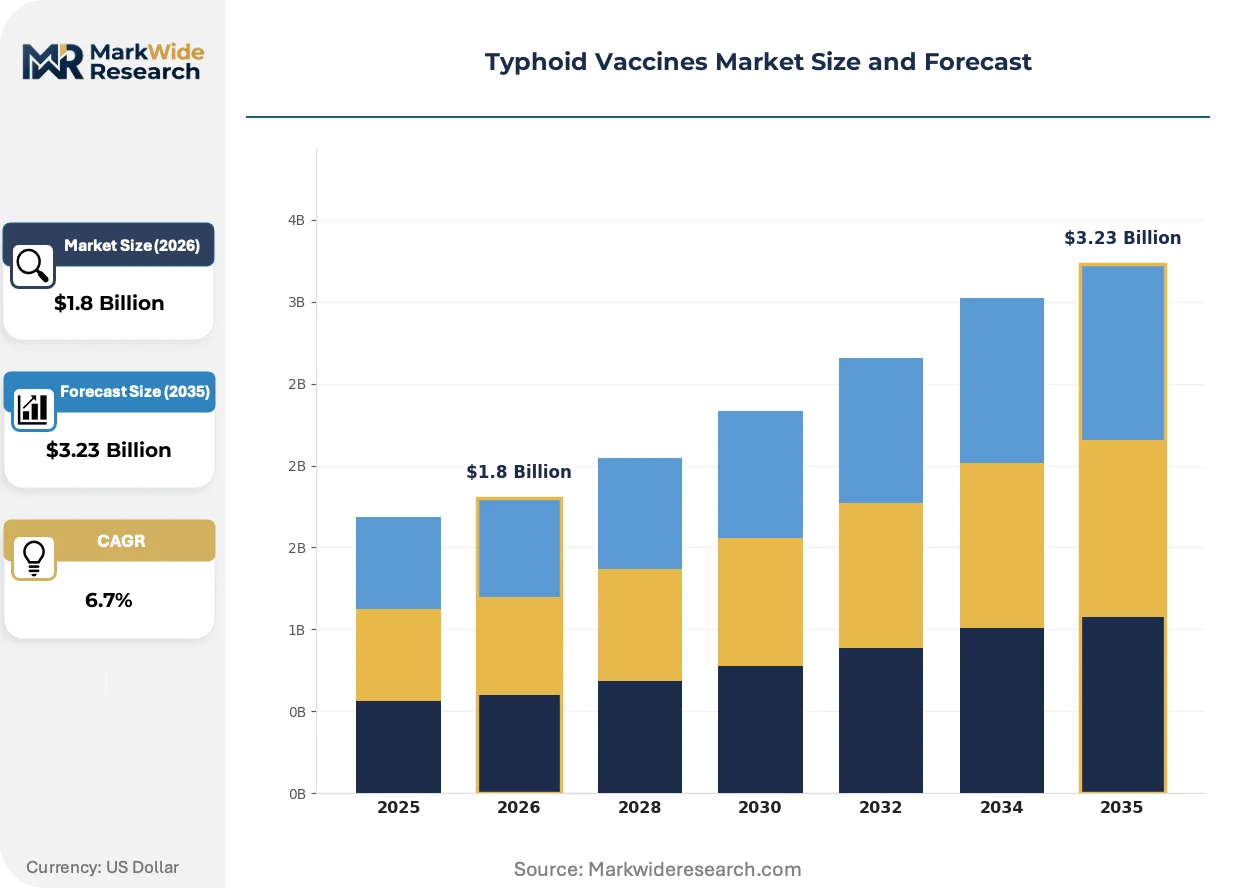
Market Dynamics
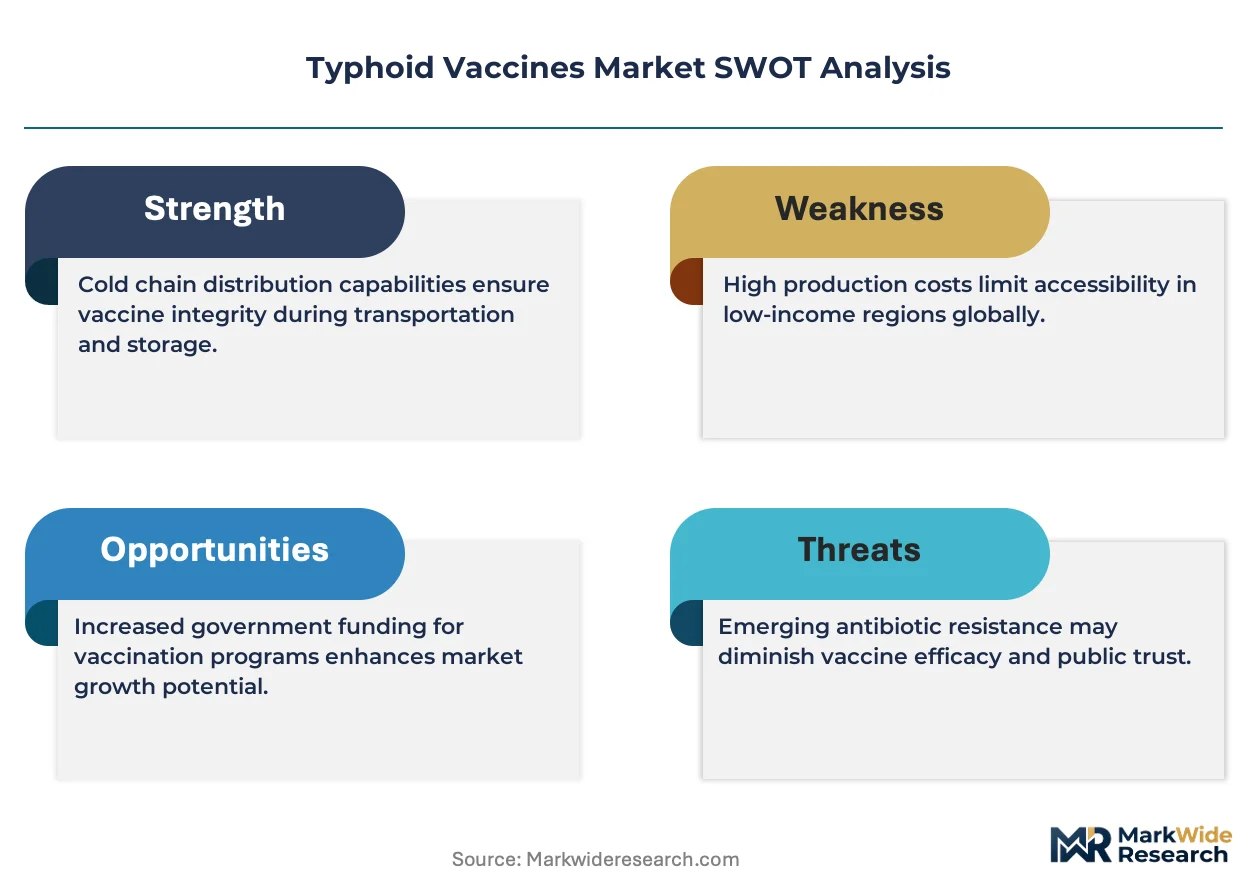
WHO prequalification requirements are compressing manufacturer margins while expanding access corridors for conjugate vaccines across Gavi-eligible countries, forcing suppliers to choose between volume scale and premium positioning.
Growth Catalysts
- Gavi procurement commitments:The vaccine alliance's multi-year purchase guarantees for Typbar-TCV de-risk manufacturing capacity investments in South Asian production facilities.
- India:The government's 2022 expansion of pediatric typhoid vaccination into routine immunization schedules created sustained demand pull for domestic Vi polysaccharide supply.
- Conjugate chemistry advances:Protein-polysaccharide linking technologies from CRM197 carriers are extending immunological memory duration in children under two years.
Market Restraints
- Cold chain infrastructure gaps:Last-mile refrigeration failures in rural sub-Saharan Africa limit effective vaccine reach despite procurement availability.
- Vi polysaccharide raw material concentration:Purified capsular antigen supply clusters among three established fermentation facilities, creating single-source vulnerability.
- Oral Ty21a thermostability limits:The live-attenuated formulation requires strict cold storage, disqualifying deployment in ambient-temperature field conditions.
Strategic Opportunities
- Pakistan:The country's pending national program adoption of conjugate vaccines opens procurement volume comparable to India's initial rollout phase.
- Thermostable formulations:Vaccine stabilization technologies eliminating cold chain dependency would unlock community health worker distribution in last-mile settings.
- mRNA platform transfer:Technology licensing agreements enabling regional manufacturers to produce nucleic acid-based typhoid candidates are shortening development timelines.
Industry Challenges
- WHO prequalification timeline compression:Accelerated review pathways for outbreak response strain regulatory affairs capacity at emerging market suppliers.
- Conjugate vaccine fill-finish capacity:Aseptic processing bottlenecks at contract manufacturing organizations delay batch release for pediatric campaigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Typhoid Vaccines Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ty21a, ViCPS, TAB, Others Delivery Mode: Oral, Injectable, Subcutaneous, Intramuscular Application: Prevention, Outbreak Control, Travel Health, Pediatric Care End User: Hospitals, Clinics, Pharmacies, Health Departments |
| Companies Covered | Bharat Biotech, GlaxoSmithKline, Sanofi, Biological E, PT Bio Farma, PaxVax, SK Bioscience, Zydus, Indian Immunologicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Typhoid Vaccines Market Evolving Landscape
mRNA platform migration is compressing traditional development timelines for typhoid candidates while conjugate manufacturing investments concentrate in WHO-prequalified South Asian facilities.
Synthetic biology approaches to Vi capsular polysaccharide production are virtualizing conventional fermentation-based manufacturing. Biotech startups and academic consortia are adopting cell-free enzymatic synthesis for carrier-protein conjugation, reducing batch-to-batch variability. This technology is virtualizing capital-intensive bioreactor infrastructure requirements for new market entrants.
WHO prequalification pathway revisions now mandate real-time stability data submission rather than accelerated aging studies, extending review cycles for conjugate formulations. The industrial consequence squeezes smaller manufacturers with limited regulatory affairs bandwidth. Pediatric vaccine suppliers targeting Gavi-eligible countries are responding by consolidating dossier preparation through specialized consulting partnerships.
National health departments are consolidating procurement authority previously dispersed across state-level immunization programs. Centralized tendering in India and Nigeria is displacing fragmented purchase orders with multi-year supply agreements. This concentration is most visible in India's transition from outbreak-response purchasing to routine preventive campaigns under the Universal Immunization Programme.
Typhoid Vaccines Market Segmentation
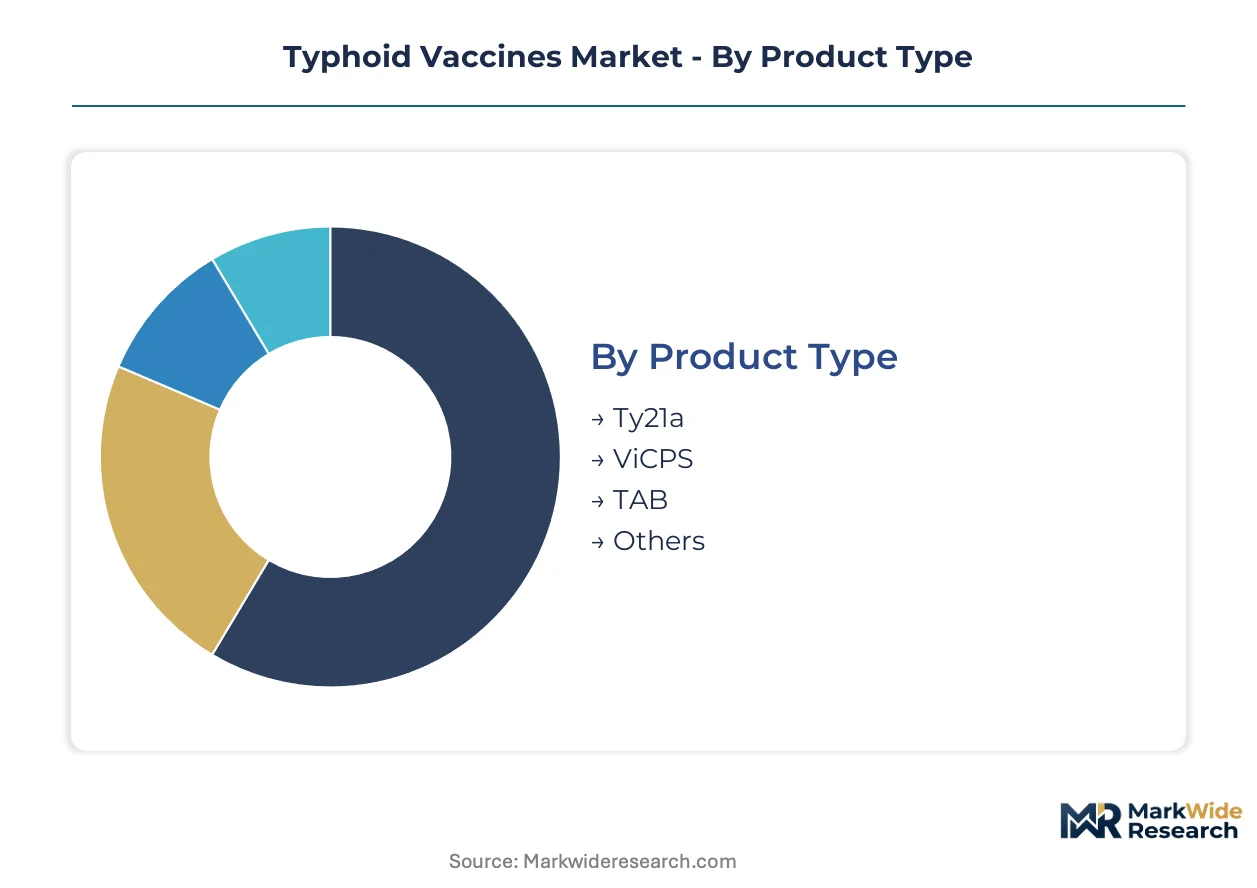
Typhoid vaccine procurement splits across product platforms, administration routes, and institutional channels with distinct cold chain, dosing, and reimbursement requirements. Understanding these segment boundaries clarifies where manufacturers compete on price versus performance, and where national programs prioritize volume over premium formulations.
Product Type:
After-sales service intensity varies sharply across product types, with live-attenuated formulations requiring cold chain monitoring support that polysaccharide suppliers rarely provide.
- ViCPS:Purified Vi capsular polysaccharide from Salmonella Typhi, administered as a single intramuscular dose without conjugation to carrier proteins. Demand concentrates in India's Universal Immunization Programme and Gavi-eligible African countries where cost constraints favor established cold chain compatibility over extended immunological memory.
- Ty21a:Live-attenuated oral formulation derived from Salmonella Typhi Ty21a strain, delivered as a multi-dose capsule regimen. Travel health clinics in North America and Europe drive procurement where patient compliance for three-dose schedules remains achievable; thermostability failures restrict deployment in ambient-temperature field settings.
- TAB:Heat-inactivated phenol-preserved whole-cell suspension combining Salmonella Typhi, Paratyphi A, and Paratyphi B antigens. Military and institutional buyers in endemic regions with legacy procurement contracts.
- Others:Emerging conjugate formulations and investigational mRNA candidates in preclinical and early clinical development pipelines.
ViCPS holds the largest share; momentum sits with conjugate chemistry advances extending pediatric indication ranges.
Delivery Mode:
Cost tier stratification separates premium patient-administered oral capsules from mass-campaign injectable formats requiring trained healthcare workers.
- Injectable:Intramuscular or subcutaneous administration of Vi polysaccharide or conjugate suspensions via prefilled syringes or multidose vials. National immunization programs in India and Nigeria standardize on this modality for school-based campaigns where cold chain infrastructure supports centralized vaccination events.
- Oral:Capsule or liquid enteric-coated formulations bypassing needle requirements and enabling self-administration in traveler populations. Pharmacy and travel clinic channels in Germany, the United Kingdom, and the United States favor this route for pre-departure prophylaxis where compliance monitoring is impractical.
- Subcutaneous:Alternative injection depth for specific patient populations with muscle atrophy or coagulation concerns; limited to specialized clinical settings.
- Intramuscular:Preferred depth for ViCPS and conjugate vaccines optimizing antigen presentation and reducing local reactogenicity; standard for pediatric schedules.
Injectable formats dominate procurement volumes; oral delivery is expanding most quickly in travel health segments.
Application:
Customer type segmentation distinguishes preventive routine immunization from reactive outbreak response with divergent tendering timelines and budget sources.
- Prevention:Routine immunization of pediatric and adolescent populations in endemic countries through scheduled national program doses. India's CDSCO-licensed manufacturers supply state health departments transitioning from campaign-style to calendar-based procurement.
- Outbreak Control:Reactive mass vaccination triggered by elevated typhoid incidence or antimicrobial resistance emergence. WHO and national emergency operations centers coordinate these deployments where rapid cold chain mobilization determines campaign reach.
- Travel Health:Pre-departure prophylaxis for tourists, business travelers, and military personnel visiting endemic regions. FDA and EMA pathways govern access to these segments with distinct stability data requirements.
- Pediatric Care:Age-specific formulations and dosing schedules for children under two years where conjugate vaccines demonstrate superior immunogenicity versus plain polysaccharide.
Prevention commands the largest procurement volumes; outbreak control is gaining share fastest as climate and urbanization patterns shift disease geography.
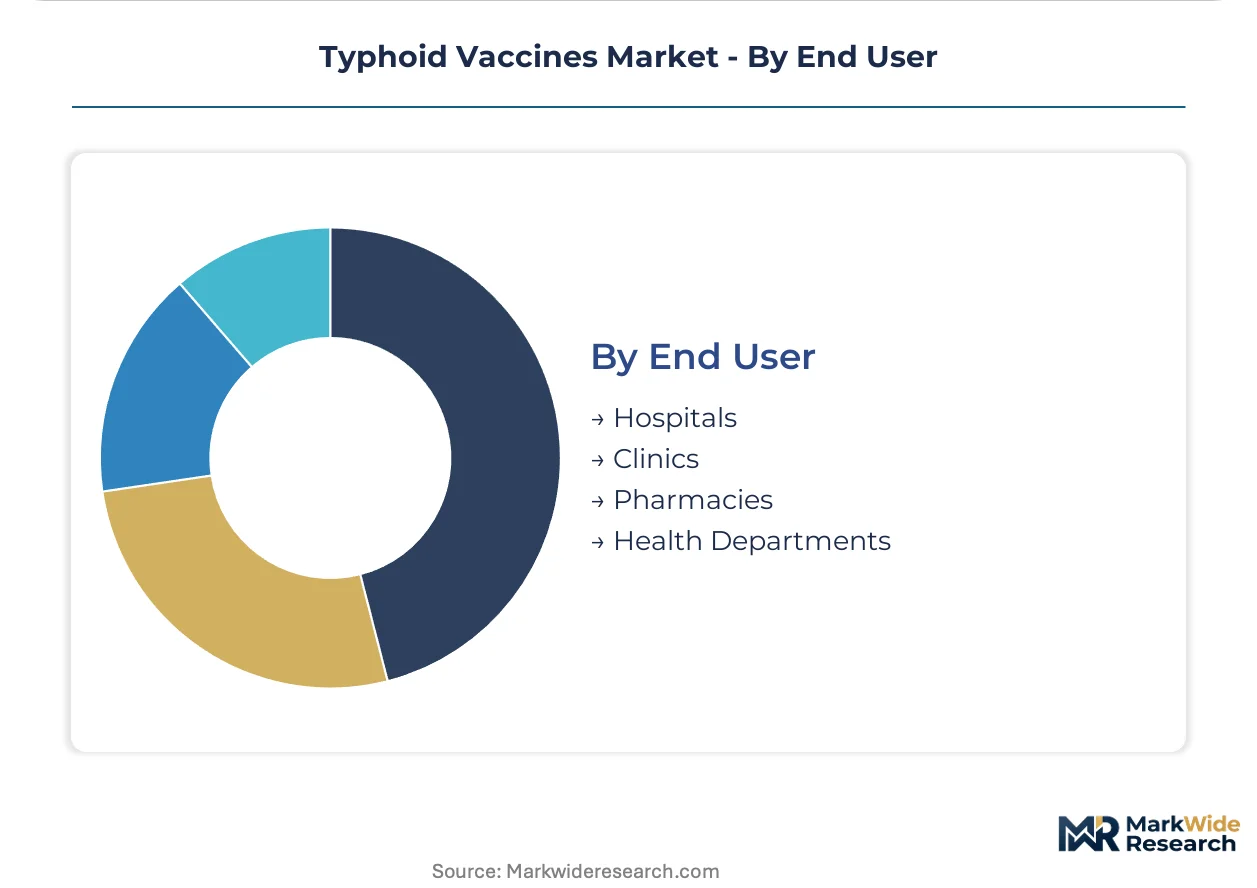
End User:
Supply concentration clusters around health departments consolidating previously fragmented state-level purchasing authority.
- Health Departments:Centralized national and state-level immunization programs managing procurement, distribution, and cold chain logistics for public sector vaccination. India's Ministry of Health and Nigeria's National Primary Health Care Development Agency exemplify this channel's transition to multi-year supply agreements.
- Hospitals:Tertiary care facilities administering vaccines to inpatients, surgical candidates, and immunocompromised populations requiring documented seroprotection. Urban medical centers in Karachi, Dhaka, and Lagos anchor demand in high-transmission settings.
- Clinics:Primary care and community health centers delivering outpatient vaccination with varying refrigeration capacity; last-mile distribution bottlenecks constrain effective reach in rural sub-Saharan Africa.
- Pharmacies:Retail and travel health pharmacy chains dispensing oral Ty21a and traveler-focused counseling in North American and European markets with private-pay reimbursement structures.
Health departments hold the largest share; pharmacies are climbing the fastest as travel health self-pay segments expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports Vi polysaccharide bulk antigen to manufacturers across sub-Saharan Africa and Southeast Asia, establishing the dominant trade corridor for typhoid vaccine raw materials. Procurement flows from Indian fermentation facilities to WHO-prequalified finishers in South Asia and East Africa anchor regional supply security. National immunization programs in recipient countries now negotiate multi-year tenders tied to these established supply routes.
India
Domestic demand from the Universal Immunization Programme consumes the majority of ViCPS output, with state health departments in Maharashtra and Uttar Pradesh anchoring procurement volume. CDSCO licensure requirements under the Drugs and Cosmetics Act govern manufacturing compliance for suppliers targeting public sector tenders. Hyderabad and Pune cluster conjugate vaccine fill-finish operations where Bharat Biotech and Biological E coordinate production campaigns.
Nigeria
The National Primary Health Care Development Agency consolidates previously fragmented state-level purchasing into centralized multi-year supply agreements for Gavi-eligible procurement. WHO prequalification standards determine manufacturer eligibility for federal tender participation, filtering supplier access to northern and southern health zones. Lagos and Kano serve as cold chain distribution hubs where federal vaccine stores buffer against last-mile refrigeration failures.
Pakistan
Pending national program adoption of conjugate vaccines creates procurement volume comparable to India's initial rollout phase, with federal health ministry negotiations underway for Typbar-TCV supply. The country's national pharmaceutical regulator evaluates dossier submissions for pediatric indication extensions. Karachi anchors import and distribution infrastructure for vaccines arriving through Port Qasim, with cold chain extension into Punjab and Sindh provinces.
Bangladesh
The Expanded Programme on Immunization maintains steady demand for single-dose Vi polysaccharide vaccines in school-based campaigns across Dhaka and Chittagong divisions. Directorate General of Drug Administration oversight applies to imported finished products and domestically repackaged supplies. Dhaka's centralized cold chain infrastructure supports distribution to district-level stores, though rural last-mile gaps persist in coastal and riverine areas.
Ethiopia
Federal Ministry of Health procurement prioritizes thermostable-compatible formulations where cold chain infrastructure remains underdeveloped in highland and pastoral regions. Ethiopian Food and Drug Authority registration pathways govern market entry for suppliers targeting outbreak response and preventive campaign dual use. Addis Ababa concentrates vaccine handling capacity with federal stores supplying regional hubs in Oromia and Amhara.
Typhoid Vaccines Market Competitive Landscape
On the supply side, the industry is consolidating around WHO-prequalified manufacturers with established fermentation capacity and conjugate chemistry expertise. Three strategic archetypes dominate: South Asian bulk antigen suppliers with backward integration into polysaccharide production, multinational finishers leveraging global distribution networks, and regional fill-finish specialists serving Gavi-eligible tenders. Capacity expansion and technology licensing represent the primary competitive moves, with mRNA platform transfers emerging as a secondary vector for pipeline positioning.
Within the South Asian supplier tier, Bharat Biotech and Biological E exemplify integrated manufacturing archetypes with domestic fermentation and conjugation capabilities. GlaxoSmithKline occupies a position among multinational finishers distributing WHO-prequalified products across endemic zones. Sanofi represents injectable delivery specialists sustaining channel presence in Francophone African markets through established hospital and clinic networks.
| Leading Market Players |
|---|
| Bharat Biotech |
| GlaxoSmithKline |
| Sanofi |
| Biological E |
| PT Bio Farma |
| PaxVax |
| SK Bioscience |
| Zydus |
| Indian Immunologicals |
| Others |
Value Network & Pricing Analysis
The Hyderabad-Port Qasim freight corridor shapes cost dynamics across South Asian typhoid vaccine distribution, compressing margins for Vi polysaccharide shippers while enabling three-tier pricing stratification between premium conjugate formulations, standard polysaccharide doses, and economy bulk tenders for Gavi-eligible procurement.
Pricing Analysis
Conjugate-to-polysaccharide-to-live-attenuated pricing gaps define procurement negotiations, with Typbar-TCV commanding premium positioning through extended pediatric immunological memory while ViCPS occupies mid-tier government tenders and Ty21a capsules serve self-pay travel health segments. Price differentiation hinges on WHO prequalification status and cold chain service bundling, with certified manufacturers capturing 40-60% premiums over non-prequalified alternatives. Pricing pressure stems from Gavi volume commitments forcing margin compression on polysaccharide supply, while national health departments in India and Nigeria exhibit highest price sensitivity and private travel clinics show lowest.
Supply Chain Analysis
Single-source vulnerability in purified Vi capsular antigen supply dominates risk exposure, with fermentation capacity clustering in India, South Korea, and Indonesia creating geographic concentration despite distributed finishing operations. Raw material dependencies center on Salmonella Typhi seed stocks, CRM197 carrier protein for conjugates, and specialized aseptic filling equipment. Tariff exposure between Indian bulk suppliers and African finishers threatens cost predictability for Gavi-funded programs. Distribution runs through federal vaccine stores in Lagos, Addis Ababa, and Karachi, with last-mile cold chain extension determining effective campaign reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Typhoid vaccine demand sits in early-cycle expansion as national immunization programs transition from outbreak response to routine pediatric schedules, with India's Universal Immunization Programme creating sustained procurement pull that Pakistan and Nigeria are positioned to replicate.
For Market Incumbents: Insulate manufacturing margins by securing captive Vi polysaccharide fermentation capacity in Hyderabad or Pune clusters, while accelerating WHO prequalification dossier consolidation to defend against emerging mRNA platform entrants. Regulatory bandwidth constraints at CDSCO and WHO create temporary moats for established conjugate suppliers. For New Entrants and Emerging Players: Pursue thermostable formulation partnerships with Ethiopian and Nigerian federal health ministries, where cold chain infrastructure gaps exclude incumbent liquid formulations. Pakistan's pending conjugate adoption represents the most penetrable geography, with fill-finish licensing agreements offering fastest route to Gavi-eligible tender participation. For Investors and Strategic Acquirers: Regional fill-finish specialists with WHO prequalification track records represent the priority acquisition archetype, offering bolt-on capacity without fermentation buildout timelines. Long-term viability hinges on mRNA platform transition velocity; the signal to watch is technology licensing announcement frequency from South Asian manufacturers to sub-Saharan African finishers.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | CDSCO-licensed manufacturers gain Gavi-eligible tender access through accelerated review cycles. |
| Conjugate Manufacturing Scale-Up | Hyderabad and Pune clusters expand CRM197 carrier-protein conjugation capacity for pediatric campaigns. |
| Thermostable Formulation Development | Ethiopian Federal Ministry procurement criteria favor ambient-temperature stability for highland distribution. |
| mRNA Platform Licensing | Technology transfer agreements shorten development timelines for nucleic acid-based typhoid candidates. |
| Cold Chain Infrastructure Partnership | Lagos and Kano federal stores buffer against last-mile refrigeration failures in northern Nigeria. |
Research Methodology
Cross-validation between primary interviews with vaccine development executives, regulatory affairs leads at CDSCO and WHO, national immunization program managers, and hospital procurement directors anchors the qualitative findings against secondary validation through WHO prequalification listings, ClinicalTrials.gov pipeline tracking, Gavi procurement disclosures, and national tender databases. Bottom-up manufacturer capacity assessments and top-down national program demand projections complete the analytical foundation.
Calibration against historical procurement volumes across product type, delivery mode, application, and end user segments shapes the analytical framework throughout the projection horizon. CAGRs derive from segmented demand modeling incorporating pediatric schedule expansion rates, conjugate chemistry adoption curves, and cold chain infrastructure investment patterns. Forecast inputs include Gavi multi-year purchase guarantee trajectories and CDSCO licensure timeline assumptions for emerging suppliers.
Sensitivities concentrate around WHO prequalification pathway revisions, Gavi funding continuity, and thermostable formulation breakthrough timing. Forecasts reflect documented assumptions on national program transition velocity from outbreak response to routine immunization. Material shifts in mRNA platform clinical success rates or conjugate vaccine cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Akabane Vaccines Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Chemotherapy Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Norethisterone Enanthate API Market