
 Biopharmaceutical Excipients Market | 2026-2036
Biopharmaceutical Excipients Market Size, Share, and Industry Trends Forecast 2026-2036
Biopharmaceutical Excipients Market Intelligence
The capital-intensity divergence between integrated excipient manufacturers and commodity suppliers is collapsing as biopharmaceutical clients demand dedicated, audit-ready production lines. Evonik Industries leverages its lipid nanoparticle expertise to anchor high-margin supply relationships with mRNA therapy developers. BASF SE sustains broad portfolio coverage across cellulose derivatives and polyols, competing through scale and pharmacopeial compliance breadth.
Biopharmaceutical excipients are inactive substances formulated alongside active pharmaceutical ingredients to enhance stability, bioavailability, or manufacturability of drug products, with parenteral grades requiring endotoxin limits below 0.25 EU/mL and particulate controls per USP <788>. Their primary purpose spans binding, filling, coating, and disintegrant functions that determine dosage form performance and shelf life. Sugars and polyols dominate current volume demand from lyophilized biologic formulations, while cellulose derivatives capture expanding share in controlled-release oral platforms. Pharmaceutical grade classifications command premium positioning over food or cosmetic grades due to batch certification burdens and dedicated equipment requirements.
FDA enforcement of ICH Q3D elemental impurity guidelines and USP-NF monograph updates directly determine which excipient lots qualify for commercial drug products, filtering supplier eligibility. EMA's Annex 1 revisions on sterile manufacturing and the EU GMP Chapter 5 expansion place concurrent pressure on European and US-based facilities to upgrade environmental controls. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards, as divergent test methods threaten to fragment qualification protocols and inflate dual-certification costs.
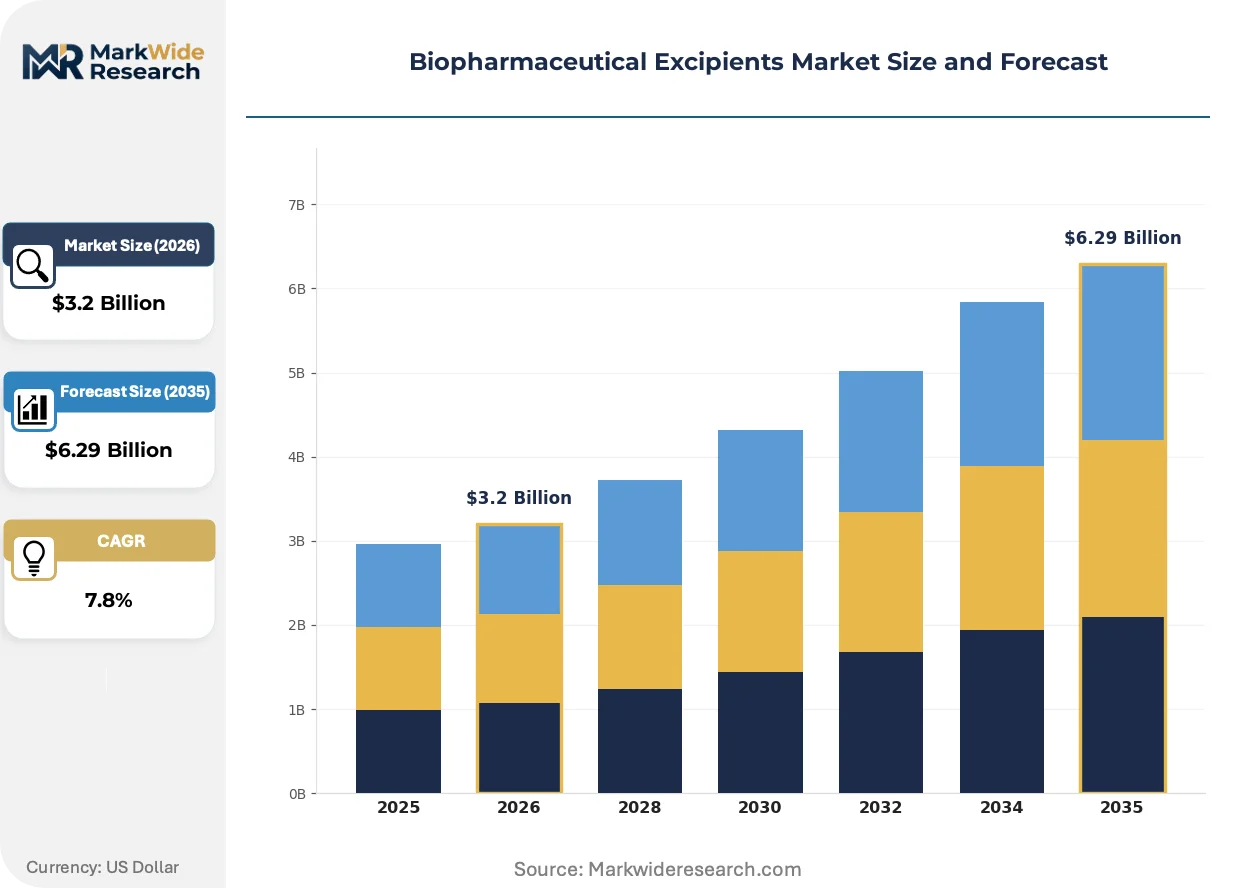
Market Dynamics
FDA's ICH Q3D enforcement and EMA's Annex 1 sterile manufacturing revisions are compressing supplier qualification timelines while biologics manufacturers demand dedicated, audit-ready excipient production lines with real-time endotoxin monitoring.
Growth Catalysts
- Lyophilized biologics expansion:mRNA and antibody-drug conjugate pipelines require cryoprotectant sugars and polyols in parenteral-grade purity. Formulation complexity is pulling excipient specifications toward sub-visible particulate controls.
- ICH Q3D compliance mandates:FDA enforcement of elemental impurity guidelines filters supplier eligibility to lots with certified low-lead, low-arsenic content. Drug sponsors now require excipient CoAs with elemental screening data.
- Boston-San Diego manufacturing clusters:United States biologics production concentration creates localized demand for just-in-time excipient delivery with temperature-controlled logistics and dedicated warehouse segregation.
Market Restraints
- High-purity cellulose ether input costs:Pharmaceutical-grade hydroxypropyl methylcellulose requires wood pulp with controlled lignin content. Pulp price volatility transmits directly to excipient margin compression.
- European supply concentration:Parenteral-grade polyol production clusters in Germany and France. Single-source dependencies for mannitol and trehalose create disruption risk during EMA facility inspections.
- Endotoxin testing bottleneck:Limulus amebocyte lysate reagent supply constraints limit batch release velocity. Test kit shortages extend excipient lot qualification timelines by 4-6 weeks.
Strategic Opportunities
- Indian CDMO integration:Contract development and manufacturing organizations in Hyderabad and Bangalore seek localized excipient sourcing to reduce import duty burdens. Domestic pharmaceutical-grade manufacturing investment qualifies under PLI scheme incentives.
- Lipid nanoparticle adjuvant demand:Ionizable cationic lipids and PEGylated phospholipids for mRNA vaccines represent formulation white space. Excipient suppliers with nucleic acid delivery expertise capture multi-year supply agreements.
- Continuous manufacturing compatibility:Direct compression-grade microcrystalline cellulose with enhanced flow properties enables real-time release testing. FDA's emerging guidance on continuous bioprocessing rewards excipient suppliers with validated process analytical technology data packages.
Industry Challenges
- Pharmacopeial harmonization gaps:Divergent USP, EP, and JP test methods for residual solvents and heavy metals force dual-certification protocols. Excipient manufacturers maintain separate analytical workflows for each geography.
- Cleanroom capex intensity:Dedicated parenteral-grade production lines require ISO 5 filling suites with isolator technology. Environmental monitoring infrastructure upgrades demand $15-25 million per facility.
- Biologics formulation scientist scarcity:Protein stabilization and excipient compatibility expertise concentrates at large pharma. Mid-tier excipient suppliers struggle to recruit talent for customer technical service roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopharmaceutical Excipients Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sugars, Starches, Cellulose Derivatives, Polyols Grade: Pharmaceutical Grade, Food Grade, Cosmetic Grade, Industrial Grade Functionality: Binders, Fillers, Coatings, Disintegrants Application: Oral Dosage Forms, Injectable Products, Topical Formulations, Others |
| Companies Covered | Roquette Frères, DFE Pharma, Evonik Industries, Corden Pharma, Ashland, BASF SE, Avantor, Colorcon, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopharmaceutical Excipients Market Strategic Shifts & Innovations
Excipient functionality is converging with drug delivery platform requirements as biologics manufacturers seek multi-functional materials that combine stabilization, controlled release, and manufacturability in single formulation components.
Engineered porous silica for protein stabilization is miniaturizing particle size distributions to sub-micron ranges while maintaining high surface area for adsorption. Biologics formulators at mRNA therapy developers are adopting these materials for lyophilized cake uniformity. The technology is miniaturizing traditional bulking agent volumes, enabling higher protein concentrations in reduced injection volumes.
EMA's Annex 1 revision on sterile manufacturing places continuous viable particle monitoring mandates on aseptic processing lines. European excipient suppliers are retrofitting facilities with rapid microbial detection systems and closed-loop sampling. Parenteral-grade polyol manufacturers in Germany face the steepest compliance timelines with 2024-2025 upgrade deadlines.
Biopharmaceutical sponsors now require excipient suppliers to provide extended characterization data packages beyond pharmacopeial monographs. Quality agreements specify forced degradation studies and extractables-leachables profiles. This specification inflation is most pronounced among United States-based biotechs with IND-stage biologics seeking to preempt FDA CMC review queries.
Biopharmaceutical Excipients Market Segmentation
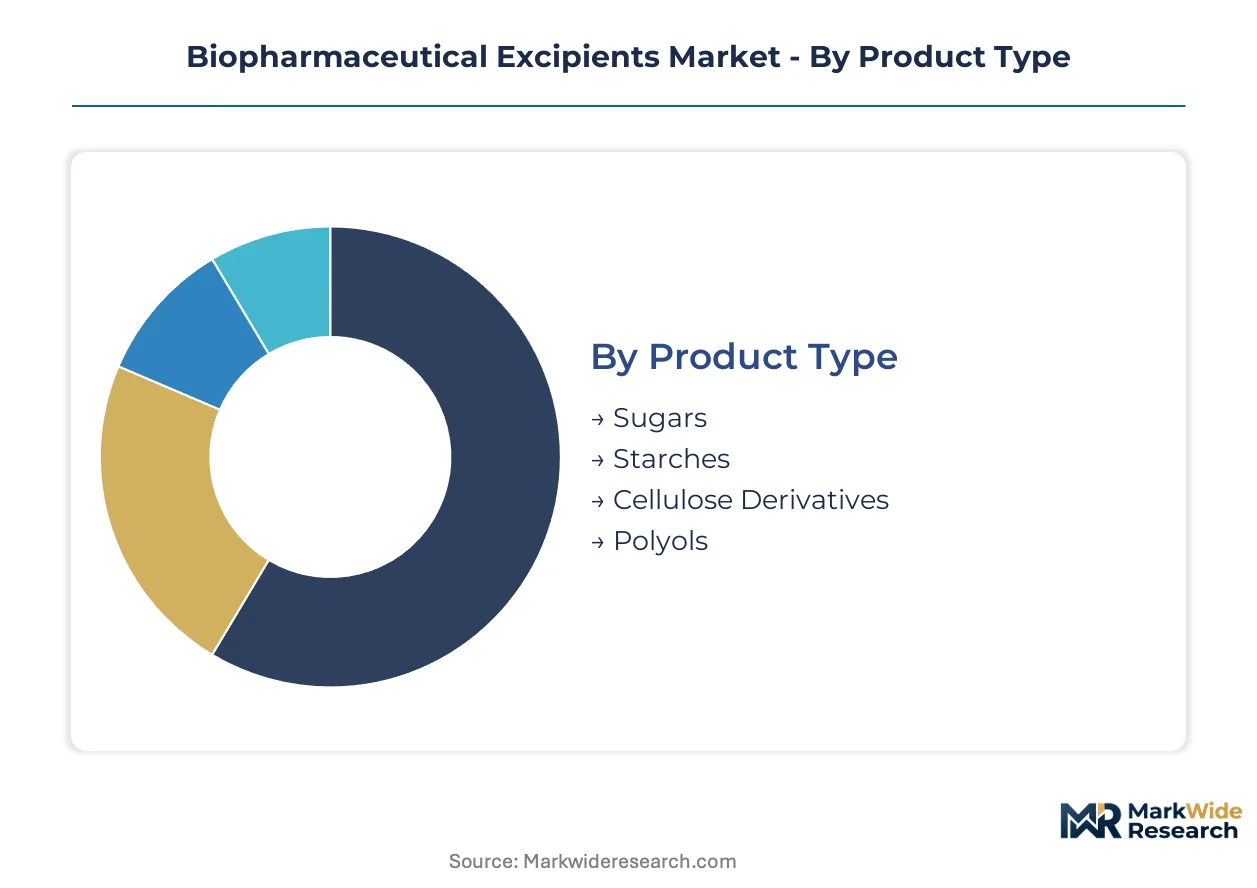
Excipient selection cascades through formulation development, manufacturing scale-up, and regulatory filing. Each segmentation axis—chemical class, purity tier, functional role, and dosage form—creates distinct procurement channels and supplier qualification burdens.
Product Type:
Channel distribution varies sharply by chemical stability and handling requirements; cryoprotectant sugars move through cold-chain logistics while cellulose derivatives utilize standard pharmaceutical warehousing.
- Sugars:Trehalose and sucrose dominate lyophilized biologic formulations for protein stabilization during freeze-thaw cycles. Demand concentrates in United States mRNA therapy manufacturing clusters where endotoxin specifications below 0.25 EU/mL are mandatory.
- Cellulose Derivatives:Hydroxypropyl methylcellulose and microcrystalline cellulose enable controlled-release matrices and direct-compression tableting. Oral solid dosage manufacturers in Germany and India drive volume through pharmacopeial-grade procurement contracts with certified low-lignin wood pulp sourcing.
- Starches:Pregelatinized starches function as disintegrants and binders in immediate-release tablets.
- Polyols:Mannitol and sorbitol serve as bulking agents and tonicity adjusters across parenteral and oral applications.
By volume, cellulose derivatives lead. By growth pace, sugars are climbing the fastest.
Grade:
Cost tier stratification separates dedicated manufacturing investments from commodity chemical sourcing.
- Pharmaceutical Grade:Batch-certified materials with complete CoA documentation, elemental impurity screening per ICH Q3D, and dedicated equipment protocols command premium positioning over lower tiers.
- Food Grade:Shared manufacturing lines with cosmetic applications reduce overhead but disqualify lots from parenteral drug submissions.
- Cosmetic Grade:Lower analytical burden suits topical delivery systems without systemic absorption requirements.
- Industrial Grade:Technical specifications exclude pharmaceutical applications entirely; bulk chemical sourcing for research use only.
Pharmaceutical grade captures margin concentration. Food grade sustains volume scale.
Functionality:
Application-driven formulation requirements determine excipient blending ratios and compatibility testing scope.
- Binders:Polyvinylpyrrolidone and starch derivatives ensure tablet integrity during compression and handling.
- Fillers:Lactose and microcrystalline cellulose provide bulk for low-dose potent APIs.
- Coatings:Enteric and film-coating polymers control dissolution profiles and protect moisture-sensitive actives.
- Disintegrants:Croscarmellose sodium and sodium starch glycolate accelerate tablet breakup for rapid API release.
Fillers dominate tonnage. Coatings show steepest specification inflation.
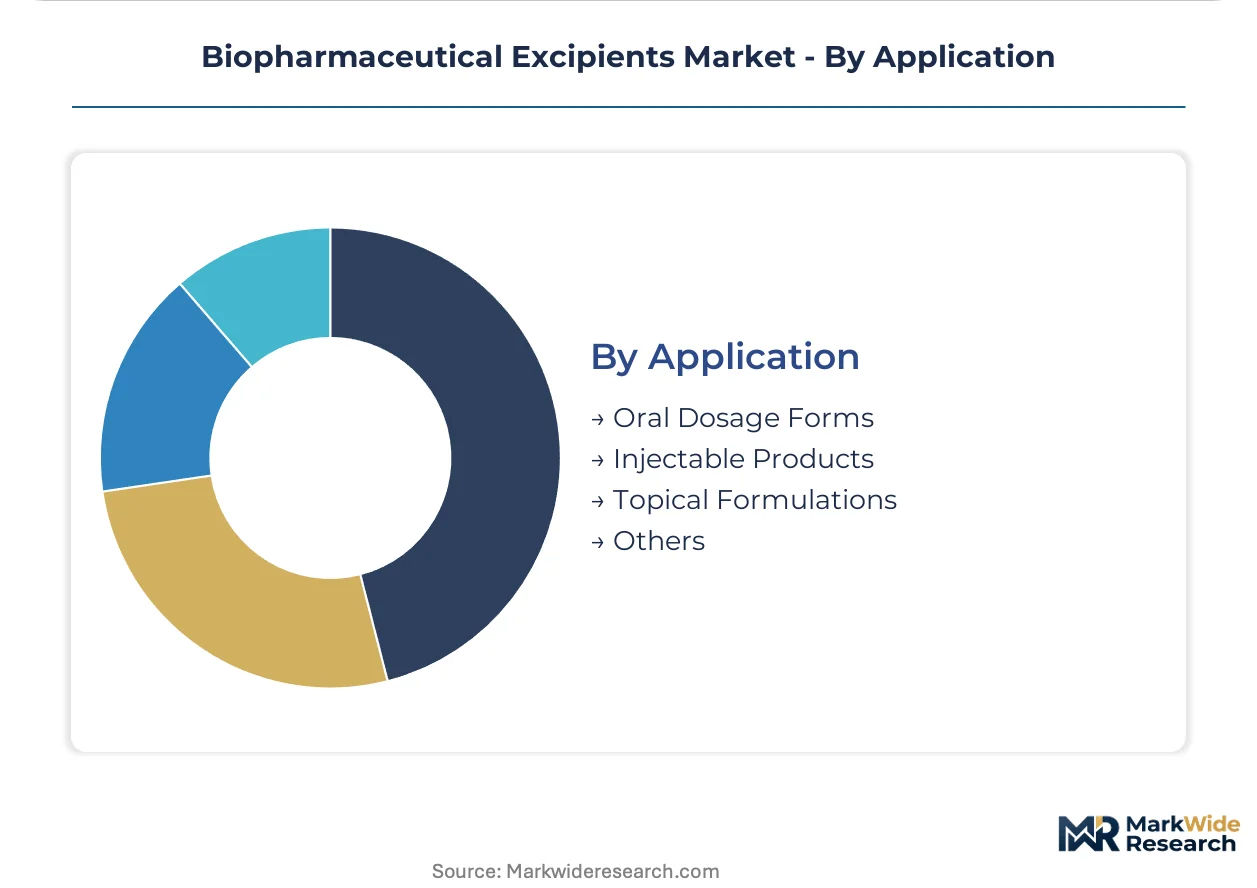
Application:
Customer type segmentation separates biologics manufacturers with dedicated quality agreements from generic solid-dosage producers.
- Injectable Products:Parenteral-grade excipients require sterile processing, sub-visible particulate controls per USP less than 788 greater than, and real-time endotoxin monitoring. Boston and San Diego biologics clusters source through audited suppliers with isolator technology.
- Oral Dosage Forms:Tablets and capsules utilize standard pharmaceutical-grade materials with broader supplier bases and compressed qualification timelines.
- Topical Formulations:Creams and ointments accept cosmetic-grade inputs where dermal absorption is minimal.
- Others:Inhalation and ophthalmic applications impose specialized particle size and sterility requirements.
Oral dosage forms lead by volume. Injectable products command value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit acute price sensitivity for standard pharmaceutical-grade materials, while United States biologics manufacturers absorb substantial premiums for parenteral-grade excipients with dedicated manufacturing lines and real-time endotoxin certification.
United States
FDA's ICH Q3D enforcement and USP-NF monograph updates filter supplier eligibility to lots with certified low-lead, low-arsenic content. The Biologics Price Competition and Innovation Act framework accelerates biosimilar filings, expanding demand for excipient CoAs with elemental screening data. Boston and San Diego manufacturing clusters source cryoprotectant sugars through audited suppliers with isolator technology and temperature-controlled logistics.
Germany
EMA's Annex 1 revision on sterile manufacturing mandates continuous viable particle monitoring on aseptic processing lines by 2024-2025. The country's national pharmaceutical regulator enforces concurrent pressure on facilities to upgrade environmental controls with ISO 5 filling suites. Parenteral-grade polyol manufacturers in the Rhineland face compressed compliance timelines for rapid microbial detection systems and closed-loop sampling retrofitting.
India
Contract development and manufacturing organizations in Hyderabad and Bangalore seek localized excipient sourcing to reduce import duty burdens on cryoprotectant sugars and cellulose derivatives. The PLI scheme incentivizes domestic pharmaceutical-grade manufacturing investment with production-linked incentives. Maharashtra and Gujarat house expanding formulation facilities that demand just-in-time delivery with dedicated warehouse segregation protocols.
China
NMPA alignment with ICH Q3D guidelines drives excipient lot qualification toward certified elemental impurity screening for commercial drug submissions. The country's national pharmaceutical regulator harmonizes pharmacopeial standards with USP and EP methods to reduce dual-certification burdens. Yangtze River Delta biologics clusters concentrate demand for lipid nanoparticle adjuvants with nucleic acid delivery expertise.
Switzerland
Swissmedic enforcement of sterile manufacturing standards elevates environmental monitoring requirements for parenteral-grade excipient production. The country's national pharmaceutical regulator emphasizes batch certification burdens and dedicated equipment protocols for commercial qualification. Basel and Zurich anchor high-value biologics manufacturing that commands premium positioning for pharmaceutical-grade classifications over food or cosmetic tiers.
Biopharmaceutical Excipients Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that fragments across functional categories and purity grades. The upper tier commands supply relationships through dedicated manufacturing lines and pharmacopeial compliance breadth, while specialists anchor positioning in cryoprotectant sugars, lipid nanoparticle adjuvants, or cellulose derivative matrices. Competitive moves concentrate on capacity expansion with isolator technology and strategic partnerships for nucleic acid delivery expertise.
Within the integrated leader tier, Evonik Industries and BASF SE exemplify archetypes that leverage scale and pharmacopeial compliance breadth to sustain broad portfolio coverage. Among specialty excipient suppliers, Roquette Frères occupies a position representing carbohydrate-based formulation expertise. These named entities anchor industry-level commentary on how vertical-tier positioning determines access to biologics manufacturing clusters with dedicated quality agreements.
| Leading Market Players |
|---|
| Roquette Frères |
| DFE Pharma |
| Evonik Industries |
| Corden Pharma |
| Ashland |
| BASF SE |
| Avantor |
| Colorcon |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
Capacity utilization at parenteral-grade manufacturing facilities shapes both supply concentration and price floors across the biopharmaceutical excipients sector. Dedicated ISO 5 filling suites with isolator technology require $15-25 million per facility upgrade, concentrating production among integrated manufacturers with audit-ready lines and compressing margin flexibility for commodity suppliers.
Pricing Analysis
After-sales revenue from technical service contracts and multi-year supply agreements drives lifetime value for excipient manufacturers serving biologics clusters. Three-tier pricing structure across pharmaceutical-grade, food-grade, and cosmetic-grade classifications separates parenteral-certified lots with endotoxin documentation from standard pharmaceutical materials. Cost compression in cellulose derivatives is intensifying because pharmaceutical-grade hydroxypropyl methylcellulose draws from controlled-lignin wood pulp with volatile input pricing. Generic solid-dosage manufacturers in India exhibit acute price sensitivity, while United States biologics sponsors absorb substantial premiums for dedicated manufacturing lines with real-time endotoxin certification.
Supply Chain Analysis
Just-in-time delivery preferences dominate biologics manufacturing clusters in Boston and San Diego, where temperature-controlled logistics and dedicated warehouse segregation minimize inventory carrying costs. Supply concentrates in Germany and France for parenteral-grade polyols, with mannitol and trehalose production anchored in Rhineland facilities facing EMA Annex 1 compliance deadlines. Raw material dependencies span controlled-lignin wood pulp for cellulose ethers, cryoprotectant sugar feedstocks, and Limulus amebocyte lysate reagents for endotoxin testing. Single-source vulnerability for mannitol and trehalose creates disruption risk during regulatory inspections. Distribution runs through audited supplier networks with quality agreements specifying forced degradation studies and extractables-leachables profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
mRNA therapy platform expansion and FDA's ICH Q3D enforcement are accelerating qualification timelines and compressing supplier eligibility, creating high-growth disruption as biologics manufacturers demand dedicated, audit-ready production lines.
For Market Incumbents: Secure isolator technology capacity additions in United States biologics corridors to anchor multi-year supply relationships with mRNA developers facing IND-stage CMC queries. Deepen backward integration into controlled-lignin wood pulp sourcing to defend margin position against input cost volatility in pharmaceutical-grade hydroxypropyl methylcellulose. For New Entrants and Emerging Players: Differentiate on nucleic acid delivery expertise by developing ionizable cationic lipids and PEGylated phospholipids for lipid nanoparticle adjuvants, a formulation white space with limited qualified suppliers. Target Hyderabad and Bangalore CDMOs seeking localized excipient sourcing under PLI scheme incentives, penetrating through reduced import duty burdens and just-in-time delivery capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among excipient suppliers with dedicated parenteral-grade manufacturing lines and multi-year quality agreements with United States biotech sponsors. Long-term viability hinges on pharmacopeial compliance breadth spanning USP, EP, and JP standards. Acquisition candidates with validated process analytical technology data packages for continuous manufacturing compatibility offer defensive positioning. Watch for EMA Annex 1 compliance deadline crossings as inflection indicators for European supply disruption and price tier separation.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Deployment | ISO 5 filling suites with closed-loop sampling satisfy FDA's enhanced purity requirements for parenteral-grade materials. |
| Backward Integration into Wood Pulp | Captive supply of controlled-lignin pulp defends hydroxypropyl methylcellulose margins against commodity volatility. |
| Lipid Nanoparticle Adjuvant Development | Ionizable cationic lipids capture multi-year supply agreements with mRNA therapy developers in Boston and San Diego. |
| Indian CDMO Partnership Expansion | Localized sourcing agreements with Hyderabad and Bangalore manufacturers qualify under PLI scheme production incentives. |
| Pharmacopeial Harmonization Investment | Unified analytical workflows for USP, EP, and JP standards reduce dual-certification costs and lot disqualification risk. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with biologics formulation scientists, regulatory affairs leads, excipient procurement managers, and CDMO supply chain directors; and secondary validation through FDA filings, EMA submissions, USP-NF monograph updates, and customs trade data. Bottom-up triangulation across dosage form demand models and top-down reconciliation with pharmacopeial certification databases anchored volume and value estimates.
Across the projection horizon, the analytical framework segmented demand by chemical class, purity tier, functional role, and dosage form application, with regional regulatory clusters modeled separately for ICH Q3D compliance intensity. CAGRs derived from weighted average of historical capacity expansion patterns and forward-looking biologics pipeline data, with lyophilized biologics expansion and lipid nanoparticle adjuvant demand as key forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained FDA ICH Q3D enforcement and EMA Annex 1 compliance timelines; material deviation in regulatory inspection intensity or Limulus amebocyte lysate reagent availability would warrant model refresh. Revision becomes warranted when endotoxin testing bottlenecks or single-source polyol disruptions cross supply security thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
North America HIV Drugs Market