
 Global Accounts Payable (AP) Automation Software Market | 2026-2036
Global Accounts Payable (AP) Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Accounts Payable (AP) Automation Software Market Foresight
Platform licensing revenue is reshaping competitive dynamics in AP automation. HighRadius leverages AI-native cash application tools to anchor its position in enterprise treasury workflows. Tipalti sustains cross-border payment automation dominance through multi-entity tax compliance capabilities. AvidXchange specializes in mid-market invoice-to-pay networks across property management and healthcare verticals.
Accounts Payable Automation Software encompasses cloud-native, on-premise, and hybrid platforms that digitize invoice capture, approval routing, payment execution, and reconciliation through optical character recognition, machine learning extraction, and API-based ERP integration. Its primary commercial purpose is to reduce manual data entry errors, accelerate payment cycles, and strengthen financial controls for finance departments. Cloud-based deployment leads adoption as enterprises prioritize scalable infrastructure with minimal IT overhead, while invoice processing functionality captures the deepest margin pools due to persistent labor-cost savings. SME end users represent the fastest-expanding buyer segment as subscription pricing democratizes access previously reserved for large enterprises.
FDA oversight of financial data integrity in healthcare payment workflows, EU GDPR requirements for supplier data handling, and SEC disclosure rules on internal controls collectively elevate demand for audit-ready automation platforms with immutable transaction logs. ISO 27001 certification has become a baseline procurement filter for financial institutions evaluating vendor shortlists. Stakeholders must weigh interoperability investments against the risk of vendor lock-in as ERP consolidation accelerates across multinational finance operations.
Market Dynamics
ERP consolidation across multinational finance operations is compressing vendor ecosystems, forcing AP automation providers to deepen API interoperability or risk displacement from core treasury workflows.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises face audit-trail requirements for automated financial decisions, accelerating procurement of platforms with immutable logging capabilities.
- Cloud infrastructure scalability:Manufacturing and retail sectors prioritize subscription-based deployment models that minimize IT overhead while supporting multi-entity operations.
- India's legacy modernization:Financial infrastructure upgrades across Indian enterprises are creating concentrated demand for invoice-to-pay digitization tools.
Market Restraints
- ISO 27001 certification costs:Baseline procurement filters at financial institutions impose compliance burdens that exclude smaller vendors from shortlists.
- Legacy ERP fragmentation:Proprietary data formats in entrenched on-premise systems create technical friction for API-based integration projects.
- Vendor lock-in risk:Concentration of enterprise treasury workflows within single platforms limits buyer negotiating leverage and switching flexibility.
Strategic Opportunities
- SME subscription democratization:Tiered pricing models are unlocking mid-market segments previously reserved for large enterprises with dedicated IT resources.
- Healthcare payment integrity:FDA oversight of financial data workflows in medical supply chains elevates demand for audit-ready automation with granular transaction tracking.
- Machine learning and OCR convergence:Hybrid extraction technologies are reducing error rates in unstructured invoice processing, opening new vertical applications.
Industry Challenges
- Cross-border tax complexity:Multi-entity operations require real-time compliance with divergent withholding and reporting rules across jurisdictions.
- Skill scarcity in treasury technology:Finance departments lack personnel capable of configuring advanced approval routing and reconciliation workflows without vendor dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Accounts Payable (AP) Automation Software Market |
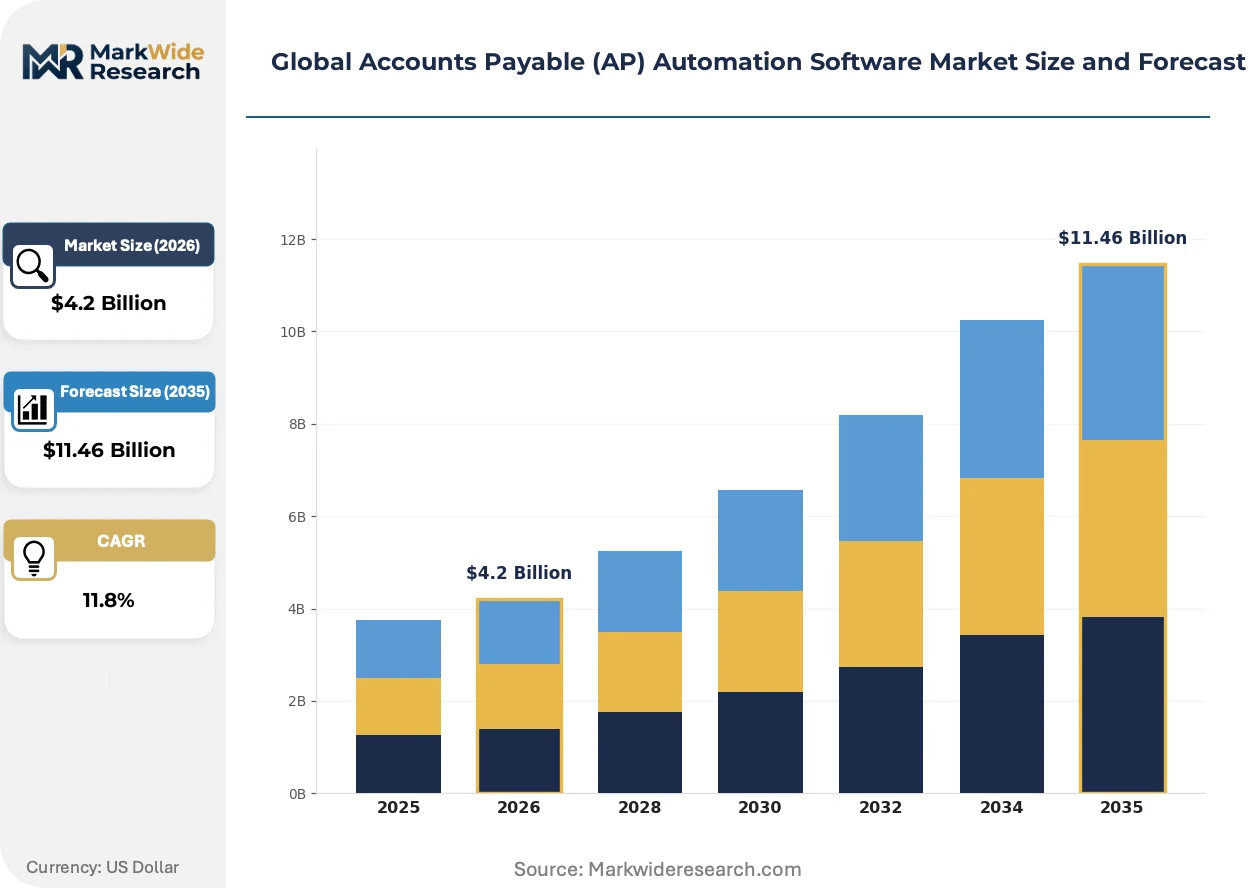
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $11.46 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: SMEs, Large Enterprises, Public Sector, Financial Institutions Functionality: Invoice Processing, Payment Management, Compliance Management, Data Analytics Integration: ERP Systems, Banking Interfaces, E-commerce Platforms, Document Management |
| Companies Covered | Tipalti, Fraxion, Stampli, Yooz, HighRadius, Coupa, Paylocity, Ramp, AvidXchange, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Accounts Payable (AP) Automation Software Market Shifts & Advancements
Artificial intelligence is embedding deeper into financial workflows, shifting competitive advantage from basic digitization toward predictive cash management and autonomous exception handling.
Intelligent document processing combining optical character recognition with natural language extraction is digitizing unstructured supplier invoices at scale. Mid-market property management and healthcare buyers are adopting these tools fastest, driven by high document volumes and thin margin pressure. The technology is digitizing previously manual verification steps, compressing processing cycles from days to hours.
The EU AI Act's risk-based classification system imposes documentation requirements on high-stakes automated financial decisions. Enterprises deploying machine learning for payment approvals must maintain explainable audit trails or face operational restrictions. German and French firms are responding by prioritizing vendors with built-in algorithmic transparency features.
Buyer preference is tilting toward outcome-based pricing tied to measurable efficiency gains rather than per-seat licensing. Channel relationships are restructuring as direct vendor relationships displace traditional systems integrators for core AP functions. This pattern is most pronounced in United States mid-market segments where finance leaders demand ROI guarantees.
Global Accounts Payable (AP) Automation Software Market Segmentation
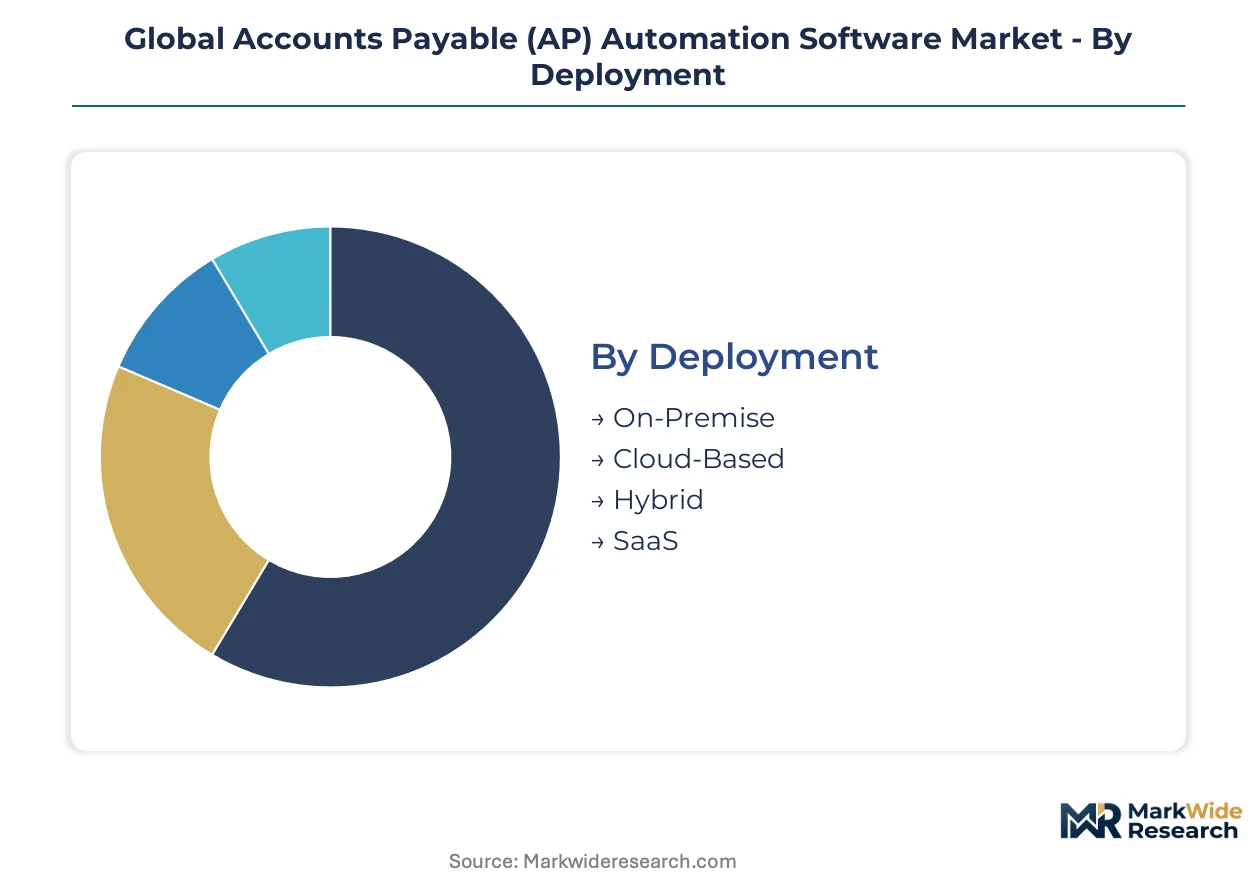
AP automation software segments by deployment speed, user scale, functional depth, and integration architecture. Each dimension carries distinct margin profiles and vendor competitive requirements. Procurement cycles vary from weeks for cloud-native SME tools to years for hybrid enterprise implementations.
Deployment:
Cloud-based platforms turn over fastest with monthly subscription renewals, while on-premise installations cycle across multi-year depreciation schedules. SaaS models compress implementation timelines from quarters to weeks.
- Cloud-Based:Multi-tenant architectures enable zero-infrastructure scaling for manufacturing and retail enterprises across Germany and India. Subscription economics eliminate capital expenditure barriers that previously gated mid-market access. Demand concentrates in United States manufacturing hubs where IT overhead reduction drives procurement decisions.
- SaaS:Pre-configured workflows with API-native ERP connectors accelerate time-to-value for finance teams lacking dedicated technical resources. Indian enterprises modernizing legacy infrastructure represent the steepest expansion trajectory as RBI guidelines push digitization.
- On-Premise:Air-gapped installations persist in European financial institutions subject to GDPR data residency mandates and SEC disclosure rules on internal controls.
- Hybrid:Split architectures accommodate sensitive payment data on-premise while routing invoice capture through cloud OCR services, common in German automotive supply chains.
On-premise dominates installed base in legacy-heavy European banking. SaaS is where expansion concentrates among mid-market buyers seeking minimal IT dependency.
End User:
Cost tier stratification separates enterprise buyers with dedicated procurement teams from SMEs purchasing through self-service channels. Public sector segments impose unique compliance overhead that reshapes vendor economics.
- Large Enterprises:Multi-entity tax compliance requirements and cross-border payment automation drive platform selection across United States and German multinational treasury operations. Tipalti's dominance in this tier reflects withholding-rule complexity that smaller vendors cannot address.
- SMEs:Tiered subscription pricing democratizes access to invoice-to-pay automation previously reserved for Fortune 500 treasury departments. Property management and healthcare verticals in the United States mid-market adopt these tools fastest due to high document volumes and thin margin pressure.
- Financial Institutions:ISO 27001 certification serves as baseline procurement filter, excluding smaller vendors from shortlists and compressing the addressable vendor ecosystem.
- Public Sector:Immutable audit-trail requirements under EU AI Act compliance mandates accelerate procurement of platforms with explainable algorithmic decision logging in French and German government entities.
Large enterprises dominate installed base with concentrated vendor relationships. SMEs represent the segment climbing fastest as subscription pricing removes IT resource barriers.
Functionality:
Application depth separates commodity digitization tools from platforms embedding predictive intelligence. Invoice processing captures deepest margin pools due to persistent labor-cost arbitrage.
- Invoice Processing:OCR-ML hybrid extraction technologies digitize unstructured supplier documents at scale, compressing processing cycles from days to hours. AvidXchange's specialization in this layer reflects persistent demand for error reduction in high-volume environments.
- Payment Management:Real-time payment execution and reconciliation automation anchor enterprise treasury workflows. HighRadius leverages AI-native cash application tools to defend position in this functional tier.
- Compliance Management:Automated audit trails satisfy FDA oversight of financial data integrity in healthcare payment workflows and SEC disclosure requirements on internal controls.
- Data Analytics:Predictive cash management and autonomous exception handling shift competitive advantage from basic digitization toward forward-looking financial intelligence.
Invoice processing dominates installed base with proven ROI metrics. Data analytics is where expansion concentrates as AI embedding deepens competitive differentiation.
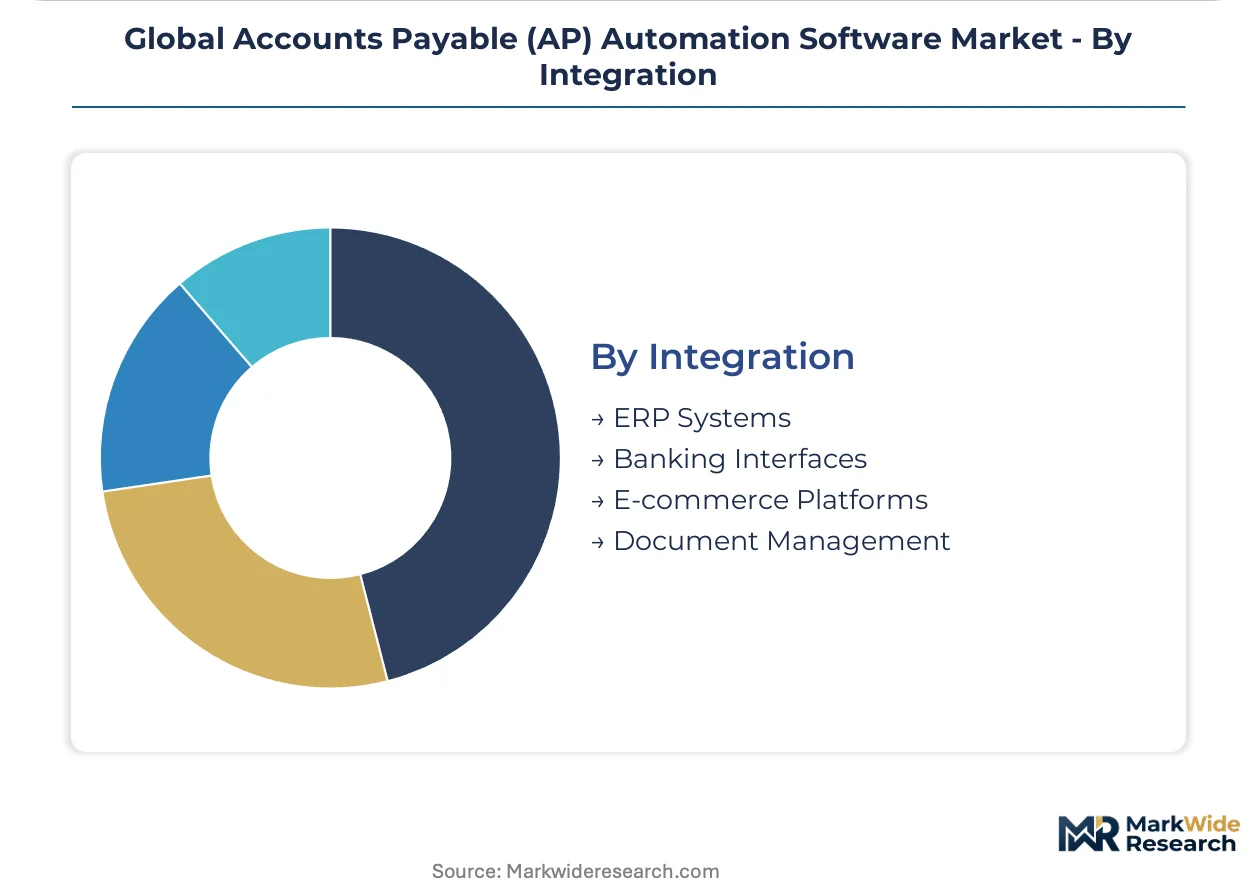
Integration:
Architecture maturity determines switching costs and vendor lock-in exposure. ERP consolidation across multinational finance operations compresses interoperability requirements.
- ERP Systems:Pre-built connectors to SAP, Oracle, and Microsoft Dynamics reduce implementation friction. Legacy ERP fragmentation in proprietary data formats creates technical barriers that API-native platforms must overcome.
- Banking Interfaces:Direct treasury connectivity enables real-time payment execution and cash position visibility. Multi-bank aggregation complexity favors established vendors with institutional banking relationships.
- E-commerce Platforms:Automated supplier onboarding and payment reconciliation for marketplace sellers. This segment expands most quickly as B2B marketplaces proliferate across Indian and United States digital supply chains.
- Document Management:Centralized repository integration with immutable logging satisfies EU AI Act documentation requirements for high-stakes automated financial decisions.
ERP systems dominate installed base with entrenched workflow dependencies. E-commerce platforms represent the segment gaining share fastest as digital supply chain transformation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor concentration clusters in the United States, Germany, and India where legacy financial infrastructure modernization drives procurement velocity. Cloud-native platforms capture disproportionate share in manufacturing hubs and retail corridors across these three markets.
United States
Mid-market property management and healthcare verticals adopt invoice-to-pay automation fastest due to high document volumes and thin margin pressure. SEC disclosure rules on internal controls elevate demand for audit-ready platforms with immutable transaction logs. Finance teams in Chicago and Dallas manufacturing corridors prioritize subscription-based deployment models that minimize IT overhead.
Germany
Automotive supply chains in Bavaria and Baden-Württemberg deploy hybrid architectures accommodating sensitive payment data on-premise while routing invoice capture through cloud OCR services. EU AI Act risk-based classification imposes documentation requirements on automated financial decisions. Frankfurt and Stuttgart treasury operations prioritize vendors with built-in algorithmic transparency features.
India
RBI guidelines push digitization across enterprises modernizing legacy financial infrastructure, creating concentrated demand for invoice-to-pay tools. Mumbai and Bangalore finance hubs drive adoption of SaaS models with pre-configured workflows and API-native ERP connectors. Subscription economics eliminate capital expenditure barriers that previously gated mid-market access.
United Kingdom
GDPR data residency mandates and immutable audit-trail requirements accelerate procurement of platforms with explainable algorithmic decision logging. London financial institutions apply ISO 27001 certification as baseline procurement filter, compressing the addressable vendor ecosystem. Fintech corridors in Manchester and Edinburgh expand adoption among SMEs through tiered pricing models.
France
EU AI Act compliance mandates drive French government entities toward platforms with automated audit-trail capabilities. Paris and Lyon manufacturing enterprises prioritize cross-border payment automation with real-time compliance for divergent withholding rules. Healthcare payment integrity requirements under national pharmaceutical regulator oversight elevate demand for granular transaction tracking.
Global Accounts Payable (AP) Automation Software Market Competitive Landscape
AI-native treasury specialists and cross-border compliance platforms split the market between predictive cash management and multi-entity tax automation. The vendor ecosystem compresses as ERP consolidation forces providers to deepen API interoperability or risk displacement. Three archetypes dominate: enterprise treasury workflow anchors, mid-market invoice-to-pay networks, and SME-focused subscription platforms. Competitive moves concentrate on strategic partnerships for banking connectivity and portfolio diversification into adjacent compliance management functions.
Within the enterprise treasury tier, HighRadius and Tipalti exemplify divergent specialization strategies. HighRadius occupies a position among AI-native cash application providers anchoring position in predictive financial workflows. Tipalti sits within the cross-border compliance archetype, representing multi-entity tax automation capabilities that address withholding-rule complexity. AvidXchange anchors the mid-market invoice-to-pay network segment, exemplifying vertical specialization in high-volume document environments.
| Leading Market Players |
|---|
| Tipalti |
| Fraxion |
| Stampli |
| Yooz |
| HighRadius |
| Coupa |
| Paylocity |
| Ramp |
| AvidXchange |
| Others |
Supply & Pricing Matrix
The Frankfurt-Dubai data corridor carries escalating bandwidth costs that compress margins for cloud-native AP automation vendors while amplifying price differentiation between ISO 27001-certified enterprise tiers and uncertified alternatives. Supply concentration among hyperscale infrastructure providers in Germany, India, and the United States feeds this dynamic, as procurement teams weigh residency-compliant deployments against subscription economics.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European deployments, separating premium audit-trail-enabled platforms from standard cloud offerings lacking algorithmic transparency features. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and vertical integration depth, with healthcare and financial institutions absorbing premium tiers for FDA and SEC compliance. Cost compression in the standard tier intensifies because API-native vendors crowd mid-market segments with minimal differentiation. SMEs exhibit highest price sensitivity, while multinational treasury operations demonstrate lowest elasticity due to switching costs and regulatory exposure.
Supply Chain Analysis
AWS, Microsoft Azure, and Google Cloud Platform hold dominant capacity positions across AP automation infrastructure provisioning. Geographic supply concentration clusters in Germany, India, and the United States, with raw material dependencies spanning semiconductor fabrication for OCR-ML accelerators, submarine cable capacity for transatlantic data transit, and specialized labor pools for ERP integration engineering. Single-source vulnerability in cloud infrastructure creates systemic exposure to regional outage events. Distribution runs through direct vendor relationships displacing traditional systems integrators, particularly in United States mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's risk-based classification system constitutes a regulatory inflection accelerating procurement of explainable automation platforms and compressing vendor ecosystems unprepared for compliance documentation burdens.
For Market Incumbents: Harden algorithmic transparency capabilities to defend against emerging AI-native entrants exploiting compliance gaps in legacy architectures. Deepen API interoperability investments to counter ERP consolidation displacement risk. Prioritize ISO 27701 privacy certification alongside baseline ISO 27001 to capture GDPR-sensitive European financial institutions.
For New Entrants and Emerging Players: Pursue SME subscription democratization in Indian manufacturing hubs where RBI digitization mandates outpace local vendor capacity. Target outcome-based pricing models with ROI guarantees to displace per-seat licensing incumbents in United States property management verticals. Leverage pre-configured ERP connectors as primary go-to-market wedge against implementation-heavy alternatives.
For Investors and Strategic Acquirers: AI-native cash application specialists with embedded treasury workflow positions represent compelling acquisition targets given predictive analytics convergence. Long-term viability hinges on platform stickiness through banking relationship depth rather than invoice processing commoditization. Watch for FDA enforcement patterns in healthcare payment integrity as inflection indicator for compliance-management module demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-native ERP connectors reduce implementation friction for SAP and Oracle environments. |
| Strategic Partnership | Banking connectivity alliances enable real-time treasury execution for multinational operations. |
| Acquisition of Specialist Firm | OCR-ML hybrid extraction capabilities address unstructured invoice volumes in healthcare verticals. |
| Geographic Expansion | Indian market entry captures RBI-mandated legacy modernization demand in Mumbai finance hubs. |
| Product Launch | Explainable algorithmic decision logging satisfies EU AI Act audit-trail requirements for German enterprises. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EU regulatory submissions, and cloud infrastructure capex disclosures. Primary interviews with CFOs, treasury operations directors, ERP integration specialists, and procurement leads at manufacturing and healthcare enterprises inform demand-side dynamics. Secondary validation draws from RBI circulars, FDA guidance documents, and ISO certification registries. Bottom-up deployment modeling and top-down market sizing triangulate volume estimates across the analysis window.
Forecast inputs span deployment architecture, organization scale, functional depth, integration complexity, and regional regulatory cluster. Modeled segments include cloud-based, SaaS, on-premise, and hybrid deployment alongside large enterprise, SME, financial institution, and public sector end users. CAGRs derive from regression analysis of subscription renewal velocity and implementation pipeline conversion. Industry-specific inputs incorporate EU AI Act compliance timeline acceleration and India's legacy infrastructure replacement cycles.
Sensitivities concentrate around regulatory enforcement intensity, hyperscale infrastructure pricing volatility, and ERP consolidation velocity. Forecasts reflect documented assumptions on compliance adoption curves and cloud migration rates. Quarterly review of FDA healthcare payment guidance, RBI digitization mandates, and EU AI Act implementing acts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Payment Analytics Software Market
Payments
B2B Payments Platform Market
Payments
In-Vehicle Payment Services Market
Payments
Middle East and Africa Buy Now Pay Later Services Market
Payments
Mexico Real Time Payments Market
Payments
France POS Terminal Market
Payments
Latin America Mobile Payment Market
Payments
Denmark Mobile Payments Market
Payments
Third Party Payment Market
Payments
Voice-Based Payments Market
Payments
Europe POS Terminal Market
Payments
Saudi Arabia Payments Market
Payments
Global Master Card Market
Payments
US Gift Card and Incentive Card Market
Payments
Hong Kong Payments Market
Payments
Singapore Remittance Market