
 B2B Payments Platform Market | 2026-2036
B2B Payments Platform Market Size, Share, and Industry Trends Forecast 2026-2036
B2B Payments Platform Market Outlook
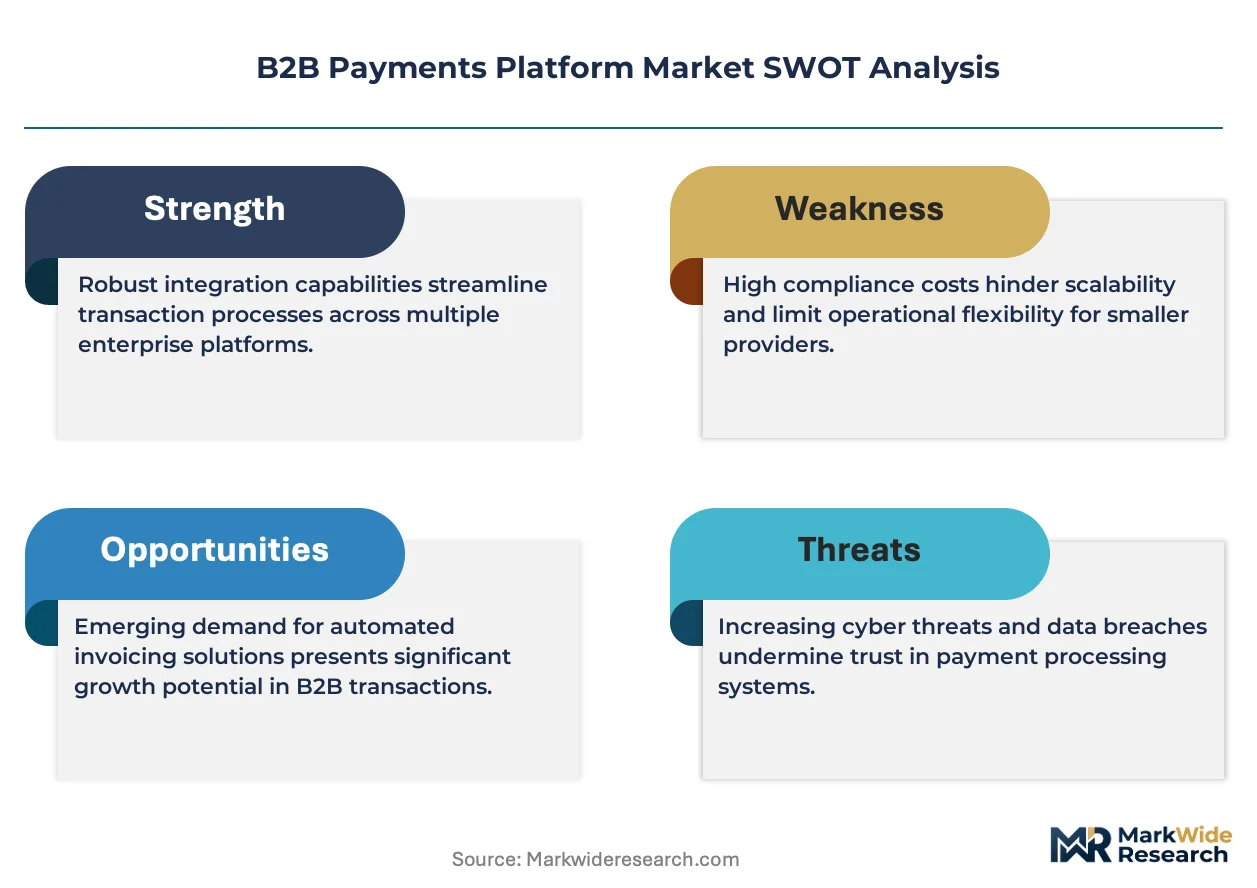
ISO 20022 is pivoting the cost-of-entry calculus for new B2B payments infrastructure, forcing platforms to overhaul messaging stacks or lose correspondent bank connectivity. Stripe leverages its developer-centric API architecture to sustain dominance in embedded finance integrations. Mastercard anchors its position through proprietary virtual card networks that compete directly with ACH modernization efforts.
A B2B payments platform is a software infrastructure layer that automates commercial fund transfers between businesses through API-driven orchestration of payment rails, typically processing transactions in ISO 8583 or ISO 20022 formats with settlement cycles ranging from real-time to three business days. Its primary purpose is to replace manual accounts payable and receivable workflows with programmable, auditable, and reconcilable payment execution. Cloud-based deployment models now lead adoption curves as mid-market firms abandon on-premises treasury workstations, while ACH transfer volumes represent the deepest margin pool despite slower growth than real-time alternatives. Digital wallet penetration within manufacturing supply chains is expanding fastest where supplier onboarding friction historically blocked electronic adoption.
The US Federal Reserve's FedNow service and the European Central Bank's TARGET Instant Payment Settlement framework are reshaping real-time liability management expectations for corporate treasurers. HIPAA transaction standards in US healthcare and the EU's PSD2 strong customer authentication requirements further segment compliance burdens by vertical. Stakeholders must monitor which payment rail—real-time, same-day ACH, or virtual card—achieves critical mass in their target industry vertical before committing platform development resources.
Market Dynamics
ISO 20022 migration timelines are compressing vendor consolidation windows as correspondent banks sever connectivity to non-compliant platforms, forcing infrastructure providers to rebuild messaging stacks or exit cross-border transaction processing entirely.
Growth Catalysts
- Real-time payment rail proliferation:FedNow in the United States and TARGET Instant Payment Settlement in Europe are creating immediate settlement expectations among corporate treasurers, pulling mid-market firms off batch-based ACH systems.
- Vertical SaaS embedding:Manufacturing ERP vendors and healthcare practice management software are white-labeling payment orchestration to capture interchange revenue, converting software buyers into payment volume originators.
- API standardization:Open banking frameworks under PSD2 in Europe are normalizing programmatic access to commercial bank accounts, reducing onboarding friction for platform-to-bank connectivity.
Market Restraints
- Correspondent banking concentration:Cross-border dollar clearing remains dominated by a narrow tier of US-headquartered global systemically important banks, creating single-point-of-failure risk for platform settlement.
- Legacy ERP integration costs:On-premises SAP and Oracle installations in industrial sectors require custom middleware development, inflating implementation timelines and suppressing mid-market adoption.
- Regulatory fragmentation:HIPAA transaction standards in US healthcare, PSD2 strong customer authentication in Europe, and divergent data localization rules across Asia-Pacific multiply compliance architecture costs for global platforms.
Strategic Opportunities
- Supplier finance digitization:Manufacturing supply chains in Germany and Japan retain high check-usage rates among tier-two vendors, creating white space for dynamic discounting and supply chain finance platforms.
- Virtual card network expansion:Commercial card products are displacing traditional trade credit in professional services verticals where spend management and reconciliation automation outweigh interchange cost sensitivity.
- Central bank digital currency infrastructure:Pilot programs by the European Central Bank and Bank of England are opening vendor selection processes for wholesale CBDC settlement rails.
Industry Challenges
- ISO 20022 talent scarcity:Message mapping expertise sits concentrated within legacy correspondent banking technology teams, constraining platform build-out velocity.
- Multi-rail reconciliation complexity:Treasurers operating across real-time, same-day ACH, and virtual card networks face fragmented data formats that erode straight-through processing rates.
- Bank partnership negotiation leverage:Platforms lack balance sheet depth to secure preferential pricing on Fedwire or CHIPS access, compressing unit economics at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B2B Payments Platform Market |
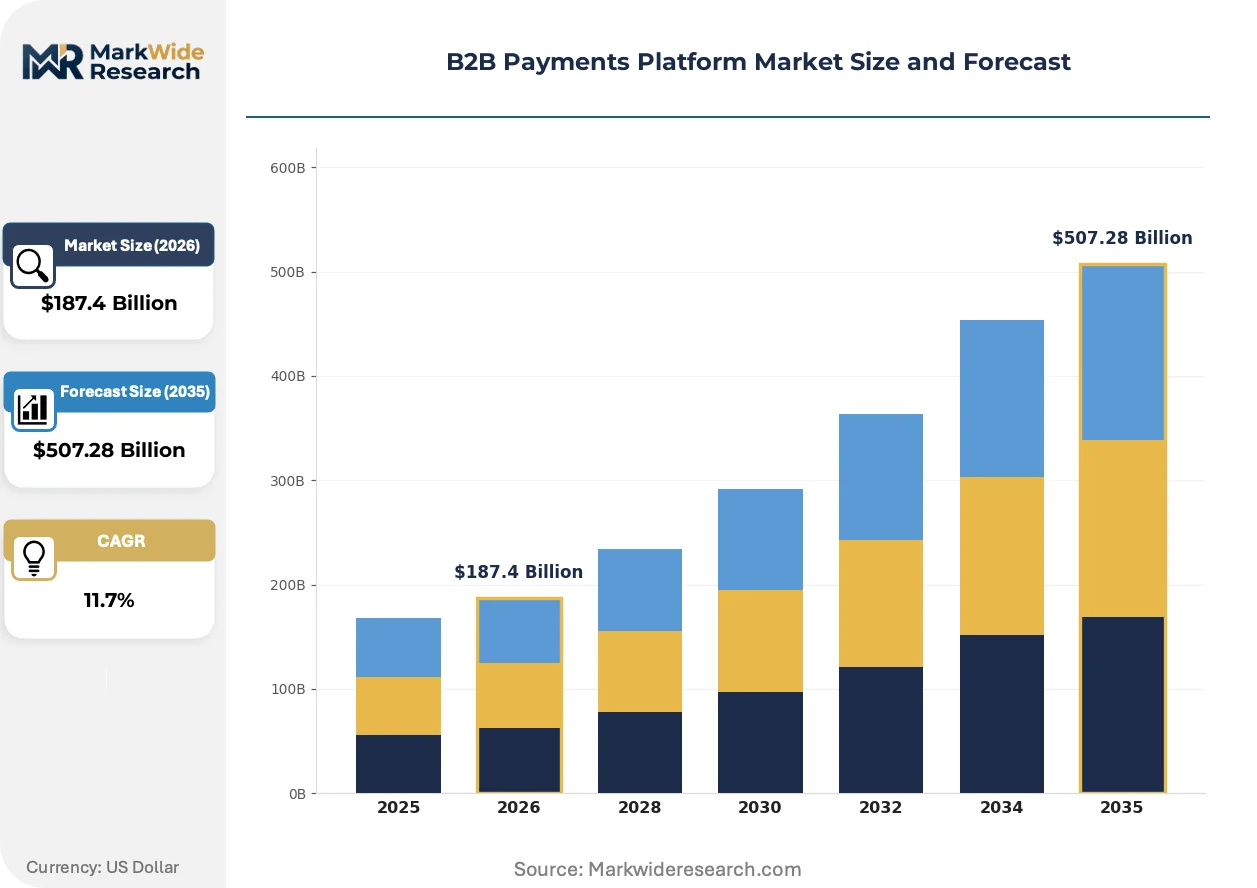
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $507.28 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, ACH Transfer, Wire Transfer, Digital Wallet Industry Vertical: Manufacturing, Retail, Healthcare, Education Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Service Transaction Size: Small, Medium, Large, Enterprise |
| Companies Covered | Stripe, PayPal, Mastercard, Visa, Payoneer, Bill.com, Ramp, AvidXchange, Fiserv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B2B Payments Platform Market Strategic Shifts
Payment orchestration layers are absorbing treasury workstation functionality as real-time visibility replaces batch reconciliation, compressing the vendor landscape toward unified API-first platforms.
Artificial intelligence-powered cash forecasting is automating liquidity positioning decisions previously executed through manual spreadsheet models. Mid-market manufacturers with seasonal working capital swings are deploying these tools fastest, compressing treasury staffing ratios from ten-to-one to four-to-one against payment volume.
Europe's Digital Operational Resilience Act is mandating business continuity testing for critical payment service providers, forcing platform operators to document failover procedures across multi-cloud architectures. Payment initiation service providers under PSD3 face heightened liability for outage-related corporate treasury losses, accelerating investment in redundant rail connectivity.
Buyer expectations for embedded payment experiences are displacing standalone treasury portal subscriptions. Construction and logistics verticals in the United States now demand invoice-to-payment workflows within project management software, collapsing the procurement-to-settlement cycle from days to minutes and eroding standalone platform attach rates.
B2B Payments Platform Market Segmentation
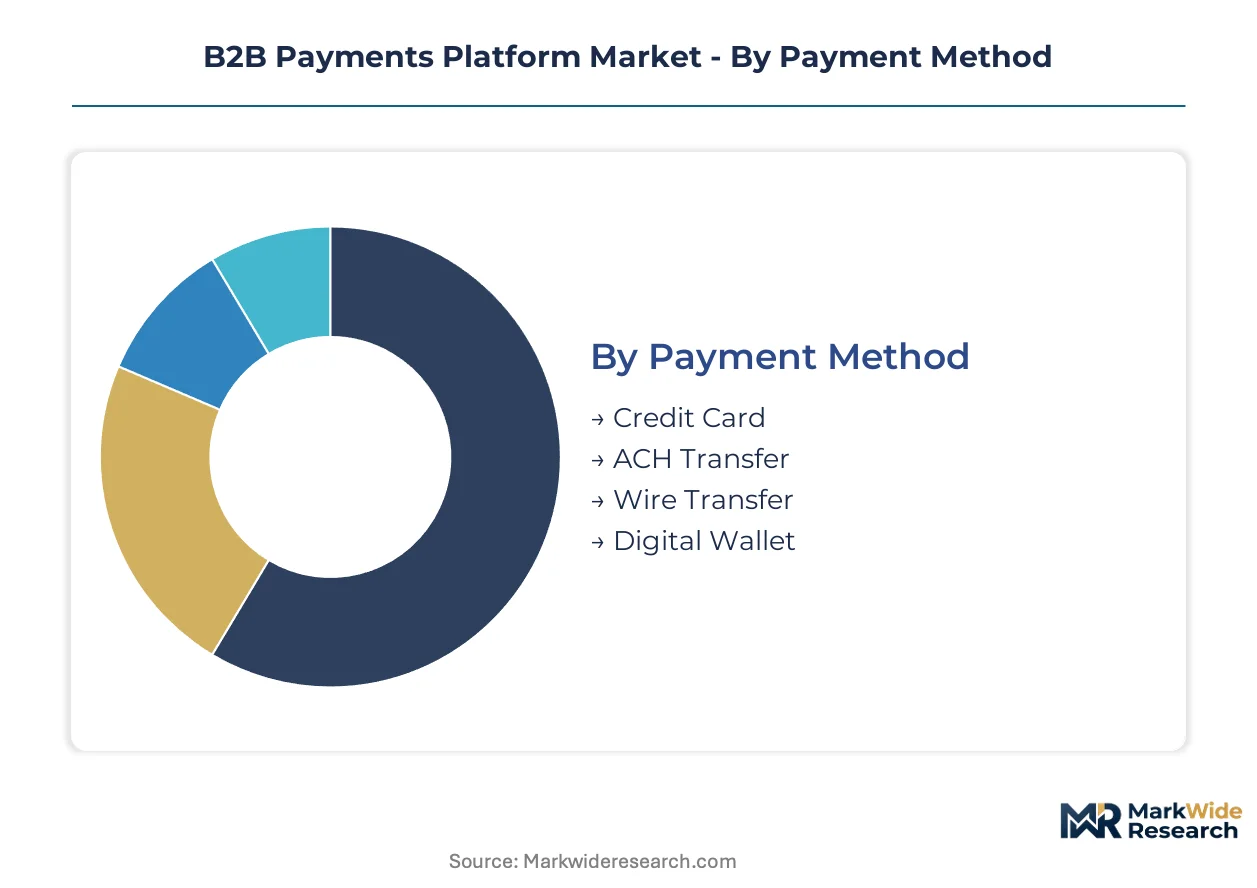
Payment rail selection and deployment architecture directly determine platform economics, compliance burden, and integration complexity for corporate treasurers. Segment boundaries are blurring as real-time infrastructure and embedded finance APIs reshape traditional category definitions.
Payment Method:
Cost sensitivity and settlement speed separate buyers across rails, with interchange tolerance and working capital requirements driving selection.
- Credit Card:Virtual card issuance dominates professional services and travel verticals where spend controls and automated reconciliation outweigh interchange costs. US healthcare systems leverage commercial cards for supplier payments to extend days payable outstanding while capturing line-item data.
- ACH Transfer:Batch-based automated clearing house remains the volume anchor for US mid-market payroll and recurring supplier disbursements, though same-day ACH adoption is compressing settlement windows. Manufacturing firms with predictable payment schedules favor ACH for its cost efficiency against wire alternatives.
- Wire Transfer:Fedwire and CHIPS handle time-critical, high-value settlements where irrevocability matters. Cross-border dollar clearing concentrates through correspondent banking networks with limited rail redundancy.
- Digital Wallet:Closed-loop wallet infrastructure expands fastest in logistics and construction verticals where project-based contractor payments require instant fund availability without traditional bank onboarding friction.
ACH Transfer leads volumes today; Digital Wallet is gaining share fastest.
Industry Vertical:
Regulatory complexity and supplier network maturity create divergent platform requirements across end-use sectors.
- Manufacturing:Tier-two supplier finance digitization in Germany and Japan drives demand for dynamic discounting platforms. HIPAA transaction standards constrain US healthcare payment data flows, elevating compliance architecture costs.
- Retail:Omnichannel inventory financing and marketplace seller disbursements require high-velocity, low-value payment orchestration with real-time settlement visibility.
- Healthcare:HIPAA transaction standards mandate specific data encryption and audit trails, segmenting platform compliance burdens from other verticals.
- Education:Tuition payment plans and international student fee processing create seasonal volume spikes requiring elastic infrastructure capacity.
Manufacturing anchors platform revenue; Healthcare shows steepest expansion trajectory.
Deployment Model:
IT modernization timelines and data sovereignty rules dictate cloud migration pace among enterprise treasuries.
- Cloud-Based:API-first SaaS platforms now dominate new adoption as mid-market firms abandon legacy treasury workstations. Europe's Digital Operational Resilience Act mandates multi-cloud failover documentation for critical payment service providers.
- On-Premises:Air-gapped installations persist in defense and government contracting where data localization requirements block external connectivity.
- Hybrid:Split architectures route sensitive payment instruction data through private infrastructure while leveraging cloud for analytics and reporting layers.
- Managed Service:Outsourced treasury operations appeal to private equity portfolio companies seeking rapid standardization across acquired entities without internal platform build-out.
Cloud-Based deployment captures majority new bookings; Hybrid models climb fastest among regulated industries.
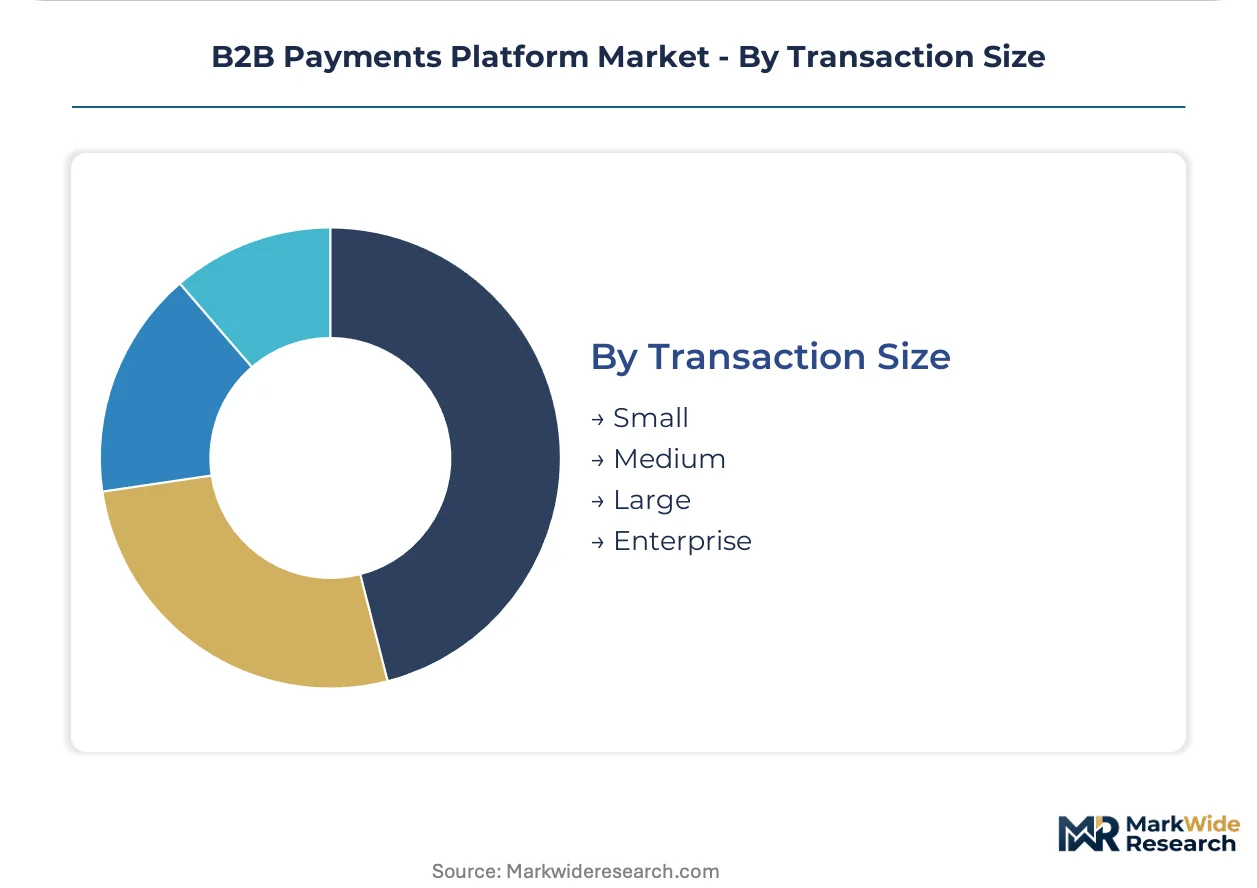
Transaction Size:
Payment value thresholds determine rail eligibility, fraud controls, and approval workflow complexity.
- Small:Sub-thousand-dollar transactions flow through real-time rails and digital wallets where per-transaction economics favor speed over batch efficiency.
- Medium:Mid-range commercial payments between ten thousand and one hundred thousand dollars represent the contested ground where same-day ACH competes with virtual cards.
- Large:Six and seven-figure settlements require multi-signature authorization workflows and integrated foreign exchange execution for cross-border exposures.
- Enterprise:Treasury-level liquidity movements across operating entities demand intraday visibility and centralized pool structures with automated sweeping mechanisms.
Medium transaction tiers generate deepest margin pools; Small-value payments expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment infrastructure engineers and treasury technology specialists concentrate in financial centers where regulatory innovation and enterprise demand intersect. These talent clusters anchor platform development velocity and shape regional competitive dynamics.
United States
Mid-market SaaS vendors embedding payments into vertical workflows drive platform adoption across manufacturing and healthcare sectors. The Federal Reserve's FedNow service creates immediate settlement expectations that pull corporate treasurers off batch-based ACH systems. San Francisco and New York host the densest concentrations of API-first infrastructure developers building real-time rail connectivity.
Germany
Tier-two supplier finance digitization in industrial manufacturing creates white space for dynamic discounting and supply chain finance platforms. The European Central Bank's TARGET Instant Payment Settlement framework mandates real-time liability management capabilities for corporate banking relationships. Munich and Frankfurt anchor the deepest pools of ISO 20022 messaging expertise outside correspondent banking headquarters.
United Kingdom
Open banking frameworks under PSD2 normalize programmatic access to commercial bank accounts, reducing onboarding friction for platform-to-bank connectivity. The Financial Conduct Authority's operational resilience requirements force multi-cloud failover documentation for critical payment service providers. London's fintech cluster generates disproportionate venture deployment into B2B orchestration layers.
Japan
Manufacturing supply chains retain high check-usage rates among tier-two vendors, creating conversion opportunity for electronic payment platforms. METI's digital transformation incentives accelerate cloud migration among mid-market industrial firms abandoning legacy treasury workstations. Tokyo and Osaka concentrate the regional headquarters of global payment networks prioritizing Asia-Pacific rail expansion.
Singapore
Cross-border trade finance digitization demands multi-currency settlement infrastructure serving ASEAN supply chain corridors. The Monetary Authority of Singapore's payments licensing framework attracts platform operators seeking regulatory clarity for regional hub strategies. The city-state's banking concentration enables direct Fedwire and CHIPS access negotiations that compress settlement costs for Southeast Asian originating volume.
B2B Payments Platform Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure where scale advantages in bank partnership negotiations separate leaders from followers. The vendor base stratifies between global payment networks with proprietary rail infrastructure, developer-centric API platforms, and vertical SaaS operators white-labeling orchestration capabilities. Three archetypes dominate: rail owners controlling settlement infrastructure, orchestration layers abstracting multi-rail complexity, and embedded finance providers capturing interchange within software workflows. M&A activity concentrates on ISO 20022 messaging competency acquisitions, while strategic partnerships with correspondent banks secure preferential pricing on real-time rail access.
Within the orchestration layer archetype, Stripe and Bill.com exemplify divergent paths to platform scale, with the former anchoring developer-centric embedded finance and the latter representing workflow-integrated payables automation. Mastercard occupies a distinct position as a rail owner competing directly with ACH modernization through proprietary virtual card networks. These three companies illustrate how competitive positioning in B2B payments depends on controlling either the settlement infrastructure, the software integration layer, or the end-user workflow capture point.
| Leading Market Players |
|---|
| Stripe |
| PayPal |
| Mastercard |
| Visa |
| Payoneer |
| Bill.com |
| Ramp |
| AvidXchange |
| Fiserv |
| Others |
Value Chain & Pricing Dynamics
Corporate treasurer demand for real-time settlement visibility is forcing infrastructure providers to unbundle legacy bundled service offerings and reprice API access tiers, compressing margins on basic orchestration while premium multi-rail reconciliation commands sustained pricing power.
Pricing Analysis
Bundled treasury workstation suites are fragmenting into unbundled API-per-call pricing models as cloud-native platforms displace on-premises installations. Three-tier pricing structure across enterprise, mid-market, and developer tiers separates high-volume real-time rail access from batch ACH processing, with ISO 20022 message mapping expertise commanding certification premiums. Cost compression in basic payment orchestration is intensifying because correspondent bank connectivity has commoditized, while virtual card interchange revenue insulates card network incumbents from price erosion. Mid-market SaaS vendors show highest price sensitivity as they white-label infrastructure without balance sheet depth to negotiate preferential rail access.
Supply Chain Analysis
ISO 20022 message mapping talent scarcity in San Francisco, New York, and London is constraining platform build-out velocity and inflating implementation costs for cross-border connectivity. Engineering resources concentrate in these three financial centers, while cloud infrastructure provisioning draws from hyperscaler data center networks across Virginia, Frankfurt, and Singapore. Single-source vulnerability sits with correspondent banking networks for dollar clearing, where Fedwire and CHIPS access hinges on narrow tier-one bank partnerships. Distribution runs through direct enterprise sales teams for large treasury departments and API documentation portals for developer-led embedded finance adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
B2B payments infrastructure functions as a stable compounder where ISO 20022 migration timelines lock in decade-long replacement cycles and embedded finance penetration deepens revenue per customer.
For Market Incumbents: Extend virtual card network dominance into real-time rail orchestration by acquiring ISO 20022 messaging specialists before talent scarcity worsens, and deepen correspondent bank partnership density to defend against fintech challengers lacking balance sheet scale for preferential Fedwire pricing. For New Entrants and Emerging Players: Tier-two manufacturing suppliers in Germany and Japan represent an underserved buyer archetype with high check-usage rates and limited electronic onboarding infrastructure, offering white-space entry through dynamic discounting platforms with simplified supplier enablement workflows. For Investors and Strategic Acquirers: Asymmetric upside sits with orchestration-layer specialists possessing proven multi-rail reconciliation engines and existing correspondent bank connectivity agreements. Long-term viability rests on FedNow adoption velocity as the inflection indicator for real-time infrastructure valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Messaging Stack Acquisition | Secures scarce talent pools and correspondent bank connectivity credentials ahead of compliance deadlines. |
| Embedded Finance API Partnership | Captures interchange revenue within vertical SaaS workflows in manufacturing and healthcare sectors. |
| Multi-Cloud Failover Architecture | Satisfies Europe's Digital Operational Resilience Act mandates for critical payment service providers. |
| Real-Time Rail Connectivity Expansion | Positions platforms for FedNow and TARGET Instant Payment Settlement volume migration. |
| Supplier Finance Digitization Program | Converts check-dependent tier-two vendors in industrial supply chains to electronic payment adoption. |
Study Parameters
Direct dialogue with corporate treasury executives, payment platform engineering leads, correspondent bank product managers, and vertical SaaS integration specialists anchored qualitative findings, cross-validated against SEC 10-K filings, Fedwire volume disclosures, ECB payment statistics, and ISO 20022 migration timeline announcements. Bottom-up transaction volume estimates and top-down market sizing triangulated segment-level projections.
Market value and volume trajectories across the analysis window reflect segment-specific modeling of payment rail adoption curves, deployment architecture shifts, and vertical penetration rates. CAGRs were derived from rail-specific volume growth assumptions, ISO 20022 compliance deadline impacts, and embedded finance attach rate progression within manufacturing and healthcare software workflows.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time rail transaction volume reporting from non-US jurisdictions introduce uncertainty bands around cross-border growth assumptions. Forecasts reflect documented assumptions regarding FedNow adoption velocity and correspondent bank consolidation patterns. Material deviation in central bank digital currency pilot program timelines or ISO 20022 deadline extensions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Spain Real Time Payments Market
Payments
Mobile Money Market
Payments
Digital Money Transfer Market
Payments
Mexico POS Terminals Market
Payments
Hong Kong Payments Market
Payments
France Virtual Cards Market
Payments
Point-Of-Sale [POS] Terminal Market
Payments
India Mobile Payments Market
Payments
Direct Carrier Billing Platform Market
Payments
Global Accounts Payable Software Market
Payments
South Africa Real Time Payments Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Europe Mobile Payment Market
Payments
P2P Payment Market
Payments
Global Smart Payment Systems Market
Payments
Middle East and Africa Buy Now Pay Later Services Market