
 Middle East and Africa Buy Now Pay Later Services Market | 2026-2036
Middle East and Africa Buy Now Pay Later Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Buy Now Pay Later Services Market Foresight
Small businesses are reorganizing payment preferences toward installment-based working capital solutions. Tabby leverages merchant network density to anchor its position in Saudi Arabia and the UAE. Tamara competes through specialized checkout integration for fashion and electronics retailers. HSBC Holdings extends its banking infrastructure to sustain corporate BNPL offerings across multiple jurisdictions.
Buy Now Pay Later services in the Middle East and Africa comprise digital credit platforms that split purchases into structured repayment schedules, typically operating through real-time risk algorithms and automated debit frameworks. These systems serve primarily to reduce cart abandonment and expand merchant conversion rates in underbanked consumer segments. Pay in Installments dominates transaction volume across the region, while Instant Credit captures the fastest expansion as mobile-first users demand immediate approval cycles. E-commerce Integrations concentrate margin pools where platform APIs embed directly at checkout, reducing friction for Online Shoppers in Fashion and Consumer Electronics applications.
The Saudi Central Bank and the UAE's central bank have both issued digital lending frameworks that mandate capital adequacy and consumer disclosure standards for BNPL operators. South Africa's National Credit Regulator applies affordability assessment rules that shape product design and limit automatic credit line increases. Stakeholders must monitor how divergent national licensing regimes affect cross-border platform scalability and capital deployment priorities.
Market Dynamics
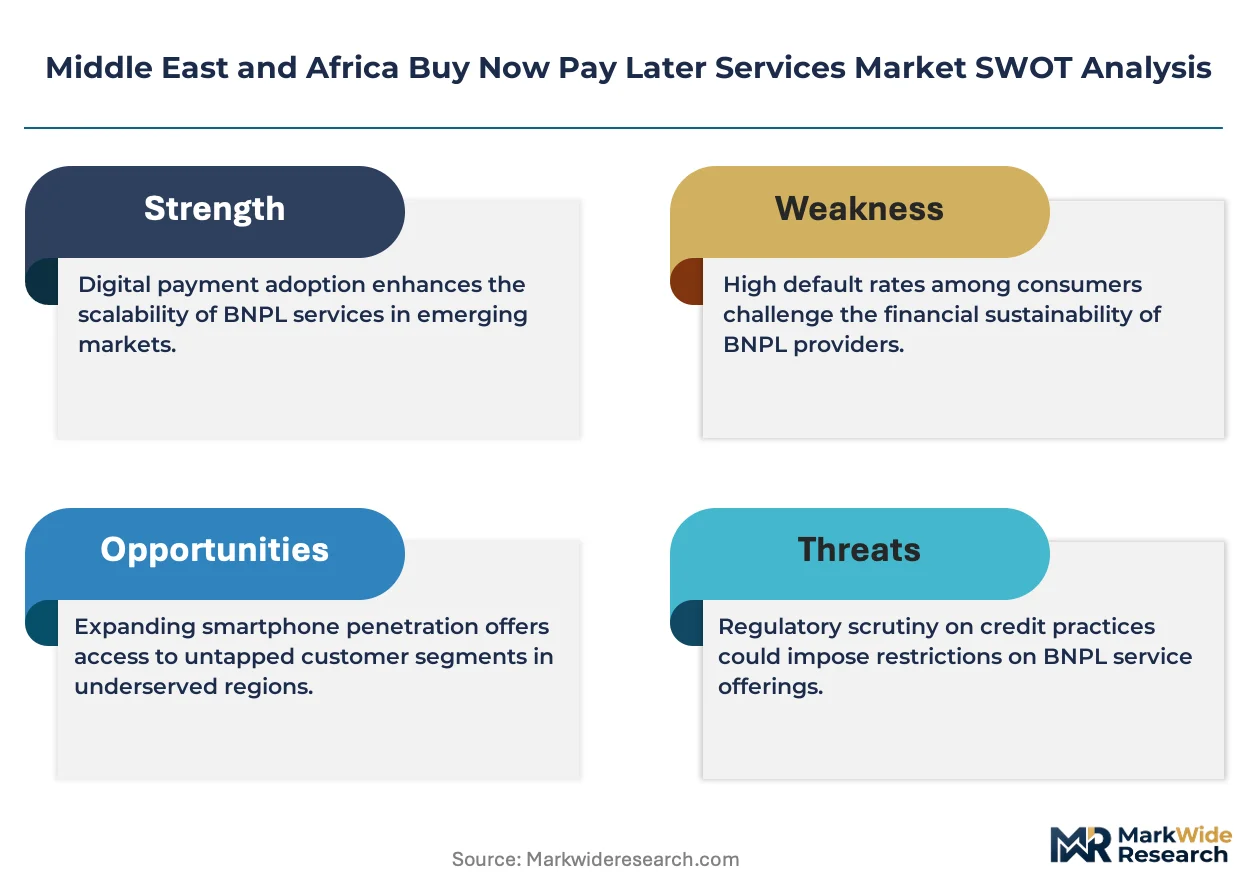
Central bank digital lending frameworks across Saudi Arabia and the UAE are restructuring capital adequacy requirements and consumer disclosure standards, forcing BNPL operators to rebuild product architectures around licensed financial institution partnerships rather than standalone fintech models.
Growth Catalysts
- SFDA and MOHAP digital lending guidelines:The Saudi Central Bank and UAE's central bank have issued explicit frameworks that legitimize deferred payment products, reducing regulatory uncertainty and attracting institutional capital into compliant platforms.
- E-commerce checkout integration density:Fashion and electronics merchants are embedding installment APIs directly at point-of-sale, converting cart abandonment into structured credit relationships with real-time risk scoring.
- Mobile-first credit access:Underbanked consumer segments across Riyadh, Dubai, and Johannesburg are bypassing traditional banking infrastructure through smartphone-native approval cycles and automated debit frameworks.
Market Restraints
- Fragmented national licensing regimes:South Africa's National Credit Regulator applies affordability assessment rules that diverge from Gulf Cooperation Council capital standards, complicating cross-border platform scalability.
- Sharia compliance complexity:Islamic finance principles require product restructuring across Saudi Arabia and UAE markets, adding legal review cycles and limiting standardized product rollouts.
- Merchant fee compression:High customer acquisition costs and competitive checkout placement bidding are squeezing net transaction margins for platform operators.
Strategic Opportunities
- Nigeria and Egypt underpenetration:Africa's largest consumer markets lack mature BNPL infrastructure, creating first-mover advantages for platforms that adapt to local payment rails and informal employment verification.
- B2B working capital extension:Small business procurement of inventory and equipment represents untapped demand for installment-based trade credit beyond consumer retail applications.
- Open banking API convergence:Real-time account data sharing frameworks enable alternative credit scoring models that bypass traditional bureau dependencies in thin-file markets.
Industry Challenges
- Collections infrastructure gaps:Automated debit failure rates spike in markets with inconsistent banking penetration, requiring hybrid human-digital recovery operations that erode unit economics.
- Credit bureau integration latency:Multi-jurisdiction data sharing agreements face technical and legal delays, limiting portfolio risk visibility for lenders operating across Saudi Arabia, UAE, and South Africa simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Buy Now Pay Later Services Market |
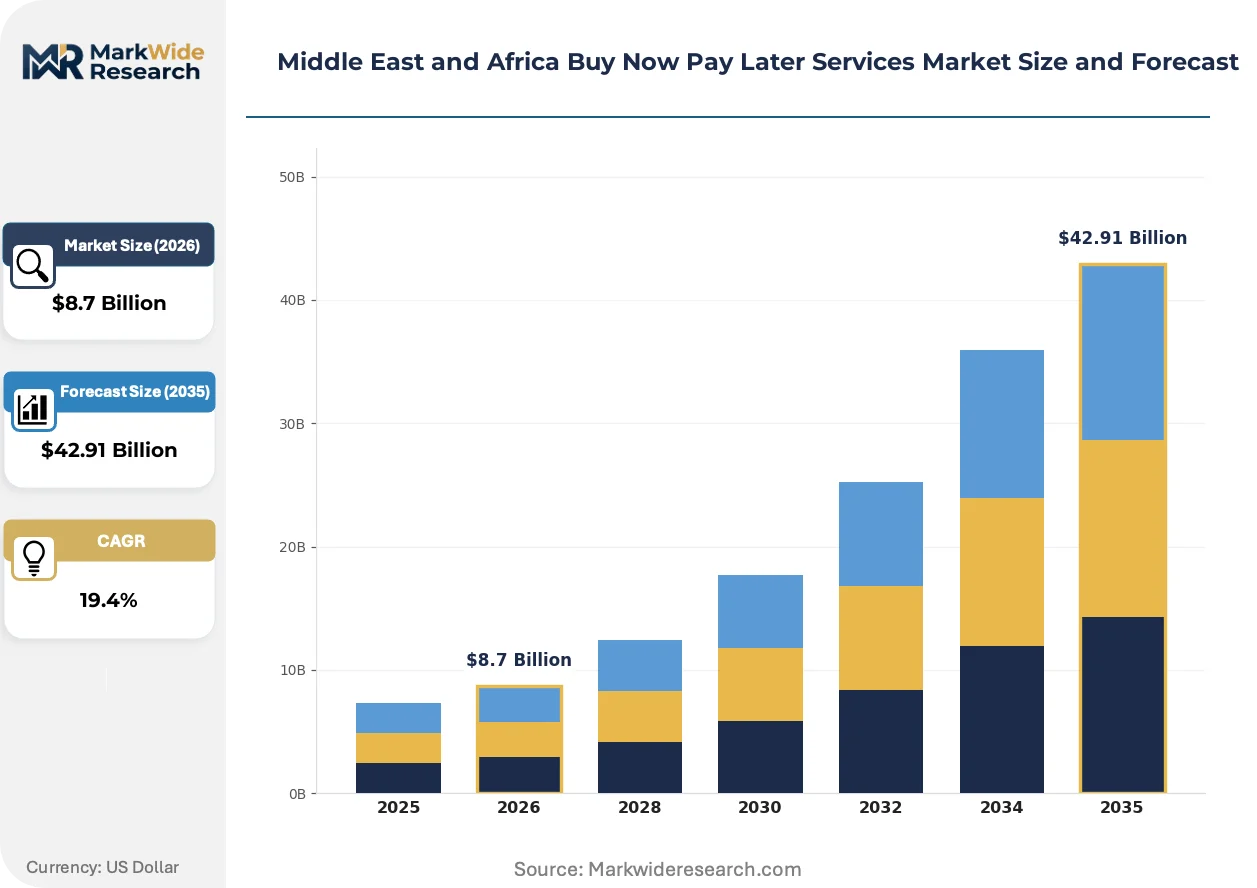
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pay in Installments, Deferred Payment, Interest-Free Credit, Instant Credit End User: Retail Customers, Online Shoppers, Small Businesses, Corporates Application: Consumer Electronics, Fashion, Home Goods, Travel Technology: Mobile Apps, Web Platforms, Payment Gateways, E-commerce Integrations |
| Companies Covered | Tabby, Tamara, Payflex, PayJustNow, Cashew, Spotii, Emirates NBD, HSBC Holdings, Zip Co, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Buy Now Pay Later Services Market Shifts & Advancements
Real-time risk decisioning engines and embedded finance architectures are displacing traditional installment origination models, compressing approval cycles from hours to seconds while expanding merchant categories beyond retail into services and B2B procurement.
Alternative data scoring is bifurcating credit access pathways across the region. Telco payment histories, gig economy platform earnings, and e-commerce transaction patterns now feed machine learning models that assess repayment capacity without traditional salary verification. Younger consumers in Saudi Arabia and UAE are adopting these models fastest, while incumbent banks struggle to integrate non-traditional data sources. The technology is bifurcating the market between thin-file specialists and established lenders dependent on conventional bureau scores.
South Africa's National Credit Regulator affordability assessment rules are reshaping product design parameters for entry-level credit. The framework mandates documented income verification and prohibits automatic credit line increases, forcing platforms to build graduated onboarding sequences rather than instant maximum approvals. Fashion and electronics retailers serving subprime segments are adapting marketing materials to emphasize responsible borrowing disclosures alongside promotional messaging.
Merchant-funded subsidy models are displacing pure lender balance sheet approaches in competitive checkout placements. Large retail chains in Dubai and Riyadh now negotiate zero-interest installment terms by absorbing platform fees as customer acquisition costs, compressing standalone BNPL provider margins. Electronics verticals with high average order values and repeat purchase cycles are driving this shift most aggressively.
Middle East and Africa Buy Now Pay Later Services Market Segmentation
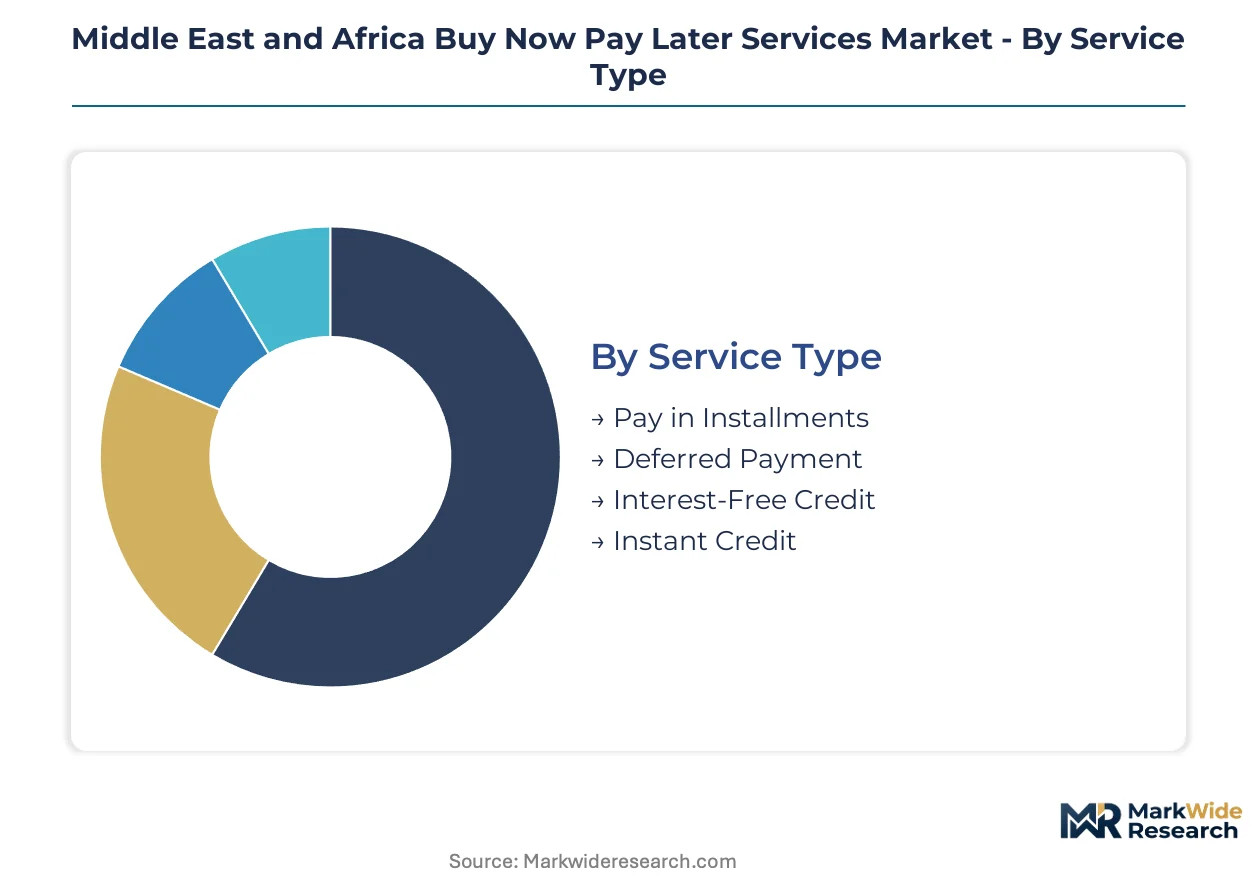
BNPL platforms in the Middle East and Africa deploy distinct service architectures to capture divergent payment behaviors across consumer and merchant segments. Channel integration patterns determine which technologies reach which end users, shaping capital allocation and partnership priorities for operators.
Service Type:
Channel distribution varies sharply by service structure, with installment products flowing through merchant-embedded APIs while instant credit concentrates in direct-to-consumer mobile channels.
- Pay in Installments:Splits purchase amounts into fixed monthly deductions with automated debit scheduling. Saudi Arabia and the UAE concentrate demand where fashion and electronics merchants embed these tools at checkout to reduce cart abandonment.
- Instant Credit:Delivers real-time approval decisions through smartphone-native interfaces, bypassing traditional bureau dependencies. Johannesburg and Riyadh show fastest adoption among underbanked segments seeking immediate purchasing power without salary verification delays.
- Deferred Payment:Extends settlement windows without structured installment schedules, common in B2B procurement contexts.
- Interest-Free Credit:Requires Sharia-compliant product restructuring across Gulf markets, adding legal review cycles.
Pay in Installments dominates installed base. Instant Credit is where expansion concentrates.
End User:
Customer acquisition costs and underwriting complexity stratify sharply across these segments, with small businesses demanding working capital solutions distinct from consumer retail applications.
- Online Shoppers:Drive transaction volume through embedded checkout integrations, particularly in Dubai and Riyadh where e-commerce penetration supports real-time risk scoring at point-of-sale.
- Small Businesses:Seek inventory and equipment financing through installment-based trade credit, with demand accelerating across the UAE as procurement digitizes.
- Retail Customers:Represent the broadest addressable base but with thinner margins per transaction.
- Corporates:Require specialized B2B platforms with extended settlement terms and vendor management integration.
Online Shoppers anchor current revenue pools. Small Businesses represent the steepest expansion trajectory as working capital solutions digitize.
Application:
Average order values and repeat purchase frequency determine merchant willingness to absorb platform fees as customer acquisition costs.
- Fashion:High-frequency, lower-ticket purchases with strong seasonal patterns. Saudi Arabia concentrates demand where youth demographics and mall culture drive installment adoption for mid-market apparel.
- Consumer Electronics:Higher average order values justify zero-interest merchant subsidies. Dubai retailers aggressively negotiate checkout placement to capture upgrade cycles in smartphones and laptops.
- Home Goods:Longer consideration periods with delivery-dependent fulfillment models.
- Travel:Booking value concentration and cancellation risk create specialized underwriting requirements.
Consumer Electronics leads merchant-funded subsidy adoption. Fashion is gaining share fastest through checkout API density.
Technology:
Platform architecture choices determine regulatory exposure and capital partnership requirements across jurisdictions.
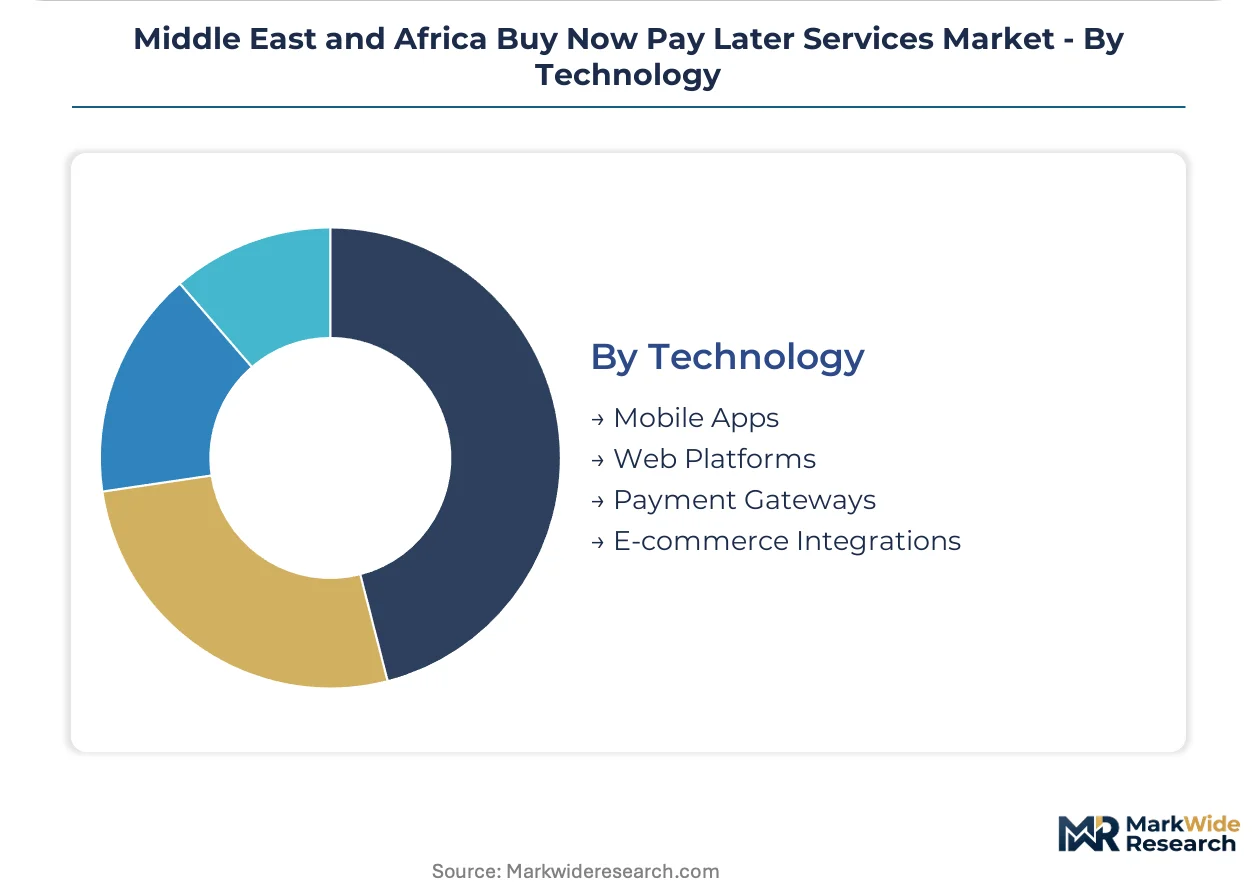
- E-commerce Integrations:Direct API embedding at merchant checkout captures margin pools through reduced friction. UAE and Saudi regulators now mandate licensed financial institution backing for these arrangements.
- Mobile Apps:Smartphone-native interfaces bypass traditional banking infrastructure entirely. South Africa's National Credit Regulator affordability rules force graduated onboarding sequences rather than instant maximum approvals.
- Payment Gateways:Intermediary infrastructure requiring multi-jurisdiction compliance coordination.
- Web Platforms:Browser-based access with higher abandonment rates than mobile-native alternatives.
E-commerce Integrations dominate merchant acquisition. Mobile Apps are climbing the fastest as smartphone penetration deepens across underbanked segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Cooperation Council's fiber-optic cable landings and data center interconnects anchor the region's digital payment infrastructure, enabling real-time credit decisioning across disparate regulatory jurisdictions.
Saudi Arabia
Riyadh's youth demographics and mall culture concentrate fashion installment demand, where smartphone penetration exceeds regional benchmarks. The Saudi Central Bank's digital lending framework mandates capital adequacy disclosures that reshape product architectures. Jeddah's retail corridors host dense merchant API integrations at electronics and apparel checkout points.
United Arab Emirates
Dubai's free zone data centers and fintech licensing regimes attract platform operators seeking regulatory clarity. The UAE central bank's consumer protection guidelines require licensed financial institution backing for embedded credit products. Abu Dhabi's sovereign wealth deployment into digital infrastructure accelerates merchant onboarding velocity.
South Africa
Johannesburg's underbanked segments drive mobile-native instant credit adoption through alternative data scoring models. The National Credit Regulator's affordability assessment rules prohibit automatic credit line increases and mandate documented income verification. Cape Town's retail networks adapt marketing materials to emphasize responsible borrowing disclosures.
Egypt
Cairo's informal employment verification challenges create demand for telco payment history and gig economy platform data in underwriting engines. The country's central bank maintains evolving digital payment regulations that lag Gulf standards in specificity. Alexandria's merchant corridors show early-stage checkout integration experiments in consumer electronics.
Nigeria
Lagos's mobile money infrastructure and agent banking networks provide alternative payment rails for installment collection in thin-file markets. The central bank's payment system licensing creates compliance thresholds for foreign platform entry. Kano's informal trade clusters represent untapped demand for B2B working capital solutions beyond retail applications.
Middle East and Africa Buy Now Pay Later Services Market Competitive Landscape
Listed leaders compete with private specialists across checkout placement density and regulatory licensing breadth. The vendor base stratifies between Gulf-based fintechs with merchant network scale and international banking conglomerates with balance sheet capacity. Three archetypes dominate: thin-file credit specialists, incumbent bank digital extensions, and cross-border platform operators. Consolidation pressure concentrates through strategic partnerships with licensed financial institutions and merchant-funded subsidy negotiations.
Among Gulf-based specialists, Tabby and Tamara exemplify the merchant-integrated archetype, occupying positions where checkout API density determines customer acquisition economics. HSBC Holdings anchors the incumbent banking tier, extending regulated lending infrastructure across multiple jurisdictions through partnership models rather than standalone fintech architectures.
| Leading Market Players |
|---|
| Tabby |
| Tamara |
| Payflex |
| PayJustNow |
| Cashew |
| Spotii |
| Emirates NBD |
| HSBC Holdings |
| Zip Co |
| Others |
Supply & Pricing Matrix
Merchant-funded subsidy models replacing pure lender balance sheet approaches are redrawing supply geography toward retail chains with customer acquisition budgets while compressing net transaction margins for standalone platform operators. This substitution simultaneously concentrates pricing power with large electronics and fashion merchants in Dubai and Riyadh and erodes the unit economics of thin-file specialists dependent on platform fees.
Pricing Analysis
Volume-discount tiering structures separate enterprise retail chains absorbing platform fees as customer acquisition costs from mid-market merchants paying standard rates. Price differentiation hinges on checkout placement priority and average order value thresholds, with electronics verticals commanding premium positioning due to repeat purchase cycles. Cost compression in the mid-merchant tier is intensifying because competitive bidding for API integration slots drives fee escalation. Small independent retailers exhibit highest price sensitivity, while sovereign wealth-backed retail conglomerates show least sensitivity given strategic customer lifetime value calculations.
Supply Chain Analysis
Inventory and lead-time observations reveal minimal physical goods movement, as BNPL services rest on digital infrastructure rather than material inputs. Supply concentrates in UAE and Saudi Arabia data centers hosting real-time risk engines, with South Africa providing alternative node redundancy. Raw material dependencies center on cloud compute capacity, telecommunications bandwidth, and licensed financial institution partnerships. Single-source vulnerability sits with merchant API gateway providers serving multiple competing platforms. Distribution runs through embedded checkout integrations at point-of-sale rather than standalone application channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large retail chains consolidating checkout placement negotiations, fragmenting the vendor landscape between merchant-captive subsidy models and independent fee-based operators.
For Market Incumbents: Consolidate merchant network density in Saudi Arabia and the UAE before competitive API saturation locks in exclusive partnerships. Deepen licensed financial institution relationships to meet central bank capital adequacy mandates. Defensive priority centers on securing electronics and fashion verticals where zero-interest subsidy models threaten standalone platform viability. For New Entrants and Emerging Players: Certification fast-tracks through UAE free zone fintech licensing offer regulatory clarity advantages over Saudi standalone applications. White-space targets concentrate in Nigeria and Egypt where mobile money infrastructure supports alternative collection rails. Most penetrable segment is B2B working capital for informal trade clusters lacking inventory financing access. Go-to-market angle emphasizes telco payment history integration for thin-file underwriting. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Gulf-based fintechs approaching scale thresholds requiring banking partnership conversion or exit. Long-term viability favors platforms with demonstrated merchant-funded subsidy negotiation capability and multi-jurisdiction licensing breadth. Acquisition target archetype is thin-file specialists with alternative data scoring engines and established Johannesburg or Lagos user bases. Signal to watch is central bank digital lending framework harmonization across Gulf Cooperation Council jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Licensed Financial Institution Partnership | UAE central bank mandates capital adequacy backing for embedded credit products. |
| Alternative Data Scoring Investment | Telco payment histories and gig platform earnings bypass traditional bureau dependencies. |
| Merchant-Funded Subsidy Negotiation | Electronics retailers in Dubai absorb platform fees as customer acquisition costs. |
| B2B Working Capital Extension | Small business procurement digitization creates installment-based trade credit demand. |
| Multi-Jurisdiction Licensing Buildout | Saudi Central Bank and South Africa National Credit Regulator divergent rules complicate scaling. |
Research Methodology
Desk research of central bank regulatory filings, fintech licensing databases, and merchant API documentation preceded structured interviews with BNPL platform risk officers, retail chain procurement directors, and licensed bank partnership leads. Secondary validation drew from Saudi Central Bank circulars, UAE central bank consumer protection guidelines, and South Africa National Credit Regulator affordability assessment frameworks. Bottom-up transaction volume estimates triangulated against top-down addressable credit market sizing.
Variance decomposition across service type, end user segment, and application vertical shaped the analytical framework. Modeled dimensions included pay-in-installments versus instant credit structures, online shopper versus small business demand patterns, and fashion versus electronics merchant categories. CAGRs derived from segment-level growth rate reconciliation with aggregate market trajectory. Forecast inputs incorporated smartphone penetration curves and e-commerce checkout integration density metrics.
Underlying assumptions cover regulatory framework stability, merchant subsidy model sustainability, and collections infrastructure reliability, with deviation risk concentrated in central bank licensing requirement changes and automated debit failure rate spikes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Asia-Pacific Payments Market
Payments
Middle East & North Africa Digital Payments Market
Payments
India Payment Gateway Market
Payments
Spain Real Time Payments Market
Payments
Asia-Pacific Payment Gateway Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
Mpos Terminals Market
Payments
North America Mobile Payments Market
Payments
3D Secure Pay Authentication Market
Payments
Latin America Subscription and Billing Management Market
Payments
Finland POS Terminals Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Japan Mobile Payments Market
Payments
Italy Gift Cards Market
Payments
Convergent Billing Market
Payments
Cash Management System Market