
 Europe Hospital Capacity Management Solutions Market | 2026-2036
Europe Hospital Capacity Management Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hospital Capacity Management Solutions Market Foresight
A capital-intensity divergence between legacy on-premises vendors and cloud-native entrants is unwinding competitive stability across the European market. Siemens Healthineers leverages its embedded hardware-installation base to bundle software contracts across German and Nordic hospital networks. Philips Healthcare anchors its position through deep integration with patient monitoring devices, creating captive demand for its capacity platforms. Dedalus Group specializes in public-sector procurement frameworks, particularly in Italy and France where national health systems favor domestic or EU-based vendors.
Hospital capacity management solutions coordinate real-time tracking of bed availability, surgical schedules, staff assignments, and equipment utilization through software platforms that interface with electronic health record systems and IoT-enabled medical devices. These systems employ predictive algorithms to forecast patient admission patterns and optimize resource deployment across acute care settings. Cloud-based systems are capturing the fastest expansion as NHS trusts and regional health authorities in Spain and the Netherlands migrate from aging on-premises infrastructure under constrained IT budgets. Machine learning applications within patient flow management are attracting disproportionate R&D investment because algorithmic discharge prediction directly reduces length-of-stay metrics that determine reimbursement rates under EU diagnostic-related group frameworks.
The EU Medical Device Regulation (MDR) classifies certain capacity management modules as Class I or IIa devices, requiring notified body certification that filters out non-compliant vendors from procurement shortlists. GDPR and the EU AI Act impose strict governance requirements on patient data processing and algorithmic decision-making, compelling vendors to re-architect platforms for explainable outputs and localized data residency. Procurement officers and clinical informatics directors must evaluate whether vendor roadmaps align with forthcoming EHR interoperability mandates under the European Health Data Space regulation.
Market Dynamics
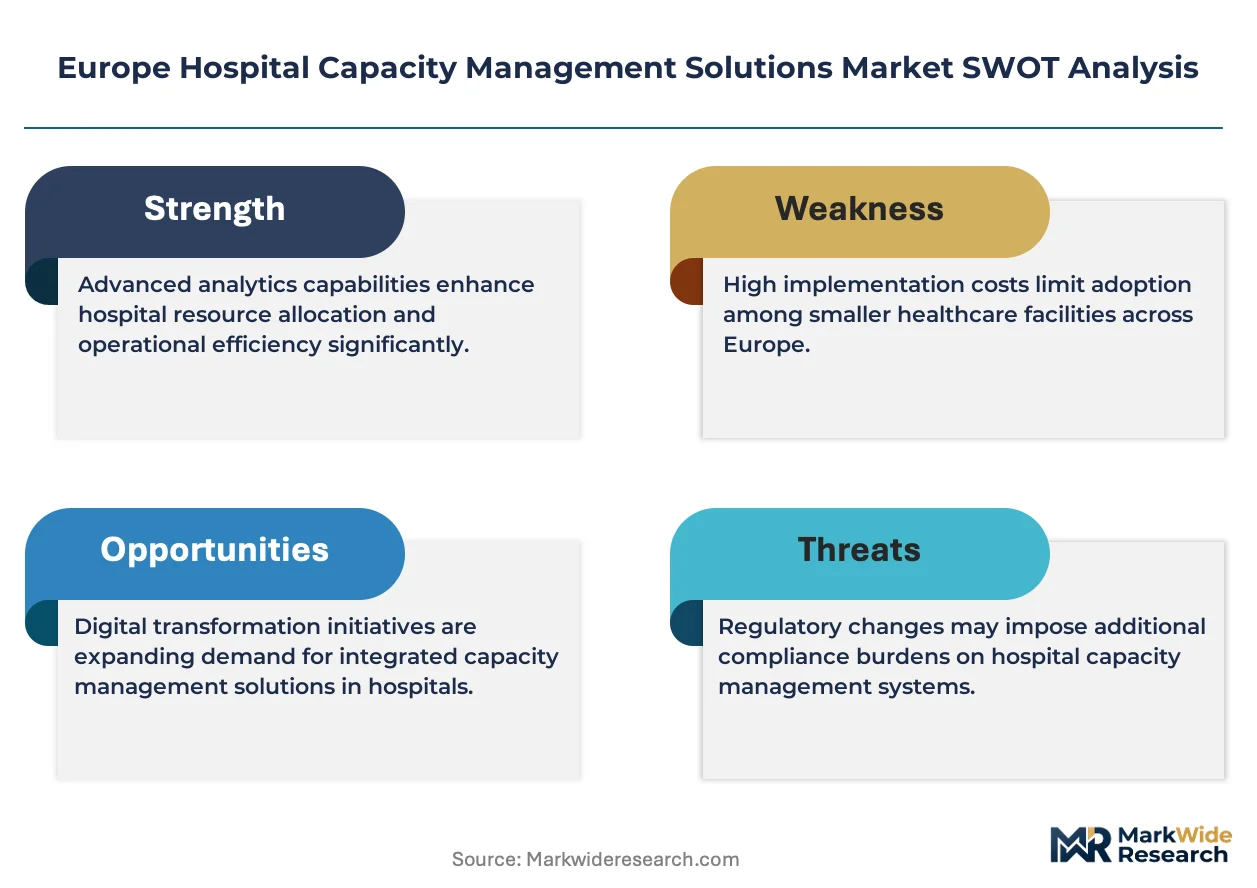
EU MDR certification requirements and GDPR data residency mandates are compressing the vendor landscape by filtering non-compliant software providers from public procurement shortlists across German, French, and UK hospital networks.
Growth Catalysts
- Workforce shortage pressures:NHS trusts facing nurse staffing gaps are automating shift scheduling and bed allocation to maintain surgical throughput without proportional headcount expansion.
- EU AI Act compliance:Algorithmic transparency requirements for patient discharge prediction tools are accelerating hospital investment in explainable machine learning platforms that satisfy regulatory audit standards.
- Elective surgery backlogs:Post-pandemic waiting list reductions in England and Spain are driving demand for real-time capacity optimization that maximizes operating room utilization.
Market Restraints
- Cloud migration costs:Legacy on-premises infrastructure replacement in Italian and Greek public hospitals requires substantial capital reallocation from constrained IT budgets.
- Notified body bottlenecks:Limited EU MDR certification capacity is extending software validation timelines by 12-18 months for Class IIa patient flow modules.
- Interoperability fragmentation:Proprietary EHR data formats from dominant vendors create integration friction that delays deployment of third-party capacity management overlays.
Strategic Opportunities
- Eastern European expansion:Polish and Romanian regional health authorities are initiating first-wave digitization programs with EU structural fund backing for hospital infrastructure.
- Predictive analytics convergence:Integration of IoT bed sensors with machine learning admission forecasting creates new value pools in length-of-stay reduction contracting.
- European Health Data Space:Interoperability mandates under this forthcoming regulation will force EHR vendors to open APIs, lowering barriers for specialized capacity management entrants.
Industry Challenges
- Clinical informatics talent scarcity:Hospitals in the Netherlands and Belgium struggle to recruit staff capable of configuring algorithmic decision-support tools without vendor dependency.
- Legacy system integration complexity:Decades-old patient administration systems in French public hospitals require expensive middleware development to enable real-time data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hospital Capacity Management Solutions Market |
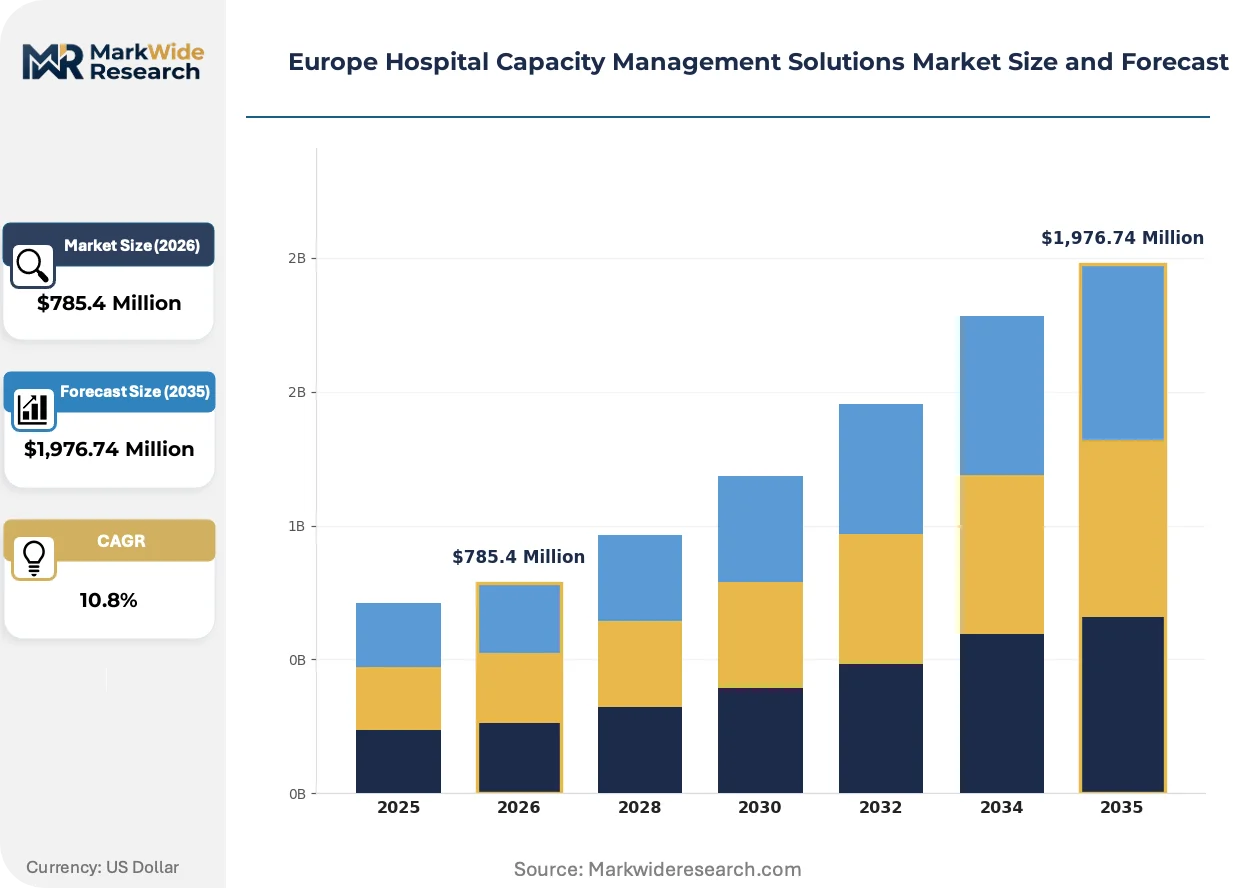
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,976.74 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Cloud-Based Systems, On-Premises Software, Analytics Tools Technology: Machine Learning, Artificial Intelligence, IoT Integration, Data Analytics End User: Public Hospitals, Private Clinics, Healthcare Networks, Emergency Services Application: Patient Flow Management, Resource Allocation, Staff Scheduling, Capacity Optimization |
| Companies Covered | Cerner Corporation, Allscripts Healthcare Solutions, McKesson Corporation, Epic Systems Corporation, Siemens Healthineers, Philips Healthcare, GE Healthcare, TeleTracking Technologies, Dedalus Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hospital Capacity Management Solutions Market Shifts & Advancements
Machine learning deployment in patient flow management is bifurcating vendor strategies between embedded EHR analytics and standalone best-of-breed platforms. This technological divergence is reshaping how hospitals evaluate procurement trade-offs between integration depth and functional specialization.
Cloud-native capacity management architectures are bifurcating the installed base between German and Nordic networks pursuing full-stack replacement and Southern European hospitals adopting hybrid edge-to-cloud configurations. NHS trusts are migrating fastest, driven by centralized procurement frameworks that favor software-as-a-service delivery models. This infrastructure shift is compressing maintenance revenue for legacy on-premises vendors while expanding recurring subscription pools for cloud entrants.
GDPR Article 22 provisions on automated decision-making are compelling vendors to re-engineer discharge prediction algorithms for human-in-the-loop validation. French CNIL enforcement actions against opaque patient scoring systems have accelerated this compliance pivot. Class IIa medical device reclassification under EU MDR is filtering non-compliant predictive analytics modules from tender shortlists in Italy and Spain.
Subscription-based capacity optimization contracts are displacing perpetual license sales in UK and Dutch procurement frameworks. Regional health authorities are consolidating vendor relationships through multi-hospital enterprise agreements that bundle implementation services with ongoing algorithm tuning. This purchasing concentration is most visible in England's NHS Integrated Care Systems, where population health budgets incentivize shared capacity platforms across formerly independent trusts.
Europe Hospital Capacity Management Solutions Market Segmentation
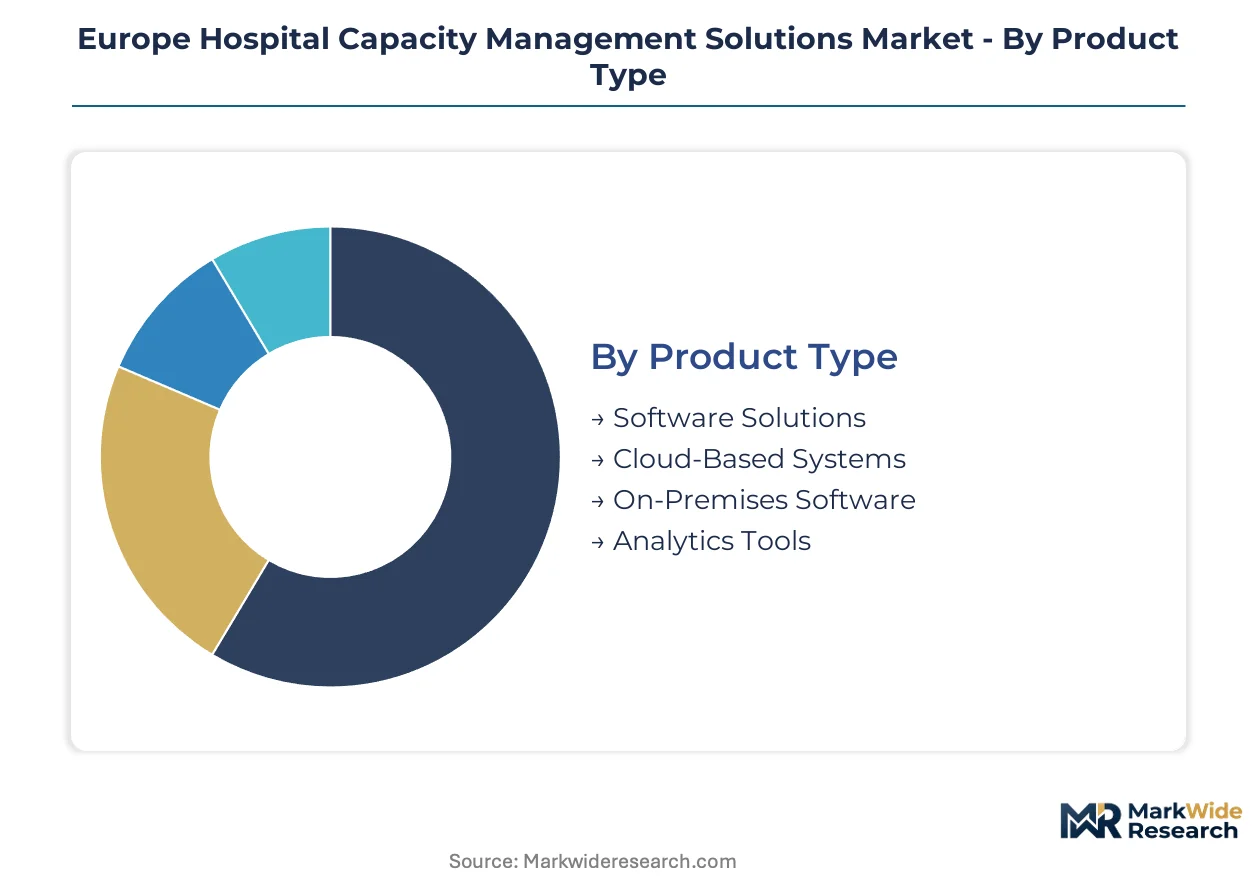
Segmentation in the Europe Hospital Capacity Management Solutions Market reveals how procurement priorities diverge across technology maturity, regulatory compliance burdens, and care delivery models. Understanding these divisions exposes where vendor substitution pressures concentrate and which configurations command pricing power.
Product Type:
Cloud-based systems face the most acute substitution threat from embedded EHR analytics, while on-premises vendors defend entrenched positions through high switching costs in Southern European public hospitals.
- Software Solutions:Modular platforms integrating bed management, surgical scheduling, and discharge planning through standardized APIs. NHS trusts in England and regional health authorities in the Netherlands concentrate procurement here, driven by EU MDR certification requirements that filter non-compliant vendors from tender shortlists.
- Cloud-Based Systems:SaaS architectures with localized data residency for GDPR compliance and elastic scaling for seasonal demand fluctuations. Spanish and French hospital networks are migrating fastest, constrained by IT budget limitations that favor subscription models over capital-intensive infrastructure replacement.
- On-Premises Software:Legacy installations in Italian and Greek public hospitals requiring substantial middleware development for interoperability with modern EHR systems.
- Analytics Tools:Standalone predictive modules for admission forecasting and length-of-stay optimization, often deployed as overlays atop existing patient administration systems.
Software solutions anchor the volume base while cloud-based systems gain share at the steepest rate.
Technology:
Cost tiers separate commodity data visualization from premium algorithmic platforms, with machine learning commanding implementation premiums that widen vendor margin dispersion.
- Machine Learning:Predictive models for patient discharge timing and readmission risk scoring, requiring explainable outputs under EU AI Act algorithmic transparency mandates. German university hospitals and Belgian academic medical centers drive demand, seeking length-of-stay reductions that improve reimbursement under diagnostic-related group frameworks.
- Artificial Intelligence:Broader cognitive automation spanning natural language processing for clinical documentation and computer vision for occupancy monitoring. Deployment concentrates in Nordic hospital networks with advanced digital maturity and sufficient clinical informatics staffing to configure decision-support tools.
- IoT Integration:Real-time bed sensors and asset tracking tags feeding centralized capacity dashboards, prevalent in UK trusts pursuing operating room utilization maximization.
- Data Analytics:Descriptive and diagnostic capabilities for historical throughput analysis, serving as entry-tier functionality for Eastern European hospitals initiating first-wave digitization.
Data analytics commands the widest installed base while machine learning expands most quickly among replacement purchases.
End User:
Customer type determines procurement channel access, with public hospitals bound by framework agreements that favor EU-based vendors while private clinics negotiate directly for best-of-breed configurations.
- Public Hospitals:National health system facilities in France, Italy, and Germany subject to domestic preference policies and lengthy tender processes. These institutions prioritize MDR-certified platforms with proven interoperability across heterogeneous EHR landscapes accumulated through decades of incremental IT investment.
- Private Clinics:Independent surgical centers and specialist hospitals in Switzerland and the United Kingdom seeking rapid deployment timelines and minimal customization requirements.
- Healthcare Networks:Multi-site systems spanning England's NHS Integrated Care Systems or Dutch regional health authorities, consolidating vendor relationships through enterprise agreements that bundle implementation with ongoing algorithm tuning.
- Emergency Services:Pre-hospital and ambulance dispatch coordination with acute care capacity, a nascent segment in Spain and Portugal exploring integration with hospital command centers.
Public hospitals absorb the majority of procurement value while healthcare networks are consolidating purchasing fastest.
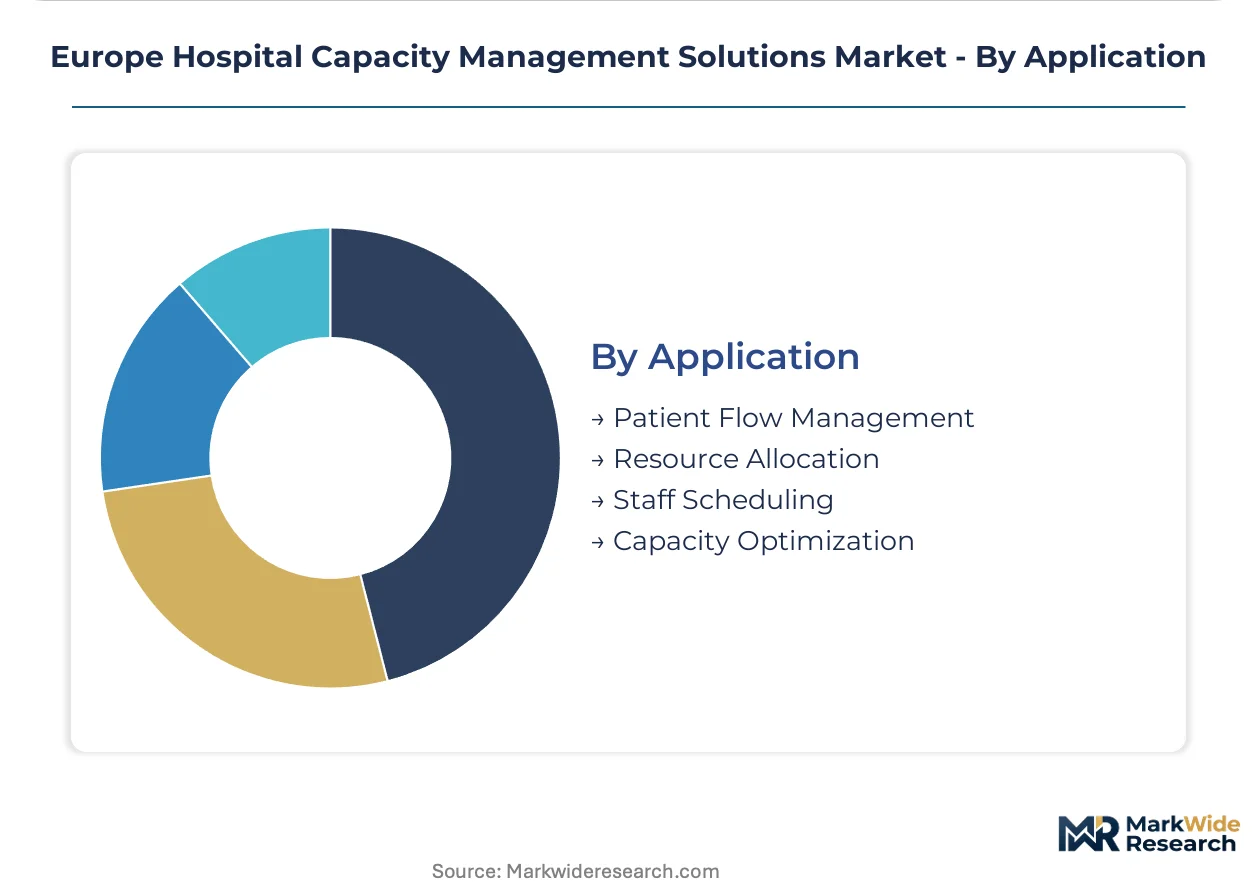
Application:
Application maturity varies sharply, with staff scheduling representing the most penetrated function and capacity optimization emerging as the most differentiated battleground for vendor competition.
- Patient Flow Management:Real-time tracking of admissions, transfers, and discharges with predictive alerts for bottleneck formation. Demand concentrates in UK trusts addressing elective surgery backlogs and in French public hospitals facing emergency department overcrowding penalties.
- Resource Allocation:Dynamic assignment of beds, equipment, and clinical spaces based on acuity scoring and anticipated demand patterns. German hospital networks lead adoption, integrating these capabilities with existing patient monitoring infrastructure from dominant medical device suppliers.
- Staff Scheduling:Automated shift matching against patient census projections and skill mix requirements, nearly ubiquitous in NHS trusts confronting nursing workforce shortages.
- Capacity Optimization:Holistic orchestration across surgical, medical, and critical care domains using simulation modeling for scenario planning, still emerging in Netherlands and Belgium where clinical informatics talent scarcity delays deployment.
Staff scheduling anchors current deployment breadth while capacity optimization climbs fastest as integrated care systems mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in hospital capacity management solutions favor EU-based vendors serving domestic health systems, with limited cross-border software licensing from North American providers facing MDR certification barriers.
Germany
University hospitals in Baden-Württemberg and Bavaria drive demand for machine learning-enabled discharge prediction tools that reduce length-of-stay under diagnostic-related group reimbursement. The KBA and BfArM enforce strict interoperability standards for patient data exchange between hospital information systems. Siemens Healthineers anchors the vendor landscape from Erlangen, bundling capacity software with imaging hardware installations across the country's largest hospital networks.
United Kingdom
NHS Integrated Care Systems confronting surgical backlogs and nurse staffing shortages are procuring cloud-native scheduling platforms at the fastest regional pace. NHS England framework agreements mandate GDPR-compliant data residency and algorithmic transparency under the EU AI Act's retained provisions. London trusts lead deployment, with Guy's and St Thomas' NHS Foundation Trust piloting predictive bed management across multiple sites.
France
Public hospitals facing emergency department overcrowding penalties are investing in real-time patient flow dashboards with CNIL-mandated human oversight of automated discharge scoring. The ANSM enforces MDR Class IIa certification for predictive analytics modules used in clinical decision support. The Paris hospital network AP-HP consolidates procurement through national framework agreements that favor Dedalus Group and other EU-based vendors.
Netherlands
Regional health authorities in the Randstad pursue enterprise-wide capacity optimization to coordinate care across formerly independent hospitals merged into integrated networks. The Dutch Health and Youth Care Inspectorate requires audit trails for algorithmic resource allocation decisions affecting patient placement. Clinical informatics talent scarcity in Amsterdam and Rotterdam delays deployment of advanced simulation modeling for surgical scheduling.
Spain
Regional health services in Catalonia and Andalusia migrate from aging on-premises infrastructure to hybrid cloud configurations under constrained IT budgets. The Spanish Agency for Medicines and Health Products applies MDR transition deadlines that filter uncertified vendors from public tenders. Barcelona's Hospital Clínic de Barcelona pilots IoT bed sensor integration with centralized command centers for operating room utilization maximization.
Europe Hospital Capacity Management Solutions Market Competitive Landscape
Concentration sits with diversified health technology conglomerates leveraging embedded hardware bases to bundle software contracts. The vendor landscape organizes into three tiers: integrated medical device suppliers, specialized health IT platforms, and cloud-native workflow entrants. Siemens Healthineers and Philips Healthcare exemplify the first archetype, while Dedalus Group occupies the public-sector specialist position. Competitive moves center on M&A to fill analytics capabilities and strategic partnerships with EHR vendors to secure interoperability certification.
Among diversified technology suppliers, Siemens Healthineers and Philips Healthcare exemplify the hardware-anchored bundling strategy, while Epic Systems Corporation represents the EHR-native platform approach. Cerner Corporation and Allscripts Healthcare Solutions occupy positions within the enterprise health IT tier, with Dedalus Group anchoring the EU-based public-sector specialist segment. These named entities illustrate how vendor origin and installed base composition determine procurement access across distinct national health system frameworks.
| Leading Market Players |
|---|
| Cerner Corporation |
| Allscripts Healthcare Solutions |
| McKesson Corporation |
| Epic Systems Corporation |
| Siemens Healthineers |
| Philips Healthcare |
| GE Healthcare |
| TeleTracking Technologies |
| Dedalus Group |
| Others |
Supply & Pricing Matrix
EU MDR certification requirements simultaneously gate vendor qualification and stratify price tiers across European hospital procurement frameworks. Cloud-native entrants bearing notified body credentials command implementation premiums against uncertified competitors excluded from NHS and German public tender shortlists.
Pricing Analysis
Configured-to-order pricing for bespoke EHR integration commands spreads of 40-60% above standard SaaS tiers. Subscription models dominate UK and Dutch procurement, while perpetual licenses persist in Italian public hospitals with constrained capital cycles. Price differentiation rests on GDPR localization infrastructure and MDR Class IIa certification status. Cost compression in standard tiers intensifies as cloud entrants compete for NHS framework slots. Private clinics in Switzerland exhibit lowest price sensitivity; Greek regional health authorities face acute budget constraints.
Supply Chain Analysis
Inventory lead times for IoT sensor hardware extend 16-24 weeks due to semiconductor allocation bottlenecks affecting UK and Spanish deployments. Software development concentrates in Germany, the Netherlands, and France; cloud infrastructure draws from Irish and Swedish data center clusters. Supply chain risk centers on single-source dependency for specialized clinical informatics talent. Distribution runs through GPO contracts in England and direct vendor relationships in Nordic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital capacity management solutions represent a service-attach opportunity where algorithm tuning and interoperability maintenance contracts expand faster than initial platform licensing. Recurring revenue from discharge prediction model retraining now exceeds hardware-margin contribution for cloud-native vendors.
For Market Incumbents: Secure MDR certification renewal pipelines ahead of 2027 transition deadlines to defend against cloud-native substitution. Anchor subscription pricing through multi-year NHS Integrated Care System enterprise agreements. Prioritize embedded analytics R&D to offset margin erosion in standalone scheduling modules threatened by EHR-native functionality expansion.
For New Entrants and Emerging Players: Anchor in Polish and Romanian regional digitization programs where EU structural funds finance first-wave procurement. Target capacity optimization overlays for French public hospitals struggling with legacy patient administration system integration. Pursue partnership routes with dominant EHR vendors to bypass interoperability certification delays.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures as containerization reduces infrastructure overhead. Long-term viability favors vendors with demonstrated EU AI Act compliance engineering. Acquisition targets should exhibit explainable algorithm development capabilities and established notified body relationships. Monitor CNIL enforcement patterns as signal for regulatory compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Class IIa Certification Pathway | Notified body approval filters non-compliant vendors from German and Italian public tenders. |
| Hospital System Partnership | AP-HP and NHS Integrated Care Systems consolidate procurement through framework agreements favoring EU-based vendors. |
| Platform Integration | Deep EHR interoperability with Epic and Cerner systems determines deployment velocity across UK trusts. |
| Software Companion Development | GDPR-compliant mobile applications for bed management extend platform utility for Dutch clinical staff. |
| Reimbursement Strategy | Length-of-stay reduction contracting aligns vendor incentives with DRG reimbursement optimization in German university hospitals. |
Research Methodology
A standing panel of hospital CIOs, clinical informatics directors, GPO contracts managers, and notified body auditors provided ongoing calibration across primary research phases. Secondary validation drew from NHS procurement databases, EMA MDR certification registries, hospital IT budget disclosures, and EU structural fund allocation records. Bottom-up deployment estimates triangulated against top-down health system expenditure analysis.
Consistency checks validated volume and value outputs against external benchmarks from health technology trade associations and regional hospital federation reports. Segmentation modeling spanned deployment architecture, end-user facility type, application function, and technology maturity tier across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable health IT categories, with adjustment for regulatory compliance cost step-functions.
Decision-makers should treat outputs as directional under assumptions of stable MDR certification capacity and continued NHS funding commitment; material deviation would warrant model refresh. Specific risk factors include notified body bottlenecks extending validation timelines and abrupt EHR vendor API policy changes under European Health Data Space implementation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Revenue Cycle Management (RCM) Market
Healthcare IT
Clinical Healthcare IT Market
Healthcare IT
Global Patient Intake Software Market
Healthcare IT
Hospital Capacity Management Solutions Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Americas Healthcare Human Resources (HR) Software Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Asia-Pacific Dental Practice Management Software Market
Healthcare IT
Chiropractic Software Market
Healthcare IT
Global Pharmaceutical Quality Management Software Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
US Revenue Cycle Management Market
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Asia Pacific Healthcare IT Market