
 Transport Data Logger Market | 2026-2036
Transport Data Logger Market Size, Share, and Industry Trends Forecast 2026-2036
Transport Data Logger Market Analytics
Embedded systems engineering talent is rotating toward transport telemetry, unlocking firmware innovation for multi-sensor loggers. Samsara leverages cloud-native architecture to sustain its position in fleet telematics. Trimble anchors its presence through precision agriculture and construction crossovers into heavy-haul monitoring. Robert Bosch GmbH dominates automotive-grade sensor integration, supplying OEMs with CAN-bus compatible units.
A transport data logger is an electronic device that records vehicle, cargo, or environmental parameters—typically sampling GPS coordinates, temperature, speed, or fuel consumption at intervals ranging from one second to fifteen minutes—using onboard memory or wireless transmission to a central platform. Its primary purpose is to generate auditable records for operational optimization, regulatory compliance, and supply chain visibility. GPS loggers and temperature loggers command the largest installed base, though IoT-enabled systems represent the fastest-expanding technology category as cellular LPWAN coverage widens. Fleet management applications absorb the majority of hardware shipments, while cold chain monitoring commands premium pricing due to pharmaceutical and perishable food compliance requirements.
The FDA enforces food traceability rules that mandate granular temperature records across distribution chains, directly expanding logger deployment among food distributors. The EPA and NHTSA impose emissions and hours-of-service regulations that fleet operators address through automated logging. ELD mandates from the Federal Motor Carrier Safety Administration eliminated paper logbooks, embedding data loggers as standard equipment in US commercial vehicles. Stakeholders must monitor evolving cybersecurity standards for connected vehicle systems, as data integrity requirements harden alongside operational demands.
Market Dynamics
Fleet operators face simultaneous pressure from ELD mandates and cybersecurity hardening requirements, compressing procurement cycles while elevating technical specifications for connected logging hardware.
Growth Catalysts
- FDA Food Safety Modernization:Traceability mandates for perishable distribution chains compel food distributors to deploy temperature loggers at every transit node, creating recurring hardware refresh cycles.
- Cellular LPWAN expansion:Narrowband-IoT infrastructure buildout across Germany, France, and the Netherlands enables real-time transmission from previously disconnected rural corridors and maritime routes.
- Automotive OEM integration:CAN-bus compatible loggers ship as factory-fit equipment in commercial vehicle platforms, embedding compliance hardware before first registration.
Market Restraints
- Semiconductor supply concentration:GPS and cellular modem chip fabrication concentrates in Taiwan and South Korea, exposing logger manufacturers to allocation volatility and extended lead times.
- Lithium battery cost inflation:Power cell inputs for autonomous field-deployed units face commodity price pressure, compressing margins on temperature loggers for pharmaceutical cold chain.
- Legacy fleet inertia:Owner-operator segments with vehicles predating OBD-II standardization resist retrofit investments despite regulatory deadlines.
Strategic Opportunities
- Indian cold chain buildout:FSSAI enforcement of temperature documentation for dairy and vaccine distribution creates first-mover advantage for IoT logger vendors establishing local assembly partnerships.
- Rail freight telemetry:Intermodal operators seek cargo-condition monitoring for refrigerated containers, an application segment with minimal incumbent penetration.
- EU CSRD alignment:Corporate sustainability reporting requirements on supply chain emissions drive demand for fuel-consumption loggers with verified carbon accounting outputs.
Industry Challenges
- Firmware security certification:ISO/SAE 21434 automotive cybersecurity standards impose lengthy validation timelines for connected logger platforms, delaying product launches.
- Multi-protocol integration:Fleet management platforms require simultaneous support for SAE J1939, FMS, and proprietary OEM data buses, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transport Data Logger Market |
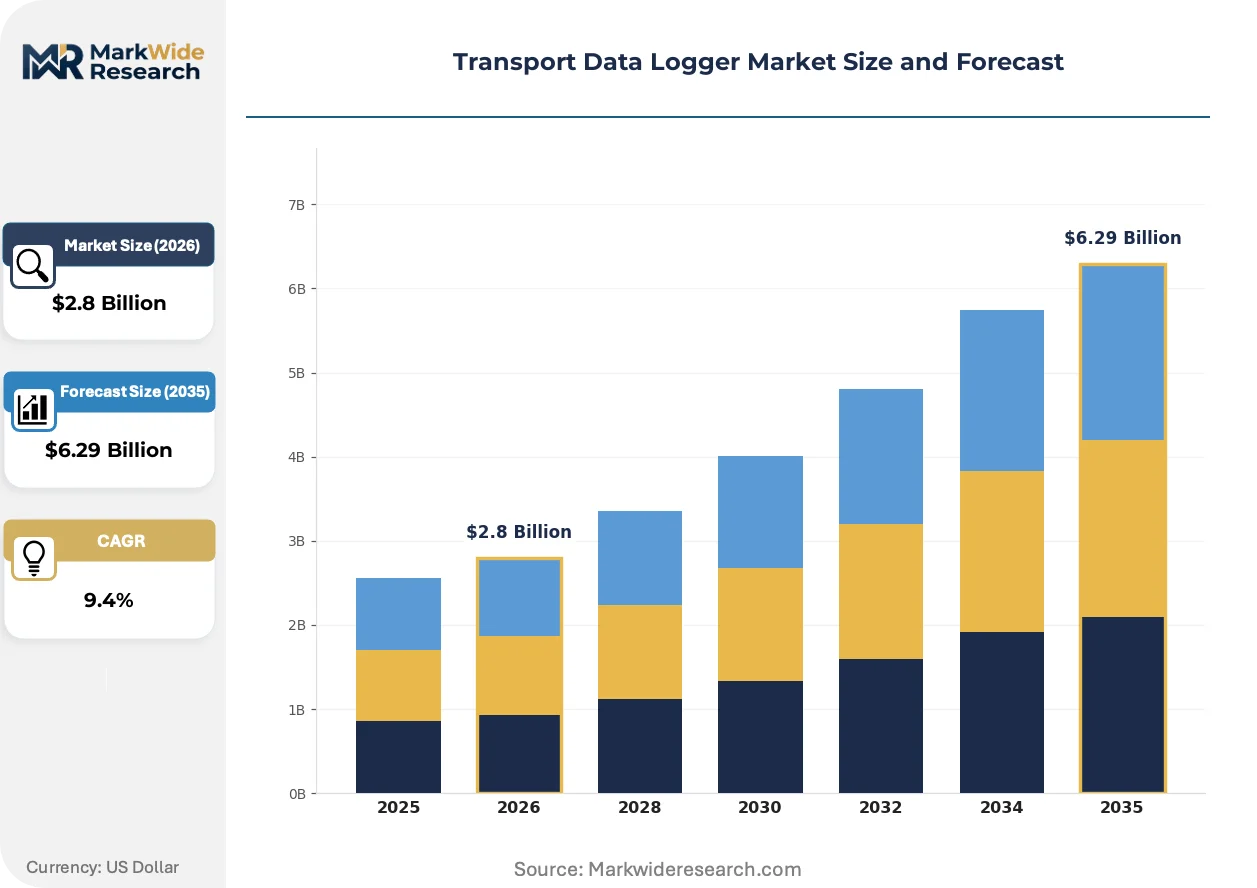
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Loggers, Temperature Loggers, Speed Loggers, Fuel Loggers Technology: Bluetooth, RFID, Wi-Fi, IoT Application: Fleet Management, Cold Chain Monitoring, Vehicle Tracking, Compliance Monitoring End User: Logistics Companies, Transportation Providers, Food Distributors, Retailers |
| Companies Covered | Teletrac Navman, Trimble, Samsara, Omnitracs, Motive, Geotab, Trackunit, Robert Bosch GmbH, Verizon Connect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transport Data Logger Market Evolving Landscape
Sensor fusion architectures and edge-computing capabilities are redefining what transport loggers capture and process locally before transmission, shifting value from data collection to real-time decision support.
Multi-sensor logger hardware is miniaturizing through system-in-package integration of accelerometers, gyroscopes, and environmental probes. Pharmaceutical distributors adopt palm-sized units for last-mile vaccine delivery validation. Component density gains are compressing unit costs while expanding deployment feasibility in space-constrained motorcycle couriers and drone payloads.
EPA emissions verification protocols now require tamper-evident data logging for heavy-duty diesel retrofits. Engine manufacturers integrate certified loggers as sealed subsystems to satisfy audit trails. Aftermarket suppliers face compliance cost escalation as Type Approval documentation requirements expand across California, Texas, and New York commercial vehicle regulations.
Buyers increasingly unbundle hardware acquisition from data platform subscriptions, treating loggers as commodity sensors while negotiating separately for analytics access. Third-party telematics aggregators in Germany and the Netherlands now provision devices below cost to capture recurring software revenue. Fleet operators in Benelux markets lead this preference shift, pressuring integrated vendors to decouple pricing architectures.
Transport Data Logger Market Segmentation
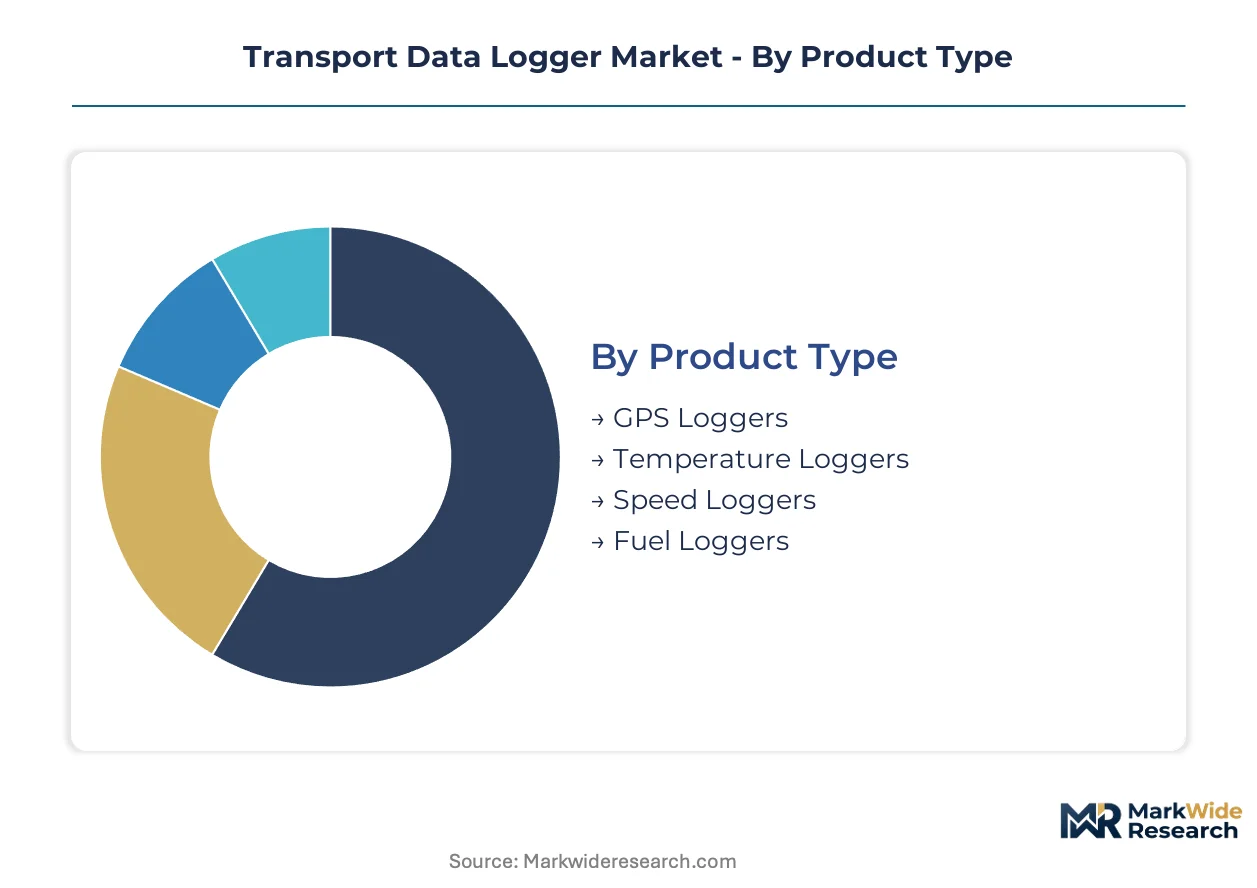
Transport data logger segmentation reveals divergent margin structures across hardware categories and service layers. Product type and technology choices determine whether vendors capture value through device sales or recurring platform subscriptions.
Product Type:
GPS loggers and temperature loggers command premium pricing pools, while speed and fuel variants compete on volume throughput.
- GPS Loggers:These units integrate multi-constellation satellite receivers with cellular modems for real-time position reporting. Fleet operators in Germany deploy factory-fit CAN-bus units for regulatory compliance and route optimization, with ELD mandates eliminating paper-based alternatives.
- Temperature Loggers:Pharmaceutical and perishable food distributors absorb hardware at three to four times standard fleet pricing due to FDA traceability requirements. Sensor calibration certificates and tamper-evident seals justify recurring validation service contracts.
- Speed Loggers:Insurance telematics programs drive aftermarket installation in commercial auto fleets.
- Fuel Loggers:Heavy-haul operators in Texas and California deploy these for EPA emissions verification and carbon accounting.
GPS loggers hold installed capacity. Temperature loggers are rotating up the share rankings.
Technology:
Technology selection determines connectivity cost structures and data latency profiles for end users.
- IoT:Narrowband-IoT and LTE-M modules enable real-time transmission from previously disconnected maritime and rural corridors. Pharmaceutical cold chain operators in the Netherlands prioritize these units for last-mile vaccine delivery validation, with cellular LPWAN infrastructure buildout reducing roaming costs.
- Bluetooth:Short-range protocols dominate last-mile handoff scenarios where cellular costs prove prohibitive.
- RFID:Passive tags support yard management and depot tracking without battery maintenance.
- Wi-Fi:Warehouse and depot environments leverage existing infrastructure for high-bandwidth uploads.
IoT deployments are climbing the fastest. Bluetooth retains dominant unit volume in cost-sensitive segments.
Application:
Application focus separates commodity hardware vendors from platform-integrated solution providers.
- Fleet Management:Telematics platforms aggregate GPS, speed, and fuel data for route optimization and driver behavior scoring. US commercial vehicle operators deploy these systems to satisfy FMCSA hours-of-service regulations, with ELD mandates embedding loggers as standard equipment.
- Cold Chain Monitoring:Temperature and humidity logging with audit trails commands software attach rates exceeding hardware pricing. Food distributors facing FDA Food Safety Modernization Act requirements deploy multi-sensor units at every transit node.
- Vehicle Tracking:Stolen vehicle recovery and asset location services drive consumer and light commercial adoption.
- Compliance Monitoring:EPA emissions verification protocols require tamper-evident data logging for heavy-duty diesel retrofits.
Fleet management absorbs majority hardware shipments. Cold chain monitoring generates highest revenue per unit.
End User:
End user type dictates procurement sophistication and subscription willingness.
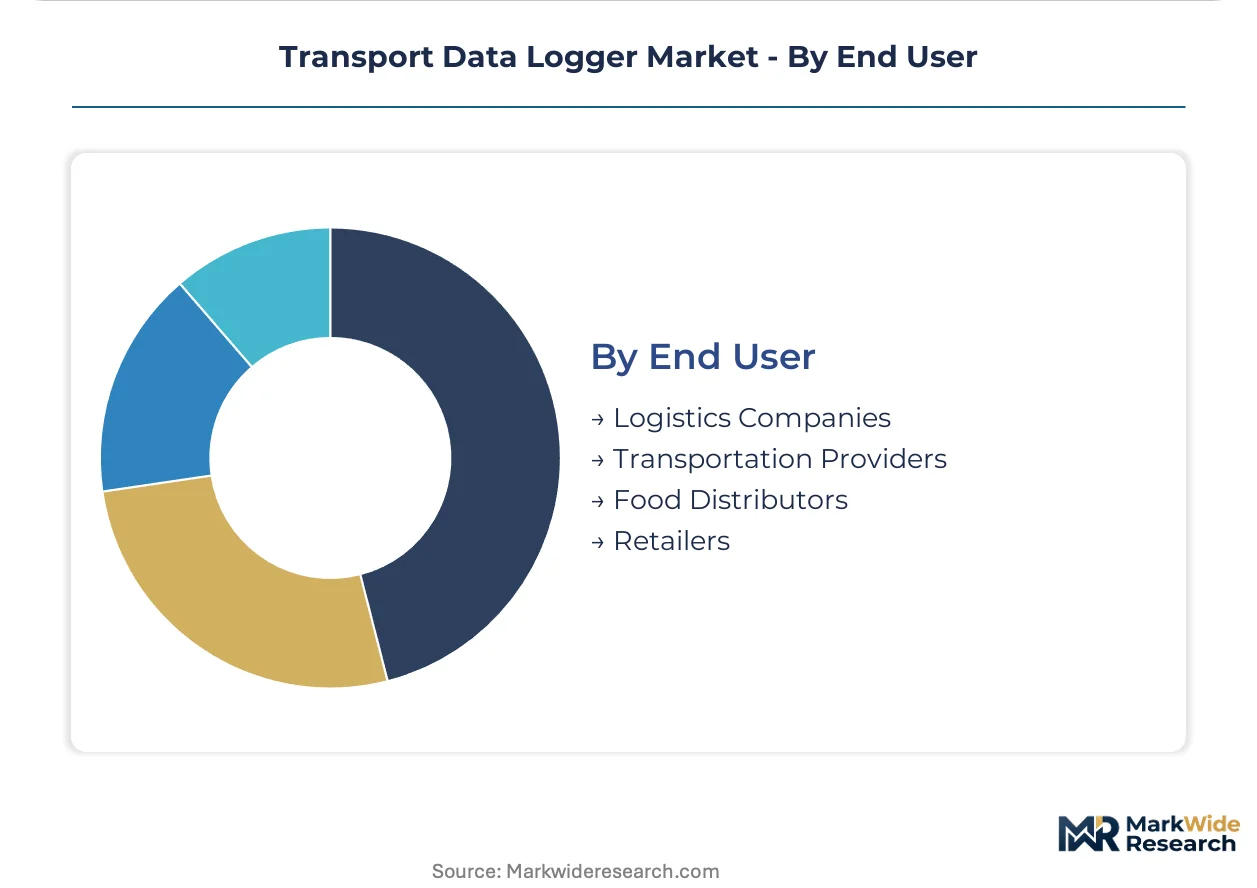
- Logistics Companies:Third-party logistics providers in Germany and the Netherlands unbundle hardware from analytics, treating loggers as commodity sensors while negotiating platform access separately. Scale operators drive volume pricing pressure on integrated vendors.
- Food Distributors:Perishable supply chain operators face regulatory mandates that override cost minimization priorities. FDA traceability rules compel temperature logger deployment across distribution nodes with documented chain-of-custody.
- Transportation Providers:Bus and rail operators seek cargo-condition monitoring for refrigerated intermodal containers.
- Retailers:Grocery chains deploy last-mile validation for e-commerce perishable delivery.
Logistics companies concentrate procurement volume. Food distributors are expanding fastest on regulatory compulsion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The KBA anchors European demand through stringent type-approval requirements for commercial vehicle telematics. Logger deployment concentrates where regulatory enforcement intersects with dense logistics infrastructure and automotive manufacturing clusters.
Germany
Automotive OEMs and third-party logistics providers drive factory-fit CAN-bus logger installations. The KBA enforces UN ECE R141 tachograph standards that mandate digital recording for commercial vehicles above 3.5 tonnes. Stuttgart and Munich anchor development clusters where Bosch and Continental integrate logging hardware into heavy-duty platforms before first registration.
United States
ELD mandates from the FMCSA eliminated paper logbooks, embedding data loggers as standard equipment in commercial vehicles. The EPA imposes emissions verification protocols requiring tamper-evident logging for heavy-duty diesel retrofits. Dallas-Fort Worth and Atlanta concentrate fleet operator procurement, with telematics aggregators provisioning devices below hardware cost to capture recurring software revenue.
Netherlands
Cellular LPWAN infrastructure buildout enables real-time transmission from maritime routes and rural corridors. The Dutch Food and Consumer Product Safety Authority enforces temperature documentation for perishable imports through Rotterdam. Eindhoven hosts embedded systems engineering clusters where firmware innovation accelerates for multi-sensor pharmaceutical cold chain units.
India
FSSAI enforcement of temperature documentation for dairy and vaccine distribution creates first-mover opportunities for IoT logger vendors. The PLI scheme for electronics manufacturing incentivizes local assembly partnerships. Maharashtra and Gujarat concentrate cold chain infrastructure buildout, with Mumbai pharmaceutical distributors deploying palm-sized validation units for last-mile delivery.
China
MIIT mandates connected vehicle data logging for new energy commercial vehicles under GB standards. Dual carbon goals drive fuel-consumption logger demand for verified carbon accounting in heavy-haul fleets. The Yangtze River Delta concentrates manufacturing capacity, with Shanghai-based telematics providers expanding narrowband-IoT coverage across inland waterway corridors.
Transport Data Logger Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with tiering determined by platform breadth versus hardware focus. The upper tier combines cloud-native software stacks with cellular-enabled hardware ecosystems, while specialists concentrate on single-parameter logging or vertical applications. Three archetypes dominate: integrated telematics platforms, automotive-grade sensor suppliers, and cold chain validation specialists. Competitive moves center on unbundling hardware from subscription pricing and establishing local assembly partnerships in emerging markets.
Within the integrated telematics tier, Samsara and Trimble occupy positions that exemplify cloud-native and precision-crossover strategies respectively. Samsara anchors the fleet management vector with cellular-first architecture, while Trimble extends construction and agriculture telemetry expertise into heavy-haul monitoring. Robert Bosch GmbH represents the automotive-grade archetype, supplying CAN-bus compatible units through factory-fit channels. Among emerging specialists, Motive demonstrates the compliance-focused positioning that targets ELD mandate saturation with driver-centric platform design.
| Leading Market Players |
|---|
| Teletrac Navman |
| Trimble |
| Samsara |
| Omnitracs |
| Motive |
| Geotab |
| Trackunit |
| Robert Bosch GmbH |
| Verizon Connect |
| Others |
Value Network & Pricing Analysis
Cellular LPWAN module substitution for legacy satellite modems simultaneously shifts component sourcing toward Taiwan and South Korea while compressing connectivity costs for fleet operators. This hardware transition redistributes value capture from device manufacturers toward platform providers bundling analytics subscriptions.
Pricing Analysis
Long-term offtake contracts dominate procurement for automotive OEMs integrating CAN-bus loggers at factory-fit, while spot purchasing persists in aftermarket retrofit segments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical units from fleet telematics hardware and basic GPS trackers. Cost compression in temperature logger tiers is intensifying because lithium battery inputs face commodity price pressure. Food distributors exhibit lowest price sensitivity due to regulatory compulsion, while owner-operator fleets resist retrofit investments despite ELD deadlines.
Supply Chain Analysis
Taiwan and South Korea anchor GPS receiver and cellular modem fabrication, with China concentrating final assembly and system integration. Logger production draws from semiconductor wafers, lithium power cells, and precision sensor substrates. Single-source vulnerability concentrates in Taiwan foundries producing automotive-grade microcontrollers. Distribution runs through telematics aggregators in Germany and the Netherlands provisioning devices below cost to capture recurring software revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellular LPWAN infrastructure buildout across Germany, France, and the Netherlands constitutes a high-growth disruption, with narrowband-IoT coverage expansion enabling real-time transmission from previously disconnected maritime and rural corridors.
For Market Incumbents: Compound platform stickiness through firmware security certification investments that satisfy ISO/SAE 21434 automotive cybersecurity standards, delaying competitive product launches. Deepen backward integration into sensor calibration capabilities to capture recurring validation service contracts from pharmaceutical distributors facing FDA traceability mandates. For New Entrants and Emerging Players: Last-mile vaccine delivery validation in India represents an underserved service-layer gap where FSSAI enforcement creates first-mover advantage for palm-sized multi-sensor units. Establish local assembly partnerships under the PLI scheme for electronics manufacturing. Target cold chain monitoring for rail freight intermodal containers through partnerships with refrigerated container operators. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telematics aggregators in Benelux markets unbundling hardware from analytics subscriptions. Five-to-ten year viability hinges on recurring revenue attach rates exceeding hardware pricing. Target acquisition archetype: cold chain validation specialists with FDA 21 CFR Part 11 compliance documentation. Signal to watch: firmware security certification timelines lengthening under evolving ISO/SAE 21434 standards.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Cloud-native architecture enables Samsara to sustain fleet telematics leadership through cellular-first design. |
| Geographic Expansion | Local assembly partnerships in Maharashtra and Gujarat capture FSSAI-mandated dairy and vaccine distribution opportunities. |
| Regulatory Certification Investment | ISO/SAE 21434 compliance documentation creates defensible moats against faster-moving unvalidated competitors. |
| Strategic Partnership | Automotive OEM integration through Bosch supplies CAN-bus compatible units before first vehicle registration. |
| Product Launch | Multi-sensor palm-sized units address pharmaceutical last-mile validation requirements for drone and motorcycle courier payloads. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs filings, FCC equipment authorization databases, and automotive production registries. Interviews with fleet operations directors, cold chain logistics managers, embedded systems engineers, and telematics platform product officers informed demand-side validation. Top-down market sizing triangulates against bottom-up unit shipment estimates across GPS, temperature, speed, and fuel logger categories.
Segmentation dimensions modeled include product type, connectivity technology, application vertical, and end-user procurement sophistication across the analysis window. CAGRs derive from regression analysis of historical adoption curves adjusted for regulatory inflection points including ELD mandates, FDA Food Safety Modernization Act enforcement, and EU CSRD alignment requirements. Forecast inputs incorporate cellular LPWAN infrastructure buildout timelines and semiconductor allocation volatility indices.
Underlying assumptions cover sustained regulatory enforcement of temperature documentation mandates, with deviation risk concentrated in semiconductor supply concentration and lithium battery cost trajectories. Recalibration cycles align with material shifts in cybersecurity certification standards and emerging market cold chain infrastructure investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
APAC Internet of Cars Market
Telematics and Infotainment
Automotive Data Monetization Market
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
GPS Tracker Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
In-Car Apps Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Video Telematics Market