
 Paper Tester Market | 2026-2036
Paper Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Tester Market Outlook
Capital-intensity divergence between automated optical systems and legacy mechanical testers is collapsing as mid-tier suppliers close the precision gap through digital sensor integration. AMETEK leverages its multi-industry instrumentation platform to cross-subsidize paper-tester R&D, while Thwing-Albert Instrument Company anchors its position through deep specialization in North American tensile and burst testing protocols. Gurley Precision Instruments competes on air-resistance measurement heritage that few rivals replicate at equivalent accuracy thresholds.
A paper tester is a quality-assurance instrument that measures physical, optical, or electrical properties of paper and paperboard, typically quantifying grammage in grams per square meter, moisture content within percentage tolerances, or thickness in micrometers to ensure conformance to ISO 534 and TAPPI T411 standards. The primary industrial purpose is to certify that raw paper stocks and finished packaging substrates perform predictably during printing, converting, and end-use handling. Optical technology leads installed base volume due to non-destructive speed advantages in high-throughput mills, while digital systems represent the fastest-expanding category as Industry 4.0 protocols demand real-time data streaming into mill ERP platforms. Mechanical testers retain durable positions in compliance verification where regulatory audit trails require physical specimen destruction for archival documentation.
ISO standards, EPA emissions guidelines for pulp and paper facilities, and EU Green Deal recycled-content verification requirements collectively elevate tester precision thresholds and calibration frequency mandates. FDA food-contact substrate rules in the United States and REACH chemical disclosure obligations in Europe further tighten the specification bands that instruments must reliably distinguish. Stakeholders should monitor how dual carbon goals in China and emerging Southeast Asian packaging hubs redirect capital toward inline digital systems that reduce laboratory bottlenecks and energy-intensive retesting cycles.
Market Dynamics
Inline digital sensor networks are collapsing the traditional separation between laboratory verification and production-floor quality control, forcing instrument suppliers to rearchitect their hardware-software stacks for real-time ERP integration.
Growth Catalysts
- EU Green Deal recycled-content mandates:Packaging converters across Germany, France, and Italy now require automated grammage verification systems to certify post-consumer fiber percentages in corrugated substrates.
- Pulp-to-packaging integration:Vertically integrated mills in the United States demand continuous moisture monitoring to reduce energy-intensive drying cycles and fiber waste.
- ISO 534 thickness standard updates:Revised calibration protocols are compelling Asian packaging hubs to replace legacy mechanical micrometers with non-contact optical systems.
Market Restraints
- Precision sensor import concentration:German and Japanese photodiode suppliers control critical components for optical testers, exposing buyers to currency volatility and allocation constraints.
- Mechanical tester installed base inertia:North American compliance laboratories retain capital-intensive burst and tensile equipment with decade-long depreciation schedules, slowing digital replacement cycles.
- REACH chemical disclosure complexity:European substrate manufacturers face documentation burdens that extend tester validation timelines and increase recertification costs.
Strategic Opportunities
- India packaging expansion:BIS certification requirements for food-contact paperboard are creating first-mover advantages for suppliers offering integrated moisture-grammage systems with localized calibration support.
- Cloud-native predictive maintenance:Convergence of edge computing and vibration analytics enables subscription-based uptime guarantees that transform capital equipment into recurring revenue streams.
- EPA emissions enforcement tightening:United States pulp mills face heightened monitoring obligations that favor inline testers reducing laboratory sample transportation and associated carbon reporting.
Industry Challenges
- Metrology technician scarcity:Specialized skills in ISO 17025 calibration procedures and TAPPI method interpretation are concentrating in aging workforces across Midwestern United States mill towns.
- Legacy DCS integration complexity:Brownfield packaging plants operate programmable logic controllers from the 1990s that lack native OPC-UA connectivity for modern digital tester data streams.
- Multi-standard harmonization delays:Divergent certification timelines between ISO, TAPPI, and JIS protocols force instrument manufacturers to maintain redundant firmware branches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Tester Market |
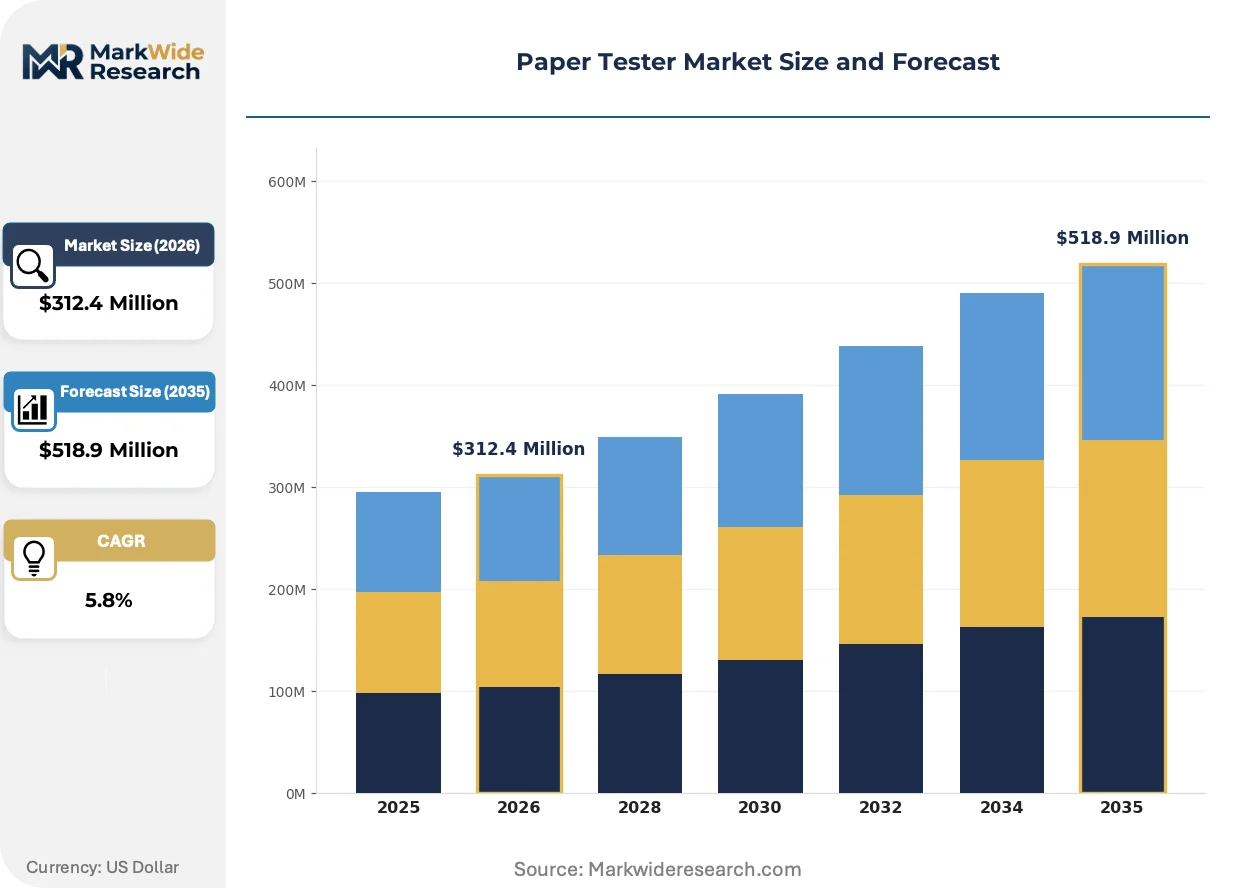
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grammage Tester, Moisture Meter, Thickness Gauge, Color Measurement Device End User: Pulp Mills, Printing Houses, Research Laboratories, Packaging Companies Technology: Optical, Mechanical, Electrical, Digital Application: Quality Control, Research & Development, Product Testing, Compliance Verification |
| Companies Covered | Testing Machines, AMETEK, Gurley Precision Instruments, Thwing-Albert Instrument Company, Techlab Systems, AML Instruments, Angels Instruments, RYCOBEL, Gester Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Tester Market Strategic Shifts
Spectral imaging systems are redefining quality assurance by capturing substrate properties invisible to mechanical contact methods, compressing inspection cycles from minutes to milliseconds.
Hyperspectral cameras paired with chemometric algorithms now detect coating uniformity and fiber orientation without physical specimen destruction. European luxury packaging converters in the Netherlands and Belgium are deploying these systems at web speeds exceeding 800 meters per minute. This capability is supplanting laboratory spot-checking protocols that previously required stopping production lines for manual sampling.
EPA effluent limitation guidelines for pulp and paper facilities are mandating tighter process control to reduce chemical oxygen demand in wastewater streams. Mills in Wisconsin and Washington State now link tester data directly to chemical dosing systems. Integrated operations teams are responding by specifying instruments with native Modbus and Ethernet/IP connectivity rather than standalone laboratory units.
Consolidated buying groups at North American corrugated producers are unbundling after-sales service from hardware procurement, negotiating third-party calibration contracts independent of original equipment manufacturers. This behavior concentrates in the Great Lakes region where packaging cooperatives aggregate demand across twelve member mills. Regional service providers with ISO 17025 accreditation are capturing maintenance revenue previously retained by instrument vendors.
Paper Tester Market Segmentation
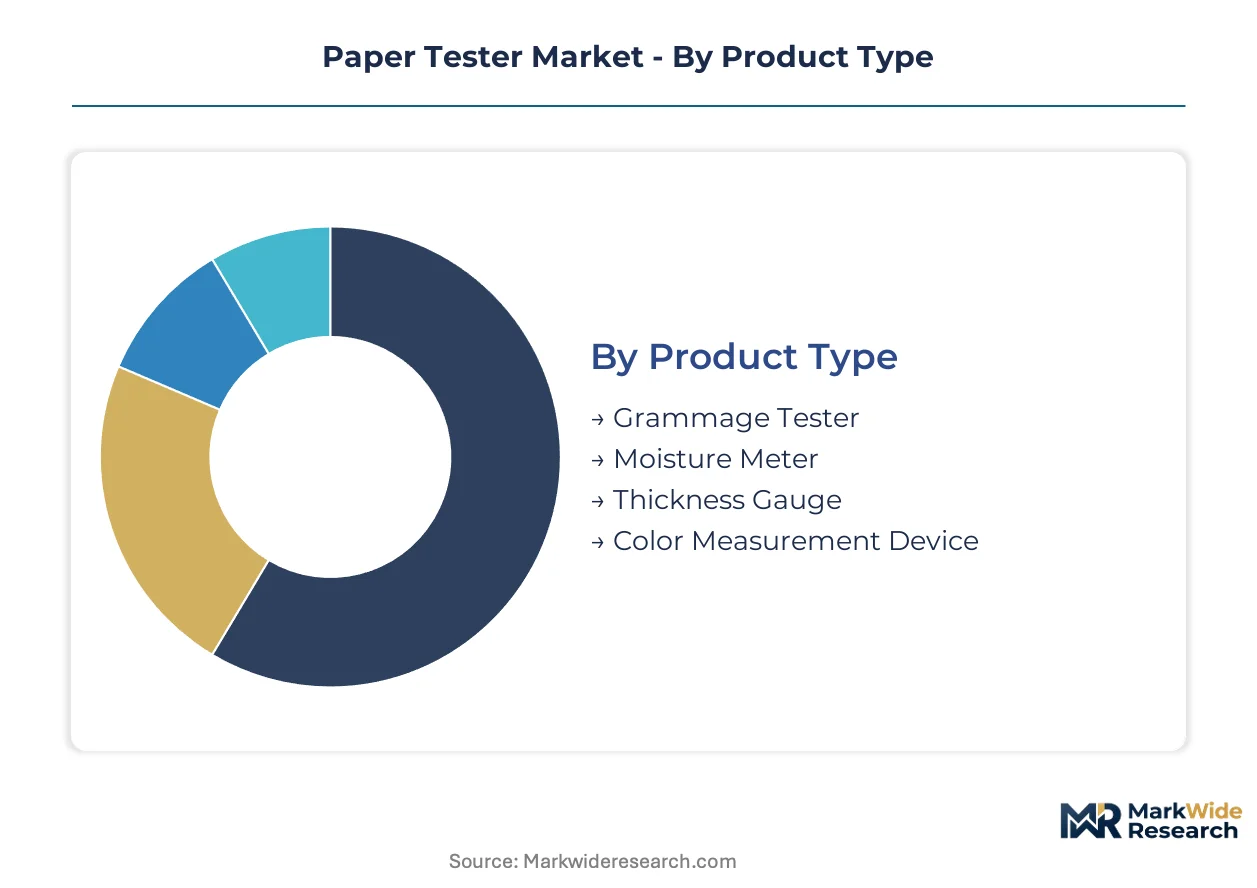
Paper tester segmentation reveals how regulatory precision thresholds reshape procurement patterns across instrument categories. Buyers now select technologies based on specific compliance mandates rather than general performance specifications.
Product Type:
EPA effluent guidelines and EU Green Deal recycled-content rules create divergent instrument requirements across substrate verification protocols.
- Grammage Tester:Measures basis weight in grams per square meter using precision load cells or beta-ray attenuation. German corrugated converters deploy these systems to certify post-consumer fiber percentages under EU Green Deal mandates, with inline configurations replacing laboratory spot-checking to eliminate production bottlenecks.
- Moisture Meter:Employs capacitance or infrared spectroscopy to quantify water content within percentage tolerances. Vertically integrated mills in Wisconsin and Washington State specify continuous monitoring versions to reduce energy-intensive drying cycles and fiber waste, directly linking tester outputs to steam valve controls.
- Thickness Gauge:ISO 534 calibration protocols favor non-contact optical micrometers over mechanical contact methods.
- Color Measurement Device:Spectrophotometric systems verify substrate whiteness and opacity for luxury packaging grades.
Grammage testers handle the majority of throughput; moisture meters are expanding most quickly on share as pulp-to-packaging integration accelerates.
End User:
Cost tier differentiation separates capital-intensive inline installations from portable laboratory units across buyer categories.
- Pulp Mills:Operate the highest-throughput testing infrastructure with continuous moisture and grammage verification at web speeds exceeding 800 meters per minute. EPA emissions enforcement in Wisconsin and Washington State drives preference for instruments with native Modbus connectivity to integrate directly with distributed control systems.
- Packaging Companies:Consolidated buying groups in the Great Lakes region now unbundle after-sales service from hardware procurement, negotiating third-party calibration contracts independent of original equipment manufacturers.
- Printing Houses:Require spot-checking portability for incoming substrate verification.
- Research Laboratories:Retain capital-intensive burst and tensile equipment with decade-long depreciation schedules.
Pulp mills command the largest installed base; packaging companies are gaining share fastest as corrugated demand concentrates in cooperative purchasing structures.
Technology:
Application maturity separates established optical methods from emerging digital architectures requiring ERP integration capabilities.
- Optical:Non-destructive spectral imaging captures substrate properties invisible to mechanical contact methods. European luxury packaging converters in the Netherlands and Belgium deploy hyperspectral cameras at web speeds exceeding 800 meters per minute, compressing inspection cycles from minutes to milliseconds.
- Digital:Industry 4.0 protocols demand real-time data streaming into mill ERP platforms through OPC-UA and MQTT connectivity. Brownfield plants face integration complexity with 1990s-era programmable logic controllers lacking native digital interfaces.
- Mechanical:Retains durable positions where regulatory audit trails require physical specimen destruction for archival documentation.
- Electrical:Measures dielectric properties for specialized coating uniformity applications.
Optical systems handle the majority of throughput; digital architectures are climbing the fastest as mill modernization programs accelerate.
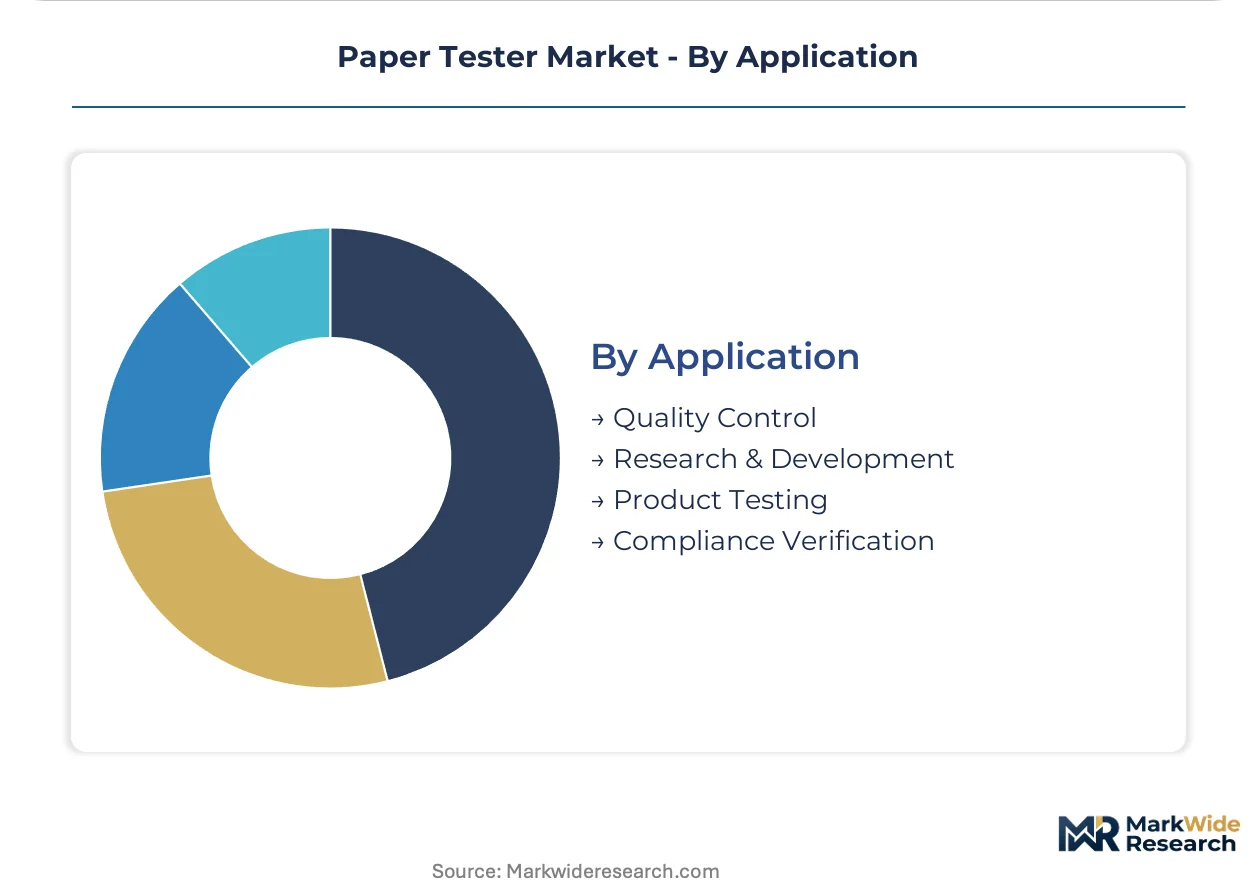
Application:
Customer type concentration splits between compliance-driven verification and proactive quality optimization objectives.
- Quality Control:Inline sensor networks collapse the traditional separation between laboratory verification and production-floor monitoring. Mills in the United States link tester data directly to chemical dosing systems to meet EPA effluent limitation guidelines for wastewater stream management.
- Compliance Verification:FDA food-contact substrate rules and REACH chemical disclosure obligations tighten specification bands that instruments must reliably distinguish. European substrate manufacturers face documentation burdens that extend tester validation timelines.
- Research & Development:Concentrates in specialized fiber science institutes and university partnerships.
- Product Testing:Supports new substrate qualification for packaging converters.
Quality control handles the majority of throughput; compliance verification is gaining share fastest as regulatory precision thresholds escalate across jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and United States mill clusters where integrated pulp-to-packaging operations demand precision verification systems. Cost-sensitive packaging converters in India and Southeast Asia favor mid-tier digital alternatives that narrow the performance gap with premium optical architectures.
United States
Wisconsin and Washington State pulp mills anchor North American demand for continuous moisture monitoring systems that reduce energy-intensive drying cycles. EPA effluent limitation guidelines for chemical oxygen demand in wastewater streams mandate tighter process control, linking tester data directly to chemical dosing infrastructure. Vertically integrated operations in the Pacific Northwest specify instruments with native Modbus connectivity for distributed control system integration.
Germany
Corrugated converters across Bavaria and North Rhine-Westphalia deploy automated grammage verification to certify post-consumer fiber percentages under EU Green Deal recycled-content mandates. REACH chemical disclosure obligations tighten specification bands that instruments must reliably distinguish, extending validation timelines for substrate manufacturers. Stuttgart-based packaging cooperatives aggregate procurement across member mills, unbundling after-sales service from hardware acquisition.
India
BIS certification requirements for food-contact paperboard create first-mover advantages for suppliers offering integrated moisture-grammage systems with localized calibration support. Maharashtra and Gujarat packaging clusters drive demand as converters modernize quality infrastructure to serve export markets. Domestic instrument providers compete on service proximity against premium imports from German and Japanese manufacturers.
China
Dual carbon goals redirect capital toward inline digital systems that reduce laboratory bottlenecks and energy-intensive retesting cycles across Yangtze River Delta packaging hubs. National standards harmonization pressures drive replacement of legacy mechanical micrometers with non-contact optical systems in Shandong Peninsula pulp operations. Provincial environmental regulators tighten emissions monitoring obligations that favor real-time verification over batch sampling protocols.
Netherlands
Luxury packaging converters in the Randstad region deploy hyperspectral imaging systems at web speeds exceeding 800 meters per minute for coating uniformity verification. EU Green Deal compliance requirements concentrate demand for non-destructive inspection that eliminates production line stoppages for manual sampling. Eindhoven-area technology clusters support edge computing integration for predictive maintenance subscriptions.
Paper Tester Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where precision optical specialists coexist with digitally-integrated mid-tier challengers. Multi-industry instrumentation conglomerates cross-subsidize paper-tester research through broader metrology platforms, while deep specialists anchor positions through decades-long calibration heritage and TAPPI protocol authority. Three archetypes dominate: diversified measurement conglomerates, heritage precision specialists, and agile digital integrators. Competitive dynamics center on strategic partnerships for ERP connectivity and geographic expansion through localized service accreditation.
Within the heritage specialist tier, Gurley Precision Instruments and Thwing-Albert Instrument Company exemplify positioning built on decades of protocol-specific expertise and North American tensile testing authority. AMETEK occupies a position as the diversified conglomerate archetype, leveraging multi-industry instrumentation scale to fund paper-tester development through cross-platform engineering resources. These three entities represent the competitive poles around which mid-tier digital challengers organize their market entry strategies.
| Leading Market Players |
|---|
| Testing Machines |
| AMETEK |
| Gurley Precision Instruments |
| Thwing-Albert Instrument Company |
| Techlab Systems |
| AML Instruments |
| Angels Instruments |
| RYCOBEL |
| Gester Instruments |
| Others |
Value Chain & Pricing Dynamics
Ninety-day lead times for German photodiode arrays concentrate pricing power with optical component suppliers, compressing margins for mid-tier instrument manufacturers while rewarding buyers with strategic stockpile positions. This inventory dynamic feeds directly into how packaging cooperatives negotiate calibration service unbundling against original equipment manufacturers.
Pricing Analysis
Configured-to-order pricing for inline digital testers commands a 40-60% premium over standard laboratory units, with differentiation driven by ERP integration depth and ISO 17025 calibration certification tier. Three-tier pricing structure across premium, standard, and economy levels stratifies by sensor precision and after-sales bundling, though cost compression in the mid-tier is intensifying as Asian digital challengers narrow the performance gap. Packaging cooperatives in the Great Lakes region exhibit highest price sensitivity through consolidated procurement, while vertically integrated pulp mills in Wisconsin and Washington State prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among North American buyers hedging against German and Japanese photodiode allocation constraints, while just-in-time procurement prevails in European luxury packaging hubs with localized supplier relationships. Component sourcing draws from Germany for precision photodiodes, Japan for infrared spectroscopy modules, and China for capacitance sensor assemblies. Single-source vulnerability in beta-ray attenuation sources creates structural exposure to export licensing delays. Distribution runs through manufacturer-direct channels for large mill installations, with regional service providers capturing aftermarket calibration revenue previously retained by original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in mid-tier digital integration, as pulp-to-packaging verticalization and regulatory precision thresholds splinter demand across specialized instrument configurations rather than consolidated procurement.
For Market Incumbents: Consolidate calibration heritage and TAPPI protocol authority into subscription-based predictive maintenance offerings, locking in revenue streams against emerging digital challengers with cloud-native architectures. Defend position by acquiring regional service providers with ISO 17025 accreditation in the Great Lakes and Pacific Northwest mill clusters, securing maintenance revenue that cooperative buying groups are actively unbundling from hardware procurement. For New Entrants and Emerging Players: Differentiate on localized calibration support and BIS certification pathway expertise for Maharashtra and Gujarat packaging clusters, where domestic instrument providers compete on service proximity against premium German and Japanese imports. Target India's food-contact paperboard verification segment as the most penetrable white space, offering integrated moisture-grammage systems with faster validation timelines than legacy import channels. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory precision mandates and Industry 4.0 integration requirements are raising barriers for sub-scale competitors while rewarding multi-protocol capability breadth. Acquisition target archetype: mid-tier digital integrators with native OPC-UA connectivity and established mill ERP integration track records. Watch EPA effluent enforcement tightening in Wisconsin and Washington State as the signal indicating accelerated replacement cycles for legacy mechanical testers.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Predictive Maintenance Launch | Transforms capital equipment into recurring revenue through vibration analytics and edge computing subscriptions. |
| Regional Service Provider Acquisition | Captures calibration revenue that Great Lakes packaging cooperatives are actively unbundling from hardware procurement. |
| ISO 17025 Accreditation Expansion | Meets EU Green Deal validation timeline requirements that REACH chemical disclosure obligations have extended. |
| Modbus and Ethernet/IP Native Integration | Aligns with EPA effluent guideline mandates linking tester data directly to chemical dosing systems in Wisconsin mills. |
| Hyperspectral Imaging Partnership | Accelerates coating uniformity verification for Netherlands luxury packaging converters operating above 800 meters per minute. |
Study Parameters
Cross-validation between mill maintenance director interviews and TAPPI technical committee documentation anchors the qualitative findings, with secondary validation drawing from EPA effluent guideline filings, ISO standard revision records, and SEC 10-K disclosures from multi-industry instrumentation conglomerates. Primary fieldwork engaged plant engineers at vertically integrated pulp operations, procurement leads at corrugated packaging cooperatives, aftermarket service heads at regional calibration providers, and technical R&D directors at optical component suppliers. Bottom-up instrument shipment analysis triangulates against top-down packaging production capacity estimates across the analysis window.
Sensitivity analysis around photodiode supply constraints and currency volatility scenarios shapes the forecast framework, with segmentation modeling across product type (grammage, moisture, thickness, color), technology architecture (optical, digital, mechanical), and end-user category (pulp mill, packaging converter, research laboratory). CAGRs derive from installed base replacement cycle analysis and greenfield capacity expansion pipelines, incorporating pulp-to-packaging integration intensity and regulatory precision threshold escalation as industry-specific demand drivers.
Material uncertainties — German and Japanese component export licensing shifts, REACH validation timeline extensions, and brownfield PLC integration complexity — sit outside the modeled envelope. Forecasts reflect assumptions around continued EPA enforcement tightening and EU Green Deal recycled-content mandate implementation. Practitioners should keep alternative scenarios live as dual carbon goal acceleration in China and BIS certification requirement evolution in India reshape capital allocation priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Mud Sediment Tester Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Viscometer Market
Testing Equipment
Adhesive Tester Market
Testing Equipment
Global Liquid Process Analyzer Market
Testing Equipment
Liquid Analytical Instrument Market
Testing Equipment
High Performance Liquid Chromatography (HPLC) Market
Testing Equipment
CHS (Carbon Hydrogen Sulfur) Analyzers Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
In Line Process Viscometer (ILPV) Market
Testing Equipment
Global Insulation Testers Market
Testing Equipment
Steel Testing Equipment Market
Testing Equipment
Gold Tester Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
FTIR Fuel Analyzer Market