
 Middle East and Africa Personal Care Packaging Market | 2026-2036
Middle East and Africa Personal Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Personal Care Packaging Market Foresight
Premium-grade laminate specifications is bifurcating the Middle East and Africa personal care packaging landscape as brands pursue longer shelf stability in hot-climate distribution. Amcor PLC leverages its regional film extrusion footprint to supply barrier-enhanced structures for fragrance and skincare clients. AptarGroup Inc competes through precision pump and sprayer technologies that dominate premium haircare and cosmetic dispensing across Gulf markets. Mondi Group anchors sustainable paper-based alternatives, positioning kraft and molded-fiber solutions for brands targeting plastic-reduction commitments.
Personal care packaging encompasses engineered containers, closures, and protective structures designed to preserve product integrity, enable controlled dispensing, and communicate brand identity through surface graphics and form factors; specifications typically address barrier performance against oxygen and moisture ingress, compatibility with alcohol-based and oil-based formulations, and compliance with regional temperature exposure profiles reaching fifty degrees Celsius in ambient storage. Plastic bottles and tubes sustain volume leadership across haircare and mass skincare segments due to cost efficiency and injection-stretch blow molding scalability. Glass jars concentrate margin pools in prestige cosmetics and fragrance where weight, clarity, and perceived luxury justify higher unit economics. Pump closures represent the fastest-growing closure category as serum and lotion formats displace traditional crimp tubes in premium skincare routines.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology shape product safety and labeling requirements for cosmetic packaging across the Gulf, while ECHA REACH frameworks influence material compliance for European-imported substrates used by regional converters. South Africa's National Regulator for Compulsory Specifications enforces migration limits and recycling content thresholds that redirect formulation choices for packaging destined in Sub-Saharan markets. Stakeholders must monitor evolving extended producer responsibility schemes and halal certification alignment as dual compliance gateways that will determine supplier qualification and contract renewal terms across the region.
Market Dynamics
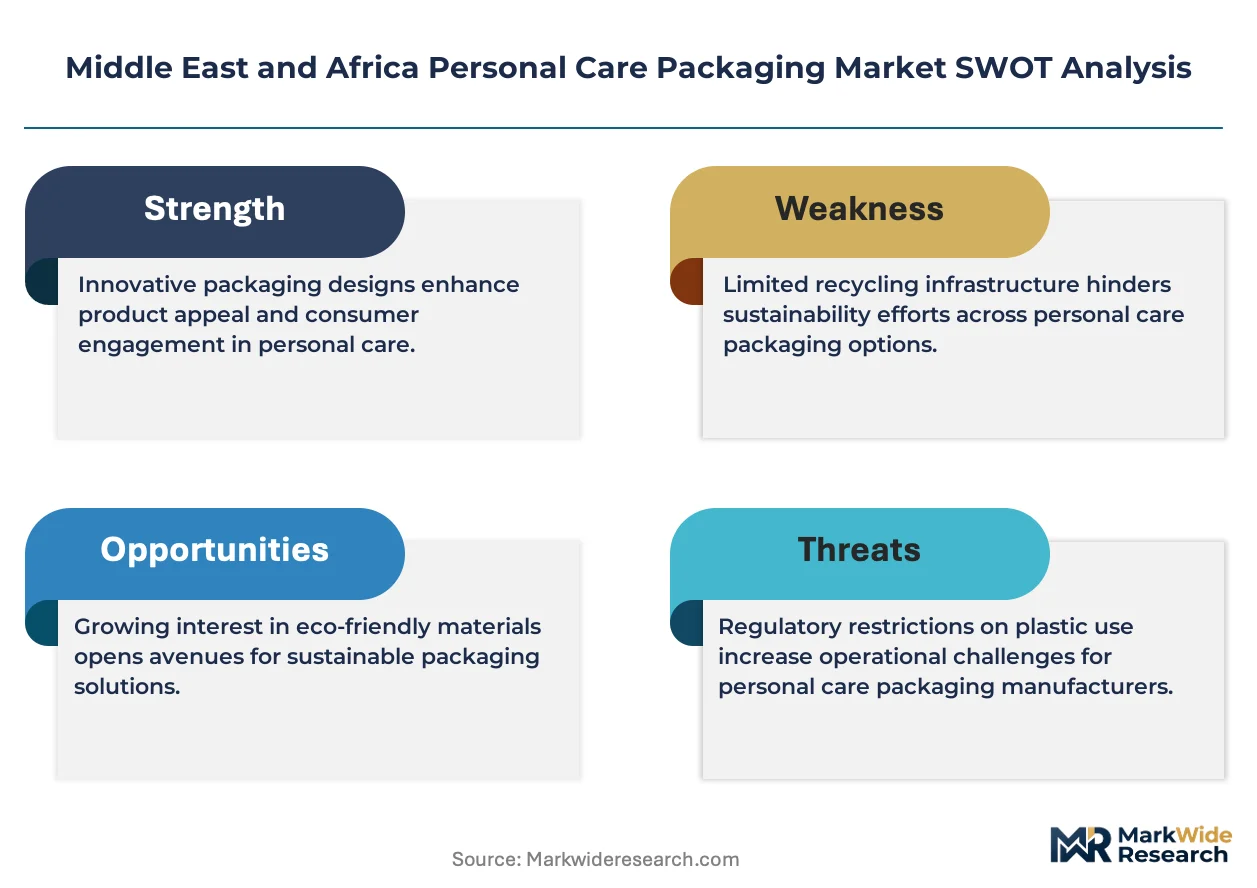
Halal certification mandates from Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology are forcing packaging converters across the Gulf to revalidate substrate supply chains and reformulate barrier coatings for alcohol-free compatibility.
Growth Catalysts
- Hot-climate barrier specifications:Premium skincare brands in Saudi Arabia and the UAE now require laminate structures rated for fifty-degree Celsius ambient storage, expanding addressable demand for high-performance films.
- SFDA halal compliance deadlines:Mandatory certification timelines for cosmetic packaging are accelerating qualification cycles for regional converters with pre-certified substrate libraries.
- Urban retail infrastructure:Mall-based prestige cosmetics retail in Dubai and Riyadh concentrates demand for pump-dispensed serum formats that command premium unit economics.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin costs fluctuate with Gulf crude pricing, compressing converter margins on fixed-price annual contracts.
- European substrate dependency:Barrier film and metallized structures for fragrance packaging concentrate supply in German and Italian extrusion facilities, exposing buyers to euro-denominated cost swings and extended lead times.
- Halal coating technical limitations:Alcohol-free adhesive systems for laminate bonding exhibit reduced shear strength versus conventional urethanes, limiting line speeds and yield rates.
Strategic Opportunities
- Nigeria and Kenya mass-market penetration:Underdeveloped formal retail channels for haircare and basic skincare present first-mover openings for sachet and flexible pouch formats at sub-dollar price points.
- South African EPR alignment:Extended producer responsibility schemes under the National Regulator for Compulsory Specifications create preferential procurement status for packaging with verified post-consumer recycled content.
- Airless pump-sachet convergence:Hybrid formats combining precision dosing with single-use economics target travel-retail and hospitality amenity channels across Gulf airport duty-free zones.
Industry Challenges
- Halal certification timeline compression:Multi-stage laboratory validation for coating migration and alcohol residue testing extends new product qualification from twelve to twenty-four weeks.
- Barrier film-to-paper reconfiguration:Brand plastic-reduction commitments require capital-intensive line conversions for molded-fiber and kraft-based alternatives with unproven scalability for high-volume haircare.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Personal Care Packaging Market |
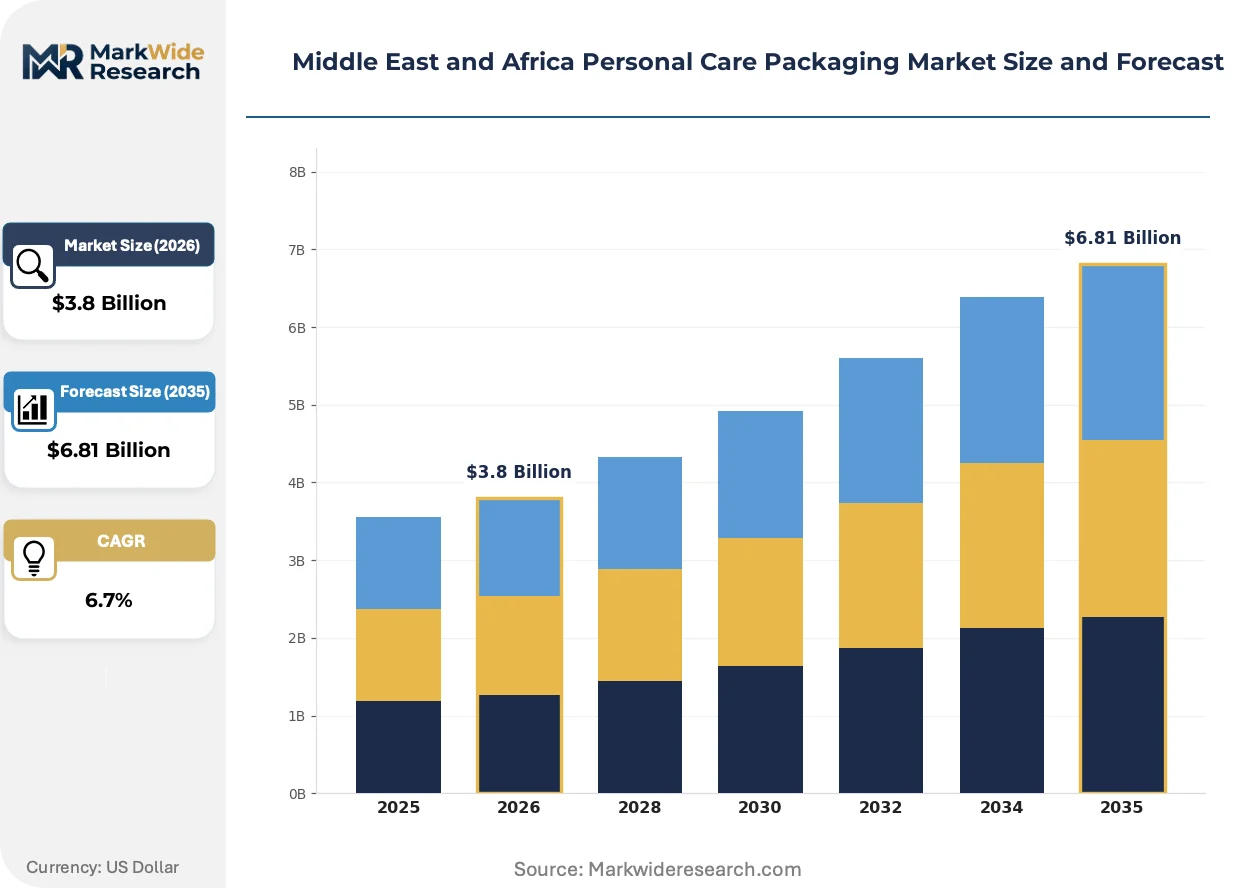
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Jars, Tubes, Pouches Material: Plastic, Glass, Metal, Paper Closure Type: Lids, Pumps, Sprayers, Caps End User: Cosmetics, Skincare, Haircare, Fragrance |
| Companies Covered | Amcor PLC, Silgan Holdings Inc, AptarGroup Inc, Berry Global Inc, Albea Group, Mondi Group, Huhtamaki Group, ALPLA Group, DS Smith PLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Personal Care Packaging Market Shifts & Advancements
Material science advances and regulatory alignment pressures are actively restructuring competitive capabilities across Middle East and Africa personal care packaging, with sustainability specifications and dispensing precision emerging as primary differentiation vectors.
Airless pump systems utilizing multi-layer EVOH barrier chambers are displacing traditional crimp tubes in premium skincare dispensing across Saudi Arabia and UAE prestige retail channels. Serum and lotion brands now specify piston-based mechanisms to eliminate oxidation and enable preservative-free formulations. This displacement compresses demand for aluminum-laminate squeeze tubes while expanding addressable margin pools for precision-molded actuator suppliers.
SFDA and ESMA alignment with ECHA REACH substance restrictions is tightening migration limits for phthalate plasticizers and bisphenol derivatives in cosmetic-contact materials. Regional converters must now document full supply chain substance inventories for fragrance and skincare packaging destined for Gulf markets. European-imported substrates face accelerated substitution pressure as local extruders invest in halal-certified alternative chemistries.
Direct-to-consumer subscription models for personalized skincare regimens are fragmenting traditional wholesale procurement patterns across South Africa and Nigeria. Beauty brands now specify smaller-batch packaging with variable surface printing for individualized regimen labeling. This behavioral shift concentrates demand for digital printing-enabled converters in Johannesburg and Lagos while compressing volume commitments to legacy rotogravure suppliers.
Middle East and Africa Personal Care Packaging Market Segmentation
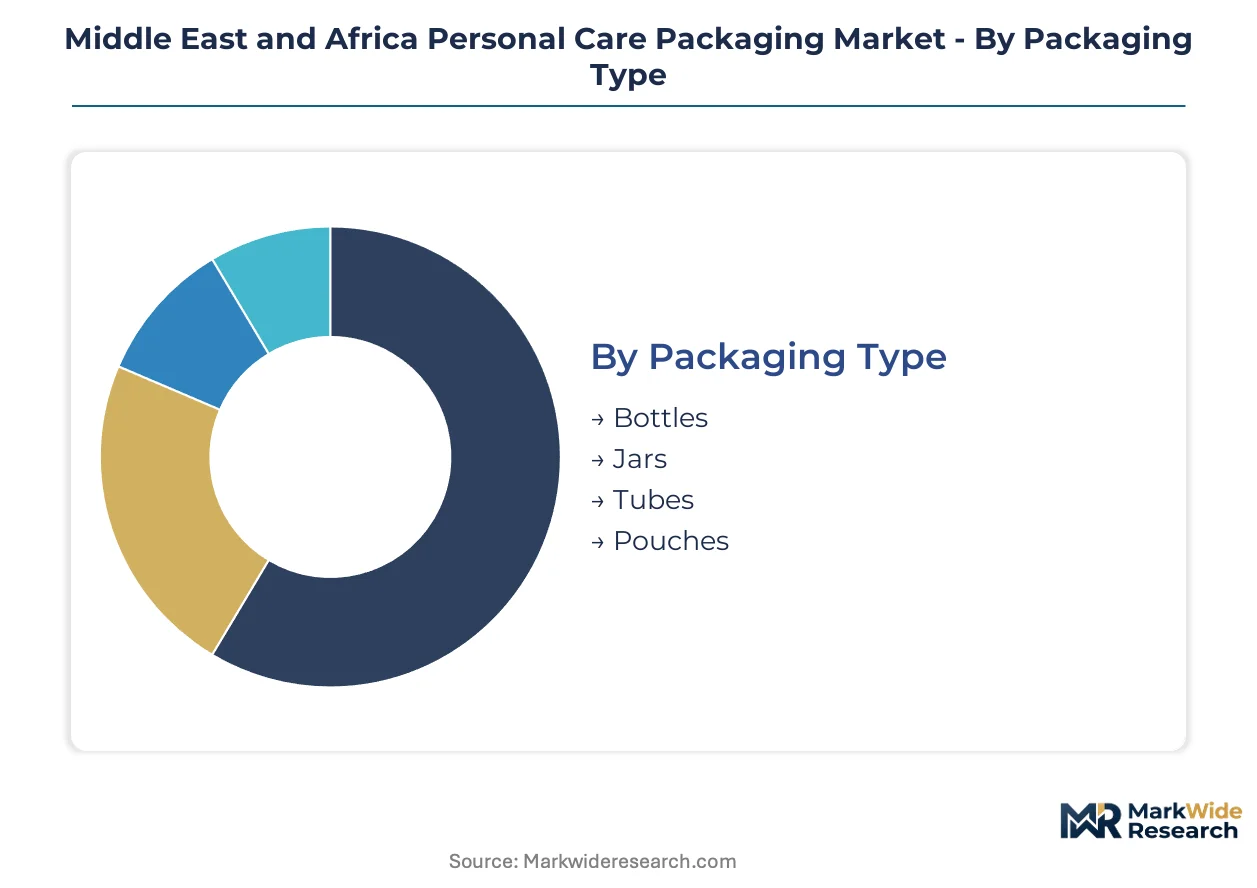
Packaging specifications across the Middle East and Africa diverge sharply between Gulf prestige retail and Sub-Saharan mass-market channels. Halal certification requirements and hot-climate distribution demands reshape which formats capture margin pools across each segment category.
Packaging Type:
Bottles command the largest margin pools in this category, driven by serum and lotion proliferation in Saudi and UAE prestige retail.
- Bottles:Injection-stretch blow molded PET and HDPE structures dominate haircare and mass skincare volumes. SFDA halal compliance deadlines accelerate demand for alcohol-free barrier coatings in Riyadh and Jeddah distribution networks.
- Jars:Glass and thick-walled PET configurations concentrate in prestige cosmetics where weight and clarity signal luxury. Dubai mall-based retail channels specify wide-mouth formats for cream and balm textures that justify premium unit economics.
- Tubes:Aluminum-laminate and all-plastic extrusions serve travel-size and sample formats across Gulf duty-free zones. Squeeze dispensing remains cost-efficient for basic haircare in Nigerian and Kenyan informal retail.
- Pouches:Flexible stand-up and flat configurations target single-use sachet economics in Sub-Saharan mass markets. Spouted variants gain traction for refill systems in South African urban convenience retail.
Bottles hold installed capacity across Gulf converter networks. Pouches are rotating up the share rankings through Nigerian and Kenyan penetration strategies.
Material:
Plastic sustains volume leadership while glass and paper capture expanding margin premiums from sustainability positioning.
- Plastic:Polypropylene and polyethylene resins supply cost-scalable formats for high-volume haircare. Petrochemical feedstock volatility tied to Gulf crude pricing compresses converter margins on annual fixed-price contracts.
- Glass:Borosilicate and soda-lime compositions serve fragrance and prestige skincare where perceived luxury justifies weight and fragility. Emirates Authority for Standardization and Metrology migration limits restrict certain decorative coatings.
- Metal:Aluminum aerosol cans and collapsible tubes concentrate in fragrance and men's grooming segments. Aerosol propellant compatibility testing extends qualification timelines for regional fillers.
- Paper:Molded-fiber and kraft-based alternatives target plastic-reduction commitments from South African brands facing National Regulator for Compulsory Specifications EPR thresholds. Barrier performance limitations restrict penetration in high-humidity storage.
Plastic holds installed capacity across regional extrusion infrastructure. Paper is rotating up the share rankings through Johannesburg converter investments.
Closure Type:
Pump mechanisms claim the steepest expansion trajectory as serum and lotion formats displace traditional dispensing methods.
- Pumps:Precision piston and diaphragm actuators enable airless dispensing for preservative-free skincare formulations. AptarGroup and regional competitors target Saudi prestige retail with hot-climate rated EVOH barrier chambers.
- Sprayers:Fine-mist and foam actuators serve fragrance and haircare styling products. Crimp-on aluminum collar systems face substitution pressure from all-plastic snap-fit alternatives.
- Lids:Screw-top and hinged configurations sustain basic jar and bottle applications. Dual-wall designs with metallized finishes support premium cosmetic positioning.
- Caps:Flip-top and disc-top formats retain cost leadership in mass-market shampoo and conditioner. Child-resistant mechanisms expand in household chemical-adjacent personal care categories.
Pumps hold installed capacity through precision molding investments. Sprayers are rotating up the share rankings through fragrance format innovation.
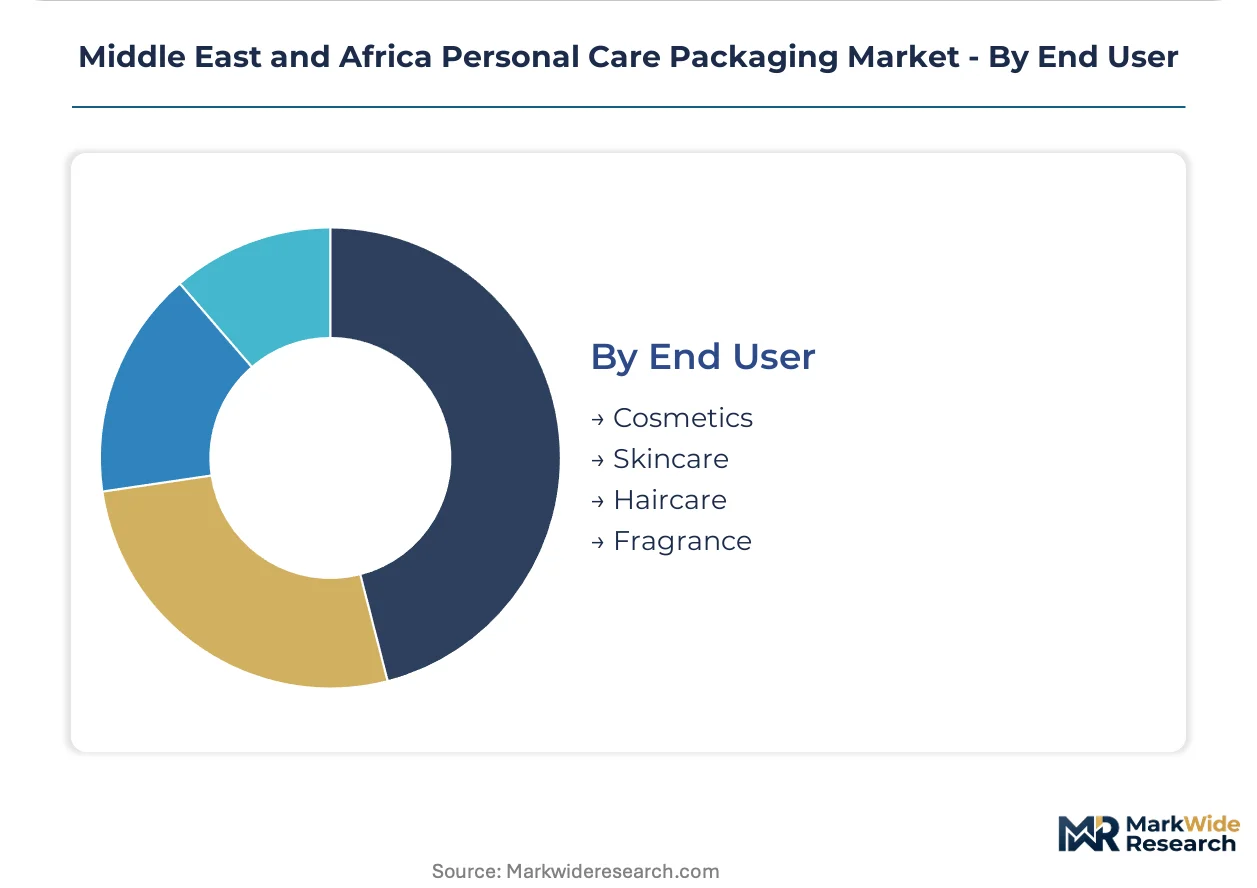
End User:
Skincare commands premium packaging economics while haircare sustains volume scale across converter portfolios.
- Skincare:Serum, essence, and moisturizer formats specify multi-layer barrier structures and precision dosing. Halal certification requirements from Saudi Food and Drug Authority reshape substrate supply chains for alcohol-free compatibility.
- Cosmetics:Color cosmetics and prestige makeup demand compact and palette configurations with magnetic closure systems. Dubai and Riyadh mall retail concentrates demand for surface-printed differentiation.
- Haircare:Shampoo and conditioner bottles sustain injection-stretch blow molding scale economies. Sachet and pouch formats penetrate Nigerian and Kenyan informal channels at sub-dollar price points.
- Fragrance:Glass bottle and metallized cap combinations concentrate margin pools in Gulf prestige retail. European substrate dependency for barrier films exposes buyers to euro-denominated cost swings.
Haircare holds installed capacity across regional blow molding networks. Skincare is rotating up the share rankings through serum format proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity concentrates in Gulf Cooperation Council states where petrochemical feedstock access and halal certification infrastructure create supply-side advantages. South Africa anchors Sub-Saharan technical capabilities through Johannesburg molding clusters. Nigeria and Kenya emerge as demand frontiers for flexible formats.
Saudi Arabia
Riyadh and Jeddah distribution networks drive demand for alcohol-free barrier coatings in prestige skincare. Saudi Food and Drug Authority halal compliance deadlines compress qualification cycles for regional converters. Eastern Province petrochemical complexes supply captive polypropylene resin to local extrusion facilities.
United Arab Emirates
Dubai mall-based retail channels concentrate demand for pump-dispensed serum formats with premium unit economics. Emirates Authority for Standardization and Metrology migration limits restrict certain decorative coatings on glass fragrance bottles. Jebel Ali free zone hosts regional headquarters for multinational packaging suppliers.
South Africa
Johannesburg converter investments in molded-fiber alternatives target plastic-reduction commitments from domestic beauty brands. National Regulator for Compulsory Specifications enforces extended producer responsibility schemes with verified post-consumer recycled content thresholds. Western Cape wine-region logistics infrastructure supports export-oriented fragrance packaging.
Nigeria
Lagos and Kano informal retail channels generate demand for sachet and flexible pouch formats at sub-dollar price points. Central Bank of Nigeria foreign exchange controls influence imported substrate costs for regional converters. Port Harcourt petrochemical feedstock availability remains constrained by refining capacity limitations.
Kenya
Nairobi urban convenience retail expands spouted pouch configurations for refill systems in basic haircare. Kenya Bureau of Standards cosmetic packaging regulations align with East African Community harmonization protocols. Mombasa port infrastructure determines lead times for European-imported barrier films.
Middle East and Africa Personal Care Packaging Market Competitive Landscape
Concentration sits with diversified multinational converters possessing regional film extrusion and precision molding capabilities. The competitive structure bifurcates between Gulf-based petrochemical-integrated suppliers and European-imported specialty substrate providers. Three archetypes dominate: integrated resin-to-package converters, precision dispensing specialists, and sustainable fiber-based innovators. Capacity expansion and halal-certified substrate qualification represent the dominant competitive moves across the analysis window.
Within the diversified multinational tier, Amcor PLC and AptarGroup Inc exemplify scale-driven positioning through regional manufacturing footprints and precision actuator technologies respectively. Mondi Group occupies a position representing sustainable fiber-based alternatives with kraft and molded-fiber solutions. Berry Global Inc anchors the plastic format scale archetype through blow molding and injection-stretch capabilities. Albea Group sits within the prestige cosmetic packaging specialist tier with historical strength in fragrance and color cosmetic formats.
| Leading Market Players |
|---|
| Amcor PLC |
| Silgan Holdings Inc |
| AptarGroup Inc |
| Berry Global Inc |
| Albea Group |
| Mondi Group |
| Huhtamaki Group |
| ALPLA Group |
| DS Smith PLC |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Gulf petrochemical complexes and regional converters lock in polypropylene resin access while capping price volatility exposure for blow-molded bottle producers serving Saudi and UAE skincare brands. These contractual structures bundle feedstock security with volume commitments that compress spot-market participation and anchor converter margins through annual fixed-price cycles.
Pricing Analysis
SFDA halal certification mandates dictate the pricing tier structure across Middle East and Africa personal care packaging. Three-tier pricing stratifies across premium serum formats with airless pump systems, standard haircare bottles with basic barrier coatings, and economy sachet configurations for Nigerian mass markets. Certification-grade differentiation separates alcohol-free laminate specifications from conventional substrates, with premium tiers absorbing validation cost pass-through. Cost compression in standard-grade plastic bottles is intensifying because petrochemical feedstock volatility tied to Gulf crude pricing erodes converter margins on legacy annual contracts. Mass-market haircare brands in Sub-Saharan informal retail channels exhibit highest price sensitivity, while prestige skincare houses in Dubai mall retail demonstrate lowest sensitivity due to brand premium absorption capacity.
Supply Chain Analysis
Strait of Hormuz transit underwrites resin feedstock flows to Saudi Eastern Province extrusion facilities serving regional converter networks. Supply concentration centers on Saudi Arabia, UAE, and Germany for barrier film substrates, with German and Italian metallized structures dominating fragrance packaging inputs. Raw material dependencies rest on polypropylene resin, EVOH barrier polymers, and aluminum coil stock for laminate tubes. Single-source vulnerability concentrates in European-imported specialty substrates for high-performance fragrance packaging, exposing buyers to euro-denominated cost swings. Distribution runs through Jebel Ali free zone warehousing for Gulf markets and Mombasa port clearance for East African channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated prestige skincare houses in Saudi Arabia and the UAE as these brands concentrate procurement volumes and demand halal-certified substrate libraries from qualified converter panels.
For Market Incumbents: Compound defensive positioning through backward integration into captive polypropylene resin production at Eastern Province petrochemical complexes and accelerated halal certification qualification cycles at existing extrusion facilities. Emerging local extruders with pre-certified substrate libraries threaten contract renewal terms with multinational converters. Certification investment represents the critical lever for margin defense. For New Entrants and Emerging Players: Digital printing-enabled short-run packaging services for direct-to-consumer subscription skincare brands in Johannesburg and Lagos represent an underserviced layer where incumbents under-serve variable surface printing demands. White-space targets concentrate in personalized regimen labeling for South African beauty brands and sachet-to-pouch upgrades for Kenyan urban convenience retail. A go-to-market angle anchored in digital printing agility with 48-hour turnaround commitments bypasses legacy rotogravure volume minimums. For Investors and Strategic Acquirers: Capital is best deployed toward precision dispensing specialists with hot-climate-rated EVOH barrier chamber capabilities and established SFDA qualification track records. Long-term viability across the analysis window favors suppliers with dual compliance gateways through both halal certification alignment and extended producer responsibility scheme readiness in South Africa. The signal to watch is converter consolidation around Johannesburg molded-fiber investments as EPR thresholds harden.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Qualification | SFDA compliance deadlines compress supplier selection timelines for prestige skincare brands. |
| Backward Integration into Resin | Eastern Province petrochemical access secures feedstock cost advantages for Gulf converters. |
| Digital Printing Capability Addition | Johannesburg and Lagos installations capture fragmented subscription skincare procurement patterns. |
| Molded-Fiber Line Conversion | South African EPR thresholds create preferential procurement status for sustainable alternatives. |
| Airless Pump Chamber Investment | Hot-climate EVOH barriers displace crimp tubes in Saudi and UAE prestige retail channels. |
Research Methodology
A spread of perspectives from packaging procurement managers at prestige skincare houses, extrusion plant engineers at Gulf converter facilities, regulatory affairs specialists navigating SFDA compliance, and distribution channel partners across Nigerian informal retail converged on the working assumptions. Primary interview insights combined with secondary validation from customs records, ECHA REACH substance restriction databases, and National Regulator for Compulsory Specifications EPR documentation. Bottom-up unit economics triangulated against top-down market sizing across packaging type, material, closure, and end-use dimensions.
Segmentation dimensions modeled include packaging format, substrate material, dispensing mechanism, product category, and regional regulatory cluster across the analysis window. CAGRs derived from trend extrapolation anchored in petrochemical feedstock cost trajectories, halal certification penetration curves, and urban retail infrastructure development patterns. Industry-specific forecast inputs incorporated serum format proliferation rates and sachet-to-pouch substitution elasticities in Sub-Saharan mass markets.
Forecasts assume regulatory continuity in SFDA halal certification timelines and South African EPR enforcement regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as Gulf petrochemical feedstock pricing and European substrate availability conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Crimp Neck Serum Bottles Market
Cosmetic Packaging
Beauty and Personal Care Packaging Market
Cosmetic Packaging
Lip Care Packaging Market
Cosmetic Packaging
Latin America Personal Care Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Asia Pacific Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Cosmetic Pump Bottle Market
Cosmetic Packaging
Injection Moulding Cosmetic Packaging Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Skin Care Packaging Market
Cosmetic Packaging
Metal Cosmetic Packaging Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Global Perfume Packaging Market
Cosmetic Packaging
Hair Care Packaging Market