
 Global Cosmetic Packaging Market | 2026-2036
Global Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cosmetic Packaging Market Foresight
ISO 22716 Good Manufacturing Practices certification is rotating as a baseline qualifier for cosmetic packaging suppliers serving multinational beauty brands. Amcor plc leverages its integrated film-to-bottle manufacturing network to sustain cost advantages across skin care and fragrance formats. HCP Packaging anchors its competitive position through specialized design capabilities for premium lipstick and compact mechanisms. Berry Global differentiates via scale production of recyclable polyethylene terephthalate containers serving mass market retail channels.
Cosmetic packaging encompasses primary and secondary containment systems engineered to protect formulation integrity, enable precise dosing, and transmit brand identity through visual and tactile design. Airless pump mechanisms maintain product sterility by preventing oxygen ingress, while aluminum tubes and glass jars provide barrier properties against ultraviolet degradation and volatile compound loss. Plastic bottles and tubes occupy the largest volume share across hair care and personal hygiene applications, where cost efficiency outweighs premium material requirements. Bioplastics and cardboard segments are expanding fastest among indie labels and e-commerce sellers responding to consumer pressure for circular packaging solutions. Glass jars and metal containers command margin concentration in luxury brand portfolios, where weight and acoustic closure quality signal product prestige.
The EU Green Deal and REACH frameworks restrict certain plastic additives and mandate recyclability disclosures, compelling European suppliers to reformulate resins and redesign multi-material assemblies. The US FDA maintains active ingredient stability requirements that influence barrier specification for skin care packaging, while China's SAMR enforces labeling standards affecting secondary packaging dimensions and information placement. Stakeholders must monitor regulatory divergence between jurisdictions to avoid redundant tooling investments and qualification cycles.
Market Dynamics
EU REACH chemical restrictions and the EU Green Deal are forcing rapid material transitions across cosmetic packaging supply chains, compressing qualification timelines and raising compliance costs for multi-material assemblies.
Growth Catalysts
- Airless pump technology:Oxygen-exclusion mechanisms preserve formulation integrity in vitamin C and retinol serums, driving specification upgrades across prestige skin care portfolios.
- South Korea's sustainable packaging mandates:Domestic beauty brands in Seoul and Busan are accelerating bioplastic adoption ahead of voluntary industry commitments.
- China's SAMR labeling enforcement:Secondary packaging redesign requirements are stimulating demand for compliant carton and insert suppliers serving tier-one city distributors.
Market Restraints
- Resin price volatility:Bio-based polyethylene and polylactic acid feedstock costs fluctuate with agricultural commodity markets, squeezing converter margins.
- Multi-layer barrier film complexity:Current mechanical recycling infrastructure cannot process metallized or adhesive-laminated structures, limiting circularity claims.
- Glass weight penalty:Luxury jar specifications increase freight costs and carbon intensity, conflicting with scope-three emission reduction targets.
Strategic Opportunities
- Indian domestic beauty expansion:Mumbai and Delhi-based brands are upgrading primary packaging specifications to compete with international labels entering through duty-free channels.
- Refill system convergence:Durable outer cases paired with recyclable inner pods combine premium aesthetics with reduced material throughput.
- E-commerce unboxing optimization:Secondary packaging dimensions are shrinking to reduce dimensional weight charges and last-mile emissions.
Industry Challenges
- ISO 22716 qualification timelines:Multinational brand audits of contract manufacturers extend supplier onboarding to 18-24 months.
- Legacy injection molding retooling:Thin-wall and recycled-content specifications require capital-intensive cavity redesigns and process validation.
- Cross-jurisdiction labeling divergence:Simultaneous compliance with EU INCI requirements, US FDA monograph formats, and China SAMR character mandates fragments print production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cosmetic Packaging Market |
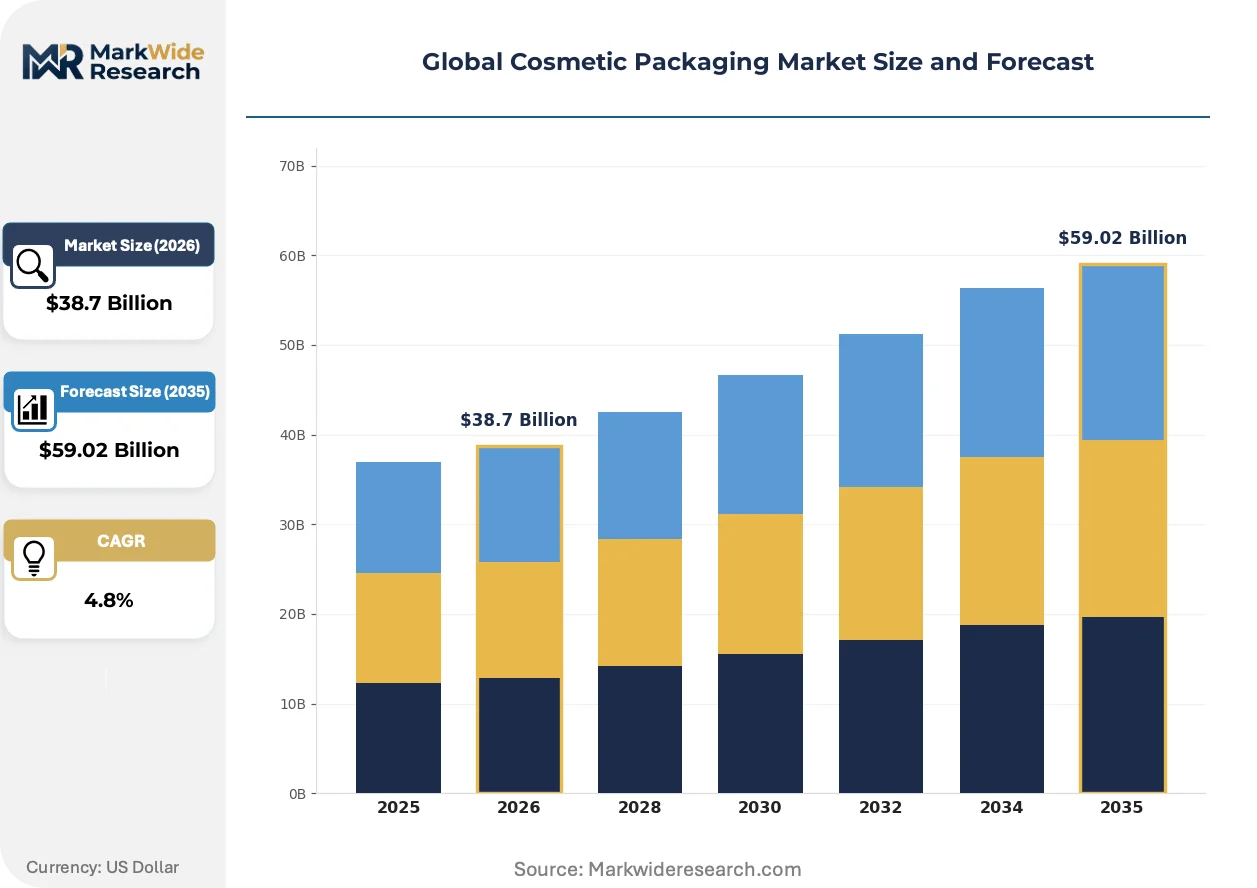
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Glass Jars, Plastic Bottles, Airless Pumps, Tubes, Compacts, Metal Containers Material: Polypropylene, PET, Aluminum, Bioplastics, Acrylic, Cardboard Application: Skin Care, Hair Care, Makeup, Fragrance, Personal Hygiene, Nail Care Customer Type: Luxury Brands, Indie Labels, Mass Market Retailers, E-commerce Sellers, Private Labels, Specialty Stores |
| Companies Covered | Amcor plc, HCP Packaging, Berry Global, Albea SA, AptarGroup, Gerresheimer AG, DS Smith, Silgan Holdings, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cosmetic Packaging Market Shifts & Advancements
Material science breakthroughs and regulatory tightening are converging to transform how cosmetic packaging protects formulations, communicates brand identity, and satisfies circular economy mandates.
Monomaterial polyethylene tubes and bottles are displacing multi-layer constructions across mass-market hair care and personal hygiene categories. Unilever and L'Oréal procurement teams are specifying single-resin designs to access mechanical recycling streams. This transition is compressing demand for metallized films and adhesive laminates that contaminate post-consumer waste recovery.
The EU Green Deal's packaging and packaging waste regulation mandates recyclability-by-design disclosures and restricts certain plastic additives. European converters are reformulating masterbatches and eliminating carbon black pigments to improve near-infrared detection at sorting facilities. Skin care brands with significant EU revenue exposure are accelerating qualification of detectable dark resins ahead of enforcement deadlines.
Direct-to-consumer subscription models are shortening packaging development cycles and fragmenting minimum order quantities. Indie beauty brands bypass traditional retail distribution to test limited-edition designs through Shopify-integrated fulfillment. This channel shift concentrates design experimentation in Brooklyn, London, and Berlin startup ecosystems where digital-native brands prioritize unboxing shareability over shelf presence.
Global Cosmetic Packaging Market Segmentation
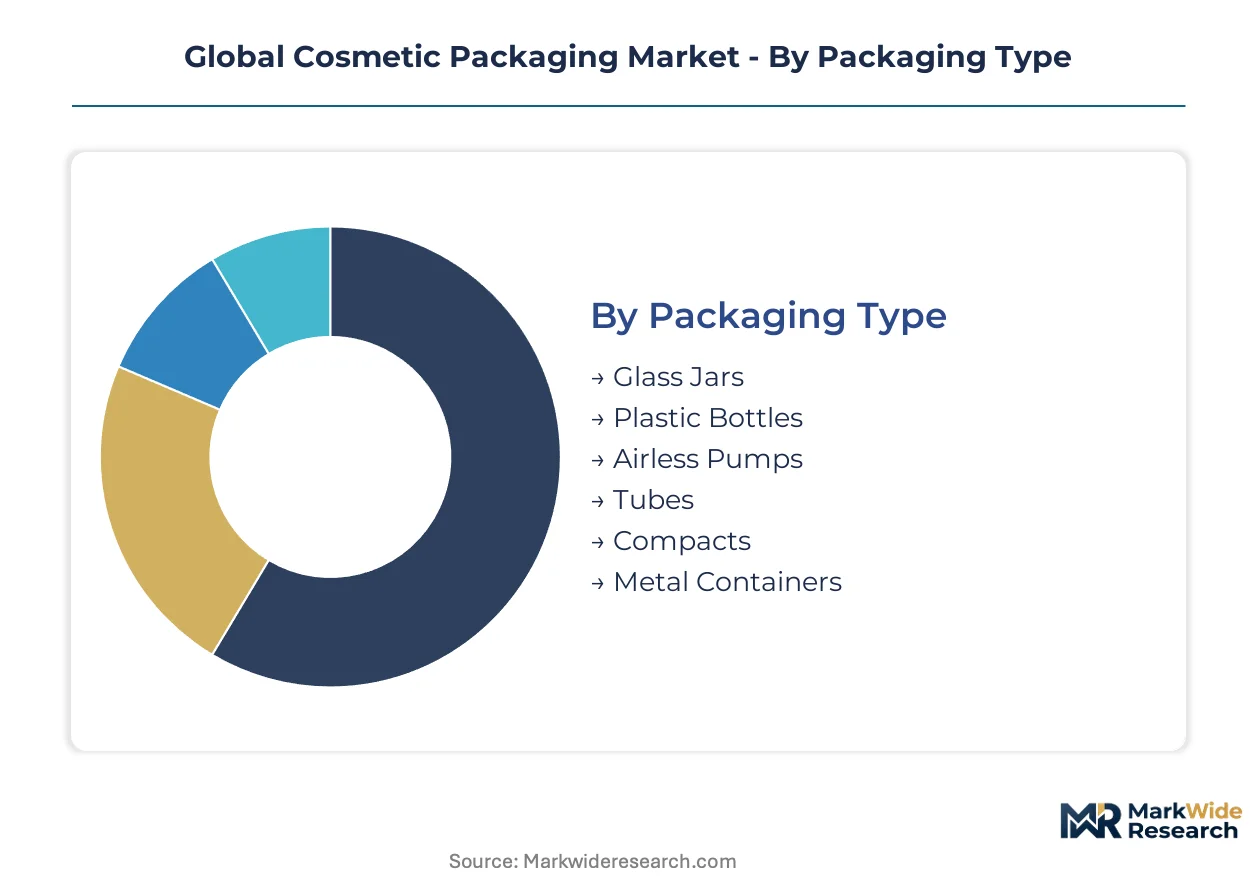
Packaging specifications diverge sharply across price tiers and distribution channels. Material choices and format dimensions determine recyclability compliance, freight economics, and shelf impact in distinct regional retail environments.
Packaging Type:
Export-led demand concentrates in airless pump and glass jar formats serving premium skin care brands in South Korea and France. Domestic volume anchors in plastic bottles and tubes for mass-market hair care and personal hygiene in China and India.
- Glass Jars:Heavy-wall borosilicate and soda-lime constructions provide ultraviolet barrier properties for retinol and vitamin C formulations. Luxury brands in Paris and Seoul specify weighted bases and acoustic closure systems to signal prestige at cosmetic counters.
- Airless Pumps:Oxygen-exclusion piston mechanisms preserve oxidative-sensitive actives in prestige serums. South Korean manufacturers in Gyeonggi Province are expanding capacity to supply domestic beauty brands accelerating sustainable packaging commitments ahead of voluntary industry targets.
- Plastic Bottles:High-density polyethylene and PET constructions dominate hair care and body wash applications where cost efficiency outweighs premium material requirements. Mass market retailers in China's tier-one cities specify these formats for high-velocity replenishment cycles.
- Tubes:Laminated and extruded designs enable precise dosing for creams and lotions. European converters are reformulating to monomaterial polyethylene to satisfy EU Green Deal recyclability mandates.
- Compacts:Hinged-lid mechanisms with magnetic closure systems house pressed powders and cream-to-powder formulations. Specialty stores in Tokyo and Milan drive specification upgrades for tactile quality.
- Metal Containers:Aluminum tins and steel compacts provide barrier properties for solid perfumes and balms. Indie labels in Brooklyn and Berlin favor these for circular packaging claims.
Plastic bottles hold the largest share; momentum sits with airless pumps.
Material:
Cost tier stratification separates commodity resins from specialty bioplastics and metals. Volume production concentrates in polypropylene and PET serving mass-market retail channels, while bioplastics and aluminum command premium positioning.
- Polypropylene:Versatile thermoplastic enables thin-wall injection molding for lightweight bottles and jars. Mass market retailers in India and Brazil specify this resin for cost-optimized primary packaging across hair care portfolios.
- PET:Clear amorphous polyester delivers glass-like clarity with shatter resistance. Berry Global and similar converters scale production of recyclable PET containers serving European supermarket chains under extended producer responsibility schemes.
- Aluminum:Infinite recyclability and barrier properties position this metal for luxury fragrance caps and tubes. French and Italian perfume houses specify anodized finishes to differentiate at duty-free retail.
- Bioplastics:Polylactic acid and bio-based polyethylene derived from sugarcane or corn starch expand fastest among e-commerce sellers responding to consumer pressure for circular solutions. Agricultural commodity price volatility constrains converter margins.
- Acrylic:High-clarity thermoplastic mimics glass aesthetics at reduced weight. Premium makeup brands in Los Angeles and London specify acrylic compacts for unboxing shareability in direct-to-consumer channels.
- Cardboard:Molded pulp and folding carton formats displace plastic secondary packaging. China's SAMR labeling enforcement is stimulating demand for compliant carton suppliers serving tier-one city distributors.
PET dominates volume; bioplastics are climbing the fastest.
Application:
Customer type determines barrier specification and format complexity. Luxury brands demand airless systems and weighted glass, while mass-market retail prioritizes cost-efficient plastic bottles and tubes.
- Skin Care:Oxygen-sensitive actives drive airless pump and ultraviolet-blocking glass specifications. South Korean brands in Seoul are accelerating bioplastic adoption ahead of domestic sustainable packaging mandates.
- Hair Care:High-volume shampoo and conditioner applications favor lightweight plastic bottles and tubes. Unilever and L'Oréal procurement teams specify monomaterial designs to access mechanical recycling streams.
- Makeup:Compacts, lipstick mechanisms, and mascara wands require precision-engineered dispensing systems. HCP Packaging anchors competitive position through specialized design capabilities for premium lipstick and compact mechanisms.
- Fragrance:Heavy glass bottles with metal caps and decorative secondary cartons signal luxury positioning. French and Italian houses maintain glass weight despite carbon intensity conflicts with scope-three emission targets.
- Personal Hygiene:Cost-optimized plastic bottles and tubes serve high-velocity deodorant and body wash markets. Mass market retailers in India's Mumbai and Delhi upgrade specifications to compete with international labels.
- Nail Care:Small-format glass bottles with precision brushes require compatible cap-thread engineering. Specialty stores in Tokyo drive specification diversity for limited-edition collections.
Skin care commands margin concentration; personal hygiene anchors volume scale.
Customer Type:
Distribution channel fragmentation is shortening development cycles and splitting minimum order quantities. E-commerce sellers and indie labels prioritize unboxing optimization over shelf presence.
- Luxury Brands:LVMH, Estée Lauder, and Chanel procurement teams enforce ISO 22716 Good Manufacturing Practices certification as baseline supplier qualification. Audits extend onboarding timelines to 18-24 months.
- Indie Labels:Digital-native brands in Brooklyn, London, and Berlin bypass traditional retail to test limited-edition designs through Shopify-integrated fulfillment. Secondary packaging dimensions shrink to reduce dimensional weight charges.
- Mass Market Retailers:Walmart, Carrefour, and Tesco specify recyclable polyethylene terephthalate containers with near-infrared detectable resins to satisfy EU sorting infrastructure requirements.
- E-commerce Sellers:Subscription models concentrate design experimentation in startup ecosystems where unboxing shareability drives social media conversion. Refill system convergence pairs durable outer cases with recyclable inner pods.
- Private Labels:Retailer-owned beauty brands in Germany and the UK specify cost-optimized formats with compliant labeling for cross-border distribution. Cross-jurisdiction divergence fragments print production runs.
- Specialty Stores:Sephora, Douglas, and Ulta Beauty demand exclusive packaging finishes and limited-edition collaborations to differentiate in-store experience. Premium specifications include acoustic closure quality and weighted bases.
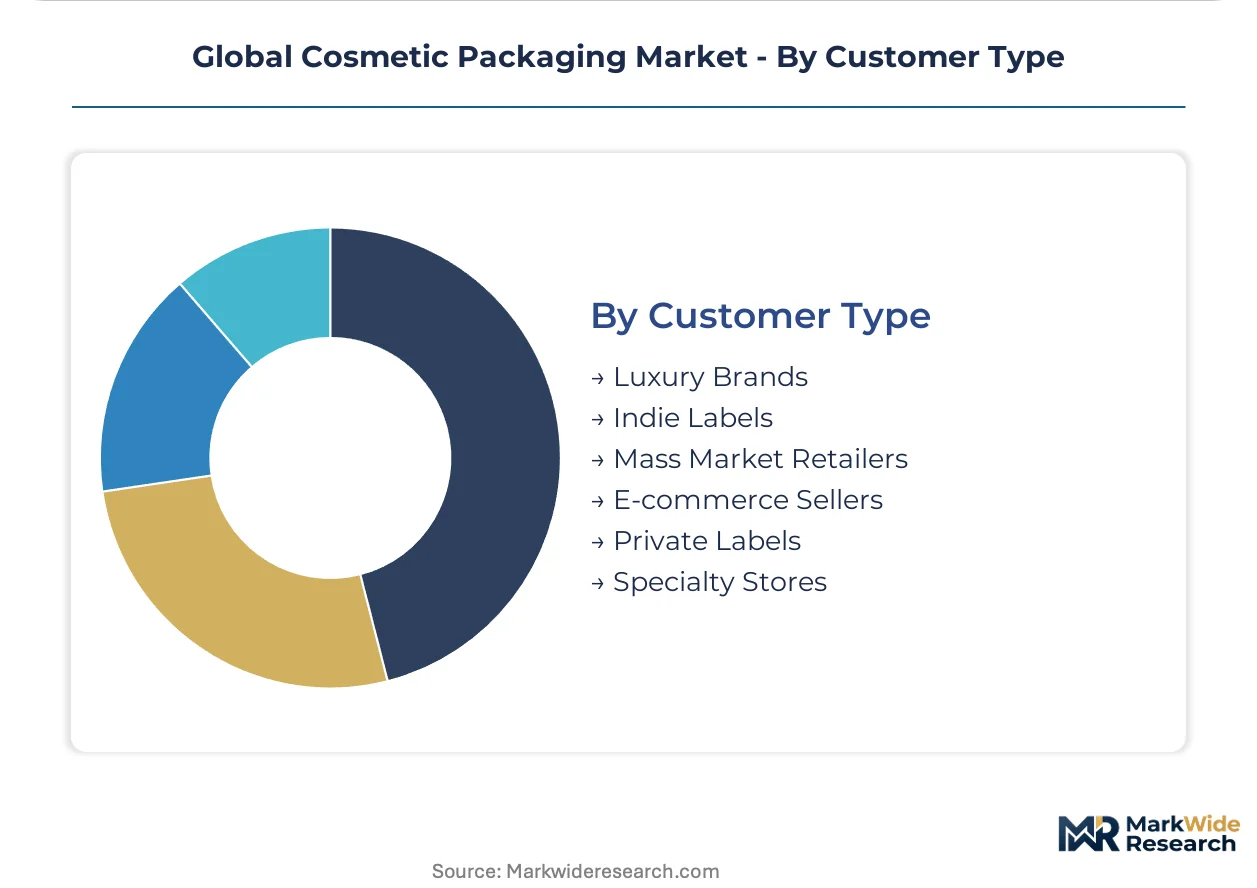
Mass market retailers hold the largest share; indie labels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH chemical restrictions and the EU Green Deal are accelerating material transitions across European supply chains, while China's SAMR labeling enforcement and South Korea's sustainable packaging mandates reshape procurement specifications in Asia-Pacific.
China
Domestic beauty brands in Shanghai and Beijing upgrade packaging specifications to compete with international labels entering through duty-free channels. China's SAMR enforces labeling standards affecting secondary packaging dimensions and information placement. Tier-one city distributors drive demand for compliant carton and insert suppliers.
South Korea
Premium skin care brands in Seoul and Busan accelerate bioplastic adoption ahead of voluntary industry commitments. The MFDS maintains stability requirements influencing barrier specifications for sensitive formulations. Manufacturers in Gyeonggi Province expand airless pump capacity to supply domestic beauty brands.
United States
Direct-to-consumer subscription models concentrate design experimentation in Brooklyn and Los Angeles startup ecosystems. The FDA maintains active ingredient stability requirements that influence barrier specifications for skin care packaging. Digital-native brands prioritize unboxing shareability over traditional shelf presence.
Germany
Mass market retailers specify recyclable PET containers with near-infrared detectable resins to satisfy EU sorting infrastructure requirements. The EU Green Deal's packaging and packaging waste regulation mandates recyclability-by-design disclosures. Converters in North Rhine-Westphalia reformulate masterbatches to eliminate carbon black pigments.
France
Luxury fragrance houses in Paris maintain glass weight specifications despite carbon intensity conflicts with scope-three emission targets. ANSM and ECHA frameworks restrict certain plastic additives across cosmetic applications. Perfume brands specify anodized aluminum finishes to differentiate at duty-free retail.
Global Cosmetic Packaging Market Competitive Landscape
Listed leaders compete with private specialists across integrated manufacturing networks and design capabilities. The supplier base organizes around three distinct tiers: scale-driven converters with film-to-bottle integration, specialized designers of premium dispensing mechanisms, and regional fabricators serving mass-market retail channels. Consolidation pressure concentrates among mid-cap converters facing ISO 22716 qualification timelines and capital-intensive retooling requirements. Dominant competitive moves include backward integration into resin formulation and geographic expansion through contract manufacturer partnerships.
Within the integrated manufacturing tier, Amcor plc exemplifies scale advantages across skin care and fragrance formats. HCP Packaging and Berry Global occupy complementary positions—HCP anchors specialized design capabilities for premium mechanisms, while Berry represents volume production of recyclable containers serving mass-market channels. These three entities collectively illustrate how competitive positioning diverges between premium specification and cost-optimized procurement.
| Leading Market Players |
|---|
| Amcor plc |
| HCP Packaging |
| Berry Global |
| Albea SA |
| AptarGroup |
| Gerresheimer AG |
| DS Smith |
| Silgan Holdings |
| Mondi Group |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four-month ISO 22716 qualification timelines concentrate pricing power with incumbent converters possessing certified manufacturing networks, while resin price volatility compresses margins for bioplastic-dependent suppliers serving sustainability-mandated beauty brands.
Pricing Analysis
Certification level creates the primary spread between premium converters and commodity suppliers. Three-tier pricing structure across ISO 22716-certified, CE-marked, and uncertified production tiers reflects audit investment recovery and brand risk premiums. Cost compression in bioplastic segments is intensifying because agricultural feedstock prices fluctuate with corn and sugarcane commodity markets. Mass-market retailers exhibit highest price sensitivity, while luxury houses prioritize acoustic closure quality and weighted glass specifications over unit cost.
Supply Chain Analysis
Inventory cycles stretching to 90-120 days for imported aluminum and specialty masterbatches expose converters to working capital strain. Manufacturing gravity centers on China, Germany, and South Korea, with Gyeonggi Province airless pump capacity expanding to serve Seoul-based beauty brands. Resin formulation draws from petrochemical complexes in the US Gulf Coast and Middle East, while anodized aluminum caps source from Italian and French metal finishers. Single-source vulnerability concentrates in carbon black pigment elimination for EU near-infrared sorting compliance. Distribution runs through contract manufacturer partnerships rather than direct brand relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refill system convergence represents an early-cycle expansion story as durable outer cases paired with recyclable inner pods penetrate prestige skin care portfolios ahead of regulatory mandates.
For Market Incumbents: Secure backward integration into detectable dark resin formulation to preempt EU Green Deal enforcement deadlines. Anchor capacity expansion in Gyeonggi Province to capture South Korean sustainable packaging acceleration ahead of voluntary industry commitments. Defend against indie label disintermediation by offering Shopify-integrated fulfillment partnerships with 1,000-unit minimum order quantities. For New Entrants and Emerging Players: Lead with e-commerce unboxing optimization for Brooklyn and Berlin digital-native brands where dimensional weight reduction drives procurement decisions. Target India's Mumbai and Delhi domestic beauty expansion where international label competition stimulates packaging specification upgrades. Pursue monomaterial polyethylene tube qualification for Unilever and L'Oréal procurement teams prioritizing mechanical recycling stream access. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because EU REACH restrictions and extended producer responsibility schemes consolidate demand toward recyclability-certified converters. Acquisition candidates include mid-cap converters with validated thin-wall injection molding capabilities and existing ISO 22716 certification. The signal to watch is carbon black pigment elimination timelines across European converter masterbatch reformulation programs.| Strategic Initiative | Industry Significance |
|---|---|
| Bioplastic Capacity Expansion | South Korean MFDS stability requirements accelerate polylactic acid adoption in Seoul skin care formulations. |
| Monomaterial Design Transition | Unilever and L'Oréal procurement teams specify single-resin tubes to access EU mechanical recycling infrastructure. |
| Airless Pump Manufacturing Scale-Up | Gyeonggi Province converters expand piston mechanism capacity for vitamin C and retinol serum protection. |
| Detectable Dark Resin Qualification | EU Green Deal near-infrared sorting mandates force carbon black pigment elimination in premium packaging. |
| Refill System Platform Launch | Durable outer cases paired with recyclable inner pods reduce scope-three emissions for Paris fragrance houses. |
Research Methodology
A spread of perspectives from packaging procurement managers at multinational beauty brands, contract manufacturing executives, resin formulation specialists, and EU regulatory affairs consultants converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, SEC 10-K disclosures from listed converters, and SAMR labeling enforcement bulletins. Bottom-up demand modeling triangulated against top-down supply capacity assessments across China, Germany, and South Korea.
Segmentation dimensions modeled include packaging type, material composition, application category, and customer tier across the projection horizon. CAGRs derived from elasticity-adjusted volume trajectories incorporating bioplastic feedstock price volatility and airless pump technology penetration curves. Industry-specific forecast inputs encompass EU Green Deal implementation timelines and China SAMR secondary packaging redesign compliance rates.
Forecasts assume regulatory continuity in EU REACH, China SAMR, and US FDA frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Single Portion Cosmetic Packaging Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
Anti-Counterfeit Cosmetic Packaging Market
Cosmetic Packaging
Europe Cosmetic Packaging Market
Cosmetic Packaging
Lip Care Packaging Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Plastic Cosmetic Packaging Market
Cosmetic Packaging
Eyeliner and Kajal Sculpting Pencil Packaging Market
Cosmetic Packaging
Middle East and Africa Cosmetic Packaging Market
Cosmetic Packaging
Europe Plastic Cosmetic Packaging Market
Cosmetic Packaging
Glass Cosmetic Bottle Market
Cosmetic Packaging
Fragrance Packaging Market
Cosmetic Packaging
US Personal Care Packaging Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
India Personal Care Packaging Market