
 Middle East and Africa Cosmetic Packaging Market | 2026-2036
Middle East and Africa Cosmetic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cosmetic Packaging Market Foresight
ISO 22716 Good Manufacturing Practices certification is rotating as the gatekeeping standard for cosmetic packaging suppliers seeking access to Gulf retail channels. Amcor plc leverages its multi-material conversion capabilities to sustain contract positions with multinational beauty houses operating in Jeddah and Casablanca. Berry Global Inc anchors regional supply through blow-molded bottle production scaled for haircare and body care volumes across North Africa.
Middle East and Africa cosmetic packaging encompasses primary and secondary containment systems engineered from polymers, silica-based glass, aluminum alloys, and cellulose substrates, with functional specifications including UV-barrier properties, airless dispensing mechanisms, and compatibility testing for alcohol-based fragrance formulations. Its commercial purpose centers on preserving product integrity, enabling precise consumer dosing, and transmitting brand positioning through tactile and visual design languages. Plastic material formulations dominate unit economics across mass-market skincare and haircare segments, while glass bottle assemblies command premium positioning within fragrance and luxury makeup categories where weight and optical clarity signal quality. Pump closure mechanisms represent the fastest-growing closure configuration, displacing screw caps in serum and lotion applications where contamination control and portion precision matter.
SFDA cosmetic regulations in Saudi Arabia mandate Arabic bilingual labeling and ingredient disclosure that reshape packaging graphics and print substrate specifications. EMA-aligned standards through Morocco's national pharmaceutical regulator create dual compliance obligations for beauty brands exporting from Casablanca manufacturing zones into European duty-free retail. REACH-compliant material declarations, though European in origin, penetrate regional supply chains through OEM specifications set by L'Oréal and Estée Lauder procurement teams operating Dubai headquarters. Stakeholders must monitor how extended producer responsibility frameworks migrate from European templates into Gulf national policies, as this transition would restructure recycling infrastructure investments and material selection criteria across the decade ahead.
Market Dynamics
ISO 22716 certification requirements from Gulf retailers are forcing packaging suppliers to restructure quality management systems, consolidating procurement toward GMP-verified converters and marginalizing uncertified regional players.
Growth Catalysts
- SFDA Bilingual Labeling Mandate:Saudi Arabia's tightening cosmetic disclosure rules compel brands to redesign packaging graphics, generating recurring demand for Arabic-compliant print substrates and specialized converting capacity.
- Airless Pump Technology:Serum and lotion formulations across premium skincare segments are migrating from screw-cap containment to piston-based airless systems that extend shelf stability and enable precise dosing.
- Dubai Free Trade Zone Clustering:Multinational beauty houses concentrate regional headquarters in Jebel Ali and Dubai South, creating captive demand for localized packaging development and rapid prototyping services.
Market Restraints
- Polymer Feedstock Volatility:Blow-molded bottle production for mass-market haircare depends on polyethylene and polypropylene resin imports, exposing converters to freight cost swings and currency mismatches against Gulf pegged rates.
- Glass Supply Concentration:Premium fragrance bottle assembly relies on European and Egyptian silica-based glass sources, creating lead-time vulnerability for Moroccan and UAE-based finishers.
- REACH Declaration Burden:European material compliance documentation demanded by L'Oréal and Estée Lauder procurement teams extends supplier onboarding timelines and raises testing expenditure for cellulose substrate providers.
Strategic Opportunities
- Extended Producer Responsibility Migration:Gulf national policies are adapting European recycling infrastructure templates, positioning early investors in post-consumer polymer recovery to capture preferential supplier status.
- UV-Barrier Film Convergence:Combination of metallized barrier layers with flexible pouch formats creates new containment options for vitamin-C and retinol formulations sensitive to oxidation.
- Casablanca EMA Export Corridor:Morocco's national pharmaceutical regulator alignment with European standards enables duty-free manufacturing zone producers to serve EU airport retail channels with simplified customs clearance.
Industry Challenges
- ISO 22716 Audit Backlogs:Certification body capacity constraints in the Gulf region extend GMP verification timelines, delaying supplier qualification for Ramadan and holiday season production windows.
- Alcohol-Based Fragrance Compatibility Testing:Pump seal and actuator material selection for high-proof perfume formulations requires extended stability protocols that compress new product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cosmetic Packaging Market |
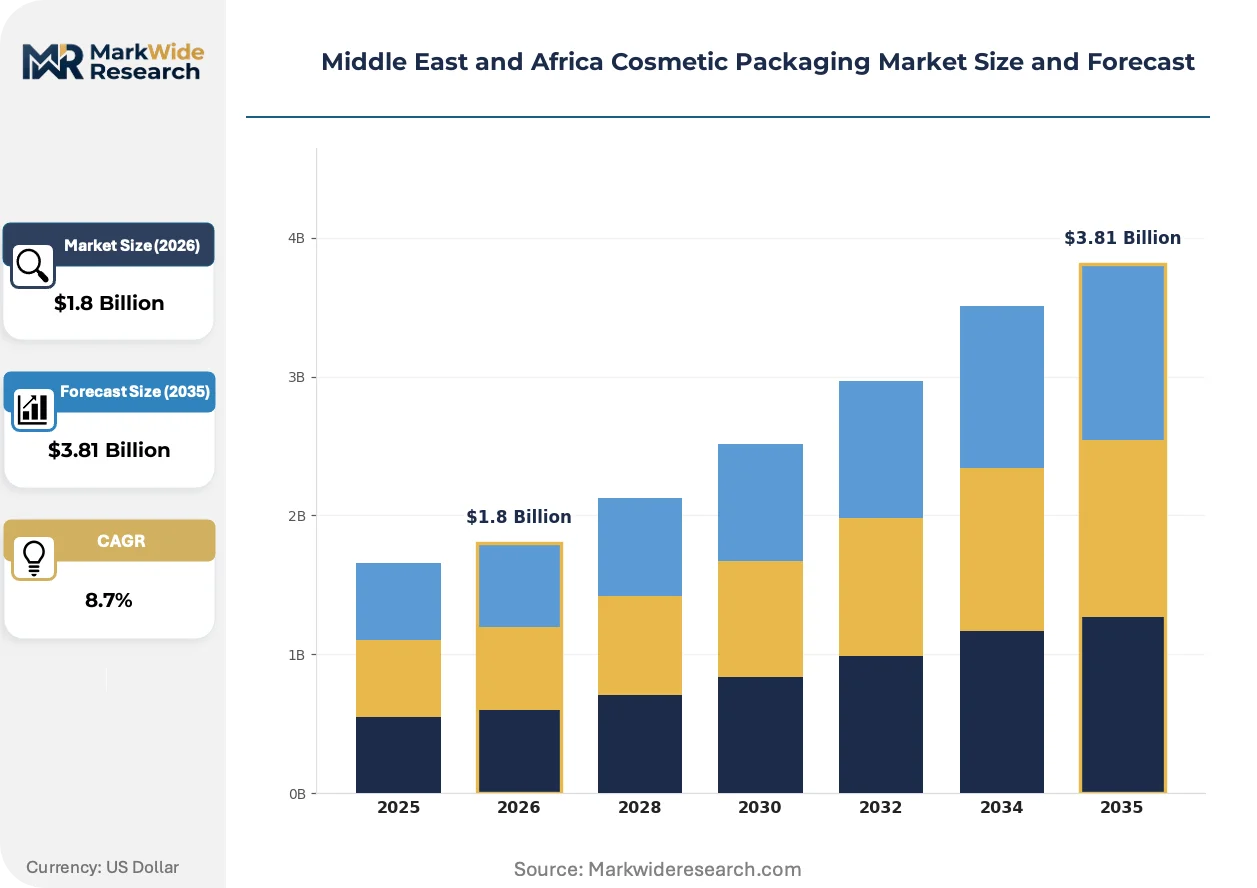
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubes, Jars, Bottles, Containers Material: Plastic, Glass, Metal, Paper Closure Type: Screw Caps, Flip Tops, Pumps, Roll-ons End User: Skincare, Haircare, Makeup, Fragrances |
| Companies Covered | Nioro Plastics (Pty) Ltd, AptarGroup Inc, Amcor plc, Mpact Plastics, Berry Global Inc, ALPLA Werke Alwin Lehner GmbH & Co KG, Al LendOn Packaging (Pty) Ltd, Silgan Holdings Inc, Napco National Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cosmetic Packaging Market Shifts & Advancements
Packaging functionality is converging with brand storytelling through tactile surface engineering and mono-material constructions that anticipate regulatory pressure while reducing sorting complexity for emerging recycling streams.
Airless dispensing systems with piston-driven evacuation mechanisms are displacing traditional dip-tube pumps in premium skincare applications. Multinational beauty houses operating Jeddah and Casablanca distribution centers specify these formats for hyaluronic acid and peptide serums where oxidation protection commands priority. The shift compresses demand for conventional screw-cap assemblies while elevating converter technical requirements for dimensional tolerance and seal integrity.
SFDA cosmetic regulations mandate Arabic bilingual ingredient disclosure that reshapes label design and print substrate specifications across Saudi Arabian retail channels. Brands must allocate additional graphic panel real estate to compliance text, reducing available space for brand messaging and forcing substrate upgrades to accommodate finer print resolution. Premium fragrance and luxury makeup categories absorb these costs most readily, while mass-market skincare segments face margin compression.
Beauty brands are consolidating procurement toward converters offering integrated design-to-delivery services with in-house tooling and rapid prototyping. Regional packaging suppliers in Dubai's free trade zones capture this demand by embedding structural design teams alongside production floor operations. The model displaces traditional arm's-length relationships with European design agencies, compressing concept-to-shelf timelines for seasonal limited-edition launches targeting Gulf consumer preferences.
Middle East and Africa Cosmetic Packaging Market Segmentation
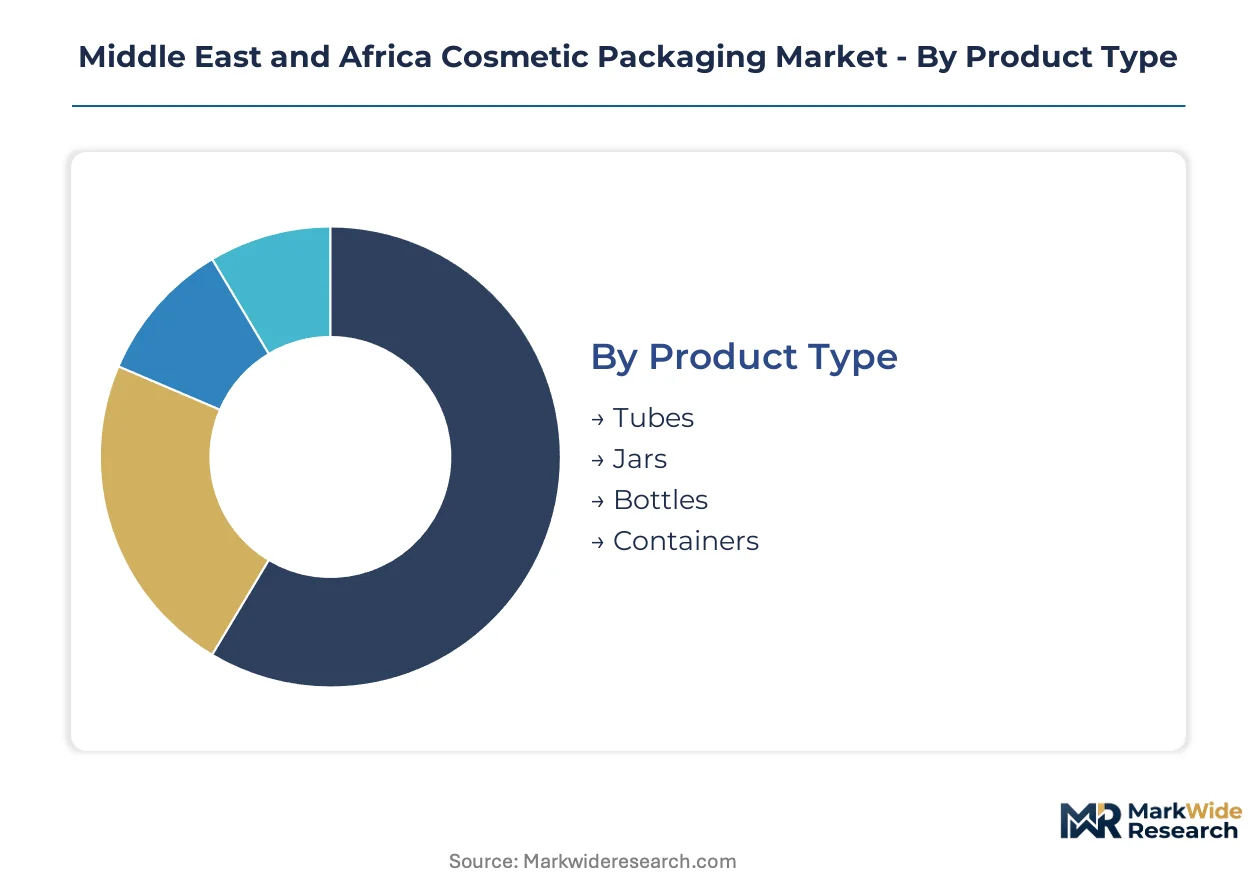
Segmentation in Middle East and Africa cosmetic packaging reveals how Gulf retail channel requirements reshape converter priorities. Product format, material selection, and closure mechanisms each carry distinct compliance obligations and margin profiles across Dubai duty-free corridors and Saudi Arabian hypermarkets.
Product Type:
Tubes, jars, bottles, and containers flow through divergent channel mixes — mass-market haircare favors high-volume bottle formats while premium skincare commands specialized jar assemblies with airless functionality.
- Tubes:Laminated aluminum-plastic multilayer constructions dominate sunscreen and haircare mask applications across North African retail. Moroccan converters scale squeeze-tube output for mass-market volumes where cost-per-unit governs procurement decisions.
- Jars:Wide-mouth glass and thick-walled PET assemblies serve premium skincare segments across UAE mall retail. Airless jar variants with piston-driven evacuation are displacing conventional dip-tube formats in Dubai's luxury beauty corridors.
- Bottles:Blow-molded HDPE and PET configurations anchor haircare and body wash distribution through Saudi Arabian hypermarket channels.
- Containers:Rigid walled boxes and compacts house pressed powder and cream-to-powder makeup formulations for professional salon supply.
Bottles dominate installed base across mass-market channels. Jars are where expansion concentrates as premium skincare brands upgrade containment specifications.
Material:
Material selection stratifies across cost tiers — polymer formulations capture volume economics while glass and metal command premium positioning through tactile quality signals.
- Plastic:Polyethylene and polypropylene resins enable blow-molded bottle production at scale for haircare and body care segments. SFDA labeling compliance drives substrate upgrades to accommodate finer Arabic print resolution without compromising barrier properties.
- Glass:Silica-based molded bottles and jars transmit luxury positioning through weight and optical clarity in fragrance and premium makeup categories. Egyptian and European glass supply sources create lead-time vulnerability for Casablanca-based finishers serving EU export channels.
- Metal:Aluminum alloy aerosol cans and compacts serve deodorant and pressed powder applications where portability matters.
- Paper:Cellulose-based cartons and folding boxes provide secondary containment and brand storytelling surfaces for gift sets and limited editions.
Plastic captures volume leadership across mass-market segments. Glass is climbing the fastest as fragrance houses expand premium bottle specifications.
Closure Type:
Closure configuration determines contamination control and dosing precision — critical differentiators for alcohol-based fragrance formulations and oxidation-sensitive skincare actives.
- Screw Caps:Threaded polypropylene closures remain standard for shampoo and conditioner bottles across North African retail. Cost minimization priorities preserve screw-cap dominance in mass-market haircare despite functional limitations.
- Flip Tops:Hinged polyolefin closures enable single-handed dispensing for shower gel and body wash applications in Saudi Arabian family households.
- Pumps:Piston-driven and dip-tube pump mechanisms are displacing screw caps in serum and lotion categories. SFDA stability requirements for hyaluronic acid formulations accelerate airless pump specification across Dubai premium retail.
- Roll-ons:Ball-and-housing assemblies serve deodorant and fragrance oil applications where controlled application area matters.
Screw caps retain installed base dominance in haircare. Pumps are gaining share fastest as skincare brands prioritize contamination control and portion precision.
End User:
End-use segmentation maps directly to regulatory exposure — fragrance and skincare carry the heaviest SFDA labeling burdens while haircare operates under lighter compliance obligations.
- Skincare:Serum, moisturizer, and sunscreen categories drive airless packaging specification and UV-barrier film demand. Dubai free trade zone clustering concentrates regional headquarters for multinational brands targeting Gulf consumer preferences with rapid prototyping requirements.
- Haircare:Shampoo and conditioner volumes anchor blow-molded bottle production across North African converter networks. Polymer feedstock import dependence exposes margins to freight cost volatility against Gulf currency pegs.
- Makeup:Liquid foundation and cream compact categories balance portability with premium tactile signals through glass and metal assemblies.
- Fragrances:High-proof alcohol formulations demand extended pump seal compatibility testing. REACH-compliant material declarations from European suppliers extend onboarding timelines for cellulose substrate providers serving L'Oréal and Estée Lauder procurement teams.
Haircare dominates unit volume through mass-market channels. Skincare is where margin expansion concentrates as premium brands upgrade airless containment specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf national policies are adapting European recycling infrastructure templates, positioning early investors in post-consumer polymer recovery to capture preferential supplier status. Dubai's free trade zones attract multinational beauty packaging investments through streamlined customs and rapid prototyping capabilities. SFDA cosmetic labeling requirements in Saudi Arabia are tightening ingredient disclosure standards, reshaping packaging graphics across the region.
United Arab Emirates
MOHAP cosmetic regulations align with Gulf standardization efforts while Dubai South and Jebel Ali free zones concentrate multinational headquarters operations. Premium skincare brands expand packaging specifications through localized development centers. Airless pump technology adoption accelerates in Dubai mall retail corridors as brands prioritize contamination control for hyaluronic acid formulations.
Saudi Arabia
SFDA bilingual labeling mandates compel brands to redesign packaging graphics, generating demand for Arabic-compliant print substrates. The national pharmaceutical regulator's tightening cosmetic disclosure rules reshape label specifications across Riyadh and Jeddah distribution channels. Eastern Province petrochemical feedstock availability supports blow-molded bottle production for mass-market haircare volumes.
Morocco
Casablanca manufacturing zones leverage EMA-aligned standards through the national pharmaceutical regulator to serve EU airport retail channels. Duty-free production status enables simplified customs clearance for beauty brands exporting into European duty-free corridors. Moroccan converters scale squeeze-tube output for sunscreen and haircare mask applications across North African retail networks.
South Africa
Polymer feedstock import dependence exposes margins to freight cost volatility against currency fluctuations. Johannesburg and Cape Town industrial corridors host regional packaging conversion capacity for mass-market skincare and haircare segments. The national standards body maintains alignment with ISO 22716 Good Manufacturing Practices certification requirements for Gulf market access.
Egypt
Silica-based glass supply sources from Egyptian manufacturers create regional lead-time advantages for fragrance bottle assembly. Cairo and Alexandria production zones serve finishers across North Africa with molded glass components for premium perfume categories. REACH-compliant material documentation extends supplier onboarding timelines for cellulose substrate providers serving European beauty house procurement teams.
Middle East and Africa Cosmetic Packaging Market Competitive Landscape
Player mix skews toward multinational material science conglomerates with multi-material conversion capabilities alongside regional specialists in blow-molded bottle production. Market structure concentrates procurement toward ISO 22716 GMP-verified converters while marginalizing uncertified regional players. Three archetypes dominate: integrated polymer converters with captive resin supply, glass and metal specialists serving premium fragrance categories, and flexible packaging innovators developing UV-barrier film formats. Competitive moves center on strategic partnerships with Dubai free trade zone operators and backward integration into polymer compounding to secure feedstock stability.
Within the multinational conglomerate tier, Amcor plc and Berry Global Inc exemplify scale-driven positioning through multi-material conversion platforms. Amcor leverages contract positions with multinational beauty houses operating in Jeddah and Casablanca, while Berry anchors regional supply through blow-molded bottle production scaled for haircare volumes. ALPLA Werke Alwin Lehner GmbH & Co KG represents the European-origin specialist archetype with technical depth in extrusion blow molding. These three entities collectively illustrate how geographic footprint breadth and material versatility determine procurement relationships with Gulf retail channel gatekeepers.
| Leading Market Players |
|---|
| Nioro Plastics (Pty) Ltd |
| AptarGroup Inc |
| Amcor plc |
| Mpact Plastics |
| Berry Global Inc |
| ALPLA Werke Alwin Lehner GmbH & Co KG |
| Al LendOn Packaging (Pty) Ltd |
| Silgan Holdings Inc |
| Napco National Company |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Gulf retailers and ISO 22716-certified converters lock in both polymer resin access and price visibility across Ramadan and holiday production windows. These arrangements tether unit economics to SFDA compliance costs and Egyptian glass supply reliability.
Pricing Analysis
Certification level (ISO 22716 GMP-grade) creates the primary spread between premium and mass-market tiers. Three-tier pricing structure across GMP-verified, transition-grade, and uncertified levels governs procurement relationships with Dubai free trade zone operators. Price compression in mass-market haircare bottles stems from polyethylene resin import volatility against Gulf currency pegs. Mass-market shampoo brands exhibit highest price sensitivity, while premium fragrance houses absorb substrate upgrades for Arabic-compliant labeling.
Supply Chain Analysis
Egypt and European glass manufacturers anchor silica-based bottle supply for premium fragrance assembly. Saudi Arabian petrochemical feedstock and Moroccan converter networks draw from polyethylene and polypropylene resin imports. Single-source vulnerability concentrates in Egyptian molded glass for Casablanca-based finishers serving EU duty-free channels. Distribution runs through Dubai free trade zone clustering with Jebel Ali customs facilitation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
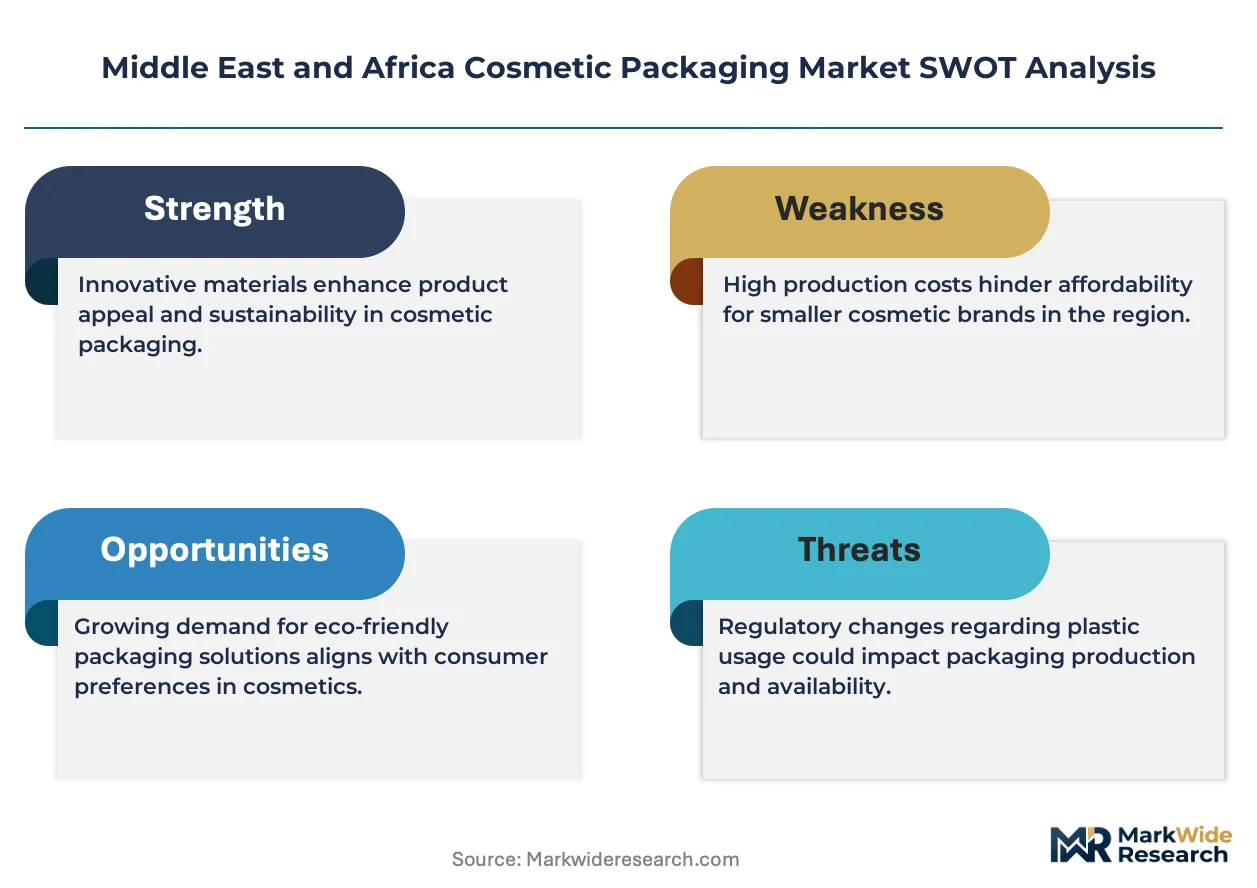
This market functions as a regulatory-moat environment where SFDA certification entrenchment and ISO 22716 audit backlogs create switching costs for Gulf retail channel access.
For Market Incumbents: Compound GMP certification advantages by embedding rapid prototyping capabilities alongside Dubai South production floors. Expand backward integration into polymer compounding to offset resin import volatility threatening mass-market haircare margins. Capture airless pump specification growth through seal integrity R&D partnerships with multinational beauty houses. For New Entrants and Emerging Players: Lead with UV-barrier film innovation targeting vitamin-C and retinol formulations in UAE mall retail corridors. White-space concentrates in post-consumer polymer recovery infrastructure as Gulf national policies adapt European extended producer responsibility templates. Pursue strategic partnerships with Casablanca manufacturing zone operators for EMA-aligned export corridor access. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors multi-material converters with captive resin supply. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale. Target acquisition archetype: ISO 22716-certified regional players with Dubai free trade zone positioning. Monitor SFDA audit backlog resolution as inflection indicator for supplier qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 22716 Certification Investment | GMP verification unlocks procurement relationships with L'Oréal and Estée Lauder Dubai headquarters. |
| Backward Integration into Polymer Compounding | In-house resin production shields margins from freight cost swings against Gulf pegged currencies. |
| Airless Pump Technology Partnership | Seal integrity collaboration with multinational brands captures premium skincare specification growth. |
| Casablanca Manufacturing Zone Expansion | EMA-aligned production status enables simplified EU airport retail customs clearance. |
| Post-Consumer Polymer Recovery Infrastructure | Early investment positions for preferential supplier status under migrating Gulf extended producer responsibility frameworks. |
Research Methodology
Desk research of customs trade records, SEC filings from multinational packaging conglomerates, and Gulf regulatory gazettes preceded structured interviews with procurement directors at Dubai-based beauty houses, plant managers at Moroccan converter facilities, SFDA compliance officers, and polymer resin distributors. Primary fieldwork across Jeddah, Casablanca, and Dubai South free zones combined with secondary validation from ISO certification body disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across material type, product format, closure mechanism, and end-use category shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth trajectory blending and cross-validation against petrochemical feedstock demand forecasts. Modeled inputs included SFDA regulatory implementation timelines and airless pump technology diffusion curves through premium skincare channels.
The analysis sits within stated boundaries; outcomes outside sustained Gulf currency peg stability or Egyptian glass supply continuity would require recalibration. Forecasts reflect assumptions around ISO 22716 audit capacity expansion and polymer resin import tariff regimes. Recalibration cycles align with material shifts in SFDA labeling enforcement and extended producer responsibility policy adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetic Packaging
Cosmetic Tubes Market
Cosmetic Packaging
Europe Personal Care Packaging Market
Cosmetic Packaging
Skin Glossing Pencil Packaging Market
Cosmetic Packaging
Cosmetic and Toiletry Containers Market
Cosmetic Packaging
Asia Pacific Personal Care Packaging Market
Cosmetic Packaging
Global Cosmetic Packaging Market
Cosmetic Packaging
China Personal Care Packaging Market
Cosmetic Packaging
Beauty Supplements Packaging Market
Cosmetic Packaging
Nail Polish Packaging Market
Cosmetic Packaging
Cosmetic Vials Market
Cosmetic Packaging
Make-Up Products Packaging Market
Cosmetic Packaging
Skin Care Packaging Market
Cosmetic Packaging
Lip Gloss Tube Market
Cosmetic Packaging
Cosmetic Spray Bottles Market
Cosmetic Packaging
Cream Jars Market
Cosmetic Packaging
US Personal Care Packaging Market