
 Wheat Protein Market | 2026-2036
Wheat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Wheat Protein Market Analysis
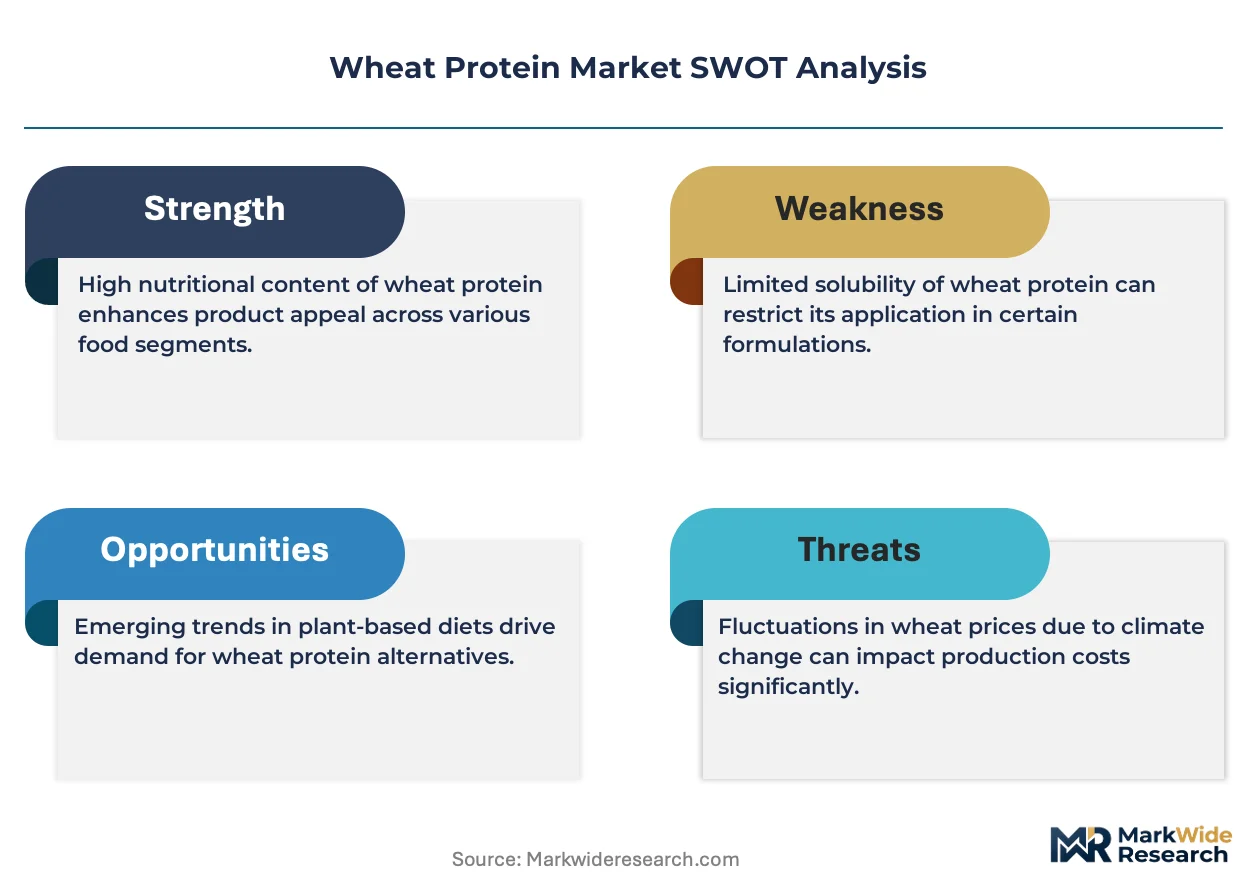
Soy protein isolate is decoupling from premium meat-alternative formulations as wheat gluten achieves comparable elasticity at lower input cost. Cargill leverages its North American grain origination network to secure feedstock for protein extraction. MGP Ingredients anchors its positioning through decades of specialty wheat protein refinement for food and beverage customers.
Wheat protein denotes the nitrogenous compounds extracted from wheat endosperm, principally glutenin and gliadin fractions that form viscoelastic networks when hydrated, typically comprising 75-85% protein on a dry basis with the balance as starch and fiber; these functional properties enable dough conditioning, meat analog structuring, and nutritional fortification across industrial food systems. Wheat gluten dominates current volume flows due to its entrenched role in commercial baking and seitan production, while textured wheat protein captures the fastest expansion as plant-based meat brands scale extrusion capacity; hydrolyzed wheat protein concentrates margin pools in cosmetics and nutraceutical channels where peptide molecular weight dictates pricing tiers.
The FDA enforces Food Allergen Labeling and Consumer Protection Act disclosures for wheat-derived ingredients, compelling reformulation investments from exporters targeting US retail shelves; EFSA evaluates novel protein extraction methods under EU food safety frameworks, shaping which hydrolysis technologies gain market access across member states. Stakeholders must monitor how divergent allergen thresholds between jurisdictions affect cross-border formulation strategies and certification costs.
Market Dynamics
Plant-based meat manufacturers are accelerating textured wheat protein procurement while the FDA and EFSA tighten allergen labeling protocols, forcing reformulation investments and reshaping competitive positioning across extraction and processing tiers.
Growth Catalysts
- EU Novel Food Framework:EFSA evaluations of enzymatic hydrolysis methods are accelerating market access for peptide-based wheat protein concentrates in nutraceutical channels.
- Extrusion Technology Maturation:High-moisture extrusion systems enable meat analog producers to achieve fibrous textures previously requiring soy protein isolates.
- German Processing Concentration:Major extraction facilities in the Lower Saxony grain belt reduce feedstock transport costs for European food manufacturers.
Market Restraints
- Celiac Disease Prevalence:Gluten-free dietary mandates in school and healthcare foodservice channels restrict wheat protein penetration in institutional nutrition.
- Input Cost Volatility:Durum and hard red winter wheat prices fluctuate with Black Sea export disruptions and North American drought cycles.
- Substitute Protein Competition:Pea protein isolates achieve comparable water-holding capacity at neutral pH, displacing wheat gluten in certain bakery applications.
Strategic Opportunities
- Cosmetics Peptide Segment:Hydrolyzed wheat proteins with sub-1000 Da molecular weight command premium positioning in dermal repair formulations.
- US BioPreferred Program:Federal procurement preferences for biobased ingredients create a dedicated demand channel for wheat protein-based adhesives and films.
- Precision Fermentation Convergence:Hybrid formulations combining wheat gluten scaffolds with fermented proteins enable next-generation whole-cut analog structures.
Industry Challenges
- Allergen Control Infrastructure:Dedicated production lines for gluten-free facilities require capital-intensive segregation systems to prevent cross-contact.
- Peptide Standardization Delays:Absence of harmonized molecular weight classification protocols complicates specification alignment between extractors and cosmetic formulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheat Protein Market |
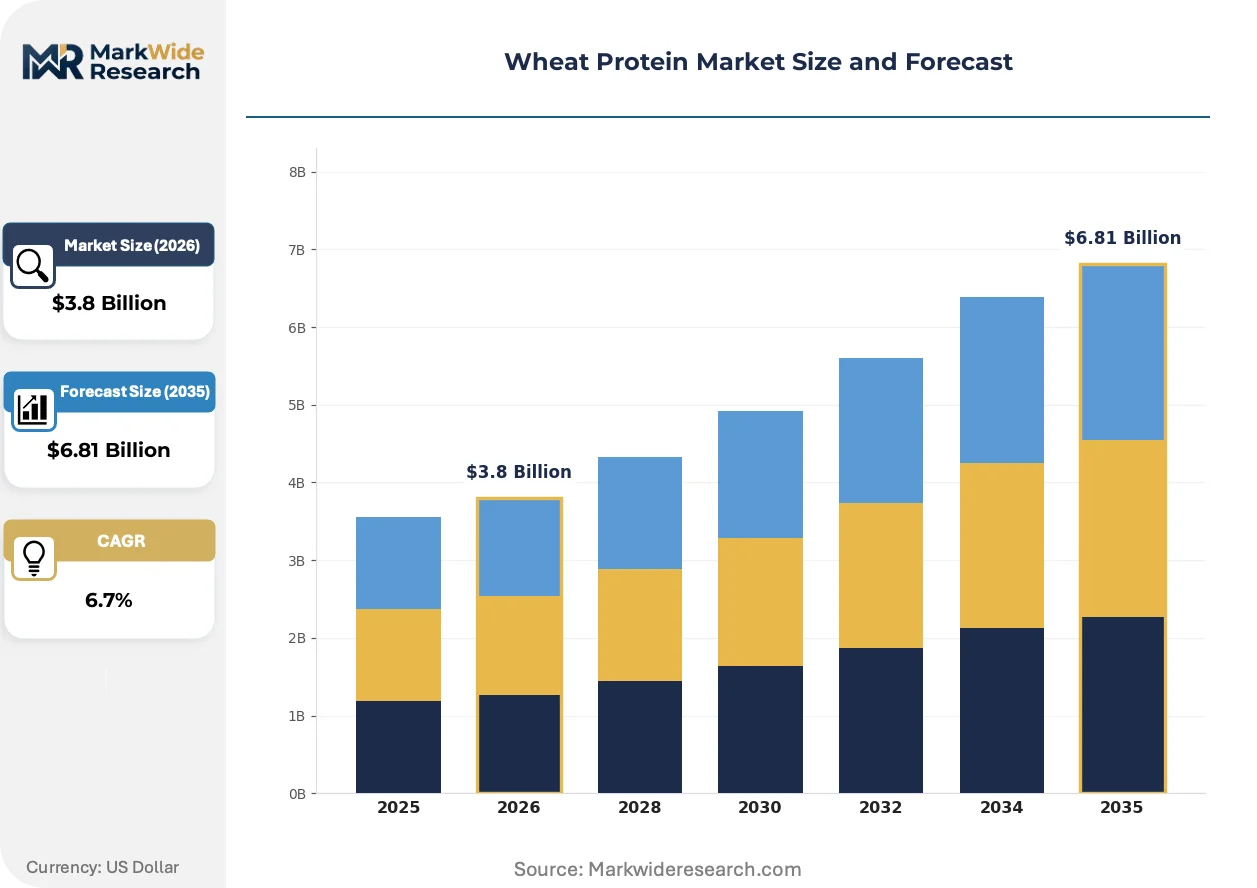
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Wheat Protein, Hydrolyzed Wheat Protein, Wheat Gluten, Wheat Protein Concentrate Application: Baked Goods, Meat Alternatives, Snack Foods, Dairy Alternatives End User: Food Industry, Animal Feed, Nutraceuticals, Cosmetics Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Archer Daniels Midland Company, Cargill, MGP Ingredients, Roquette, Manildra Group, Crespel & Deiters GmbH and Co. KG, Südzucker AG, Tereos, Kerry Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheat Protein Market Emerging Trajectories
Extraction technologies and regulatory frameworks are converging to redefine wheat protein valorization pathways, with enzymatic processing and allergen management protocols emerging as decisive competitive differentiators.
Enzymatic hydrolysis systems with membrane filtration integration enable precise molecular weight fractionation for cosmetic and nutraceutical applications. Specialty chemical producers are adopting these platforms at accelerated cadence. This capability is rewriting margin distribution across the wheat protein value chain, concentrating returns in fractionation rather than bulk gluten extraction.
REACH registration requirements for novel protein hydrolysates are tightening substance characterization obligations for EU market access. Industrial users must now submit extended safety data sets covering peptide allergenicity profiles. Bakery and meat analog segments are responding by securing pre-registration consulting and building analytical capabilities in-house.
Direct contracting between plant-based meat brands and wheat processors is compressing traditional ingredient distribution layers. Foodservice distributors and commodity brokers are losing share to bilateral supply agreements with volume commitments and co-development clauses. This pattern is most pronounced in Germany and the Netherlands where seitan and analog production clusters concentrate demand.
Wheat Protein Market Segmentation
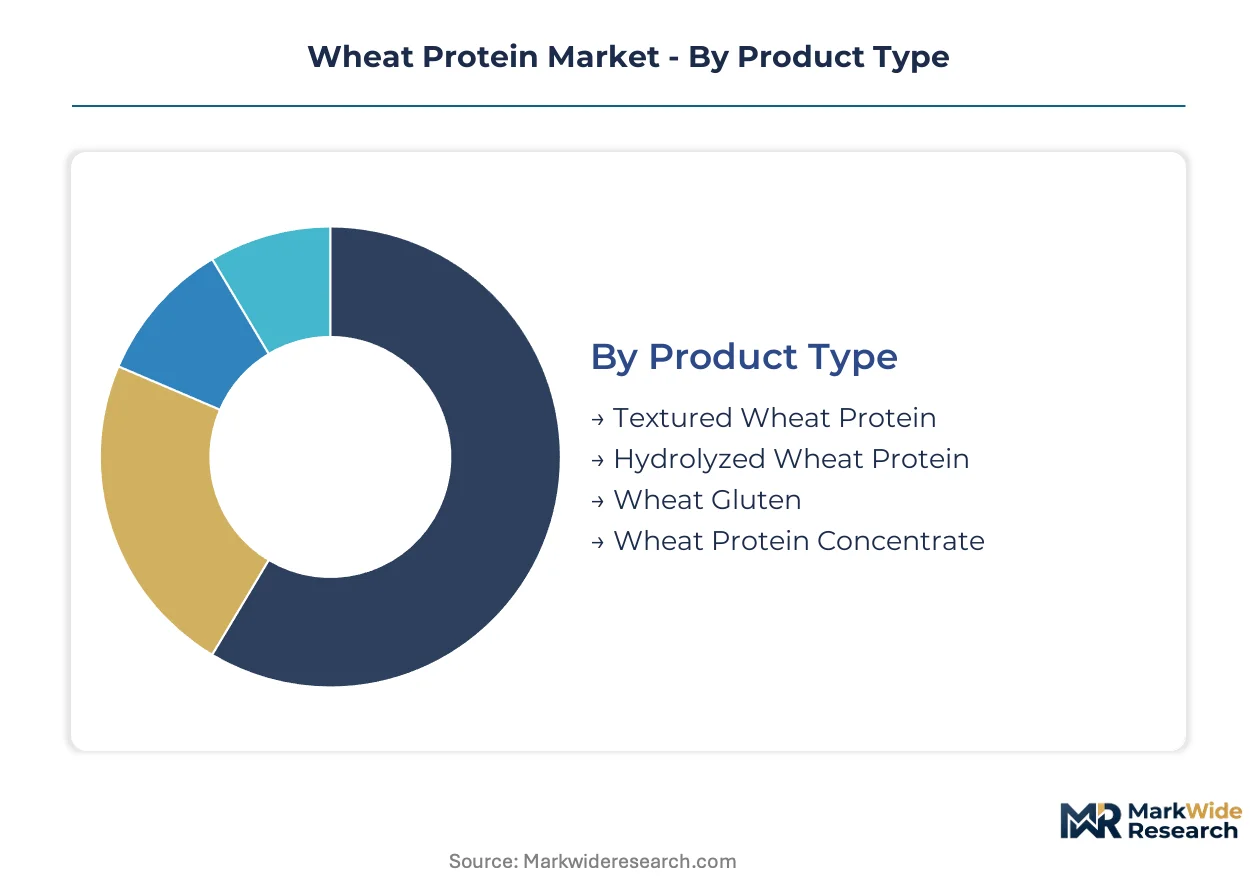
Wheat protein segmentation reveals divergent margin profiles across extraction technologies and end-use channels. Product type stratification separates commodity gluten flows from premium peptide concentrates, while application splits expose which sectors absorb functional premiums versus price-sensitive bulk purchasing.
Product Type:
Volume flows concentrate in wheat gluten, while value capture shifts toward hydrolyzed fractions with cosmetic and nutraceutical certification.
- Wheat Gluten:Comprising 75-85% protein on dry basis with viscoelastic glutenin-gliadin networks. Commercial baking and seitan manufacturing in Germany absorb the majority of output, constrained by celiac-related institutional procurement restrictions.
- Hydrolyzed Wheat Protein:Enzymatically fractionated peptides with molecular weight tiers dictating pricing. Sub-1000 Da fractions command premium positioning in dermal repair formulations from French and Swiss cosmetics houses.
- Textured Wheat Protein:High-moisture extrusion enables fibrous meat analog structures. Plant-based brands in the Netherlands and Germany are accelerating procurement through direct processor contracts.
- Wheat Protein Concentrate:Intermediate protein grade bridging feed and food applications. Animal feed compounders in Lower Saxony represent steady offtake for standard concentrates.
Mature deployment sits with wheat gluten. Newer deployment is concentrated in hydrolyzed wheat protein.
Application:
Functional requirements determine protein grade selection, with elasticity demands in baking contrasting against water-holding specifications in meat alternatives.
- Baked Goods:Dough conditioning remains the foundational use case. Artisan and industrial bakeries across Germany, Italy, and France specify vital wheat gluten for volume and crumb structure.
- Meat Alternatives:Textured wheat protein achieves fibrous textures previously requiring soy isolates. High-moisture extrusion capacity expansion in the Netherlands is climbing the fastest among application channels.
- Snack Foods:Protein fortification and texture modification in extruded snacks. CPG manufacturers balance cost against allergen labeling complexity.
- Dairy Alternatives:Emulsification and mouthfeel enhancement in plant-based cheeses and creams. Smaller volume segment with formulation development ongoing.
Established penetration sits with baked goods. Emerging deployment concentrates in meat alternatives.
End User:
Regulatory exposure varies sharply across end users, with food allergen mandates imposing compliance costs that nutraceutical and cosmetic channels absorb more readily.
- Food Industry:Dominant volume channel spanning bakery, meat analog, and processed food manufacturing. FDA and EFSA labeling protocols force reformulation investments from exporters targeting retail shelves.
- Cosmetics:Hydrolyzed peptide concentrates for hair and skin formulations. REACH registration requirements for novel hydrolysates tighten substance characterization obligations for EU market access.
- Nutraceuticals:Protein fortification and peptide-based functional ingredients. EFSA evaluations of enzymatic hydrolysis methods are accelerating market access for peptide concentrates.
- Animal Feed:Cost-driven segment utilizing lower-grade concentrates. Compound feed manufacturers prioritize protein content per unit cost over functional properties.
Volume concentration sits with food industry. Margin expansion concentrates in cosmetics.
Distribution Channel:
Channel structure is restructuring as direct contracting between plant-based brands and wheat processors compresses traditional distribution layers.
- Direct Sales:Bilateral supply agreements with volume commitments and co-development clauses. Most pronounced in Germany and the Netherlands where seitan and analog production clusters concentrate demand.
- Supermarkets:Branded consumer gluten and specialty wheat ingredients. Retail shelf placement requires allergen compliance documentation.
- Specialty Stores:Health food and organic channels for premium and certified products. Smaller volume with higher service expectations.
- Online Retail:Direct-to-consumer and small-scale B2B procurement. Growing share for niche peptide grades and specialty hydrolysates.
Traditional volume sits with supermarkets. Relationship-based contracting concentrates in direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for wheat protein concentrates in Germany and the Netherlands, where plant-based meat clusters drive textured protein procurement. FDA allergen labeling mandates and EFSA novel food evaluations reshape formulation strategies for exporters targeting these jurisdictions. Processing infrastructure concentrates in the Lower Saxony grain belt and Dutch extrusion hubs.
Germany
Textured wheat protein procurement from plant-based meat manufacturers accelerates in the Lower Saxony region. EFSA novel food framework evaluations shape enzymatic hydrolysis technology adoption for peptide concentrates. Crespel & Deiters GmbH and Co. KG and Südzucker AG operate major extraction facilities in the northwestern grain belt, reducing feedstock transport costs for European food manufacturers.
United States
Vital wheat gluten demand from commercial baking and seitan production sustains volume flows. FDA Food Allergen Labeling and Consumer Protection Act disclosures compel reformulation investments from exporters targeting retail shelves. MGP Ingredients anchors specialty wheat protein refinement operations in Kansas, serving food and beverage customers through decades of technical expertise.
Netherlands
High-moisture extrusion capacity for meat analog applications climbs fastest among European application channels. REACH registration requirements for novel protein hydrolysates tighten substance characterization obligations for EU market access. Direct contracting between plant-based brands and wheat processors compresses traditional ingredient distribution layers in Dutch production clusters.
France
Hydrolyzed wheat protein peptides with sub-1000 Da molecular weight command premium positioning in dermal repair formulations. EFSA evaluates enzymatic hydrolysis methods under EU food safety frameworks, shaping technology access across member states. French and Swiss cosmetics houses concentrate demand for cosmetic-grade peptide concentrates from specialized extractors.
China
Feedstock origination networks secure hard red winter wheat supplies for protein extraction operations. GB standards and SAMR regulations govern food ingredient safety classifications for wheat-derived additives. Yangtze River Delta processing hubs expand fractionation capacity for intermediate protein grades bridging feed and food applications.
Wheat Protein Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with bulk gluten extraction consolidating around grain originators and peptide fractionation fragmenting among enzymatic processing specialists. Three archetypes dominate: agricultural conglomerates with captive wheat supply, specialty ingredient refiners with decades of technical expertise, and enzymatic technology platforms serving cosmetic and nutraceutical channels. Competitive moves concentrate on direct contracting partnerships with plant-based meat brands and backward integration into grain origination networks.
Within the specialty refining tier, MGP Ingredients exemplifies decades-long positioning in wheat protein technical applications, while Crespel & Deiters GmbH and Co. KG occupies a central position in European enzymatic processing. Among agricultural conglomerates with scale advantages, Cargill represents the archetype of grain origination networks feeding extraction operations.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| MGP Ingredients |
| Roquette |
| Manildra Group |
| Crespel & Deiters GmbH and Co. KG |
| Südzucker AG |
| Tereos |
| Kerry Group PLC |
| Others |
Supply Flow & Price Mechanics
Enzymatic processing specialists in the Lower Saxony grain belt command wage premiums that widen spreads between commodity gluten and peptide-grade concentrates. Labor-cost differentials between fractionation technicians and bulk extraction operators translate directly into three-tier pricing stratification across food, feed, and cosmetic channels.
Pricing Analysis
Volume flows anchor in commodity wheat gluten while margin capture concentrates in sub-1000 Da hydrolysates for dermal repair formulations. Pricing stratifies across premium cosmetic-grade, standard food-grade, and economy feed-grade tiers based on molecular weight certification and REACH registration status. Cost compression in standard food-grade gluten is intensifying because pea protein isolates achieve comparable water-holding capacity at neutral pH. Animal feed compounders exhibit highest price sensitivity; French and Swiss cosmetics houses absorb premium positioning with minimal volume elasticity.
Supply Chain Analysis
Reverse-logistics flows for hydrolyzed peptide returns and expired cosmetic batches remain underdeveloped, creating working capital drag for specialized extractors. Feedstock origination draws from hard red winter wheat networks in the United States, durum belts in Canada, and Black Sea export corridors. Supply chain risk centers on single-source vulnerability for high-purity enzyme supplies used in fractionation. Distribution runs through direct bilateral agreements between plant-based meat brands and processors, compressing traditional commodity broker layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wheat protein sector is executing a technology-transition phase as enzymatic hydrolysis with membrane filtration displaces legacy acid-hydrolysis methods for peptide production.
For Market Incumbents: Extend technical service capabilities into co-development partnerships with plant-based meat brands to lock in volume commitments before extrusion capacity saturates. Deepen backward integration into North American grain origination networks to secure feedstock cost advantage against Black Sea price volatility. Prioritize REACH pre-registration consulting investments to accelerate EU market access for novel hydrolysates. For New Entrants and Emerging Players: Enter via the cosmetics peptide segment where sub-1000 Da molecular weight specifications command premium positioning and incumbent capacity constraints create white space. Target nutraceutical channels in Germany and the Netherlands where EFSA novel food framework evaluations are accelerating market access for enzymatic hydrolysis methods. Deploy contract manufacturing partnerships with established extractors to bypass capital-intensive fractionation infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with enzymatic technology platforms given EFSA acceleration of peptide concentrate approvals and REACH registration moats. Long-term viability favors specialists with captive enzyme supply and membrane filtration capabilities over commodity gluten processors. Monitor FDA allergen labeling enforcement intensity as inflection indicator for reformulation-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill's North American network secures feedstock cost advantage against Black Sea volatility. |
| Enzymatic Hydrolysis Technology Licensing | Crespel & Deiters GmbH leverages decades of fractionation expertise for cosmetic-grade peptide production. |
| Direct Processor-Brand Contracting | Plant-based meat manufacturers in the Netherlands bypass distributors for textured wheat protein procurement. |
| REACH Registration Pre-Consulting | Specialty extractors build analytical capabilities to meet ECHA substance characterization obligations. |
| High-Moisture Extrusion Capacity Expansion | Dutch production clusters enable fibrous meat analog structures previously requiring soy protein isolates. |
Methodological Framework
Document review covered FDA Food Allergen Labeling and Consumer Protection Act filings, EFSA novel food evaluation databases, REACH registration guidance documents, and SEC 10-K disclosures from listed ingredient processors, complemented by interviews with enzymatic processing engineers, plant-based meat procurement leads, cosmetics formulators, and feed compounder technical directors. Bottom-up triangulation across extraction facility capacity data and top-down validation against customs trade flows anchored volume estimates.
Cross-reference between historical price series for hard red winter wheat and panel input from grain origination specialists shaped the projection framework. Segmentation dimensions modeled include product type, application channel, end-user industry, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves across the projection horizon, incorporating EFSA evaluation timelines and FDA enforcement intensity as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Black Sea export disruption scenarios and accelerated celiac-related institutional procurement restrictions. Practitioners should monitor FDA warning letter issuance rates for allergen labeling violations and EFSA novel food approval cadence for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Pea Grits Market
Grains
Egypt Rice Market
Grains
Wheat Bran Market
Grains
Grain and Cereal Crop Market
Grains
Asia Pacific Maize Market
Grains
Africa Wheat Flour Market
Grains
North America Oats Market
Grains
Soya Flour Market
Grains
United States Rice Market
Grains
North America Wheat Protein Market
Grains
Grain-Based Flours Market
Grains
Europe Rice Market
Grains
Soy Grits Market
Grains
Wheat Fiber Market
Grains
Barley Market
Grains
White Rice Flour Market