
 Asia Pacific Poultry Feed Market | 2026-2036
Asia Pacific Poultry Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Poultry Feed Market Outlook
Layer farm operations across Vietnam and Indonesia is broadening the addressable base for compound feed suppliers. Charoen Pokphand Foods Public Company Limited anchors production scale across Thailand's integrated poultry belt. De Heus Animal Nutrition competes through specialized aqua-poultry nutrition crossover expertise. Cargill Incorporated controls upstream grain origination networks that sustain margin stability across volatile commodity cycles.
Asia Pacific poultry feed denotes formulated rations combining corn, soybean meal, wheat, and protein sources with amino acid premixes, enzymes, and coccidiostats to optimize feed conversion ratios in broiler and layer operations. Broiler feed dominates volume throughput due to intensive stocking densities and shortened grow-out cycles, while layer feed commands premium pricing tied to extended production phases and shell quality specifications. Specialty feed segments including antibiotic-free and probiotic-enriched variants capture expanding margin pools as integrators in Indonesia and the Philippines reformulate rations to meet export market residue standards.
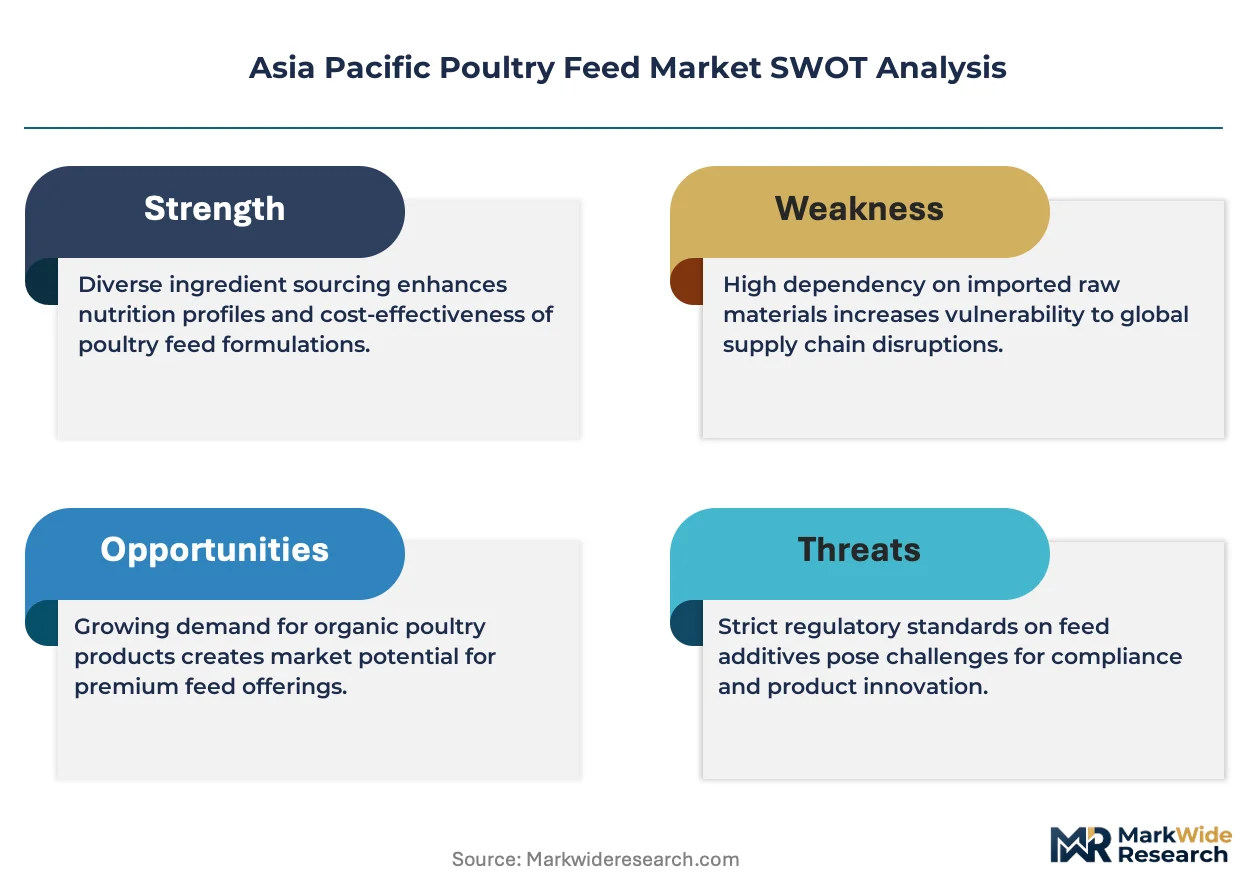
China's SAMR enforces GB standards on veterinary drug residues in feed formulations, while India's FSSAI mandates contaminant limits for aflatoxin and heavy metals in compounded feeds. These frameworks elevate compliance costs for small-scale regional blenders and redirect procurement toward certified premix suppliers. Stakeholders must monitor regulatory divergence between ASEAN harmonization initiatives and country-specific residue protocols when configuring cross-border formulation strategies.
Market Dynamics
Contract farming expansion across Southeast Asia is consolidating procurement power into the hands of commercial integrators, compressing margins for independent feed blenders while elevating volume commitments for certified premix suppliers.
Growth Catalysts
- Indonesia's Java corridor concentration:Intensive broiler operations in this belt generate sustained bulk demand for compound feed, creating captive offtake agreements that stabilize supplier throughput.
- GB standards for antibiotic-free formulations:China's SAMR enforcement of residue limits is forcing integrators to reformulate rations, opening premium pricing tiers for compliant premix alternatives.
- Enzyme supplementation technology:Phytase and protease additives are improving feed conversion ratios in Vietnamese layer operations, reducing per-unit protein input costs.
Market Restraints
- Corn and soybean meal volatility:Asia Pacific feed milling remains exposed to Black Sea and South American grain supply disruptions, compressing gross margins during price spikes.
- Small-scale regional blender fragmentation:India's FSSAI compliance costs are driving consolidation among micro-formulators unable to fund aflatoxin testing infrastructure.
- Protein source substitution limits:Insect meal and single-cell proteins face technical barriers to amino acid digestibility equivalence, slowing displacement of fishmeal in premium layer feeds.
Strategic Opportunities
- Philippines Mindanao poultry belt:Underdeveloped feed milling infrastructure in this southern corridor offers first-mover positioning for integrated aqua-poultry nutrition specialists.
- FSSAI feed safety certification:India's mandatory contaminant limits are creating tiered supplier accreditation that favors certified premix vendors over commodity blenders.
- Probiotic-enriched feed convergence:Layer operations are combining direct-fed microbials with organic acidifiers to replace antibiotic growth promoters, opening formulation service contracts.
Industry Challenges
- Feed safety laboratory capacity:FSSAI-mandated aflatoxin and heavy metal testing requires capital investment in HPLC equipment that strains small-formulator balance sheets.
- Cross-border formulation standardization:Divergent ASEAN harmonization timelines versus country-specific residue protocols complicate multi-plant recipe management for regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Poultry Feed Market |
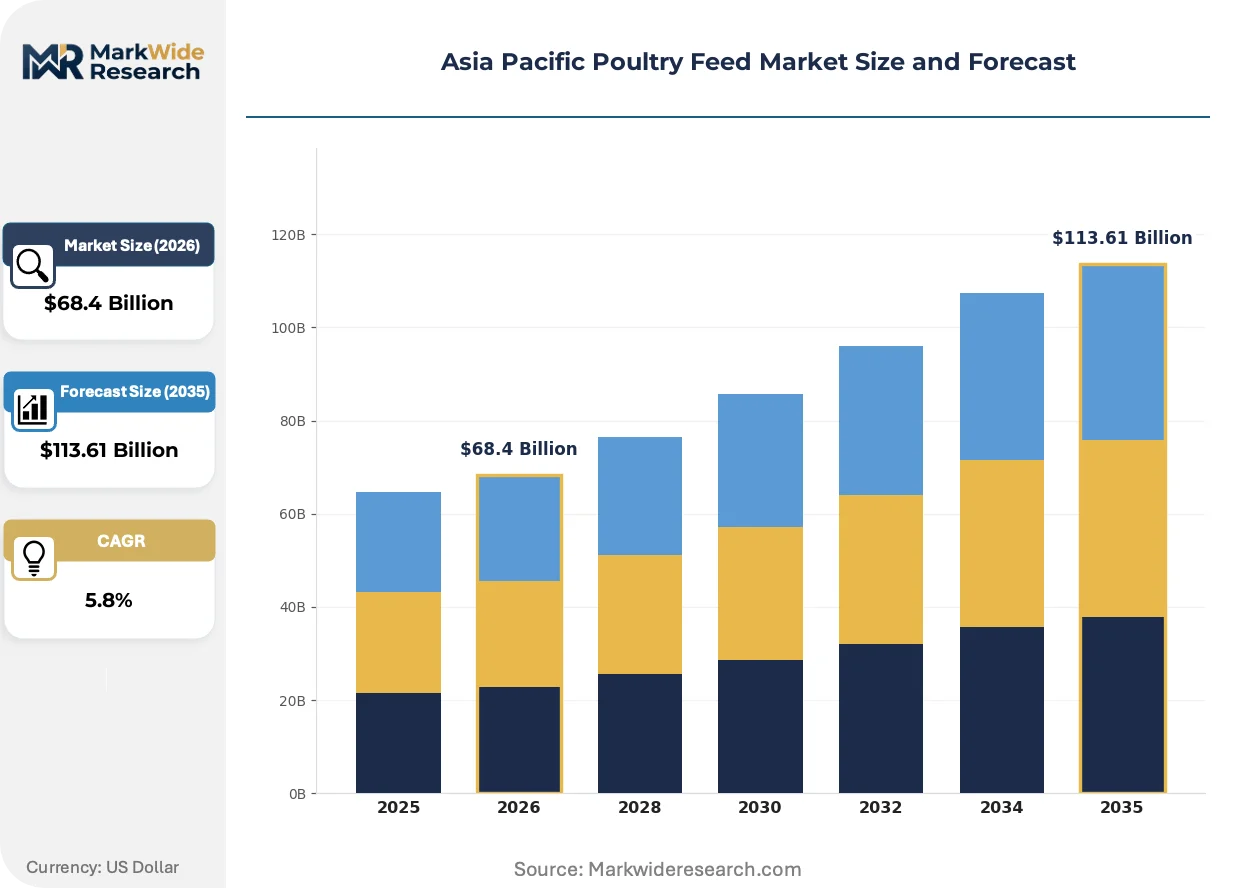
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broiler Feed, Layer Feed, Turkey Feed, Specialty Feed Ingredient Type: Corn, Soybean Meal, Wheat, Protein Sources Distribution Channel: Online Retail, Farm Supply Stores, Distributors, Agriculture Cooperatives End User: Poultry Farms, Commercial Growers, Backyard Poultry Owners, Integrators |
| Companies Covered | Cargill Incorporated, Alltech Inc., Archer Daniels Midland Company, Nutreco N.V., BASF SE, Charoen Pokphand Foods Public Company Limited, De Heus Animal Nutrition, Kyodo Shiryo Company, CP Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Poultry Feed Market Strategic Shifts
Precision formulation technologies and residue compliance automation are compressing the gap between commodity feed blending and specialized nutrition services across Asia Pacific poultry belts.
Near-infrared spectroscopy coupled with automated batching systems is automating real-time nutrient adjustment in Thai integrated feed mills. Commercial integrators in Charoen Pokphand Foods' supply network are deploying these systems to reduce formulation variance below 2% coefficient of variation. The technology is automating quality control labor out of mid-scale operations while concentrating formulation expertise at central R&D hubs.
China's SAMR enforcement of GB 31650 veterinary drug residue limits is eliminating antibiotic growth promoters from export-oriented broiler rations. Integrators serving EU and Japanese buyers are reformulating with organic acids and essential oils to meet MRL compliance. Layer operations face the steepest cost adjustment due to extended production cycles requiring sustained gut health management without subtherapeutic antibiotics.
Integrator procurement departments are consolidating supplier rosters from fifteen-plus vendors to four certified premix partners capable of FSSAI and GB dual compliance. Vietnam's Mekong Delta poultry belt exhibits the most aggressive consolidation, with VinGroup and Dabaco Group centralizing feed sourcing through long-term toll-milling agreements. This concentration is displacing spot-market soybean meal purchases with fixed-price annual contracts indexed to Chicago futures.
Asia Pacific Poultry Feed Market Segmentation
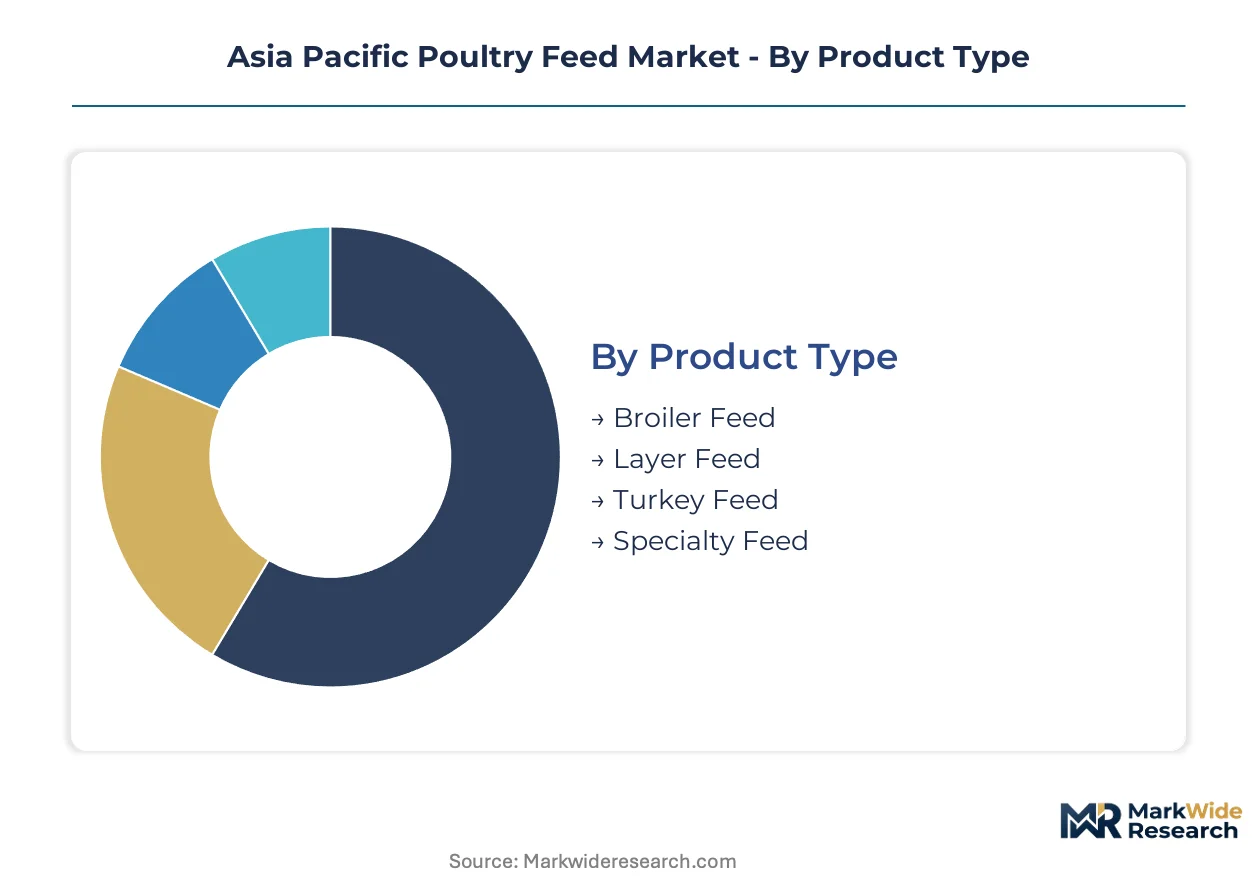
Asia Pacific poultry feed segmentation reveals how formulation complexity, procurement scale, and regulatory compliance reshape supplier economics across diverse production systems. Distinct cost tiers and channel structures emerge between industrial integrators and fragmented backyard operations.
Product Type:
Customization intensity varies sharply across this category, from standardized commodity formulations to precision-engineered specialty rations requiring residue certification.
- Broiler Feed:High-density formulations optimize feed conversion ratios through amino acid premixes and coccidiostats for 35-42 day grow-out cycles. Demand concentrates in Indonesia's Java corridor and Vietnam's Mekong Delta, where Charoen Pokphand Foods and Dabaco Group operate captive feed mills under toll-milling agreements that displace spot-market soybean meal procurement.
- Layer Feed:Extended production-phase rations incorporate shell-quality minerals and sustained gut health additives to maintain 80+ week laying cycles. Premium pricing reflects FSSAI aflatoxin compliance costs and GB-standard antibiotic-free requirements for export-oriented operations in India's Andhra Pradesh and China's Shandong province.
- Turkey Feed:Niche category serving limited commercial production bases in Australia and select Southeast Asian markets with specialized amino acid profiles for slower-growing genetic lines.
- Specialty Feed:Probiotic-enriched and organic-certified variants capture margin pools from EU and Japanese export compliance requirements, though volumes remain constrained by higher per-ton formulation costs.
Leading the category by volume: Broiler Feed. Growing fastest: Specialty Feed.
Ingredient Type:
Cost tier differentiation dominates this category, with commodity grains anchoring baseline formulations while protein alternatives command premium positioning.
- Corn:Primary energy source subject to Black Sea and South American supply volatility that compresses mill margins during price spikes. Thai and Vietnamese integrators hedge through Chicago futures-indexed annual contracts rather than spot purchases.
- Soybean Meal:Dominant protein input standardized at 44-48% crude protein specifications across ASEAN milling operations. Import dependence on South American crushing capacity creates procurement concentration risk that SAMR and FSSAI residue monitoring amplifies through certified supplier requirements.
- Wheat:Regional substitute grain utilized in Australian and Indian formulations where local harvests reduce import dependency, though amino acid supplementation requirements increase processing complexity.
- Protein Sources:Fishmeal, insect meal, and single-cell proteins serve premium layer segments despite technical barriers to digestibility equivalence that slow displacement rates in mainstream broiler rations.
Volume leadership: Corn and Soybean Meal as paired foundation inputs. Fastest substitution interest: alternative Protein Sources.
Distribution Channel:
Customer scale determines channel economics, with procurement consolidation favoring direct-supply relationships over fragmented retail networks.
- Distributors:Regional logistics networks serve mid-scale independent farms across India's Tamil Nadu and the Philippines' Luzon corridor, though FSSAI compliance costs are driving roster consolidation toward certified premix partners.
- Agriculture Cooperatives:Collective purchasing structures in Vietnam and Indonesia aggregate smallholder demand into volume commitments that qualify for integrator toll-milling arrangements.
- Farm Supply Stores:Traditional retail channel retains relevance for backyard poultry owners and micro-farms below commercial integration thresholds, particularly in secondary Indian districts.
- Online Retail:Emerging platform-based procurement for specialty additives and probiotic supplements, constrained by cold-chain requirements for live microbial products.
Channel concentration: Distributors and Agriculture Cooperatives through integrator consolidation. Emerging trajectory: Online Retail for specialty inputs.
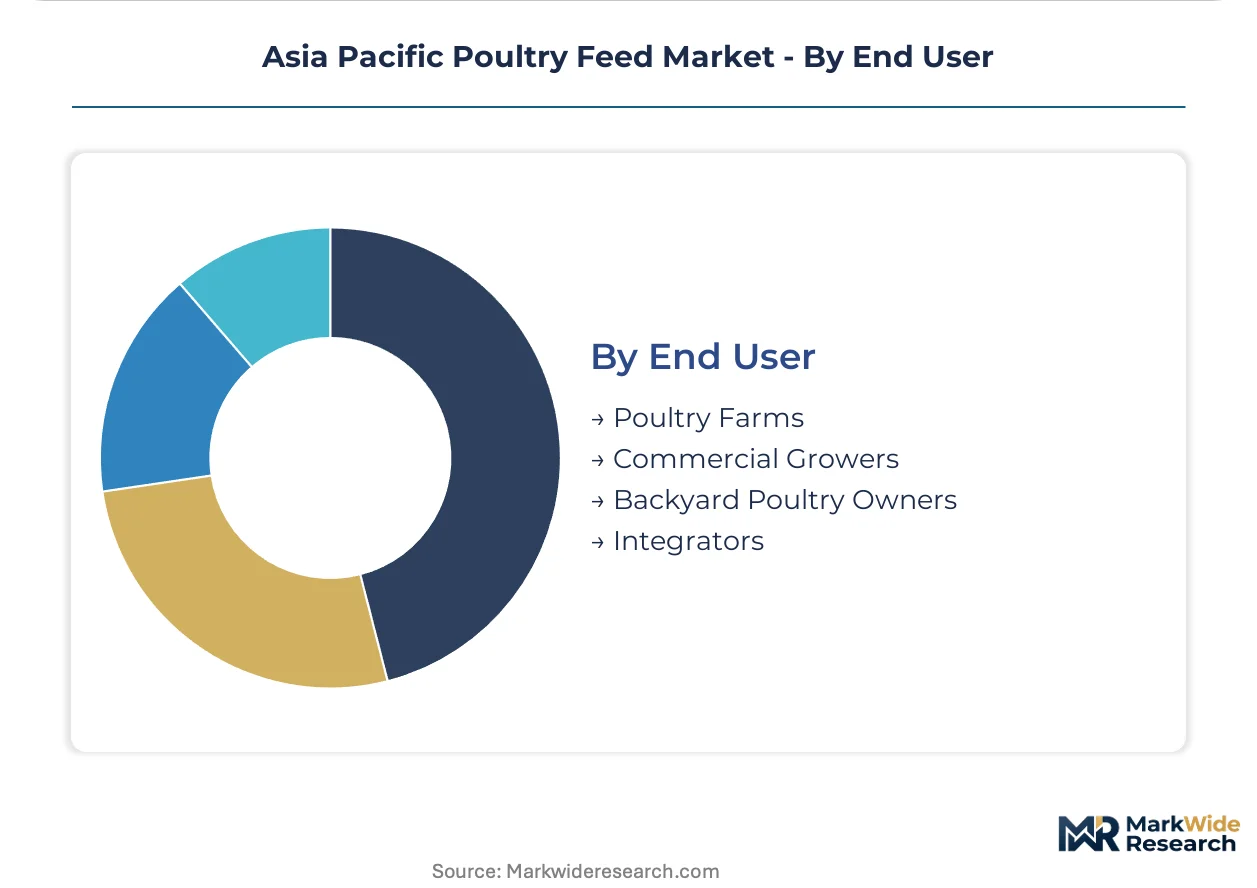
End User:
Procurement sophistication separates this category, from certified premix contracts to commodity spot purchasing.
- Integrators:Commercial operations like Charoen Pokphand Foods and VinGroup centralize formulation control through captive feed mills and long-term supplier accreditations spanning FSSAI and GB dual compliance.
- Commercial Growers:Contract farming participants in Thailand's integrated poultry belt receive ration specifications from integrator procurement departments, eliminating independent formulation decisions.
- Poultry Farms:Independent operations across Indonesia's outer islands and India's Karnataka maintain spot-market flexibility but face margin compression from certified premix cost premiums.
- Backyard Poultry Owners:Fragmented demand base served through farm supply retail, with minimal regulatory compliance exposure due to non-commercial scale.
Procurement scale leadership: Integrators. Fastest structural shift: Commercial Growers under contract farming expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Batam Free Trade Zone and Vietnam's Chu Lai Open Economic Zone concentrate feed milling infrastructure near deepwater ports, accelerating bulk grain import processing for Southeast Asian poultry belts.
China
Shandong province's layer operations drive demand for GB-compliant antibiotic-free formulations. SAMR enforces residue limits through spot-testing protocols at Qingdao port entry points. Yangtze River Delta integrators reformulate rations with organic acidifiers to maintain EU export eligibility.
India
Andhra Pradesh's broiler belt generates volume demand for FSSAI-certified compound feeds. The national regulator mandates aflatoxin screening through accredited laboratories, elevating procurement toward certified premix vendors. Karnataka's independent farms face margin compression from compliance cost premiums.
Vietnam
Mekong Delta contract farming expansion concentrates feed demand under integrator toll-milling agreements. The Ministry of Agriculture and Rural Development enforces veterinary drug residue monitoring at processing facilities. VinGroup's captive feed mills in Long An province displace spot-market soybean meal procurement.
Thailand
Central Plains integrated poultry operations anchor compound feed throughput for export-oriented broiler production. The Department of Livestock Development harmonizes ASEAN residue standards with EU import requirements. Charoen Pokphand Foods' supply network deploys near-infrared spectroscopy at Saraburi formulation facilities.
Indonesia
Java corridor intensive broiler farms sustain bulk demand for high-density grow-out rations. The National Agency for Drug and Food Control mandates feed safety certification for commercial integrators. East Java's Sidoarjo district concentrates toll-milling capacity serving CP Group contract farming participants.
Asia Pacific Poultry Feed Market Competitive Environment
Top-tier vendors anchor integrated supply chains, while regional blenders compete on spot-market flexibility. The market exhibits tiered concentration with multinational nutrition specialists controlling certified premix supply. Three archetypes dominate: grain-origination multinationals, integrated protein conglomerates, and specialized aqua-poultry crossover formulators. Competitive positioning hardens through backward integration into grain origination and long-term toll-milling agreements with commercial integrators.
Within the integrated protein tier, Charoen Pokphand Foods Public Company Limited and CP Group exemplify Southeast Asian conglomerates with captive feed milling networks spanning Thailand and Indonesia. Cargill Incorporated represents grain-origination multinationals leveraging upstream control over Black Sea and South American supply corridors. De Heus Animal Nutrition occupies a position among specialized crossover formulators combining aqua and poultry nutrition expertise for Vietnamese and Philippine integrators.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Alltech Inc. |
| Archer Daniels Midland Company |
| Nutreco N.V. |
| BASF SE |
| Charoen Pokphand Foods Public Company Limited |
| De Heus Animal Nutrition |
| Kyodo Shiryo Company |
| CP Group |
| Others |
Value Chain & Pricing Dynamics
Integrator procurement consolidation across Vietnam and Indonesia is forcing feed millers to abandon spot-market soybean meal purchases in favor of fixed-price annual contracts indexed to Chicago futures, compressing margin flexibility for non-integrated blenders while stabilizing input costs for toll-milling partners.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Charoen Pokphand Foods and VinGroup impose just-in-time delivery requirements on certified premix suppliers. Three-tier pricing structure across antibiotic-free certified, FSSAI-compliant standard, and commodity economy formulations separates compliance-grade product from undifferentiated bulk rations. Cost compression in the economy tier is intensifying because Black Sea grain volatility forces spot purchasers to absorb margin erosion during price spikes. Small-scale independent farms across India's Karnataka exhibit highest price sensitivity, while export-oriented integrators in Thailand's Central Plains demonstrate lowest sensitivity due to pass-through mechanisms in toll-milling agreements.
Supply Chain Analysis
Regional distribution centers in Indonesia's Batam Free Trade Zone and Vietnam's Chu Lai Open Economic Zone anchor hub-and-spoke grain processing networks serving Southeast Asian poultry belts. Supply concentration centers on Black Sea corn corridors, South American soybean crushing capacity, and Thai aquaculture byproduct processing for protein alternatives. Raw material dependencies rest on corn, soybean meal, and fishmeal specifications that SAMR and FSSAI residue monitoring amplifies through certified supplier requirements. Single-source vulnerability in South American soybean meal creates structural exposure that integrators hedge through multi-origin procurement strategies. Distribution runs through integrator-controlled captive feed mills and agriculture cooperative aggregators, with spot-market distributors losing share to long-term toll-milling arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where FSSAI and GB compliance costs are systematically eliminating micro-formulators unable to fund aflatoxin testing infrastructure, concentrating procurement power among certified premix suppliers.
For Market Incumbents: Anticipate margin compression from enzyme supplementation technology commoditization by accelerating backward integration into grain origination networks across Black Sea and South American supply corridors. Defensive positioning requires centralizing formulation expertise at R&D hubs deploying near-infrared spectroscopy automation, while channel control demands expanding toll-milling agreements with VinGroup and Dabaco Group to lock in volume commitments.
For New Entrants and Emerging Players: FSSAI feed safety certification in India opens a window for accredited premix vendors to displace commodity blenders in Andhra Pradesh's broiler belt. White-space targets include Philippines Mindanao poultry belt underdeveloped feed milling infrastructure and probiotic-enriched feed formulation services for layer operations replacing antibiotic growth promoters. Go-to-market positioning as aqua-poultry nutrition crossover specialists leverages technical credibility with Vietnamese integrators seeking integrated ration solutions.
For Investors and Strategic Acquirers: The window for entry favors certified premix suppliers with dual FSSAI-GB compliance capabilities and established toll-milling relationships with Southeast Asian integrators. Long-term viability hinges on acquisition targets possessing grain origination hedging infrastructure and automated formulation technology that reduces coefficient of variation below integrator thresholds. Signal to monitor: integrator roster consolidation velocity from fifteen-plus vendors to four certified partners as indicator of pricing power inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Cargill's Black Sea and South American supply networks sustain margin stability across volatile commodity cycles. |
| Certified Premix Compliance Investment | FSSAI and GB dual accreditation creates supplier tiering that favors capitalized formulators over micro-blenders. |
| Toll-Milling Agreement Expansion | Charoen Pokphand Foods' captive feed mill networks lock in volume commitments through long-term integrator contracts. |
| Precision Formulation Technology Deployment | Near-infrared spectroscopy automation at Thai facilities reduces formulation variance below 2% coefficient of variation. |
| Aqua-Poultry Nutrition Crossover Development | De Heus leverages specialized expertise to capture Mindanao belt positioning for integrated ration solutions. |
Study Parameters
Trade databases, customs records, and SEC filings formed the secondary backbone of this analysis, supplemented by regulatory documentation from SAMR, FSSAI, and ASEAN harmonization initiatives. Primary interviews with feed mill procurement directors, integrator supply chain managers, premix supplier technical directors, and agriculture cooperative purchasing heads combined with secondary validation through bottom-up and top-down triangulation. The approach cross-referenced compound feed production volumes, grain import flows, and certified supplier accreditation rosters to establish market sizing foundations.
Historical trendline analysis of feed conversion ratio improvements, regulatory compliance cost trajectories, and integrator consolidation patterns informed the projection framework. Segmentation modeling incorporated product type differentiation, ingredient cost tier dynamics, distribution channel concentration, and end-user procurement sophistication across the analysis window. CAGR derivation rested on volume throughput projections for Java corridor and Mekong Delta poultry belts, enzyme adoption rates in Vietnamese layer operations, and antibiotic-free formulation penetration in export-oriented integrators.
The model assumes a particular technology adoption path for precision formulation and residue compliance automation; alternative pathways for near-infrared spectroscopy deployment or probiotic-enriched feed convergence would alter the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement intensity, grain price volatility persistence, and integrator procurement consolidation velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Sugar Cane Market
Agriculture and Agri Products
Sophora Japonica Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Global Ruminant Feed Market
Agriculture and Agri Products
Asia-Pacific Swine Feed Market
Agriculture and Agri Products
South Africa Alfalfa Hay Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
Forage Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Oman Agriculture Market