
 Thailand Compound Feed Market | 2026-2036
Thailand Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Compound Feed Market Analytics
Buyer concentration among commercial farms is hardening as Thailand's livestock sector consolidates from backyard operations into integrated contract-farming systems. Charoen Pokphand Foods PCL leverages its vertically integrated poultry and swine operations to anchor captive feed demand across the Central and Eastern regions. Betagro Public Company Limited competes through specialized swine and broiler nutrition programs tailored to high-density farming zones.
Compound feed constitutes nutritionally complete formulated rations combining cereal grains, protein meals, vitamins, and minerals to meet species-specific growth requirements, typically processed through pelleting or extrusion to enhance digestibility and reduce feed waste in intensive production systems. Poultry feed dominates volume as Thailand maintains its position as a leading global broiler exporter, while aquafeed represents the fastest-expanding category amid government-backed shrimp and tilapia intensification programs. Ingredient margins concentrate in additives and functional premixes where formulation expertise creates differentiation against commodity grain blending.
Thailand's Department of Livestock Development enforces Good Manufacturing Practice standards for feed mills, while the National Bureau of Agricultural Commodity and Food Standards monitors mycotoxin limits and antibiotic residue controls under Hazard Analysis Critical Point frameworks. These regulations compound feed producers to invest in quality-assurance laboratories and traceability systems, reshaping competitive barriers toward capital-intensive compliance. Stakeholders must monitor pending restrictions on antibiotic growth promoters and evolving sustainability disclosure requirements that will redefine formulation strategies and sourcing protocols.
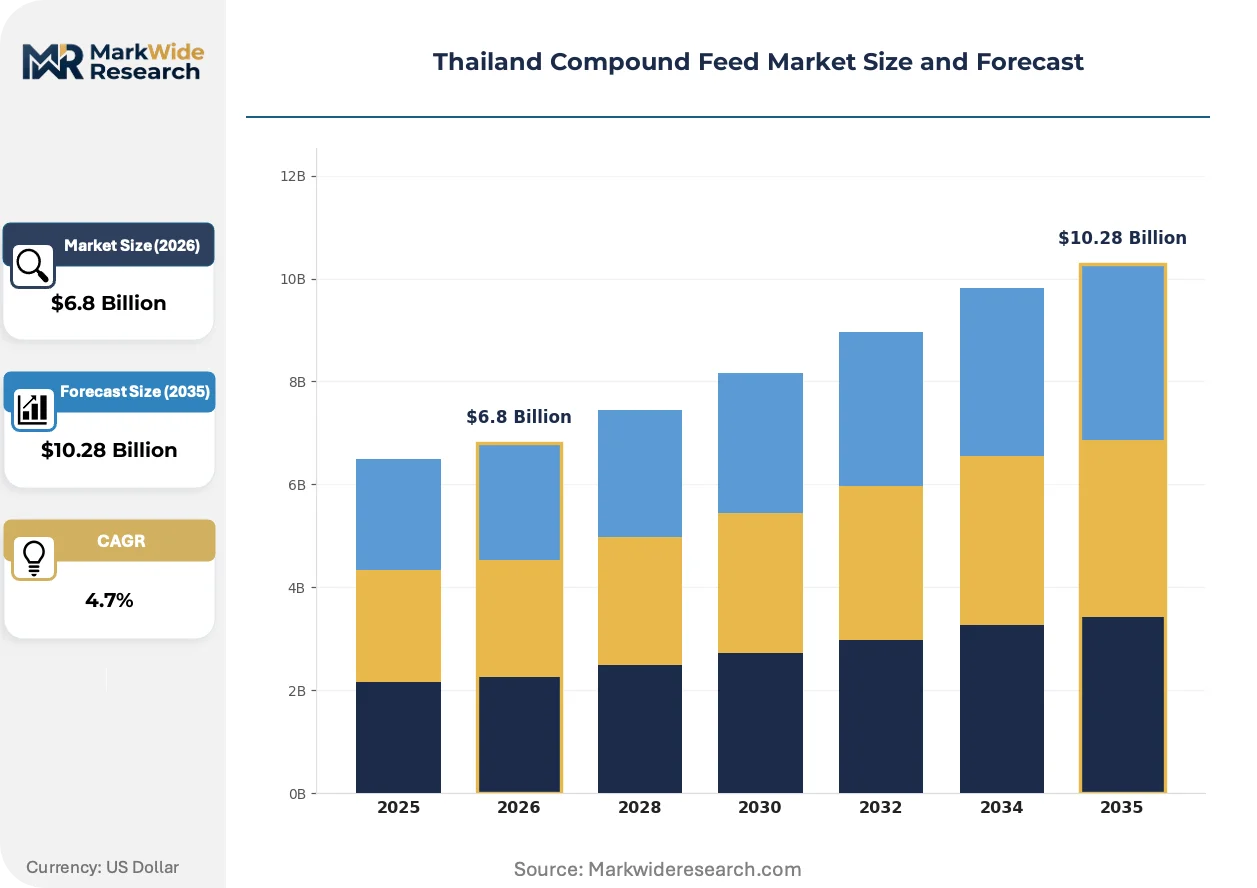
Market Dynamics
Thailand's livestock sector consolidation is compressing feed procurement into fewer, larger buyers while the Department of Livestock Development tightens antibiotic residue controls, forcing mills to restructure formulation capabilities and traceability infrastructure.
Growth Catalysts
- Contract Farming Expansion:Integrated poultry and swine operations in the Central Plains are absorbing compound feed at scale, replacing fragmented backyard demand with predictable volume contracts.
- Aquaculture Intensification:Government-backed shrimp and tilapia programs in coastal provinces are accelerating specialized aquafeed consumption faster than terrestrial categories.
- Export-Oriented Livestock:Thailand's position as a leading global broiler exporter sustains premium feed demand aligned with EU and Japanese import standards.
Market Restraints
- Imported Protein Meal Dependency:Soybean and fishmeal concentrate in Argentine and Peruvian supply chains, exposing Thai mills to currency volatility and port congestion.
- Antibiotic Growth Promoter Phase-Out:Pending Department of Livestock Development restrictions on sub-therapeutic additives threaten conventional formulation cost structures.
- Mycotoxin Surveillance Burden:National Bureau of Agricultural Commodity and Food Standards mandates laboratory testing that elevates fixed costs for smaller regional mills.
Strategic Opportunities
- Northeastern Region Underpenetration:Isaan's emerging commercial pig and poultry zones lack sufficient local milling capacity, creating greenfield site potential.
- Functional Additive Premiumization:Probiotic and enzyme premixes command formulation expertise margins distinct from commodity grain blending.
- Traceability Technology Convergence:Blockchain and near-infrared spectroscopy integration enables antibiotic-free certification premiums for export-contracted farms.
Industry Challenges
- Formulation Chemist Scarcity:Specialized nutrition expertise for species-specific rations concentrates in Bangkok-based multinationals, constraining regional mill upgrading.
- Pelleting Equipment Retrofit Costs:Shifting to antibiotic-free extrusion systems demands capital outlays that compress returns for mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Compound Feed Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Swine Feed, Ruminant Feed, Aquafeed Ingredient Type: Cereal Grains, Soybean Meal, Fish Meal, Additives End User: Commercial Farms, Backyard Farmers, Feed Manufacturers, Retailers Distribution Channel: Online Sales, Direct Sales, Wholesalers, Distributors |
| Companies Covered | INTEQC Feed Co. Ltd, SPM Feed Mill Company Limited, Charoen Pokphand Foods PCL, Alltech Inc., Laemthong Corporation Group, Betagro Public Company Limited, Thai Foods Group Public Company Limited, Sun Feed Co. Ltd, Cargill, Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Compound Feed Market Evolving Landscape
Digital formulation platforms and precision nutrition are displacing experience-based mixing protocols across Thai feed mills, while regulatory pressure on residue transparency accelerates investment in real-time quality monitoring.
Near-infrared spectroscopy is rewriting compound feed quality assurance by enabling instant ingredient composition verification at receiving bays. Large integrated operations in Ratchaburi and Chonburi are deploying these systems to compress batch release cycles from hours to minutes. This compression is eliminating the lag between laboratory results and production scheduling that previously trapped mills in inventory-heavy safety stocks.
The Department of Livestock Development's pending restrictions on antibiotic growth promoters are forcing reformulation toward acidifiers, phytogenics, and probiotic alternatives. Mills serving export-contracted farms must complete transition protocols before EU and Japanese audit seasons, compressing implementation timelines. Aquafeed producers in Samut Sakhon face the steepest compliance curve given shrimp's historical reliance on prophylactic medication.
Buyer concentration among contract-farming integrators is consolidating procurement decisions into centralized nutrition teams. Independent regional distributors that previously served fragmented backyard operations are losing volume to direct mill-integrator relationships. This channel compression is most visible in Nakhon Pathom and Ayutthaya provinces where Charoen Pokphand Foods and Betagro have anchored captive feed demand.
Thailand Compound Feed Market Segmentation
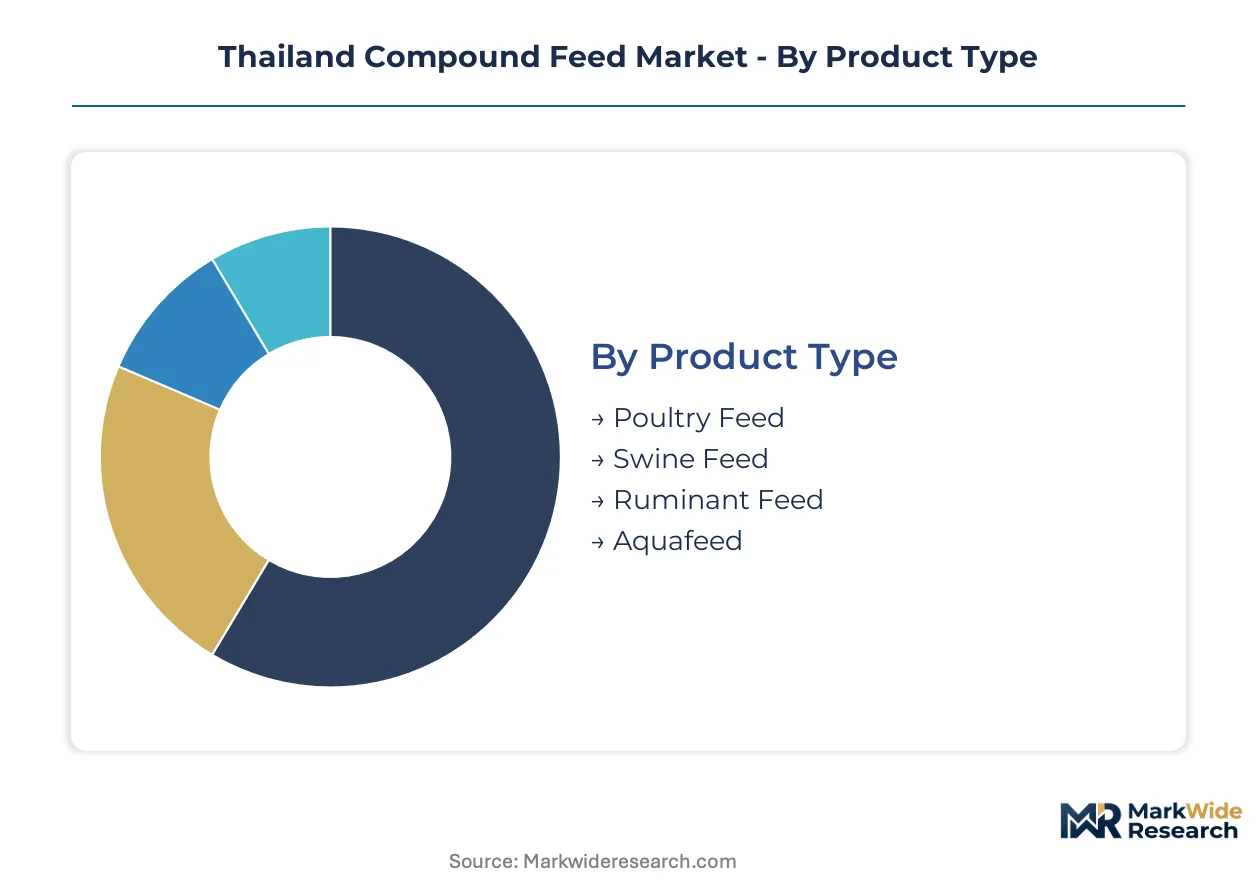
Feed segmentation in Thailand reflects capital intensity disparities between species-specific formulations and commodity ingredient blending. Procurement patterns among commercial integrators favor volume-contracted categories with traceability infrastructure, while smaller operators remain price-sensitive toward generic rations.
Product Type:
Capital requirements vary sharply across species, with aquafeed demanding extrusion systems three to four times costlier than conventional pelleting equipment.
- Poultry Feed:Broiler and layer rations incorporate corn-soybean meal bases with amino acid fortification for rapid weight gain and egg production. Central Plains contract farms surrounding Bangkok absorb the majority of volume as Charoen Pokphand Foods and Betagro anchor captive demand for export-certified broiler operations.
- Aquafeed:Shrimp and tilapia formulations require specialized extrusion for water stability and precise protein-lipid ratios to minimize pond pollution. Coastal provinces including Samut Sakhon and Chanthaburi concentrate demand amid government intensification programs targeting EU and Japanese export compliance.
- Swine Feed:Grower-finisher rations balance energy density with lysine supplementation for lean meat yield in commercial operations.
- Ruminant Feed:Cattle and buffalo rations emphasize fiber content and bypass protein for draft and dairy applications in Northeastern grazing zones.
Poultry feed absorbs the bulk of installed capacity; aquafeed is expanding most quickly.
Ingredient Type:
Margin concentration follows processing complexity, with functional additives commanding formulation premiums far above commodity grain trading.
- Additives:Probiotic, enzyme, and acidifier premixes enable antibiotic-free certification for export-contracted farms. Bangkok-based multinationals control technical expertise as Department of Livestock Development restrictions on growth promoters force reformulation investments.
- Fish Meal:Peruvian anchovy supply chains provide essential amino acid profiles for aquafeed and premium poultry rations. Price volatility and sustainability certification requirements constrain sourcing flexibility for coastal mill operators.
- Soybean Meal:Argentine and Brazilian crush imports supply lysine-rich protein for monogastric formulations across Central Plains feed mills.
- Cereal Grains:Domestic corn and imported wheat form energy bases subject to mycotoxin surveillance under National Bureau of Agricultural Commodity and Food Standards protocols.
Additives capture the highest margin per ton; fish meal faces the steepest procurement cost pressure.
End User:
Customer scale determines service intensity, with commercial integrators demanding technical support and traceability systems unavailable to fragmented backyard operations.
- Commercial Farms:Vertically integrated poultry and swine operations in Ratchaburi, Nakhon Pathom, and Ayutthaya provinces procure through direct mill relationships with volume commitments and nutritionist consulting. Antibiotic-free certification requirements for EU and Japanese export contracts elevate formulation specifications above commodity standards.
- Feed Manufacturers:Regional mills in Northeastern provinces blend base mixes with local ingredients to serve emerging commercial zones around Khon Kaen and Udon Thani.
- Backyard Farmers:Small-scale operations in Northern and Southern provinces purchase bagged feed through retail channels with minimal technical support.
- Retailers:Agricultural supply stores and cooperatives distribute branded rations to independent producers with credit terms and delivery logistics.
Commercial farms command procurement volume leadership; feed manufacturers in the Northeast are gaining share fastest.
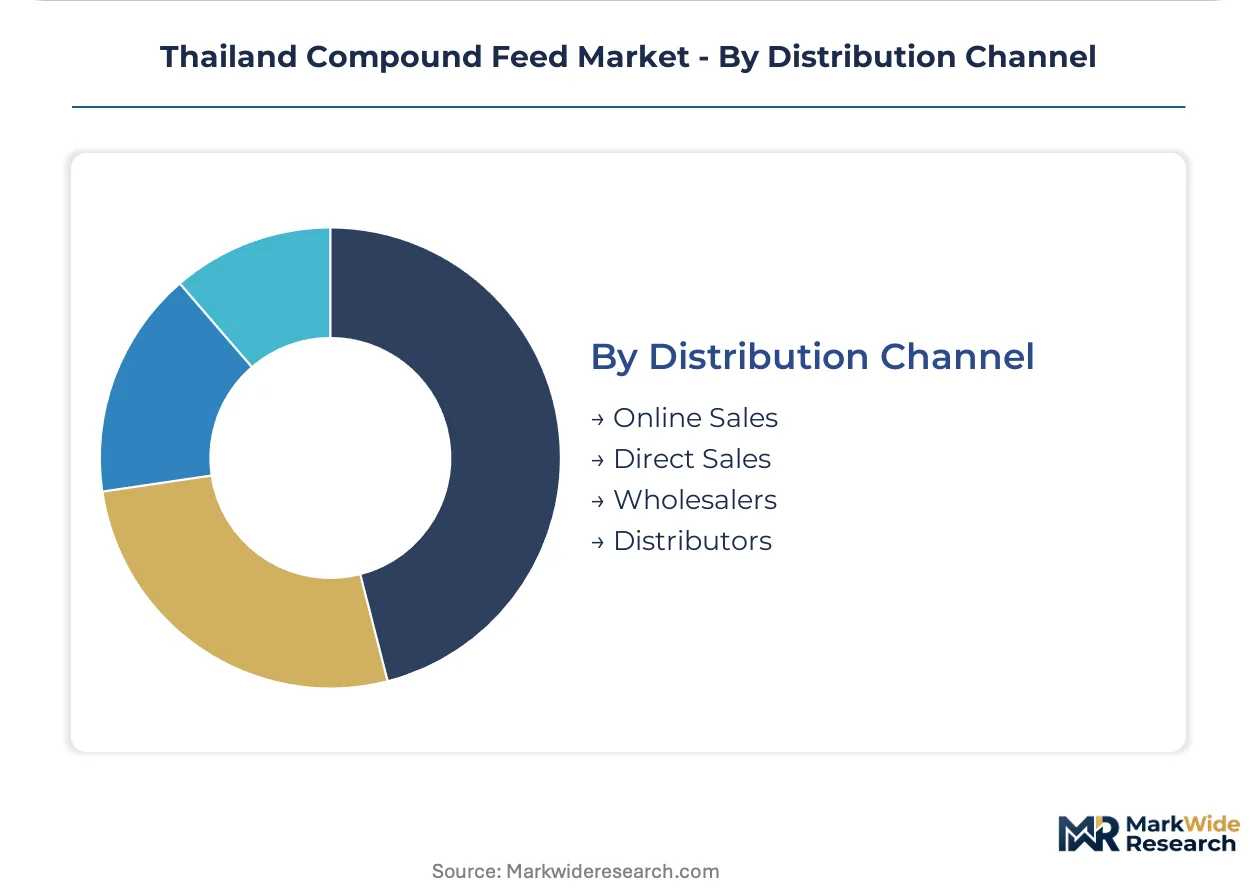
Distribution Channel:
Channel economics favor direct relationships for high-volume accounts, while intermediary networks retain relevance in geographically dispersed markets.
- Direct Sales:Mill-integrator contracts eliminate distributor margins for Central Plains poultry and swine operations with dedicated nutrition teams and bulk receiving infrastructure. Charoen Pokphand Foods and Betagro procurement departments centralize purchasing decisions across captive farming networks.
- Distributors:Regional wholesalers maintain inventory positions in Isaan and Northern provinces where mill density lags behind commercial farm expansion.
- Wholesalers:Aggregators serve independent retailers and smaller commercial operations with mixed-product logistics and credit extension.
- Online Sales:E-commerce platforms emerging in Bangkok metropolitan area offer price transparency and delivery scheduling for time-constrained farm managers.
Direct sales lock in the largest volume commitments; distributor networks in peripheral regions are extending coverage most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial feed demand concentrates heavily in the Central Plains, where Bangkok-centered integrators anchor procurement volume. The Department of Livestock Development enforces uniform standards nationwide, yet milling capacity and farm density vary sharply across sub-regions.
Central Plains
Broiler and swine contract farming dominates absorption in Ratchaburi, Nakhon Pathom, and Ayutthaya provinces. The National Bureau of Agricultural Commodity and Food Standards operates mycotoxin surveillance laboratories in this zone. Charoen Pokphand Foods and Betagro have anchored captive feed demand through vertically integrated operations surrounding Bangkok processing infrastructure.
Eastern Region
Coastal aquaculture intensification in Chonburi and Rayong provinces accelerates specialized aquafeed consumption. Government-backed shrimp export programs align with EU compliance requirements. Samut Sakhon-based extrusion facilities serve intensifying tilapia and vannamei operations targeting Japanese market access.
Northeastern Region
Isaan's emerging commercial pig and poultry zones in Khon Kaen and Udon Thani lack sufficient local milling capacity. The Department of Livestock Development promotes disease-free zone certification for cross-border livestock trade. Regional distributors extend coverage aggressively as contract farming displaces backyard operations.
Northern Region
Chiang Mai and Chiang Rai provinces retain fragmented backyard demand alongside nascent commercial dairy expansion. Provincial agricultural offices coordinate feed quality extension programs. Retail channels dominate distribution where farm scale remains below bulk procurement thresholds.
Southern Region
Surat Thani and Nakhon Si Thammarat concentrate rubber-integrated livestock systems with limited compound feed penetration. Coastal fishmeal production supplements imported protein sources. Port infrastructure constraints elevate logistics costs for soybean meal arriving from Argentine supply chains.
Thailand Compound Feed Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue functional additive specialization and traceability technology convergence. The vendor base compresses toward integrated operations with captive farming networks and regional mills serving dispersed independent accounts. Three archetypes dominate: Bangkok-based multinationals with nutritionist consulting capabilities, coastal specialists in aquafeed extrusion, and Northeastern regional blenders expanding into emerging commercial zones. Competitive moves center on direct mill-integrator contract consolidation and antibiotic-free certification infrastructure investment.
Among Thailand-based integrated operators, Charoen Pokphand Foods PCL exemplifies the captive demand archetype through poultry and swine network control. Betagro Public Company Limited occupies a parallel position in broiler nutrition programs. Cargill, Incorporated represents the multinational technical-services tier with formulation expertise concentrated in Bangkok metropolitan operations.
| Leading Market Players |
|---|
| INTEQC Feed Co. Ltd |
| SPM Feed Mill Company Limited |
| Charoen Pokphand Foods PCL |
| Alltech Inc. |
| Laemthong Corporation Group |
| Betagro Public Company Limited |
| Thai Foods Group Public Company Limited |
| Sun Feed Co. Ltd |
| Cargill, Incorporated |
| Others |
Value Network & Pricing Analysis
Antibiotic-free certification tiers bifurcate Thailand's compound feed market into premium export-contracted rations and commodity domestic grades, with this divergence manifesting in both formulation premiums and procurement concentration patterns. The Department of Livestock Development's pending growth promoter restrictions are compressing margins on conventional formulations while elevating price realization for mills serving EU and Japanese audit-compliant operations.
Pricing Analysis
Volume concentration among Central Plains integrators squeezes per-ton margins on commodity poultry and swine rations, while functional additive premixes capture formulation expertise premiums. Price differentiation hinges on antibiotic-free certification grade and volume scale, with export-contracted farms absorbing technical consulting costs within bulk contracts. Pricing pressure stems from imported soybean meal currency exposure and mycotoxin testing compliance burdens. Backyard operators in Northern and Southern provinces exhibit highest price sensitivity, while commercial integrators prioritize traceability over unit cost.
Supply Chain Analysis
Regional distribution centers in Bangkok metropolitan and Eastern coastal zones anchor hub-and-spoke patterns serving Central Plains contract farms and Samut Sakhon aquafeed extrusion facilities. Thai mills draw from Argentine soybean crush, Peruvian anchovy fishmeal, and domestic corn harvests. Single-source vulnerability concentrates in Peruvian fishmeal supply chains exposed to El Niño harvest disruptions. Distribution runs through direct mill-integrator contracts for high-volume accounts, with regional wholesalers extending coverage into Isaan's emerging commercial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's compound feed sector is consolidating into a vertical-integration race where captive farming networks and in-house additive formulation capabilities determine competitive durability. Players are pursuing upstream control over protein meal sourcing and downstream integration into contract farming operations as the decisive lever.
For Market Incumbents: Deploy captive demand anchoring by deepening direct mill-integrator relationships in Nakhon Pathom and Ayutthaya provinces before Northeastern regional blenders scale. Invest in near-infrared spectroscopy infrastructure to compress batch release cycles and defend position against Bangkok-based multinationals with superior laboratory capabilities. Antibiotic growth promoter phase-out timelines from the Department of Livestock Development threaten conventional formulation cost structures, necessitating accelerated acidifier and probiotic premix partnerships. For New Entrants and Emerging Players: Enter via Isaan's underpenetrated commercial pig and poultry zones around Khon Kaen and Udon Thani, where local milling capacity lags behind contract farming expansion. Target aquafeed extrusion specialization for government-backed shrimp intensification programs in Chanthaburi province, leveraging EU compliance requirements as qualification barrier. Pursue technical service partnerships with emerging integrators lacking in-house nutrition teams as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with regional blenders possessing greenfield site rights in Northeastern provinces given Department of Livestock Development disease-free zone certification momentum for cross-border livestock trade. Long-term viability over a multi-year horizon favors mills with backward integration into functional additive sourcing or forward integration into captive farming networks. Monitor antibiotic-free certification completion rates among export-contracted farms as the inflection signal for formulation premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Antibiotic-Free Certification Infrastructure | Enables EU and Japanese market access for export-contracted broiler and shrimp operations. |
| Backward Integration into Additive Premixes | Captures formulation expertise margins distinct from commodity grain blending competition. |
| Northeastern Regional Milling Capacity | Addresses Isaan's emerging commercial farm demand before incumbent network extension. |
| Near-Infrared Spectroscopy Deployment | Compresses quality assurance cycles from hours to minutes at receiving bays. |
| Aquafeed Extrusion Specialization | Serves government-backed shrimp intensification programs in Samut Sakhon and Chanthaburi. |
Research Methodology
Multi-period observation of feed mill capacity utilization, contract farming expansion rates, and Department of Livestock Development regulatory filing patterns anchored the trend analysis, supplemented by interviews with nutrition directors at integrated poultry and swine operations, procurement leads at regional distributors, plant managers at extrusion facilities, and regulatory affairs specialists at Bangkok-based multinationals. Secondary validation drew from National Bureau of Agricultural Commodity and Food Standards mycotoxin surveillance reports, Department of Livestock Development GMP certification databases, customs import records for soybean meal and fishmeal, and industry association production statistics. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Input-output matrices modeled feed consumption against livestock inventory projections and species-specific feed conversion ratios across the analysis window. Segmentation dimensions included species category, ingredient processing complexity, end-user scale tier, and distribution channel structure. CAGRs were derived from regression analysis of historical consumption patterns adjusted for regulatory transition timelines and commercial farm consolidation trajectories. Forecast inputs incorporated protein meal price volatility indices and aquaculture intensification program targets.
Revisions become necessary when Department of Livestock Development antibiotic restriction timelines accelerate, Peruvian fishmeal harvests collapse due to climatic events, or currency volatility disrupts Argentine soybean meal import economics. Forecasts reflect assumptions regarding contract farming displacement rates and export market access continuity. Periodic stress-testing of base assumptions against regulatory enforcement intensity and integrator procurement centralization trends is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
North America Swine Feed Premix Market
Agriculture and Agri Products
India Compound Feed Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
Philippines Feed Industry Market
Agriculture and Agri Products
Flower Pot Market
Agriculture and Agri Products
Centella Asiatica Market
Agriculture and Agri Products
Guarana Market
Agriculture and Agri Products
US Residential Organic Compost Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
North America Alfalfa Hay Market
Agriculture and Agri Products
Canada Animal Protein Market
Agriculture and Agri Products
Poultry Processing Product Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Algae-Based Animal Feed Market
Agriculture and Agri Products
Global Palm Oil Market