
 Global Sea Air Logistics Market | 2026-2036
Global Sea Air Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sea Air Logistics Market Outlook
A capital-intensity divergence between asset-heavy ocean carriers and asset-light freight forwarders is unwinding competitive dynamics in hybrid logistics. DSV leverages its integrated network to control key Asia-Europe corridors. Kuehne + Nagel anchors its position through digital booking platforms that compress quote-to-cargo timelines. Expeditors specializes in customs brokerage, differentiating on compliance velocity rather than physical fleet scale.
Sea air logistics combines maritime container movement with air freight acceleration, typically cutting pure ocean transit times by 40-60% while maintaining 70-80% cost savings versus exclusive air cargo. Freight forwarding commands the largest service-type revenue pool as shippers outsource route optimization. E-commerce end users represent the fastest-expanding demand segment, driven by inventory velocity requirements and seasonal surge tolerance. Full Container Load shipping methods retain margin superiority on dense, high-value electronics corridors from East Asia.
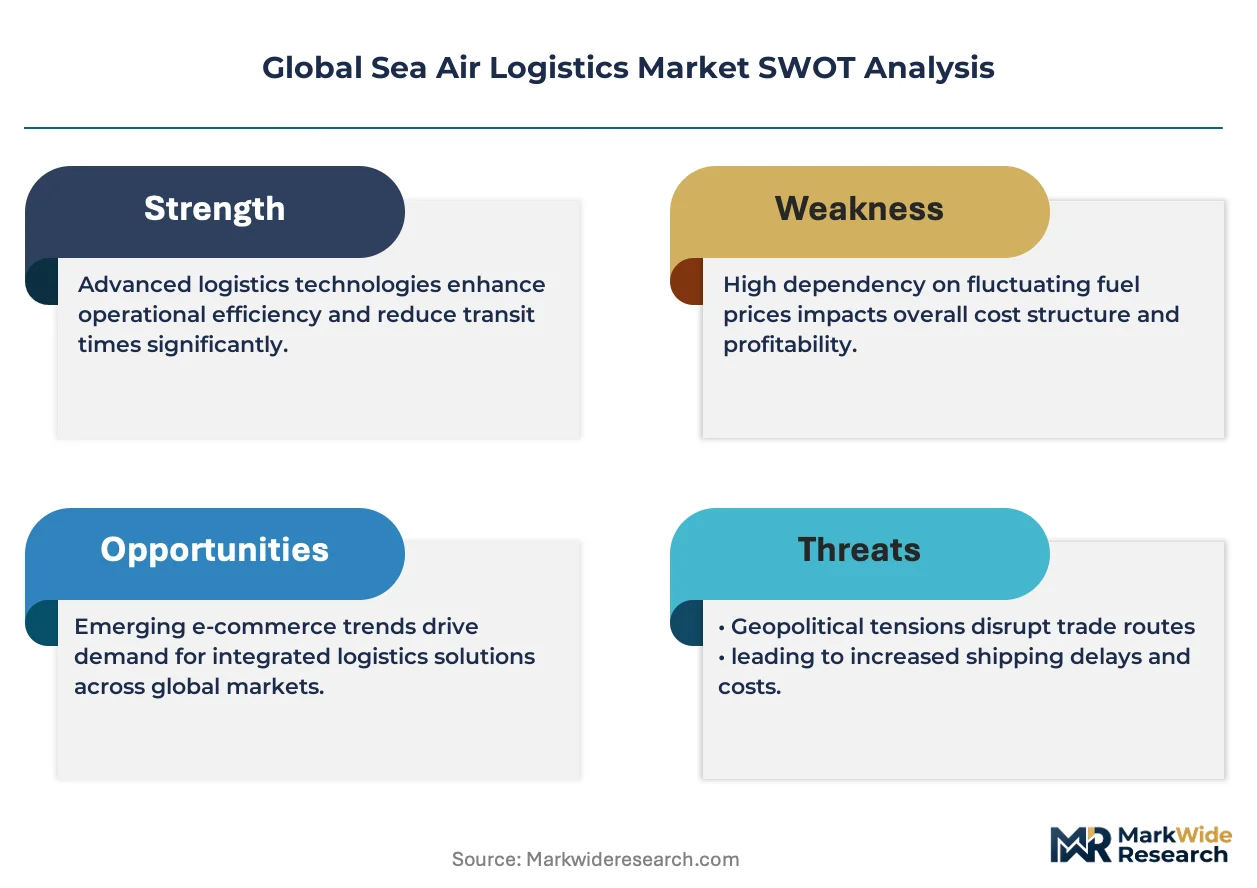
The International Maritime Organization enforces sulfur caps under MARPOL Annex VI, forcing carriers to retrofit scrubbers or switch to low-sulfur fuels. The EU Green Deal extends emissions monitoring to multimodal chains entering European ports. Customs authorities in Dubai and Singapore apply divergent security protocols that shape transshipment hub selection. Stakeholders must monitor regulatory fragmentation across origin, transshipment, and destination jurisdictions to preserve route economics.
Market Dynamics
Carbon border adjustments and sulfur emission mandates are forcing multimodal operators to reconfigure transshipment networks around scrubber-equipped vessels and low-carbon air corridors. This regulatory compression is redrawing route economics between Asia-Pacific manufacturing clusters and European consumption centers.
Growth Catalysts
- E-commerce inventory velocity mandates:Fashion and electronics retailers now require 14-21 day replenishment cycles that pure ocean cannot satisfy. Sea-air bridges this gap.
- EU Green Deal multimodal extension:Emissions monitoring now covers entire logistics chains entering Rotterdam and Hamburg, rewarding operators with verified low-carbon handoffs.
- Middle Eastern gateway expansion:Dubai and Abu Dhabi air cargo capacity additions create alternative routing that bypasses traditional European congestion points.
Market Restraints
- Low-sulfur fuel cost pass-through:MARPOL Annex VI compliance adds bunker adjustment factors that erode the 70-80% cost advantage over pure air freight.
- Transshipment concentration risk:Over 60% of Asia-Europe sea-air volume funnels through Singapore and Dubai, creating single-point vulnerability.
- Modal handoff inflexibility:Container availability mismatches between ocean and air legs force inventory buffering that compresses working capital.
Strategic Opportunities
- Vietnam-to-Europe direct air bridges:Manufacturing diversification from China creates demand for Phnom Penh and Hanoi origin sea-air products.
- Blockchain-enabled documentation:Smart contracts across ocean-air handoffs reduce customs clearance friction and insurance costs.
- India PLI scheme export corridors:Electronics and pharmaceutical production incentives generate high-value cargo suited to sea-air economics.
Industry Challenges
- Intermodal IT integration:Ocean carrier EDI systems rarely interface natively with air cargo booking platforms, requiring expensive middleware development.
- Customs brokerage specialization gaps:Sea-air shipments demand dual expertise in maritime and aviation security protocols that few freight forwarders maintain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sea Air Logistics Market |
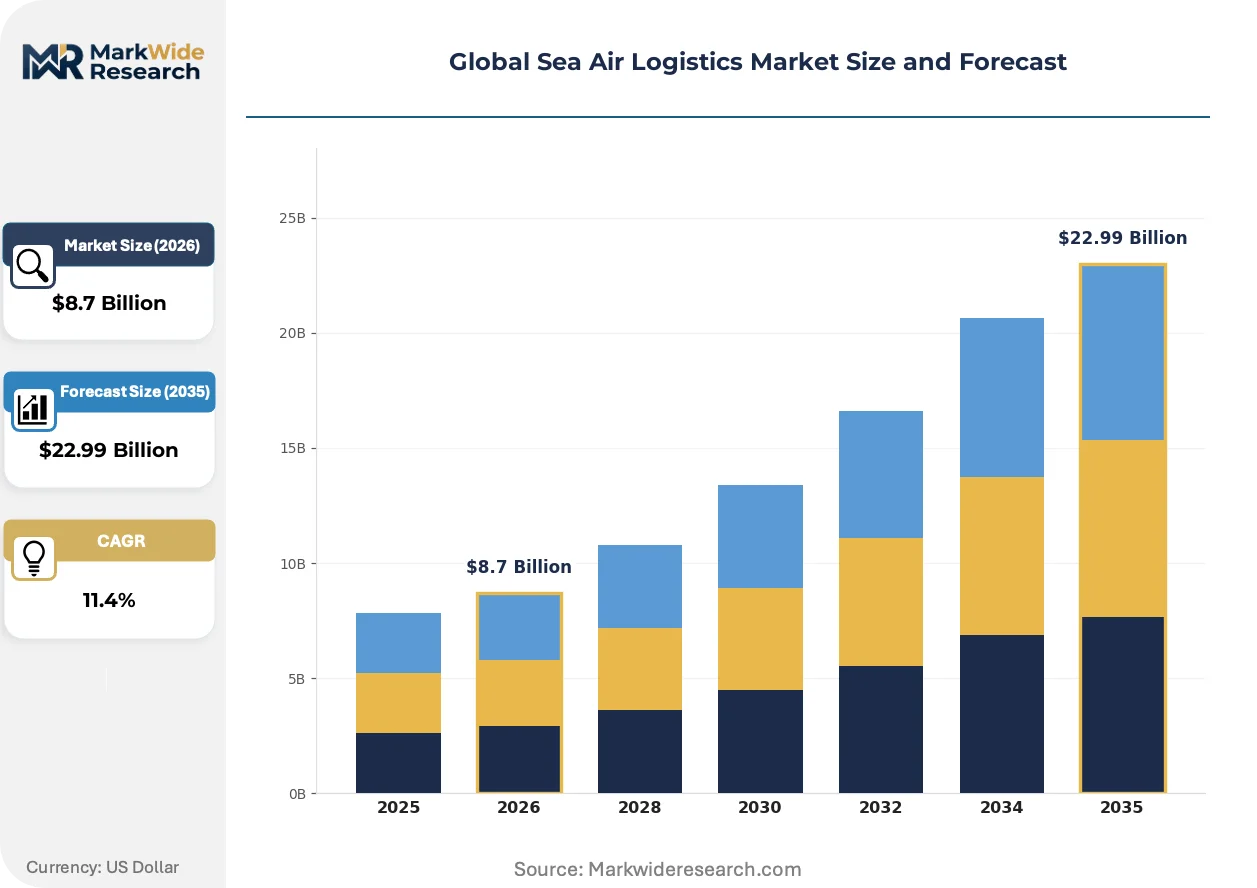
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Freight Forwarding, Customs Brokerage, Warehousing, Distribution End User: Manufacturers, Retailers, Wholesalers, E-commerce Shipping Method: Full Container Load, Less than Container Load, Air Freight, Intermodal Market Segment: Commercial, Industrial, Government, Others |
| Companies Covered | DSV, Kuehne + Nagel, DHL Global Forwarding, C.H. Robinson, Expeditors, Sinotrans, CEVA Logistics, Nippon Express, UPS Supply Chain Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sea Air Logistics Market Strategic Shifts
Digitization is collapsing the information asymmetry that historically separated ocean and air cargo booking. Real-time visibility platforms now enable dynamic mode-switching decisions that were previously impossible.
Sensor-integrated container tracking is miniaturizing. Battery-powered IoT devices now transmit location, temperature, and shock data across both maritime and aviation environments without removal. Pharmaceutical and electronics shippers in Germany and Switzerland are adopting these units at scale. The technology is miniaturizing the acceptable risk window for high-value cargo, allowing insurers to price premiums more granularly.
The EU F-Gas Regulation is tightening refrigerant standards for temperature-controlled containers entering European ports. Reefer operators must retrofit units or face exclusion from Rotterdam and Antwerp. Pharmaceutical and perishable segments are responding by consolidating volumes with carriers that have completed fleet upgrades, narrowing the supplier base.
Shippers are unbundling freight procurement from logistics management. Large retailers now contract directly with ocean carriers for maritime legs while retaining forwarders only for air acceleration and customs clearance. This bifurcation is most advanced in the Netherlands and Belgium, where buying power concentrates among a handful of distribution groups.
Global Sea Air Logistics Market Segmentation
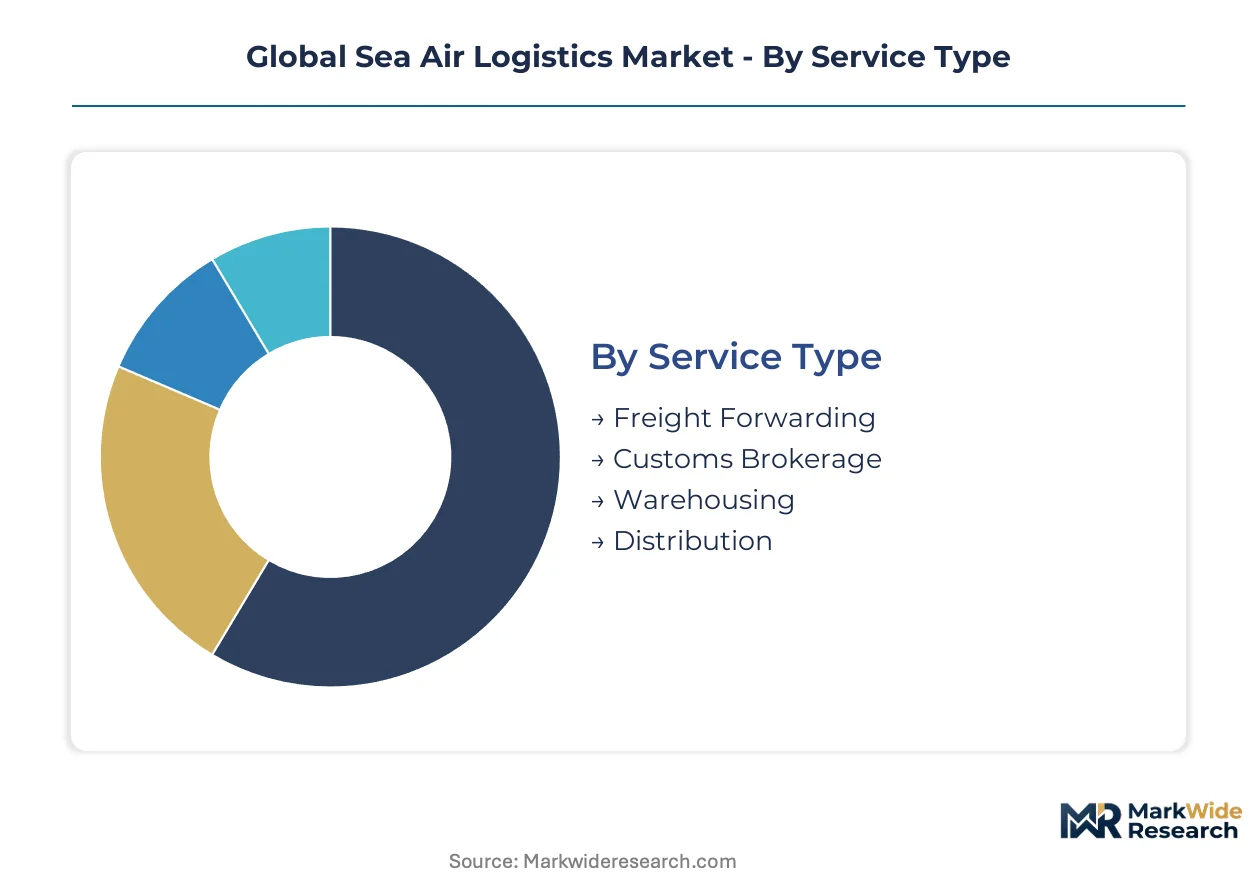
Sea air logistics operators configure service portfolios around modal handoff economics and customer inventory velocity requirements. Segment boundaries blur as freight forwarders bundle customs brokerage with warehousing, and as e-commerce shippers demand integrated distribution rather than point-to-point transport.
Service Type:
Channel mix varies sharply: freight forwarding flows through digital booking platforms, while customs brokerage and warehousing require physical presence at transshipment hubs.
- Freight Forwarding:Route optimization and carrier procurement services that consolidate ocean and air legs under single documentation. Demand concentrates with electronics manufacturers in Vietnam and Thailand seeking 14-21 day Asia-Europe transit. DSV and Kuehne + Nagel capture volume through integrated network control.
- Customs Brokerage:Compliance velocity services spanning maritime and aviation security protocols. Retailers in the Netherlands and Belgium outsource this function to specialists like Expeditors, where dual expertise in Rotterdam port procedures and Schiphol air cargo clearance commands premium pricing.
- Warehousing:Inventory buffering at modal interchange points, typically Dubai, Singapore, or Abu Dhabi. Facilities buffer container availability mismatches between ocean and air legs.
- Distribution:Final-mile injection from air cargo terminals to regional fulfillment centers. E-commerce platforms in Germany and Switzerland drive adoption of sensor-integrated tracking through this channel.
Freight forwarding dominates installed base. Customs brokerage is where expansion concentrates.
End User:
Cost tier stratification separates asset-owning manufacturers from asset-light intermediaries, with margin capture shifting accordingly.
- E-commerce:Inventory velocity mandates from fashion and electronics retailers require seasonal surge tolerance that pure ocean cannot satisfy. This segment climbs the fastest as platforms expand hybrid freight procurement.
- Manufacturers:Dense, high-value electronics producers in East Asia, particularly semiconductor and smartphone assemblers. These shippers retain direct ocean carrier contracts while outsourcing only air acceleration.
- Retailers:Large distribution groups in the Netherlands and Belgium unbundling freight procurement from logistics management, contracting maritime legs directly.
- Wholesalers:Intermediate traders consolidating fragmented cargo for sea-air bundling, particularly in India under PLI scheme export corridors.
Manufacturers dominate installed base. E-commerce is where expansion concentrates.
Shipping Method:
Volume concentration shapes equipment allocation, with dense cargo favoring containerized solutions and time-sensitive shipments requiring breakbulk air handling.
- Full Container Load:Dense, high-value electronics corridors from East Asia retain margin superiority. Semiconductor and automotive component shippers in South Korea and Japan specify FCL for ocean legs to protect against consolidation delays.
- Air Freight:Acceleration segments bridging maritime arrival and final destination, typically 40-60% faster than pure ocean. Pharmaceutical shippers in Switzerland and Germany adopt sensor-integrated containers for this leg.
- Less than Container Load:Fragmented cargo from diversified manufacturing bases, particularly Vietnam and Cambodia as production shifts from China.
- Intermodal:Systematic ocean-air handoffs under single bill of lading, requiring middleware integration between carrier EDI systems.
Full Container Load dominates installed base. Air Freight acceleration segments are where expansion concentrates.
Market Segment:
Maturity differentiation separates established commercial flows from emerging industrial applications and regulated government procurement.
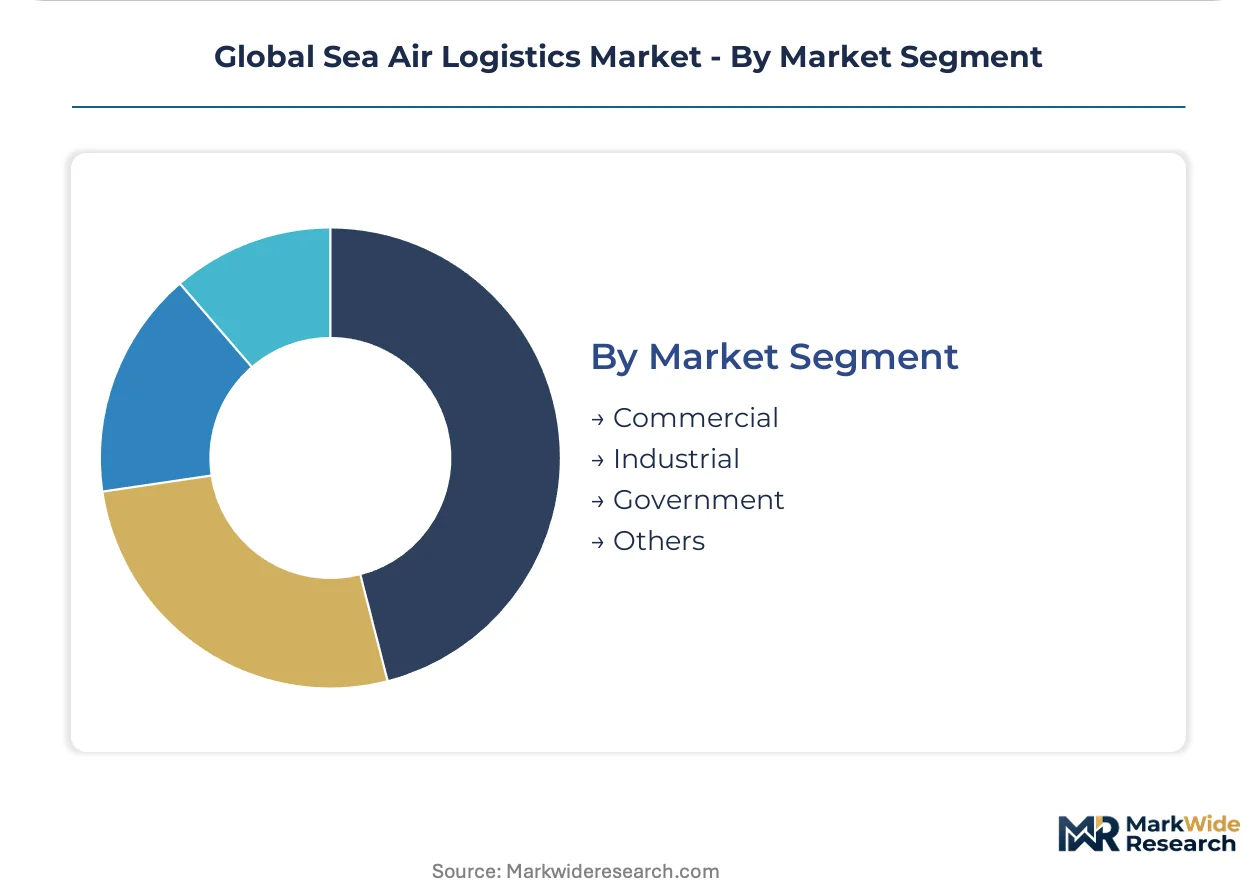
- Commercial:Private-sector logistics spanning retail, electronics, and fashion supply chains. This segment captures the majority of current revenue as EU Green Deal emissions monitoring extends to multimodal chains entering Rotterdam and Hamburg.
- Industrial:Capital equipment and automotive component logistics with longer planning horizons but higher per-shipment value. German and Swiss pharmaceutical exporters are consolidating volumes with scrubber-equipped carriers.
- Government:Defense and humanitarian cargo requiring specialized security clearances and customs protocols. Dubai and Singapore apply divergent security standards that shape hub selection.
- Others:Project cargo and exhibition logistics with irregular frequency but high service requirements.
Commercial dominates installed base. Industrial is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shippers in Germany and Switzerland exhibit the lowest price elasticity, absorbing premium rates for sensor-integrated pharmaceutical cargo, while Vietnamese electronics exporters face acute cost pressure that compresses forwarder margins on Asia-Europe corridors.
United States
Fashion retailers in Los Angeles and New York mandate 14-21 day replenishment cycles that pure ocean cannot satisfy. The Federal Aviation Administration enforces security protocols that shape air cargo screening at West Coast gateways. Electronics distributors in the Pacific Northwest consolidate volumes through Seattle-Tacoma for Asia-origin sea-air products.
Germany
Pharmaceutical exporters in Baden-Württemberg and Bavaria drive demand for temperature-controlled sea-air corridors. The EU F-Gas Regulation tightens refrigerant standards for reefer containers entering Rotterdam and Hamburg. Industrial clusters around Frankfurt and Munich consolidate volumes with scrubber-equipped carriers to maintain EU Green Deal compliance.
China
Semiconductor and smartphone assemblers in the Yangtze River Delta and Pearl River Delta retain direct ocean carrier contracts while outsourcing air acceleration. The Ministry of Ecology and Environment enforces dual carbon goals that pressure multimodal operators to document emissions across supply chains. Manufacturing hubs in Shenzhen and Shanghai deepen integration with Dubai and Singapore transshipment gateways.
United Arab Emirates
Dubai and Abu Dhabi air cargo capacity expansions create alternative routing that bypasses traditional European congestion points. The Ministry of Health and Prevention applies security protocols that diverge from Singapore standards, shaping hub selection for pharmaceutical cargo. Jebel Ali port operators buffer container availability mismatches between ocean and air legs.
Vietnam
Electronics manufacturers in Hanoi and Ho Chi Minh City generate fragmented cargo volumes as production diversifies from China. The Ministry of Industry and Trade administers export incentives under industrial promotion schemes. Manufacturing parks in Bac Ninh and Dong Nai province drive demand for Phnom Penh and Hanoi origin sea-air products.
Global Sea Air Logistics Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in sea air logistics, with integrated network operators commanding premium positioning while asset-light forwarders compete on procurement efficiency. The market structure concentrates around three tiers: global integrators with owned air and ocean assets, regional specialists with hub-specific customs expertise, and digital-native platforms compressing quote-to-cargo timelines. Dominant competitive moves include middleware development bridging ocean carrier EDI with air cargo booking systems, and strategic partnerships with scrubber-equipped vessel operators to secure low-sulfur capacity.
Among European-integrated logistics providers, DSV and Kuehne + Nagel occupy positions exemplifying network control archetypes, while Expeditors represents the compliance velocity specialist tier. DSV leverages integrated Asia-Europe corridor control, Kuehne + Nagel anchors through digital booking platform scale, and Expeditors sits within the customs brokerage differentiation segment where dual maritime-aviation security expertise commands premium positioning.
| Leading Market Players |
|---|
| DSV |
| Kuehne + Nagel |
| DHL Global Forwarding |
| C.H. Robinson |
| Expeditors |
| Sinotrans |
| CEVA Logistics |
| Nippon Express |
| UPS Supply Chain Solutions |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal emissions monitoring gates both carrier qualification and price differentiation simultaneously, as scrubber-equipped vessels and verified low-carbon handoffs command premium positioning while non-compliant operators face Rotterdam and Hamburg port exclusion.
Pricing Analysis
After-sales service contracts and extended customs brokerage engagements drive lifetime value for freight forwarders. Three-tier pricing structure across premium, standard, and economy levels segments by compliance velocity and sensor integration. Price differentiation rests on EU F-Gas reefer certification and blockchain documentation grade. Cost compression in standard-tier Asia-Europe corridors is intensifying because low-sulfur fuel pass-throughs erode the air freight savings advantage. Vietnamese electronics exporters exhibit highest price sensitivity, while Swiss pharmaceutical shippers absorb premium rates for temperature-controlled cargo.
Supply Chain Analysis
Singapore and Dubai transshipment chokepoints underwrite route economics for 60% of Asia-Europe sea-air volume. Supply concentrates in China, South Korea, and Vietnam for electronics manufacturing, with container availability and air cargo slot access as critical inputs. Single-point vulnerability at dual-hub concentration creates systemic risk from port congestion or security protocol divergence. Distribution runs through Dubai and Abu Dhabi for Middle Eastern gateway expansion, with final-mile injection into German and Belgian retail distribution clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual expertise in maritime and aviation security protocols represents a scarce capability that fragments competitive positioning between integrated network operators and specialized customs brokers.
For Market Incumbents: Fortify corridor control through middleware development bridging ocean carrier EDI with air cargo booking systems. Secure scrubber-equipped vessel partnerships to maintain EU Green Deal compliance access. Capacity additions in Vietnam and India production zones defend against manufacturing diversification threats. For New Entrants and Emerging Players: Customs brokerage specialization gaps in dual-protocol compliance present white-space opportunity. Target India PLI scheme export corridors where pharmaceutical and electronics volumes lack seasoned sea-air operators. Digital-native platforms compressing quote-to-cargo timelines offer viable go-to-market positioning against legacy forwarder procurement inefficiency. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light freight forwarding sub-segments as shippers unbundle procurement from logistics management. Long-term viability favors operators with verified low-carbon handoff capabilities and blockchain-enabled documentation infrastructure. Acquisition target archetype: regional specialists with hub-specific customs expertise and sensor-integrated container tracking deployment. Signal to monitor: divergence in Dubai and Singapore security protocol stringency reshaping transshipment hub selection.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Platform Development | EDI integration between ocean and air systems reduces customs clearance friction at Rotterdam and Hamburg. |
| Scrubber-Equipped Vessel Partnership | Low-sulfur fuel compliance secures EU Green Deal access for Asia-Europe corridor economics. |
| Sensor-Integrated Container Deployment | IoT tracking miniaturizes risk windows for Swiss and German pharmaceutical temperature-controlled cargo. |
| Vietnam Corridor Capacity Expansion | Hanoi and Ho Chi Minh City origins capture electronics manufacturing diversification from China. |
| Blockchain Documentation Implementation | Smart contracts across ocean-air handoffs reduce insurance premiums and customs brokerage costs. |
Study Parameters
Initial hypotheses were tested against primary input from freight forwarding operations directors, customs brokerage compliance leads, carrier procurement managers, and e-commerce supply chain planners and refined through secondary validation against IMO MARPOL enforcement records, EU emissions monitoring databases, Dubai and Singapore port authority trade statistics, and SEC filings from listed logistics providers. Bottom-up volume modeling triangulated against top-down corridor capacity assessments.
Variance decomposition across service type, end user, shipping method, and market segment dimensions structured the analytical framework. CAGRs were derived from modal handoff economics and inventory velocity requirement trajectories. Forecast inputs incorporated scrubber retrofit penetration rates and Middle Eastern air cargo capacity expansion schedules.
Underlying assumptions cover sustained EU Green Deal enforcement stringency and MARPOL Annex VI sulfur cap adherence, with deviation risk concentrated in transshipment hub security protocol fragmentation and low-sulfur fuel price volatility. Practitioners should keep alternative scenarios live as F-Gas reefer retrofit timelines and India PLI scheme export incentive extensions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Apparel Logistics Market
Logistics and Shipping
Japan Freight and Logistics Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Freight Management System Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Mexico Freight and Logistics Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
Spain Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Global Air Cargo and Freight Logistics Market