
 Middle East and Africa Lumber Pallet Market | 2026-2036
Middle East and Africa Lumber Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Lumber Pallet Market Foresight
The gap between premium-grade kiln-dried hardwood pallets and commodity softwood units is shifting procurement patterns across the Middle East and Africa. CHEP leverages its pooled pallet network to dominate high-velocity retail channels. Emirates Pallets Factory anchors regional supply through integrated sawmill-to-pallet manufacturing in the UAE. Brambles Limited sustains competitive position via standardized quality protocols across multiple African markets.
Middle East and Africa lumber pallets are wooden platforms constructed from softwood or hardwood lumber, typically measuring 1200mm by 1000mm, assembled through nail-fastened stringer or block designs to enable forklift and racking compatibility in supply chains. They serve as the foundational load-bearing interface between goods and material-handling equipment across warehousing, transportation, and distribution systems. Wood product types retain volume leadership due to lower unit costs and repairability, while plastic alternatives capture premium segments demanding hygiene certification and extended lifecycle performance. Standard-size configurations dominate installed base volumes, though custom dimensions attract margin pools from specialized automotive and electronics end users requiring exact rack-fit specifications.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces ISPM-15 heat treatment mandates for export-bound wooden packaging, directly conditioning manufacturing standards across regional producers. The UAE's Ministry of Climate Change and Environment aligns port-entry inspections with international phytosanitary protocols, shaping compliance costs for importers and domestic fabricators alike. Stakeholders must monitor evolving treatment capacity investments and certification traceability systems as regulatory stringency tightens across key trade corridors.
Market Dynamics
ISPM-15 heat treatment mandates across Middle Eastern and African export corridors are forcing capital retooling at sawmill-to-pallet fabricators, compressing margins for untreated softwood suppliers while creating compliance premiums for certified hardwood producers.
Growth Catalysts
- Cold-chain logistics expansion:Food and beverage distributors across South Africa and the UAE are deploying heat-treated hardwood pallets for temperature-controlled pharmaceutical and fresh produce movements.
- ISPM-15 alignment:The UAE's Ministry of Climate Change and Environment enforces port-entry inspections matching international phytosanitary protocols, driving replacement demand for compliant wooden packaging.
- Jebel Ali logistics clustering:Dubai's free-zone warehousing concentration generates dense pallet pooling opportunities for high-velocity retail and electronics fulfillment.
Market Restraints
- Timber input cost volatility:Southern African pine and eucalyptus supply fluctuations squeeze softwood pallet margins during drought cycles and export log competition from Asian buyers.
- Plastic substitution threat:Hygiene-certified plastic pallets capture pharmaceutical and food processing segments requiring extended lifecycle performance and moisture resistance.
- Treatment capacity concentration:ISPM-15 certified kiln infrastructure clusters in South Africa's coastal manufacturing corridors, leaving inland producers dependent on costly third-party treatment.
Strategic Opportunities
- Saudi Arabia's logistics corridor buildout:The Kingdom's port modernization and bonded warehousing expansion creates greenfield demand for standardized pooled pallet networks.
- Automotive rack-fit customization:Precision-dimensioned block pallets for just-in-time assembly lines at Moroccan and South African vehicle plants command margin premiums over commodity sizes.
- Digital tracking convergence:RFID-embedded hardwood units combining ISPM-15 compliance with real-time inventory visibility attract cold-chain pharmaceutical distributors.
Industry Challenges
- Heat treatment certification timelines:Backlogs at South Africa's Department of Agriculture, Land Reform and Rural Development inspection facilities delay export shipments and strain working capital.
- Repair network fragmentation:Inconsistent quality standards across informal pallet refurbishment operations in Nigeria and Kenya undermine pooled asset reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Lumber Pallet Market |
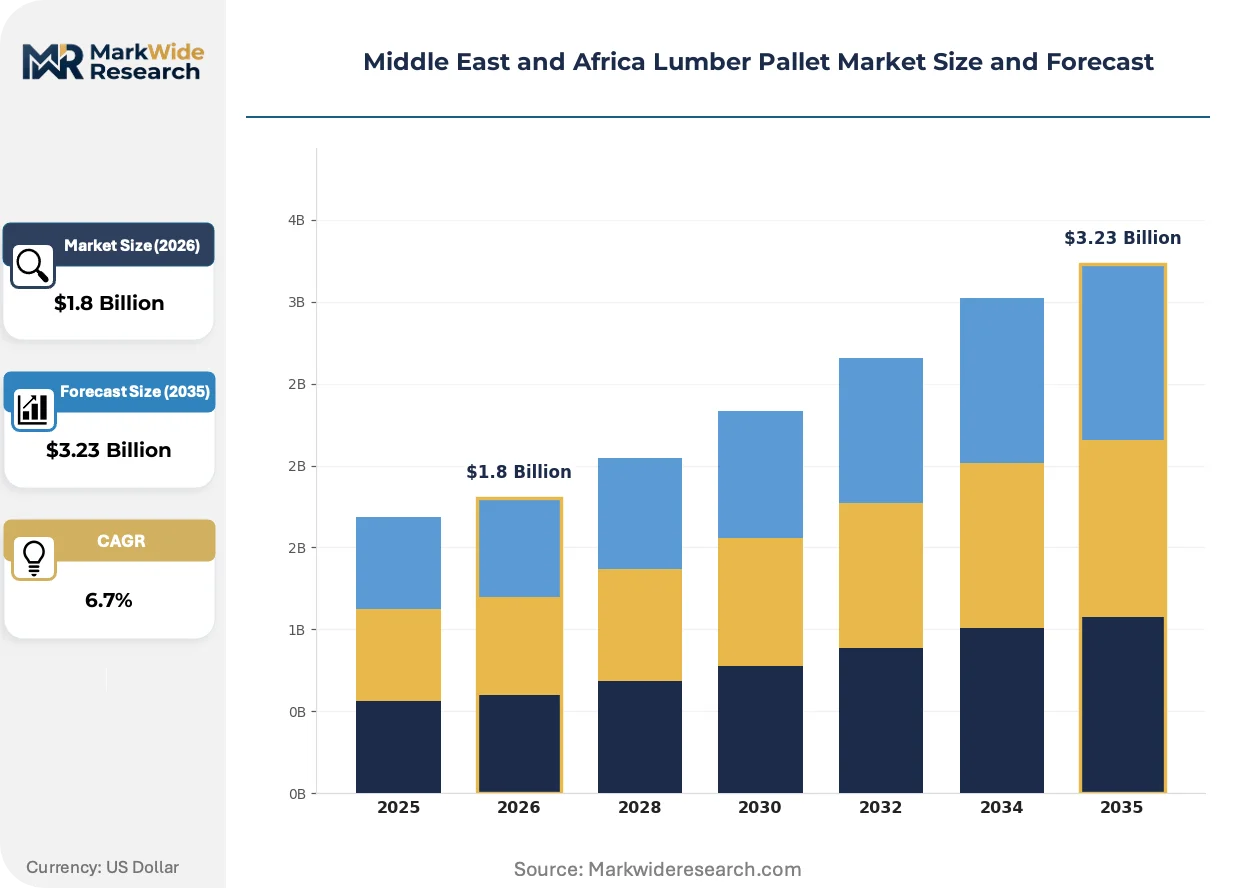
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood, Plastic, Metal, Composite End User: Retail, Food & Beverage, Automotive, Electronics Size: Standard, Custom, Heavy Duty, Foldable Distribution Channel: Direct Sales, Wholesalers, Online, Distributors |
| Companies Covered | PalletOne, Conitex Sonoco, CHEP, Emirates Pallets Factory, Cabka Group, Brambles Limited, Greif, PALLETBIZ, Universal Forest Products, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Lumber Pallet Market Shifts & Advancements
Digital traceability and automated sorting systems are penetrating Middle East and Africa lumber pallet operations, compressing manual inspection labor while raising asset utilization rates for pooled network operators.
Radio-frequency identification tags embedded in hardwood stringers are consolidating pallet-level tracking from warehouse receiving through last-mile delivery. Pharmaceutical distributors in the UAE and South Africa are adopting tagged units fastest, with cold-chain operators requiring temperature-logging integration. This technology is consolidating visibility data previously scattered across paper manifests and handheld scanners into unified fleet management platforms.
South Africa's Department of Agriculture, Land Reform and Rural Development has tightened ISPM-15 heat treatment documentation requirements for export-bound wooden packaging. Treatment facilities must now maintain digital certification traceability systems subject to unannounced audits. Small-scale fabricators in KwaZulu-Natal and Eastern Cape provinces face consolidation pressure as compliance costs rise.
Asset-light leasing models are displacing outright pallet purchases among mid-sized food and beverage distributors. Third-party pooling providers assume treatment, repair, and rotation responsibilities, converting capital expenditure to per-trip operating costs. This shift concentrates most visibly in South Africa's Western Cape wine export corridor and the UAE's retail grocery distribution networks.
Middle East and Africa Lumber Pallet Market Segmentation
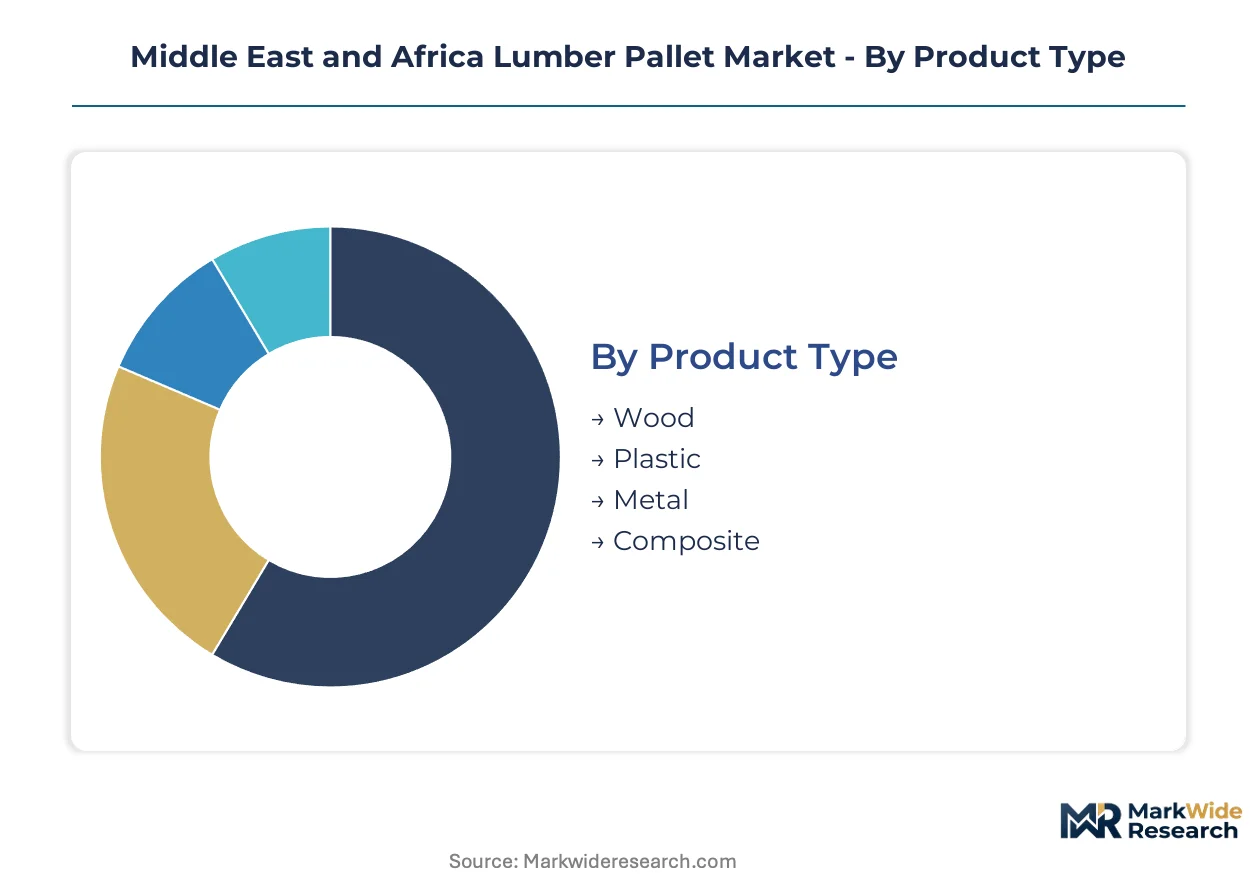
Segmentation in the Middle East and Africa lumber pallet market reveals divergent capital requirements and margin structures across material types, end-use applications, and distribution architectures. Procurement patterns vary sharply between pooled network operators seeking standardized assets and specialized manufacturers serving precision rack-fit requirements.
Product Type:
Capital intensity peaks with heat-treatment infrastructure and kiln-drying capacity, creating divergent barriers to entry across material categories.
- Wood:Softwood stringer and block pallets dominate unit volumes through lower raw material costs and established repair networks. Heat-treated hardwood units command compliance premiums in South Africa's wine export corridor and UAE pharmaceutical cold chains where ISPM-15 certification is mandatory.
- Plastic:Injection-molded HDPE pallets require substantial upfront tooling investment but capture food processing and pharmaceutical segments demanding moisture resistance and extended lifecycle performance. The segment concentrates in UAE dairy and meat processing facilities.
- Metal:Steel and aluminum platforms serve heavy industrial applications with extreme load requirements. Limited regional fabrication capacity constrains adoption outside South African mining and petrochemical installations.
- Composite:Wood-plastic hybrid constructions balance repairability with moisture tolerance. Emerging adoption in Moroccan automotive assembly plants seeking lighter alternatives to pure metal platforms.
Most installed capacity flows through wood. Expansion is steepest in plastic.
End User:
Application-specific performance requirements reshape procurement specifications and replacement cycles across vertical markets.
- Food & Beverage:Temperature-controlled logistics drive demand for heat-treated hardwood and hygiene-certified plastic pallets across South African fresh produce exports and UAE retail grocery distribution. ISPM-15 compliance and cold-chain integrity dominate vendor selection criteria.
- Retail:High-velocity fulfillment networks in Dubai's Jebel Ali free zone favor standardized pooled pallets with RFID tracking capabilities. Turn velocity and asset recovery rates determine total cost of ownership calculations.
- Automotive:Precision block pallets with exact dimensional tolerances serve just-in-time assembly lines at South African and Moroccan vehicle plants. Custom rack-fit specifications command margin premiums over commodity sizes.
- Electronics:Anti-static and contamination-sensitive requirements favor plastic and composite platforms in semiconductor and consumer electronics distribution. Limited regional manufacturing pushes import dependency.
Procurement volumes concentrate in food and beverage. Customization intensity peaks in automotive.
Size:
Dimensional standardization versus specialization creates a bifurcated margin structure across the installed base.
- Standard:1200mm by 1000mm configurations dominate pooled network volumes and interoperability requirements. South African and UAE logistics operators prioritize interchangeability over optimization.
- Custom:Application-specific dimensions attract margin premiums from automotive and electronics end users requiring exact rack-fit specifications. Engineering and tooling costs elevate minimum order quantities.
- Heavy Duty:Reinforced stringer and block designs serve mining equipment and industrial machinery with concentrated load requirements. Limited to South African extractive industries and Gulf petrochemical facilities.
- Foldable:Collapsible designs reduce return freight costs in long-distance distribution. Adoption concentrates in Nigerian and Kenyan import corridors with expensive backhaul economics.
Standard sizes anchor volume throughput. Foldable formats are climbing the fastest in cost-sensitive corridors.
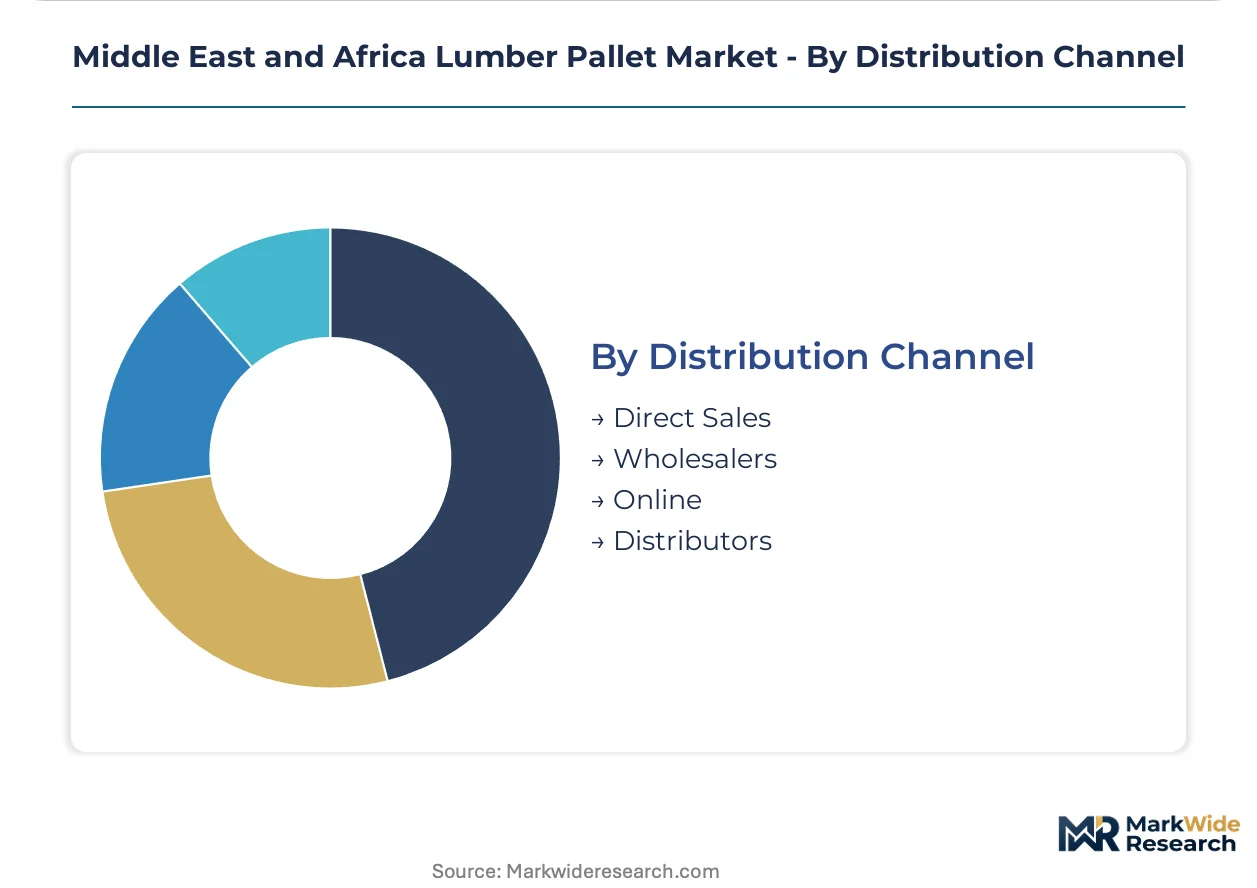
Distribution Channel:
Channel economics reflect customer scale, geographic concentration, and service intensity requirements.
- Direct Sales:Large-volume agreements with pooled network operators and major retailers bypass intermediary margins. Emirates Pallets Factory and comparable integrated manufacturers dominate this channel.
- Wholesalers:Regional stockists serve mid-sized distributors with fragmented demand across multiple SKUs. Inventory carrying costs and credit terms shape competitive positioning.
- Distributors:Specialized logistics providers bundle pallet supply with treatment, repair, and rotation services. Asset-light leasing models displace outright purchases among food and beverage operators.
- Online:Digital procurement platforms emerge for standardized commodity pallets with immediate availability requirements. Limited traction outside South Africa's Western Cape manufacturing corridor.
Direct sales capture the largest contract values. Distributor-led service bundling is gaining share fastest among mid-market accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sawmill-to-pallet fabricators cluster along South Africa's coastal manufacturing corridors and the UAE's Jebel Ali logistics zone, anchoring skilled treatment and assembly workforces across both regions.
South Africa
Wine export logistics and automotive assembly drive hardwood pallet demand in the Western Cape and Eastern Cape provinces. The Department of Agriculture, Land Reform and Rural Development enforces ISPM-15 heat treatment mandates for all export-bound wooden packaging. Durban-Gqeberha manufacturing corridors concentrate certified kiln infrastructure, leaving inland KwaZulu-Natal producers dependent on third-party treatment services.
United Arab Emirates
Pharmaceutical cold-chain distribution and retail grocery fulfillment expand requirements for hygiene-certified pallet platforms. The Ministry of Climate Change and Environment aligns port-entry inspections with international phytosanitary protocols, raising compliance costs for untreated imports. Jebel Ali free-zone warehousing clusters generate dense demand for standardized pooled pallet networks serving high-velocity electronics and FMCG sectors.
Saudi Arabia
Port modernization and bonded warehousing expansion under Vision 2030 create greenfield demand for standardized logistics assets. The Saudi Food and Drug Authority (SFDA) tightens traceability requirements for temperature-sensitive pharmaceutical shipments. King Abdullah Economic City and Jeddah Islamic Port logistics zones attract pooled pallet network operators seeking first-mover positioning in underdeveloped infrastructure corridors.
Morocco
Automotive just-in-time assembly lines at Renault and Stellantis plants command precision-dimensioned block pallets with exact rack-fit tolerances. The country's national standards body enforces quality certification for wooden packaging entering European export channels. Casablanca-Settat and Tangier-Med industrial zones concentrate custom fabrication capacity serving OEM supply chains.
Nigeria
Import corridor economics and expensive backhaul freight drive adoption of collapsible pallet designs reducing return shipment costs. The country's national agricultural regulator enforces phytosanitary treatment for wooden packaging in cross-border West African trade. Lagos-Apapa port complex and Kano manufacturing zones fragment between informal refurbishment operations and emerging standardized pooling ventures.
Middle East and Africa Lumber Pallet Market Competitive Landscape
Top-tier vendors anchor pooled network operations and integrated manufacturing, while mid-scale fabricators compete on treatment certification and regional repair density. Market structure tilts toward asset-heavy operators with captive kiln capacity and standardized quality protocols. Three archetypes dominate: multinational pooling networks with RFID-tracked fleets, sawmill-integrated regional manufacturers, and specialized custom fabricators serving automotive rack-fit specifications. Competitive moves concentrate on treatment capacity expansion and digital tracking integration.
Within the multinational pooling tier, CHEP and Brambles Limited represent asset-heavy network operators with standardized quality protocols across multiple African markets. Emirates Pallets Factory anchors regional supply through integrated sawmill-to-pallet manufacturing in the UAE. Among specialty fabricators, PalletOne and Universal Forest Products exemplify North American-origin operators with scale advantages in hardwood treatment and export certification.
| Leading Market Players |
|---|
| PalletOne |
| Conitex Sonoco |
| CHEP |
| Emirates Pallets Factory |
| Cabka Group |
| Brambles Limited |
| Greif |
| PALLETBIZ |
| Universal Forest Products |
| Others |
Supply & Pricing Matrix
ISPM-15 heat treatment mandates across South Africa and the UAE are forcing procurement departments to specify certified hardwood pallets over untreated softwood alternatives, compelling suppliers to absorb kiln infrastructure costs or forfeit cross-border contracts. This specification tightening concentrates purchasing power among pooled network operators while fragmenting spot-market pricing for commodity units.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across the Middle East and Africa lumber pallet market. Asset-light leasing models bundle treatment, repair, and rotation into per-trip fees, commanding premium positioning against transactional spot purchases. Price differentiation rests on ISPM-15 certification grade and RFID tracking integration, with pharmaceutical cold-chain operators least sensitive to unit cost. Cost compression in softwood stringer segments is intensifying because untreated suppliers face exclusion from export corridors.
Supply Chain Analysis
Warehouse-distribution layer concentration in Dubai's Jebel Ali free zone and South Africa's Durban-Gqeberha corridor anchors regional pallet pooling economics. Manufacturing draws from Southern African pine plantations, UAE softwood imports, and Moroccan hardwood feedstocks. Supply chain risk centers on treatment capacity concentration at coastal kilns, leaving inland producers tethered to third-party logistics. Distribution runs through bonded warehousing clusters serving high-velocity retail and automotive fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
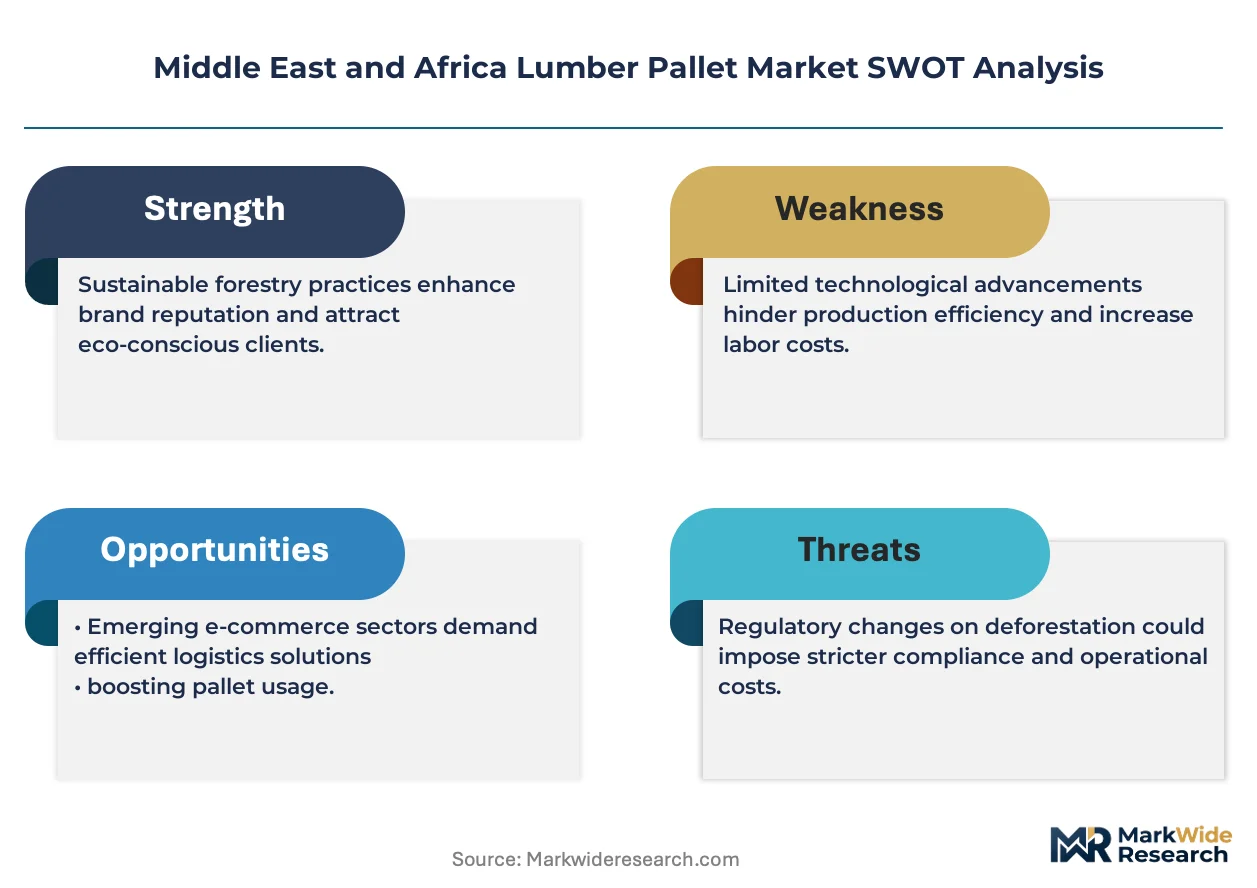
The Middle East and Africa lumber pallet market represents a late-cycle quality story as pharmaceutical and food export specifications harden around heat-treated hardwood with digital traceability. Procurement departments now mandate ISPM-15 certification and RFID integration as baseline requirements.
For Market Incumbents: To counter plastic substitution in hygiene-sensitive segments, expand captive kiln capacity in Saudi Arabia's King Abdullah Economic City and integrate RFID tagging at the point of manufacture. Certification depth and real-time asset visibility are the defensive moats. For New Entrants and Emerging Players: Capture collapsible pallet demand in Nigeria's Lagos-Apapa import corridor where expensive backhaul economics favor space-efficient return logistics. Target mid-sized food distributors with asset-light leasing models that convert capital expenditure to operating costs. For Investors and Strategic Acquirers: Asymmetric upside sits with sawmill-integrated regional manufacturers possessing untreated-to-certified hardwood flexibility across multiple African markets. Long-term viability hinges on treatment capacity ownership rather than pooled fleet scale. Watch Saudi port modernization timelines as the inflection signal for greenfield logistics asset demand.| Strategic Initiative | Industry Significance |
|---|---|
| ISPM-15 Kiln Capacity Expansion | Captures compliance premiums as South Africa's Department of Agriculture tightens export documentation requirements. |
| RFID-Enabled Asset Tracking Integration | Consolidates pharmaceutical distributor relationships requiring temperature-logging and real-time inventory visibility. |
| Backward Integration into Sawmill Operations | Secures hardwood feedstock access amid Southern African pine supply volatility and Asian export competition. |
| Collapsible Pallet Design Introduction | Addresses Nigerian and Kenyan import corridors with expensive backhaul freight economics. |
| Pooled Network Partnership with Retail Grocers | Locks in high-velocity turnover contracts across UAE's Jebel Ali logistics clustering. |
Research Methodology
Multiple input streams — pallet fabricator production data, pooled network operator fleet statistics, and customs trade records — were reconciled against primary interviews with sawmill procurement directors, logistics warehouse managers, ISPM-15 certification auditors, and pharmaceutical supply chain executives. Secondary validation drew from South African Department of Agriculture enforcement bulletins, UAE Ministry of Climate Change and Environment port inspection reports, and timber industry association capacity surveys. Bottom-up unit economics and top-down sectoral demand estimates were triangulated to anchor volume and value projections.
Cross-referencing historical treatment capacity buildout patterns against panel input from kiln operators and certification bodies shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material type, end-use vertical, dimensional specification, and distribution channel architecture. CAGRs were derived from demand elasticity coefficients applied to trade corridor growth assumptions, with cold-chain logistics expansion and automotive assembly output serving as industry-specific forecast inputs.
Timber input cost volatility, ISPM-15 regulatory enforcement timing, and plastic pallet substitution velocity are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding treatment capacity expansion schedules and pooled network penetration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Global Wood Pallet Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Pallet Corner Boards Market