
 Europe Poultry Meat Market | 2026-2036
Europe Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Poultry Meat Market Insights
The EU Green Deal is expanding sustainability requirements across livestock value chains, compelling processors to document carbon intensity and water stewardship. MHP leverages its integrated grain-to-meat operations in Ukraine and southeastern Europe to control feed costs and traceability. LDC sustains competitive positioning through specialized duck and guinea fowl production that commands premium positioning in French retail channels. Plukon Food Group anchors volume leadership in the Netherlands and Belgium through automated deboning technology that reduces labor dependency.
Europe poultry meat encompasses chicken, turkey, duck, and other avian species raised for human consumption, typically processed to moisture content below 75 percent and distributed under chilled, frozen, or fresh classifications. The product serves as a primary protein source for retail consumers, food service operators, and further processors seeking lower-cost, faster-cooking alternatives to red meat. Whole chicken and chicken parts dominate volume flows through supermarkets and wholesalers, where price transparency and promotional cycling compress margins for undifferentiated offerings. Frozen and chilled processing types capture divergent margin pools, with chilled commanding premium shelf placement in German and UK retail while frozen sustains institutional food service contracts across southern Europe.
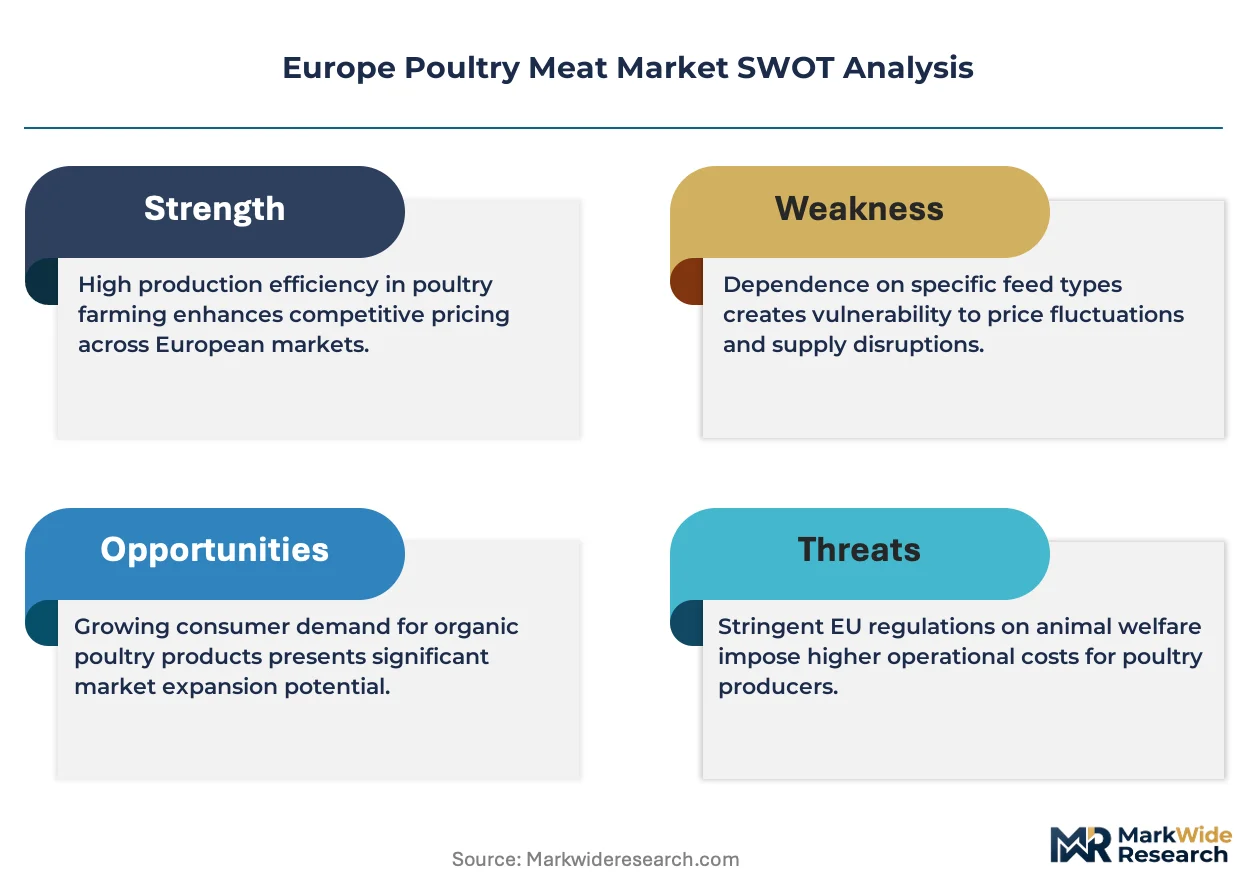
The European Food Safety Authority enforces microbiological standards for campylobacter and salmonella that dictate slaughterhouse operating protocols and compliance costs. REACH and the EU F-Gas Regulation constrain refrigerant choices in cold chain infrastructure, elevating capital requirements for processors maintaining temperature integrity from abattoir to retail. Stakeholders must monitor how the EU AI Act and pending digital product passport mandates reshape traceability investments and data-sharing obligations across integrated supply networks.
Market Dynamics
The EU Green Deal is compressing operational margins across European poultry supply chains while simultaneously rewarding processors that document carbon intensity and water stewardship from feed sourcing through retail distribution.
Growth Catalysts
- EU Green Deal compliance mandates:Processors investing in traceability infrastructure capture preferential shelf placement in German and French retail channels where environmental documentation now gates procurement decisions.
- Food service operator consolidation:Large-scale catering contracts across institutional buyers in Poland and the Netherlands favor suppliers with verified low-carbon footprints and automated deboning capacity.
- Chilled distribution network expansion:Cold chain infrastructure upgrades in southeastern Europe unlock premium positioning for temperature-controlled poultry products previously constrained by logistics gaps.
Market Restraints
- Feed grain price volatility:Ukrainian grain supply disruptions elevate input costs for processors without captive feed milling operations or long-term origination contracts.
- Slaughterhouse concentration in Poland:Over half of European deboning capacity sits within a 200-kilometer corridor, creating single-point vulnerability for continental supply security.
- REACH refrigerant constraints:The EU F-Gas Regulation limits hydrofluorocarbon options for cold chain equipment, forcing capital-intensive retrofits of existing chilling and freezing infrastructure.
Strategic Opportunities
- Romanian and Bulgarian retail modernization:Supermarket format expansion in these markets creates first-mover advantage for chilled poultry brands with EU-compliant traceability systems.
- Digital product passport readiness:Early alignment with pending EU digital product passport requirements positions integrated processors to capture data-sharing premiums from retail partners.
- Halal certification arbitrage:Dual slaughter line investments serving domestic European and export Middle Eastern markets extract margin premiums from specialized religious compliance infrastructure.
Industry Challenges
- Microbiological compliance talent scarcity:EFSA campylobacter and salmonella testing protocols require specialized laboratory personnel that processors in eastern Europe struggle to recruit and retain.
- Legacy ERP integration with traceability platforms:Mid-scale processors face multi-year system migration timelines to achieve real-time data capture demanded by EU AI Act supply chain transparency provisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Poultry Meat Market |
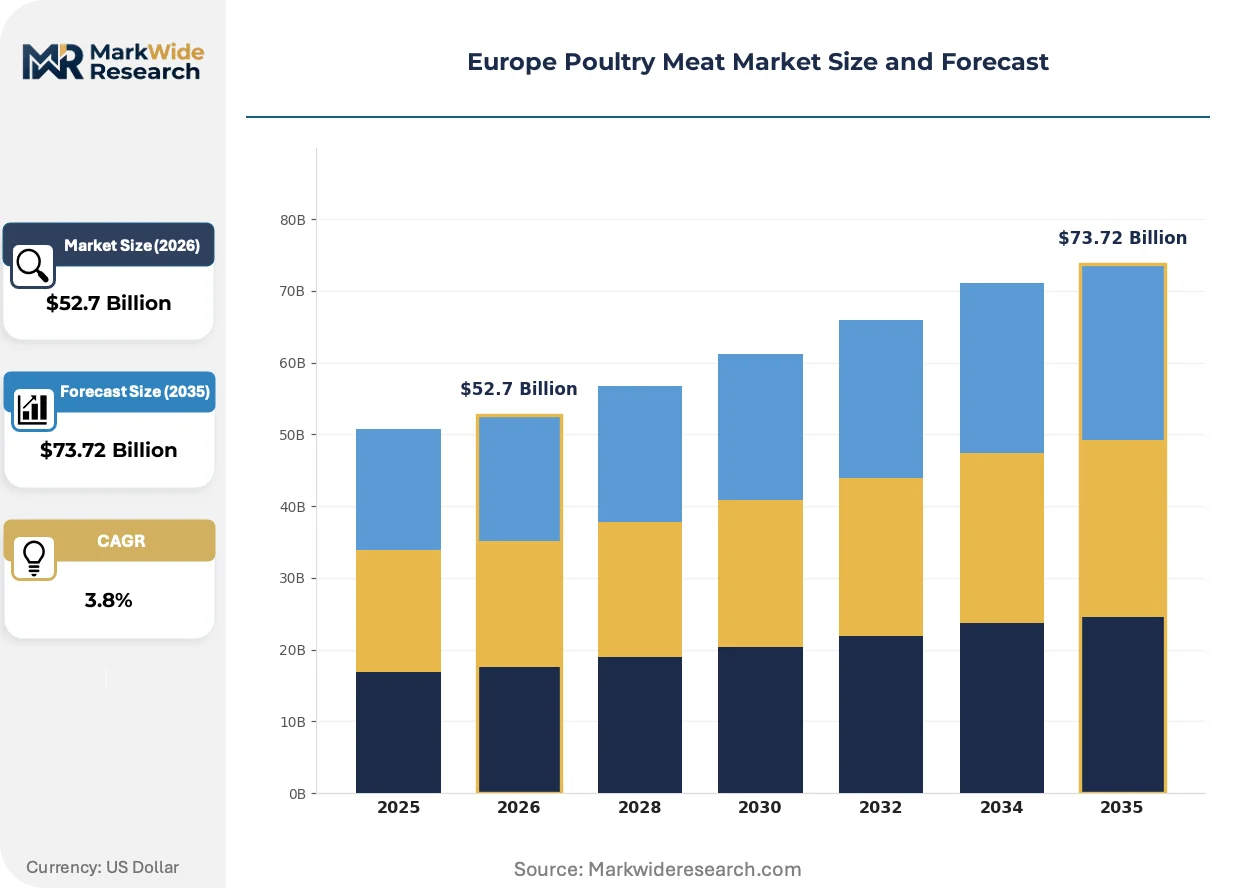
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $73.72 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chicken, Chicken Parts, Turkey, Duck Distribution Channel: Supermarkets, Online Retail, Wholesalers, Convenience Stores End User: Retail Consumers, Food Service, Restaurants, Processors Processing Type: Fresh, Frozen, Chilled, Processed |
| Companies Covered | MHP, LDC, Plukon Food Group, Moy Park, 2 Sisters Food Group, Gruppo Veronesi, PHW-Gruppe, Cedrob, Amadori, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Poultry Meat Market Trends and Innovations
Automation, regulatory data architecture, and shifting protein procurement priorities are restructuring how poultry moves from slaughterhouse to consumer plate across European markets.
Computer vision-guided robotic deboning is converging with predictive maintenance algorithms to transform labor economics in high-volume processing facilities. Dutch and Belgian operators are deploying these systems fastest, replacing manual knife work with precision cutting tools that reduce yield loss. The technology is converging with workforce constraints to accelerate adoption timelines previously stretched across decade-long investment cycles.
The EU AI Act is imposing algorithmic transparency requirements on supply chain forecasting tools used by major poultry distributors. Processors must now document how automated ordering systems weight variables from weather patterns to promotional calendars. French retail cooperatives are responding by demanding third-party audits of supplier AI systems before contract renewal.
Contract structures for food service procurement are compressing from annual to quarterly terms as operators seek flexibility against input cost swings. Institutional buyers in German healthcare and education sectors are abandoning fixed-price agreements in favor of indexed contracts tied to grain futures. This behavioral shift is most visible in Rhineland industrial canteen networks where procurement directors now prioritize price elasticity over supply security.
Europe Poultry Meat Market Segmentation
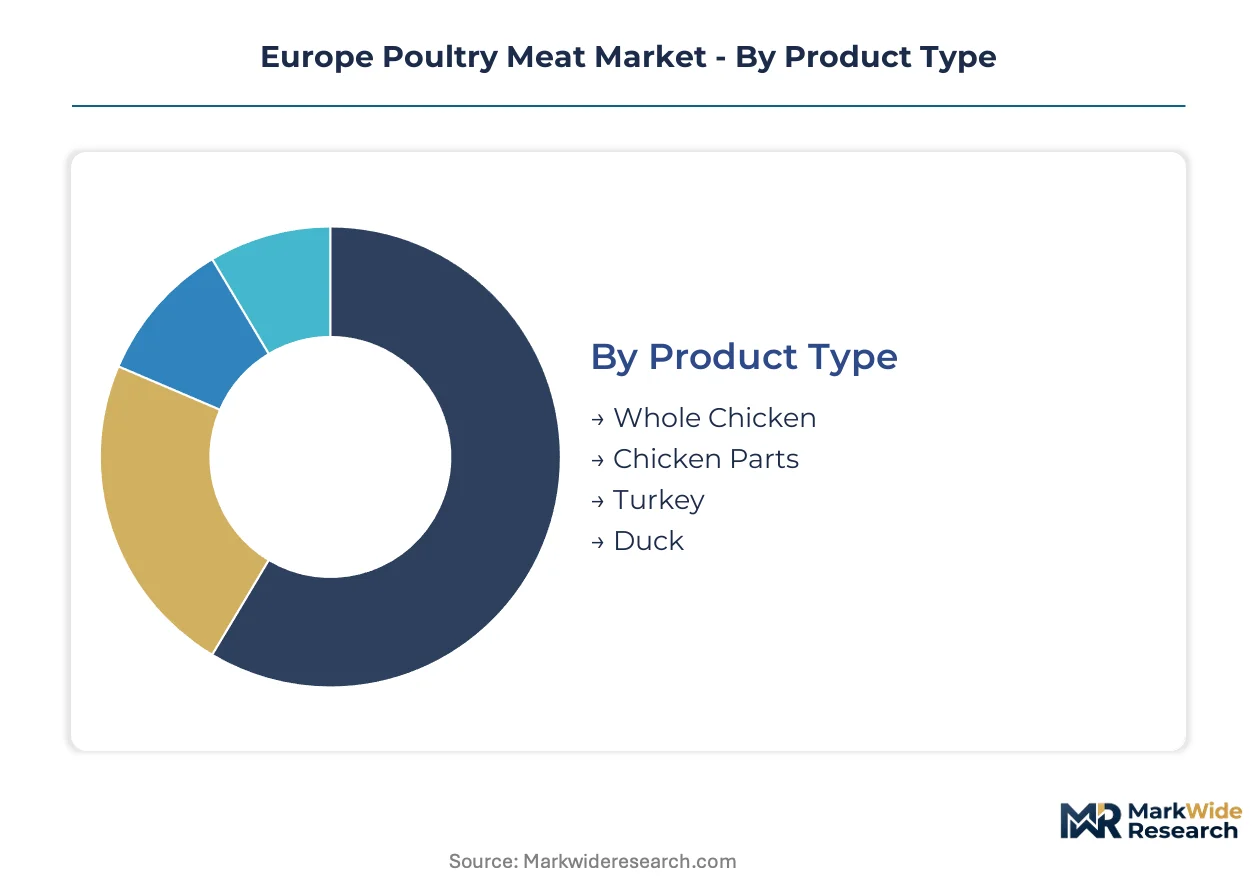
Supply concentration across Poland's processing corridor and the Netherlands' automated facilities shapes how each segment captures margin. Differentiation in temperature control, channel access, and end-use specifications determines which product formats secure shelf placement under tightening EU Green Deal compliance.
Product Type:
Whole chicken and chicken parts concentrate slaughterhouse throughput in Poland and the Netherlands, where deboning automation and cold chain density create cost advantages over peripheral production zones.
- Whole Chicken:Carcass sales dominate volume flows through German and French retail, where promotional cycling and price transparency compress margins. EFSA campylobacter testing protocols elevate compliance costs for slaughterhouses serving this undifferentiated segment.
- Chicken Parts:Deboned thighs, wings, and breast portions command premium positioning in UK and Dutch supermarkets where convenience-oriented consumers trade up from whole bird purchases. Automated cutting lines in Belgian and Dutch facilities reduce labor dependency and yield loss compared to manual processing.
- Turkey:Seasonal demand concentration in German and UK Christmas procurement cycles creates volume spikes that strain slaughterhouse scheduling.
- Duck:French retail channels sustain specialized production through LDC's integrated operations serving premium positioning.
Today's leader: Chicken Parts. Tomorrow's challenger: Duck.
Distribution Channel:
Channel selection determines temperature protocol requirements and traceability documentation burdens under REACH refrigerant constraints and pending digital product passport mandates.
- Supermarkets:Chilled poultry shelf placement in German and French retail gates procurement through verified carbon intensity documentation. Promotional cycling and private label concentration compress supplier margins while demanding real-time inventory data sharing.
- Wholesalers:Frozen bulk distribution serves institutional food service contracts across southern Europe where logistics gaps previously constrained temperature-controlled delivery. REACH F-Gas Regulation compliance elevates cold chain capital requirements for operators serving this channel.
- Online Retail:Last-mile temperature integrity challenges limit chilled poultry penetration to frozen and processed formats in most European markets.
- Convenience Stores:Grab-and-go processed chicken products target urban commuter demand in UK and Benelux cities with limited fresh preparation capacity.
Supermarkets currently anchor value capture. Online retail presents the steepest expansion trajectory as cold chain infrastructure matures.
End User:
End-use specifications diverge sharply between retail consumers seeking convenience and food service operators optimizing protein cost per serving.
- Food Service:Large-scale catering contracts across Polish and Dutch institutional buyers favor suppliers with automated deboning capacity and verified low-carbon footprints. Quarterly contract indexing to grain futures replaces annual fixed-price agreements as procurement directors prioritize flexibility.
- Retail Consumers:German and UK supermarket shoppers drive chilled poultry demand where price transparency and promotional sensitivity limit brand loyalty.
- Restaurants:Quick-service and casual dining operators in France and Spain source chicken parts through specialized wholesalers serving halal certification requirements.
- Processors:Further processing into nuggets, sausages, and ready meals concentrates in Belgium and the Netherlands where formulation expertise and scale economies dominate.
Food service commands procurement volume leadership. Processors are gaining share fastest as convenience-oriented product innovation accelerates.
Processing Type:
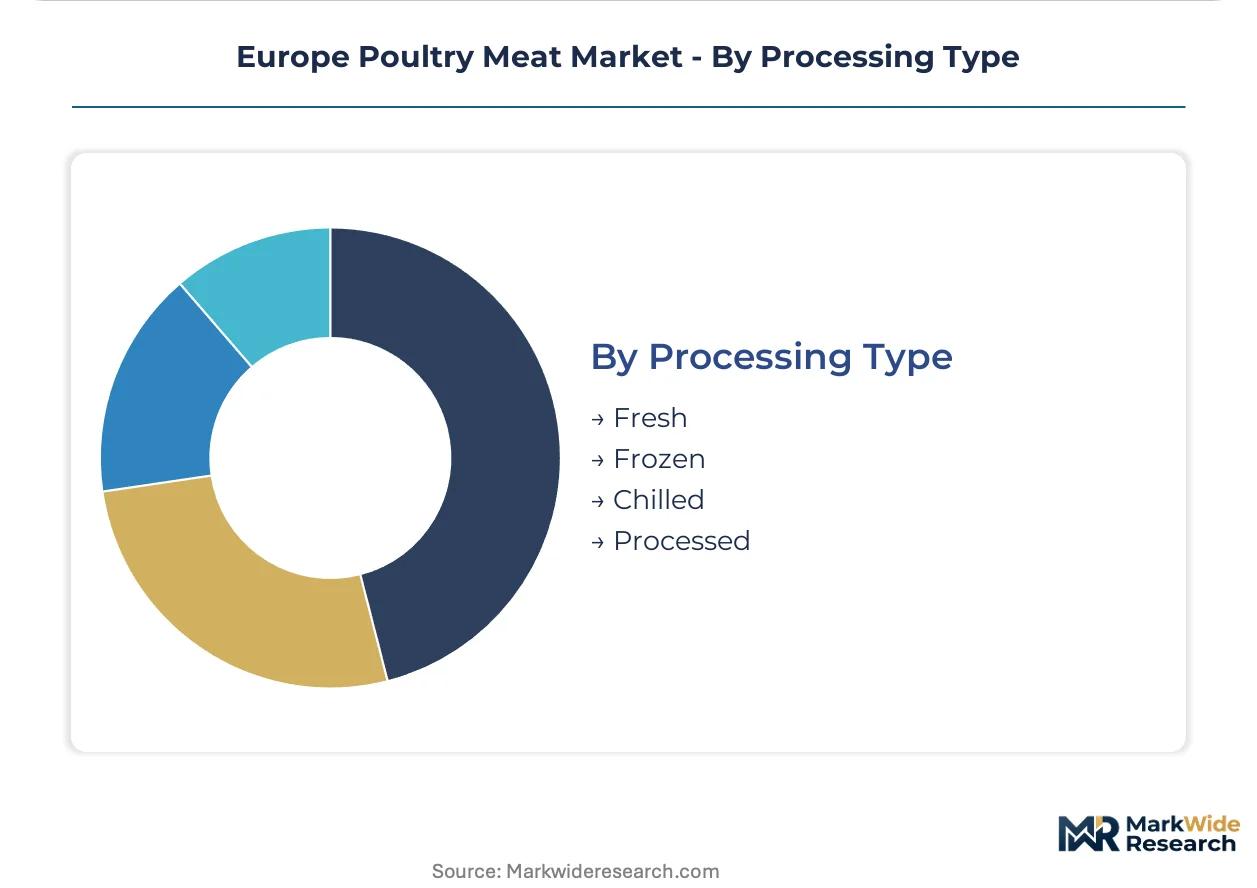
Temperature classification dictates shelf life, logistics infrastructure, and margin capture potential across divergent European cold chain maturity levels.
- Chilled:Temperature-controlled distribution between 0°C and 4°C secures premium shelf placement in German and UK retail where consumers trade freshness assurance against shorter shelf life. Cold chain infrastructure upgrades in southeastern Europe unlock new addressable market expansion.
- Frozen:Blast freezing at -18°C sustains institutional food service contracts and export flows to Middle Eastern markets where halal certification arbitrage extracts margin premiums.
- Fresh:Same-day slaughter-to-retail distribution in France and Italy serves traditional consumer preferences with minimal processing intervention.
- Processed:Marinated, breaded, and ready-to-cook formats target convenience demand in UK and Benelux urban markets.
Chilled holds margin leadership. Processed formats present the most aggressive expansion path as convenience demand reshapes meal preparation habits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's vertically integrated processing corridor concentrates skilled deboning technicians and cold chain logistics specialists who anchor continental supply security. Workforce density in this corridor outmatches peripheral European production zones.
Germany
Food service operators in Rhineland industrial canteen networks are scaling poultry procurement as institutional buyers prioritize verified low-carbon footprints. The EU Green Deal tightens environmental compliance documentation requirements across livestock supply chains. Automated deboning facilities in Lower Saxony and North Rhine-Westphalia capture preferential shelf placement through carbon intensity traceability systems.
France
French retail cooperatives demand third-party audits of supplier AI systems before contract renewal under EU AI Act algorithmic transparency mandates. EFSA campylobacter testing protocols elevate compliance costs for slaughterhouses serving supermarket promotional cycles. LDC's integrated operations in western France sustain specialized duck and guinea fowl production commanding premium positioning.
Netherlands
Computer vision-guided robotic deboning converges with predictive maintenance algorithms across Dutch processing facilities to transform labor economics. REACH and the EU F-Gas Regulation constrain refrigerant choices in cold chain infrastructure, elevating capital requirements. Plukon Food Group anchors volume leadership through automated technology that reduces labor dependency in Belgian and Dutch facilities.
Poland
Over half of European deboning capacity sits within a 200-kilometer corridor creating single-point vulnerability for continental supply security. Ukrainian grain supply disruptions elevate input costs for processors without captive feed milling operations. Capacity investments in this vertically integrated processing corridor outpace other European production zones.
United Kingdom
UK supermarket shoppers drive chilled poultry demand where price transparency and promotional sensitivity limit brand loyalty. Quarterly contract indexing to grain futures replaces annual fixed-price agreements as procurement directors prioritize flexibility. Convenience-oriented consumers in London and southeast England trade up from whole bird purchases to deboned portions.
Europe Poultry Meat Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across tiered competitive positions. The vendor base separates between integrated grain-to-meat operators controlling upstream feed costs and specialized processors focusing on premium species or automated technology deployment. Three archetypes dominate: vertically integrated agro-industrial conglomerates with captive feed milling, automated technology leaders in deboning and cold chain logistics, and specialized premium species producers serving differentiated retail channels. Competitive intensity manifests through capacity expansion in Poland's processing corridor and strategic partnerships securing preferential shelf placement under EU Green Deal procurement gating.
Within the integrated agro-industrial tier, MHP leverages Ukrainian and southeastern European operations to control feed costs and traceability. Among specialized premium producers, LDC occupies a position exemplifying French retail channel concentration in duck and guinea fowl. At the automated technology vector, Plukon Food Group represents volume leadership in the Netherlands and Belgium through labor-reducing deboning systems. These three anchors illustrate how geographic positioning and capability specialization stratify competitive returns under tightening EU compliance frameworks.
| Leading Market Players |
|---|
| MHP |
| LDC |
| Plukon Food Group |
| Moy Park |
| 2 Sisters Food Group |
| Gruppo Veronesi |
| PHW-Gruppe |
| Cedrob |
| Amadori |
| Others |
Pricing and Supply Chain Analysis
Food service operators in Rhineland industrial canteen networks and Polish institutional catering chains anchor pricing power through volume consolidation and quarterly contract indexing. Their procurement concentration shifts supplier margins toward grain-futures-linked agreements and away from fixed-price annual terms.
Pricing Analysis
Three-tier pricing structure across premium chilled, standard frozen, and economy fresh levels governs European poultry transactions. Premium positioning draws from EU Green Deal carbon intensity documentation and halal certification compliance, while economy tiers compete on feed cost efficiency in Polish integrated corridors. Cost compression in standard frozen segments is intensifying because Ukrainian grain supply disruptions elevate input costs for processors without captive milling operations. Food service operators exhibit highest price sensitivity through indexed contracts, whereas French retail cooperatives trading up to LDC's duck and guinea fowl show lowest elasticity.
Supply Chain Analysis
Ukrainian grain supply rests on Black Sea corridor stability and southeastern European origination networks for feed cost control. Polish, Dutch, and Belgian processing facilities concentrate deboning capacity and automated cutting technology deployment. Single-source vulnerability concentrates in Poland's 200-kilometer processing corridor where over half of European capacity sits. Distribution runs through German and French retail cooperatives for chilled products and southern European wholesalers for frozen bulk institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal functions as a regulatory compounder, with digital product passport mandates and carbon intensity documentation requirements driving sustained investment in traceability infrastructure across integrated supply chains.
For Market Incumbents: Cement preferential shelf placement in German and French retail by accelerating EU AI Act compliance for algorithmic transparency in automated ordering systems. Expand captive feed milling capacity in southeastern Europe to offset Ukrainian grain supply volatility. Prioritize cold chain infrastructure retrofits under REACH F-Gas Regulation constraints before compliance deadlines tighten.
For New Entrants and Emerging Players: EU Green Deal procurement gating in German and French retail channels opens a window for chilled poultry brands with pre-built traceability systems. Target Romanian and Bulgarian supermarket format expansion where cold chain infrastructure gaps previously blocked temperature-controlled distribution. Enter through halal certification arbitrage serving dual domestic European and Middle Eastern export markets.
For Investors and Strategic Acquirers: Integrated agro-industrial conglomerates with captive feed milling and automated deboning technology are the most active acquirer in this space. Long-term viability centers on processors controlling upstream grain origination and downstream retail data-sharing relationships. Watch EFSA campylobacter testing protocol enforcement as an inflection indicator for compliance cost escalation and slaughterhouse consolidation pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Deboning Technology Deployment | Computer vision-guided systems in Dutch and Belgian facilities reduce labor dependency and yield loss. |
| Captive Feed Milling Expansion | Upstream grain control in Ukraine and southeastern Europe insulates processors from input cost volatility. |
| Digital Product Passport Readiness | Early EU compliance alignment captures data-sharing premiums from German and French retail cooperatives. |
| Halal Certification Infrastructure | Dual slaughter line investments extract margin premiums from Middle Eastern export markets. |
| Cold Chain F-Gas Retrofit | REACH refrigerant compliance in Polish and Dutch facilities secures temperature integrity from abattoir to retail. |
Research Methodology
Bottom-up food service and retail channel modeling reconciled against top-down slaughterhouse capacity and feed grain supply tracking forms the analytical core of this study. Primary interviews with procurement directors at German institutional catering networks, French retail cooperative category managers, Polish processing facility operations heads, and Dutch automated technology engineers combined with secondary validation from EFSA compliance filings, EU Green Deal regulatory texts, REACH F-Gas Regulation implementation guidance, and customs trade data for Ukrainian grain flows. Triangulation between demand-side contract structures and supply-side capacity investments anchors forecast precision.
Input-output matrices map feed grain costs through processing yields to end-use pricing across product type, distribution channel, end user, and processing type dimensions. CAGRs derive from segment-level volume trajectories weighted by price evolution assumptions across the projection horizon. Industry-specific forecast inputs include EFSA microbiological testing compliance cost curves and EU AI Act algorithmic transparency implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Ukrainian grain supply disruption or accelerated EU digital product passport enforcement. Forecasts reflect documented assumptions regarding cold chain infrastructure investment rates and food service operator contract structure evolution. A small set of named triggers warrants ongoing watch: EFSA campylobacter protocol stringency, REACH F-Gas retrofit capital availability, and EU AI Act third-party audit requirements for supplier algorithmic systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Bacon Slicers Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
India Poultry Meat Market
Meat Products
North America Red Meat Market
Meat Products
China Processed Meat Market
Meat Products
Beef Bouillon Market
Meat Products
Organic Lamb Market
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
Meat Products Market
Meat Products
Reduced Fat Meat Market
Meat Products
Hams Market
Meat Products
Pork Belly Meat Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Western Europe Ready-To-Eat Meat Market