
 South America Indoor LED Lighting Market | 2026-2036
South America Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
South America Indoor LED Lighting Market Insights
Electrical distributor networks across South America is rewriting how LED luminaires reach end users, with traditional wholesale channels losing ground to direct contractor relationships and digital procurement platforms. Signify leverages its established Brazilian manufacturing footprint to sustain pricing flexibility against import-dependent rivals. OSRAM GmbH anchors its regional position through specialized automotive-to-lighting technology transfer that differentiates its driver electronics portfolio.
South America Indoor LED Lighting comprises solid-state illumination systems engineered with semiconductor-based emitters typically operating at correlated color temperatures between 2700K and 6500K, designed for enclosed interior environments requiring controlled luminous efficacy above 80 lumens per watt. Panel lights dominate commercial retrofit volumes due to their compatibility with suspended ceiling grids prevalent in aging office stock across São Paulo and Santiago. Smart lighting technology captures the fastest expansion trajectory as Brazilian and Colombian facility managers prioritize connected systems for energy compliance reporting, though standard LED bulbs still occupy the largest installed base among residential homeowners.
INMETRO, Brazil's national metrology institute, mandates efficiency labeling that filters substandard imports while Argentina's IRAM standards and Chile's SEC certifications create layered compliance requirements for manufacturers serving multiple Andean markets. These regulatory frameworks collectively push suppliers toward higher-performance product architectures that meet the strictest national threshold rather than maintaining country-specific SKUs. Stakeholders must monitor how Mercosur harmonization negotiations reshape certification reciprocity and whether local content requirements emerge as Brazil advances its domestic manufacturing incentives.
Market Dynamics
Retrofit cycles in São Paulo and Buenos Aires commercial towers are compressing replacement timelines from seven years to under four, driven by INMETRO efficiency mandates and rising electricity tariffs that make payback periods attractive for building operators.
Growth Catalysts
- INMETRO efficiency labeling:Brazil's mandatory luminaire certification filters substandard imports and elevates baseline product quality thresholds across the regional supply base.
- Smart lighting convergence:Connected systems integrating occupancy sensing and daylight harvesting are capturing facility manager attention as energy compliance reporting requirements tighten.
- Southeastern industrial corridor:Demand concentrates visibly across São Paulo, Minas Gerais, and Rio de Janeiro states where manufacturing and logistics facilities drive panel light volumes.
Market Restraints
- Import-dependent supply chains:Driver electronics and semiconductor components flow primarily from Asian manufacturing hubs, exposing distributors to currency volatility and extended lead times.
- Layered certification costs:Argentina's IRAM standards and Chile's SEC requirements force manufacturers to maintain parallel testing regimes for Andean market access.
- Fluorescent residual stock:Aging T8 and T5 installations in public buildings and budget-constrained residential sectors delay full LED conversion.
Strategic Opportunities
- Colombian facility modernization:Bogotá and Medellín commercial stock lags São Paulo retrofit penetration by approximately half, presenting untapped specification potential for connected systems.
- Mercosur harmonization:Pending reciprocity negotiations for certification mutual recognition could collapse multi-country compliance costs for pan-regional suppliers.
- Digital procurement platforms:Contractor-direct purchasing through specialized B2B marketplaces is displacing traditional electrical distributor markups in Brazilian metropolitan markets.
Industry Challenges
- Legacy control protocol fragmentation:DALI, 0-10V, and proprietary wireless standards create integration complexity for smart lighting deployments in mixed-vendor environments.
- Certification timeline compression:INMETRO testing queue backlogs extend product launch windows by four to six months for new market entrants.
- Technical workforce scarcity:Qualified commissioning engineers for networked lighting control systems remain concentrated in São Paulo and Santiago, constraining rollout velocity elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Indoor LED Lighting Market |
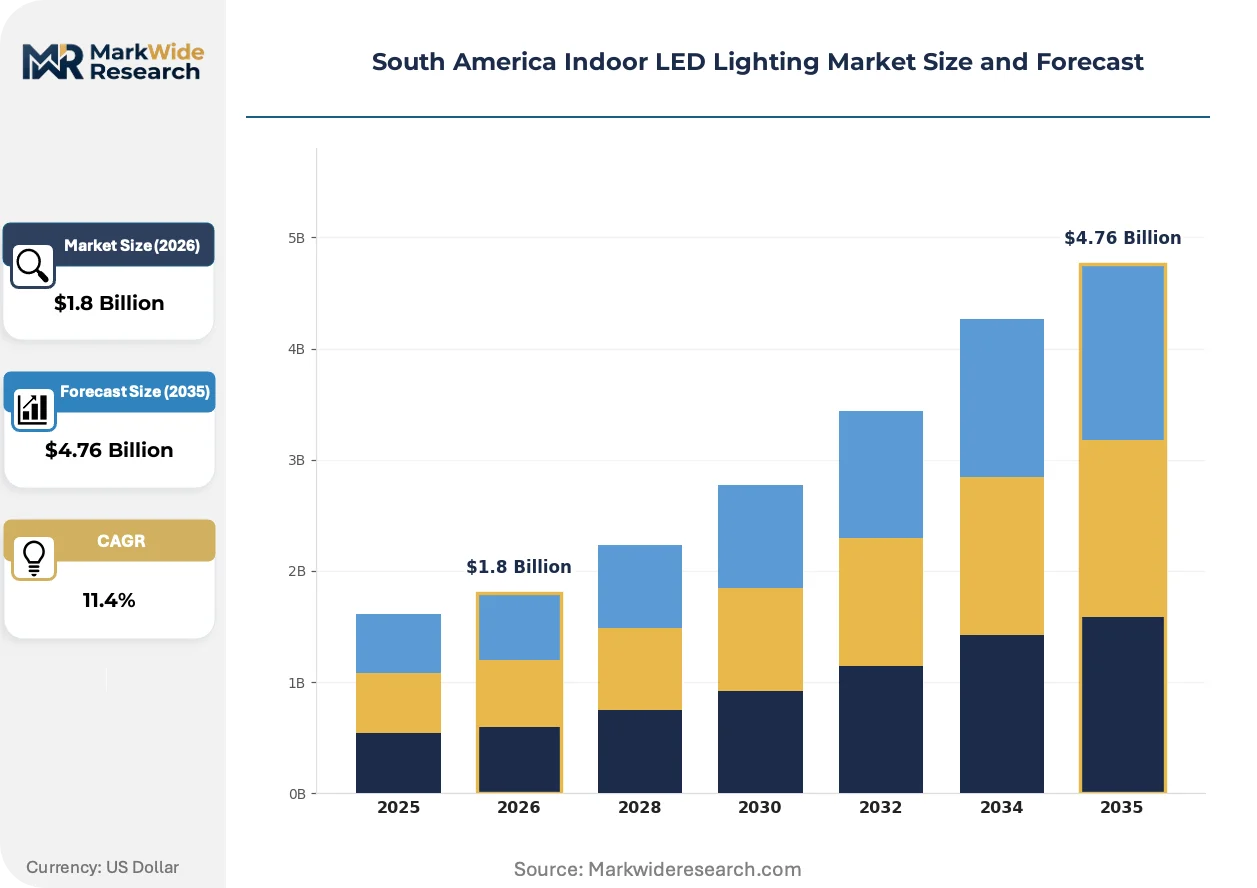
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Lights, Downlights, Bulbs, High Bay Lights Application: Residential, Commercial, Hospitality, Industrial Technology: Smart Lighting, Dimmable, RGB, Standard End User: Contractors, Retailers, Developers, Homeowners |
| Companies Covered | Signify, OSRAM GmbH, Acuity Brands Inc, Cree LED, LEDVANCE GmbH, OPPLE Lighting Co Ltd, EGLO Leuchten GmbH, NVC International Holdings Limited, Thorn Lighting Ltd, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Indoor LED Lighting Market Trends and Innovations
Connected lighting infrastructure is digitizing how buildings manage energy, shifting competitive advantage from lumen output to data architecture and software integration capabilities.
Human-centric lighting systems using tunable white LED arrays and circadian rhythm algorithms are digitizing workplace wellness specifications. Corporate real estate managers in São Paulo financial districts specify these systems for talent retention and productivity claims. The technology is compressing traditional fixture procurement into bundled service contracts where hardware margins subsidize software subscriptions.
INMETRO's 2024 efficiency tier upgrades for luminaires are tightening import gates and forcing architectural revisions to driver electronics and thermal management. Domestic Brazilian manufacturers with captive testing laboratories capture six-month speed-to-market advantages over import-dependent rivals. Panel light and downlight categories face the steepest compliance cost escalations given their volume exposure.
Electrical contractor purchasing collectives in Buenos Aires and Santiago are consolidating specification authority that distributors once held. These buying groups negotiate direct manufacturer relationships and bypass traditional wholesale tiers entirely. The disintermediation is most visible in commercial retrofit projects above five hundred fixture units where contractor margins exceed distributor value-add.
South America Indoor LED Lighting Market Segmentation
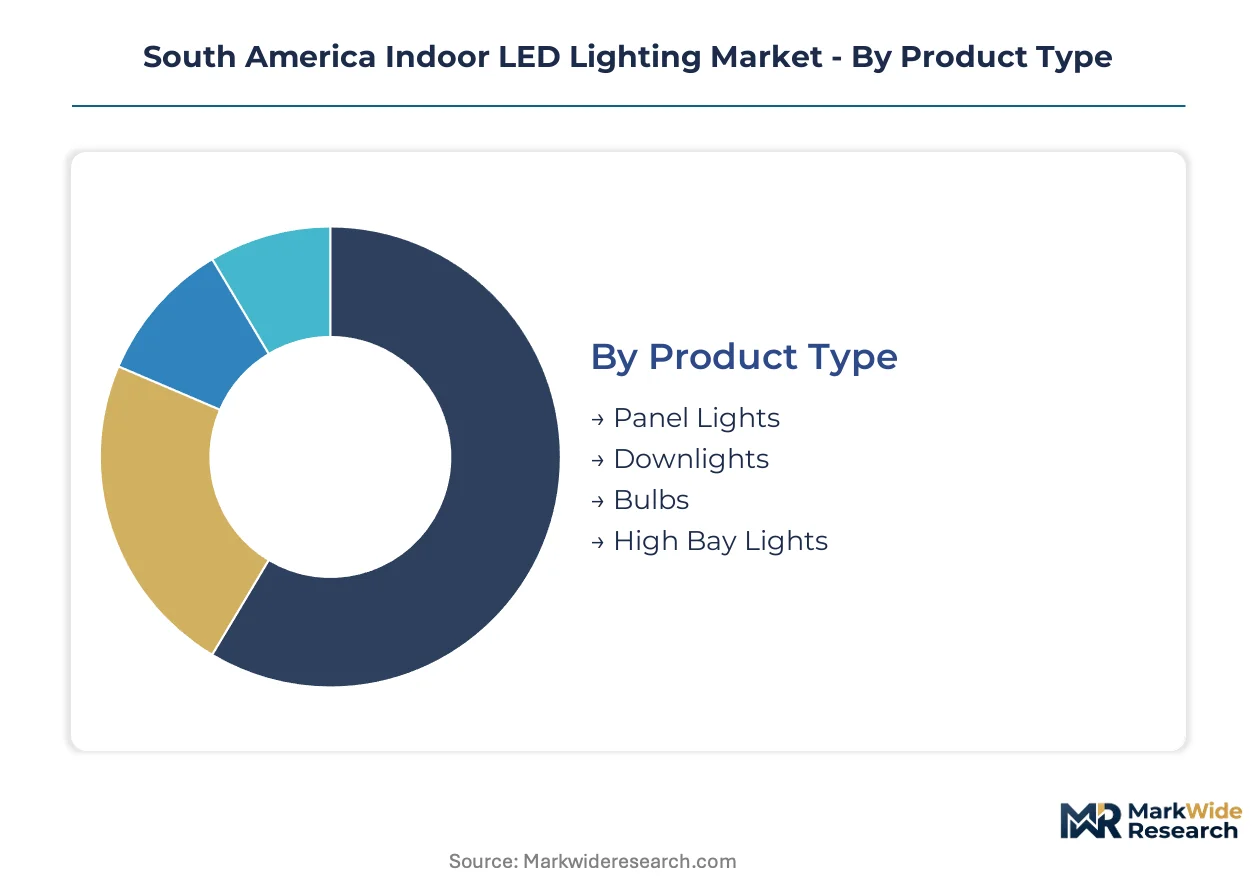
South America Indoor LED Lighting Market segmentation reveals how fixture specifications, procurement channels, and control architectures diverge across building types and buyer sophistication levels. Understanding these divides illuminates where specification authority concentrates and which technology tiers command premium positioning.
Product Type:
Use-case spectrum spans suspended ceiling retrofits in aging commercial stock through high-ceiling manufacturing facilities requiring specialized thermal management.
- Panel Lights:Edge-lit and back-lit flat panel configurations dominate suspended ceiling grid replacements across São Paulo and Santiago office towers. INMETRO efficiency mandates accelerate fixture replacement cycles in buildings where T8 fluorescent tubes still occupy ceiling infrastructure.
- Downlights:Recessed and surface-mounted circular fixtures concentrate in hospitality lobbies and retail environments where beam angle control and glare suppression drive specification. Buenos Aires hotel renovation pipelines favor COB LED downlights with 90+ CRI for lobby and corridor applications.
- Bulbs:Retrofit lamps for existing sockets maintain the largest residential installed base across Brazilian and Argentine households where fixture replacement lags behind lamp substitution economics.
- High Bay Lights:Industrial-grade fixtures with specialized heat sinking serve manufacturing and logistics facilities across São Paulo state's industrial corridor where mounting heights exceed six meters.
Established volume favors bulbs; emerging adoption favors panel lights.
Application:
Cost tier separation distinguishes premium-specified commercial environments from price-sensitive residential retrofit decisions.
- Commercial:Office towers and retail complexes in São Paulo and Buenos Aires drive specification-grade fixture procurement with connected control requirements. Facility managers prioritize luminaires with embedded occupancy sensing and daylight harvesting for energy compliance reporting.
- Industrial:Manufacturing plants and distribution centers across Minas Gerais and Rio de Janeiro states demand high-lumen output fixtures with IP65+ ingress protection. Procurement concentrates through contractor-direct relationships bypassing traditional distributor markups.
- Residential:Homeowners in Brazilian and Colombian urban centers prioritize lamp-level retrofits over fixture replacement, sustaining standard LED bulb volumes despite smart lighting availability.
- Hospitality:Hotels and restaurants in Santiago and Bogotá specify tunable white and dimmable fixtures for ambiance control, though penetration lags commercial retrofit intensity by approximately half.
Commercial applications anchor specification revenue; residential channels sustain unit volume leadership.
Technology:
Maturity gradient separates legacy on-off switching from networked control architectures requiring commissioning expertise.
- Smart Lighting:Connected systems with wireless mesh protocols and cloud-based energy dashboards capture facility manager attention in Brazilian commercial stock. Integration complexity with legacy DALI and 0-10V infrastructure constrains rollout velocity outside São Paulo and Santiago technical labor pools.
- Standard:Non-dimmable, non-connected fixtures maintain dominant residential share where homeowner willingness to pay for connectivity remains limited. Argentine and Colombian price sensitivity sustains this tier's volume position.
- Dimmable:Phase-cut and 0-10V dimming modules serve hospitality and high-end residential segments where ambiance control justifies incremental hardware cost.
- RGB:Color-tunable arrays concentrate in entertainment venues and architectural accent applications with limited penetration into mainstream commercial specification.
Standard technology defends volume base; smart lighting climbs the fastest trajectory.
End User:
Procurement authority migration reshapes channel economics as contractor collectives consolidate specification influence.
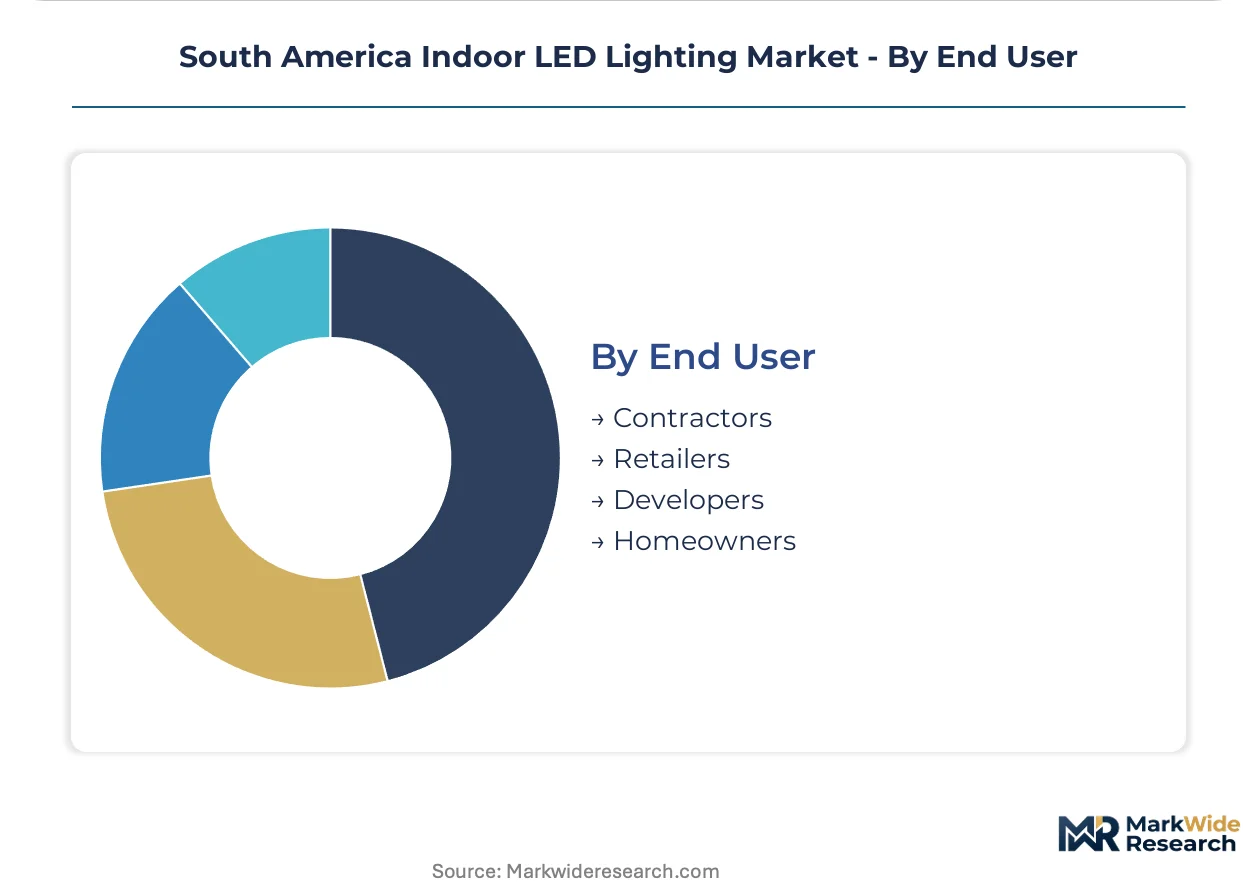
- Contractors:Electrical installation firms in Buenos Aires and Santiago purchasing collectives negotiate direct manufacturer relationships for commercial projects above five hundred fixture units. These groups displace traditional electrical distributor markups through volume aggregation.
- Retailers:Home improvement chains and electrical supply houses serve residential homeowners and small commercial accounts with bulb and basic fixture assortments. Brazilian metropolitan markets show fastest digital procurement platform adoption.
- Developers:New construction specification in Colombian and Chilean commercial towers favors integrated lighting-control packages bundled with building management systems.
- Homeowners:Individual consumers drive lamp-level replacement cycles with limited fixture renovation, sustaining economy-tier bulb demand across South American residential markets.
Retailers sustain transaction frequency; contractors capture specification value migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
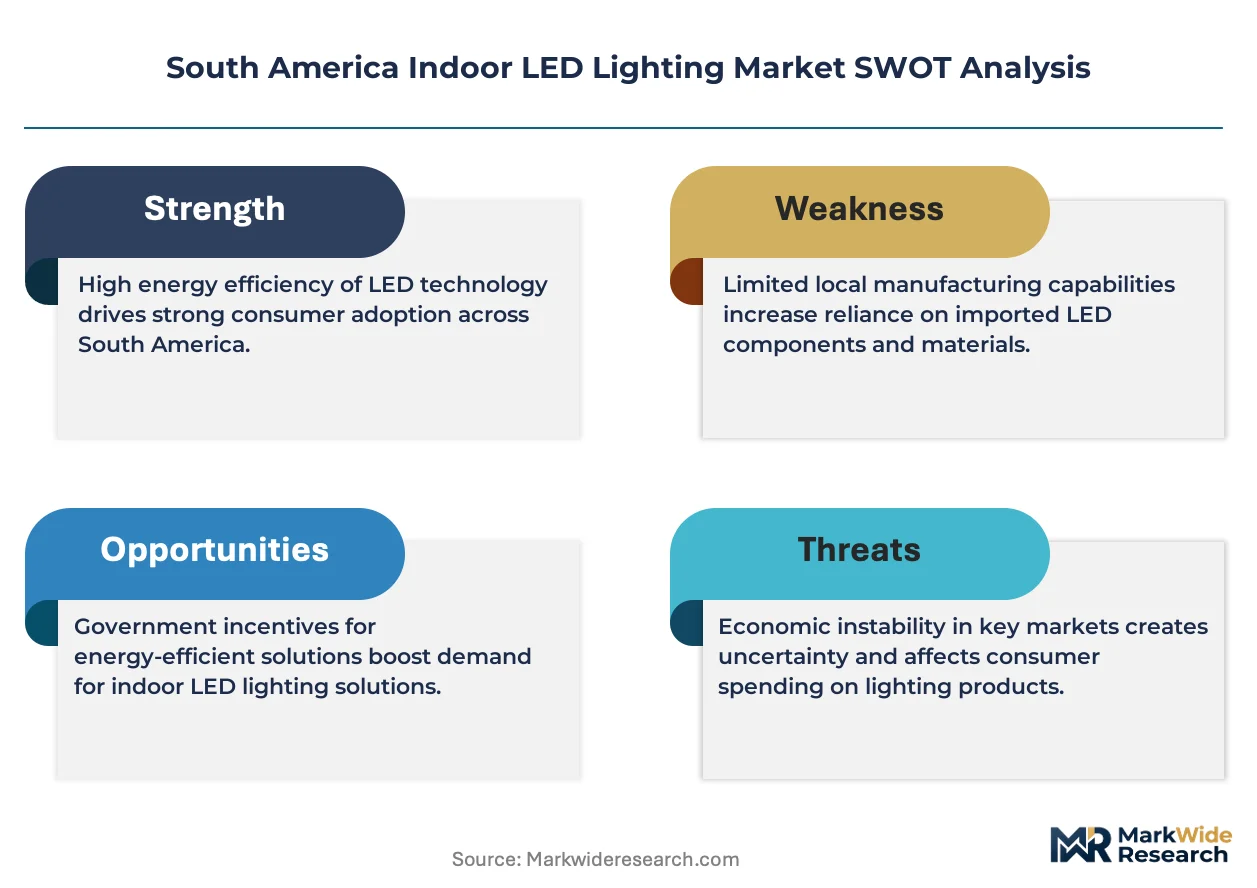
Brazil commands pricing power across the South American indoor LED lighting market, while Argentine distributors absorb currency-driven cost volatility that compresses margin structures. This asymmetry shapes procurement patterns, with Brazilian buyers leveraging scale for direct manufacturer relationships while Andean markets remain tethered to import-dependent supply chains.
Brazil
INMETRO efficiency labeling mandates filter substandard imports and compress replacement cycles in São Paulo commercial towers. The southeastern industrial corridor spanning São Paulo, Minas Gerais, and Rio de Janeiro states concentrates panel light demand from manufacturing and logistics facilities. Domestic manufacturers with captive testing laboratories capture six-month speed-to-market advantages over import-dependent rivals.
Argentina
IRAM certification requirements layer compliance costs onto manufacturers serving Buenos Aires commercial retrofit projects. Electrical contractor purchasing collectives consolidate specification authority and negotiate direct manufacturer relationships for projects above five hundred fixture units. Retrofit intensity in Buenos Aires financial district lags São Paulo penetration by approximately half.
Chile
SEC certification standards create testing queue backlogs that extend product launch windows for new market entrants. Santiago facility managers prioritize connected lighting systems for energy compliance reporting. The metropolitan region concentrates qualified commissioning engineers for networked lighting control deployments.
Colombia
Bogotá and Medellín commercial stock modernization presents untapped specification potential for smart lighting systems. Facility managers in Colombian urban centers show rising interest in occupancy sensing and daylight harvesting technologies. Procurement channels remain fragmented between traditional electrical distributors and emerging digital platforms.
South America Indoor LED Lighting Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream where driver electronics and semiconductor sourcing determines cost position. The South American indoor LED lighting market structures around three tiers: multinational conglomerates with regional manufacturing footprints, mid-scale specialists focused on architectural specification, and import-dependent distributors serving price-sensitive residential channels. Two dominant competitive moves define current positioning: domestic certification laboratory investment to compress INMETRO approval timelines, and contractor-direct relationship cultivation to bypass traditional wholesale markups.
Among European-headquartered lighting conglomerates, Signify and OSRAM GmbH exemplify divergent strategic archetypes. Signify leverages established Brazilian manufacturing presence to sustain pricing flexibility against import-dependent rivals. OSRAM GmbH anchors its regional position through technology transfer capabilities that differentiate driver electronics portfolios. LEDVANCE GmbH, spun from OSRAM's general lighting business, occupies a position within the mid-tier specification channel serving commercial retrofit projects.
| Leading Market Players |
|---|
| Signify |
| OSRAM GmbH |
| Acuity Brands Inc |
| Cree LED |
| LEDVANCE GmbH |
| OPPLE Lighting Co Ltd |
| EGLO Leuchten GmbH |
| NVC International Holdings Limited |
| Thorn Lighting Ltd |
| Others |
Pricing and Supply Chain Analysis
INMETRO certification queue backlogs constitute the dominant risk vector compressing margin structures across the South American indoor LED lighting market, forcing manufacturers to absorb extended cash conversion cycles while tiering pricing around testing capability access rather than pure component cost.
Pricing Analysis
Configured-to-order pricing for smart lighting systems with embedded commissioning services commands spreads exceeding standard panel light transactions by significant multiples. Three-tier pricing structure across premium specification-grade, standard INMETRO-compliant, and economy import tiers separates buyers by certification grade and volume commitment. Pricing pressure stems from contractor purchasing collectives consolidating specification authority and squeezing distributor markups in São Paulo and Buenos Aires. Residential homeowners exhibit highest price sensitivity, while commercial facility managers prioritize energy compliance reporting capabilities over unit cost.
Supply Chain Analysis
Upstream feedstock flows for LED driver ICs and phosphor materials center on Taiwan, China, and South Korea manufacturing hubs. Semiconductor components, aluminum heat sinks, and optical diffusers constitute critical input dependencies. Single-source vulnerability concentrates in advanced driver electronics where Asian foundry capacity constraints create allocation risk. Distribution runs through electrical contractor collectives in Brazilian metropolitan markets and traditional wholesale tiers in Andean corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware margins are compressing toward commodity levels while software subscription layers for energy management and predictive maintenance expand faster than fixture revenue, repositioning competitive advantage around service-attach rates.
For Market Incumbents: Entrench certification laboratory capabilities to compress INMETRO approval timelines and defend against import-dependent rivals facing six-month launch delays. Deepen captive driver electronics sourcing to offset Asian semiconductor volatility. Prioritize direct contractor relationship cultivation in São Paulo purchasing collectives to bypass distributor disintermediation. For New Entrants and Emerging Players: Build out specification authority in Colombian commercial stock modernization where smart lighting penetration lags São Paulo retrofit intensity by approximately half. Target Bogotá and Medellín facility managers with bundled energy compliance reporting solutions. Pursue digital procurement platform partnerships to reach contractor buyers outside traditional wholesale channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform integrators with software architecture capabilities over pure hardware manufacturers. Five-to-ten year viability hinges on recurring revenue attachment rates exceeding hardware replacement cycles. Acquisition targets should demonstrate commissioning engineer density in underserved Andean markets. Monitor INMETRO reciprocity negotiations with Mercosur partners as inflection signal for pan-regional compliance cost collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Investment | Captive INMETRO testing compresses product launch windows versus import-dependent competitors. |
| Contractor-Direct Relationship Cultivation | Bypasses distributor markups in Brazilian purchasing collectives consolidating specification authority. |
| Software Platform Integration | Energy management subscriptions expand recurring revenue faster than hardware replacement cycles. |
| Smart Lighting Specification Push | Connected systems with daylight harvesting capture facility manager priority for compliance reporting. |
| Andean Market Expansion | Colombian and Chilean commercial stock modernization presents untapped specification potential. |
Research Methodology
The analysis maps panel light, downlight, bulb, and high bay categories, each validated through facility managers, electrical contractors, distributor procurement leads, and lighting specification engineers. Primary interview data triangulates against INMETRO certification records, customs import declarations, SEC filings from listed lighting conglomerates, and energy utility rebate program databases. Bottom-up fixture volume estimates reconcile with top-down market value assessments across the projection horizon.
Fixed assumptions include INMETRO efficiency tier standards, Mercosur trade framework continuity, and semiconductor input cost trajectories; varied conditions span electricity tariff escalation rates and smart lighting adoption curves. Segmentation dimensions modeled encompass product type, application, technology tier, and end user procurement channel. CAGRs derive from fitted growth curves applied to baseline penetration data. Forecast inputs incorporate commercial retrofit cycle compression timelines and residential lamp replacement frequency patterns.
Stress conditions across currency volatility bands, certification timeline extensions, and contractor collective bargaining power were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and supply chain configuration. Specific risk factors that could revise projections include Mercosur harmonization failure, Asian semiconductor allocation crises, and technical workforce scarcity constraining smart lighting rollout velocity. Cross-checking against national energy efficiency program disbursement records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
France Outdoor LED Lighting Market
LED
Germany Outdoor LED Lighting Market
LED
Middle East and Africa Outdoor LED Lighting Market
LED
Xenon Market
LED
Microled Market
LED
Monochrome Outdoor LED Display Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Global Chip Scale Package (CSP) LED Market
LED
LED Encapsulation Market
LED
North America Outdoor LED Lighting Market
LED
Superluminescent Diodes Market
LED
India Indoor LED Lighting Market
LED
United States Micro LED Market
LED
US Outdoor LED Lighting Market
LED
France Indoor LED Lighting Market
LED
UV-C LED Market