
 Asia-Pacific Food Enzymes Market | 2026-2036
Asia-Pacific Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Food Enzymes Market Outlook
Specialty snack producers is bifurcating from commodity baking houses as the primary demand vector in the Asia-Pacific food enzymes landscape. Novozymes leverages its fungal enzyme platform to dominate high-purity lipase supply for premium chocolate manufacturers. Kerry Group anchors South Asian distribution through localized fermentation capacity, while Advanced Enzymes competes on cost-engineered protease blends for regional meat processors.
Food enzymes comprise protein-based biocatalysts, typically operating at 30–70°C and pH 4.0–8.0, that accelerate hydrolysis, oxidation, or isomerization reactions without permanent consumption in food matrices. Carbohydrases command the largest product type position due to their indispensability in starch liquefaction for Asian noodle and syrup production. Beverage application growth outpaces baking as Japanese and Australian brewers adopt glucoamylase for low-calorie formulation, while powder form maintains margin superiority over liquid alternatives in tropical supply chains where refrigeration remains uneven.
FSSAI in India enforces microbial specification limits that determine import eligibility for European enzyme suppliers, while China's SAMR aligns GB standards with CODEX Alimentarius for transglutaminase use in restructured meat. Japan's MHLW maintains separate positive-list requirements that fragment product registration burdens across Northeast Asian markets. Stakeholders must calibrate formulation portfolios against divergent national purity regimes rather than pursuing single-standard regional compliance.
Market Dynamics
Clean-label mandates across Southeast Asian retail channels are compressing formulation cycles for enzyme suppliers, forcing simultaneous purity upgrades and cost reductions in tropical supply chains.
Growth Catalysts
- FSSAI Microbial Specifications:India's tightened import eligibility rules for European enzyme preparations are accelerating local fermentation investments by domestic suppliers seeking exemption from border testing delays.
- Fungal Protease Retrofits:Dairy cooperatives in Gujarat and Maharashtra are replacing chemical hydrolysis with enzymatic systems, cutting processing energy by half while meeting cooperative-grade output targets.
- Glucoamylase Brewing Adoption:Japanese and Australian brewers are deploying this carbohydrase for low-calorie beer formulation, creating specification pull for high-activity enzyme concentrates.
Market Restraints
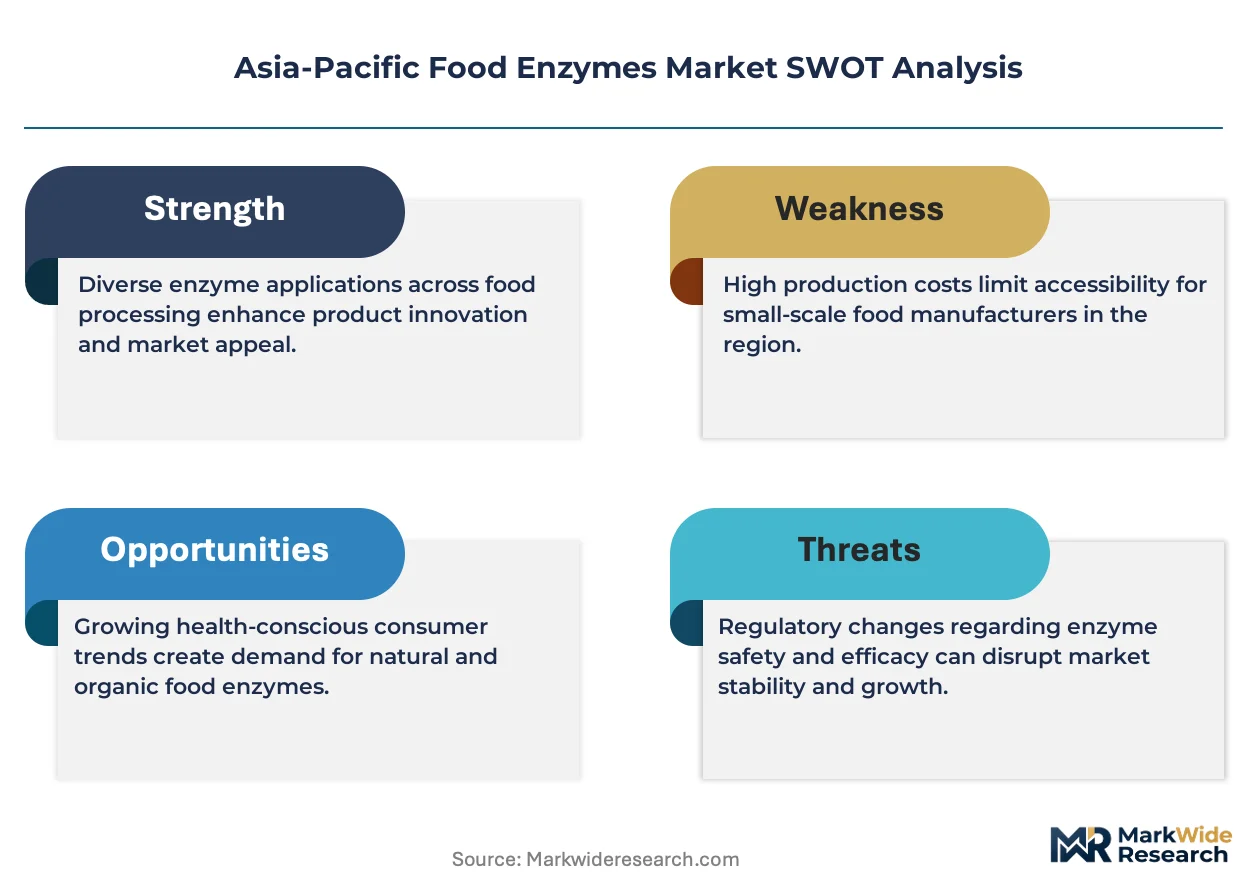
- Refrigeration Infrastructure Gaps:Liquid enzyme stability requirements clash with uneven cold-chain coverage across Indonesian archipelago logistics, forcing powder-form premiums that squeeze processor margins.
- GB Standards Alignment Costs:China's SAMR purity threshold revisions for transglutaminase imports impose re-certification burdens that freeze European supplier portfolios during transition windows.
- Starch Price Volatility:Regional noodle and syrup manufacturers face input cost swings that compress enzyme procurement budgets during high-corn-price cycles.
Strategic Opportunities
- Vietnamese Snack Processing Corridor:Specialty crisp and extruded snack producers in Binh Duong province remain underpenetrated by fungal lipase suppliers serving premium chocolate and confectionery channels.
- MEE Dual Carbon Compliance:China's environmental ministry enforcement is creating enzyme demand for bio-based processing aids that replace thermal-intensive chemical steps in starch modification.
- Direct-to-Cooperative Distribution:Kerala and Karnataka dairy federations are piloting bulk enzyme procurement platforms that bypass traditional distributor markups for protease and lactase volumes.
Industry Challenges
- Fermentation Specialist Scarcity:Upstream enzyme production expansion in Thailand and Vietnam outpaces available industrial microbiology talent pools, extending commissioning timelines for new bioreactor facilities.
- Legacy System Integration:Dairy processors retrofitting continuous-flow enzymatic hydrolysis encounter control-system incompatibilities with existing batch-oriented plant automation architectures.
- Positive-List Registration Fragmentation:Japan's MHLW maintains separate approval pathways that duplicate testing costs for enzyme products already certified under Australia's TGA or South Korea's MFDS frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Food Enzymes Market |
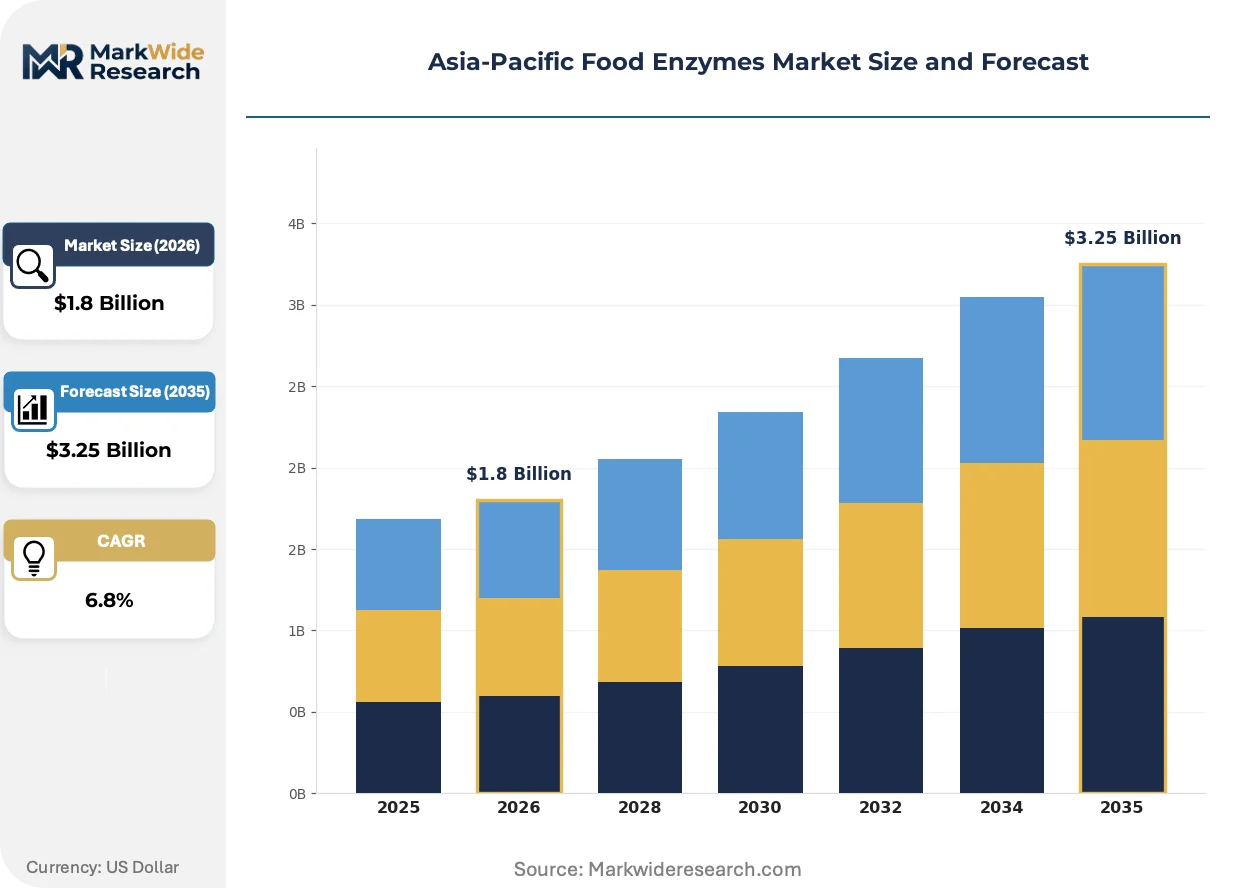
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Carbohydrases, Proteases, Lipases Application: Baking, Dairy Processing, Beverage Production, Meat Processing Form: Liquid, Powder, Granular, Tablet End User: Food Manufacturers, Beverage Companies, Snack Producers, Culinary Professionals |
| Companies Covered | Novozymes, DuPont de Nemours, DSM-Firmenich, Kerry Group, BASF, Chr. Hansen, AB Enzymes, Advanced Enzymes, Jiangsu Boli Bioproducts, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Food Enzymes Market Strategic Shifts
Enzyme engineering platforms are compressing development timelines for temperature-tolerant biocatalysts, while regulatory divergence across Northeast Asian markets fragments product standardization efforts.
Cell-free enzyme synthesis is decomposing traditional fermentation bottlenecks by enabling direct production of engineered lipases without microbial cultivation steps. Specialty chocolate manufacturers in Malaysia and Indonesia are piloting these biocatalysts for cocoa butter modification, cutting supplier qualification cycles from months to weeks. This technology is decomposing capital barriers for mid-scale processors seeking enzyme access without minimum order commitments.
China's SAMR has aligned GB standards with CODEX Alimentarius for transglutaminase use in restructured meat applications, creating a unified compliance reference for multinational suppliers. This harmonization reduces formulation variant counts for regional meat processors operating across Greater China and export markets. Restructured seafood and surimi segments in Shandong and Fujian provinces are accelerating adoption in response to simplified import documentation.
Bulk cooperative procurement platforms are consolidating enzyme purchasing for Indian dairy federations, displacing fragmented distributor networks that previously captured margin through geographic fragmentation. Kerala Milk Marketing Federation and Karnataka Milk Federation are negotiating directly with fermentation houses for protease and lactase volumes. This consolidation is most visible in South India's dairy processing corridor, where cooperative-owned plants represent the dominant installed base.
Asia-Pacific Food Enzymes Market Segmentation
Food enzyme procurement patterns diverge sharply across application channels in the Asia-Pacific region. Specialty snack producers route through direct fermentation house contracts, while dairy cooperatives and beverage manufacturers rely on distributor networks with divergent purity certification requirements.
Product Type:
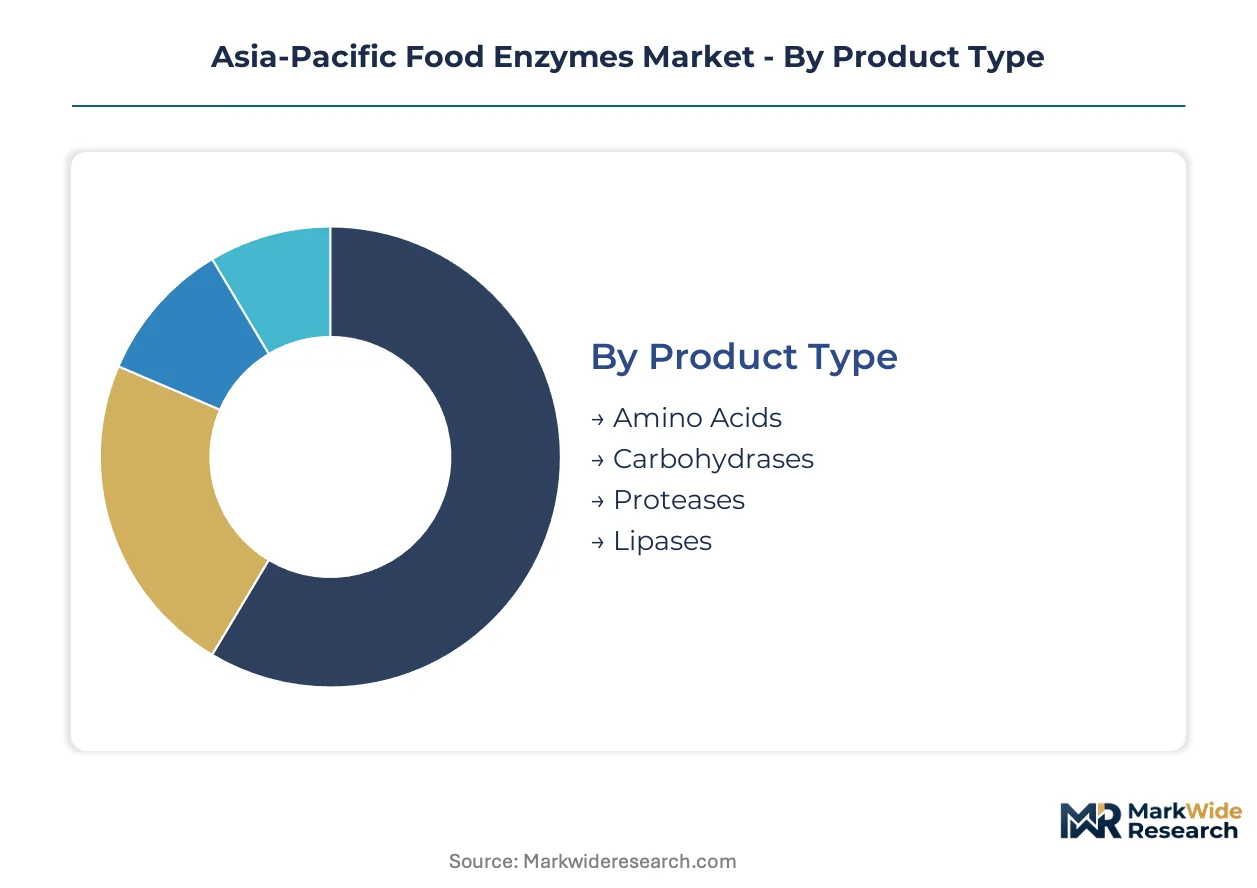
Channel mix varies by biocatalyst stability requirements and end-use concentration needs, with carbohydrases and proteases dominating bulk procurement while lipases command premium direct sales.
- Carbohydrases:These starch-hydrolyzing enzymes operate optimally at 60–70°C with pH 5.5–6.5 specifications. Demand concentrates in China's Shandong and Jiangsu noodle manufacturing clusters, where GB standard compliance for amylase activity determines import eligibility. SAMR's revised purity thresholds are forcing simultaneous reformulation across regional starch processors.
- Proteases:Protein-cleaving biocatalysts from fungal and bacterial sources function across 40–60°C with broader pH tolerance. Gujarat and Maharashtra dairy cooperatives are retrofitting plants with these systems to replace chemical hydrolysis, cutting energy consumption while meeting cooperative-grade output targets.
- Lipases:Ester bond-cleaving enzymes specified for cocoa butter modification and dairy fat hydrolysis.
- Amino Acids:Fermentation-derived processing aids for flavor enhancement and nutritional fortification.
Carbohydrases dominate installed base. Lipases are where expansion concentrates.
Application:
Cost tier stratification separates commodity baking enzymes from premium beverage and dairy formulations, with meat processing occupying a mid-tier position.
- Beverage Production:Glucoamylase deployment for low-calorie beer formulation requires high-activity concentrates stable at 4–10°C storage. Japanese and Australian brewers are driving specification pull for these carbohydrases, creating demand for cold-chain-compatible powder forms that bypass Indonesia's refrigeration infrastructure gaps.
- Dairy Processing:Protease and lactase systems for whey hydrolysis and lactose reduction operate in continuous-flow configurations. Kerala and Karnataka milk federations are piloting bulk procurement platforms that bypass traditional distributor markups, consolidating volumes previously fragmented across cooperative networks.
- Baking:Amylase and xylanase blends for dough conditioning and shelf-life extension.
- Meat Processing:Transglutaminase for protein cross-linking in restructured products.
Beverage Production commands margin premiums. Dairy Processing shows steepest expansion trajectory.
Form:
Volume concentration favors powder formats in tropical supply chains where cold-chain coverage remains uneven, while liquid forms retain position in temperature-controlled urban processing centers.
- Powder:Spray-dried enzyme concentrates with 12–24 month stability at ambient conditions. Indonesian archipelago logistics and Vietnamese snack processing corridors favor this form, despite reconstitution requirements that add processing steps.
- Liquid:Standardized enzyme solutions with immediate activity but stringent 2–8°C storage requirements. Australian and Japanese beverage manufacturers with reliable refrigeration infrastructure maintain procurement of these higher-activity formats.
- Granular:Dust-free formulations for bulk handling in flour milling operations.
- Tablet:Pre-measured units for small-scale culinary and artisanal applications.
Powder dominates installed base. Liquid is where expansion concentrates.
End User:
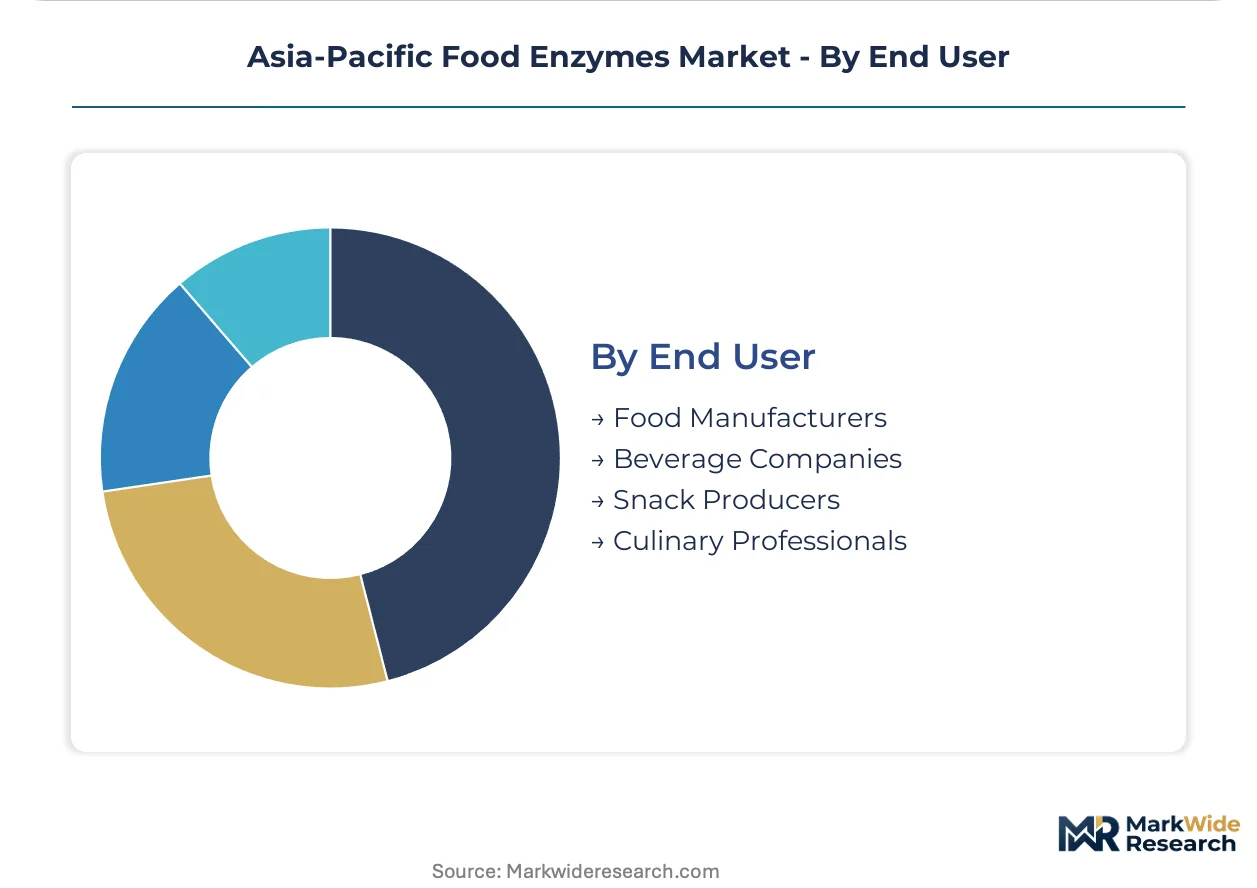
Customer type determines contract structure, with food manufacturers negotiating annual volumes while snack producers and culinary professionals purchase through spot markets or distributor tiers.
- Food Manufacturers:Large-scale processors of noodles, syrups, and baked goods operating continuous production lines. These buyers enforce stringent FSSAI microbial specifications in India and SAMR GB standards in China, consolidating procurement through approved supplier lists.
- Snack Producers:Specialty crisp and extruded snack manufacturers in Vietnam's Binh Duong province and Malaysia's Johor corridor. This segment remains underpenetrated by fungal lipase suppliers, creating whitespace for direct fermentation house relationships.
- Beverage Companies:Brewers and soft drink manufacturers with enzyme requirements tied to formulation innovation cycles.
- Culinary Professionals:Restaurant chains and catering operations with small-volume, high-frequency purchasing patterns.
Food Manufacturers dominate installed base. Snack Producers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports enzyme preparations to Southeast Asian processors while India's dairy cooperatives import fungal protease systems from European fermentation houses. Japan and Australia source high-activity glucoamylase concentrates for beverage applications. Vietnam's snack corridor draws supply from regional distributors.
China
Shandong and Jiangsu noodle manufacturing clusters drive carbohydrase demand for starch liquefaction. SAMR's revised GB standards for transglutaminase purity impose re-certification burdens on European suppliers during transition windows. The Yangtze River Delta concentration of starch processors is forcing simultaneous reformulation across regional facilities.
India
Gujarat and Maharashtra dairy cooperatives are retrofitting plants with fungal protease systems to replace chemical hydrolysis. FSSAI microbial specification limits determine import eligibility for European enzyme preparations, accelerating local fermentation investments. Kerala and Karnataka milk federations pilot bulk procurement platforms that bypass traditional distributor markups.
Japan
Japanese brewers deploy glucoamylase for low-calorie beer formulation, creating specification pull for high-activity concentrates. MHLW maintains separate positive-list requirements that duplicate testing costs for products certified under Australia's TGA or South Korea's MFDS. Kanto-based beverage manufacturers with reliable refrigeration infrastructure maintain procurement of liquid enzyme formats.
Australia
Australian brewers adopt glucoamylase concentrates for reduced-calorie formulation alongside Japanese counterparts. The country's national food safety regulator aligns with CODEX Alimentarius frameworks, simplifying import documentation for multinational suppliers. Urban processing centers in Sydney and Melbourne leverage temperature-controlled infrastructure for liquid enzyme stability.
Vietnam
Specialty crisp and extruded snack producers in Binh Duong province remain underpenetrated by fungal lipase suppliers serving premium confectionery channels. Uneven cold-chain coverage across the archipelago logistics forces powder-form premiums that squeeze processor margins. Ho Chi Minh City-based distributors fragment supply across geographic sub-markets.
Asia-Pacific Food Enzymes Market Competitive Environment
Listed leaders compete with private specialists across formulation purity and tropical supply chain reliability. The vendor base splits between multinational fermentation houses with regional distribution networks and domestic suppliers leveraging local regulatory exemptions. Three archetypes dominate: purity-focused premium suppliers, cost-engineered volume players, and cooperative-direct distributors. Capacity expansion and strategic partnerships represent the dominant competitive moves as players calibrate against divergent national compliance regimes.
Within the multinational tier, Novozymes and DSM-Firmenich occupy positions anchored by fungal enzyme platforms and integrated fermentation capacity. Kerry Group exemplifies the regional distribution archetype through localized supply chain presence. Advanced Enzymes represents the cost-competitive domestic specialist model competing on engineered protease blends. These three patterns illustrate how competitive positioning stratifies across premium purity, regional reach, and cost-engineered volume vectors.
| Leading Market Players |
|---|
| Novozymes |
| DuPont de Nemours |
| DSM-Firmenich |
| Kerry Group |
| BASF |
| Chr. Hansen |
| AB Enzymes |
| Advanced Enzymes |
| Jiangsu Boli Bioproducts |
| Others |
Value Chain & Pricing Dynamics
FSSAI microbial specifications and SAMR GB standards gate both supplier qualification and price differentiation simultaneously, forcing European fermentation houses to invest in purity upgrades while domestic Indian and Chinese producers leverage regulatory exemptions to undercut on cost. This dual-gate mechanism stratifies pricing across certification tiers, with import-eligible preparations commanding substantial premiums over locally certified alternatives.
Pricing Analysis
Next-generation cell-free enzyme synthesis platforms are compressing supplier qualification cycles from months to weeks, widening the price gap against traditional fermentation-derived biocatalysts. Three-tier pricing structure across premium, standard, and economy levels separates cold-chain-compatible powder concentrates from liquid formats and basic spray-dried grades. Pricing pressure stems from starch price volatility squeezing procurement budgets at regional noodle manufacturers. Commodity baking houses exhibit highest price sensitivity, while Japanese brewers purchasing glucoamylase for low-calorie formulation show lowest.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo and Singapore-Johor trade lanes elevates inbound logistics costs for European enzyme preparations entering Southeast Asian processing corridors. Supply concentrates in China, India, and Denmark, with Shandong fermentation clusters and Gujarat dairy cooperatives anchoring regional production. Raw material dependencies include corn starch feedstocks, fungal cultivation substrates, and specialized filtration membranes. Single-source vulnerability runs through cold-chain infrastructure gaps across Indonesian archipelago logistics. Distribution runs through cooperative-direct platforms in South India and distributor networks in Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence across FSSAI, SAMR, and MHLW frameworks fragments standardization, creating whitespace for specialists who calibrate formulations against single national purity regimes rather than pursuing regional compliance. Clean-label mandates bifurcating from commodity channels generate niche entry points.
For Market Incumbents: Shield premium positioning by accelerating backward integration into fermentation capacity within India and Vietnam, bypassing border testing delays that freeze European competitor portfolios during FSSAI and SAMR transition windows. Deepen certification investments for MHLW positive-list registration to capture Japanese brewer demand for high-activity glucoamylase concentrates. For New Entrants and Emerging Players: Differentiate on cell-free synthesis platforms serving Malaysian and Indonesian specialty chocolate manufacturers seeking cocoa butter modification without minimum order commitments. Target Vietnam's Binh Duong snack processing corridor, where fungal lipase penetration remains thin. Pursue direct-to-cooperative distribution in Kerala and Karnataka to displace fragmented distributor markups. For Investors and Strategic Acquirers: China's MEE dual carbon compliance reshapes the acquisition landscape by elevating enzyme-based bio-processing aids that replace thermal-intensive chemical steps. Long-term viability centers on fermentation houses with demonstrated regulatory navigation across multiple national purity regimes. Monitor bulk cooperative procurement platform adoption rates across Indian dairy federations as inflection signal for distributor displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Fermentation Capacity Expansion | Captures FSSAI and SAMR regulatory exemptions while shortening lead times to Gujarat dairy cooperatives. |
| Cell-Free Enzyme Synthesis Platform Deployment | Eliminates microbial cultivation bottlenecks for Malaysian cocoa butter modification specialists. |
| Direct-to-Cooperative Distribution Partnership | Displaces traditional distributor markups in Kerala and Karnataka milk federation procurement. |
| MHLW Positive-List Registration Investment | Unlocks Japanese brewer demand for cold-chain-compatible glucoamylase concentrates. |
| Backward Integration into Starch Feedstock Supply | Hedges input cost volatility for Shandong and Jiangsu noodle manufacturing clusters. |
Study Parameters
A spread of perspectives from fermentation plant managers, dairy cooperative procurement leads, enzyme distributor channel partners, and regulatory affairs specialists at FSSAI and SAMR converged on the working assumptions. Primary interview insights combined with secondary validation from customs trade records, FSSAI microbial specification filings, SAMR GB standard revisions, and CODEX Alimentarius alignment documentation. Bottom-up volume modeling across product type, application, form, and end-user segments triangulated against top-down market sizing.
Segmentation dimensions modeled include biocatalyst product type, processing application, physical form, and end-user archetype across the analysis window. CAGRs derived from trend extrapolation of procurement volumes at named dairy cooperatives, noodle manufacturing clusters, and beverage formulation pipelines. Industry-specific forecast inputs incorporate FSSAI import eligibility rule changes and MEE environmental enforcement trajectories.
The analysis sits within stated boundaries; outcomes outside continued regulatory divergence and clean-label mandate acceleration would require recalibration. Forecasts reflect assumptions on fermentation capacity commissioning timelines and cooperative procurement platform adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Germany Food Emulsifiers Market
Food Additives and Ingredients
Global Organic Food Preservatives Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Global Cereal Ingredients Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
PVPP Beer Stabilizer Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
Casamino Acids Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Clean Label Ingredients Market
Food Additives and Ingredients
Brazil Food Enzymes Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Granulated Tapioca Market