
 Flour Treatment Agent Market | 2026-2036
Flour Treatment Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Flour Treatment Agent Market Insights
Enzyme engineering talent scarcity is rotating toward the center of competitive strategy in flour treatment formulation. Corbion leverages its biotechnology R&D footprint to sustain leadership in enzyme-based dough conditioners across European milling corridors. AB Mauri anchors its position through backward integration into fermentation-derived ingredient streams, while Puratos differentiates through specialized bakery application centers that bind technical service to ingredient sales.
Flour treatment agents comprise functional additives that modify wheat flour protein networks, rheology, and oxidation states through enzymatic, chemical, or oxidative mechanisms, typically dosed at 10–200 parts per million to achieve targeted dough extensibility or gas retention. Their primary purpose is to standardize flour performance across variable harvest conditions and enable consistent processing in high-speed baking operations. Enzyme formulations are capturing margin pools as clean-label positioning displaces traditional chemical oxidizers in premium bakery segments. Baking applications dominate volume absorption, though noodle production is emerging as a structurally distinct demand channel where gluten-strengthening agents face differentiated performance specifications.
EFSA additive safety assessments, FDA GRAS self-affirmation pathways, and EU enzyme regulation under the Food Improvement Agents Package collectively determine which active ingredients achieve commercial scale in target markets. Regulatory divergence between jurisdictions forces manufacturers to maintain parallel formulation portfolios, elevating compliance costs but also creating defensible positions for regionally certified suppliers. Stakeholders must monitor pending enzyme novel food approvals and evolving maximum residue limits to anticipate which treatment platforms will retain formulation access.
Market Dynamics
The flour treatment agent sector is experiencing a fundamental restructuring as EFSA's tightened additive authorization protocols force formulators to abandon traditional chemical oxidizers in favor of enzyme-based alternatives. This regulatory compression is redrawing competitive boundaries around biotechnology capabilities and clean-label certification.
Growth Catalysts
- Enzyme-based dough conditioning:Artisan and industrial bakeries across Germany and France are scaling enzymatic formulations to satisfy consumer clean-label expectations and retailer procurement mandates.
- EFSA regulatory redirection:The European Union's additive safety assessments under the Food Improvement Agents Package are channeling R&D investment toward novel enzyme platforms with established toxicological profiles.
- Craft bakery revival:Premium milling corridors in Germany are pulling specialized treatment agent volumes as heritage baking methods regain market share in Western European retail channels.
Market Restraints
- Wheat protein variability:Harvest condition inconsistency across the Black Sea region forces formulators to maintain broader dosage ranges, compressing margin predictability.
- Enzyme engineering talent scarcity:The limited pool of protein biochemists with cereal science expertise concentrates R&D capability in established biotechnology clusters.
- Parallel formulation portfolios:Regulatory divergence between EFSA, FDA GRAS pathways, and other jurisdictions elevates compliance costs for multi-regional suppliers.
Strategic Opportunities
- Noodle production channel:Asian wheat-based noodle manufacturers present structurally distinct demand for gluten-strengthening agents with differentiated performance specifications.
- EU Green Deal alignment:Fermentation-derived ingredient streams qualify for sustainability-linked procurement preferences in European food manufacturing.
- Application center binding:Technical service integration with ingredient sales creates defensive positions against commodity enzyme suppliers.
Industry Challenges
- Novel food approval timelines:Pending enzyme submissions under EFSA's novel food framework create uncertainty windows that delay commercialization planning.
- Maximum residue limit evolution:Shifting MRL standards for processing aids require continuous reformulation and re-certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flour Treatment Agent Market |
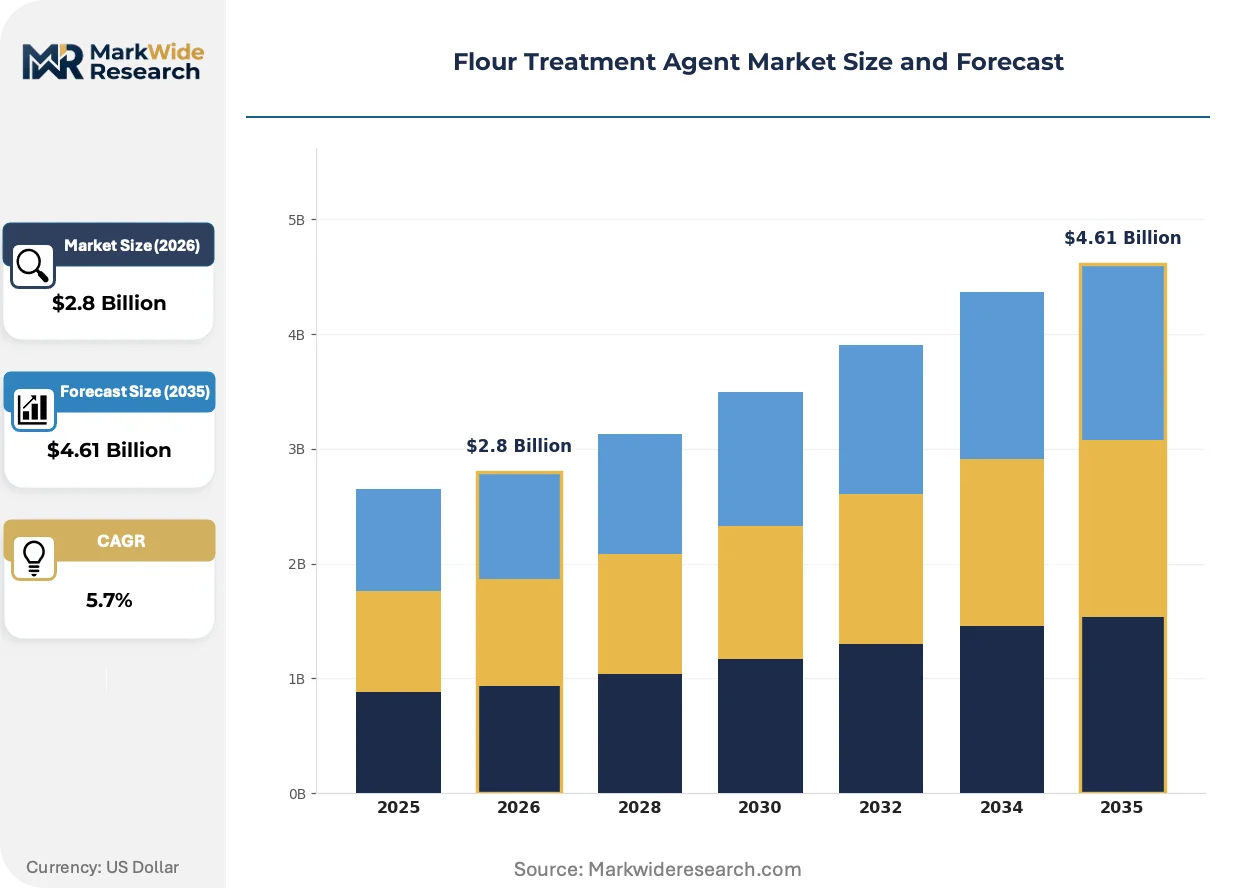
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxidizing Agents, Reducing Agents, Enzymes, Chemicals Application: Baking, Noodle Production, Pasta Making, Confectionery End User: Household, Food Industry, Restaurants, Bakeries Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Corbion, AB Mauri, Nutricepts, Canton Chem, Penta Manufacturing Company, Brolite Products, Handary, RIKEN VITAMIN, Puratos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flour Treatment Agent Market Trends and Innovations
Formulation science in flour treatment is splitting along clean-label versus performance-maximizing trajectories, with biotechnology and regulatory science now determining competitive outcomes more than traditional chemical engineering.
Enzymatic oxidation systems is bifurcating the treatment agent landscape between premium clean-label positions and conventional chemical alternatives. High-speed industrial bakeries in Germany and the Netherlands are adopting transglutaminase and glucose oxidase blends at accelerated procurement cycles. This technological division is compressing margin pools for legacy potassium bromate and azodicarbonamide suppliers while expanding biotechnology service contracts.
EFSA's implementation of tightened additive authorization protocols under the Food Improvement Agents Package is systematically disqualifying traditional chemical oxidizers from new product approvals. European milling operations are responding by qualifying enzyme alternatives ahead of anticipated regulatory sunsets. Premium bakery segments in France and Italy are most affected, with reformulation timelines compressing to match retailer clean-label commitments.
Buyer concentration among European retail baking cooperatives is consolidating procurement authority and demanding outcome-based technical partnerships rather than transactional ingredient supply. Specialized bakery application centers are displacing traditional distributor relationships in Germany and Belgium. This pattern is most visible in craft-industrial hybrid bakeries where technical service integration determines supplier selection.
Flour Treatment Agent Market Segmentation
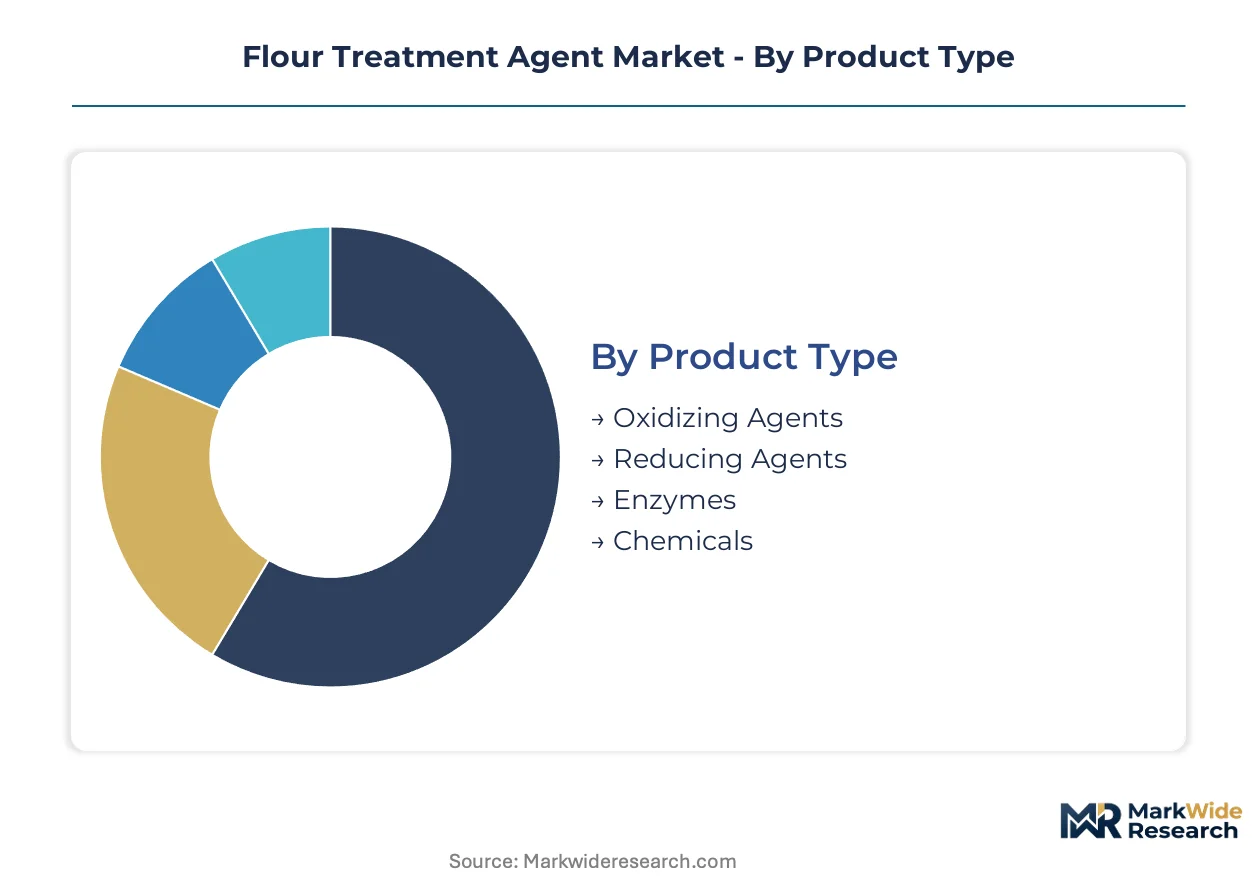
Flour treatment agent procurement patterns diverge sharply across product categories, with enzyme formulations commanding premium positioning in Western European clean-label markets while oxidizing agents retain cost-driven volume in industrial baking corridors. Application-specific performance requirements create distinct formulation specifications that resist standardization.
Product Type:
Domestic milling operations in Germany and France anchor demand for enzyme-based formulations, while export-led chemical oxidizer supply concentrates in Eastern European production hubs serving price-sensitive industrial bakeries.
- Enzymes:Protein biocatalysts including amylases, lipases, and xylanases modify dough rheology through substrate-specific hydrolysis. German craft-industrial hybrid bakeries are scaling transglutaminase procurement to meet retailer clean-label mandates under EFSA's tightened additive protocols.
- Oxidizing Agents:Ascorbic acid and potassium bromate derivatives strengthen gluten networks through disulfide bond formation. Black Sea wheat variability forces French industrial mills to maintain broader dosage ranges, compressing margin predictability for azodicarbonamide suppliers.
- Reducing Agents:L-cysteine and sodium metabisulfite relax dough structure for sheeted products.
- Chemicals:Bleaching and maturing agents including benzoyl peroxide face regulatory sunset pressure.
Enzymes command the established base. The steepest expansion runs through oxidizing agent alternatives as EFSA authorization timelines compress.
Application:
Volume concentration tracks wheat-processing infrastructure density, with high-speed baking lines in the Netherlands and Belgium absorbing treatment agents at scale while Asian noodle manufacturers impose differentiated gluten-strengthening specifications.
- Baking:Bread and pastry production consumes treatment agents for dough conditioning, oxidation control, and shelf-life extension. German retail baking cooperatives are consolidating procurement authority and demanding outcome-based technical partnerships rather than transactional supply.
- Noodle Production:Wheat-based Asian noodle manufacturing requires specialized gluten-strengthening agents with elasticity retention under high-shear processing. Japanese udon and Chinese lamian producers specify performance characteristics that diverge from Western baking norms.
- Pasta Making:Durum wheat processing employs treatment agents for color stabilization and cooking tolerance.
- Confectionery:Cake and biscuit applications utilize reducing agents for crumb structure control.
Baking absorbs the dominant volume share. Noodle production is climbing the fastest as Asian wheat-processing capacity expands.
End User:
Customer scale determines service intensity, with industrial food manufacturers in Italy and Spain requiring technical integration while household segments transact through retail packaging with minimal formulation guidance.
- Food Industry:Large-scale milling and baking operations specify treatment agents through procurement contracts tied to flour performance guarantees. Puratos operates specialized application centers in Belgium that bind technical service to ingredient sales for industrial accounts.
- Bakeries:Artisan and craft-industrial operations in France prioritize clean-label positioning and enzyme-based conditioning. AB Mauri anchors supply relationships through backward integration into fermentation-derived ingredient streams.
- Restaurants:Foodservice operations source treatment agents through distributor networks with limited technical support.
- Household:Consumer-packaged treatment agents for home baking represent minimal volume with commodity pricing.
Food Industry commands the established base. The steepest expansion runs through Bakeries as craft revival accelerates enzyme adoption.
Distribution Channel:
Channel selection reflects buyer technical sophistication, with enzyme formulations requiring direct technical service while commodity chemicals flow through wholesale distributors.
- Direct Sales:Biotechnology suppliers including Corbion deploy technical specialists to European milling corridors for formulation development and dosage optimization. Direct relationships capture premium pricing through service integration.
- Wholesale:Industrial chemical oxidizers and standard enzyme blends distribute through milling supply cooperatives in Germany and Poland.
- Retail:Consumer-packaged treatment agents for household baking reach supermarkets and specialty food stores.
- Online:E-commerce channels serve small-scale bakeries and restaurant accounts with standardized product configurations.
Direct Sales commands the established base. The steepest expansion runs through Wholesale as procurement consolidation elevates distributor leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's Food Improvement Agents Package anchors regulatory direction across Western European milling corridors. Procurement concentration in Germany and France is redirecting formulation science toward enzyme platforms. Asian wheat-processing expansion is opening structurally distinct demand channels for gluten-modifying agents.
Germany
Craft bakery revival and retail cooperative consolidation are accelerating enzyme-based dough conditioner procurement in Baden-Württemberg and North Rhine-Westphalia. EFSA authorization protocols under the Food Improvement Agents Package are disqualifying traditional chemical oxidizers from new product approvals. Stuttgart and Cologne anchor milling technology clusters where Corbion and Puratos operate specialized application centers.
France
Premium bakery segments in Île-de-France and Auvergne-Rhône-Alpes are compressing reformulation timelines to match retailer clean-label commitments. ANSM and DGCCRF enforcement of EFSA additive safety assessments is channeling R&D toward novel enzyme platforms. Lyon and Paris house heritage baking method revival zones pulling specialized treatment agent volumes.
China
Wheat-based noodle manufacturers in Shandong and Henan provinces present differentiated demand for gluten-strengthening agents with elasticity retention specifications. SAMR and GB standards for food additives are evolving toward stricter processing aid classifications. Zhengzhou and Jinan concentrate domestic enzyme engineering capability serving both local mills and export channels.
Japan
Udon and lamian producers specify performance characteristics diverging from Western baking norms, requiring specialized transglutaminase formulations. PMDA and MHLW food additive regulations maintain distinct approval pathways from EFSA and FDA frameworks. Osaka and Nagoya anchor wheat-processing infrastructure with technical service demands binding suppliers to regional milling accounts.
United States
Industrial high-speed baking lines in the Midwest and Southeast absorb treatment agents at scale through procurement contracts tied to flour performance guarantees. FDA GRAS self-affirmation pathways allow faster enzyme commercialization than EFSA novel food timelines. Minneapolis and Chicago concentrate milling operations where direct sales channels capture premium pricing through formulation development services.
Flour Treatment Agent Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in flour treatment agent supply. Biotechnology capabilities and clean-label certification are redrawing competitive boundaries as EFSA regulatory compression accelerates. Three archetypes dominate: fermentation-derived ingredient stream controllers, enzyme engineering specialists with cereal science expertise, and application-integrated technical service providers. M&A activity concentrates around biotechnology R&D footprints, while geographic expansion targets Asian wheat-processing corridors.
Within the integrated fermentation tier, AB Mauri anchors supply relationships through backward integration into ingredient streams. Corbion exemplifies the enzyme engineering specialist archetype with its biotechnology R&D positioning across European milling corridors. Puratos occupies the application-integrated tier, binding technical service to ingredient sales through specialized bakery application centers. These three players represent distinct competitive vectors as procurement authority consolidates among retail baking cooperatives demanding outcome-based partnerships rather than transactional supply.
| Leading Market Players |
|---|
| Corbion |
| AB Mauri |
| Nutricepts |
| Canton Chem |
| Penta Manufacturing Company |
| Brolite Products |
| Handary |
| RIKEN VITAMIN |
| Puratos |
| Others |
Pricing and Supply Chain Analysis
Enzyme substitution for chemical oxidizers is redrawing procurement geography and compressing margin pools for legacy suppliers while elevating biotechnology service premiums across European milling corridors.
Pricing Analysis
Long-term offtake contracts dominate procurement between industrial bakeries and enzyme suppliers, though spot purchasing persists for commodity chemical oxidizers in price-sensitive Eastern European markets. Three-tier pricing structure across premium enzyme formulations, standard blends, and economy chemical alternatives reflects certification grade and technical service bundling. Cost compression in commodity oxidizers is intensifying because EFSA authorization sunsets are disqualifying potassium bromate and azodicarbonamide from new approvals. Industrial food manufacturers exhibit lowest price sensitivity due to performance guarantees, while craft bakeries negotiate hardest on per-kilogram enzyme costs.
Supply Chain Analysis
Netherlands and Belgium anchor fermentation-derived enzyme production for European milling corridors, while China concentrates chemical oxidizer manufacturing serving price-driven industrial bakeries. Active ingredient supply draws from Danish biotechnology clusters for engineered amylases, Black Sea wheat belts for protein variability management, and Indian fermentation capacity for L-cysteine. Single-source vulnerability concentrates in specialized transglutaminase strains held by limited biotechnology R&D footprints. Distribution runs through direct technical service channels for enzyme formulations and wholesale milling cooperatives for commodity chemicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among retail baking cooperatives consolidating procurement authority, fragmenting supplier leverage across fragmented craft-industrial hybrid segments.
For Market Incumbents: Consolidate biotechnology R&D capability around cereal science expertise to defend against emerging fermentation-derived ingredient specialists. Deepen backward integration into captive enzyme production strains to offset margin pressure from EFSA-driven reformulation cycles. Lock in long-term offtake contracts with German retail cooperatives before procurement authority further centralizes.
For New Entrants and Emerging Players: FDA GRAS self-affirmation fast-tracks offer accelerated commercialization pathways relative to EFSA novel food timelines, opening white-space entry into US industrial baking corridors. Target Asian noodle manufacturers in Shandong and Henan provinces with specialized gluten-strengthening formulations diverging from Western baking specifications. Bind technical service to ingredient sales through application center investments to differentiate from commodity enzyme distributors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed enzyme engineering specialists holding cereal science talent pools in European biotechnology clusters. Five-to-ten year viability hinges on clean-label certification durability and regulatory divergence persistence between EFSA and FDA frameworks. Monitor pending EFSA enzyme novel food approval timelines as inflection indicators for formulation platform commercialization windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive enzyme production secures margin control against EFSA-driven supply disruptions. |
| Application Center Expansion | Technical service binding in Belgium and Germany defends against commodity enzyme suppliers. |
| Regulatory Fast-Track Certification | FDA GRAS self-affirmation accelerates US commercialization ahead of EFSA novel food timelines. |
| Asian Noodle Channel Development | Specialized gluten-strengthening formulations capture differentiated demand in Shandong processing clusters. |
| Clean-Label Platform Repositioning | Enzyme-based alternatives displace chemical oxidizers facing EFSA authorization sunsets. |
Research Methodology
Initial hypotheses were tested against primary input from milling operations managers, bakery procurement leads, enzyme R&D directors, and regulatory affairs specialists and refined through secondary validation against EFSA additive safety assessments, FDA GRAS notifications, EU enzyme regulation frameworks, and customs trade data. Bottom-up volume modeling triangulated with top-down value estimates across product type, application, end user, and distribution channel segmentation.
Variance decomposition isolates drivers across the projection horizon through multiplicative segmentation modeling. Product type splits across enzymes, oxidizing agents, reducing agents, and chemicals; application across baking, noodle production, pasta making, and confectionery; end user across food industry, bakeries, restaurants, and household; and distribution channel across direct sales, wholesale, retail, and online. CAGRs derive from segment-level growth rate reconciliation against macro wheat-processing capacity expansion. Forecast inputs incorporate EFSA authorization timeline probabilities and Asian wheat-based noodle capacity buildouts.
Decision-makers should treat outputs as directional under assumptions of sustained EFSA regulatory compression and stable wheat protein variability patterns; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in additive authorization protocols and regional procurement consolidation milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Instant Fat Powder Market
Food Additives and Ingredients
Australia Food Acidulants Market
Food Additives and Ingredients
North America Food Acidulants Market
Food Additives and Ingredients
Mexico Food Additives Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
Mexico Food Emulsifiers Market
Food Additives and Ingredients
Activated Cake Emulsifier Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Bakery Release Agents Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market