
 Asia-Pacific Hard Facility Management Market | 2026-2036
Asia-Pacific Hard Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hard Facility Management Market Outlook
Direct service channels between OEMs and end users is narrowing as integrated facility management providers consolidate technical control. Johnson Controls International leverages its building automation heritage to anchor premium maintenance contracts across East Asian commercial towers. Siemens AG competes through digital twin diagnostics, while CBRE Group Inc extends its brokerage relationships into long-term hard FM retainers.
Asia-Pacific Hard Facility Management encompasses the physical upkeep of building infrastructure, including HVAC systems, electrical distribution, plumbing networks, fire safety equipment, and structural elements, typically governed by asset lifecycle metrics such as mean time between failures and energy performance coefficients. Its primary purpose is ensuring operational continuity, regulatory compliance, and capital asset preservation across commercial and industrial property portfolios. Maintenance services dominate contract value due to recurring revenue structures, while IoT Solutions within the technology segment represent the fastest-expanding capability layer as predictive diagnostics displace scheduled interventions. Corporate Offices and Healthcare Facilities anchor end-user demand, though Manufacturing Units present higher-margin opportunities given specialized equipment uptime requirements.
Japan's METI enforces building energy codes that mandate periodic inspection and retrofit of HVAC and lighting systems, directly expanding technical service contracts. China's SAMR coordinates national GB standards for elevator safety and fire protection equipment, creating compliance-driven demand for certified maintenance providers. India's CEA electrical safety regulations and BIS energy labeling requirements compound inspection obligations across commercial stock. Stakeholders must weigh captive technical teams against outsourced specialization as regulatory inspection frequencies intensify and digital compliance reporting becomes mandatory.
Market Dynamics
Building automation convergence with predictive maintenance platforms is compressing service intervals and rewriting contract structures across Asia-Pacific commercial portfolios. OEMs now embed diagnostic sensors as standard, forcing independent facility managers to upgrade technical capabilities or cede high-value contracts to integrated providers.
Growth Catalysts
- China's SAMR elevator safety mandates:Mandatory inspection frequencies for aging vertical transportation stock in Shanghai and Beijing generate recurring certification revenue for qualified service providers.
- Healthcare infrastructure expansion:Southeast Asian hospital construction programs in Vietnam and Indonesia require specialized HVAC and medical gas system maintenance with 24/7 uptime guarantees.
- Digital twin deployment:Asset virtualization platforms enable remote diagnostics of electrical distribution networks, reducing emergency dispatch costs for portfolio operators.
Market Restraints
- Copper and rare-earth price volatility:Electrical component refurbishment costs fluctuate with commodity markets, squeezing fixed-price maintenance margins.
- Certified technician concentration:Japan and South Korea dominate the region's qualified elevator and fire safety inspector pool, creating cross-border labor dependency.
- Legacy building automation incompatibility:Proprietary protocols from 1990s installations block seamless IoT retrofit without complete control system replacement.
Strategic Opportunities
- India's BIS energy-efficiency compliance:Commercial buildings in Mumbai and Delhi face mandatory HVAC retrofit deadlines, opening audit-to-execution service bundling.
- Pharmaceutical manufacturing clusters:Cleanroom validation and specialized air handling maintenance in Singapore and Hyderabad command premium pricing.
- Performance-based contracting:Energy savings guarantees displace time-and-materials billing for mechanical services in Australian and Japanese commercial towers.
Industry Challenges
- Building management system integration complexity:Merging BACnet, Modbus, and proprietary OEM protocols demands scarce controls engineering expertise.
- Fire safety certification backlogs:Australia's state-level inspector accreditation queues delay contract commencement for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hard Facility Management Market |
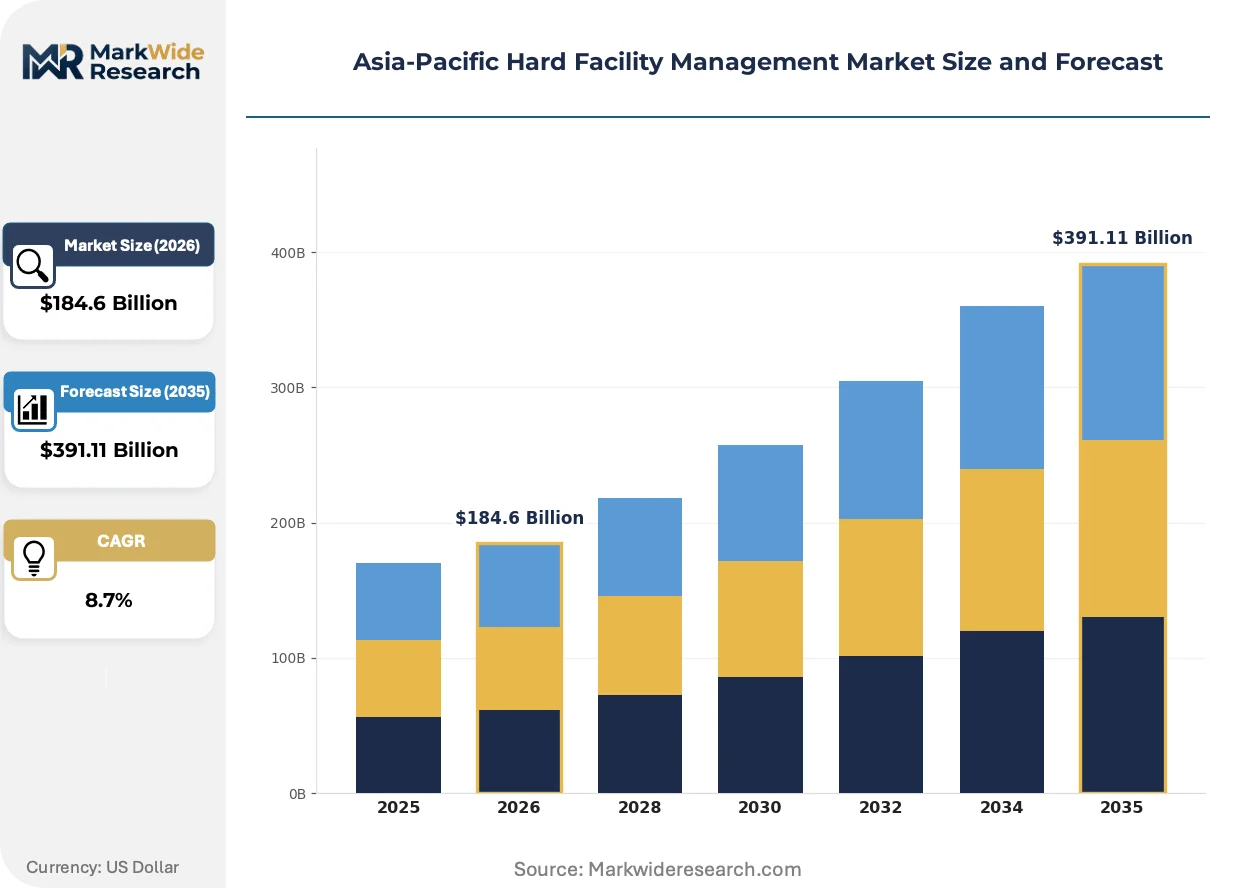
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $391.11 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Repair, Renovation, Operations Technology: IoT Solutions, Cloud Computing, CMS, AI Applications End User: Manufacturing Units, Educational Institutions, Corporate Offices, Healthcare Facilities Contract Type: Fixed Price, Time and Materials, Cost Plus, Turnkey |
| Companies Covered | Johnson Controls International, Honeywell International Inc., Jones Lang LaSalle Incorporated (JLL), Aden Group, Fujitsu Limited, Sodexo S.A., Siemens AG, Volvo CE, CBRE Group Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hard Facility Management Market Strategic Shifts
Predictive analytics platforms are resequencing maintenance workflows from calendar-based to condition-triggered interventions. Three interconnected developments are compressing traditional service models and elevating technical capability requirements.
Edge computing for vibration analysis is migrating from scheduled manual readings to continuous automated monitoring. Manufacturing facilities in South Korea and Thailand deploy wireless sensors on critical rotating equipment, enabling failure prediction 48-72 hours before breakdown. This capability is migrating from capital-intensive process industries to mid-sized commercial portfolios as sensor costs decline.
Japan's METI building energy codes now mandate periodic HVAC and lighting system inspection with digital reporting submission. Facility managers in Osaka and Tokyo must upgrade documentation systems to comply with centralized compliance databases. Commercial office landlords respond by consolidating mechanical maintenance under single providers capable of automated regulatory filing.
Integrated service agreements now bundle energy performance guarantees with traditional upkeep obligations. Australian and Singaporean commercial property funds negotiate contracts where providers absorb utility cost variance risk. This structure concentrates contract value with technically capable operators while marginalizing pure maintenance vendors lacking engineering design competency.
Asia-Pacific Hard Facility Management Market Segmentation
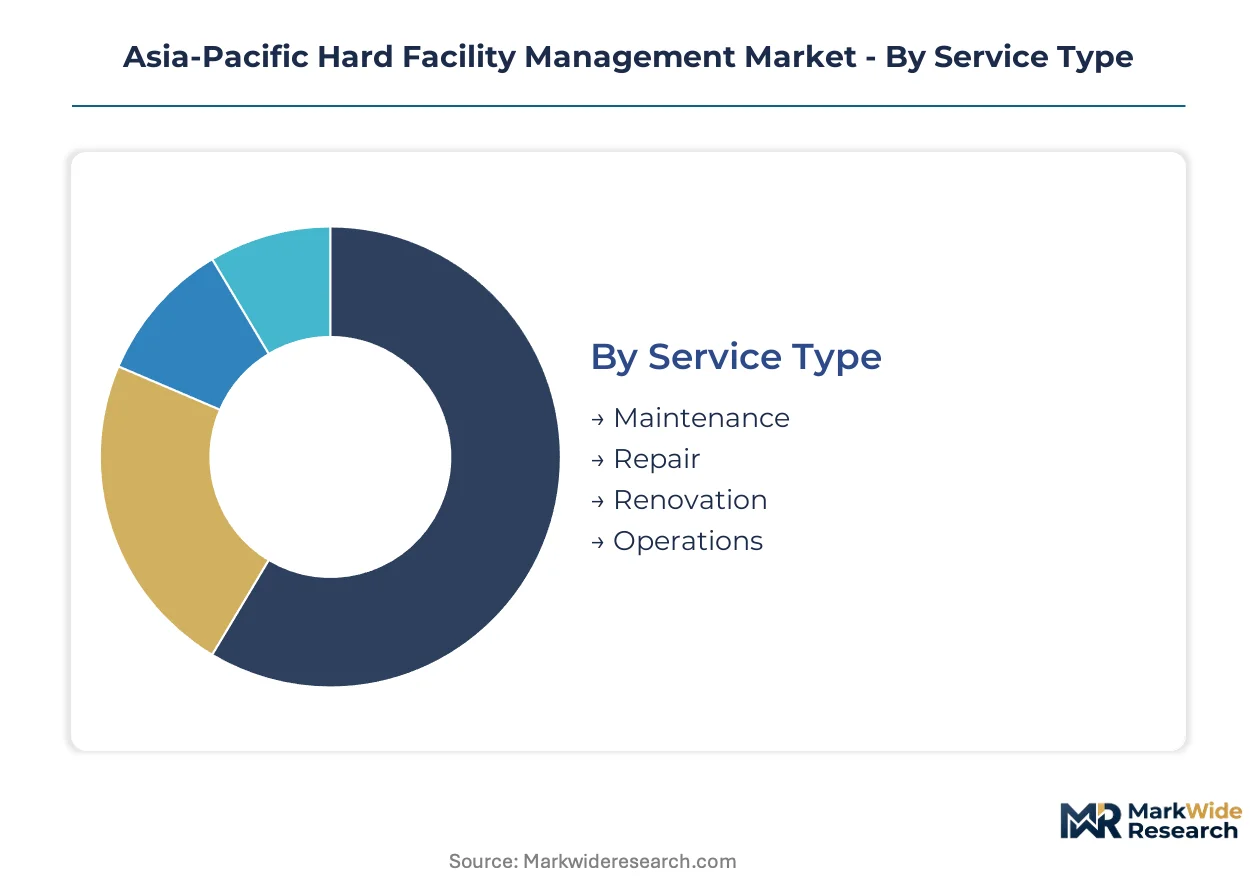
Hard facility management contracts fragment across service intensity, technical sophistication, and risk allocation models. Each segmentation axis reveals distinct margin profiles and capability requirements that reshape competitive positioning across Asia-Pacific commercial portfolios.
Service Type:
Maintenance cycles compress fastest where regulatory inspection mandates intensify, while renovation and capital projects turn over slowest with multi-year procurement horizons.
- Maintenance:Recurring technical services covering HVAC, electrical, and mechanical systems governed by mean time between failure metrics. Demand concentrates in China's tier-one cities where SAMR elevator safety mandates and aging commercial stock force intensive refurbishment schedules.
- Repair:Reactive interventions restoring failed building systems to operational status. Healthcare facilities in Vietnam and Indonesia drive emergency response requirements with 24/7 uptime guarantees for critical care infrastructure.
- Renovation:Capital-intensive building system overhauls extending asset lifecycle. India's BIS energy-efficiency compliance deadlines for Mumbai and Delhi commercial stock accelerate HVAC retrofit procurement.
- Operations:Continuous facility oversight integrating technical staffing with energy management. Australian and Japanese commercial property funds adopt performance-based structures where providers absorb utility cost variance risk.
Maintenance dominates installed base. Repair is where expansion concentrates.
Technology:
Capability investment stratifies sharply between established digital infrastructure and emerging diagnostic layers requiring specialized engineering talent.
- IoT Solutions:Wireless sensor networks enabling continuous equipment monitoring and automated fault detection. South Korean and Thai manufacturing facilities deploy vibration analysis sensors predicting rotating equipment failure 48-72 hours before breakdown.
- Cloud Computing:Centralized data platforms aggregating building performance metrics across distributed portfolios. Singaporean commercial property funds leverage remote diagnostics to reduce emergency dispatch costs for electrical distribution networks.
- CMS:Computerized maintenance management systems scheduling work orders and tracking asset histories. Osaka and Tokyo facility managers upgrade documentation systems to comply with METI-mandated digital regulatory filing.
- AI Applications:Machine learning models optimizing energy consumption and predicting system degradation. Pharmaceutical cleanroom operations in Hyderabad command premium pricing for specialized air handling validation.
CMS anchors legacy installed base. IoT Solutions is climbing the fastest.
End User:
Technical complexity and uptime criticality create divergent margin profiles across facility categories.
- Corporate Offices:Standardized mechanical and electrical maintenance across commercial tower portfolios. Shanghai and Beijing landlords consolidate technical control under single providers capable of automated compliance reporting.
- Healthcare Facilities:Specialized HVAC, medical gas, and fire safety systems demanding continuous certification. Southeast Asian hospital construction programs in Vietnam and Indonesia require 24/7 technical coverage with guaranteed response times.
- Manufacturing Units:Process-critical equipment maintenance with uptime penalties for production interruption. Cleanroom validation in Singapore commands premium pricing given specialized air handling requirements.
- Educational Institutions:Seasonal occupancy patterns and deferred maintenance backlogs characterizing public sector procurement. Indian state universities face BIS energy labeling compliance gaps in aging laboratory infrastructure.
Corporate Offices dominate contract volume. Healthcare Facilities is where margin expansion concentrates.
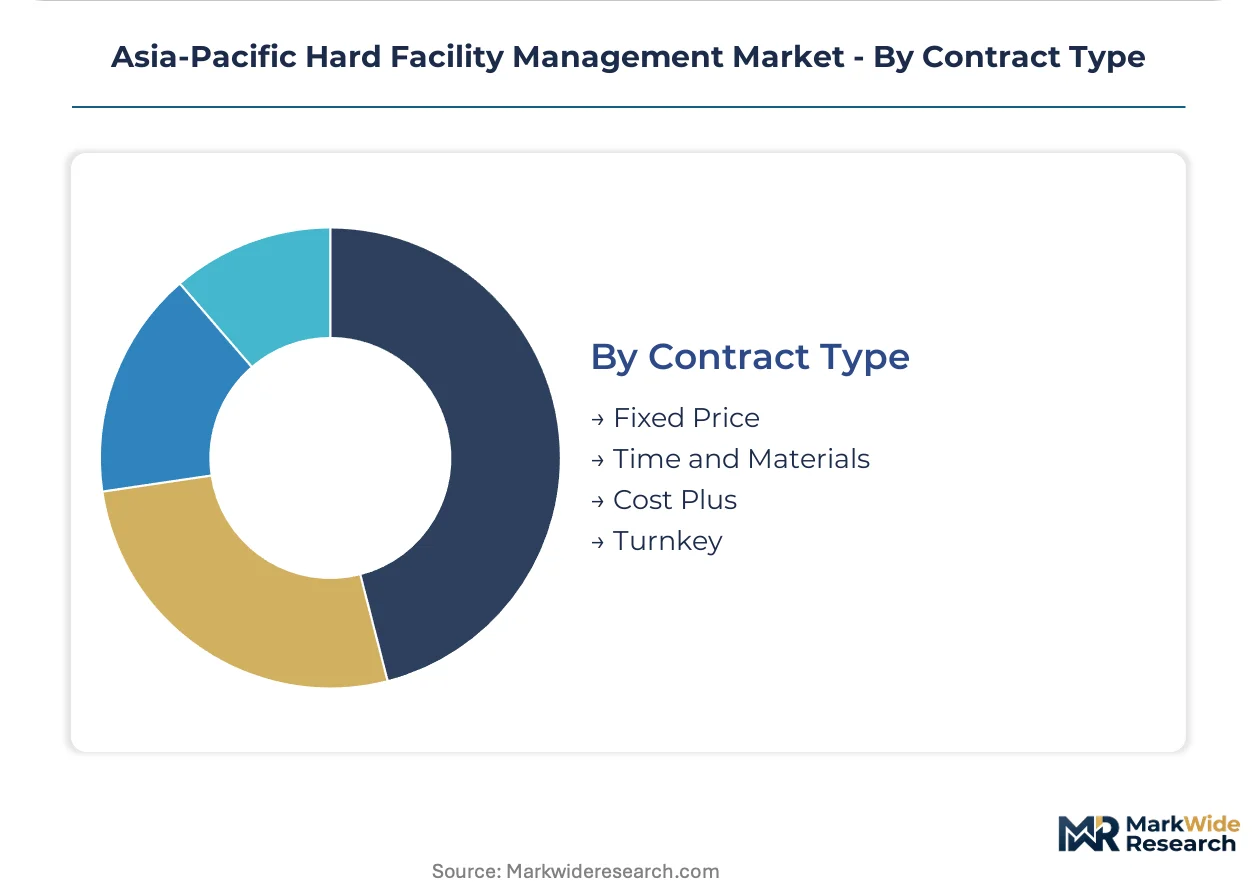
Contract Type:
Risk transfer mechanisms reshape provider economics and technical capability requirements across procurement structures.
- Fixed Price:Predetermined scope and pricing with provider absorbing cost overrun risk. Australian commercial towers adopt energy savings guarantees displacing time-and-materials billing for mechanical services.
- Time and Materials:Labor and material costs passed through with markup. Legacy agreements persist where asset condition uncertainty prevents accurate scope definition.
- Cost Plus:Reimbursement of actual costs plus fixed fee for contractor margin. Renovation projects with hidden condition risks default to this structure.
- Turnkey:Single-source responsibility for design, execution, and commissioning. India's BIS-mandated HVAC retrofits open audit-to-execution service bundling opportunities.
Time and Materials dominates legacy relationships. Fixed Price is where contract innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium service pricing concentrates in Singapore and Australia, where performance-based contracts absorb energy cost risk. Chinese and Indian markets compete on volume, compressing margins for standardized maintenance. Southeast Asian healthcare expansion creates intermediate pricing tiers for specialized technical coverage.
China
Shanghai and Beijing commercial towers drive elevator refurbishment demand under SAMR safety mandates. GB standards for fire protection equipment require certified inspection frequencies that expand technical service contracts. Tier-one city landlords consolidate mechanical maintenance under single providers capable of automated compliance reporting.
Japan
Osaka and Tokyo facility managers face METI-mandated HVAC and lighting system inspections with digital submission requirements. Aging commercial stock in Kansai and Kanto regions intensifies predictive maintenance adoption. Building automation convergence compresses service intervals for legacy mechanical systems.
India
Mumbai and Delhi commercial buildings face BIS energy-efficiency compliance deadlines for HVAC retrofit procurement. CEA electrical safety regulations compound inspection obligations across aging commercial stock. Hyderabad pharmaceutical manufacturing clusters command premium pricing for cleanroom validation services.
Australia
Sydney and Melbourne commercial property funds negotiate performance-based contracts where providers absorb utility cost variance risk. State-level fire safety inspector accreditation queues delay contract commencement for new market entrants. Energy savings guarantees displace time-and-materials billing for mechanical services.
South Korea
Seoul Capital Area manufacturing facilities deploy wireless vibration sensors predicting rotating equipment failure 48-72 hours before breakdown. MFDS-aligned healthcare facility standards expand specialized maintenance requirements for medical gas systems. Busan-Ulsan industrial corridors concentrate certified technician pools for cross-border service deployment.
Asia-Pacific Hard Facility Management Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fragmented niches. The Asia-Pacific Hard Facility Management market consolidates around integrated facility management providers with building automation heritage, while independent mechanical contractors compete on localized response speed. Three archetypes dominate: OEM-anchored service platforms, brokerage-extended FM operators, and regional specialist consolidators. M&A activity concentrates technical capability acquisition, and strategic partnerships bridge protocol incompatibility gaps in legacy building automation retrofits.
Within the OEM-anchored tier, Johnson Controls International and Siemens AG exemplify platform integrators leveraging automation heritage into premium maintenance retainers. CBRE Group Inc occupies a position among brokerage-extended operators translating property management relationships into long-term technical service contracts. These three represent distinct archetypes: building technology origin, real estate services extension, and integrated engineering capability.
| Leading Market Players |
|---|
| Johnson Controls International |
| Honeywell International Inc. |
| Jones Lang LaSalle Incorporated (JLL) |
| Aden Group |
| Fujitsu Limited |
| Sodexo S.A. |
| Siemens AG |
| Volvo CE |
| CBRE Group Inc |
| Others |
Value Chain & Pricing Dynamics
Copper and rare-earth price volatility determines both pricing tier spreads and supply chain shape across Asia-Pacific hard facility management. Certified technician concentration in Japan and South Korea creates geographic dependency that amplifies cost variance for electrical component refurbishment and elevator safety inspection services.
Pricing Analysis
Configured-to-order pricing for specialized cleanroom validation and medical gas system maintenance commands substantial premiums over standardized HVAC maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical manufacturing clusters in Singapore from mid-market commercial towers in China's tier-two cities. Cost compression in the standard tier is intensifying because fixed-price energy performance guarantees displace time-and-materials billing. Corporate office landlords in Shanghai and Beijing demonstrate highest price sensitivity, while healthcare facilities in Vietnam and Indonesia absorb premium pricing for guaranteed uptime coverage.
Supply Chain Analysis
Contract manufacturing concentration for building automation controllers and IoT sensor hardware rests with electronics manufacturing service providers in Taiwan, South Korea, and coastal China. Component sourcing draws from Malaysian rare-earth processing facilities, Australian copper smelters, and Japanese precision actuator manufacturers. Single-source vulnerability concentrates in proprietary BACnet and Modbus protocol licensing from dominant controls engineering houses. Distribution runs through integrated facility management providers that consolidate technical procurement across multi-site commercial portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific hard facility management sits at a high-growth disruption driven by METI-mandated digital compliance reporting and predictive maintenance platform convergence.
For Market Incumbents: Entrench building automation heritage through exclusive sensor-embedded OEM partnerships that lock out independent facility managers from high-value predictive diagnostics contracts. Deepen upstream control over certified technician training pipelines in Japan and South Korea to defend against cross-border labor poaching. METI inspection frequency escalation threatens margin compression for providers lacking automated regulatory filing capabilities.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given fragmented incumbent presence and accelerating BIS compliance deadlines. India's state university laboratory infrastructure presents audit-to-execution bundling opportunities where aging BIS energy labeling gaps create immediate retrofit demand. Lead with cloud-based CMS platforms that undercut legacy documentation system upgrade costs for Osaka and Tokyo facility managers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated engineering capability over pure maintenance vendors lacking digital twin deployment competency. Acquisition targets should demonstrate proven pharmaceutical cleanroom validation credentials or established SAMR elevator safety certification relationships. Watch for SAMR inspection frequency expansion beyond tier-one cities as the inflection signal for scalable contract value concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Building Automation Platform Integration | Johnson Controls and Siemens leverage sensor-embedded diagnostics to anchor premium maintenance retainers across East Asian commercial towers. |
| Certified Technician Training Pipeline Expansion | Busan-Ulsan industrial corridors feed cross-border deployment capacity for elevator and fire safety inspection backlogs in Australia and Southeast Asia. |
| Performance-Based Contracting Transition | Australian commercial property funds shift utility cost variance risk to providers with engineering design competency, marginalizing pure maintenance vendors. |
| Regulatory Compliance Automation Investment | Osaka and Tokyo facility managers upgrade documentation systems to satisfy METI-mandated digital filing requirements for HVAC and lighting inspections. |
| Healthcare Infrastructure Specialization | Vietnam and Indonesia hospital construction programs demand 24/7 technical coverage with guaranteed response times for medical gas and critical care systems. |
Study Parameters
Initial hypotheses were tested against primary input from facility management executives, building automation engineers, healthcare infrastructure procurement managers, and commercial property fund asset directors and refined through secondary validation. Bottom-up contract value analysis triangulated with top-down market sizing drew from SAMR regulatory filings, METI compliance database disclosures, BIS energy labeling records, and CBRE Group property management contract announcements.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed service intensity tiers, technology deployment sophistication, end-user uptime criticality, and regional regulatory enforcement patterns. CAGRs were derived from installed base turnover rates and compliance-driven contract expansion trajectories. Forecast inputs incorporated elevator safety mandate rollout schedules and pharmaceutical manufacturing cluster development pipelines.
Practitioners should monitor rare-earth price indices and SAMR inspection frequency expansion announcements for early signals of margin compression or contract value migration. Quarterly review of certified technician visa policy changes and BIS retrofit deadline enforcement intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Hong Kong Facility Management Market
Facility Management
Middle East and Africa Facility Management Market
Facility Management
Czech Republic Facility Management Market
Facility Management
United Arab Emirates Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Chile Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
New Zealand Facility Management Market
Facility Management
Luxembourg Facility Management Market
Facility Management
Europe Soft Facility Management Market
Facility Management
Middle East and Africa Hard Facility Management Market
Facility Management
Cold Storage Warehouse Market
Facility Management
Sweden Facility Management Market
Facility Management
Indonesia Facility Management Market
Facility Management
Qatar Facility Management Market
Facility Management
UK Facility Management Market