
 Germany EV Battery Pack Market | 2026-2036
Germany EV Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Germany EV Battery Pack Market Insights
Modular pack architectures with swappable cell modules is expanding buyer choice across German EV platforms. CATL leverages its Erfurt gigafactory output to anchor supply contracts with domestic OEMs. LG Energy Solution sustains R&D intensity on nickel-rich cathode formulations for extended-range configurations. Samsung SDI competes through prismatic cell designs optimized for German premium vehicle thermal envelopes.
A Germany EV battery pack is an integrated electromechanical assembly housing lithium-ion cells, thermal management circuits, and battery management electronics within a structural enclosure rated for automotive crash loads and IP67 ingress protection. Its primary purpose is to store and deliver direct-current energy to electric drivetrains while maintaining cell longevity through active temperature regulation. Lithium-ion chemistries dominate current production scale, though solid-state prototypes are attracting capital as manufacturers seek higher energy density without flammable liquid electrolytes. Fast charging technology leads infrastructure-linked demand, while battery management systems concentrate margin pools through software-defined performance optimization and warranty risk reduction.
KBA type-approval requirements, EU Battery Regulation due diligence rules, and REACH chemical compliance frameworks collectively shape cell sourcing protocols and recyclability mandates for German pack assemblers. The EU AI Act adds emerging conformity obligations for autonomous battery diagnostics embedded in management system firmware. Stakeholders must monitor how carbon border adjustments on imported cathode materials reshape total cost of ownership for domestically assembled versus imported packs.
Market Dynamics
Cell-to-pack architectures are compressing module assembly steps and redistributing value capture toward cell producers with direct OEM relationships. This structural shift concentrates procurement leverage around Stuttgart, Wolfsburg, and Munich production corridors while marginalizing independent pack integrators.
Growth Catalysts
- EU Green Deal CO2 Fleet Standards:Phased emissions mandates force German OEMs to electrify passenger vehicle portfolios, creating binding procurement commitments for high-voltage battery systems through 2035.
- Fast Charging Infrastructure:800V platform proliferation across German premium EV architectures concentrates demand on thermal management solutions capable of sustained high-current throughput.
- Bavaria-Saxony Production Corridor:CATL's Erfurt gigafactory anchors localized cell supply, reducing logistics exposure and qualifying output for EU Battery Regulation carbon footprint thresholds.
Market Restraints
- Cathode Material Cost Volatility:Nickel and cobalt price swings transmit directly to pack bill-of-materials, compressing assembler margins when long-term OEM contracts fix pricing.
- Asian Cell Supply Concentration:Korean and Chinese producers control over 70% of prismatic and cylindrical cell capacity, creating single-source vulnerability for German pack assemblers.
- REACH Chemical Compliance:Restrictions on fluorinated electrolyte additives and conflict mineral due diligence extend qualification timelines for new cell chemistries.
Strategic Opportunities
- Solid-State Prototype Scale-Up:BMW's Munich pilot line and Volkswagen's partnerships with QuantumScape position German OEMs to capture first-mover advantage as solid electrolytes mature.
- Second-Life Stationary Storage:Retired automotive packs from Berlin and Hamburg fleets feed grid-balancing installations, extending value extraction before recycling.
- Battery Pass Digital Product Passport:EU Battery Regulation mandates create service revenue pools for German software vendors verifying carbon intensity and material provenance across supply chains.
Industry Challenges
- Thermal Engineering Talent Scarcity:Cell-to-pack designs demand specialists fluent in both electrochemistry and vehicle crash simulation, a skill intersection scarce in German labor markets.
- KBA Type-Approval Timelines:Revised UN ECE R100 testing protocols for thermal runaway propagation extend homologation cycles, delaying platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany EV Battery Pack Market |
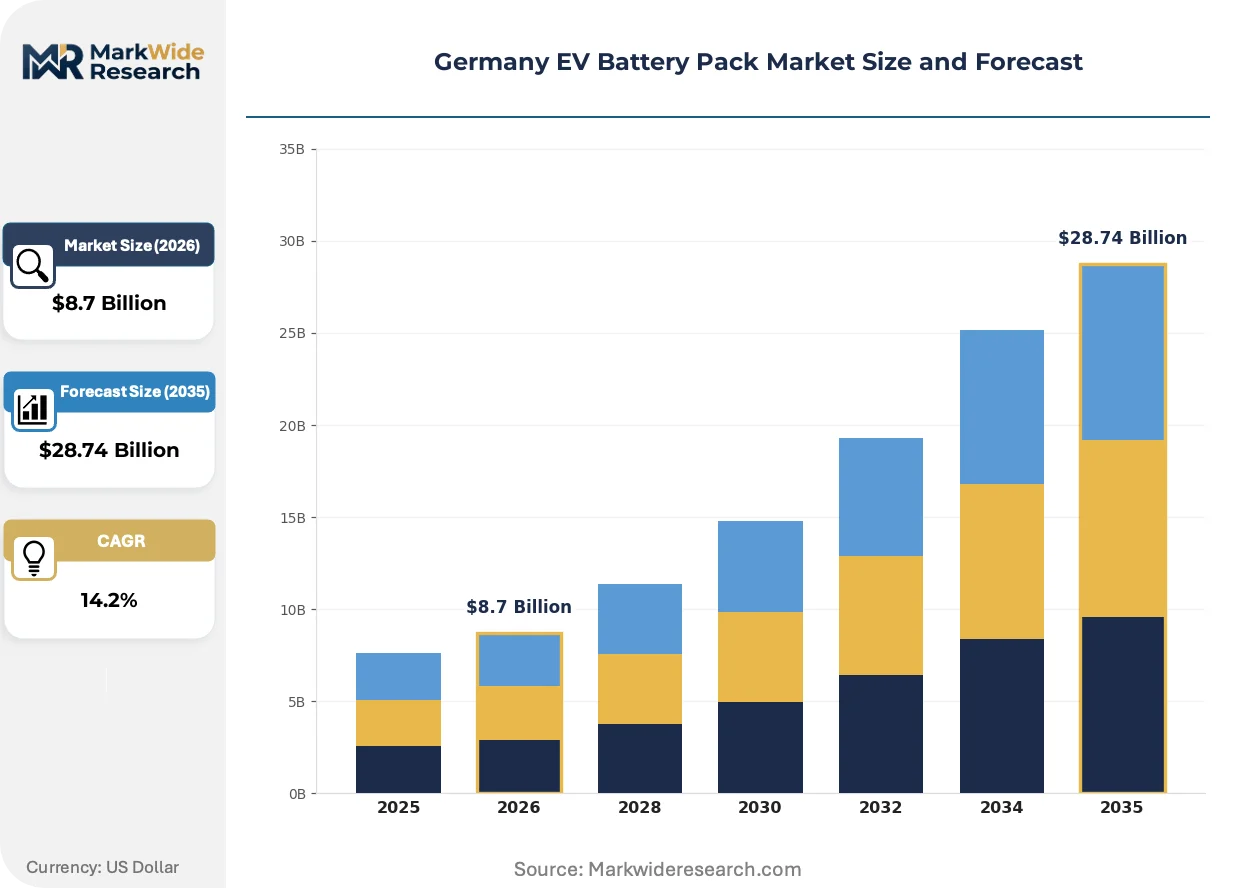
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Solid State, Nickel Metal Hydride, Lead Acid End User: Passenger Vehicles, Commercial Vehicles, E-Bikes, Industrial Equipment Technology: Fast Charging, Wireless Charging, Regenerative Braking, Battery Management Systems Application: Automotive, Energy Storage Systems, Grid Stability, Marine |
| Companies Covered | CATL, LG Energy Solution, Samsung SDI, Northvolt, Automotive Cells Company, BMZ Group, Akasol, VARTA, PowerCo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany EV Battery Pack Market Trends and Innovations
Software-defined battery management is displacing hardware-centric architectures, enabling remote performance optimization and warranty risk transfer to cloud-based analytics providers. This convergence reshapes competitive differentiation toward firmware capabilities and data infrastructure ownership.
Cell-to-pack structural battery technology is automating module elimination by bonding cells directly to vehicle floor pans, replacing discrete pack enclosures with crash-rated cell housings. German OEMs adopting this approach for 2027 platform launches compress assembly labor content by 40% while redistributing structural validation liability toward cell suppliers. The technology is automating tier-one supplier consolidation as integrators without cell manufacturing capabilities lose design-in access.
The EU AI Act imposes conformity assessment obligations on autonomous battery diagnostics embedded in management system firmware. German pack assemblers must now document algorithmic decision pathways for thermal runaway prediction models, adding software validation costs but creating differentiation for vendors with pre-certified architectures. Premium EV platforms in Stuttgart and Munich face earliest enforcement timelines due to autonomous driving feature bundling.
Fleet operators in Berlin and Hamburg are consolidating procurement through battery-as-a-service contracts, unbundling capital expenditure from vehicle acquisition. This model transfers residual value risk to financial intermediaries and cell manufacturers, compressing direct OEM pack sales while expanding long-term service revenue pools. German municipal transit authorities lead this shift, followed by commercial logistics operators seeking balance sheet optimization.
Germany EV Battery Pack Market Segmentation
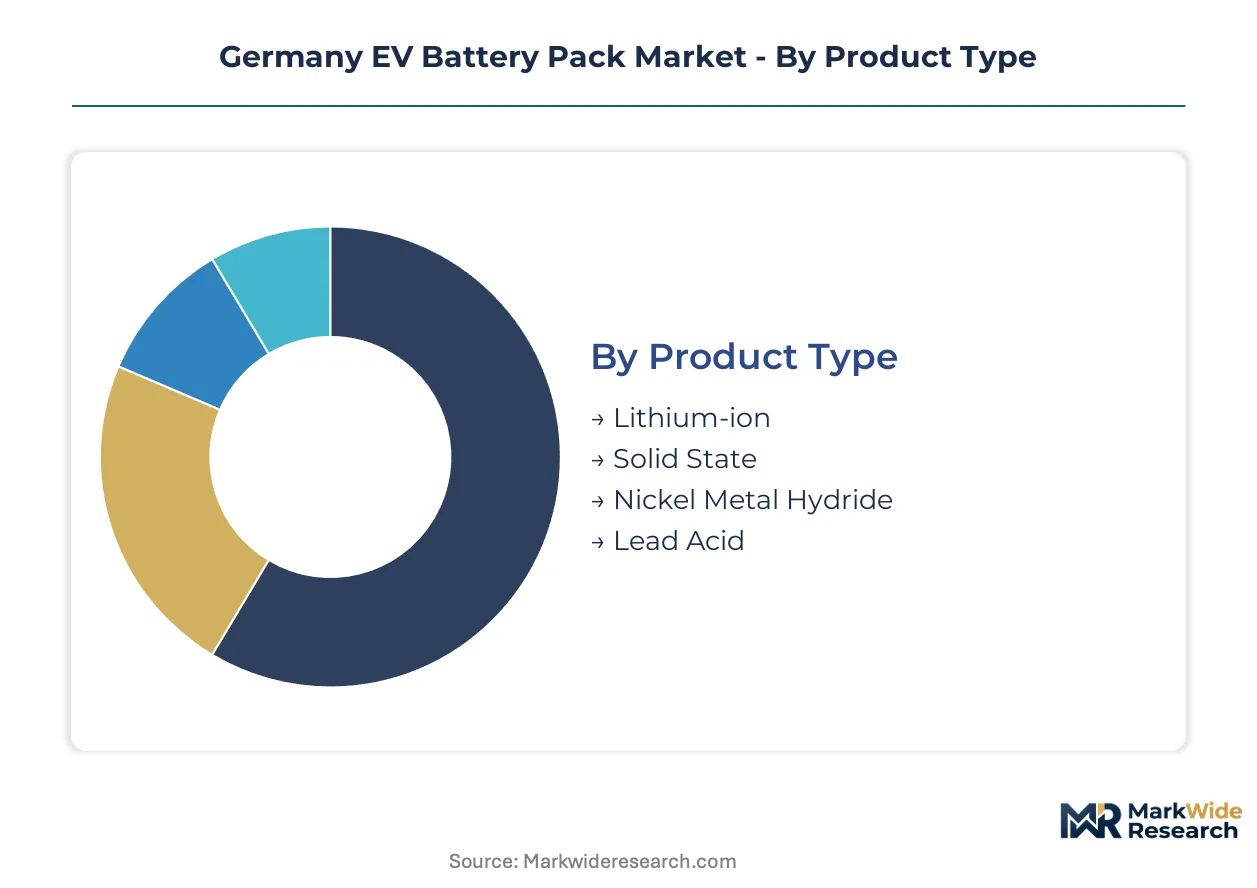
German OEM procurement patterns concentrate value capture around specific chemistries and charging architectures. Segmentation reveals how cell-to-pack integration is redistributing competitive advantage across product categories and end-use applications.
Product Type:
Cell chemistry supply concentrates around Asian producers with direct Erfurt corridor access, compressing margins for independent German pack integrators lacking captive cell capacity.
- Lithium-ion:NMC and LFP formulations dominate current German EV platform qualifications. Stuttgart and Wolfsburg production corridors anchor demand for nickel-rich configurations supporting 800V architectures.
- Solid State:Sulfide-based electrolyte prototypes under BMW Munich pilot line evaluation promise energy density gains without flammable liquid components. QuantumScape partnerships position Volkswagen for first-mover qualification timelines.
- Nickel Metal Hydride:Legacy hybrid applications in compact urban delivery vehicles retain niche procurement volumes.
- Lead Acid:Auxiliary 12V systems in commercial vehicle starter circuits sustain residual demand outside traction power applications.
Lithium-ion absorbs the bulk of installed capacity; solid state is expanding most quickly.
End User:
Passenger vehicle procurement volumes determine tier-one supplier consolidation patterns, with commercial fleet operators unbundling capital expenditure through battery-as-a-service structures.
- Passenger Vehicles:Premium platform architectures from Stuttgart and Munich concentrate demand for cell-to-pack thermal management solutions. KBA type-approval timelines extend homologation cycles for new entrant suppliers.
- Commercial Vehicles:Berlin and Hamburg municipal transit authorities consolidate procurement through service contracts transferring residual value risk. Logistics operators seek balance sheet optimization through unbundled battery financing.
- E-Bikes:Compact pack formats for last-mile delivery fleets in urban centers drive localized assembly demand.
- Industrial Equipment:Forklift and warehouse automation applications sustain niche demand for standardized cell modules.
Passenger vehicles command the dominant share of cell procurement; commercial vehicles are climbing the fastest as fleet electrification accelerates.
Technology:
Software-defined architectures are displacing hardware-centric designs, redistributing margin pools toward firmware providers with pre-certified EU AI Act compliance pathways.
- Fast Charging:800V platform proliferation demands thermal management circuits capable of sustained high-current throughput. German premium OEMs specify liquid-cooled busbars and predictive temperature algorithms.
- Wireless Charging:Inductive pad systems for autonomous taxi fleets in Munich pilot zones attract capital for infrastructure-linked revenue models.
- Regenerative Braking:Bidirectional power electronics integration captures kinetic energy recovery for extended-range configurations.
- Battery Management Systems:Cloud-based analytics providers extract warranty risk reduction value through remote performance optimization algorithms.
Battery management systems capture the deepest margin pools; fast charging infrastructure is gaining share fastest as platform voltages escalate.
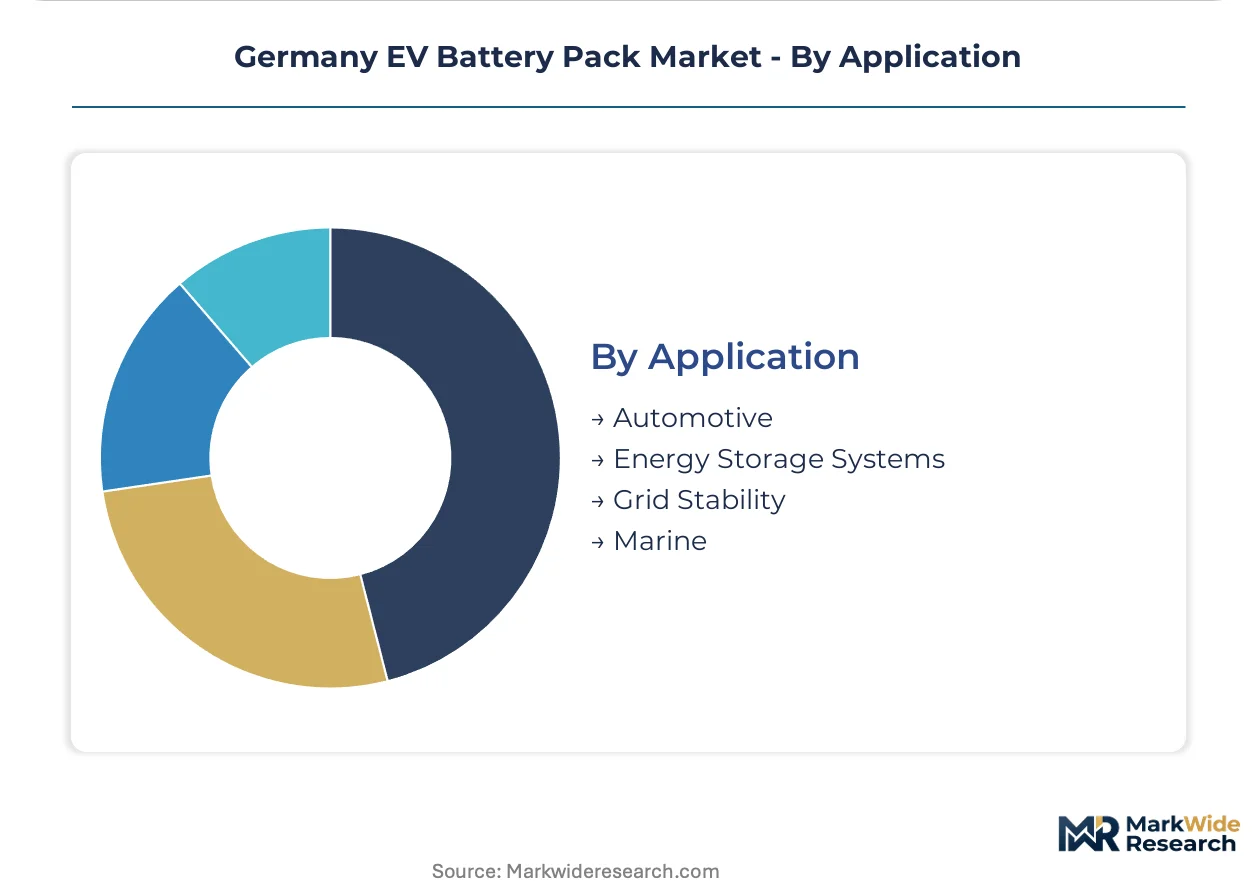
Application:
Automotive qualification requirements create the steepest entry barriers, while stationary energy storage opens alternative revenue streams for retired pack assets.
- Automotive:Crash-rated enclosures with IP67 ingress protection and UN ECE R100 thermal runaway compliance anchor German OEM specification sheets. Cell-to-pack bonding eliminates discrete module assembly steps.
- Energy Storage Systems:Second-life installations from Berlin and Hamburg retired fleets feed grid-balancing revenue pools before recycling.
- Grid Stability:Frequency regulation contracts for aggregated automotive pack assets create utility-facing revenue streams.
- Marine:Inland waterway electrification projects on Rhine corridors sustain niche demand for saltwater-resistant enclosure designs.
Automotive applications absorb the dominant share of engineering resources; energy storage systems are expanding most quickly as fleet retirement volumes accumulate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones along Germany's automotive production corridors concentrate cell-to-pack assembly capacity. The EU Green Deal's phased CO2 fleet standards bind OEM procurement commitments through 2035. KBA type-approval requirements and EU Battery Regulation carbon footprint thresholds reshape sourcing protocols across sub-regional manufacturing clusters.
Bavaria
Munich anchors BMW's solid-state pilot line evaluation and premium EV platform development. The EU AI Act imposes conformity obligations on autonomous battery diagnostics embedded in management system firmware. BMW's Munich engineering center concentrates thermal runaway prediction algorithm development for 2027 platform launches.
Baden-Württemberg
Stuttgart production corridors concentrate demand for nickel-rich NMC configurations supporting 800V architectures. REACH chemical compliance restrictions on fluorinated electrolyte additives extend qualification timelines for new cell chemistries. Mercedes-Benz's Sindelfingen plant integrates cell-to-pack bonding for EQS and EQE platform assembly.
Lower Saxony
Wolfsburg anchors Volkswagen's PowerCo cell manufacturing partnerships and QuantumScape solid-state development. The EU Battery Regulation's due diligence rules reshape cathode material sourcing protocols for domestically assembled packs. Volkswagen's Salzgitter cell factory concentrates prismatic cell output for MEB platform variants.
Thuringia
Erfurt hosts CATL's gigafactory output anchoring localized supply contracts with domestic OEMs. EU Battery Regulation carbon footprint thresholds qualify Erfurt-produced cells for domestic OEM procurement. The Thuringian production corridor reduces logistics exposure for Stuttgart and Munich assembly plants.
Berlin-Brandenburg
Berlin municipal transit authorities consolidate procurement through battery-as-a-service contracts transferring residual value risk. KBA type-approval timelines for revised UN ECE R100 thermal runaway propagation protocols extend homologation cycles. Tesla's Grünheide facility concentrates 4680 cell production for Model Y platform supply.
Germany EV Battery Pack Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across German EV battery pack assembly. The market structure concentrates procurement leverage around cell producers with direct OEM relationships while marginalizing independent pack integrators. Three archetypes dominate: Asian cell giants with European manufacturing footprints, European challengers building domestic gigafactory capacity, and German system integrators lacking captive cell production. Strategic moves center on backward integration into cathode material supply and technology licensing partnerships for solid-state electrolyte formulations.
Among Asian manufacturers with European production presence, CATL, LG Energy Solution, and Samsung SDI exemplify the scale-driven archetype. CATL occupies a position as the anchor tenant in Germany's Erfurt corridor. LG Energy Solution represents sustained R&D intensity on advanced cathode formulations. Samsung SDI sits within the prismatic cell specialization tier serving German premium thermal envelope requirements.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Samsung SDI |
| Northvolt |
| Automotive Cells Company |
| BMZ Group |
| Akasol |
| VARTA |
| PowerCo |
| Others |
Pricing and Supply Chain Analysis
Captive cell production by Asian manufacturers anchors both supply security and pricing leverage for German OEM procurement. CATL's Erfurt gigafactory, LG Energy Solution's R&D intensity, and Samsung SDI's prismatic specialization concentrate upstream control while compressing margins for independent pack integrators lacking in-house cell capacity.
Pricing Analysis
Premium pricing attaches to cells qualifying under EU Battery Regulation carbon footprint thresholds with sub-90-day lead times, while spot-market inventory from non-compliant sources trades at discounts. Contract-based long-term offtake dominates procurement structures, with price differentiation hinging on volume scale and REACH certification tier. Pricing pressure intensifies in standard-grade NMC configurations as Korean and Chinese producers expand Erfurt corridor capacity. Fleet operators exhibit highest price sensitivity through battery-as-a-service unbundling, whereas premium OEMs prioritize thermal envelope performance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Stuttgart, Wolfsburg, and Munich production corridors, bypassing independent distributors. Cathode material supply concentrates in China, Indonesia, and the Democratic Republic of Congo for nickel and cobalt feedstocks. German pack assemblers draw from Korean and Japanese precursor chemical suppliers for electrolyte formulations. Single-source vulnerability pervades prismatic cell procurement, with over 70% of capacity controlled by CATL, LG Energy Solution, and Samsung SDI. Distribution runs through just-in-time corridors linking Erfurt to Bavarian and Baden-Württemberg assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into cathode material supply and solid-state electrolyte partnerships constitutes the defining competitive race. Players securing upstream control over nickel refining and sulfide-based electrolyte formulations capture structural margin pools.
For Market Incumbents: Hedge against Asian cell supply concentration by qualifying secondary cell sources from Northvolt's Skellefteå expansion and Automotive Cells Company's French gigafactory ramp. Secure long-term offtake agreements with Indonesian nickel processors to reduce cathode cost volatility exposure. Invest in KBA pre-certification for thermal runaway propagation protocols to compress homologation timelines for 2027 platform launches.
For New Entrants and Emerging Players: Launch via battery-as-a-service contracts targeting Berlin and Hamburg municipal transit authorities, where procurement consolidation creates white-space for financial intermediaries unbundling capital expenditure. Target second-life stationary storage applications for retired automotive packs, where grid-balancing revenue pools remain underdeveloped. Pursue EU Battery Regulation compliance software as a service entry point, verifying carbon intensity and material provenance for mid-tier pack assemblers.
For Investors and Strategic Acquirers: Exit pathways concentrate in solid-state technology licensing and battery management system firmware acquisitions, with BMW's Munich pilot line and QuantumScape partnerships signaling first-mover qualification timelines. Long-term viability favors targets with captive thermal engineering talent and pre-certified EU AI Act algorithmic decision pathways. Watch for inflection in KBA type-approval velocity as indicator of platform launch cadence and cell procurement volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Adoption | BMW's Munich engineering center bonds cells directly to vehicle floor pans, eliminating module assembly labor. |
| EU Battery Regulation Compliance Investment | Carbon footprint threshold qualification secures OEM procurement preference under due diligence rules. |
| Solid-State Electrolyte Partnership | Volkswagen's QuantumScape collaboration positions for first-mover energy density gains without liquid electrolytes. |
| Battery-as-a-Service Platform Launch | Berlin municipal transit contracts transfer residual value risk from fleet operators to financial intermediaries. |
| Thermal Engineering Talent Acquisition | Scarcity of electrochemistry and crash simulation specialists concentrates in Stuttgart and Munich corridors. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, KBA homologation specialists, and cathode material traders underwrites the qualitative findings. Primary interviews with thermal management circuit designers and battery management system firmware architects combined with secondary validation from EU Battery Regulation implementation guidance, REACH chemical restriction updates, UN ECE R100 testing protocol revisions, and IHS Markit vehicle production databases. Bottom-up cell procurement volume estimates triangulate against top-down OEM electrification commitment disclosures.
Comparable-period anchoring to historical EU CO2 fleet standard compliance phases and preceding platform launch cycles structures the projection horizon. Segmentation modeling spans cell chemistry tier, vehicle class, charging architecture voltage, and regional production cluster. CAGRs derive from installed capacity buildout trajectories and OEM procurement commitment visibility. Forecast inputs incorporate cell-to-pack adoption curves, solid-state prototype qualification timelines, and battery-as-a-service contract penetration rates.
The model assumes a particular technology adoption path; alternative pathways for sulfide-based solid electrolytes or lithium-metal anodes would alter the outlook. Forecasts reflect assumptions regarding KBA type-approval velocity, EU Battery Regulation enforcement timing, and Asian cell producer capacity allocation decisions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
China Electric Vehicle Battery Materials Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
EV Battery Cell and Pack Materials Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
EV Batteries Market
EV Batteries
China Hybrid Electric Vehicle Battery Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
EV Battery Cells Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
EV Battery Heating System Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
United States Electric Vehicle Battery Materials Market
EV Batteries
North America Electric Vehicle Battery Manufacturing Market
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market