
 EV Battery Cell and Pack Materials Market | 2026-2036
EV Battery Cell and Pack Materials Market Size, Share, and Industry Trends Forecast 2026-2036
EV Battery Cell and Pack Materials Market Intelligence
The market's center of gravity is pivoting from solely passenger electric vehicles towards a diversified mix that includes commercial fleets and stationary energy storage systems. This fundamental shift creates new performance, longevity, and cost requirements for material suppliers. CATL dominates the high-volume passenger vehicle segment through its immense manufacturing scale and supply chain control. In contrast, Northvolt specializes in sustainable battery production for the European market, targeting premium automotive OEMs and industrial applications.
EV battery cell and pack materials are the refined chemicals and engineered components used to construct lithium-ion batteries. These materials, including active cathode and anode substances, facilitate the electrochemical process of ion intercalation to store and release energy. Cathode materials, especially Lithium Nickel Manganese Cobalt chemistries, command the largest value share due to high raw material costs. Meanwhile, Lithium Iron Phosphate is gaining ground in standard-range vehicles, and silicon anodes represent a key area for next-generation performance.
Regulatory frameworks like the EU's REACH regulation and China's GB standards impose strict chemical safety and performance criteria on battery materials. Concurrently, policies such as the US Inflation Reduction Act create powerful incentives for localizing material processing and battery manufacturing supply chains. Navigating these divergent regional policies while securing access to compliant raw materials is the central strategic challenge for all market participants.
Market Dynamics
The central dynamic shaping the market is the strategic friction between policy-driven supply chain regionalization, exemplified by the US Inflation Reduction Act, and the deeply entrenched concentration of mid-stream material processing and refining within China.
Growth Catalysts
- Policy Incentives:The US Inflation Reduction Act provides significant tax credits for sourcing battery materials from North America or free-trade partners, directly stimulating investment in regional processing and mining infrastructure.
- Chemistry Diversification:The adoption of Lithium Iron Phosphate (LFP) cathodes for standard-range passenger vehicles and commercial fleets lowers battery pack costs, expanding the total addressable market for electric mobility.
- Commercial Fleet Electrification:Growing deployments of electric buses, delivery vans, and trucks create a new, high-volume demand stream for materials optimized for durability, safety, and high-cycle life over maximum energy density.
Market Restraints
- Raw Material Volatility:Extreme price fluctuations in key metals like lithium and cobalt create significant cost instability for cathode manufacturers, complicating long-term supply agreements and impacting automaker profitability.
- Geopolitical Supply Concentration:A heavy reliance on China for the refining of critical battery-grade materials, including spherical graphite and lithium hydroxide, poses significant supply chain risks for automakers in Europe and North America.
- Technical Hurdles for Next-Gen Materials:The commercial-scale production of high-performance silicon anodes is constrained by technical challenges related to material stability and cycle life, slowing their widespread adoption in mass-market EVs.
Strategic Opportunities
- Stationary Energy Storage:Grid-scale battery energy storage systems (BESS) represent a major growth vector, creating demand for chemistries like LFP and sodium-ion that prioritize low cost, long duration, and high cycle counts.
- Circular Economy Mandates:The EU Battery Regulation's requirements for recycled content and material recovery open a substantial market for urban mining and the production of battery-grade materials from recycled feedstock.
- Solid-State Material Development:Long-term research and development into solid electrolytes, such as sulfides and polymers, presents a transformative opportunity to supply materials for a new generation of safer, more energy-dense batteries.
Industry Challenges
- Capital-Intensive Localization:Building new, non-Chinese refining and synthesis plants for cathode and anode materials requires massive capital investment, long lead times, and navigating complex environmental permitting processes.
- Divergent Regulatory Compliance:Material suppliers face the operational burden of ensuring products simultaneously meet the chemical safety standards of the EU's REACH, performance criteria of China's GB standards, and sourcing rules of the US IRA.
- Specialized Talent Scarcity:A shortage of chemical engineers, metallurgists, and process technicians with experience in high-purity battery material production hinders the rapid scale-up of new manufacturing facilities outside of established Asian hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV Battery Cell and Pack Materials Market |
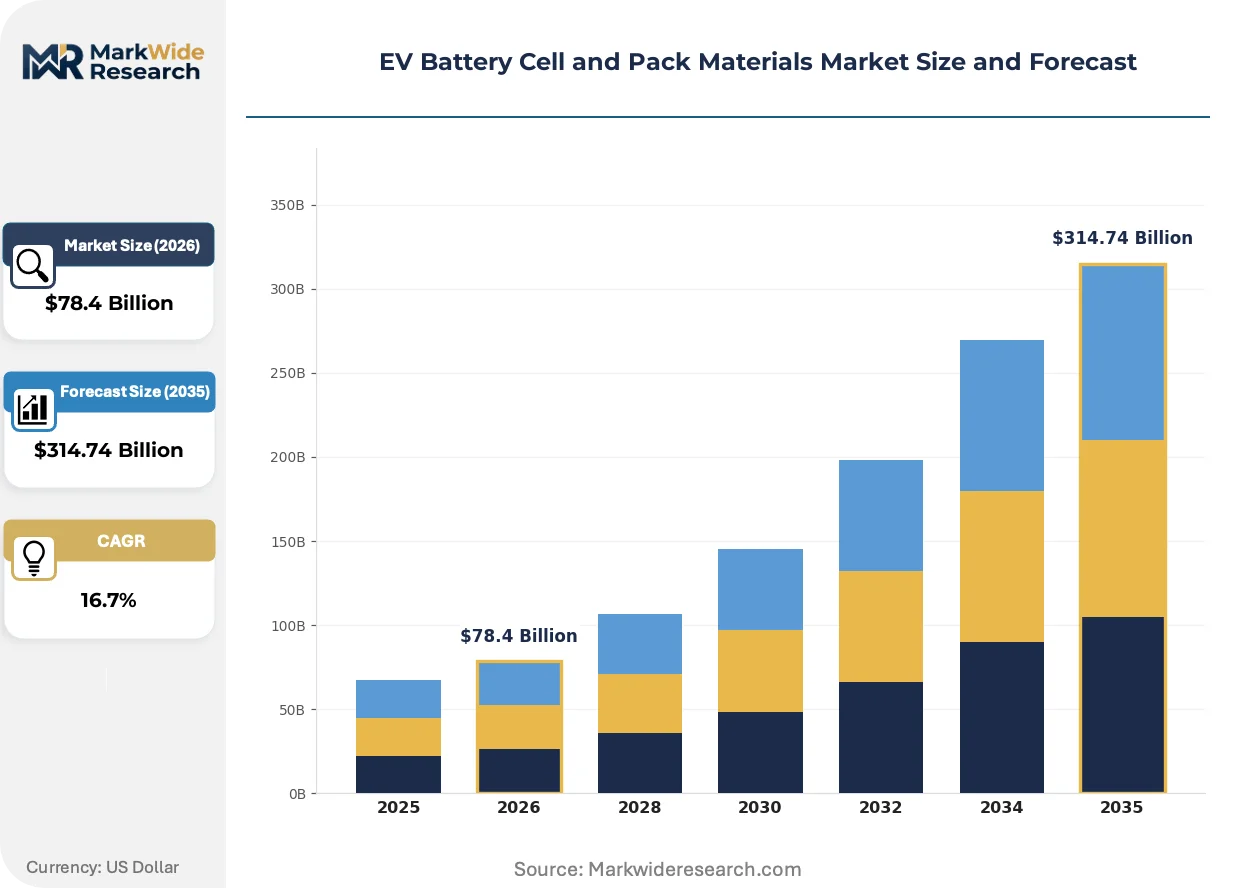
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $314.74 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Lithium Nickel Manganese Cobalt, Lithium Iron Phosphate, Solid Electrolytes, Graphite, Silicon Anodes Battery Component: Cathode, Anode, Electrolyte, Separator, Current Collector Application: Electric Vehicles, Energy Storage Systems, E-Bikes, Electric Buses, Commercial Fleet End User: OEMs, Battery Manufacturers, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | CATL, LG Energy Solution, Panasonic, Samsung SDI, BYD, Sunwoda Electronic, C4V, SK Innovation, Northvolt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Battery Cell and Pack Materials Market Strategic Shifts & Innovations
The market's evolution is defined by a dual pursuit of performance and sustainability. Innovations in material science aim for higher energy density and faster charging, while regulatory and consumer pressures push the entire supply chain toward greater transparency and circularity.
Silicon anode material offers a clear pathway to increasing the energy density of lithium-ion battery cells. Automakers focused on premium, long-range EVs are the primary early adopters, seeking a competitive performance advantage. Development of stable silicon-graphite composites is converging with advanced electrolyte additives designed to manage volumetric expansion, which is critical for improving cycle life and unlocking widespread commercial use.
The European Union's Battery Regulation mandates specific minimum thresholds for recycled content in new industrial and EV batteries sold in the region. This policy directly stimulates investment in advanced hydrometallurgical and pyrometallurgical recycling facilities capable of recovering high-purity metals. Cathode material producers are the most impacted segment, now forced to develop supply chains for secondary cobalt, lithium, and nickel to ensure market access in Europe.
Automaker sourcing decisions are expanding beyond pure cost metrics to incorporate sustainability criteria, particularly the verified carbon footprint of battery materials. This shift creates a competitive advantage for material suppliers who can provide audited Product Carbon Footprint (PCF) data for their products. This demand-side change is most advanced in Europe, where regulations like the Corporate Sustainability Reporting Directive (CSRD) compel greater supply chain transparency.
EV Battery Cell and Pack Materials Market Segmentation
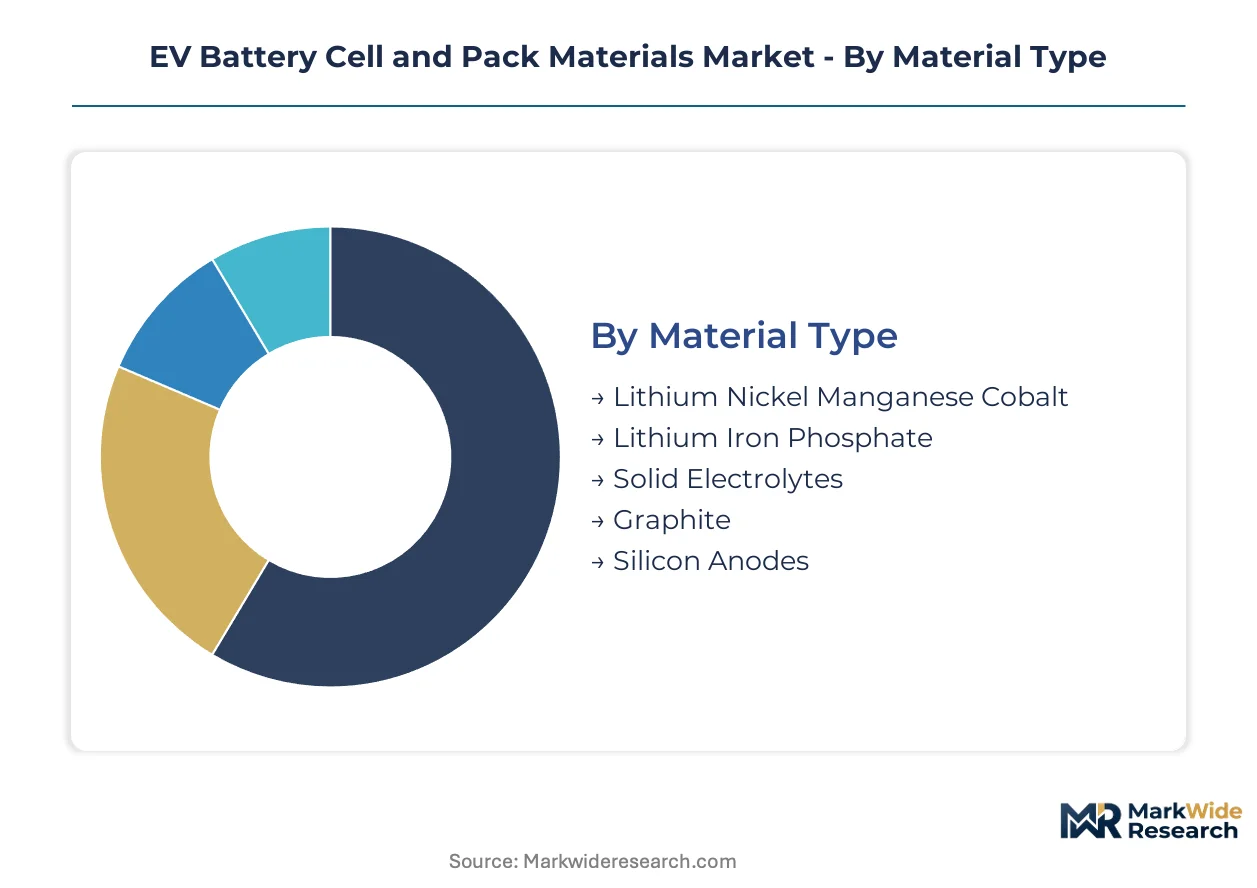
Understanding the intricate segmentation of the EV battery cell and pack materials market reveals distinct value pools and technological priorities. Each material type, component, application, and end user segment exhibits unique performance requirements and cost sensitivities. Strategic positioning within these segments is essential for market participants seeking sustainable growth.
Material Type:
The market for battery materials splits between high-volume, cost-effective chemistries and premium, performance-driven alternatives.
- Lithium Nickel Manganese Cobalt:These cathode materials offer high energy density and power output, making them suitable for premium electric vehicles requiring long range and fast acceleration. Demand concentrates in Europe and North America for high-performance passenger cars.
- Lithium Iron Phosphate:LFP cathodes provide excellent safety, long cycle life, and lower cost per kilowatt-hour, making them ideal for standard-range EVs, commercial fleets, and stationary energy storage systems. China's domestic market drives significant demand for LFP in mass-market vehicles.
- Solid Electrolytes:This category includes advanced materials designed to replace liquid electrolytes, promising enhanced safety, higher energy density, and faster charging for next-generation solid-state batteries. Research and development efforts globally focus on overcoming technical challenges for commercial viability.
- Graphite:Graphite serves as the primary anode material, providing a stable structure for lithium ion intercalation and deintercalation. China dominates the processing and supply of battery-grade spherical graphite.
- Silicon Anodes:Silicon anode materials offer significantly higher theoretical energy capacity compared to graphite, positioning them for high-performance applications in premium electric vehicles. Technical hurdles related to volumetric expansion during cycling remain a focus for material scientists.
Mature deployment sits with Lithium Nickel Manganese Cobalt. Newer deployment is concentrated in Solid Electrolytes.
Battery Component:
The value contribution of battery components varies significantly based on material complexity and processing requirements.
- Cathode:Cathode materials represent the largest cost component of a lithium-ion battery due to the high value of raw metals like lithium, nickel, and cobalt. These active materials determine the battery's energy density and power characteristics.
- Anode:Anode materials facilitate the storage of lithium ions during charging and their release during discharge, influencing battery cycle life and power density. Innovations in anode materials, such as silicon-graphite composites, aim to boost energy capacity.
- Electrolyte:The electrolyte solution enables the movement of lithium ions between the cathode and anode, a critical function for battery operation. Electrolyte formulations are continually evolving to improve safety and performance across temperature ranges.
- Separator:The separator is a porous membrane that physically separates the cathode and anode, preventing short circuits while allowing ion transport. Advanced separators enhance battery safety and thermal stability.
- Current Collector:Current collectors, typically made of aluminum foil for cathodes and copper foil for anodes, gather and transfer electrons to the external circuit. Their design impacts the battery's internal resistance and overall efficiency.
Material costs are highest for the Cathode component. Performance enhancements are most actively pursued within the Anode component.
Application:
Each application segment imposes distinct requirements on battery material performance and longevity.
- Electric Vehicles:This segment represents the largest volume demand for battery materials, driven by the global transition to sustainable transportation. Materials must balance high energy density for range with power for acceleration and fast charging capabilities.
- Energy Storage Systems:Grid-scale and residential energy storage applications prioritize long cycle life, safety, and cost-effectiveness over maximum energy density. LFP chemistries are particularly well-suited for these stationary deployments.
- Commercial Fleet:Electric buses, trucks, and delivery vans require battery materials optimized for durability, rapid charging, and high-cycle throughput under demanding operational conditions. Safety and reliability are paramount for these high-utilization vehicles.
- E-Bikes:This segment demands lightweight and compact battery solutions, often utilizing materials that offer a good balance of energy density and cost. Urban mobility trends support continued growth in e-bike battery demand.
- Electric Buses:Electric buses require large battery capacities to ensure sufficient range and often utilize LFP chemistry due to its robust safety profile and extended cycle life. Fast charging capabilities are essential for operational efficiency in public transport.
The Electric Vehicles segment represents the largest volume consumption. The Energy Storage Systems segment is expanding most quickly.
End User:
Different end users within the value chain have varying purchasing power and influence over material specifications.
- Battery Manufacturers:These entities are the primary direct purchasers of battery cell and pack materials, converting raw materials into finished battery cells and modules. Their procurement decisions significantly shape material demand and specifications.
- OEMs:Automotive Original Equipment Manufacturers (OEMs) define the performance, safety, and cost requirements for their electric vehicles, thereby influencing the choice of battery materials. Many OEMs are increasingly involved in direct material sourcing or battery cell production.
- Tier-1 Suppliers:Tier-1 suppliers often provide battery packs or sub-systems to OEMs, integrating cells from battery manufacturers with cooling systems, battery management systems, and enclosures. They influence material selection through design specifications.
- Vehicle Assemblers:Vehicle assemblers integrate battery packs into the final electric vehicle chassis, focusing on manufacturing efficiency and quality control. Their material influence is primarily indirect, through OEM specifications.
- Aftermarket Providers:Aftermarket providers supply replacement battery packs or components for existing electric vehicles. Their material choices are often dictated by compatibility with original vehicle designs and cost considerations.
Battery Manufacturers hold significant direct purchasing power. OEMs establish crucial material specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global EV battery cell and pack materials market exhibits a distinct divide between material processing and end-use consumption. China maintains a dominant position in mid-stream refining and synthesis, while North American and European regions increasingly focus on localizing battery manufacturing and material sourcing. This dynamic creates both dependencies and strategic imperatives for regional supply chain development.
China
Domestic demand for Lithium Iron Phosphate (LFP) cathodes drives substantial material consumption for mass-market electric vehicles and commercial fleets. China's GB standards impose stringent performance and safety criteria on battery materials. Major manufacturing clusters in the Yangtze River Delta and Pearl River Delta regions continue to expand production capabilities for both cells and integrated materials.
United States
Policy incentives from the US Inflation Reduction Act stimulate significant investment in domestic processing and mining infrastructure for battery materials. The push for commercial fleet electrification creates new demand streams for durable and safe battery chemistries. New Gigafactory developments across states like Nevada, Georgia, and Michigan are establishing localized supply chains for cell production.
Germany
European Union Battery Regulation mandates for sustainable sourcing and recycled content influence material selection for premium electric vehicles. Germany's automotive industry drives demand for high-energy-density Lithium Nickel Manganese Cobalt (NMC) chemistries. Investments by companies like Northvolt and CATL in Brandenburg and Thuringia aim to establish significant battery cell and material production capacities.
South Korea
High-performance electric vehicle production from major automotive OEMs drives demand for advanced battery materials, including those for next-generation solid-state technologies. South Korea's Ministry of Trade, Industry and Energy (MOTIE) supports research and development in battery chemistry and material innovation. Major battery manufacturing hubs in Ulsan and Cheonan focus on scaling up cell production and material integration.
Japan
Advanced material research and development efforts focus on improving energy density and safety for long-range electric vehicles. Japan's METI promotes initiatives for securing stable raw material supplies and developing circular economy solutions. Collaborations between automotive giants like Toyota and battery manufacturers in regions such as Aichi and Osaka aim to commercialize new battery technologies.
EV Battery Cell and Pack Materials Market Key Industry Players
Top-tier vendors anchor the global EV battery cell and pack materials market, while specialized material suppliers and emerging technology developers contribute to its evolving structure. The market sees a tiered competitive landscape, with large integrated battery manufacturers often controlling significant portions of their material supply chains. Key strategic archetypes include integrated cell producers, specialized cathode material providers, and next-generation anode material innovators. Capacity expansion and strategic partnerships remain dominant competitive moves across the industry.
Within the integrated cell production tier, CATL and LG Energy Solution exemplify the scale-driven approach to battery manufacturing, influencing material specifications across global supply chains. CATL, a Chinese company, dominates the high-volume passenger vehicle segment through immense manufacturing capacity. LG Energy Solution, a South Korean entity, maintains a broad global presence and diversified chemistry portfolio. Northvolt, a Swedish company, represents a European archetype focused on sustainable battery production for premium automotive OEMs and industrial applications.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic |
| Samsung SDI |
| BYD |
| Sunwoda Electronic |
| C4V |
| SK Innovation |
| Northvolt |
Cost & Logistics Intelligence
A scarcity of chemical engineers and metallurgists in established Asian hubs creates labor-cost differentials, which directly influence pricing-tier spreads for battery-grade materials. This specialized workforce concentration impacts the cost structure for high-purity cathode and anode substances.
Pricing Analysis
Cost-down pressure on Lithium Iron Phosphate (LFP) materials accelerates because of intense competition within the standard-range electric vehicle segment. Pricing for EV battery materials operates on a hybrid model, combining long-term contract-based offtake agreements for stable supply with commodity spot pricing for raw metal inputs. Price differentiation stems from battery-grade purity levels and compliance with regional regulations like the EU Battery Regulation. The commercial fleet and stationary energy storage segments exhibit the highest price sensitivity, while premium electric vehicle manufacturers are less sensitive to material cost fluctuations.
Supply Chain Analysis
The US Inflation Reduction Act's domestic-content mandates are reshaping global sourcing strategies for battery materials. China concentrates the mid-stream processing and refining of critical battery-grade materials, including spherical graphite and lithium hydroxide. Key raw material dependencies include lithium, nickel, and cobalt, primarily sourced from Australia, Indonesia, and the Democratic Republic of Congo. Geopolitical supply concentration in refining poses a significant structural risk for European and North American automakers. Distribution primarily involves direct sales channels from material producers to battery cell manufacturers, with some automotive OEMs establishing direct material sourcing initiatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EV battery materials market functions as a cost-of-compliance story, with the EU Battery Regulation creating a significant barrier-to-entry moat for compliant material suppliers.
For Market Incumbents: Lock in long-term raw material supply contracts to mitigate extreme price volatility, a persistent threat to cathode manufacturers. Invest heavily in advanced hydrometallurgical recycling facilities in Europe and North America to meet future recycled content mandates. Deepen vertical integration into upstream processing to gain greater control over material quality and cost structures, enhancing competitive positioning against emerging entrants. Capacity expansion in strategic regions like the United States should prioritize materials for commercial fleets.
For New Entrants and Emerging Players: Digital platforms for supply chain traceability offer a clear pathway to penetrate the European market by demonstrating compliance with sustainability mandates. Target specialized material niches like high-performance silicon anodes or advanced solid electrolytes, which serve premium electric vehicle applications. The stationary energy storage segment presents a penetrable entry point due to its lower energy density requirements compared to automotive applications. Partnering with specialized industrial integrators can provide a go-to-market angle for new material chemistries.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized material science firms given the long-term shift towards electric mobility and grid modernization. Focus on acquisition targets with proven intellectual property in next-generation battery materials or advanced recycling technologies. Long-term viability extends across the coming decade as demand for battery materials continues to expand globally. The widespread commercialization of solid-state battery technology represents a key inflection indicator to watch for significant valuation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases regional material supply, reducing reliance on concentrated processing hubs. |
| Long-term Supply Agreement | Stabilizes raw material costs for cathode manufacturers, improving profitability forecasts. |
| Green Manufacturing Transition | Attracts premium automotive OEM customers prioritizing verified carbon footprints. |
| Joint Venture | Accelerates technology transfer for advanced materials like silicon anodes. |
| Product Launch (Solid Electrolytes) | Positions firms for leadership in next-generation battery safety and energy density. |
Research Approach
Industry association reports, government energy agency publications, corporate financial filings, and academic journals formed the secondary backbone of this market analysis. This desk research was complemented by primary interviews with battery manufacturers, material suppliers, automotive OEMs, and recycling specialists. Bottom-up and top-down triangulation methods were applied to validate market sizing and growth projections.
Historical trendline analysis established the foundation for the quantitative framework, projecting market evolution across the analysis window. The analytical framework incorporated segmentation dimensions including material type, battery component, application, end user, and regional regulatory frameworks. Compound annual growth rates were derived from regression models, informed by expert consensus. Key forecast inputs included global electric vehicle adoption rates and future raw material price forecasts.
Inputs from published reports and industry databases were available through the study window; gaps in emerging technology adoption rates introduce uncertainty bands. Forecasts reflect assumptions regarding economic stability and regulatory continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
Cold-Climate Optimized EV Battery Systems Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
South America Electric Vehicle Battery Manufacturing Market
EV Batteries
North America LFP Battery Pack Market
EV Batteries
US EV Battery Pack Market
EV Batteries
Italy Electric Vehicle Battery Electrolyte Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Cobalt Powder for EV Battery Market
EV Batteries
North America Electric Vehicle Battery Materials Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Market
EV Batteries
Italy Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Solid State Battery Market
EV Batteries
Canada EV Battery Pack Market