
 US Electronic Gadgets Insurance Market | 2026-2036
US Electronic Gadgets Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
US Electronic Gadgets Insurance Market Analytics
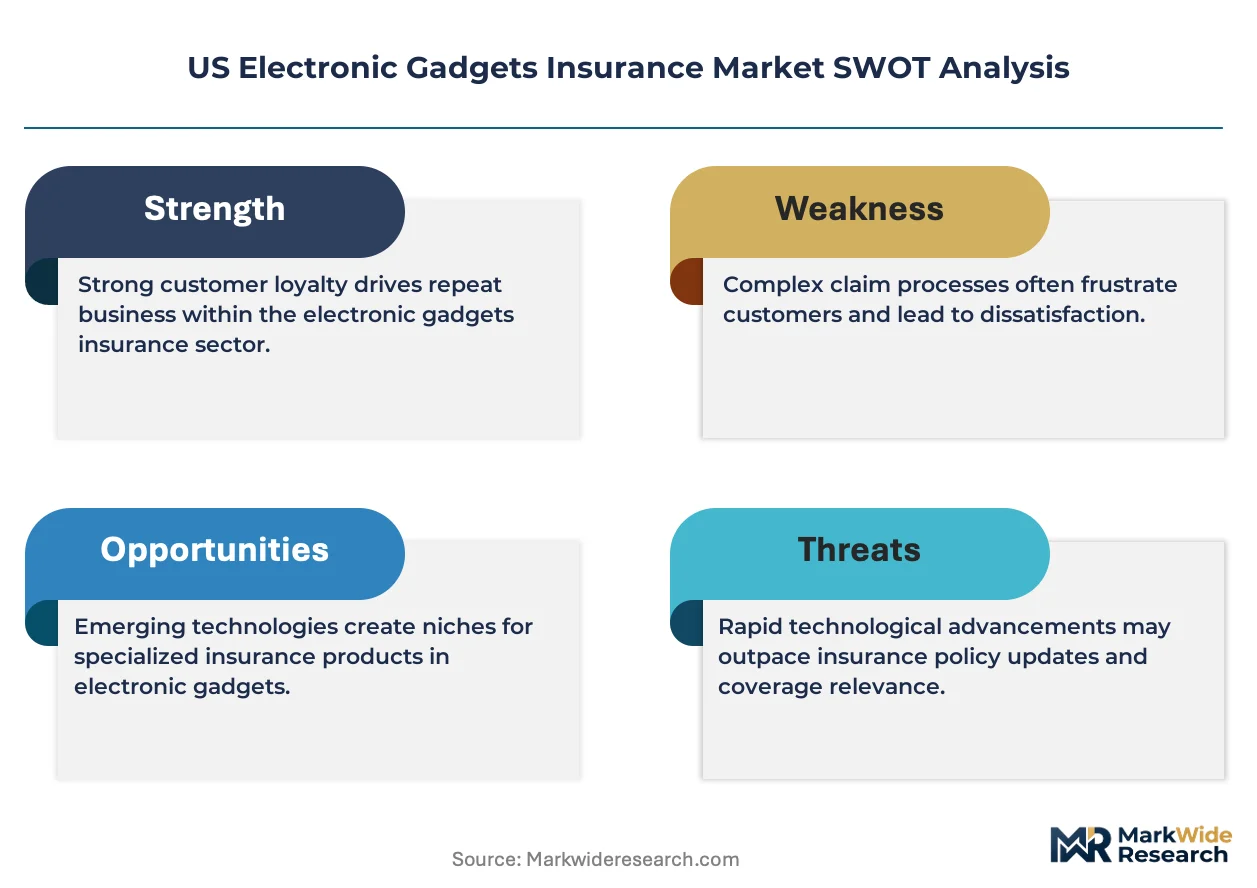
NAIC producer licensing standards for gadget insurance is unwinding competitive access across state lines, forcing carriers to rebuild compliance infrastructure. Progressive leverages its direct-to-consumer platform to dominate personal lines distribution. Assurant Inc. anchors the mobile carrier-embedded segment through partnerships with AT&T Inc. Chubb specializes in high-value corporate fleet coverage for enterprise device deployments.
Electronic gadgets insurance covers portable consumer electronics against financial loss from physical damage, theft, or malfunction through indemnity contracts that specify per-occurrence deductibles, replacement value caps, and depreciation schedules. Policies typically exclude cosmetic wear and unauthorized modifications while requiring proof of purchase and serial number registration to validate claims. Smartphone coverage leads premium volume due to elevated breakage rates and shorter replacement cycles. Accidental damage policies capture the fastest-growing margin pool as consumers reject manufacturer warranties with narrower scope. Corporate customer segments sustain higher retention than individual buyers due to master policy structures and volume pricing.
The National Association of Insurance Commissioners coordinates state-level rate filings and reserve requirements that govern carrier solvency and policy form approvals. The Federal Trade Commission monitors marketing disclosures and claim denial practices under consumer protection statutes. The Consumer Financial Protection Bureau scrutinizes add-on insurance sales at electronics retail points for unfair lending linkage. Stakeholders must track state-by-state regulatory divergence as California and New York advance distinct gadget insurance disclosure frameworks that could fragment national product design.
Market Dynamics
The FCC's device authentication mandates are forcing insurers to rebuild risk-scoring algorithms around verified hardware provenance, compressing margins for carriers that lag in compliance infrastructure deployment.
Growth Catalysts
- Remote workforce device proliferation:California's tech corridors and Texas metro clusters sustain elevated policy uptake as smartphone-dependent workers demand breakage coverage outside employer master policies.
- NAIC producer licensing standards:Unwinding competitive access across state lines creates first-mover advantages for carriers that rebuild multi-jurisdictional compliance infrastructure ahead of rivals.
- Accidental damage policy expansion:Consumers reject manufacturer warranties with narrower scope, migrating premium volume toward indemnity contracts with per-occurrence deductible flexibility.
Market Restraints
- Depreciation schedule compression:Shorter replacement cycles for flagship smartphones compress claim payout windows, squeezing actuarial reserves.
- State regulatory fragmentation:California and New York advance distinct gadget insurance disclosure frameworks that fragment national product design and multiply form-approval costs.
- Cosmetic wear exclusion disputes:Policy language ambiguity around screen micro-fractures generates claims litigation that inflates loss-adjustment expenses.
Strategic Opportunities
- Corporate fleet master policies:Enterprise device deployments sustain higher retention than individual buyers through volume pricing structures and centralized claims administration.
- Embedded carrier partnerships:Mobile network operators at point-of-sale capture low-friction enrollment for breakage coverage before warranty expiration windows close.
- Serial number blockchain verification:Distributed ledger integration with FCC authentication databases streamlines claims validation and reduces fraud investigation cycles.
Industry Challenges
- Proof-of-purchase documentation gaps:Secondary market device sales lack receipt trails that validate original ownership dates for claims processing.
- Unauthorized modification detection:Firmware tampering voids coverage terms but requires specialized diagnostic labor that extends claim resolution timelines.
- Multi-state rate filing synchronization:NAIC reserve requirements diverge across jurisdictions, complicating national pricing models for personal lines distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Electronic Gadgets Insurance Market |
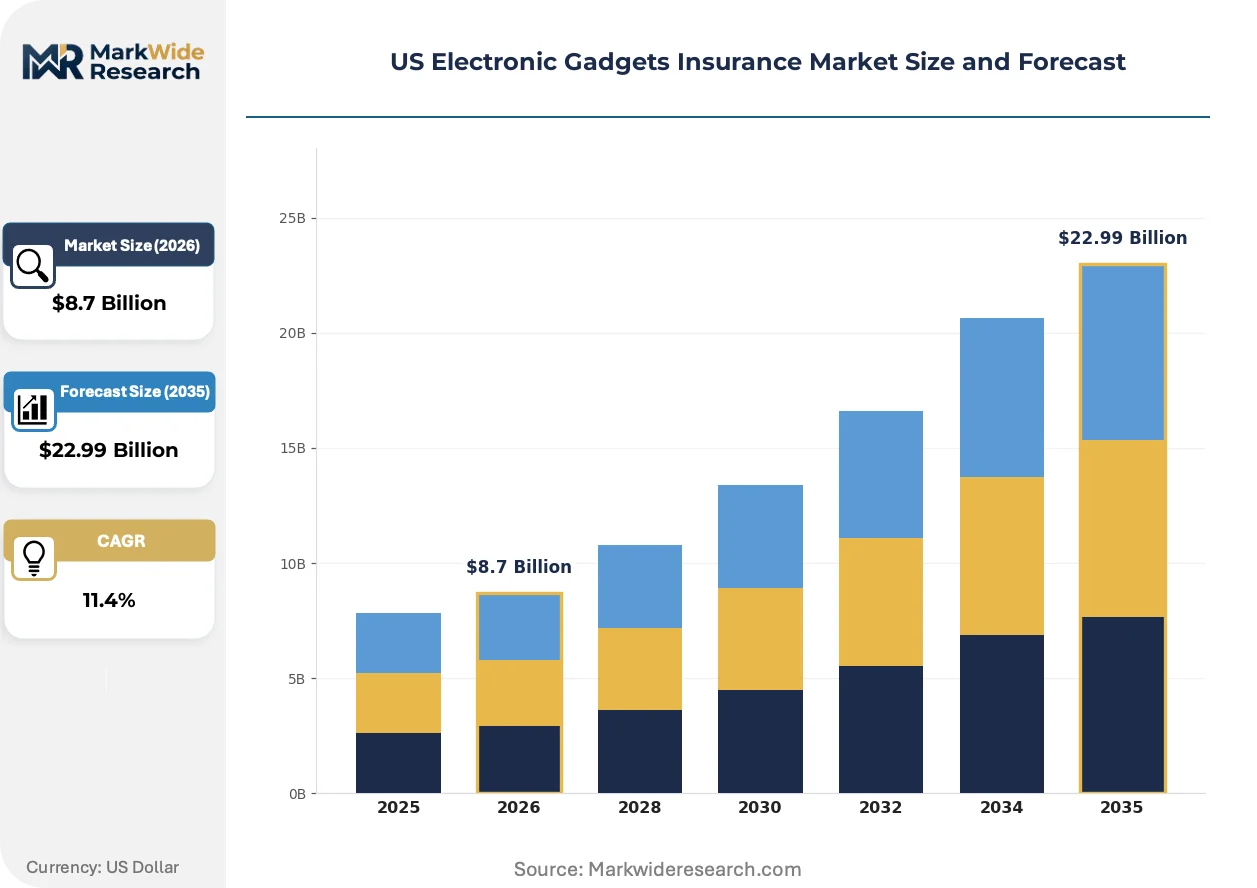
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Laptops, Tablets, Wearables Coverage Type: Theft, Accidental Damage, Liquid Damage, Extended Warranty Customer Type: Individuals, Small Businesses, Corporates, Educational Institutions Sales Channel: Online Retailers, Insurance Brokers, Electronics Stores, Direct Sales |
| Companies Covered | AXA, Aviva, Allianz Insurance, Progressive, Amica Mutual Insurance, AIG, Chubb, AT&T Inc., Assurant Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Electronic Gadgets Insurance Market Evolving Landscape
Telematics-enabled risk assessment is reshaping how carriers price gadget coverage, shifting from static depreciation tables toward dynamic usage-pattern scoring that reflects actual device handling behaviors.
Embedded sensor diagnostics is fragmenting traditional claims workflows. Accelerometer and gyroscope data streams from smartphones now establish impact force thresholds that automate first-notice-of-loss reporting. Enterprise fleet managers adopt this telemetry for bulk policy administration, while individual buyers resist privacy trade-offs. The technology is fragmenting adjuster roles into specialized data-interpretation functions.
The FTC's intensified scrutiny of marketing disclosures under consumer protection statutes is compressing permissible claim-denial language. Carriers must refile policy forms to specify exact cosmetic-damage thresholds and pre-existing condition windows. The mobile carrier-embedded segment faces the steepest compliance retrofit costs as point-of-sale scripts require real-time disclosure synchronization.
After-sales service unbundling is displacing bundled manufacturer protection plans. Corporate procurement teams now separately negotiate hardware, software, and insurance contracts, forcing carriers to compete in standalone RFP processes. Texas enterprise clusters lead this disaggregation, with individual consumers in California metro areas following the purchasing pattern through employer-sponsored voluntary benefit portals.
US Electronic Gadgets Insurance Market Segmentation
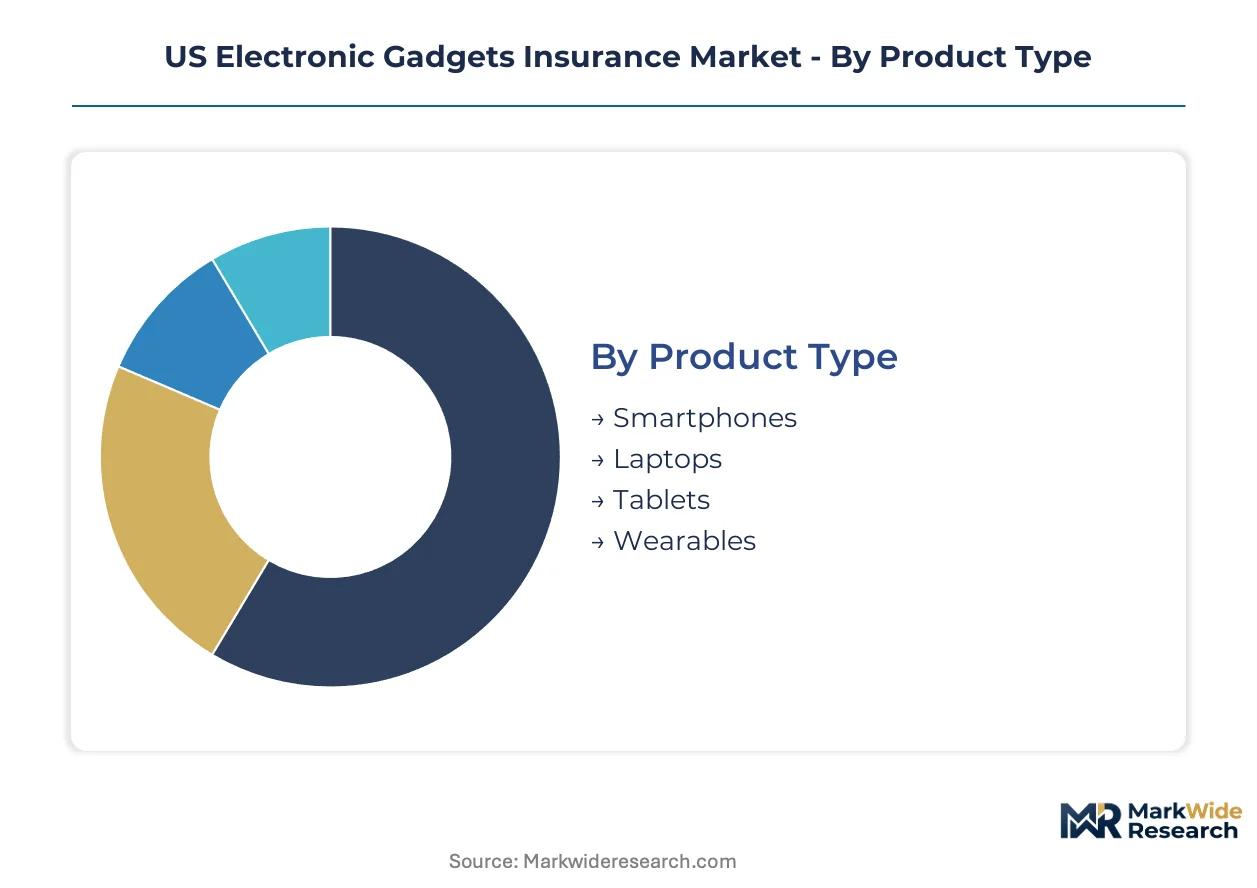
Segmentation reveals how gadget insurance demand fragments across device categories, risk profiles, and procurement channels. Carriers calibrate pricing models and distribution investments around these fault lines.
Product Type:
Smartphone coverage dominates domestic premium volume, while laptop and tablet policies show stronger attachment to employer-sponsored programs in Texas and California enterprise corridors.
- Smartphones:Shorter replacement cycles and elevated breakage rates concentrate premium volume here. California's remote workforce clusters sustain the steepest policy uptake as smartphone-dependent workers seek coverage outside employer master policies.
- Laptops:Corporate procurement drives bulk enrollment through centralized fleet administration. Texas metro enterprise deployments favor laptop coverage tied to hardware refresh cycles and volume pricing structures.
- Tablets:Educational institutional demand anchors this segment, with K-12 districts and universities negotiating master policies for student device deployments.
- Wearables:Fitness trackers and smartwatches attract younger individual buyers through embedded carrier partnerships at point-of-sale.
Smartphones hold the largest share; momentum sits with wearables as health-integrated devices expand the addressable base.
Coverage Type:
Premium differentiation runs widest across coverage tiers, with accidental damage commanding rate flexibility and theft protection facing stricter documentation requirements.
- Accidental Damage:Per-occurrence deductible flexibility attracts consumers rejecting narrower manufacturer warranties. This coverage tier captures the most dynamic margin expansion as policy language around screen micro-fractures evolves.
- Theft:Proof-of-purchase documentation gaps complicate claims validation for secondary market devices. FCC device authentication mandates are compressing fraud investigation cycles for verified hardware.
- Liquid Damage:Specialized diagnostic requirements extend claim resolution timelines. Corrosion detection protocols vary by carrier, creating service-level differentiation.
- Extended Warranty:Manufacturer protection plan displacement is accelerating as corporate procurement teams unbundle after-sales service contracts. Texas enterprise clusters lead this purchasing pattern shift.
Accidental damage holds the largest share; momentum sits with extended warranty as standalone RFP processes displace bundled offerings.
Customer Type:
Retention economics diverge sharply between individual buyers with high churn and corporate accounts with multi-year master policy structures.
- Corporates:Enterprise device deployments sustain superior retention through centralized claims administration and volume pricing. Fleet telemetry adoption is automating first-notice-of-loss reporting for bulk policyholders.
- Individuals:Price-sensitive buyers cycle between carriers annually, with California metro areas showing elevated shopping behavior through employer-sponsored voluntary benefit portals.
- Small Businesses:Owner-operated firms lack procurement scale for fleet pricing but seek breakage coverage beyond personal lines. NAIC producer licensing standards are forcing compliance infrastructure rebuilds for this segment's multi-state operations.
- Educational Institutions:District-level negotiations concentrate demand seasonally around academic calendar procurement windows. Student device one-to-one programs drive predictable enrollment spikes.
Corporates hold the largest share; momentum sits with educational institutions as one-to-one deployment programs scale.
Sales Channel:
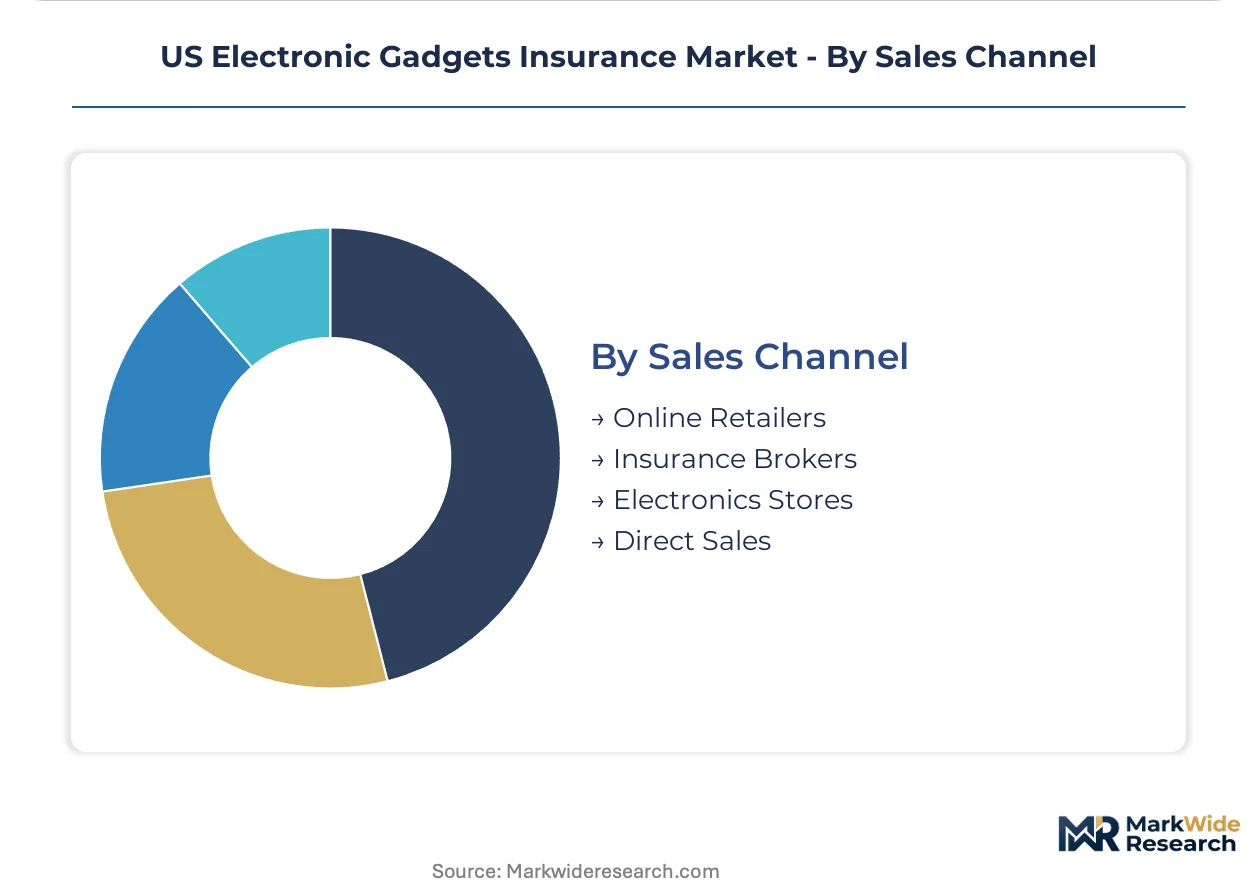
Channel economics reflect friction gradients, with embedded carrier partnerships capturing enrollment before warranty expiration windows close and direct sales facing higher customer acquisition costs.
- Electronics Stores:Point-of-sale placement captures low-friction enrollment at device purchase. FTC marketing disclosure scrutiny is compressing permissible script language and inflating compliance retrofit costs.
- Insurance Brokers:Independent agents serve small business clients with multi-policy bundling needs. NAIC multi-state licensing requirements complicate broker access across state lines.
- Online Retailers:E-commerce checkout integration enables impulse attachment of coverage to device orders. California and New York disclosure framework divergence fragments national product design for digital sales.
- Direct Sales:Carrier-owned platforms like Progressive's direct-to-consumer infrastructure dominate personal lines distribution with rate transparency tools.
Electronics stores hold the largest share; momentum sits with online retailers as e-commerce device sales expand checkout-integrated coverage attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NAIC producer licensing standards are forcing carriers to rebuild multi-jurisdictional compliance infrastructure, reshaping competitive access across state lines. California and Texas anchor premium volume through tech corridor density and enterprise fleet deployments.
California
Remote workforce clusters in Silicon Valley and San Francisco sustain the steepest smartphone policy uptake as smartphone-dependent workers seek coverage outside employer master policies. The state's Department of Insurance advances distinct gadget insurance disclosure frameworks that fragment national product design. Los Angeles and San Diego metro areas concentrate embedded carrier partnership enrollment through mobile network operator point-of-sale channels.
Texas
Enterprise device deployments in Austin, Dallas, and Houston drive bulk laptop and tablet coverage through centralized fleet administration. The Texas Department of Insurance coordinates rate filings that diverge from NAIC reserve requirements, complicating national pricing models. Corporate procurement teams in Texas metro clusters lead after-sales service unbundling, separately negotiating hardware and insurance contracts.
New York
Financial services sector density in Manhattan generates demand for high-value corporate fleet coverage with stringent documentation requirements. The New York State Department of Financial Services scrutinizes add-on insurance sales at electronics retail points for unfair lending linkage. Upstate educational institutions negotiate master policies for student device deployments, concentrating seasonal demand around academic calendar procurement windows.
Florida
Retiree and seasonal resident populations sustain individual buyer segments with elevated shopping behavior through employer-sponsored voluntary benefit portals. The Florida Office of Insurance Regulation enforces consumer protection statutes that compress permissible claim-denial language. Miami and Tampa metro areas show growing small business demand for breakage coverage beyond personal lines, though procurement scale limits fleet pricing access.
Illinois
Midwest corporate headquarters in Chicago anchor enterprise device insurance with multi-year master policy structures. The Illinois Department of Insurance tracks NAIC rate filing synchronization challenges that complicate national personal lines distribution. Educational institutions across the state negotiate one-to-one deployment programs, driving predictable enrollment spikes for student device coverage.
US Electronic Gadgets Insurance Market Competitive Landscape
Player mix skews toward diversified property-casualty carriers with direct-to-consumer platforms and specialized mobile carrier-embedded underwriters. Market structure concentrates around carriers with established personal lines infrastructure and point-of-sale distribution partnerships. Two strategic archetypes dominate: direct-to-consumer personal lines specialists and mobile network operator-embedded underwriters. Competitive moves center on compliance infrastructure rebuilds for multi-state licensing and embedded partnership expansion at device purchase points.
Among the diversified carrier tier, Progressive and Chubb exemplify contrasting positioning archetypes. Progressive leverages its direct-to-consumer platform dominance in personal lines distribution, while Chubb occupies the high-value corporate fleet coverage segment for enterprise device deployments. Within the mobile carrier-embedded tier, Assurant Inc. anchors partnerships with AT&T Inc., capturing low-friction enrollment for breakage coverage before warranty expiration windows close. These three carriers represent the structural fault lines between direct sales, corporate specialty, and embedded distribution models.
| Leading Market Players |
|---|
| AXA |
| Aviva |
| Allianz Insurance |
| Progressive |
| Amica Mutual Insurance |
| AIG |
| Chubb |
| AT&T Inc. |
| Assurant Inc. |
| Others |
Value Network & Pricing Analysis
FCC device authentication mandates gate both supply qualification and price differentiation simultaneously, compressing margins for carriers that lag in compliance infrastructure deployment while rewarding early movers with premium positioning in verified-hardware coverage tiers.
Pricing Analysis
Cost-plus contract patterns with NAIC rate indexation dominate carrier pricing structures. Three-tier pricing structure across premium, standard, and economy levels separates corporate fleet master policies from individual direct-to-consumer plans and embedded point-of-sale coverage. Price differentiation rests on volume scale and FCC authentication tier compliance. Cost compression in the individual buyer segment is intensifying because Progressive's direct-to-consumer platform transparency accelerates annual shopping behavior. Small businesses show the highest price sensitivity, while enterprise fleet accounts with centralized procurement demonstrate the least.
Supply Chain Analysis
Inbound logistics costs through West Coast port congestion and container availability constraints on the Asia-Pacific trade lane complicate hardware replacement timelines for liquid damage and theft claims. Geographic supply concentration centers on China, South Korea, and Taiwan for semiconductor components and display assemblies. Raw material dependencies include lithium-ion battery cells, OLED panels, and rare-earth magnets for speaker systems. Single-source vulnerability in Taiwan's advanced chip fabrication creates claims resolution risk for high-end smartphone replacements. Distribution runs through mobile carrier-embedded partnerships at point-of-sale, direct-to-consumer platforms, and electronics retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, with remote workforce device proliferation sustaining policy uptake ahead of employer master policy saturation in California and Texas tech corridors.
For Market Incumbents: Compound defensive positioning through backward integration into FCC authentication database partnerships and captive claims diagnostic technology development. The threat of embedded carrier partnership consolidation by Assurant and AT&T demands channel control investments. Vertical integration into telematics-enabled risk scoring is the critical lever for retention economics. For New Entrants and Emerging Players: Anchor in small business multi-state operations where NAIC producer licensing standards have forced compliance infrastructure gaps among regional carriers. The most penetrable segment sits with educational institutions negotiating one-to-one deployment programs around academic calendar windows. A go-to-market angle through employer-sponsored voluntary benefit portals captures low-friction enrollment. For Investors and Strategic Acquirers: FCC authentication mandate implementation reshapes the acquisition landscape toward carriers with deployed compliance infrastructure and verified-hardware claims validation capabilities. Long-term viability favors platforms with embedded distribution partnerships and corporate fleet master policy retention mechanics. The signal to watch is state regulatory divergence acceleration in California and New York disclosure frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| FCC Authentication Compliance Infrastructure | NAIC rate filings now require verified hardware provenance, gating market access for laggard carriers. |
| Telematics-Enabled Risk Scoring Platform | Dynamic usage-pattern data from accelerometer and gyroscope sensors displaces static depreciation tables. |
| Embedded Carrier Partnership Expansion | AT&T and Verizon point-of-sale channels capture enrollment before manufacturer warranty expiration windows close. |
| Corporate Fleet Master Policy Development | Texas and California enterprise deployments sustain superior retention through volume pricing and centralized claims administration. |
| Blockchain Serial Number Verification | Distributed ledger integration with FCC databases streamlines claims validation and compresses fraud investigation cycles. |
Research Methodology
Operator-level perspectives from claims operations directors, actuarial pricing leads, mobile carrier partnership managers, and state insurance regulatory staff anchored the qualitative base. Primary interviews combined with secondary validation from NAIC rate filing databases, SEC 10-K insurance segment disclosures, FCC equipment authorization records, and Consumer Financial Protection Bureau enforcement actions. Bottom-up policy enrollment data triangulated against top-down carrier premium volume estimates.
Sensitivity analysis tested forecast robustness across the projection horizon through scenario modeling of regulatory divergence acceleration and remote workforce stabilization. Segmentation dimensions included device category, coverage type, customer archetype, and distribution channel, with FCC authentication compliance tier as an industry-specific overlay. CAGRs derived from trend extrapolation of historical enrollment patterns adjusted for structural shifts in employer-sponsored benefit design.
Decision-makers should treat outputs as directional under assumptions of sustained remote workforce device dependence and gradual NAIC harmonization; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Art Insurance Market
Insurance
Global AI in Auto-Insurance Market
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Business Insurance Market
Insurance
Aviation Insurance Market
Insurance
Global Mobile Phone Insurance Ecosystem Market
Insurance
Insurance Analytics Market
Insurance
France Liability Insurance Market
Insurance
Germany Travel Insurance Market
Insurance
Saudi Arabia Health Insurance Market
Insurance
Africa Microinsurance Market
Insurance
Workers Compensation Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Telematics-Based Auto Insurance Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
Europe Bancassurance Market