
 Busbar for EV Market | 2026-2036
Busbar for EV Market Size, Share, and Industry Trends Forecast 2026-2036
Busbar for EV Market Insights
Platform licensing revenue from 800-volt electrical architectures is reshaping how tier-one suppliers capture value in EV power distribution. Schneider Electric leverages its industrial electrification heritage to anchor high-voltage busbar contracts with European OEMs. Siemens competes through integrated power distribution systems that extend from charging infrastructure into vehicle-side busbar design. TE Connectivity specializes in miniaturized interconnect solutions that occupy critical space-constrained zones within battery modules.
A busbar for EV is a rigid or flexible metallic conductor—typically copper or aluminum with nickel or silver plating—engineered to distribute direct current between battery cells, inverters, and electric motors at voltages ranging from 400V to 800V, with cross-sectional areas calibrated to minimize resistive losses and thermal rise during peak discharge cycles. Insulated busbar configurations dominate current OEM specifications because integrated dielectric layers reduce assembly complexity and improve crash safety compared with bare conductor alternatives. Aluminum material grades represent the fastest-expanding segment as automakers seek mass reduction in battery enclosures, though hybrid copper-aluminum joints are gaining traction where conductivity and weight must be balanced across the power path.
The EPA tailpipe emissions standards and NHTSA fuel economy rules in the United States are accelerating OEM transitions to dedicated EV platforms that require redesigned busbar topologies. ECE R100 and the EU Battery Regulation are mandating traceable material sourcing and thermal runaway containment protocols that directly influence busbar insulation specifications and joint reliability testing. Stakeholders must monitor how solid-state battery cell formats and cell-to-pack architectures eliminate traditional module-level busbars, potentially displacing incumbent interconnect suppliers that fail to adapt conductor geometries.
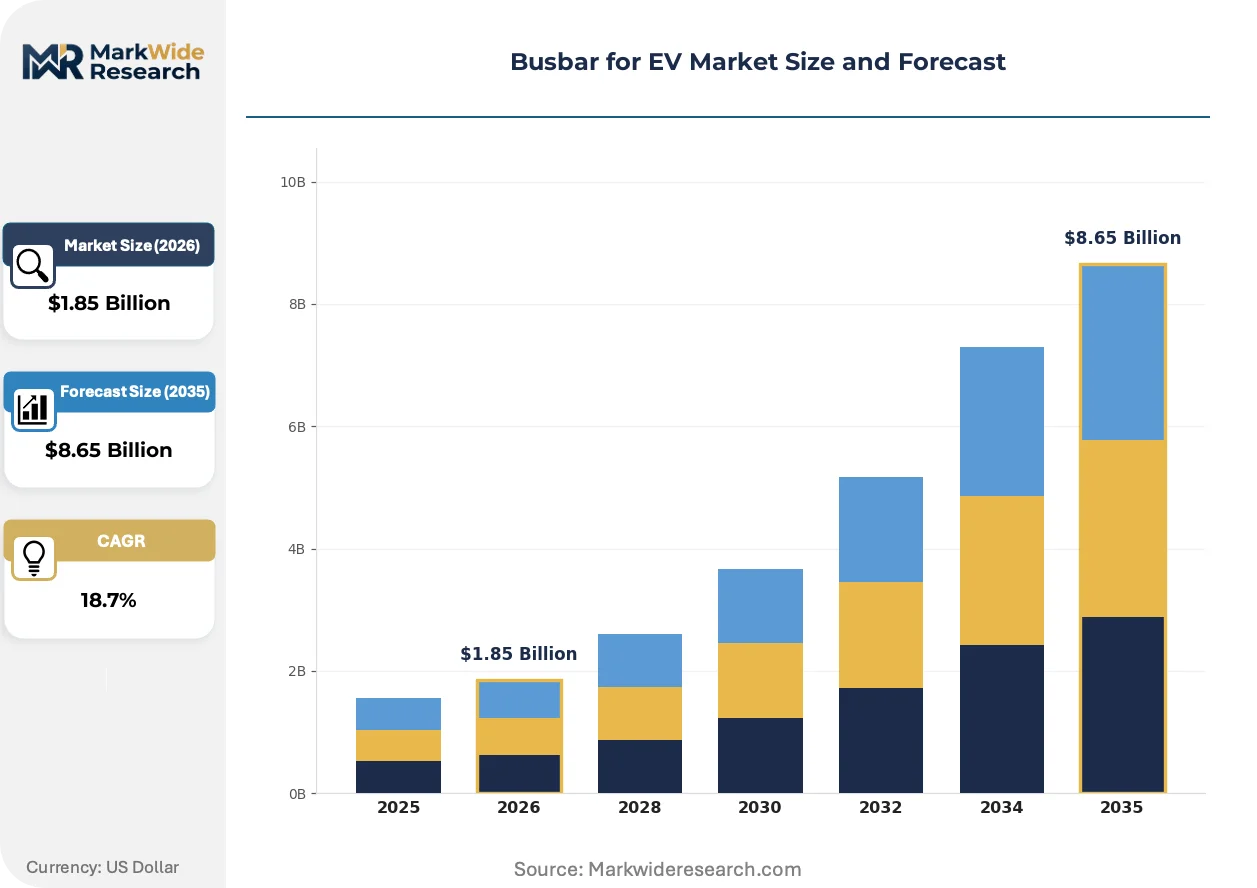
Market Dynamics
Cell-to-pack battery architectures are eliminating module-level busbar assemblies, forcing suppliers to redesign conductor geometries for direct cell tab welding and integrated cooling channels.
Growth Catalysts
- China's NEV credit mandate:OEMs must accumulate credits through electrified vehicle sales, accelerating 800V platform rollouts that demand high-current busbar systems with enhanced thermal management.
- Aluminum conductor grades:Automakers specify A6101 and A1350 alloys to reduce battery enclosure mass by 30-40% versus copper equivalents without sacrificing conductivity in low-temperature applications.
- Germany's industrial corridor:Volkswagen, BMW, and Mercedes-Benz operate vertically integrated battery-pack assembly in Lower Saxony and Bavaria, concentrating procurement of laminated busbar assemblies.
Market Restraints
- Copper price volatility:LME copper futures swing 15-25% quarterly, squeezing margin structures for busbar fabricators locked into annual OEM supply agreements.
- Single-source plating chemistry:Silver and nickel electroplating capacity concentrates in East Asian specialty chemical suppliers, creating input bottlenecks during demand surges.
- ECE R100 thermal containment:The regulation mandates 5-minute no-fire propagation standards that require thicker insulation layers, adding mass and cost to busbar assemblies.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Cell manufacturing incentives are attracting busbar suppliers to Gujarat and Tamil Nadu to localize content for Tata Motors and Mahindra Electric.
- Solid-state cell formats:Oxide and sulfide electrolyte designs enable prismatic and pouch configurations that demand flexible busbar ribbons rather than rigid laminated bars.
- Vehicle-to-grid integration:Bidirectional charging hardware requires busbar systems rated for sustained 350A reverse current flow, opening aftermarket upgrade paths.
Industry Challenges
- Welding technician scarcity:Ultrasonic and laser welding of dissimilar copper-aluminum joints requires certified operators, with training pipelines lagging OEM ramp schedules by 18-24 months.
- ISO 26262 functional safety certification:ASIL-D qualification for high-voltage interconnects demands 12-18 month validation cycles, delaying platform launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Busbar for EV Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $8.65 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Busbar, Bare Busbar, Busway, Flexible Busbar Material: Copper, Aluminum, Hybrid, Stainless Steel Application: Battery Storage, Power Distribution, Charging Stations, Electric Motors End User: OEMs, Aftermarket Providers, Fleet Operators, Utilities |
| Companies Covered | TE Connectivity, Amphenol Corporation, Schneider Electric, Siemens, Rogers Corporation, Leoni AG, APTIV, Mersen SA, Ennovi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Busbar for EV Market Trends and Innovations
Power distribution architectures are compressing physical layers as automakers eliminate redundant connectors and consolidate grounding paths. Three developments are restructuring supplier value capture.
Laminated busbar stacks with integrated film capacitors are collapsing the discrete component count inside inverters. Tier-one suppliers specify these assemblies for 800V silicon carbide drives, reducing electromagnetic interference and assembly labor by 40% versus conventional wire harnesses. The technology is collapsing procurement categories as purchasing teams consolidate vendor lists from three suppliers to single-source laminated system providers.
Europe's EU Battery Regulation mandates recycled content quotas and supply chain due diligence for critical raw materials. Busbar manufacturers must document copper and aluminum provenance through mass-balance certification, adding traceability software costs that favor integrated miners and refiners with captive smelting. German OEMs are responding by pre-qualifying suppliers with closed-loop recycling partnerships.
Fleet operators now specify total-cost-of-ownership metrics rather than unit pricing for high-voltage interconnects. Leasing companies and municipal transit authorities in California and the Netherlands require 15-year corrosion warranties and predictive maintenance telemetry, shifting supplier relationships from transactional component sales to performance-guaranteed service agreements. This restructuring favors busbar vendors with embedded sensor capabilities and digital twin integration.
Busbar for EV Market Segmentation
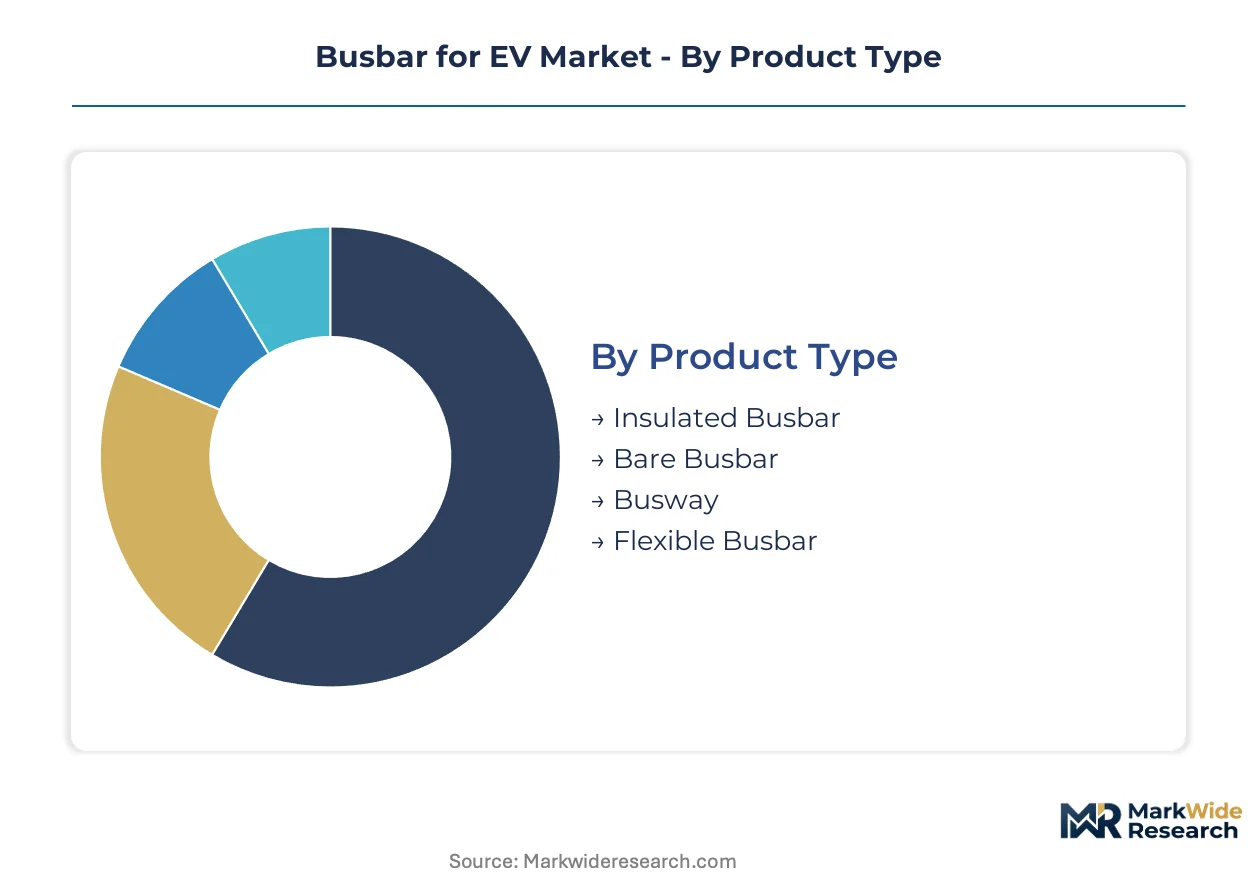
Busbar segmentation in the EV sector tracks how conductor geometry, material science, and application voltage interact with platform electrification strategies. Each dimension carries distinct procurement logic and supplier qualification requirements.
Product Type:
Cost tier differentiation separates commodity conductors from engineered assemblies with integrated insulation and sensing capabilities.
- Insulated Busbar:Dielectric-layered conductors with polyimide or epoxy coatings eliminate separate sleeving assembly steps. European OEMs specify these for 800V battery packs where ECE R100 thermal containment mandates thicker barrier materials.
- Bare Busbar:Unplated copper or aluminum strips serve cost-sensitive commercial vehicle retrofits and repair channels. Demand concentrates in India's electric bus conversion market where local fabricators supply state transport utilities under PLI-linked procurement.
- Busway:Enclosed modular systems with plug-in tap boxes distribute power across charging depot infrastructure. Schneider Electric and Siemens dominate this segment for megawatt-scale fleet charging installations in Germany.
- Flexible Busbar:Laminated foil stacks with polymer interlayers accommodate vibration and thermal cycling in cell-to-pack architectures. Solid-state battery prototypes from Toyota and QuantumScape specify these for prismatic cell tab connections.
Insulated configurations command the established base. The steepest expansion runs through flexible busbar formats.
Material:
Volume and weight tradeoffs drive material selection across passenger, commercial, and performance vehicle segments.
- Copper:C11000 electrolytic tough pitch delivers maximum conductivity for high-discharge performance EVs. Porsche Taycan and Hyundai Ioniq 5 N specify copper busbars in inverter-to-motor links where resistive losses directly impact acceleration metrics.
- Aluminum:A6101 and A1350 alloys reduce mass in battery enclosure structures without conductivity penalty at operating temperatures below 80°C. Chinese NEV manufacturers specify aluminum for entry-level BEV platforms where cost and weight compete as primary design variables.
- Hybrid:Copper-aluminum transition joints combine conductivity at cell terminals with weight savings in long distribution runs. Welding complexity limits adoption to premium platforms with qualified ultrasonic bonding capacity.
- Stainless Steel:304 and 316 grades serve grounding and structural busbar applications where corrosion resistance outweighs conductivity requirements. Coastal fleet operators in California specify these for salt-exposed underbody installations.
Copper retains the revenue base. Aluminum alloys are climbing the fastest as cell-to-pack mass reduction targets tighten.
Application:
Customer type and voltage class segment demand across vehicle-side and infrastructure-side installations.
- Battery Storage:Cell-to-cell and module-to-module interconnects carry continuous DC loads with pulse discharge peaks. Tesla's 4680 structural battery packs eliminate module-level busbars entirely, forcing suppliers to redesign for direct cell tab welding.
- Power Distribution:Inverter input and motor phase conductors manage 400-800V switching transients. Silicon carbide inverter adoption is compressing physical space for these assemblies, favoring laminated configurations with integrated EMI shielding.
- Charging Stations:DC fast charger internal busbars and cable management systems handle 350A+ sustained currents. ChargePoint and EVgo specify nickel-plated copper for connector interface durability across 10,000+ mating cycles.
- Electric Motors:Stator winding terminations and controller links require flexible geometries for thermal expansion accommodation. Hairpin motor designs from BorgWarner and Valeo are reshaping busbar routing in integrated drive units.
Battery storage applications anchor supplier relationships. Charging infrastructure delivers the steepest volume trajectory as depot electrification accelerates.
End User:
Procurement authority and specification control separate integrated platform decisions from aftermarket and fleet retrofit opportunities.
- OEMs:Volkswagen, BMW, and Mercedes-Benz qualify busbar suppliers through 24-36 month platform development cycles with ASIL-D functional safety requirements. Cell-to-pack architectures are collapsing module-level supplier tiers into single-source laminated system awards.
- Aftermarket Providers:Independent service networks and repair shops source standardized busbar kits for collision repair and warranty extensions. Catalog distributors like Digi-Key and Mouser are expanding EV-specific high-voltage interconnect inventories.
- Fleet Operators:Municipal transit authorities and logistics companies specify total-cost-of-ownership terms with 15-year corrosion warranties. California Air Resources Board compliance deadlines are accelerating depot busbar procurement for school bus and drayage truck electrification.
- Utilities:Distribution network operators deploy busbar assemblies for grid-scale battery storage and vehicle-to-grid integration pilots. Pacific Gas & Electric and Southern California Edison are testing bidirectional charging hardware with 350A reverse-current-rated busbar systems.
OEMs control the specification base. Fleet operators are gaining share fastest as performance-guaranteed service contracts displace component sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes busbar assemblies for mass-market battery enclosures where aluminum dominates, while Germany specifies copper-intensive laminated systems for performance EV platforms, and the United States splits demand between fleet depot infrastructure and integrated OEM supply chains.
China
NEV credit mandates from MIIT accelerate 800V platform rollouts across BYD and NIO vehicle lines. GB standards for high-voltage safety tighten insulation specifications on cell-to-pack interconnects. The Yangtze River Delta cluster around Shanghai and Suzhou concentrates CATL and BYD battery assembly, pulling laminated busbar procurement toward local fabricators.
Germany
Volkswagen, BMW, and Mercedes-Benz operate vertically integrated battery-pack assembly in Lower Saxony and Bavaria. ECE R100 thermal containment rules mandate thicker dielectric layers for 5-minute no-fire propagation standards. The industrial corridor between Wolfsburg and Munich anchors European procurement of insulated busbar systems with ASIL-D functional safety certification.
United States
EPA tailpipe emissions standards and NHTSA fuel economy rules accelerate dedicated EV platform transitions at Ford and General Motors. California Air Resources Board compliance deadlines drive depot electrification for school bus and drayage truck fleets. The Midwest manufacturing belt spanning Michigan and Ohio concentrates stamping and welding capacity for copper-aluminum hybrid joints.
India
PLI scheme incentives for ACC battery manufacturing attract busbar suppliers to Gujarat and Tamil Nadu. BIS certification requirements for high-voltage interconnects delay market entry for unqualified foreign fabricators. The automotive corridor between Pune and Chennai localizes content for Tata Motors and Mahindra Electric as cell production scales.
South Korea
Hyundai and Kia's E-GMP platform volumes pull demand for flexible busbar ribbons in cell-to-pack architectures. MFDS-equivalent automotive safety regulations align with ISO 26262 ASIL-D qualification timelines. The Seoul Capital Area and Busan-Ulsan industrial zone concentrate LG Energy Solution and SK On cell manufacturing, integrating conductor procurement into captive supply chains.
Busbar for EV Market Competitive Landscape
Capability concentration sits with tier-one integrated system suppliers; scale advantage sits with commodity conductor fabricators. The market structures around three tiers: multinational electrical equipment conglomerates with platform licensing power, specialized interconnect manufacturers with miniaturization expertise, and regional metal formers serving cost-sensitive retrofit channels. Two competitive moves dominate: backward integration into plating chemistry and resin compounding to secure input supply, and strategic partnerships with solid-state battery developers to pre-qualify conductor geometries for next-generation cell formats.
Within the integrated systems tier, Schneider Electric and Siemens exemplify European-origin conglomerates that leverage industrial electrification heritage into high-voltage automotive contracts. TE Connectivity occupies a position among specialized interconnect manufacturers, representing the miniaturization-focused archetype that targets space-constrained battery module zones. These three anchors illustrate how supplier value capture diverges between platform-level system integration and component-level engineering specialization.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Schneider Electric |
| Siemens |
| Rogers Corporation |
| Leoni AG |
| APTIV |
| Mersen SA |
| Ennovi |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian electroplating facilities is compressing input costs for nickel and silver surface treatments while simultaneously eroding pricing power for commodity busbar fabricators serving China's NEV sector.
Pricing Analysis
Long-term offtake contracts dominate procurement between German OEMs and laminated busbar suppliers, locking in volume commitments that insulate tier-one providers from LME copper volatility while exposing smaller fabricators to spot-market margin squeezes. Price differentiation rests on ASIL-D certification tier and plating chemistry specification, with certified suppliers commanding premiums over uncertified competitors. Cost compression in bare aluminum busbar tiers is intensifying because Chinese cell-to-pack architectures are eliminating module-level assemblies. Fleet operators exhibit the highest price sensitivity due to total-cost-of-ownership procurement models, whereas performance EV OEMs prioritize conductivity metrics over unit economics.
Supply Chain Analysis
Export control regimes restricting advanced welding equipment flows to certain jurisdictions are fragmenting ultrasonic bonding capacity across regional supplier bases. Raw material sourcing concentrates in Chile for copper cathode and Guinea for bauxite-alumina feedstock, with secondary refining anchored in China and Germany. The supply chain draws from East Asian specialty chemical suppliers for electroplating electrolytes, creating single-source vulnerability during demand surges. Distribution runs through tier-one system integrators that consolidate conductor, insulation, and sensor components into platform-certified assemblies for direct OEM delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among vertically integrated battery OEMs that are collapsing multi-tier supplier structures into single-source laminated system awards, fragmenting negotiating leverage for incumbent component vendors.
For Market Incumbents: Build captive plating chemistry capabilities to secure nickel and silver electroplating supply against East Asian input bottlenecks. Add ultrasonic welding capacity in Lower Saxony to defend against cell-to-pack architectures eliminating traditional module-level busbar tiers. ISO 26262 ASIL-D certification investment remains essential as qualification timelines extend platform lock-in periods. For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat and Tamil Nadu corridors where PLI-linked ACC battery manufacturing is localizing content requirements for Tata Motors and Mahindra Electric. Target flexible busbar ribbon formats for solid-state battery prototypes where incumbent rigid laminated suppliers lack qualified geometries. Pursue partnerships with oxide and sulfide electrolyte developers to pre-qualify conductor designs before platform specification freezes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated sensing-capable busbar assemblies as embedded telemetry and digital twin integration become standard fleet procurement requirements. Acquisition targets should display closed-loop copper recycling partnerships that satisfy EU Battery Regulation mass-balance certification mandates. Monitor solid-state battery platform announcement cadence as the inflection signal for flexible conductor format demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plating Chemistry | Captive nickel and silver electroplating capacity insulates margins against East Asian supply bottlenecks during demand surges. |
| Solid-State Battery Partnership | Pre-qualified flexible busbar geometries for Toyota and QuantumScape prototypes secure next-generation platform specifications. |
| ASIL-D Certification Investment | Functional safety qualification from TÜV or DEKRA accelerates approval cycles with Volkswagen and BMW platform teams. |
| Closed-Loop Recycling Partnership | Mass-balance copper provenance documentation satisfies ECE R100 and EU Battery Regulation mandates for German OEM supply. |
| Embedded Sensor Capability Development | Predictive maintenance telemetry integration captures fleet operator service contracts shifting from component sales to performance guarantees. |
Research Methodology
The analysis maps conductor geometry configurations, material grade specifications, and insulation system tiers, each validated through primary interviews with OEM platform engineers, tier-one supplier procurement directors, battery pack assembly technicians, and fleet operator maintenance heads. Secondary sources include vehicle production databases from IHS Markit, SEC 10-K filings from listed electrical equipment suppliers, customs trade data for copper and aluminum semi-finished products, and ECE R100 regulatory documentation. Bottom-up cell-level demand estimates were triangulated against top-down OEM platform production forecasts.
Assumptions regarding 800V architecture penetration rates, cell-to-pack adoption timelines, and solid-state battery commercialization pathways were held fixed across baseline scenarios while aluminum alloy substitution rates and plating chemistry cost trajectories were varied in sensitivity testing. Segmentation dimensions modeled include product type, material grade, application voltage class, and end-user procurement authority. CAGRs were derived from slope-log regression across the projection horizon, with inputs from silicon carbide inverter adoption curves and NEV credit mandate compliance schedules.
Stress conditions across LME copper price bands, electroplating capacity utilization thresholds, and welding technician training pipeline lag times were modeled; outcomes outside those bands fall beyond the analytical envelope. Material shifts in solid-state battery cell format standardization or ECE R100 thermal containment test protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
Asia Pacific Electric Scooter Market
Electric Vehicles
Luxury Electric Vehicle Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Electric Sports Utility Vehicle (E-SUV) Market
Electric Vehicles
France E-Bike Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
Battery-Swapping for Electric Two-Wheeler Market
Electric Vehicles
Electric Vehicle Electric Heating Film Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market