
 Canada Solar E-Bike Market | 2026-2036
Canada Solar E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Solar E-Bike Market Insights
Urban delivery services is rebalancing the end-user composition as fleet operators replace conventional last-mile vans with solar-assisted electric bicycles. Daymak leverages its Ontario manufacturing base to supply integrated solar charging systems for commercial logistics clients. Biktrix anchors its position through heavy-duty cargo configurations designed for Canadian weather extremes. Rad Power Bikes competes via direct-to-consumer channels that bypass traditional retail markups.
A solar e-bike combines photovoltaic panel integration with battery-electric propulsion, typically incorporating monocrystalline silicon cells rated between 15 and 25 watts that trickle-charge a 48V lithium-ion pack during daylight operation; the primary purpose is extending range between plug-in charges for commuter and utility cycling applications. Commuter product types dominate unit volume as Toronto and Montreal workers substitute car trips with weather-protected solar-assisted cycling. Fleet operators represent the fastest-growing end-user segment because delivery services amortize fuel savings across high-utilization routes. Battery components command the largest margin pool due to cell chemistry specialization and cold-climate performance requirements.
Health Canada and Transport Canada shape product safety standards through electrical system certifications and vehicle classification rules that determine where solar e-bikes may operate legally. Provincial regulators including BC Hydro and Ontario's Ministry of Transportation administer rebate programs that directly influence consumer purchase decisions. Stakeholders must monitor how municipal bylaws evolve to accommodate solar charging infrastructure on public rights-of-way.
Market Dynamics
Fleet electrification mandates from Ontario and British Columbia are compressing procurement timelines for commercial solar e-bike deployments, forcing manufacturers to accelerate cold-weather battery validation cycles.
Growth Catalysts
- Clean Mobility Rebates:British Columbia's provincial incentive programs reduce upfront acquisition costs for urban delivery fleets operating in Metro Vancouver corridors.
- Fleet Operators:Last-mile logistics providers in Toronto are substituting diesel vans with solar-assisted cargo bicycles to circumvent congestion pricing zones.
- Monocrystalline Silicon:Advances in panel efficiency are extending trickle-charge rates during low-light winter conditions prevalent across Canadian latitudes.
Market Restraints
- Lithium Carbonate Volatility:Cell chemistry costs fluctuate with commodity markets, squeezing margins on 48V battery packs optimized for sub-zero operation.
- Single-Source Panel Supply:Photovoltaic module production concentrates with Asian contract manufacturers, exposing assemblers to tariff and shipping disruptions.
- Range Anxiety in Winter:Cold-climate performance degradation limits solar charging contribution during December-February peak delivery seasons.
Strategic Opportunities
- Quebec Expansion:Montreal's cycling infrastructure investments create underpenetrated corridors for solar e-bike commuter adoption outside Toronto-Vancouver dominance.
- Grid-Interactive Charging:Vehicle-to-building protocols allow fleet batteries to participate in BC Hydro demand-response programs during peak evening loads.
- Municipal Electrification:Calgary and Ottawa are piloting solar charging station networks on public rights-of-way, reducing depot infrastructure requirements.
Industry Challenges
- Battery Thermal Management:Engineers with cold-climate lithium-ion expertise command premium compensation, constraining R&D team scaling.
- Transport Canada Classification:Vehicle categorization rules determine street-legal operation zones, creating province-by-province certification complexity.
- Photovoltaic Integration Standards:Absence of unified electrical system certifications delays product launches across provincial jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Solar E-Bike Market |
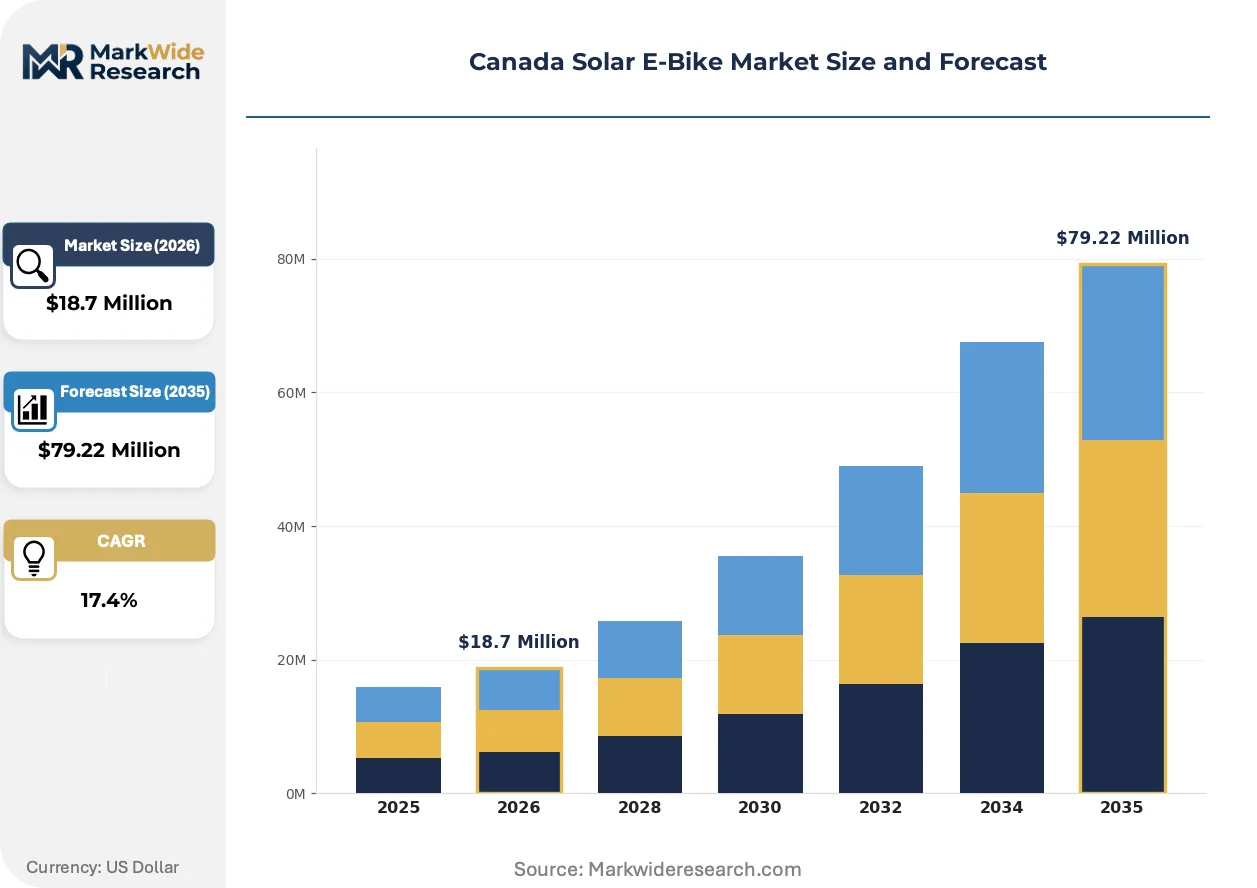
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $79.22 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foldable, Mountain, Commuter, Cruiser Component: Battery, Motor, Solar Panel, Charger End User: Urban Riders, Recreational Users, Delivery Services, Fleet Operators Distribution Channel: Retail, E-Commerce, Direct Sales, Distributors |
| Companies Covered | Daymak, Biktrix, OHM Cycles, Surface 604, Rad Power Bikes, VoltBike, ENVO Electric Bikes, Rize Bikes, Lectric eBikes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Solar E-Bike Market Trends and Innovations
Hardware-software convergence is redefining how solar e-bike systems optimize energy capture, storage, and dispatch across variable Canadian weather patterns.
Perovskite-silicon tandem cells are integrating into next-generation panel arrays, boosting low-light efficiency by capturing broader spectrum wavelengths. Toronto-based fleet operators are piloting these modules on high-utilization delivery routes where winter irradiance drops sharply. This photovoltaic advancement is integrating with predictive battery management algorithms that pre-condition cell temperatures before dawn charging cycles.
Health Canada's updated electrical system certifications are mandating IP67 ingress protection for solar charging controllers exposed to road spray and slush. The regulatory tightening disqualifies consumer-grade electronics from commercial fleet deployments. Ontario manufacturers are responding by redesigning junction boxes with marine-grade sealing, adding eight to twelve weeks to product validation timelines.
Direct-to-consumer channels are displacing traditional bicycle retail networks for solar e-bike purchases. Urban commuters in Vancouver and Montreal now configure battery capacity and panel wattage through online portals before factory fulfillment. This disintermediation concentrates customer acquisition spend with digital platforms rather than local dealer networks, altering post-sale service expectations toward mobile technician dispatch models.
Canada Solar E-Bike Market Segmentation
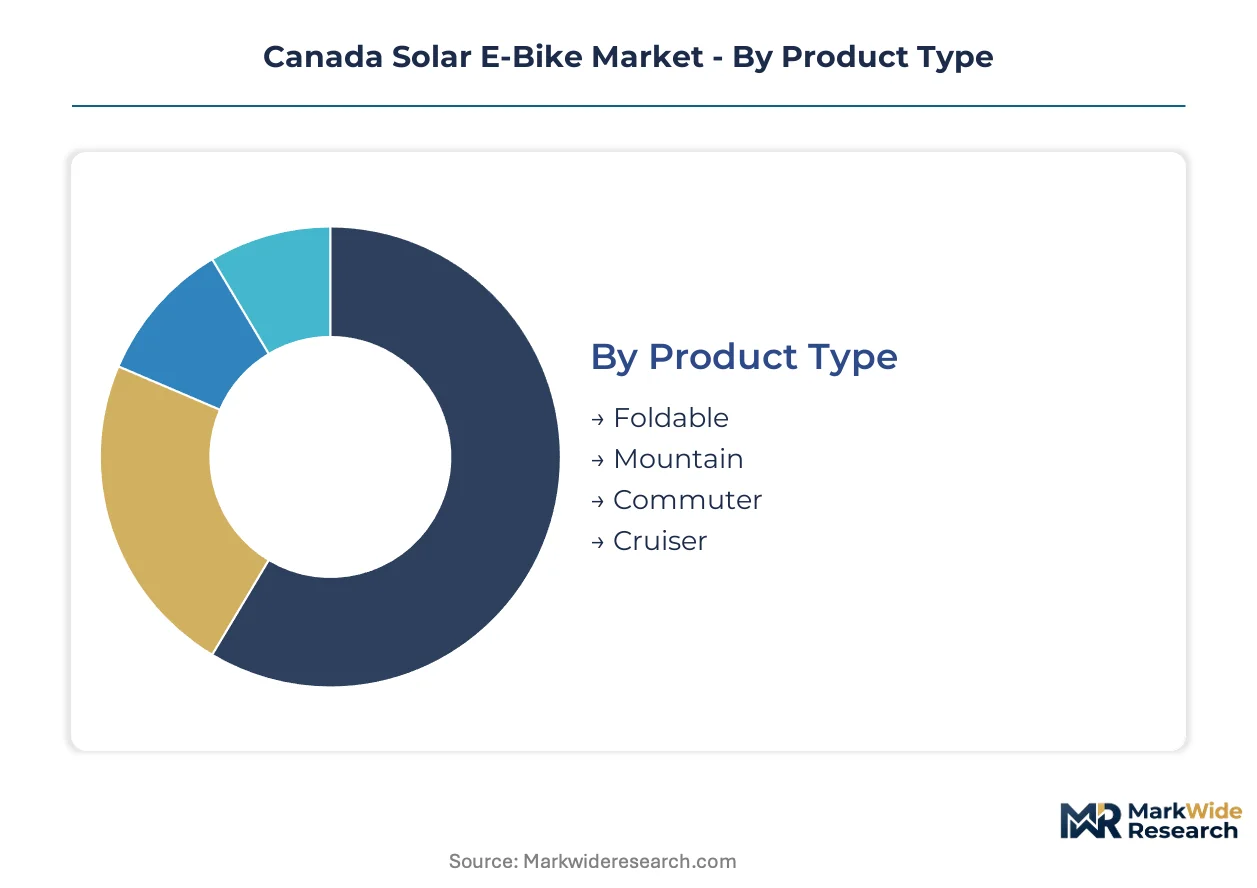
Canada's solar e-bike market segments along four dimensions that reflect divergent buyer priorities across urban mobility, commercial logistics, and recreational cycling. Product configuration, component sourcing, end-use application, and purchase channel each shape how manufacturers allocate R&D investment and distribution resources.
Product Type:
Urban commuters prioritize weather protection and cargo capacity; recreational buyers emphasize terrain handling and foldability for multi-modal transit.
- Commuter:Step-through frames with integrated fenders and rack systems dominate Toronto and Vancouver urban corridors. Demand concentrates among professionals substituting car trips for solar-assisted cycling along separated bike lane networks.
- Mountain:Full-suspension configurations with reinforced solar panel mounting systems address British Columbia's trail networks and Alberta's recreational demand. Buyers prioritize battery thermal management for backcountry temperature swings.
- Foldable:Compact designs with detachable solar arrays serve multi-modal commuters combining cycling with GO Transit and SkyTrain connections.
- Cruiser:Upright seating geometries with oversized solar trunk racks attract recreational users in Ontario's lake country and Quebec's resort corridors.
Volume sits with Commuter configurations; growth tilts toward Mountain variants as trail infrastructure expands in Western Canada.
Component:
Margin concentration varies sharply across the four component categories, with cold-climate performance requirements elevating certain subsystems above commodity pricing.
- Battery:48V lithium-ion packs with active thermal management command premium pricing due to sub-zero range preservation requirements. Cell chemistry specialization for Canadian winters drives procurement decisions among fleet operators.
- Solar Panel:Monocrystalline silicon arrays rated 15-25 watts integrate into frame tubing and rear racks. Low-light efficiency during December-February operations determines panel selection for commercial deployments.
- Motor:Hub-drive and mid-drive configurations balance torque delivery against weather-sealing requirements for slush and road spray exposure.
- Charger:IP67-rated controllers with Health Canada electrical certifications add validation timelines but unlock fleet procurement eligibility.
Revenue pools deepest in Battery procurement; supplier competition intensifies fastest in Solar Panel sourcing as Asian contract manufacturers expand module efficiency.
End User:
Commercial utilization patterns diverge fundamentally from consumer purchase cycles, with fleet procurement compressing decision timelines and elevating service-level requirements.
- Fleet Operators:Last-mile logistics providers in Toronto's congestion pricing zones and Vancouver's Metro Core deploy solar-assisted cargo bicycles for high-utilization routes. Fuel cost amortization and parking exemption access drive replacement of diesel vans.
- Delivery Services:Food and parcel couriers prioritize swappable battery systems and rapid solar trickle-charging between drops. Seasonal demand spikes during holiday periods stress thermal management systems.
- Urban Riders:Commuters in Montreal and Calgary substitute solar e-bikes for car ownership, configuring systems through direct-to-consumer portals.
- Recreational Users:Weekend cyclists in Ontario's cottage country and British Columbia's wine regions value extended range for rural exploration without plug-in dependency.
Unit sales concentrate with Urban Riders; expansion accelerates most steeply among Fleet Operators as provincial electrification mandates tighten compliance deadlines.
Distribution Channel:
Channel selection determines post-sale service architecture, with direct models shifting warranty fulfillment toward mobile technician networks rather than dealer service bays.
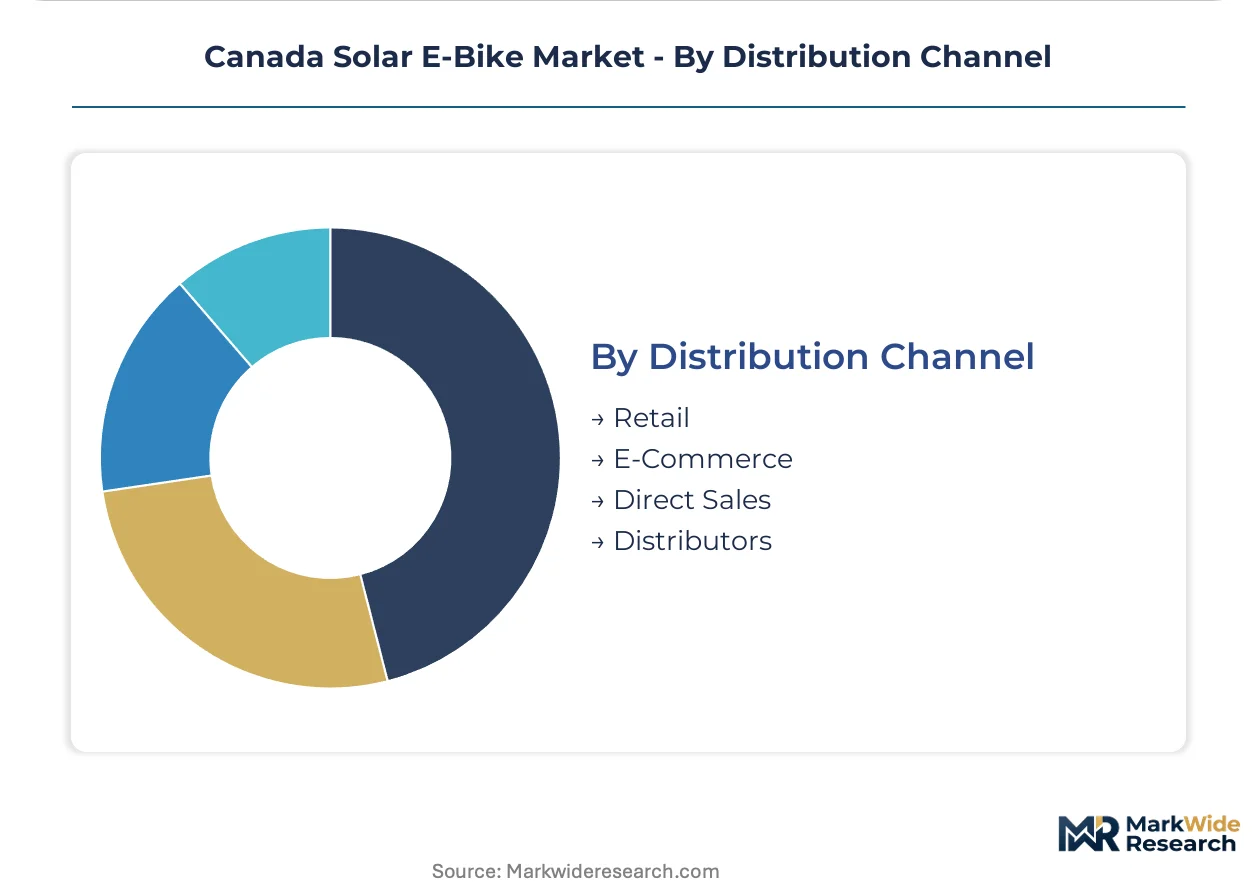
- E-Commerce:Online configuration portals allow battery capacity and panel wattage selection before factory fulfillment. Digital customer acquisition concentrates spend away from traditional bicycle retail networks.
- Direct Sales:Manufacturer-owned showrooms in Toronto and Vancouver offer test-ride facilities and same-day mobile service dispatch for commercial accounts.
- Retail:Independent bicycle dealers provide assembly and maintenance services for consumers prioritizing local service relationships.
- Distributors:Regional wholesalers serve Quebec and Prairie provinces with inventory positioning that reduces delivery timelines for fleet procurement.
Transaction volume flows through E-Commerce; channel investment shifts most aggressively toward Direct Sales as manufacturers capture margin and control service quality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian solar e-bike production concentrates in Ontario and Quebec manufacturing corridors, while consumption clusters in coastal metropolitan areas where municipal electrification programs intersect with dense cycling infrastructure. This geographic split shapes distribution networks and service architectures across provincial boundaries.
Ontario
Toronto's congestion pricing zones and last-mile delivery density drive fleet operator procurement at scale. Transport Canada vehicle classification rules determine street-legal operation parameters for solar-assisted cargo bicycles. The Greater Toronto Area hosts multiple assembly operations supplying integrated solar charging systems to commercial logistics clients.
British Columbia
Metro Vancouver's municipal electrification programs and BC Hydro clean mobility rebates accelerate consumer uptake among urban commuters. Health Canada electrical system certifications mandate IP67 ingress protection for controllers exposed to coastal precipitation. Vancouver corridors concentrate pilot deployments of perovskite-silicon tandem cell arrays for winter low-light conditions.
Quebec
Montreal's expanding separated bike lane networks create underpenetrated demand corridors outside Toronto-Vancouver dominance. Provincial clean mobility incentives administered through regional transit authorities influence purchase decisions. The Montreal metropolitan area attracts direct-to-consumer fulfillment operations targeting francophone commuter segments.
Alberta
Calgary's pilot solar charging station networks on public rights-of-way reduce depot infrastructure requirements for fleet operators. Municipal electrification programs prioritize grid-interactive charging protocols. The Calgary-Edmonton corridor demonstrates recreational demand for mountain-configured solar e-bikes across trail networks.
Atlantic Canada
Halifax and St. John's municipal governments explore solar charging infrastructure for coastal delivery services facing harsh maritime winters. Provincial rebate programs lag Ontario and British Columbia in incentive magnitude. Limited cycling infrastructure investment constrains commuter adoption relative to central Canadian corridors.
Canada Solar E-Bike Market Competitive Landscape
Top-tier vendors anchor integrated solar charging system production, while mid-tier assemblers compete on cargo configuration specialization. The vendor base stratifies across three archetypes: Ontario-based manufacturers with captive solar panel integration, direct-to-consumer digital natives bypassing retail markups, and regional distributors serving Quebec and Prairie provinces with inventory positioning. Competitive moves concentrate on cold-weather battery validation acceleration and Health Canada certification timeline compression.
Among Ontario-based manufacturers, Daymak and Biktrix occupy distinct positioning archetypes. Daymak represents the integrated solar charging tier with manufacturing base leverage for commercial logistics supply. Biktrix exemplifies heavy-duty cargo configuration specialization designed for Canadian weather extremes. Rad Power Bikes anchors the direct-to-consumer vector, demonstrating digital-native customer acquisition models that displace traditional bicycle retail networks. These three patterns illustrate how geographic origin and channel strategy stratify competitive positioning across the provincial market.
| Leading Market Players |
|---|
| Daymak |
| Biktrix |
| OHM Cycles |
| Surface 604 |
| Rad Power Bikes |
| VoltBike |
| ENVO Electric Bikes |
| Rize Bikes |
| Lectric eBikes |
| Others |
Pricing and Supply Chain Analysis
Fleet operator procurement concentration in Toronto and Vancouver corridors anchors contract-based long-term offtake as the dominant pricing model, with volume commitments from last-mile logistics providers compressing margins for 48V battery pack suppliers.
Pricing Analysis
Margin tightening in the battery tier reflects lithium carbonate volatility and cold-climate cell chemistry specialization. Three-tier pricing structure across premium, standard, and economy levels separates fleet-certified configurations with Health Canada IP67 validation from consumer-grade alternatives. Cost compression accelerates because Asian contract manufacturers are expanding monocrystalline silicon module capacity. Urban commuters demonstrate highest price sensitivity through direct-to-consumer portal configuration behavior, while fleet operators prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Single-source vulnerability sits with photovoltaic module production concentrated among Asian contract manufacturers, exposing assemblers to tariff and shipping disruptions. Cell chemistry inputs draw from China, South Korea, and Japan, while monocrystalline silicon wafer supply rests on Taiwanese and Malaysian production hubs. Commodity price volatility in lithium carbonate markets creates margin instability for 48V pack assemblers. Distribution runs through manufacturer-direct fulfillment centers in Toronto and Vancouver, supplemented by regional distributors serving Quebec and Prairie provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-climate battery thermal management expertise constitutes the binding capacity constraint, propping pricing for qualified engineering talent and validated pack configurations across the procurement landscape.
For Market Incumbents: Anticipate margin compression from direct-to-consumer digital natives bypassing traditional retail markups by accelerating Health Canada certification timeline compression and securing captive supply of IP67-rated charging controllers. Backward integration into junction box assembly reduces exposure to marine-grade sealing validation delays. For New Entrants and Emerging Players: Enter via Montreal's underpenetrated separated bike lane corridors, where francophone commuter segments remain underserved by Toronto-Vancouver fulfillment operations. Quebec's provincial clean mobility incentives administered through regional transit authorities create accessible procurement pathways absent congestion pricing zone complexity. For Investors and Strategic Acquirers: The window for entry favors Ontario-based assemblers with integrated solar charging system capabilities and existing Health Canada electrical certifications. Cold-climate lithium-ion R&D team scaling constraints signal inflection when engineering compensation premiums compress project feasibility timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Certification Investment | IP67 ingress protection validation unlocks fleet procurement eligibility and commercial account access. |
| Perovskite-Silicon Tandem Cell Integration | Low-light efficiency gains capture winter irradiance drops across Toronto and Vancouver delivery routes. |
| Direct-to-Consumer Portal Launch | Digital configuration shifts customer acquisition spend from dealer networks to factory fulfillment control. |
| Quebec Distribution Partnership | Regional inventory positioning reduces delivery timelines for Montreal metropolitan francophone segments. |
| Grid-Interactive Charging Protocol Development | BC Hydro demand-response participation creates ancillary revenue streams from fleet battery assets. |
Research Methodology
Document review covered Transport Canada vehicle classification filings, BC Hydro clean mobility program disclosures, and Health Canada electrical system certification records, complemented by interviews with fleet procurement managers at Toronto last-mile logistics providers, Ontario-based manufacturing operations leads, and Quebec regional distributor principals. Secondary validation drew from provincial transportation ministry rebate program documentation, municipal cycling infrastructure investment announcements, and lithium carbonate commodity market assessments. Bottom-up unit demand estimates from fleet operator deployment schedules triangulated against top-down market value projections.
Unit shipment and value estimates across the projection horizon reflect segmentation by product type, component category, end-user archetype, and distribution channel, with particular attention to cold-climate performance tier differentiation. CAGRs were derived from logistic adoption curve fitting against provincial electrification mandate compliance deadlines. Forecast inputs incorporated battery thermal management validation timelines and perovskite-silicon tandem cell pilot deployment outcomes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium carbonate price spike scenarios or Transport Canada classification rule revisions. Projections assume continued BC Hydro and Ontario Ministry of Transportation rebate program continuity without federal incentive restructuring. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Saudi Arabia E-Bike Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
E-SUV Market
Electric Vehicles
Europe Hybrid Electric Vehicle Battery Market
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Asia-Pacific Electric Vehicle (EV) Fluids Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
Mexico Automotive High Performance Electric Vehicle Market
Electric Vehicles
Agricultural Electric Vehicles Market
Electric Vehicles
Electric Vehicle Panoramic Sunroof Market
Electric Vehicles
Solar Car Market
Electric Vehicles
Belgium Solar E-Bike Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Norway Electric Cars Market