
 Global Automotive Inductive Wireless Charging Systems Market | 2026-2036
Global Automotive Inductive Wireless Charging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Inductive Wireless Charging Systems Market Intelligence
The replacement of standard copper wiring with high-frequency litz wire in charging pads is shifting the cost-performance balance for resonant systems. WiTricity Corporation specializes in the licensing of its magnetic resonance technology patents. Qualcomm Technologies leverages its Halo portfolio to secure design wins with major automotive OEMs. Meanwhile, Continental AG focuses on integrating these systems into vehicle architectures as a Tier-1 supplier.
Automotive inductive wireless charging systems are solutions that transfer electrical energy from a ground-based pad to a vehicle-mounted receiver via an electromagnetic field. These systems typically operate in the 85 kHz frequency band and are designed to achieve power transfer efficiencies above 90%. Resonant inductive coupling technology dominates due to its tolerance for misalignment between the charging pads. While electric passenger cars constitute the largest application by volume, integrated systems designed for public transit buses represent a high-margin opportunity for suppliers.
Market access depends on compliance with electromagnetic compatibility standards, governed by the FCC in the United States and CE marking directives in Europe. The SAE J2954 standard is critical for establishing interoperability and safety protocols for systems up to 11 kW. Original Equipment Manufacturers now face a strategic decision between developing proprietary charging ecosystems or committing to universal standards to maximize vehicle compatibility.
Market Dynamics
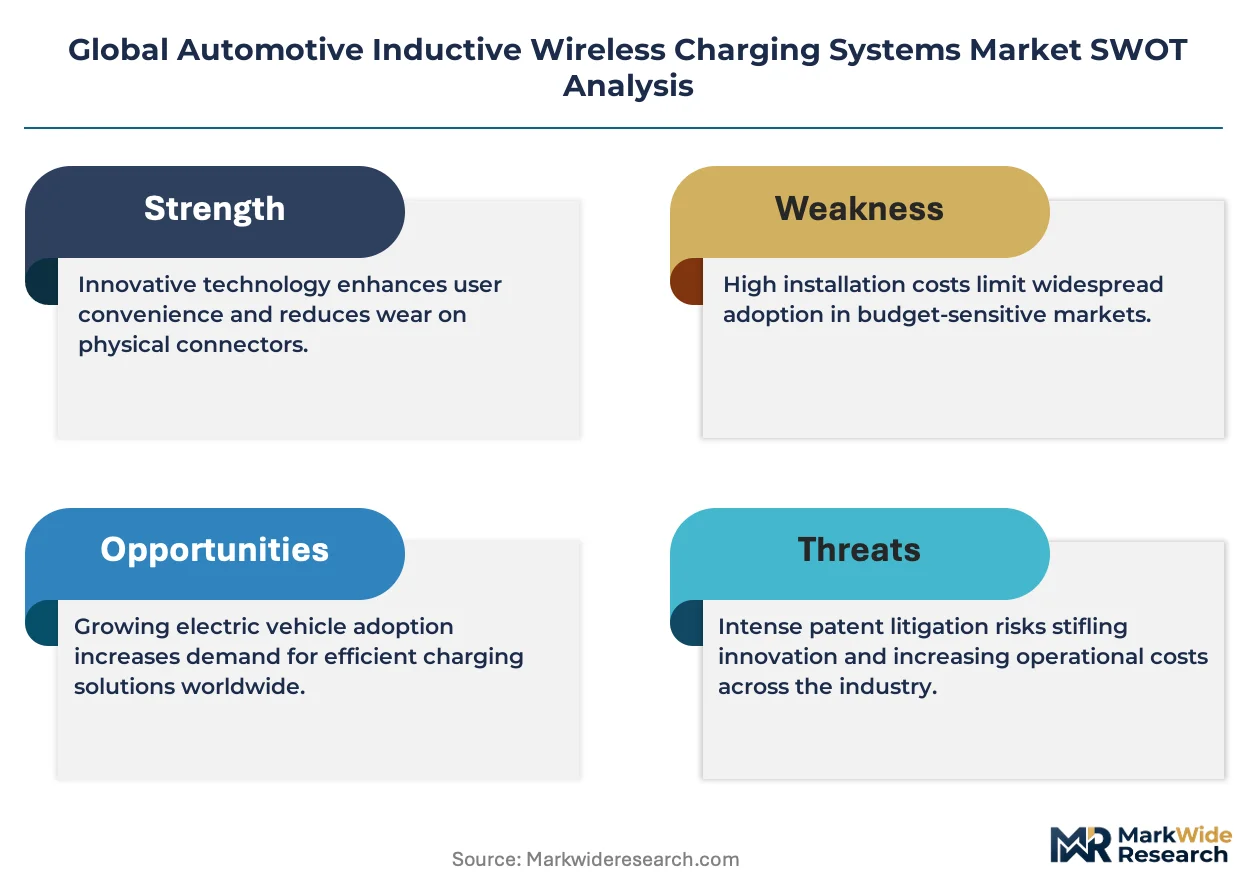
The central tension between developing proprietary charging ecosystems and committing to universal interoperability standards like SAE J2954 is the primary structural force shaping the market. This choice dictates OEM strategy, supply chain partnerships, and long-term infrastructure compatibility for consumers.
Growth Catalysts
- Municipal Fleet Mandates:Electrification targets for public transit fleets in cities across China and Germany are creating consistent, high-volume demand for scheduled, high-power wireless charging systems for buses.
- Resonant Coupling Technology:The maturation of resonant inductive coupling technology provides greater tolerance for vehicle misalignment, making the user experience more reliable and driving adoption in public and private parking environments.
- Standardization Efforts:The SAE J2954 standard provides a common technical protocol for interoperability between vehicle and charging pad brands, reducing fragmentation and giving infrastructure investors confidence in the technology's longevity.
Market Restraints
- Input Material Cost:The use of high-frequency litz wire, while essential for efficiency in resonant systems, carries a significant cost premium over standard copper wiring, impacting the price competitiveness of charging pads.
- Power Transfer Limitations:System efficiency degrades significantly with large vertical gaps or extreme lateral misalignment, posing a design constraint for vehicles with high ground clearance like SUVs and trucks.
- Regulatory Compliance Burden:Manufacturers must navigate and comply with distinct electromagnetic compatibility (EMC) requirements, such as FCC Part 18 in the United States and CE marking directives in Europe, increasing testing time and costs.
Strategic Opportunities
- Autonomous Vehicle Integration:The need for fully autonomous charging cycles for self-driving taxis and delivery pods creates a significant opportunity for integrated wireless systems that eliminate human intervention.
- Vehicle-to-Grid (V2G) Capability:Developing bidirectional wireless charging systems that allow EVs to transfer power back to the grid opens new revenue streams from ancillary grid services for fleet operators and homeowners.
- Aftermarket Conversions:A market exists for retrofitting first-generation electric vehicles with aftermarket wireless charging receivers, targeting enthusiasts and owners seeking to upgrade their charging convenience.
Industry Challenges
- High-Power Standardization:The lack of a finalized, globally accepted standard for wireless charging above 11 kW is delaying the deployment of faster charging solutions for passenger cars and light commercial vehicles.
- Thermal Management Complexity:Dissipating heat generated from energy losses in both the ground pad and the vehicle receiver, especially at higher power levels, presents a significant engineering and materials science challenge.
- Vehicle Integration Hurdles:Integrating the vehicle-side receiver pad and its associated electronics without compromising vehicle dynamics, ground clearance, or manufacturability remains a complex task for automotive engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Inductive Wireless Charging Systems Market |
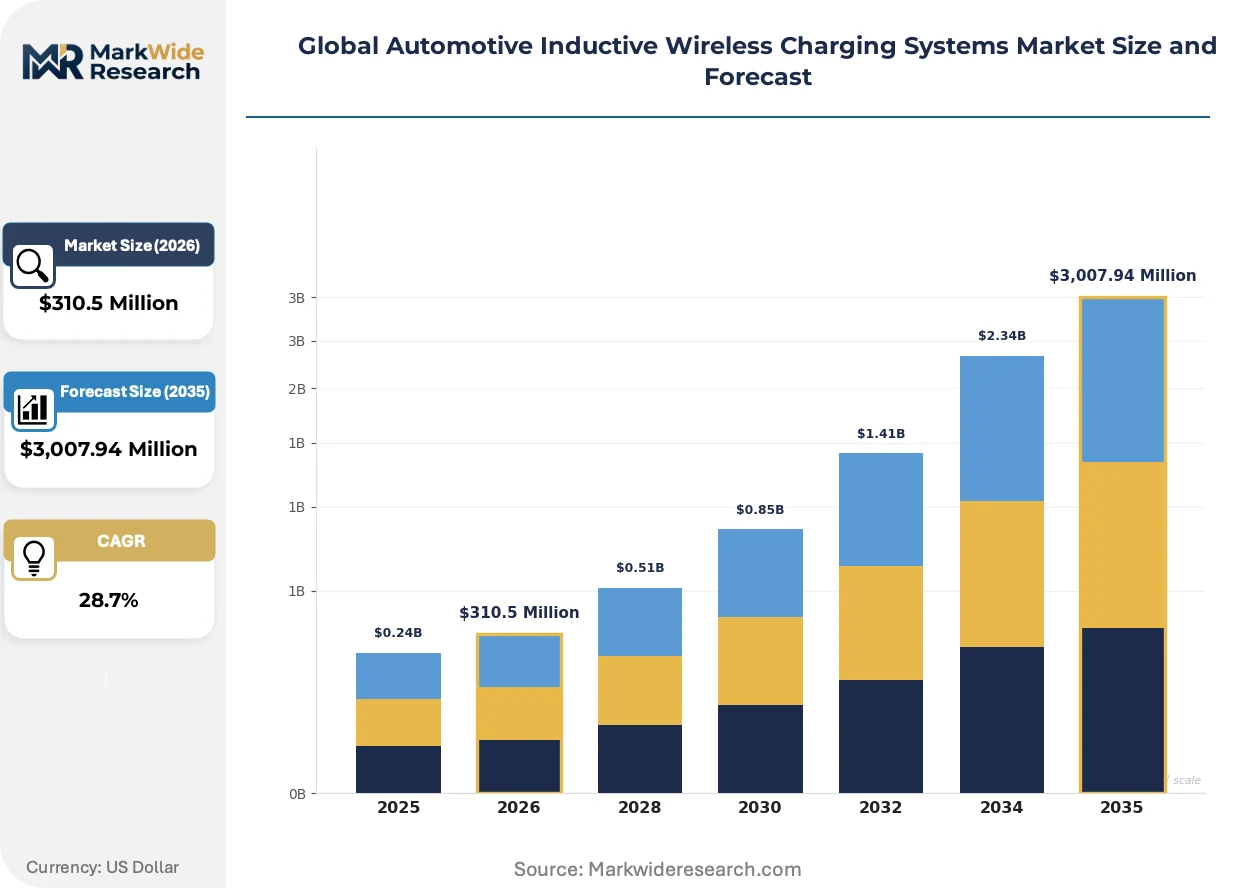
| Market Size in 2026 | $310.5 Million |
| Market Size in 2035 | $3,007.94 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Systems, Add-on Modules, Portable Chargers, Embedded Plates, Retrofit Kits Technology: Resonant Inductive Coupling, Magnetic Resonance, Radio Frequency, Capacitive Coupling, Infrared Transmission Application: Electric Passenger Cars, Public Transit Buses, Commercial Payload Vehicles, Autonomous Delivery Units, Shared Mobility Fleets End User: Original Equipment Manufacturers, Tier-1 Component Suppliers, Vehicle Maintenance Service Providers, Specialty Dealers |
| Companies Covered | WiTricity Corporation, Qualcomm Technologies, Samsung Electronics, Toyota Motor Corporation, Robert Bosch GmbH, Continental AG, Toshiba Corporation, Momentum Dynamics Corporation, InductEV Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Inductive Wireless Charging Systems Market Strategic Shifts & Innovations
Innovation is shifting from pure power transfer breakthroughs to enhancing system intelligence, efficiency, and integration. The market is moving toward solutions that are not just functional but are also seamless extensions of the vehicle and the surrounding energy infrastructure.
The use of wide-bandgap semiconductors like Gallium Nitride (GaN) in power electronics is a key development. Automotive Tier-1 suppliers are adopting GaN components to build smaller, lighter, and more efficient inverters for both ground and vehicle units. The superior switching frequency of GaN technology is rewriting the physical footprint and thermal management requirements for high-power charging pads, enabling more compact designs.
Regulatory harmonization through the IEC 61980 series of standards is streamlining market access for manufacturers. This framework for wireless power transfer safety and functionality reduces the need for duplicative testing when entering new international markets. Public transit authorities in Europe and Asia are now frequently referencing IEC 61980 compliance in procurement tenders for bus depot charging infrastructure.
A distinct preference is forming among luxury EV owners for charging solutions that are fully integrated into the built environment, such as home garages or dedicated parking spaces. This disrupts the standalone hardware model, creating demand for systems sold through property developers and architects rather than traditional automotive channels. This trend is most advanced in new high-end residential and commercial construction projects in South Korea and the United States.
Global Automotive Inductive Wireless Charging Systems Market Segmentation
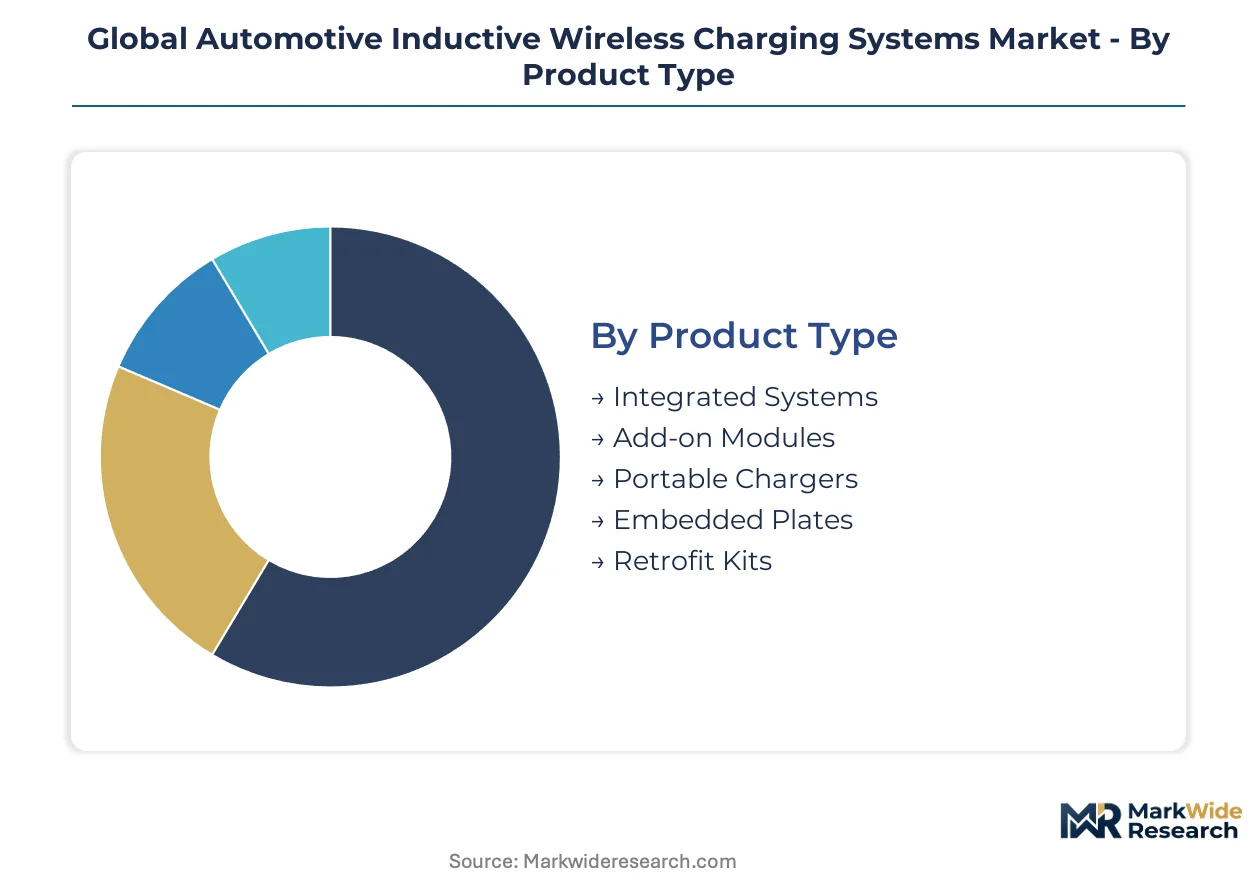
The automotive inductive wireless charging systems market exhibits diverse segmentation across product types, underlying technologies, application areas, and end-user profiles. Understanding these distinctions is critical for identifying specific demand pockets and strategic investment opportunities within the evolving landscape.
Product Type:
The volume versus premium split often dictates market entry strategies, with some product types targeting broad adoption while others focus on specialized convenience or performance.
- Integrated Systems:These solutions are factory-installed components, designed as an intrinsic part of the vehicle's original architecture, offering seamless operation and optimized performance. Demand concentrates in new electric vehicle models across Germany and China, driven by OEM commitments to advanced charging experiences.
- Add-on Modules:These systems provide an aftermarket option for enhancing existing electric vehicles with wireless charging capabilities, often comprising receiver pads and control units. Demand is growing in the United States for luxury EV owners seeking enhanced convenience without replacing their current vehicle.
- Portable Chargers:These flexible units offer temporary or mobile wireless charging solutions, often used for smaller electric vehicles or in situations requiring quick deployment. Their compact design supports niche applications like electric scooter charging.
- Embedded Plates:Ground-side charging plates are installed directly into parking spots or garage floors, providing a discreet and permanent infrastructure solution. This segment is gaining traction in new residential construction projects in South Korea.
- Retrofit Kits:These kits enable older electric vehicles to be converted for wireless charging, targeting enthusiasts and owners of first-generation EVs. The market for these kits is expanding among early adopters in Europe.
Mature deployment sits with Integrated Systems. Newer deployment is concentrated in Retrofit Kits.
Technology:
Maturity of underlying technologies influences system efficiency, power transfer capabilities, and tolerance for misalignment, directly impacting user experience and infrastructure requirements.
- Resonant Inductive Coupling:This technology utilizes magnetic resonance to transfer energy over larger air gaps and with greater tolerance for misalignment between charging pads. Its robust performance drives adoption in public transit bus fleets in China, where consistent operation is paramount.
- Magnetic Resonance:Leveraging principles of magnetic resonance, these systems enable efficient power transfer between vehicle and ground units, even with minor positional variations. WiTricity Corporation specializes in licensing patents for this core technology.
- Radio Frequency:This method employs radio waves for energy transfer, typically suited for lower power applications and smaller devices due to efficiency and range limitations. Research continues into its viability for very short-range, low-power automotive sensing.
- Capacitive Coupling:Utilizing electric fields for power transfer, capacitive coupling offers potential benefits in terms of cost and weight, but often requires precise alignment and struggles with higher power levels. Its application is limited in high-power automotive charging.
- Infrared Transmission:This technology transfers energy using infrared light, requiring a clear line of sight and exhibiting sensitivity to environmental factors like dust or fog. Practical automotive applications are currently minimal.
Innovations in Technology are driving system performance and market expansion.
Application:
Diverse application areas reflect varied operational demands and power requirements, from high-volume passenger vehicles to specialized commercial fleets.
- Electric Passenger Cars:This segment represents the largest volume application, driving demand for convenient home and public charging solutions. Original Equipment Manufacturers are integrating wireless charging into premium EV models to enhance the user experience.
- Public Transit Buses:Integrated systems designed for public transit buses represent a high-margin opportunity, with consistent, high-power charging requirements for scheduled routes. Municipal fleet electrification mandates in Germany are a significant demand driver.
- Commercial Payload Vehicles:This category includes electric vans and trucks used for logistics and delivery, where reliable and efficient charging directly impacts operational uptime. Autonomous delivery units are exploring this technology for seamless recharging.
- Autonomous Delivery Units:Self-driving vehicles require fully autonomous charging cycles, making integrated wireless systems essential for eliminating human intervention. This application presents a strategic opportunity for system developers.
- Shared Mobility Fleets:Car-sharing and ride-hailing services benefit from wireless charging by reducing vehicle downtime and operational costs associated with manual plugging in. Urban centers are piloting these solutions to improve fleet efficiency.
The Application landscape is characterized by distinct user needs and infrastructure investment patterns.
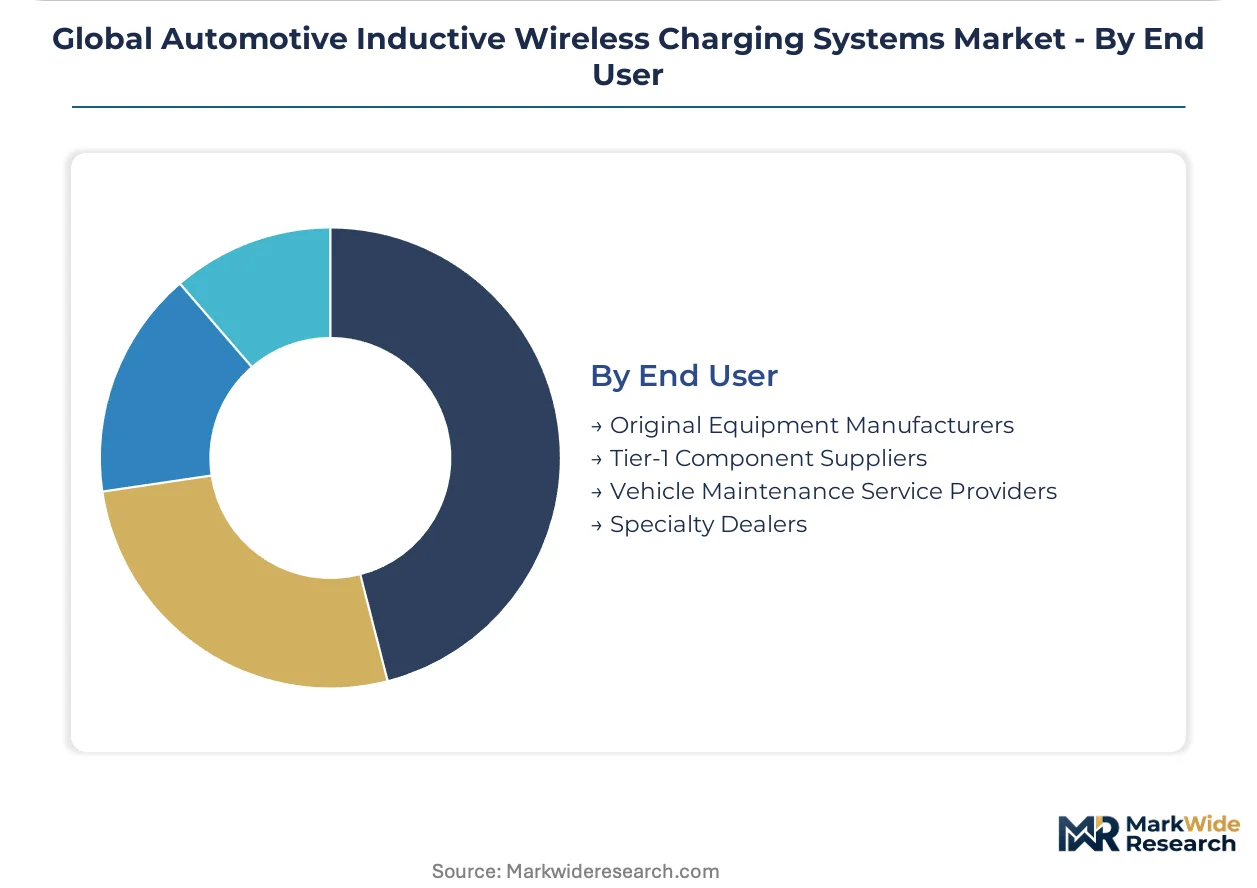
End User:
Participation across the value chain dictates the strategic influence of various end-user segments, from vehicle manufacturing to aftermarket service provision.
- Original Equipment Manufacturers:OEMs are central to market development, making strategic decisions between proprietary charging ecosystems and universal standards like SAE J2954. Qualcomm Technologies secures design wins with major automotive OEMs.
- Tier-1 Component Suppliers:These suppliers integrate wireless charging technology into vehicle architectures, acting as crucial intermediaries between technology developers and OEMs. Continental AG focuses on this integration role.
- Vehicle Maintenance Service Providers:As wireless charging systems become more prevalent, these providers will offer installation, diagnostics, and repair services for both vehicle-side and ground-side components. Training for specialized technicians is a nascent requirement.
- Specialty Dealers:These retailers may offer aftermarket wireless charging solutions and installation services, targeting consumers seeking upgrades for their existing electric vehicles. Their role is primarily in the retrofit market.
Strategic partnerships between Original Equipment Manufacturers and Tier-1 Component Suppliers are crucial for market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strategic industrial zones across several key economies are catalyzing the expansion of automotive inductive wireless charging systems. These zones leverage government support and concentrated technological expertise. This fosters an environment conducive to rapid infrastructure development and market adoption.
China
China's municipal fleet mandates are a primary driver for high-power wireless charging systems for buses. The nation's dual carbon goals support extensive EV infrastructure deployment. Cities like Shanghai and Shenzhen are implementing advanced charging solutions within their smart city initiatives.
Germany
German OEMs integrate wireless charging into new EV models, driven by a commitment to advanced user experiences. CE marking directives ensure system safety and electromagnetic compatibility across the European market. Automotive manufacturing hubs in Stuttgart and Munich focus on seamless vehicle integration.
United States
The United States sees demand from luxury EV owners seeking convenient add-on modules and autonomous delivery units. FCC Part 18 governs electromagnetic compatibility for wireless power transfer devices. California and Texas are piloting autonomous vehicle charging solutions in urban centers.
South Korea
In South Korea, new high-end residential and commercial construction projects are integrating embedded charging plates. National EV infrastructure policies encourage the development of advanced charging solutions. The Seoul Capital Area is a key region for smart city integration and property-developer led installations.
Japan
Japanese automotive manufacturers are actively exploring wireless charging for future autonomous vehicle integration. METI promotes research and development in advanced mobility technologies and EV infrastructure. Tokyo and Nagoya serve as R&D centers for next-generation automotive power solutions.
Global Automotive Inductive Wireless Charging Systems Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the competitive landscape. This market exhibits a tiered structure, with technology licensors, Tier-1 component suppliers, and automotive Original Equipment Manufacturers. Key archetypes include intellectual property holders, integration experts, and vehicle platform developers. Strategic partnerships and technology licensing agreements are prevalent competitive moves.
Technology innovators like WiTricity Corporation, a US-based company, exemplify the patent licensing model for magnetic resonance technology. Qualcomm Technologies, Inc., also based in the United States, occupies a position as a major technology provider through its Halo portfolio. Continental AG, a German-based Aktiengesellschaft, represents a Tier-1 supplier integrating these advanced systems directly into vehicle architectures for global OEMs.
| Leading Market Players |
|---|
| WiTricity Corporation |
| Qualcomm Technologies |
| Samsung Electronics |
| Toyota Motor Corporation |
| Robert Bosch GmbH |
| Continental AG |
| Toshiba Corporation |
| Momentum Dynamics Corporation |
| InductEV Inc. |
| Others |
Cost & Logistics Intelligence
Copper commodity prices, a key input for high-frequency litz wire, cascade through the supply chain, influencing the cost structure of charging pads and shaping OEM procurement strategies. This raw material volatility impacts pricing tiers for both integrated systems and aftermarket solutions.
Pricing Analysis
Short lead times for specialized high-power components command a premium, while standard integrated systems face increasing cost compression due to OEM volume targets. The dominant pricing model for core technology is licensing and royalty-based, supplemented by project-based fees for system integration. Price differentiation stems from power transfer efficiency, compliance with SAE J2954 standards, and the brand premium of automotive OEMs. Pricing pressure stems from the need for cost-effective mass-market adoption for passenger cars. Municipal fleets purchasing bus charging systems are generally more price-sensitive than luxury EV owners seeking add-on convenience modules.
Supply Chain Analysis
High-frequency litz wire production rests on specialized manufacturers, primarily concentrated in China and select European countries. The supply chain sources wide-bandgap semiconductors like Gallium Nitride (GaN) from a limited number of global suppliers. A structural supply chain risk is single-source vulnerability for patented magnetic resonance technologies. Distribution runs through Tier-1 component suppliers for integrated OEM solutions, and via specialty dealers and property developers for aftermarket and embedded systems, respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for automotive inductive wireless charging systems is currently supply-constrained, with the limited availability of high-power, thermally managed components propping up pricing for advanced solutions.
For Market Incumbents: Hedge against future supply chain disruptions by securing long-term contracts for wide-bandgap semiconductors and specialized litz wire. Invest heavily in advanced thermal management R&D to maintain a performance edge over emerging competitors. Consolidate intellectual property through strategic acquisitions to counter fragmentation in patent landscapes. Prioritize full compliance with IEC 61980 and SAE J2954 standards to reduce market access barriers.
For New Entrants and Emerging Players: IEC 61980 compliance in Europe and Asia opens a window for specialized high-power solutions above 11 kW. Target the public transit bus segment in rapidly urbanizing regions for consistent demand and higher margins. Focus on developing bidirectional Vehicle-to-Grid (V2G) capabilities as a key differentiator. Partner with energy infrastructure developers and smart city planners to integrate charging solutions directly into urban planning.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term growth in foundational EV infrastructure over the next decade. Identify acquisition targets with strong intellectual property in resonant inductive coupling technology or proven expertise in thermal management solutions. A key signal to watch is the finalization of globally accepted standards for wireless charging above 11 kW, which will unlock significant market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization Investment | Ensures interoperability across vehicle brands, driving broader consumer acceptance and infrastructure scalability. |
| Charging Infrastructure Partnerships | Accelerates deployment of ground-side charging pads in public and commercial environments, expanding user access. |
| Software-Defined Vehicle Integration | Enables seamless communication between vehicle and charger, optimizing energy transfer and user experience. |
| Specialized Component Capacity Expansion | Addresses supply bottlenecks for high-frequency litz wire and GaN semiconductors, stabilizing system costs. |
| Technology Licensing Agreements | Facilitates wider adoption of patented magnetic resonance solutions, standardizing core power transfer methods. |
Research Approach
SAE J2954 documentation, IEC 61980 standards, and FCC Part 18 filings formed the secondary backbone for this analysis, supplemented by customs data and academic research. This data was validated through primary interviews with automotive OEM engineers, Tier-1 supplier product managers, public transit fleet managers, and technology patent holders. The study employed both bottom-up and top-down triangulation to ensure data accuracy.
A bottom-up analysis of electric vehicle production forecasts and a top-down market sizing approach were integrated across the analysis window. The forecast framework segmented the market by product type (integrated, add-on), technology (resonant, magnetic resonance), application (passenger cars, buses), end-user (OEMs, suppliers), and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trend analysis and future adoption projections, utilizing EV sales projections and infrastructure development plans as key inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery advancements or competing energy transfer methods would alter the outlook. Forecasts reflect assumptions on standardization progress and regulatory stability within key markets. Rapid shifts in global trade policies or unforeseen technological breakthroughs represent specific risk factors that could revise projections; a small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Norway Electric Vehicle Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
EV Eaxle Market
Electric Vehicles
E-Rickshaw Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
Electric Vehicle Lithium-Ion Battery Market
Electric Vehicles
South America Automotive High Performance Electric Vehicles Market
Electric Vehicles
Electric Vehicle Operations Management Solutions Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Middle East Wireless EV Charging Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market