
 Australia Data Center Power Market | 2026-2036
Australia Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Data Center Power Market Insights
Australia's Renewable Energy Target is shifting procurement priorities across the data center power sector. Schneider Electric leverages its integrated energy management portfolio to dominate uninterruptible power supply deployments. Eaton Corporation anchors its position through advanced power distribution unit engineering for hyperscale facilities. Vertiv Group specializes in thermal and power infrastructure convergence, competing on liquid-cooled rack density solutions.
Australia data center power encompasses electrical infrastructure engineered to deliver conditioned, redundant, and scalable energy to server environments, typically operating at voltages from 208V to 415V with power usage effectiveness targets below 1.3. This infrastructure integrates switchgear, busway, and static transfer switches to ensure continuous operations for digital asset hosting. Backup power solutions lead current revenue pools due to grid reliability concerns and utility-scale outage risks. Renewable power segments are expanding fastest as operators contract directly with wind and solar farms to meet corporate sustainability commitments. UPS systems remain the most mature product category, with margin concentration shifting toward intelligent power distribution units that enable real-time monitoring.
Clean Energy Regulator oversight of renewable energy certificates directly shapes power procurement contracting structures for facility operators. Australian Energy Market Operator grid interconnection standards dictate backup power redundancy thresholds for new builds exceeding 10 megawatts. Australian Building Codes Board energy efficiency requirements filter into cooling-electrical integration specifications. Stakeholders must weigh stranded asset risk against modular deployment timelines as hydrogen fuel cells and battery energy storage systems challenge diesel generator dominance in long-duration backup applications.
Market Dynamics
Hyperscale cloud operators in Sydney and Melbourne are compressing deployment timelines for liquid-cooled infrastructure, forcing power architecture suppliers to converge thermal and electrical systems faster than traditional build cycles allow.
Growth Catalysts
- Clean Energy Regulator oversight:Renewable energy certificate frameworks are mandating direct power purchase agreements between data center operators and solar or wind farms, accelerating clean procurement contracting.
- Liquid immersion cooling:Rack densities exceeding 50 kilowatts per cabinet are forcing adoption of dielectric fluid systems that reduce power usage effectiveness below 1.2.
- Victoria and New South Wales:State-level net-zero mandates are concentrating new facility investment in these jurisdictions, creating clustered demand for modular power infrastructure.
Market Restraints
- Grid interconnection queues:Australian Energy Market Operator standards for facilities exceeding 10 megawatts are extending commissioning timelines by 18-24 months in metropolitan zones.
- Diesel generator lock-in:Existing backup power contracts and sunk capital in rotating machinery are delaying battery energy storage system adoption for long-duration applications.
- Copper and silicon carbide supply:Power semiconductor material constraints are inflating lead times for intelligent power distribution units by 12-16 weeks.
Strategic Opportunities
- Queensland and Western Australia:Underpenetrated markets with abundant land and renewable resources offer greenfield development potential outside Sydney-Melbourne saturation.
- Hydrogen fuel cell integration:Convergence of electrolyzer cost declines and fuel cell durability improvements is opening zero-emission backup power architectures for 8-hour-plus runtime requirements.
- Behind-the-meter solar plus storage:Australian Building Codes Board efficiency requirements are creating channel demand for integrated microgrid solutions at the facility level.
Industry Challenges
- High-voltage direct current skill scarcity:Specialized technicians for 380V DC bus architecture deployment are concentrated among a limited contractor base, constraining workforce scaling.
- Legacy alternating current retrofit complexity:Existing facilities with 208V three-phase infrastructure face stranded asset risk when integrating next-generation liquid-cooled racks requiring 415V distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Data Center Power Market |
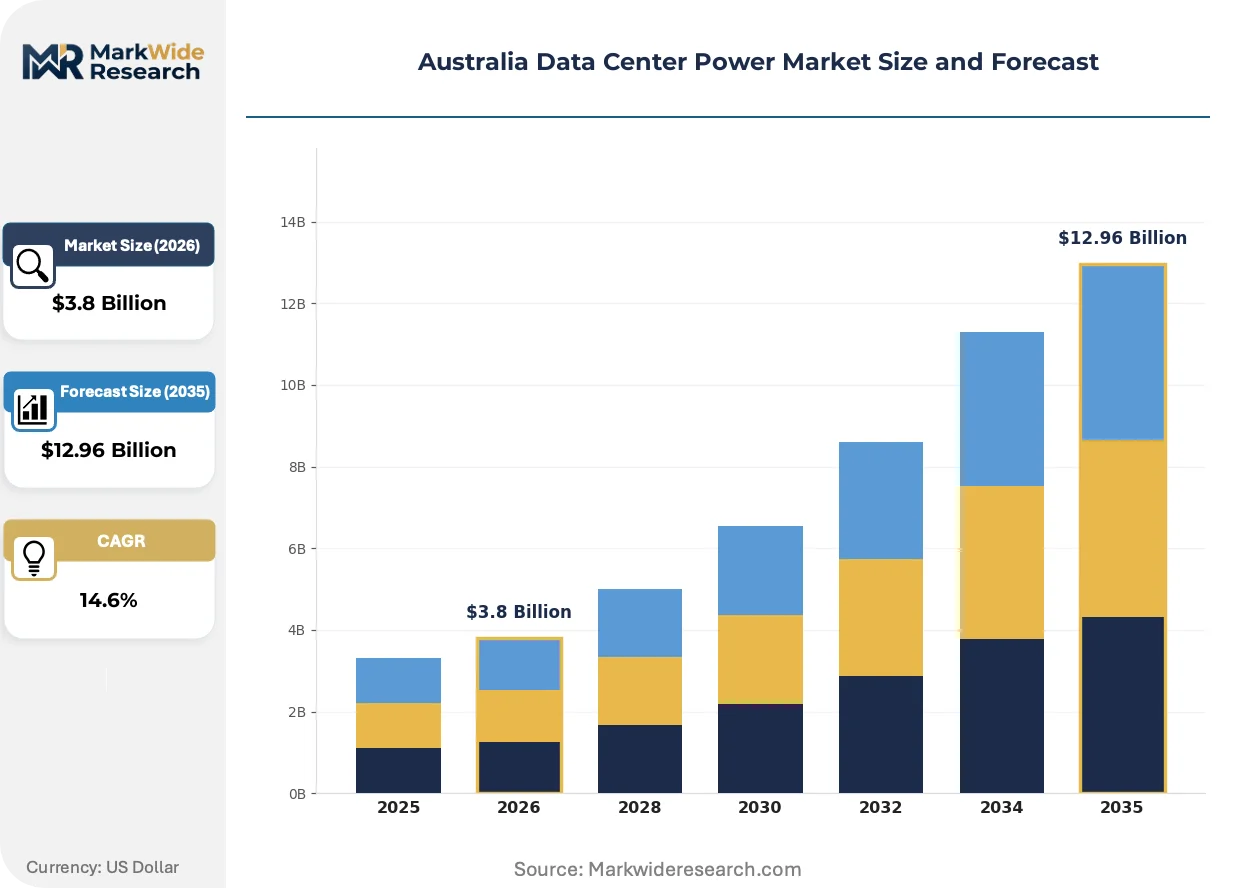
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Type: AC Power, DC Power, Renewable Power, Backup Power Product Type: UPS Systems, Power Distribution Units, Generators, Transformers End User: IT & Telecom, BFSI, Government, Manufacturing Cooling Solution: Air Cooling, Liquid Cooling, Hybrid Cooling, Economizer Cooling |
| Companies Covered | Schneider Electric, Eaton Corporation, Vertiv Group, ABB Ltd, Legrand, Siemens AG, Caterpillar Inc, Generac Holdings Inc, Equinix Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Data Center Power Market Trends and Innovations
Power infrastructure convergence is collapsing the traditional separation between electrical distribution and thermal management, creating unified procurement specifications that favor integrated platform suppliers over component vendors.
Busbar trunking systems with integrated tap-off units are electrifying power distribution in hyperscale halls, replacing cable tray assemblies with continuous copper busway that enables 30% faster rack repositioning. Amazon Web Services and Microsoft Azure facilities in Sydney are specifying these systems for 100 megawatt-plus deployments. The technology is electrifying competitive positioning by compressing installation labor content and enabling real-time capacity rebalancing without electrical shutdowns.
The Australian Energy Market Operator's 2024 interconnection standards are tightening backup power redundancy thresholds for new builds, requiring N+1 generator configurations for facilities above 10 megawatts and mandating black-start capability testing. This regulatory tightening is extending engineering procurement construction timelines and inflating switchgear specification complexity. Colocation providers are responding by pre-certifying modular power blocks to accelerate planning approval cycles.
Direct contracting between data center operators and renewable developers is displacing traditional utility-mediated power procurement, with hyperscalers now originating 15-year solar and wind power purchase agreements before facility construction begins. This shift is fragmenting the buyer base into two tiers: self-originating operators and retail-dependent smaller facilities. The behavioral change is most visible in Victoria, where the state renewable energy target has normalized merchant offtake structures for sub-5 megawatt deployments previously reliant on grid supply.
Australia Data Center Power Market Segmentation
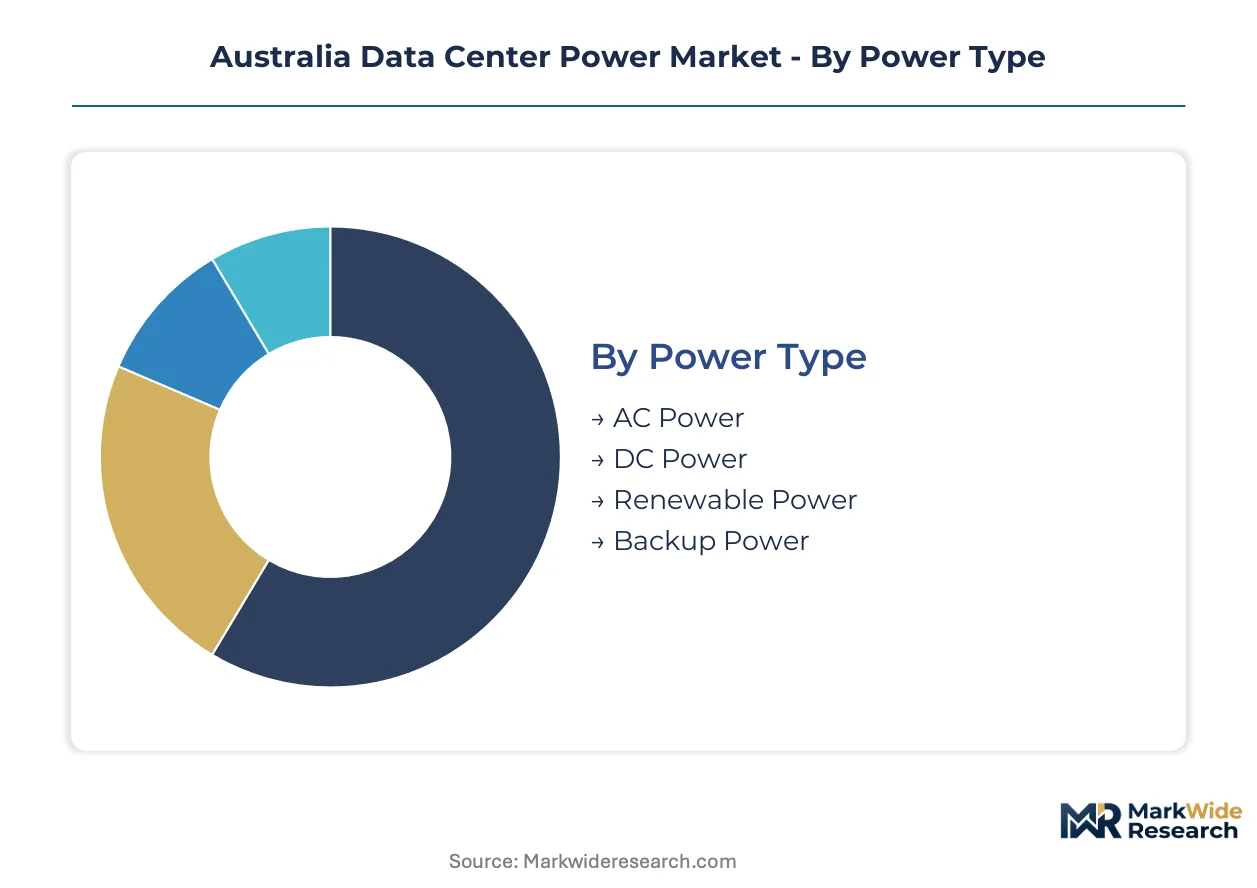
Power architecture segmentation in Australian data centers reveals how procurement priorities split between legacy reliability investments and next-generation efficiency mandates. Understanding these divisions helps suppliers align product roadmaps with the divergent requirements of hyperscale cloud operators versus enterprise colocation tenants.
Power Type:
Technical specifications for electrical delivery architectures determine capital allocation across facility development cycles, with voltage standards and source redundancy shaping procurement decisions.
- AC Power:Alternating current infrastructure at 208V to 415V dominates existing facility footprints across Sydney and Melbourne. Three-phase distribution remains the default specification for legacy rack densities below 30 kilowatts per cabinet.
- DC Power:Direct current bus architectures at 380V eliminate conversion losses in hyperscale deployments. Victoria facilities exceeding 50 megawatts are specifying DC distribution to support liquid-cooled rack densities above 50 kilowatts.
- Renewable Power:Solar and wind power purchase agreements contracted directly with generators. Clean Energy Regulator certificate frameworks mandate this procurement structure for new builds seeking carbon-neutral certification.
- Backup Power:Diesel generators and battery energy storage systems ensuring continuity during grid outages. Australian Energy Market Operator standards require N+1 redundancy for facilities above 10 megawatts.
Backup power leads on scale; renewable power leads on momentum.
Product Type:
Component-level procurement patterns reflect divergent margin structures between mature categories and integrated systems commanding premium positioning.
- UPS Systems:Uninterruptible power supply units providing conditioned power during voltage sags and brief outages. New South Wales hyperscale halls are specifying modular UPS architectures enabling capacity scaling without full system replacement.
- Power Distribution Units:Intelligent rack-level units with real-time monitoring and remote switching capabilities. Copper and silicon carbide supply constraints are extending lead times by 12-16 weeks for advanced models.
- Generators:Rotating machinery for long-duration backup during extended grid failures. Existing diesel contracts and sunk capital are delaying battery energy storage system adoption for runtime requirements exceeding four hours.
- Transformers:Voltage step-down equipment interfacing with utility distribution networks. Grid interconnection queues in metropolitan zones are extending transformer procurement timelines by 18-24 months.
UPS systems command the largest installed base; power distribution units are expanding most quickly.
End User:
Vertical-specific requirements drive divergent specifications for redundancy tiers, sustainability certification, and deployment velocity across customer segments.
- IT & Telecom:Cloud operators and telecommunications carriers requiring Tier III and Tier IV reliability certifications. Sydney and Melbourne concentrations account for the majority of new capacity additions.
- BFSI:Banking, financial services, and insurance institutions mandating geographic diversity for disaster recovery. Queensland and Western Australia are attracting greenfield development for secondary site requirements.
- Government:Federal and state agencies with sovereign data residency requirements. Australian Signals Directorate certification dictates physical security integration with power architecture specifications.
- Manufacturing:Industrial enterprises deploying edge computing for predictive maintenance and quality control. Regional facilities outside capital cities are driving demand for modular power blocks.
IT and Telecom dominates absolute capacity; BFSI is diversifying geographic footprint fastest.
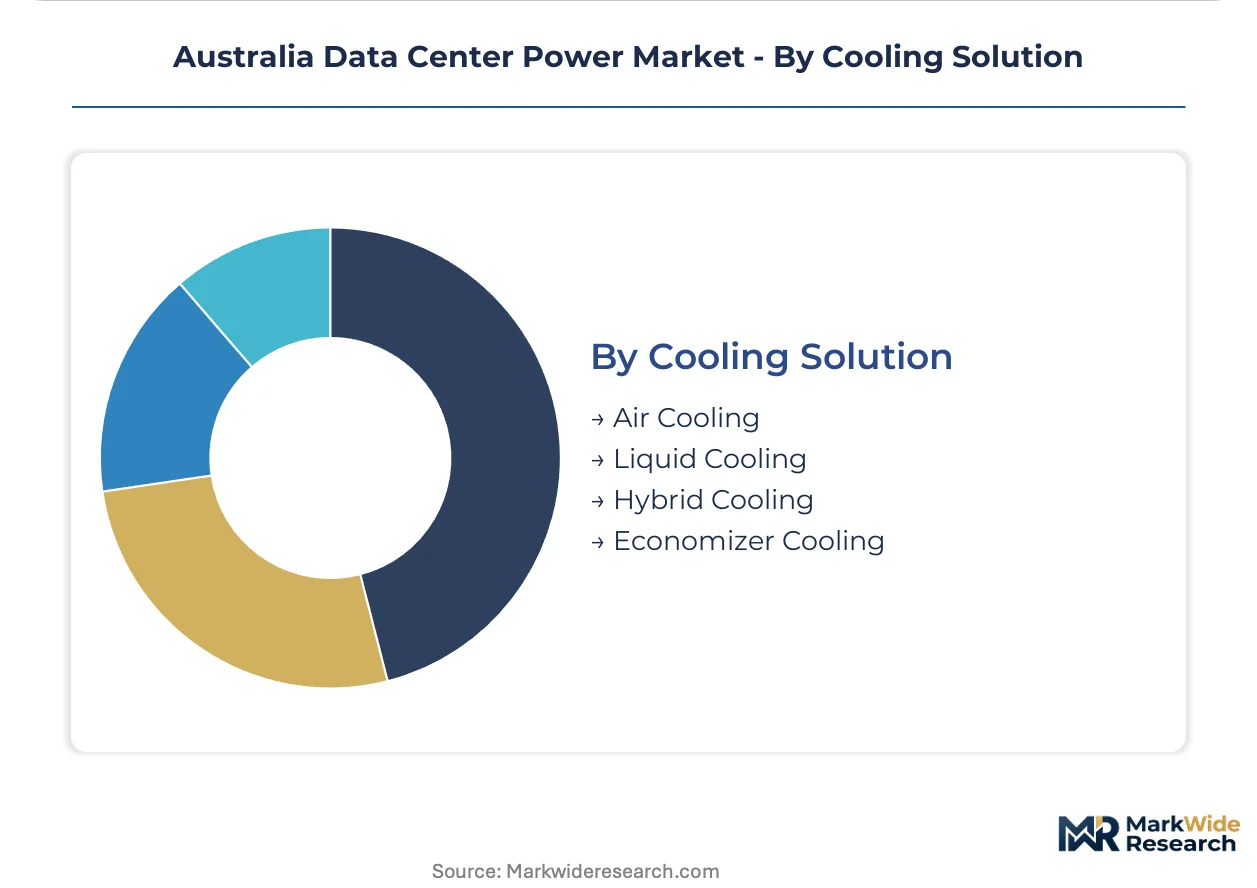
Cooling Solution:
Thermal management specifications are converging with electrical distribution requirements as rack densities exceed traditional air-cooling thresholds.
- Air Cooling:Traditional raised-floor perimeter and in-row cooling for densities below 15 kilowatts per rack. Legacy facilities in Sydney face stranded asset risk as tenant requirements shift toward liquid-cooled architectures.
- Liquid Cooling:Dielectric fluid systems and direct-to-chip cooling enabling densities above 50 kilowatts. Amazon Web Services and Microsoft Azure specifications are normalizing this technology for 100 megawatt-plus deployments.
- Hybrid Cooling:Combined air and liquid systems enabling phased infrastructure transitions. Colocation providers are specifying hybrid architectures to accommodate mixed tenant density requirements.
- Economizer Cooling:Free-air and evaporative systems leveraging ambient temperature conditions. Melbourne and Sydney climate profiles support substantial economizer operating hours.
Air cooling retains the largest installed base; liquid cooling is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical engineering talent pools concentrate in Sydney and Melbourne, anchoring procurement decision-making for power infrastructure across the national market.
New South Wales
Hyperscale cloud operators are compressing deployment timelines for liquid-cooled infrastructure in Sydney. The Australian Energy Market Operator's 2024 interconnection standards mandate N+1 generator configurations for facilities exceeding 10 megawatts. Western Sydney's emerging data center corridor is attracting modular power block pre-certification to accelerate planning approvals.
Victoria
State-level net-zero mandates are concentrating new facility investment in Melbourne and surrounding regions. The Clean Energy Regulator's renewable energy certificate frameworks mandate direct power purchase agreements between operators and solar or wind farms. Melbourne's established electrical contracting base supports faster commissioning for DC bus architectures at 380V.
Queensland
Abundant land and renewable resources are attracting greenfield development outside Sydney-Melbourne saturation zones. The state's renewable energy target is normalizing merchant offtake structures for sub-5 megawatt deployments. Brisbane and emerging regional hubs are driving demand for integrated microgrid solutions at the facility level.
Western Australia
Underpenetrated market status offers expansion potential for operators seeking geographic diversity. Grid reliability concerns in remote locations are elevating backup power redundancy requirements. Perth's isolation from eastern grid infrastructure is forcing self-contained power architecture specifications with extended diesel generator runtime.
Australia Data Center Power Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the power infrastructure value chain. The vendor base separates between integrated platform suppliers commanding premium positioning and component vendors facing margin compression. Three archetypes dominate: multinational electrical conglomerates with energy management portfolios, specialized thermal-power convergence specialists, and rotating machinery manufacturers with generator expertise. Competitive moves center on strategic partnerships for liquid-cooled rack integration and geographic expansion into underpenetrated state markets.
Within the integrated energy management tier, Schneider Electric anchors multinational presence through uninterruptible power supply deployments. Eaton Corporation exemplifies advanced power distribution engineering for hyperscale facilities. Vertiv Group occupies a position specializing in thermal and power infrastructure convergence for liquid-cooled rack density solutions.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| Vertiv Group |
| ABB Ltd |
| Legrand |
| Siemens AG |
| Caterpillar Inc |
| Generac Holdings Inc |
| Equinix Inc |
| Others |
Pricing and Supply Chain Analysis
Hydrogen fuel cell procurement mandates from hyperscale operators are forcing suppliers to reconfigure manufacturing footprints and absorb electrolyzer cost premiums into long-term service contracts. This demand-side specification shift compresses margins for traditional diesel generator vendors while elevating pricing power for integrated clean power platform providers.
Pricing Analysis
Bundled power-as-a-service contracts dominate hyperscale procurement, separating premium integrated thermal-electrical platforms from commoditized component sales. Price differentiation hinges on N+1 redundancy certification tier and liquid-cooled rack compatibility rather than base hardware specifications. Cost compression in standard UPS systems is intensifying because silicon carbide supply constraints limit premium intelligent PDU availability. Enterprise colocation tenants exhibit highest price sensitivity, while cloud operators prioritize performance guarantees over unit economics.
Supply Chain Analysis
Domestic-content thresholds under Australian Building Codes Board efficiency requirements are reshaping sourcing toward local electrical contractors for final-mile integration. Manufacturing concentrates in China for power semiconductors, Germany for precision switchgear, and the United States for advanced battery management systems. Copper busbar and silicon carbide MOSFET dependencies create single-source vulnerability for intelligent PDU production. Distribution runs through authorized integrator networks rather than direct OEM sales for projects below 10 megawatts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia data center power has entered late-cycle quality phase, with procurement committees now weighting liquid-cooled compatibility and black-start certification above baseline cost metrics.
For Market Incumbents: Lock in hyperscale relationships through pre-certified modular power blocks that compress Australian Energy Market Operator approval timelines. Deepen backward integration into copper busbar fabrication to insulate against 12-16 week PDU lead time volatility. Defend against emerging hydrogen fuel cell specialists by anchoring diesel-to-battery transition roadmaps with existing generator maintenance contracts. For New Entrants and Emerging Players: Capture Queensland and Western Australia greenfield demand where incumbent service networks remain thin. Prioritize behind-the-meter solar plus storage microgrids for sub-5 megawatt deployments seeking merchant offtake structures outside Sydney-Melbourne saturation. Differentiate through 380V DC bus architecture expertise, addressing high-voltage direct current skill scarcity constraining workforce scaling. For Investors and Strategic Acquirers: Asymmetric upside sits with thermal-power convergence specialists possessing liquid-cooled rack integration credentials. Five-to-ten year viability favors platforms with electrolyzer partnerships for 8-hour-plus backup runtime rather than pure-play rotating machinery. Watch hydrogen fuel cell durability improvement announcements as inflection signal for zero-emission backup power economics.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Power Block Pre-certification | Compresses Australian Energy Market Operator planning approval cycles for hyperscale deployments. |
| Hydrogen Fuel Cell Integration Partnership | Positions suppliers for 8-hour-plus zero-emission backup runtime requirements displacing diesel. |
| 380V DC Bus Architecture Capability Buildout | Addresses skill scarcity constraining liquid-cooled rack deployment in Victoria facilities. |
| Behind-the-Meter Solar Plus Storage Microgrid | Captures Queensland demand for integrated solutions under state renewable energy targets. |
| Copper Busbar Backward Integration | Insulates intelligent PDU margins against semiconductor material supply volatility. |
Research Methodology
Coverage spans New South Wales, Victoria, Queensland, and Western Australia, with primary inputs from each jurisdiction combined with secondary validation. Interviews with data center facility engineering directors, electrical contracting firm principals, Clean Energy Regulator compliance officers, and hyperscale cloud procurement managers anchored demand-side intelligence. Secondary sources include Australian Energy Market Operator interconnection filings, Clean Energy Regulator certificate registry data, Australian Building Codes Board efficiency standards, and state renewable energy target progress reports. Bottom-up project pipelines and top-down infrastructure investment flows underwent cross-triangulation.
Rate-of-change decomposition separated volume growth from value-per-unit shifts across the projection horizon. Segmentation modeling incorporated power type, product category, end-user vertical, and cooling solution compatibility. CAGRs derived from facility commissioning timelines, renewable power purchase agreement origination rates, and liquid-cooled rack density adoption curves. Hydrogen fuel cell cost decline trajectories and electrolyzer manufacturing scale factors informed long-duration backup power substitution assumptions.
Grid interconnection queue extensions, copper and silicon carbide supply disruptions, and hydrogen infrastructure buildout delays are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market
Data Center Infrastructure
Asia-Pacific Virtual Desktop Infrastructure Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Israel Data Center Rack Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
North America Data Center Rack Market
Data Center Infrastructure
North America Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Power Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
South Africa Data Center Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market