
 Data Center Modeling and Simulation Tools Market | 2026-2036
Data Center Modeling and Simulation Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Modeling and Simulation Tools Market Outlook
Platform licensing is narrowing as a margin pool as vendors shift toward subscription-based cloud delivery and embedded analytics. Schneider Electric SE leverages its integrated power and cooling portfolio to bundle simulation tools with physical infrastructure. Siemens AG anchors its position through deep ties to industrial automation customers expanding into data center operations. ANSYS, Inc. specializes in high-fidelity thermal and electromagnetic modeling that serves semiconductor-adjacent facility design.
Data center modeling and simulation tools comprise software platforms that create digital representations of facility thermal behavior, power distribution, airflow dynamics, and IT workload placement to predict performance before physical construction or modification. These systems typically resolve computational fluid dynamics at sub-rack granularity while integrating real-time sensor feeds from building management systems, enabling operators to validate cooling redundancy and identify hot spots without production risk. Energy Management Solutions command the deepest margin pools as carbon reporting mandates and power purchase agreement optimization become standard procurement criteria. Cloud-Based Solutions represent the fastest-expanding delivery mode as operators seek elastic compute for scenario modeling without capital-intensive on-premises licensing. Capacity Planning Tools remain the most mature segment, though growth is now shifting toward Workload Distribution Models that address AI training cluster orchestration.
EPA ENERGY STAR certification requirements for data centers and the EU F-Gas Regulation on cooling refrigerants are tightening the specifications that simulation tools must validate before facility commissioning. BIS energy efficiency standards in India and China's GB 50174 data center design code add compliance layers that drive recurring software engagement across multinational operator portfolios. Stakeholders must weigh whether to build native AI inference optimization modules or partner with chip vendors as thermal design power thresholds reset facility planning assumptions.
Market Dynamics
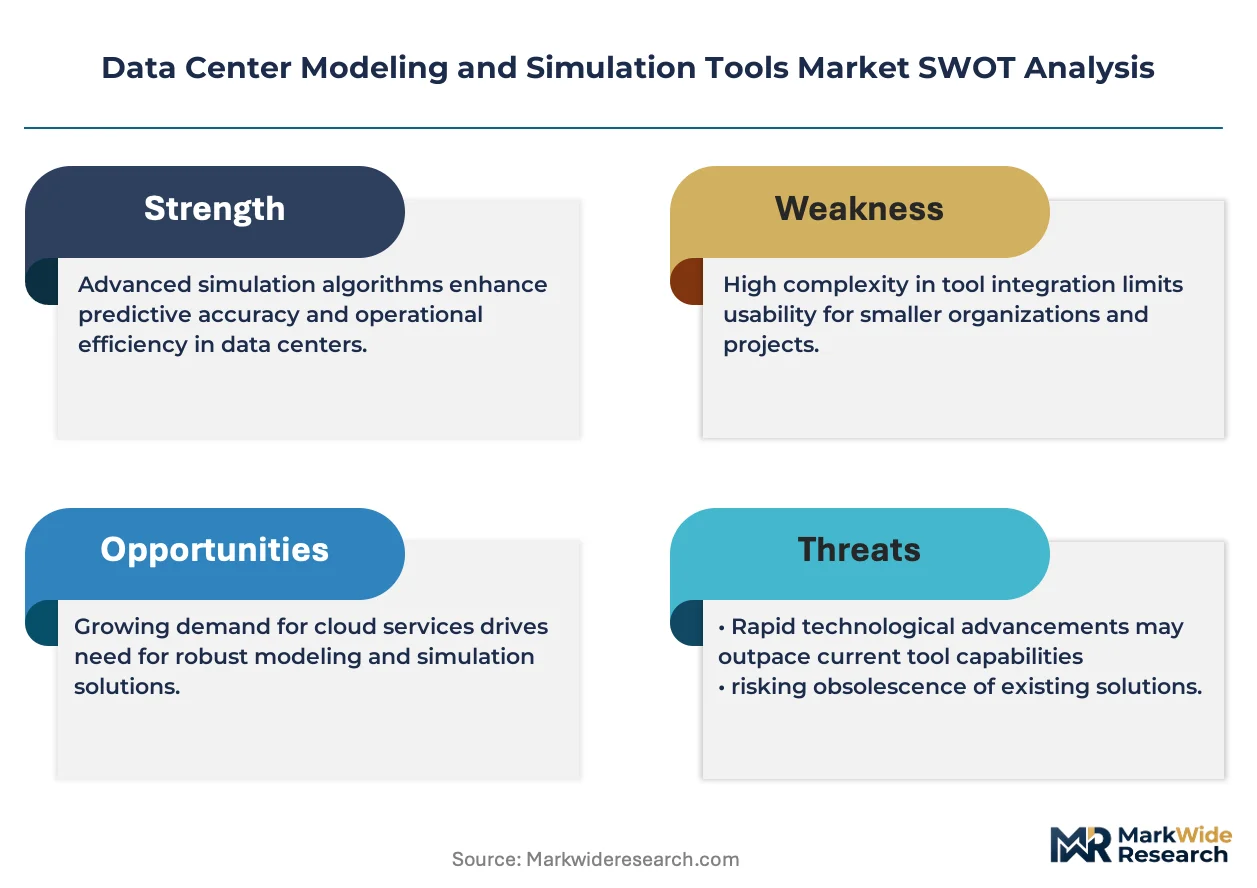
AI training cluster densities above 100 kW per rack are forcing facility operators to abandon rule-of-thumb cooling designs in favor of physics-validated thermal simulation before breaking ground.
Growth Catalysts
- EU Energy Efficiency Directive:The directive mandates granular power usage effectiveness reporting that operators cannot satisfy without continuous simulation-based validation of cooling performance.
- Hyperscale cloud buildouts:Amazon Web Services, Microsoft Azure, and Google Cloud are commissioning simulation tools to de-risk thermal failures in multi-megawatt training halls before hardware deployment.
- Computational fluid dynamics resolution:Sub-rack granularity now resolves individual server inlet temperatures, enabling hot spot prediction that prevents catastrophic AI workload throttling.
Market Restraints
- Specialized talent scarcity:Thermal engineers capable of interpreting CFD outputs against ASHRAE guidelines command compensation premiums that inflate total cost of ownership for simulation programs.
- On-premises licensing drag:Perpetual software licenses with three-year refresh cycles trap capital that operators increasingly prefer to deploy toward liquid cooling hardware.
- Data sovereignty fragmentation:China's GB 50174 design code and India's BIS efficiency standards impose conflicting validation protocols that complicate multinational operator tool standardization.
Strategic Opportunities
- India data center expansion:The country's PLI scheme for electronics manufacturing is attracting hyperscale investment that requires local simulation capability for tropical climate adaptation.
- Digital twin convergence:Integration with building information modeling platforms creates sticky enterprise relationships as facility operators seek unified design-to-operations workflows.
- Carbon border adjustment mechanism:The EU's CBAM will force non-EU data center exports to document embodied carbon, driving demand for lifecycle simulation tools that trace power and cooling emissions.
Industry Challenges
- Legacy BMS integration friction:Decades-old building management systems in brownfield facilities resist API connectivity that real-time simulation requires for sensor feed validation.
- ASIC thermal design power volatility:NVIDIA, AMD, and custom AI chip roadmaps reset power envelopes every 18 months, forcing simulation vendors to rebuild thermal models before prior versions achieve ROI.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Modeling and Simulation Tools Market |
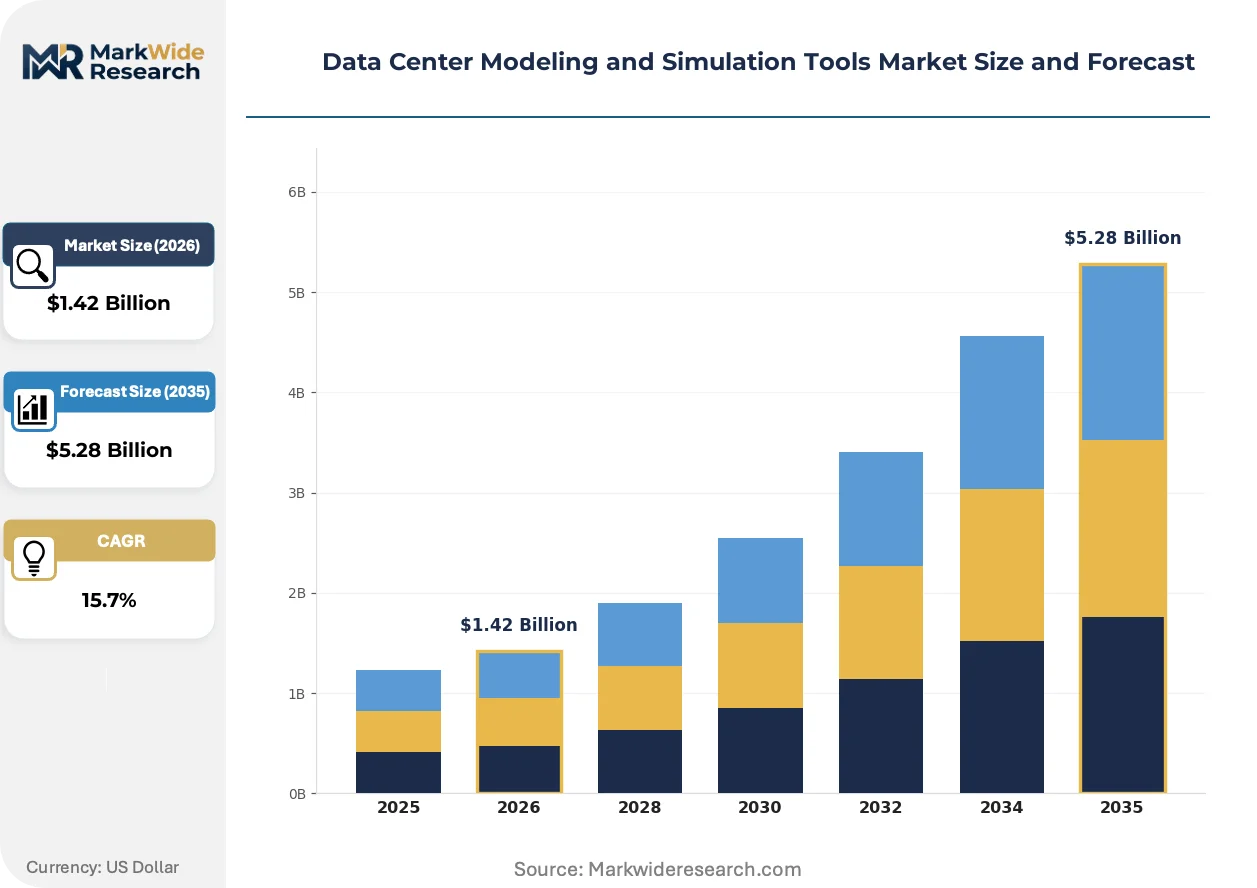
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $5.28 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacity Planning Tools, Performance Simulation Software, Energy Management Solutions, Workload Distribution Models End User: Data Center Operators, IT Service Providers, Telecom Companies, Research Institutions Technology: Cloud-Based Solutions, On-Premises Software, Hybrid Models, Virtualization Platforms Application: Power Optimization, Resource Allocation, Disaster Recovery Planning, Efficiency Analysis |
| Companies Covered | Schneider Electric SE, Siemens AG, ANSYS, Inc., Cadence Design Systems, Inc., Future Facilities Ltd., Autodesk, Inc., Dassault Systèmes SE, Bentley Systems Inc., Altair Engineering Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Modeling and Simulation Tools Market Strategic Shifts
Simulation delivery models and computational architectures are undergoing simultaneous transformation as operators seek elasticity without sacrificing physics fidelity.
Physics-informed neural networks are migrating from academic research into commercial platforms. These architectures embed Navier-Stokes constraints directly into machine learning layers, reducing CFD solve times from hours to minutes. Mid-sized colocation operators in Germany and the Netherlands are piloting these tools for what-if scenario modeling during sales negotiations. The compression in computational overhead is lowering the entry threshold for operators who previously outsourced thermal analysis to specialized consultancies.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules that directly constrain cooling system design. Simulation tools must now validate alternative heat rejection architectures—adiabatic cooling, two-phase immersion, and direct liquid-to-chip—against performance degradation under peak summer ambient conditions. Facility operators in Frankfurt and Amsterdam clusters are demanding pre-commissioning simulation reports that demonstrate F-Gas compliance before local authorities issue operating permits.
Subscription-based cloud delivery is displacing perpetual licensing for scenario modeling workloads. Colocation and enterprise operators in Singapore and Sydney are purchasing simulation capacity by the hour through browser interfaces, eliminating upfront capital commitment. This consumption pattern is most visible among operators managing fewer than ten facilities who lack dedicated thermal engineering staff but face investor pressure to document efficiency improvements quarterly.
Data Center Modeling and Simulation Tools Market Segmentation
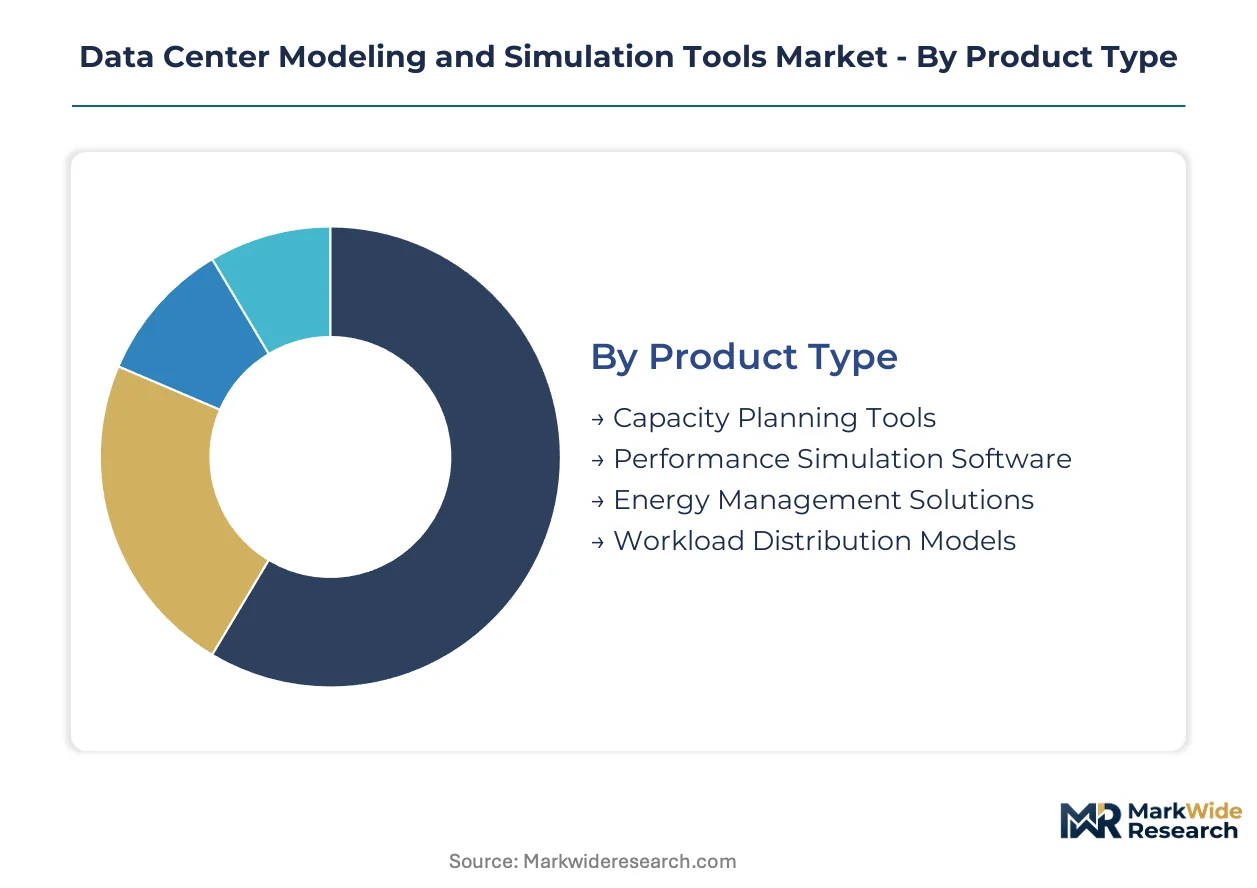
Segmentation in data center modeling tools reveals divergent procurement patterns between hyperscale operators optimizing multi-megawatt training halls and enterprise facilities managing legacy cooling retrofits. Product architecture, deployment mode, and end-user technical maturity collectively determine vendor selection criteria and pricing elasticity across customer tiers.
Product Type:
Maturity spans from commoditized capacity forecasting to emerging AI workload orchestration modules that reset thermal design assumptions.
- Capacity Planning Tools:Long-established modules project rack-level power and space consumption against five-to-ten-year growth scenarios. Hyperscale operators in Germany and the Netherlands deploy these for pre-construction feasibility studies where local efficiency codes mandate documented redundancy margins.
- Energy Management Solutions:Platforms integrating real-time sensor feeds with carbon accounting engines command premium pricing as EU CSRD disclosure requirements tighten. Frankfurt-based colocation providers purchase these bundles to automate power usage effectiveness reporting for facility certification.
- Performance Simulation Software:CFD-based thermal modeling resolves airflow at sub-rack granularity for liquid cooling validation.
- Workload Distribution Models:Emerging category addressing AI training cluster orchestration across heterogeneous chip architectures.
Capacity Planning Tools retain volume leadership; Workload Distribution Models hold the steepest expansion curve.
End User:
Technical sophistication and procurement scale separate hyperscale self-builders from outsourced infrastructure consumers.
- Data Center Operators:Direct owners of physical infrastructure employ full-stack simulation suites spanning design-phase CFD through operational digital twins. Singapore-based operators leverage these tools for tropical climate adaptation where ambient wet-bulb temperatures constrain free cooling hours.
- IT Service Providers:Managed infrastructure vendors purchase scenario-modeling capacity by the hour through cloud interfaces to support client sales negotiations without dedicated thermal engineering benches.
- Telecom Companies:Edge facility operators prioritize compact, rapid-deployment modules for 5G aggregation node thermal validation.
- Research Institutions:Academic and national laboratory users drive adoption of physics-informed neural network architectures for algorithmic research.
Data Center Operators dominate current procurement volumes; IT Service Providers are climbing the fastest as outsourced infrastructure consumption accelerates.
Technology:
Deployment economics favor elasticity over capital intensity among mid-sized facility portfolios.
- Cloud-Based Solutions:Browser-delivered simulation capacity eliminates perpetual licensing overhead and enables burst compute for what-if scenario modeling. Sydney-based colocation operators under ten facilities adopt this mode to satisfy investor efficiency documentation requirements without dedicated simulation staff.
- On-Premises Software:Perpetual licenses with three-year refresh cycles persist among security-sensitive operators and those with sustained high-volume workloads where amortization favors captive infrastructure.
- Hybrid Models:Split architectures retain sensitive design data locally while offloading compute-intensive CFD resolution to elastic cloud resources.
- Virtualization Platforms:Containerized simulation environments enable rapid tool chain replication across distributed engineering teams.
On-Premises Software retains installed base dominance; Cloud-Based Solutions are gaining share fastest as procurement shifts toward operational expenditure structures.
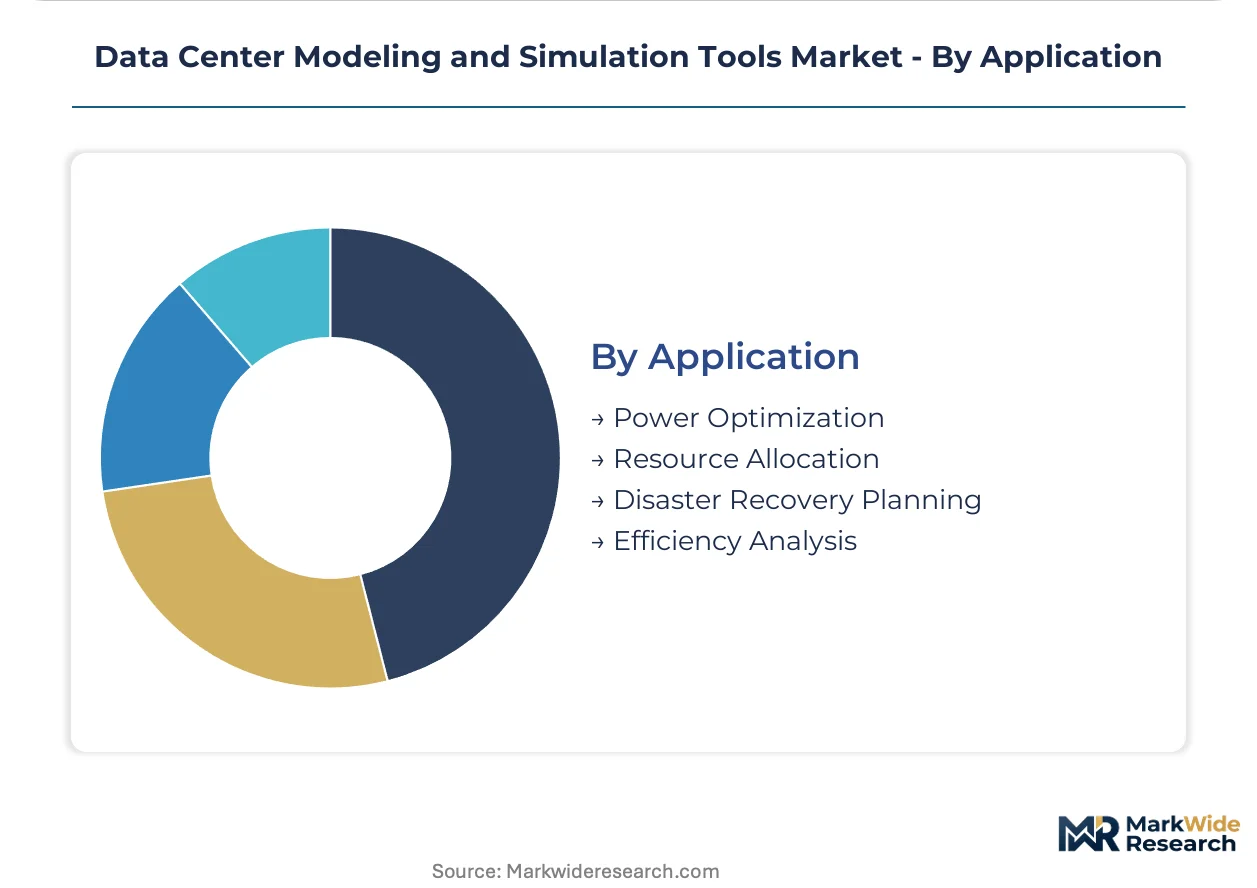
Application:
Use case specificity determines integration depth with building management systems and carbon accounting workflows.
- Power Optimization:Modules balancing server load against time-of-use electricity rates and power purchase agreement constraints. Indian operators under BIS efficiency standards deploy these to validate transformer sizing and UPS redundancy before commissioning.
- Resource Allocation:Workload placement algorithms minimizing thermal interference between high-density AI training racks and legacy air-cooled infrastructure.
- Disaster Recovery Planning:Cooling failure scenario modeling for regulatory compliance and insurance documentation.
- Efficiency Analysis:Continuous monitoring against ENERGY STAR and EU Code of Conduct for Data Centre Energy Efficiency benchmarks.
Power Optimization captures the deepest current engagement; Resource Allocation is expanding most quickly as AI cluster densities force thermal orchestration redesigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement tiers. Enterprise operators in Singapore and Sydney purchase cloud-based simulation capacity by the hour, while hyperscale builders in Frankfurt and Amsterdam absorb perpetual licensing costs for sub-rack CFD granularity. Germany commands the deepest engagement as efficiency codes tighten.
United States
Hyperscale cloud operators commission multi-megawatt training hall simulations before hardware deployment. EPA ENERGY STAR certification mandates continuous cooling performance validation that operators satisfy through embedded analytics. Northern Virginia's data center corridor drives procurement of workload distribution models for AI cluster orchestration.
Germany
Industrial data center buildouts and stringent efficiency codes accelerate advanced simulation procurement. The EU F-Gas Regulation imposes refrigerant phase-down schedules that constrain cooling system design validation. Frankfurt and Amsterdam clusters demand pre-commissioning reports demonstrating compliance before operating permits issue.
China
GB 50174 data center design code adds compliance layers that drive recurring software engagement across multinational portfolios. The country's national electronics regulator enforces dual carbon goals that reshape thermal planning assumptions. Yangtze River Delta operators pilot physics-informed neural networks for rapid scenario modeling.
India
The PLI scheme for electronics manufacturing attracts hyperscale investment requiring local simulation capability for tropical climate adaptation. BIS energy efficiency standards validate transformer sizing and UPS redundancy before commissioning. Mumbai and Bengaluru facility operators deploy cloud-based solutions to satisfy investor documentation requirements.
Singapore
Colocation operators under ten facilities adopt browser-delivered simulation capacity to eliminate upfront capital commitment. The tropical wet-bulb temperature regime constrains free cooling hours and demands precise ambient condition modeling. Marina Bay and Jurong data center clusters prioritize subscription pricing for quarterly efficiency reporting.
Data Center Modeling and Simulation Tools Market Competitive Environment
Capability concentration sits with specialized thermal engineering software houses; scale advantage sits with diversified industrial automation conglomerates. The market structures around three tiers: integrated infrastructure vendors bundling simulation with physical equipment, standalone CFD specialists serving semiconductor-adjacent facility design, and emerging cloud-native platforms displacing perpetual licensing. Dominant competitive moves include portfolio diversification into digital twin convergence and strategic partnerships with chip vendors for thermal design power calibration.
Within the integrated infrastructure tier, Schneider Electric SE and Siemens AG exemplify archetypes that leverage captive power and cooling portfolios to bundle simulation tools with physical equipment. ANSYS, Inc. occupies a position among high-fidelity specialists serving thermal and electromagnetic modeling demands. These three anchors represent distinct strategic postures: bundled infrastructure delivery, industrial automation extension, and physics-engineering depth.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| ANSYS, Inc. |
| Cadence Design Systems, Inc. |
| Future Facilities Ltd. |
| Autodesk, Inc. |
| Dassault Systèmes SE |
| Bentley Systems Inc. |
| Altair Engineering Inc. |
| Others |
Value Chain & Pricing Dynamics
Software engineering talent concentration in Germany and the Netherlands anchors premium pricing for high-fidelity thermal simulation modules. Margin pools concentrate in after-sales service contracts and continuous compliance validation rather than initial license fees.
Pricing Analysis
Recurring service and support contracts drive lifetime value for simulation vendors. Subscription-based cloud delivery displaces perpetual licensing as the dominant pricing model across mid-sized colocation operators. Price differentiation rests on CFD resolution granularity and ENERGY STAR certification tier. Pricing pressure intensifies as hyperscale operators negotiate enterprise-wide site licenses. IT service providers purchasing hourly capacity exhibit highest price sensitivity; hyperscale self-builders absorbing perpetual licenses show lowest.
Supply Chain Analysis
Computational hardware feedstock draws from Taiwan, South Korea, and the United States for GPU clusters powering physics-informed neural networks. Software development centers on Germany, India, and the United States for thermal engineering expertise. Cloud infrastructure dependencies create single-source vulnerability through concentrated hyperscaler platforms. Distribution runs through direct vendor sales teams for enterprise accounts and browser-based self-service portals for mid-market consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around EU F-Gas compliance and ENERGY STAR certification creates defensive moats for established simulation vendors. Switching costs escalate as facility operators embed these tools into digital twin workflows spanning design through operations.
For Market Incumbents: Insulate market position by deepening integration with building information modeling platforms and chip vendor thermal design power calibration partnerships. Cloud-native entrants threaten subscription pricing tiers. Certification investment in EU CSRD carbon accounting modules reinforces switching cost advantages.
For New Entrants and Emerging Players: Mid-market colocation operators in Southeast Asia represent the most penetrable entry point for browser-delivered simulation capacity. Edge facility thermal validation for 5G aggregation nodes offers second white-space target. Channel partnership with regional IT distributors accelerates go-to-market velocity without dedicated sales infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial automation specialists seeking data center adjacency expansion. Long-term viability across a decade-long infrastructure buildout window favors vendors with embedded analytics and recurring revenue concentration. Monitor hyperscale capital expenditure announcements as inflection indicator for simulation procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Physics-Informed Neural Network Integration | Reduces CFD solve times from hours to minutes for German colocation operators. |
| Cloud-Native Platform Launch | Eliminates perpetual licensing overhead for Singapore-based mid-market buyers. |
| Chip Vendor Thermal Design Partnership | Calibrates models against NVIDIA and AMD power envelope roadmaps before facility commissioning. |
| Digital Twin Convergence | Creates sticky enterprise relationships through unified design-to-operations workflows. |
| EU F-Gas Compliance Module Development | Validates alternative cooling architectures for Frankfurt cluster operating permits. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of hyperscaler capital expenditure disclosures, EPA ENERGY STAR certification databases, and EU regulatory filings. Interviews with data center engineering directors, thermal simulation software product managers, colocation procurement officers, and building management system integrators inform demand-side validation. Secondary sources include SEC 10-K infrastructure software segments, customs records for simulation software licensing, and national efficiency standard publications. Bottom-up facility buildout tracking triangulates against top-down vendor revenue analysis.
Forecast inputs span deployment model, end-user technical sophistication, CFD resolution tier, and regional regulatory stringency across the projection horizon. Segmentation dimensions modeled include product architecture, delivery mode, application use case, and geographic adoption pattern. CAGRs derive from elasticity-adjusted scenario modeling against infrastructure buildout pipelines. AI training cluster density trajectories and refrigerant phase-down schedules constitute industry-specific forecast inputs.
Practitioners should monitor hyperscale capital expenditure revisions and EU F-Gas regulation amendment timelines for early signals of forecast deviation. Cross-checking against EPA ENERGY STAR certification velocity and national data center efficiency code adoption rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Germany Data Center Physical Security Market
Data Center Infrastructure
Taiwan Data Center Rack Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Server Station Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
APAC Data Center Server Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
Asia-Pacific Data Center Market