
 GCC Event Logistics Market | 2026-2036
GCC Event Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Event Logistics Market Insights
A shift from fragmented single-source contracts toward consolidated multi-source logistics partnerships is recalibrating procurement patterns across GCC event supply chains. DP World leverages its port-to-venue infrastructure footprint to anchor regional distribution networks. GWC Logistics sustains dominant positioning within Qatar's stadium and exhibition ecosystem through temperature-controlled warehousing specialization. Sasat Logistics differentiates via dedicated concert touring fleets serving Riyadh and Jeddah.
GCC event logistics encompasses the planning, coordination, and execution of time-critical material flows for temporary large-scale gatherings, requiring ISO-certified temperature bands for catering cargo and bonded customs corridors for international equipment. The sector serves commercial purposes spanning corporate brand activation, government national-day programming, and entertainment tourism. Transportation commands the largest service-type revenue pool due to cross-border equipment haulage for touring productions, while on-site management captures superior margins through unionized labor coordination and real-time dispatch technology. Corporate clients generate the most predictable booking volumes, though festival event types exhibit the steepest growth trajectory as Saudi entertainment calendar expansion continues.
Saudi Entertainment Authority licensing protocols and UAE MOHAP food-safety standards for catered events jointly elevate compliance costs for new market entrants. Dubai's Department of Economy and Tourism enforces venue-specific logistics windows that constrain delivery scheduling flexibility. Stakeholders must monitor evolving customs-bond requirements for temporary imports as each Gulf state advances independent entertainment visa frameworks.
Market Dynamics
Saudi Entertainment Authority licensing reforms and UAE visa liberalization are compressing event lead times while elevating cross-border coordination requirements across the Gulf logistics ecosystem.
Growth Catalysts
- Mega-sporting infrastructure:Saudi Arabia's stadium construction pipeline is generating sustained demand for specialized freight corridors and on-site material staging yards.
- MOHAP food-safety certification:UAE catering logistics mandates are driving investment in ISO-certified temperature-controlled warehousing across Dubai's exhibition zones.
- Concert touring fleet specialization:Dedicated vehicle pools for entertainment cargo are reducing equipment damage rates and accelerating load turnaround at Riyadh and Jeddah venues.
Market Restraints
- Unionized labor coordination costs:On-site dispatch requirements at Dubai venue logistics windows inflate operational overhead for international equipment haulage.
- Customs-bond fragmentation:Independent temporary import frameworks across Bahrain, Kuwait, and Oman create compliance complexity for touring productions crossing multiple Gulf states.
- Bonded corridor scarcity:Limited dedicated customs lanes for entertainment equipment concentrate clearance risk at Jebel Ali and King Abdulaziz Port.
Strategic Opportunities
- Expo City Dubai infrastructure:Permanent warehousing and last-mile concentration zones offer anchor points for regional distribution network expansion.
- Saudi entertainment calendar density:Year-round programming beyond seasonal peaks is creating baseline demand for retained logistics capacity in Riyadh.
- Real-time dispatch technology convergence:Integration of GPS fleet tracking with venue access control systems is compressing equipment positioning windows at activated sites.
Industry Challenges
- Certified cold-chain technician scarcity:MOHAP-compliant food-safety handling credentials are outpacing training pipeline capacity in Qatar and Kuwait.
- Multi-source contract integration:Procurement consolidation from fragmented single-source arrangements to coordinated partnerships demands new vendor management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Event Logistics Market |
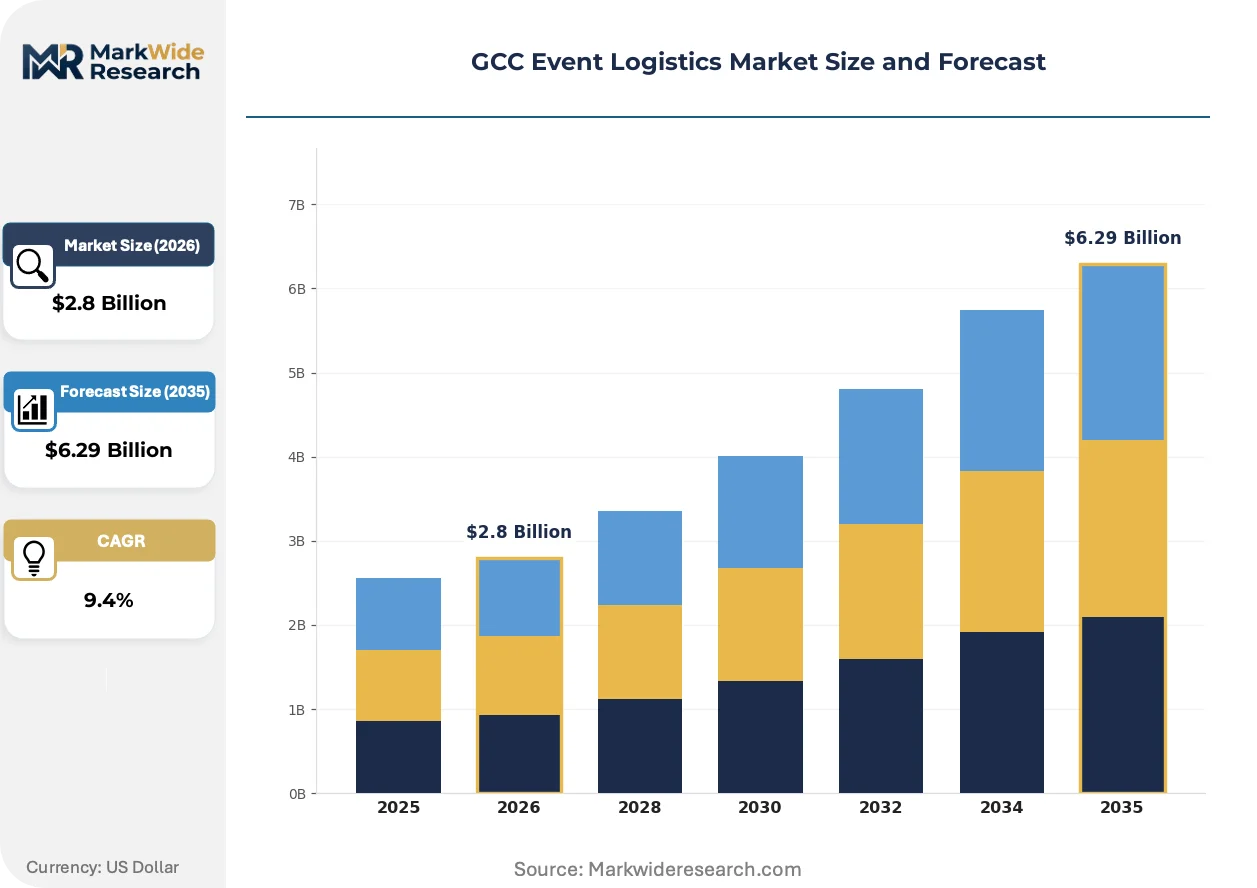
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, On-Site Management, Catering Client Type: Corporates, Non-Profits, Government, Educational Institutions Event Type: Conferences, Trade Shows, Concerts, Festivals Delivery Mode: Ground, Air, Ocean, Rail |
| Companies Covered | Sasat Logistics, Handle Logistics, DP World, Glaube Logistics, Gulf Agency Company, GWC Logistics, SOS Global Logistics, Clarion Integrated Logistics Solutions, 4Events, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Event Logistics Market Trends and Innovations
Technology convergence with regulatory compression is reconfiguring how event cargo moves across Gulf borders and enters controlled venue perimeters.
RFID-enabled cargo tracking is integrating with customs pre-clearance platforms to accelerate temporary import processing for touring equipment. Major festival organizers in Saudi Arabia are mandating chip-based manifests for all cross-border haulage. This visibility layer is integrating previously siloed freight forwarding, warehousing, and on-site coordination into unified command structures.
SFDA and MOHAP are tightening parallel food-safety enforcement for catered events, requiring temperature-logging documentation from origin kitchen through final venue handoff. Compliance costs are rising for logistics providers lacking dedicated cold-chain infrastructure. High-volume corporate hospitality segments in Dubai are responding by pre-qualifying carriers based on real-time monitoring certification rather than price alone.
Consolidated multi-year logistics partnerships are displacing transactional spot contracting for recurring entertainment properties. Festival promoters in Saudi Arabia and the UAE are bundling transportation, warehousing, and on-site management under single-source agreements with penalty clauses for delivery window failures. This behavioral shift is most pronounced in Riyadh's emerging concert circuit, where repeat venue relationships reward retained logistics capacity over lowest-bid procurement.
GCC Event Logistics Market Segmentation
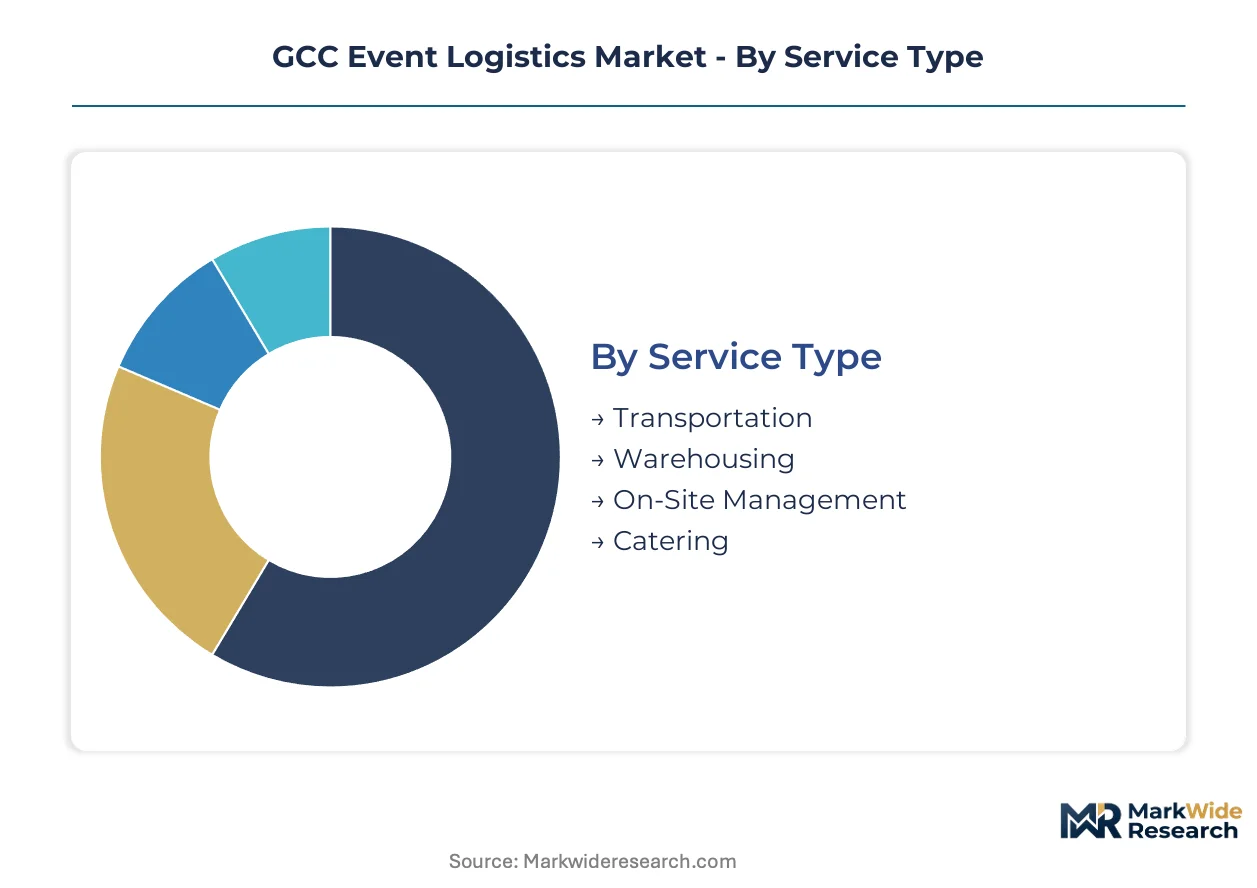
GCC event logistics procurement varies sharply by service intensity, client risk tolerance, and cargo sensitivity. Segment boundaries are blurring as Saudi entertainment expansion and Dubai exhibition density force multi-service bundling.
Service Type:
Client procurement decisions hinge on cargo value density and time-criticality rather than pure transport cost.
- Transportation:Cross-border equipment haulage for touring productions dominates volume, requiring bonded customs corridors and specialized flatbed fleets for stage infrastructure. Saudi Arabia's stadium construction pipeline and Riyadh-Jeddah concert circuit are concentrating investment in dedicated entertainment trucking pools.
- On-Site Management:Unionized labor coordination and real-time dispatch technology command premium margins through venue-specific logistics windows enforced by Dubai's Department of Economy and Tourism. Expo City Dubai infrastructure is anchoring regional dispatch centers for multi-venue event series.
- Warehousing:Temperature-controlled facilities near Doha stadium zones and Dubai exhibition districts serve bonded storage for temporary imports.
- Catering:MOHAP food-safety certification mandates ISO-compliant cold chains from origin kitchen through final handoff.
Transportation leads on scale; On-Site Management leads on momentum.
Client Type:
Contract duration and compliance burden separate procurement patterns across buyer categories.
- Corporates:Recurring brand activations and hospitality programming generate predictable booking volumes with multi-year partnership structures. Dubai corporate clients are pre-qualifying carriers on real-time monitoring certification rather than price.
- Government:National-day programming and state-led mega-events in Saudi Arabia sustain peak demand for specialized freight corridors and on-site staging yards.
- Non-Profits:Donor-funded gatherings exhibit sporadic scheduling with compressed lead times.
- Educational Institutions:Academic conferences and graduation ceremonies produce seasonal demand clusters.
Government commands peak capacity absorption; Corporates anchor year-round retention.
Event Type:
Venue technical requirements and audience scale determine logistics complexity tiers.
- Festivals:Multi-day outdoor programming with camping infrastructure demands comprehensive site logistics including power distribution, waste management, and emergency medical staging. Saudi Entertainment Authority licensing reforms are compressing lead times while expanding calendar density beyond seasonal peaks.
- Concerts:Touring productions require rapid equipment turnaround across Riyadh, Jeddah, and Dubai venues with minimal damage tolerance for specialized stage elements.
- Conferences:Corporate meeting formats prioritize predictable scheduling with standard AV and catering flows.
- Trade Shows:Exhibition cargo exhibits lower time sensitivity but higher volume concentration at Dubai World Trade Centre and Riyadh exhibition zones.
Concerts dominate cross-border freight intensity; Festivals gain share fastest on Saudi entertainment calendar expansion.
Delivery Mode:
Modal selection tracks cargo value-to-weight ratios and customs clearance urgency.
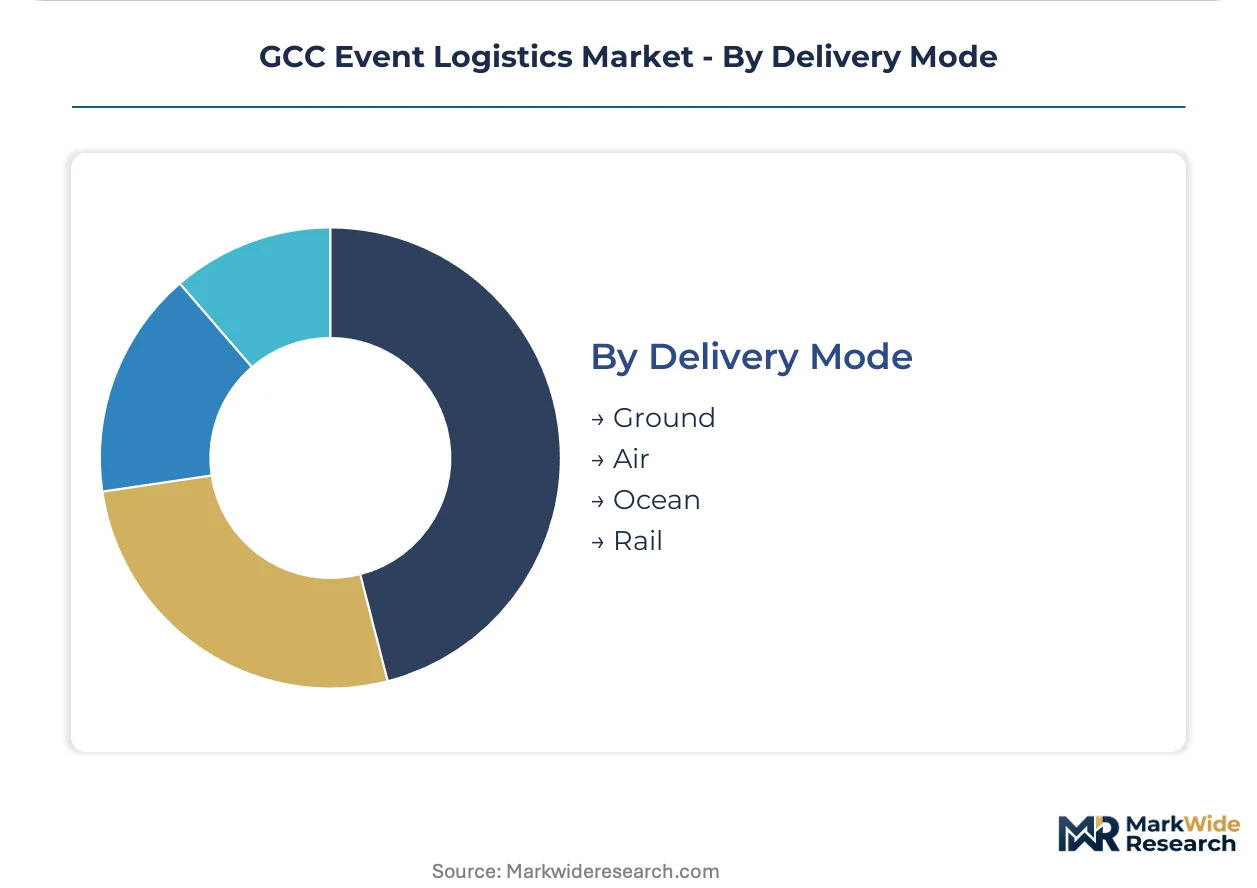
- Ground:Dedicated concert touring fleets serve Saudi Arabia's emerging circuit with chip-based RFID manifests now mandated by major festival organizers. Jebel Ali and King Abdulaziz Port concentration creates bonded corridor scarcity risks for international equipment.
- Air:Time-critical touring elements and perishable catering cargo utilize Dubai International Airport and King Khalid International Airport freight terminals.
- Ocean:Bulk stage infrastructure and temporary venue materials move through consolidated container shipments for extended-setup events.
- Rail:Limited network coverage restricts usage to select GCC corridor freight for non-time-sensitive exhibition materials.
Ground transportation anchors regional distribution; Air freight captures premium urgency segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expo City Dubai infrastructure anchors logistics network design across the Gulf Cooperation Council states, with cross-border coordination requirements intensifying as Saudi Arabia's entertainment calendar expands beyond seasonal peaks.
United Arab Emirates
Dubai's Department of Economy and Tourism enforces venue-specific logistics windows that compress delivery scheduling flexibility for international touring productions. MOHAP food-safety certification mandates ISO-compliant cold chains from origin kitchen through final venue handoff, elevating compliance costs for new market entrants. Expo City Dubai's permanent warehousing concentration zones offer anchor points for regional distribution network expansion across corporate hospitality segments.
Saudi Arabia
The Saudi Entertainment Authority licensing reforms are compressing event lead times while generating sustained demand for specialized freight corridors and on-site material staging yards around Riyadh and Jeddah venues. SFDA parallel food-safety enforcement for catered events requires temperature-logging documentation across the supply chain. The emerging Riyadh-Jeddah concert circuit is concentrating investment in dedicated entertainment trucking pools with chip-based RFID manifest capabilities.
Qatar
Stadium zone logistics requirements from mega-sporting infrastructure sustain peak demand for bonded warehousing and temperature-controlled facilities near Doha exhibition districts. The country's national event regulator enforces compliance protocols for temporary imports that elevate operational overhead for cross-border touring productions. Industrial clusters around Doha Port concentrate customs clearance risk for international equipment haulage.
Kuwait
Independent temporary import frameworks create compliance complexity for touring productions crossing multiple Gulf states, fragmenting bonded corridor availability for entertainment cargo. The national customs authority maintains distinct procedures from neighboring UAE and Saudi Arabia, inflating coordination costs for multi-country event circuits. Limited dedicated cold-chain infrastructure concentrates certified technician scarcity risks for MOHAP-equivalent catering logistics.
Bahrain
Smaller venue scale limits dedicated logistics infrastructure investment, forcing reliance on cross-border haulage from Saudi Arabia and UAE distribution hubs. The island's customs administration operates independent temporary import frameworks that extend clearance timelines for international touring equipment. Manama's exhibition zones depend on regional freight forwarding networks rather than captive warehousing capacity.
GCC Event Logistics Market Competitive Landscape
Global majors compete with regional champions across port-to-venue infrastructure control, with the market exhibiting tiered consolidation around specialized service capabilities. Port operators and integrated logistics groups anchor upstream freight corridors, while dedicated event specialists capture downstream on-site coordination margins. Three archetypes dominate: port-centric integrated providers, temperature-controlled warehousing specialists, and concert touring fleet operators. Competitive moves concentrate on multi-year partnership bundling and real-time dispatch technology integration.
Among regional champions, DP World exemplifies port-centric network anchoring across Jebel Ali and King Abdulaziz Port corridors. GWC Logistics occupies a position within the temperature-controlled warehousing specialist tier, serving Qatar's stadium ecosystem. Sasat Logistics represents the dedicated concert touring fleet archetype, with operational concentration across Riyadh and Jeddah venues. These three anchors illustrate how procurement consolidation from fragmented single-source arrangements toward coordinated partnerships is recalibrating vendor selection criteria across GCC event supply chains.
| Leading Market Players |
|---|
| Sasat Logistics |
| Handle Logistics |
| DP World |
| Glaube Logistics |
| Gulf Agency Company |
| GWC Logistics |
| SOS Global Logistics |
| Clarion Integrated Logistics Solutions |
| 4Events |
| Others |
Pricing and Supply Chain Analysis
Diesel benchmark fluctuations at Jebel Ali and King Abdulaziz Port cascade through bonded trucking rates into three distinct service tiers across GCC event logistics, with fuel surcharges now separating retained capacity contracts from spot-market procurement.
Pricing Analysis
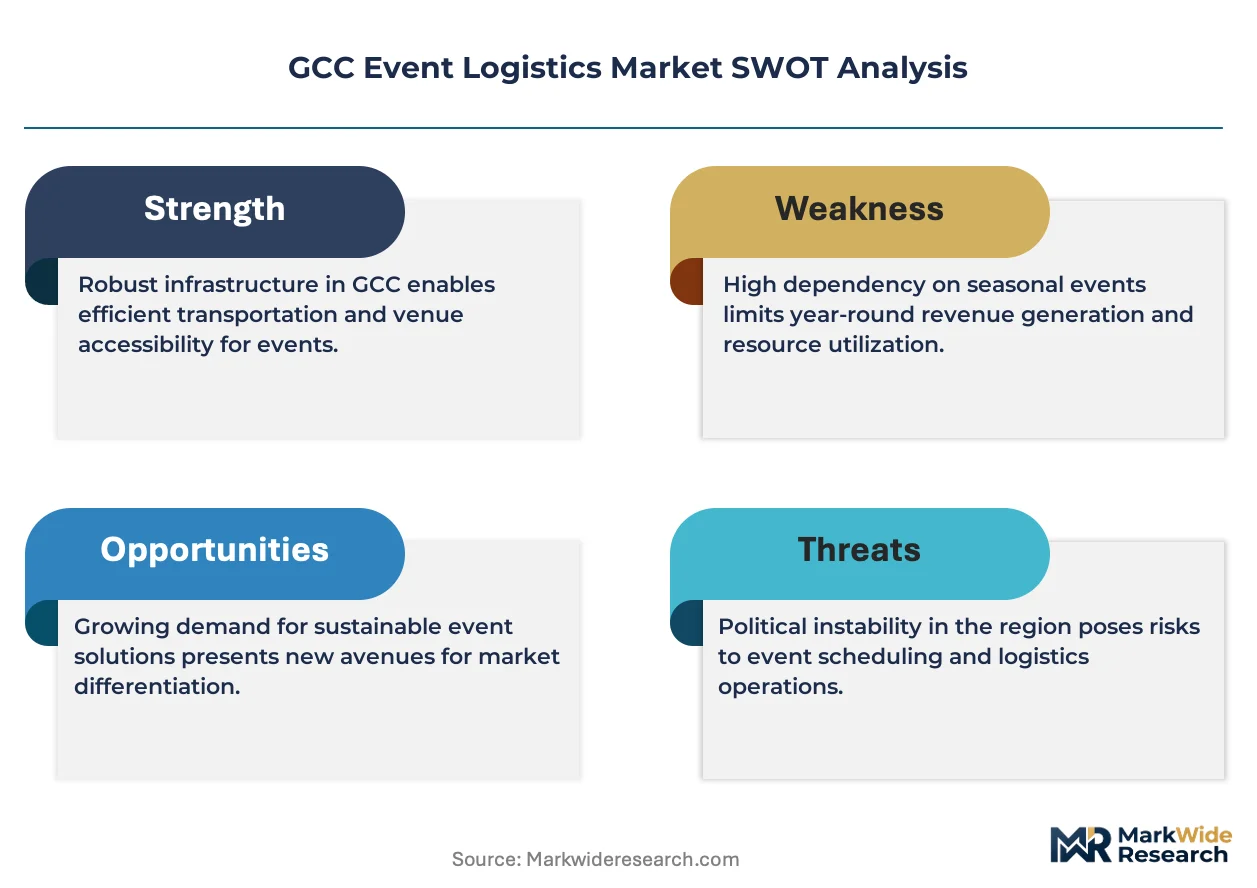
Input-cost pass-through from specialized flatbed fleet leasing and unionized labor dispatch rates shapes contract structures across the sector. Three-tier pricing stratifies across ISO-certified cold-chain, bonded customs corridor, and standard ground transport levels. Price differentiation hinges on MOHAP food-safety certification tier and real-time GPS tracking integration. Cost compression in standard ground transport is intensifying because of concert touring fleet oversupply around Riyadh venues. Government clients exhibit lowest price sensitivity due to national-day programming mandates, while non-profit donors drive hardest bargain negotiation.
Supply Chain Analysis
Direct-to-venue channels handle hyperscale government and corporate event demand, bypassing traditional freight forwarding layers. Supply concentrates in the United Arab Emirates, Saudi Arabia, and Qatar as anchor points for regional distribution. Raw material dependencies include refrigerated trailer chassis, RFID tracking hardware, and temperature-controlled container units. Single-source vulnerability runs through bonded customs corridor scarcity at Jebel Ali and King Abdulaziz Port. Distribution runs through port-centric integrated providers, temperature-controlled warehousing specialists, and dedicated concert touring fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC event logistics functions as a regulatory compounder where Saudi Entertainment Authority licensing reforms and UAE MOHAP certification mandates continuously elevate compliance barriers and service premiums.
For Market Incumbents: Lock in multi-year partnership bundling with Saudi Entertainment Authority-licensed promoters before spot-market competitors capture retained capacity slots. Defend margin position through backward integration into temperature-controlled warehousing near Doha stadium zones and Riyadh exhibition districts. Counter emerging fleet oversupply threats by anchoring exclusive venue access agreements with Dubai's Department of Economy and Tourism.
For New Entrants and Emerging Players: Begin with MOHAP food-safety certification investment to penetrate Dubai corporate hospitality segments where pre-qualification barriers exclude uncertified carriers. Target Bahrain and Kuwait cross-border coordination white space where independent temporary import frameworks fragment incumbent service consistency. Pursue chip-based RFID manifest capabilities as mandatory entry ticket for Saudi festival organizer vendor lists.
For Investors and Strategic Acquirers: Asymmetric upside sits with temperature-controlled warehousing specialists possessing dual UAE-Qatar operational footprints and existing SFDA compliance infrastructure. Five-to-ten year viability favors providers capturing year-round retained capacity rather than seasonal peak dependence. Monitor Saudi Entertainment Authority licensing calendar density as inflection signal for baseline demand stabilization.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Partnership Bundling | Consolidates transportation, warehousing, and on-site management under single-source agreements with penalty clauses. |
| MOHAP Certification Investment | Unlocks Dubai corporate hospitality pre-qualification where real-time monitoring certification outweighs price competition. |
| RFID Manifest Integration | Meets Saudi festival organizer mandates for chip-based cargo tracking across cross-border haulage corridors. |
| Backward Integration into Cold-Chain Warehousing | Captures premium margins from SFDA and MOHAP parallel enforcement requiring temperature-logging documentation. |
| Exclusive Venue Access Agreements | Secures logistics window priority with Dubai's Department of Economy and Tourism enforcement constraints. |
Research Methodology
Direct dialogue with logistics operations directors, Saudi Entertainment Authority licensing officers, UAE MOHAP compliance auditors, and festival production managers grounded qualitative findings in operational reality. Secondary validation drew from customs authority temporary import procedure documentation, GCC national event regulator filings, bonded warehousing facility registries, and exhibition venue logistics window schedules. Bottom-up service provider capacity assessments and top-down event calendar demand modeling enabled cross-verification.
Segment-level projections across service type, client category, event format, and delivery mode dimensions were generated through driver-based modeling. CAGRs were derived from historical event volume trajectories, infrastructure investment pipelines, and regulatory calendar expansion schedules. Key inputs included Saudi stadium construction completion timelines, Expo City Dubai warehousing absorption rates, and cross-border trucking fleet deployment patterns.
Several conditions sit outside the modeled scope, including geopolitical disruption to GCC customs union functionality, abrupt entertainment visa framework reversals, and pandemic-scale event cancellation scenarios. Forecasts reflect assumptions around sustained regulatory reform momentum and infrastructure investment continuity. Periodic stress-testing of base assumptions is recommended against actual licensing calendar density and bonded corridor capacity utilization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Tennessee Freight and Logistics Market
Logistics and Shipping
United Kingdom Cold Chain Logistics Market
Logistics and Shipping
GCC Secure Logistics Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
China Same Day Delivery Market
Logistics and Shipping
Germany Third-Party Logistics (3PL) Market
Logistics and Shipping
China Third-Party Logistics (3PL) Market
Logistics and Shipping
Maritime Logistics and Services Market
Logistics and Shipping
South Africa Air Freight Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
Shipping Container Modification Market
Logistics and Shipping
Freight Brokerage Market
Logistics and Shipping
Global Automated Container Terminal Market