
 Faucet Market | 2026-2036
Faucet Market Size, Share, and Industry Trends Forecast 2026-2036
Faucet Market Intelligence
The concentration of purchasing power among large-scale residential developers and hotel chains is decoupling brand selection from individual end-user preference. LIXIL Group Corporation leverages its extensive brand portfolio, including Grohe and American Standard, to serve multiple market tiers. Kohler sustains its premium positioning through design innovation and strong relationships with architects. Delta Faucet Company competes on proprietary water-saving technologies and a broad distribution network.
A faucet is a valve-controlled plumbing fixture for delivering water from a single pipe or system. Core functionality relies on internal cartridges, often ceramic disc or compression types, to regulate water flow and temperature precisely. Bathroom faucets command the largest market share, while kitchen faucets with integrated pull-down sprayers represent a high-growth product category. In terms of materials, brass remains the standard for premium offerings, while stainless steel leads in commercial settings.
Water efficiency standards, such as the EPA's WaterSense program in the United States and Australia's WELS scheme, mandate specific maximum flow rates for products. Concurrently, regulations like Europe's REACH and California's Proposition 65 restrict the use of lead and other hazardous substances in brass alloys. Navigating these fragmented and evolving water conservation and material safety regulations is a critical competency for market participants.
Market Dynamics
The central dynamic in the faucet market is the tension between increasingly stringent water conservation mandates and parallel regulations governing material safety. Manufacturers must engineer products that meet flow rate limits set by schemes like the EPA's WaterSense while simultaneously reformulating alloys to comply with substance restrictions under Europe's REACH framework.
Growth Catalysts
- Urban Development Projects:Large-scale residential and hospitality construction in developing urban centers, particularly across India and Brazil, creates substantial volume demand for faucets across all tiers.
- Advanced Finishing Processes:The adoption of Physical Vapor Deposition (PVD) technology allows for a wider range of durable and aesthetically varied finishes, catering to designer and consumer demand for customization in the premium residential sector.
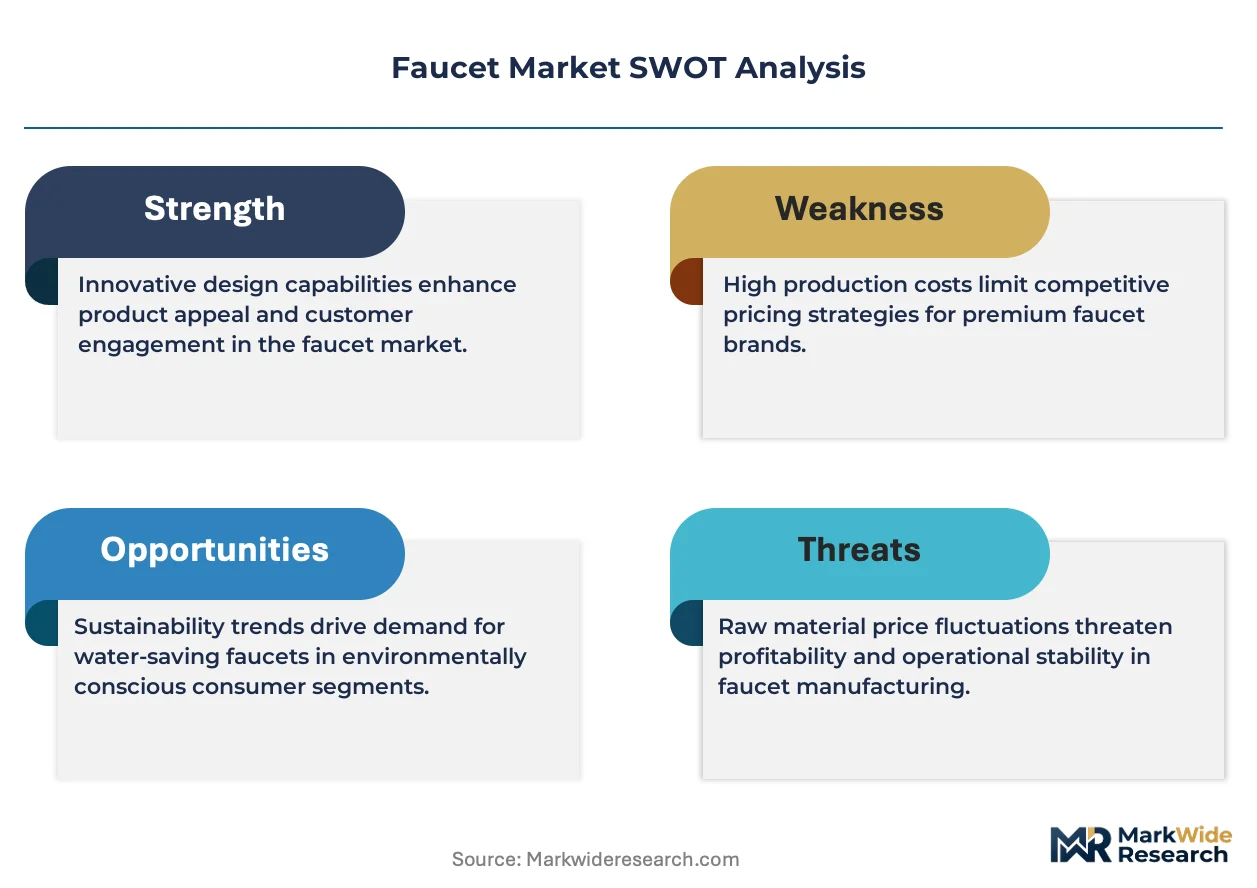
- Water-Saving Technologies:Proprietary innovations in aeration and valve design that exceed mandatory water efficiency standards provide a key competitive differentiator, appealing to environmentally conscious consumers and commercial operators seeking lower utility costs.
Market Restraints
- Input Material Volatility:Fluctuation in the price of core raw materials, especially commodity metals like brass and zinc, directly impacts manufacturing costs and creates significant margin pressure for producers.
- Fragmented Material Regulations:Divergent chemical safety standards, such as Europe's REACH and California's Proposition 65, necessitate costly region-specific product formulations and testing, complicating global supply chain management.
- Threat from Polymer Substitutes:In price-sensitive, entry-level market segments, the performance of lower-cost polymer and composite faucets is improving, presenting a substitution threat to traditional metallic fixtures.
Strategic Opportunities
- Smart Home Integration:Incorporating IoT connectivity for voice activation, temperature presets, and water usage monitoring presents an opportunity to create a new premium category of intelligent faucets for the connected home.
- Aftermarket and Renovation Kits:Developing easy-to-install retrofit kits with modern features like touchless sensors or enhanced water efficiency targets the large, underpenetrated renovation segment in mature North American and European markets.
- Direct-to-Consumer Channels:Expanding direct-to-consumer (DTC) e-commerce capabilities allows brands to bypass traditional wholesale distribution, control brand messaging, and capture higher margins on design-led products.
Industry Challenges
- Complex Certification Pathways:Navigating the lengthy and expensive certification processes for multiple standards, including WaterSense for efficiency and NSF/ANSI 61 for material safety, for each new product delays time-to-market.
- Specialized Component Sourcing:The supply of critical components like high-performance ceramic disc cartridges is concentrated among a few specialized suppliers, creating potential bottlenecks and sourcing vulnerabilities for faucet manufacturers.
- Intellectual Property Protection:Defending unique design aesthetics and proprietary water-saving mechanisms from counterfeit manufacturing and IP infringement remains a persistent operational challenge in several high-growth regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Faucet Market |
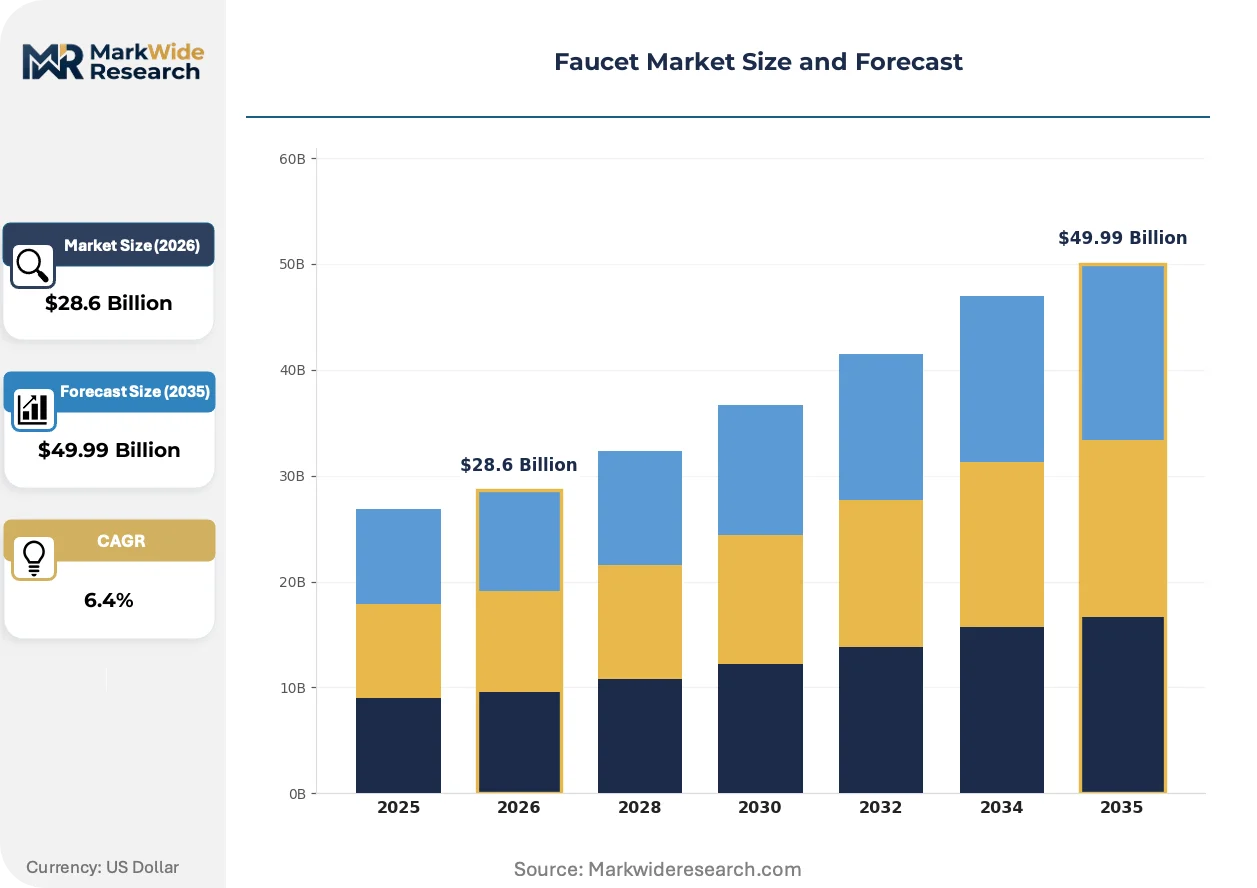
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Faucets, Bathroom Faucets, Shower Faucets, Bidet Faucets Installation Type: Wall-Mounted, Deck-Mounted, Freestanding, Under-Sink Material: Stainless Steel, Brass, Plastic, Chrome Style: Modern, Traditional, Industrial, Rustic |
| Companies Covered | TOTO, Hansgrohe, Kohler, Pfister, American Standard, Moen, Delta Faucet Company, LIXIL Group Corporation, Grohe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Faucet Market Strategic Shifts & Innovations
Innovation in the faucet market is driven by the convergence of sustainability requirements and a demand for greater user interaction and aesthetic value. This pushes product development beyond mere water delivery to focus on hygiene, convenience, and design expression within kitchens and bathrooms.
Digital controls and touchless sensor technology are defining the next generation of faucet interfaces. Commercial and healthcare facilities are the primary adopters, driven by hygiene imperatives, with the high-end residential segment following. This integration of electronics is absorbing the traditional mechanical cartridge's role, transforming the faucet from a simple valve into an intelligent water delivery device.
European Union regulations, particularly REACH, are forcing significant material science innovation. The directive's strict limitations on lead and other hazardous substances in brass alloys compel manufacturers to invest in and commercialize new lead-free metal formulations. This affects the entire premium segment, which is now marketing these safer materials as a key product benefit.
Aesthetic and material coordination is a visible demand-side shift influencing purchasing decisions. Consumers and designers increasingly select faucets as part of a complete hardware suite, requiring finishes and forms to match cabinet pulls, lighting, and accessories. This trend is most prominent in the North American and European residential renovation markets, elevating the role of design specification.
Faucet Market Segmentation
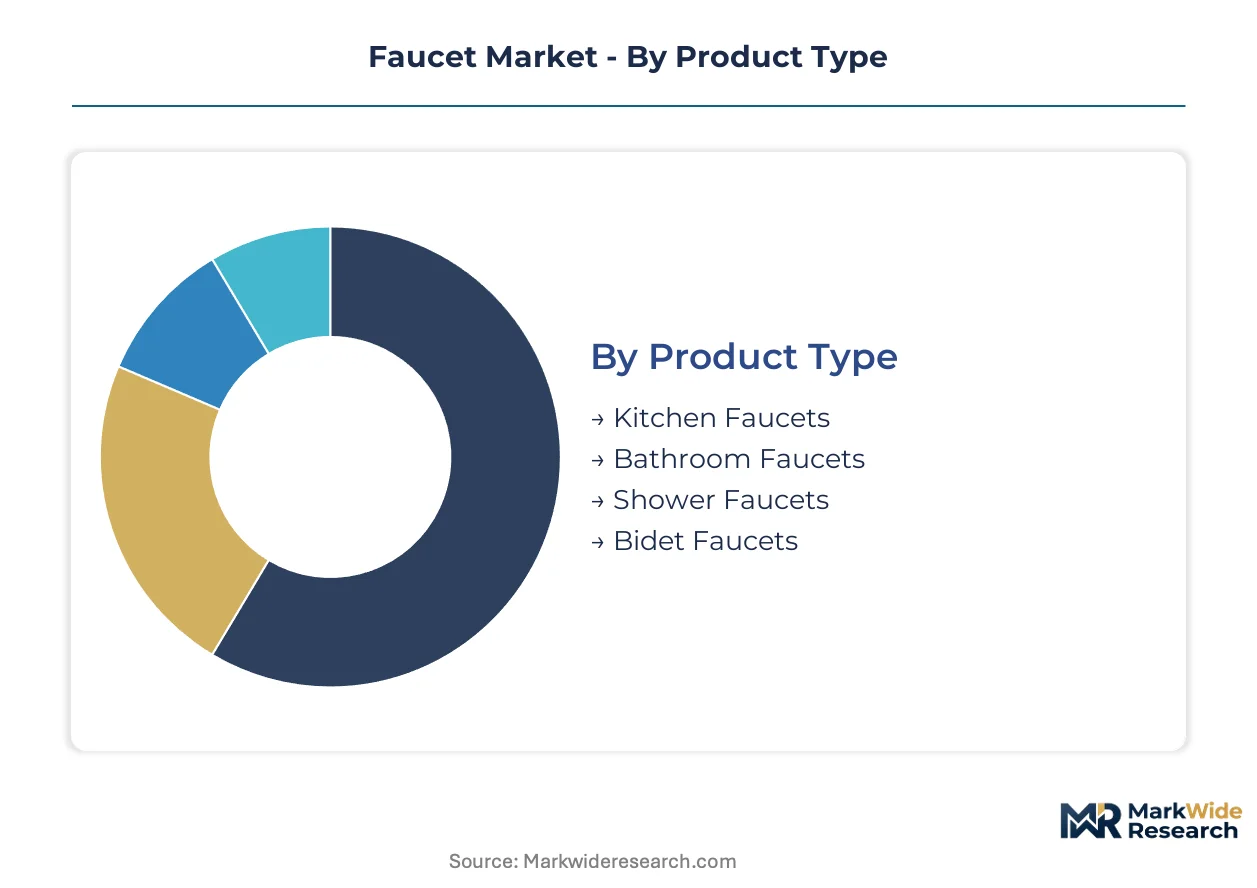
Understanding the distinct segments within the faucet market reveals the varied demands across residential, commercial, and hospitality sectors. Product specifications, material choices, and installation methods directly influence manufacturing processes and distribution channels. This granular segmentation allows market participants to tailor product development and marketing strategies to specific end-user needs and regulatory environments.
Product Type:
The functional specification of a faucet dictates its primary application and design complexity, influencing both user interaction and installation requirements.
- Kitchen Faucets:These fixtures often integrate advanced features like pull-down sprayers and touchless activation, catering to convenience and hygiene in high-use areas. Demand for kitchen faucets with integrated water filtration systems is expanding in urban households across India.
- Bathroom Faucets:Commanding the largest market share, bathroom faucets focus on aesthetic integration with vanity designs and water efficiency standards like EPA's WaterSense. High-end residential projects in Brazil frequently specify designer bathroom fixtures.
- Shower Faucets:These products emphasize water delivery patterns and temperature control, often incorporating thermostatic valves for user comfort and safety. Shower faucet innovation focuses on multi-function spray settings.
- Bidet Faucets:Primarily found in specific cultural markets and luxury residential settings, bidet faucets offer specialized hygiene functions. Their design often mirrors accompanying toilet and sink fixtures for aesthetic cohesion.
Bathroom Faucets leads on scale; Kitchen Faucets leads on momentum.
Installation Type:
Installation complexity and aesthetic preference drive the differentiation across various mounting configurations, impacting both plumbing requirements and visual design.
- Wall-Mounted:These faucets free up counter space and offer a minimalist aesthetic, frequently specified in modern bathroom and kitchen designs. Wall-mounted installations require precise in-wall plumbing for proper function.
- Deck-Mounted:Representing the most common installation type, deck-mounted faucets are easily integrated into standard sink and countertop configurations. Their widespread use makes them a volume driver in new construction projects.
- Freestanding:Typically used for bathtubs in luxury bathrooms, freestanding faucets serve as a design focal point. These installations require floor-mounted plumbing connections and stable base support.
- Under-Sink:Primarily for specialized applications like filtered water dispensers, under-sink installations are discreet and connect directly to a dedicated water line. These units prioritize functionality over visible design elements.
Deck-mounted faucets dominate standard residential applications, while wall-mounted variants offer design flexibility in contemporary spaces.
Material:
Material composition directly influences a faucet's durability, aesthetic finish, and compliance with safety regulations across diverse applications.
- Stainless Steel:Valued for its corrosion resistance and hygienic properties, stainless steel is a preferred material for commercial kitchens and healthcare facilities. Its lead-free composition also appeals to markets with strict material safety regulations.
- Brass:This alloy remains the industry standard for premium faucet bodies due to its machinability, durability, and ability to hold various finishes. Manufacturers are reformulating brass to meet lead restriction mandates like California's Proposition 65.
- Plastic:Used in budget-sensitive applications and utility areas, plastic faucets offer cost-effectiveness and resistance to certain chemicals. The performance of polymer substitutes is improving in entry-level market segments.
- Chrome:Often a finish applied over brass or other metals, chrome provides a durable, reflective surface that is easy to clean. Chrome is a popular choice for its classic aesthetic and wide availability.
Brass alloys define the premium segment, while stainless steel secures preference in high-durability and commercial environments.
Style:
Aesthetic considerations and architectural trends define the distinct style categories within the faucet market, catering to varied interior design preferences.
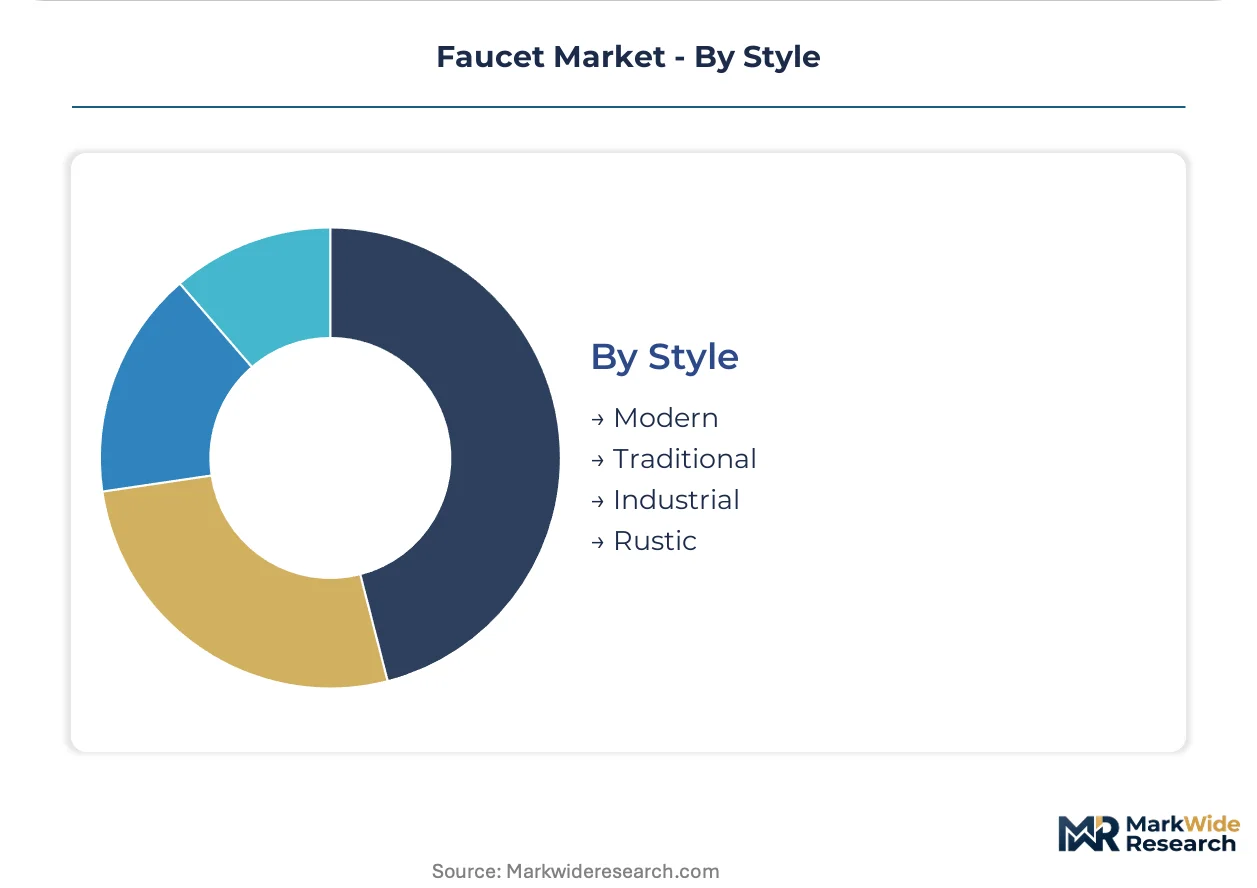
- Modern:Characterized by clean lines, minimalist forms, and often geometric shapes, modern faucets appeal to contemporary interior design schemes. This style frequently incorporates new technologies like touchless sensors.
- Traditional:Featuring ornate details, classic curves, and often cross-handle designs, traditional faucets complement vintage or classic bathroom and kitchen aesthetics. This style maintains consistent demand in established renovation markets.
- Industrial:Drawing inspiration from factory and utilitarian designs, industrial faucets often feature exposed pipes, raw metal finishes, and robust construction. This style is gaining traction in urban loft and commercial-inspired spaces.
- Rustic:Evoking a natural or farmhouse feel, rustic faucets incorporate distressed finishes, natural materials, and often lever-style handles. This aesthetic resonates with consumers seeking a warm and earthy design.
Modern styles capture contemporary design preferences, as traditional aesthetics maintain a consistent demand in established markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highly skilled labor in manufacturing and design across Germany's industrial heartland anchors European faucet production. This talent concentration supports advanced engineering and aesthetic innovation in premium offerings. Global demand for sophisticated fixtures shapes product development cycles.
India
Demand for kitchen faucets with integrated water filtration systems drives volume in Indian urban households. The PLI scheme supports domestic manufacturing and technological upgrades. Major urban development projects in Mumbai and Delhi create substantial demand for new installations.
Brazil
Rising middle-class housing needs and hospitality sector expansion fuel faucet demand across Brazil. ANVISA regulations ensure material safety and product quality for consumer goods. High-end residential projects in São Paulo frequently specify designer bathroom fixtures.
United States
Residential renovation markets and commercial construction projects generate consistent faucet demand in the United States. The EPA's WaterSense program mandates specific maximum flow rates for water efficiency. California's Proposition 65 restricts hazardous substances in brass alloys, impacting product formulations in major cities like Los Angeles.
Germany
Premium design innovation and stringent quality standards characterize the German faucet market. Europe's REACH framework compels manufacturers to reformulate alloys to comply with substance restrictions. Production hubs in North Rhine-Westphalia focus on high-performance and aesthetically advanced fixtures.
China
Large-scale urban development and a growing middle class increase demand for both functional and aesthetic faucets in China. GB standards ensure product quality and safety across all market tiers. Manufacturing clusters in Guangdong province serve both domestic and export markets with diverse product ranges.
Faucet Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the faucet market, influencing pricing and product availability. This market structure features a mix of global brands leveraging extensive portfolios and regional manufacturers concentrating on specific niches and customer segments. Strategic archetypes include design-driven innovators, volume-oriented producers, and technology specialists focusing on water-saving features and smart home integration. Competitive moves often involve portfolio diversification to cover multiple price points and geographic expansion into high-growth urban centers, alongside strategic partnerships for distribution.
Within the premium segment, Kohler exemplifies a design-driven innovator, sustaining its positioning through strong architect relationships. LIXIL Group Corporation, a diversified conglomerate, leverages its extensive brand portfolio, including Grohe and American Standard, to serve multiple market tiers. Delta Faucet Company represents a technology specialist, competing on proprietary water-saving technologies and a broad distribution network. These entities anchor distinct competitive approaches, from aesthetic leadership to functional differentiation and broad market reach.
| Leading Market Players |
|---|
| TOTO |
| Hansgrohe |
| Kohler |
| Pfister |
| American Standard |
| Moen |
| Delta Faucet Company |
| LIXIL Group Corporation |
| Grohe |
| Others |
Cost & Logistics Intelligence
Brass commodity prices, a primary input for premium faucet bodies, cascade through the supply chain, directly influencing manufacturing costs and tiered product pricing. This material cost volatility impacts profit margins across all market segments.
Pricing Analysis
Capacity additions in China are reshaping price floors for entry-level and mid-tier faucet products. The market primarily operates on a tiered premium-mid-economy pricing differentiation, reflecting brand premium and certification level for water efficiency and material safety. Pricing softness reflects intense competition from polymer substitutes in price-sensitive segments. High-end residential projects and commercial operators demonstrate lower price sensitivity, prioritizing design and performance.
Supply Chain Analysis
Skilled labor availability in manufacturing hubs like Germany and China influences component sourcing. The faucet supply chain draws from concentrated raw material sources for brass alloys and specialized component suppliers for ceramic disc cartridges. Commodity price volatility for metals like zinc and brass presents a significant structural risk. Downstream distribution runs through broad networks, increasingly supplemented by direct-to-consumer e-commerce channels for design-led products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost differentials between China and Germany create geographic-arbitrage opportunities in the faucet market, allowing for optimized production strategies. Regulatory compliance costs also vary significantly by region.
For Market Incumbents: To counter input material volatility and IP infringement, incumbents should deepen vertical integration into key component manufacturing, particularly for ceramic disc cartridges. Investing in R&D for advanced lead-free brass formulations secures compliance with evolving regulations like California's Proposition 65. Expanding distribution in high-growth urban centers across India and Brazil defends market share against regional competitors.
For New Entrants and Emerging Players: Capture white-space opportunities by focusing on smart home integration for faucets, targeting tech-savvy urban households. The renovation market in mature North American and European markets offers a penetrable segment through easy-to-install retrofit kits with enhanced water efficiency. A direct-to-consumer e-commerce strategy allows for controlled brand messaging and higher margins on design-led products.
For Investors and Strategic Acquirers: Asymmetric upside sits with technology specialists and design-driven innovators capable of navigating complex regulatory landscapes. Long-term viability hinges on companies that can integrate IoT connectivity and commercialize sustainable, lead-free material solutions. Adoption rates of smart home devices in residential construction serve as a critical signal to watch for future market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D | Commercializing lead-free brass alloys ensures compliance with REACH and Proposition 65, appealing to environmentally conscious consumers. |
| IoT Faucet Product Launch | Introducing intelligent faucets with voice activation and water usage monitoring creates a new premium category in the connected home. |
| Direct-to-Consumer Channel Expansion | Establishing robust e-commerce platforms allows brands to bypass traditional wholesale, enhancing margin control and customer engagement. |
| Retrofit Kit Development | Offering easy-to-install renovation kits targets the large, underpenetrated aftermarket in North American and European markets. |
| Strategic Partnerships for Smart Home | Collaborating with smart home ecosystem providers accelerates integration and broadens market reach for intelligent faucet solutions. |
Research Approach
Bottom-up residential developers and hotel chains modeling reconciled against top-down faucet manufacturers tracking forms the analytical core of this study. The methodology integrates extensive primary interviews with R&D directors, procurement leads, hospitality project managers, and regulatory compliance officers. Secondary validation draws from EPA WaterSense databases, REACH compliance documents, construction project pipelines, and relevant trade association reports.
Historical trendline analysis informs the projection of market progression across the analysis window. This framework models market segmentation by product type, installation type, material, style, and end-use sector, alongside regional adoption patterns. Compound annual growth rates are derived from a multi-variant analysis incorporating urban development project pipelines and raw material price forecasts.
Raw material price volatility, evolving regulatory standards, and global construction cycles are the dominant revision risks. Forecasts reflect assumptions documented through stakeholder consultations and secondary research. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
New Zealand Bathroom Products Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Luxury Plumbing Fixtures Market
Bathroom Fixtures and Accessories
Shower Chairs Market
Bathroom Fixtures and Accessories
Pullout Faucets Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
US Toilet Partition Market
Bathroom Fixtures and Accessories
Washbasin Market
Bathroom Fixtures and Accessories
Bidet Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
Smart Toilet Seat Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market