
 US Smart Kitchen and Bathroom Products Market | 2026-2036
US Smart Kitchen and Bathroom Products Market Size, Share, and Industry Trends Forecast 2026-2036
US Smart Kitchen and Bathroom Products Market Insights
Stainless steel is pivoting toward brushed nickel and matte black finishes across fixture portfolios, altering unit economics for premium smart faucets and shower systems. Moen Incorporated leverages its voice-activated technology leadership to dominate connected-bath installations in high-rise residential towers. Kohler Co. anchors its position through captive ceramic production and proprietary valve engineering. Delta Faucet Company competes on modular retrofit platforms that reduce contractor labor hours.
Smart kitchen and bathroom products encompass sensor-enabled fixtures and appliances integrating IoT architectures, voice recognition modules, and wireless protocols to automate water delivery, climate control, and cooking functions. These systems typically operate on 2.4 GHz Wi-Fi or Zigbee mesh networks with IP67-rated seals for moisture resistance, serving residential and commercial users seeking operational efficiency and hygiene automation. Smart faucets lead product type revenue due to replacement-cycle frequency and lower installation complexity, while smart ovens capture margin concentration through embedded camera systems and AI-driven recipe platforms. Voice activation technology sustains the fastest growth trajectory as Amazon Alexa and Google Home ecosystems penetrate builder-grade specifications.
The EPA WaterSense program and DOE appliance efficiency standards constrain flow rates and energy consumption, compelling manufacturers to recalibrate sensor sensitivity and heating element design. FCC certification requirements govern wireless connectivity modules, adding compliance layers for IoT-enabled product lines. Stakeholders must monitor state-level water restriction statutes in California and Arizona, as these jurisdictions typically prefigure national efficiency rulemaking.
Market Dynamics
Voice-activated fixture control is compressing replacement cycles across residential new construction, while EPA WaterSense flow-rate mandates force sensor recalibration that lengthens product development timelines by 8-14 months.
Growth Catalysts
- Builder specification mandates:Luxury multifamily developers in Manhattan and Miami now require smart shower systems as standard amenity packages, pulling forward demand from renovation cycles.
- DOE appliance efficiency standards:Tightening energy consumption thresholds for connected ovens and warming drawers accelerate replacement of pre-2018 installed base.
- Zigbee mesh protocol adoption:Interoperability improvements reduce homeowner setup friction, expanding retrofit penetration in Texas and Florida residential corridors.
Market Restraints
- Semiconductor input volatility:Wi-Fi and Bluetooth module lead times remain extended, constraining production scheduling for sensor-enabled faucets.
- California water restriction prefiguration:State-level flow-rate statutes below federal WaterSense floors force SKU fragmentation that elevates inventory carrying costs.
- Copper and nickel price instability:Raw material swings compress margin predictability for brushed nickel and matte black finish portfolios.
Strategic Opportunities
- Aging-in-place retrofit demand:Voice-activated temperature control and automatic shutoff functionality address caregiver-assisted living installations in Florida retirement communities.
- IRA residential energy credits:Federal tax incentives for efficient appliance upgrades subsidize smart oven replacements in suburban Texas markets.
- AI-driven recipe platform convergence:Embedded camera systems and machine learning recommendation engines differentiate premium connected cooking appliances.
Industry Challenges
- FCC certification timeline compression:Wireless connectivity module approvals for 2.4 GHz and 5 GHz bands extend product launch windows by 90-120 days.
- Legacy plumbing contractor skill gaps:Electrical and network configuration requirements exceed traditional trade training, creating installation quality variance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smart Kitchen and Bathroom Products Market |
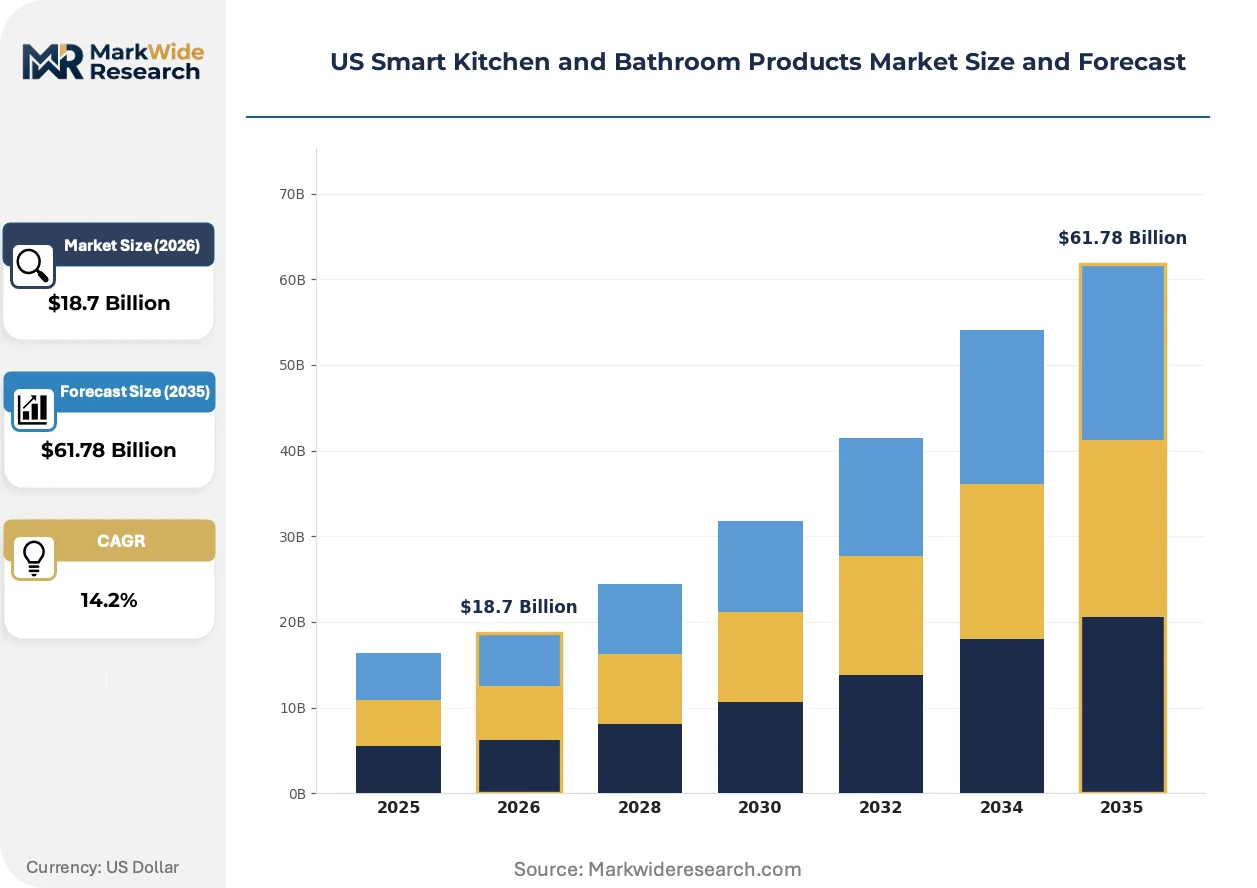
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Faucets, Smart Showers, Smart Ovens, Smart Refrigerators Technology: IoT, Voice Activation, Motion Sensing, Wireless Connectivity End User: Households, Commercial Kitchens, Hotels, Healthcare Facilities Installation Type: Built-in, Retrofit, Modular, Custom |
| Companies Covered | Delta Faucet Company, Moen Incorporated, Kohler Co., Signature Hardware, Pfister, American Standard, GROHE AMERICA, INC., Kraus USA Plumbing LLC, TOTO LTD., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smart Kitchen and Bathroom Products Market Trends and Innovations
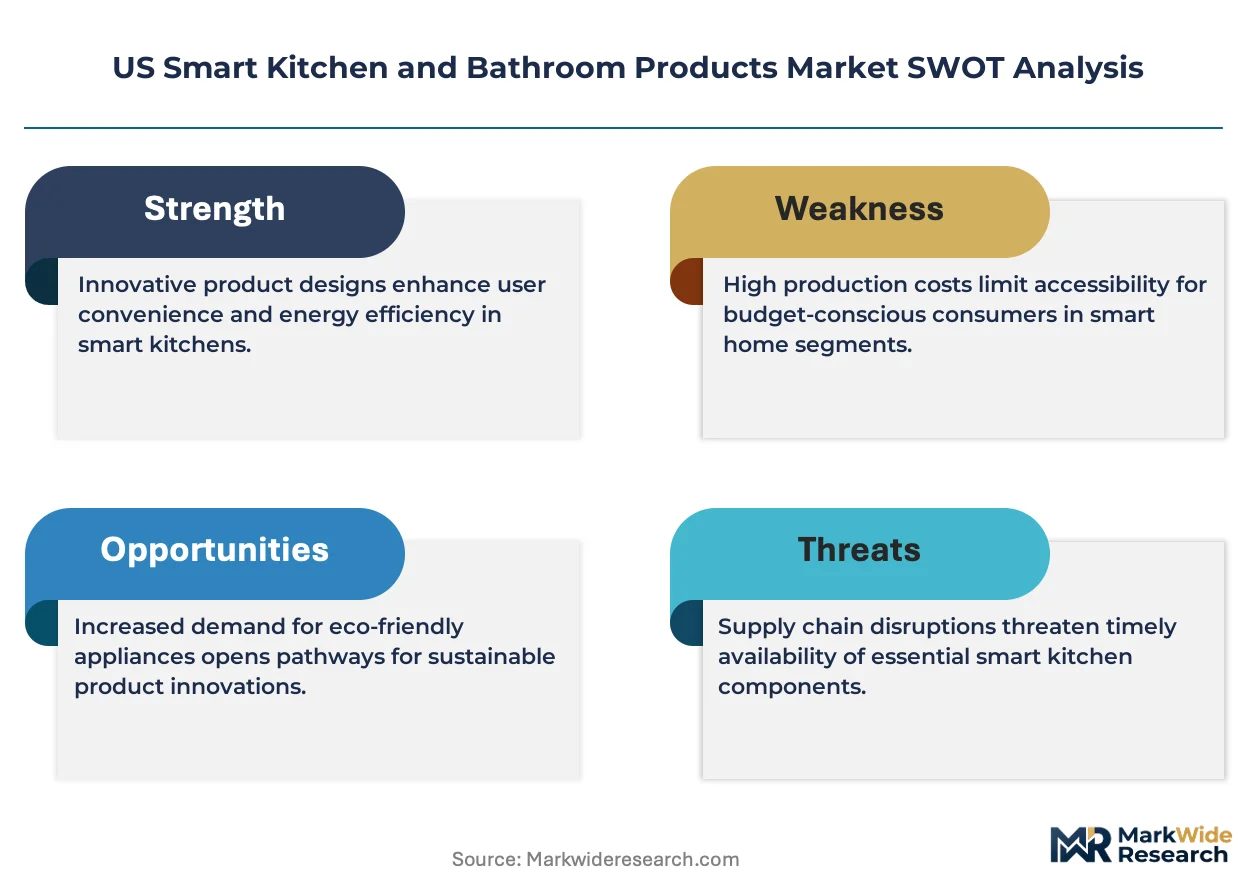
Connected fixture architectures are bifurcating between closed proprietary ecosystems and open interoperability standards, forcing manufacturers to place platform bets that will determine 2030 competitive positioning.
Touchless infrared sensor technology is expanding into mid-market faucet replacements, with regional home improvement retailers in Texas and Florida now stocking IP67-rated units alongside traditional mechanical models. Production scale at sensor module suppliers is compressing unit costs by one-third annually, enabling penetration below the $200 retail threshold. This expansion is displacing basic ceramic disc cartridge faucets in new construction specifications.
EPA WaterSense certification requirements are tightening maximum flow rates for lavatory and kitchen fixtures, compelling manufacturers to recalibrate aerator geometry and pressure-compensating valve design. The industrial consequence is elevated R&D allocation toward computational fluid dynamics simulation and rapid prototyping. High-rise residential towers in Manhattan face the most acute compliance pressure, as dual-flush smart toilets and restricted-flow showerheads become mandatory for municipal permitting.
Homeowner procurement of smart fixtures is migrating from showrooms to direct-to-manufacturer digital channels, with configuration tools that visualize finish and feature combinations replacing physical sample handling. This channel shift compresses distributor margins while elevating brand-owned customer data assets. The pattern is most pronounced in Florida markets, where seasonal residents complete renovation planning remotely before arrival.
US Smart Kitchen and Bathroom Products Market Segmentation
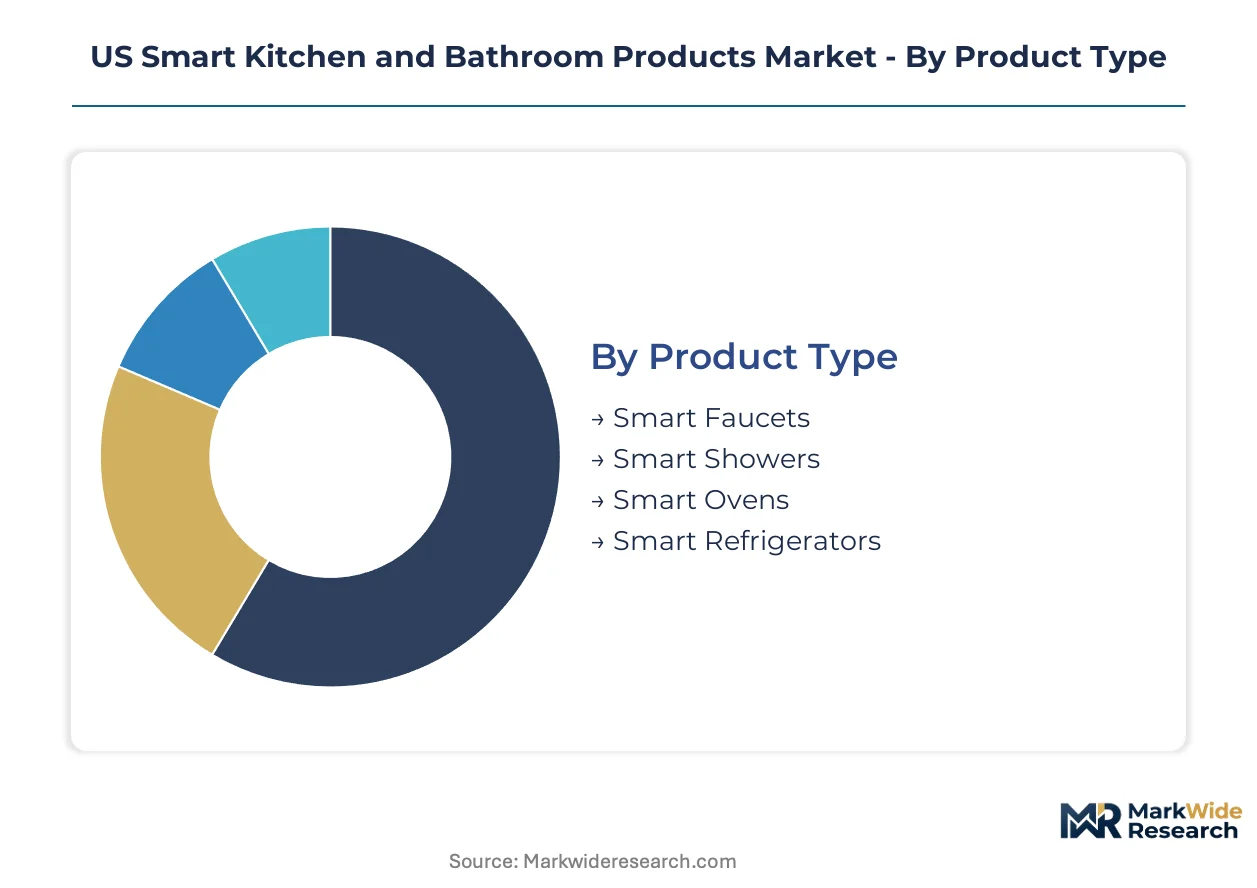
Smart kitchen and bathroom product manufacturers calibrate portfolio allocation across four distinct segmentation axes. Each dimension reveals divergent margin profiles, installation complexity thresholds, and regulatory exposure that shape capital deployment decisions.
Product Type:
Supply concentration in sensor module manufacturing favors high-volume fixture categories with standardized electronic architectures over appliance categories requiring custom thermal management systems.
- Smart Faucets:Sensor-enabled water delivery systems integrate infrared proximity detection and solenoid valve control within IP67-rated housings. Demand concentrates in Texas and Florida residential construction corridors where replacement-cycle frequency and lower contractor labor requirements accelerate penetration.
- Smart Showers:Thermostatic mixing valves with digital temperature control and preset programming interface with home automation hubs. Manhattan and Miami luxury multifamily developers specify these as standard amenity packages, pulling forward demand from renovation cycles.
- Smart Ovens:Embedded camera systems and AI-driven recipe platforms differentiate premium connected cooking appliances.
- Smart Refrigerators:Inventory tracking and climate zone automation command premium positioning in suburban Texas markets eligible for IRA residential energy credits.
Today's leader: Smart Faucets. Tomorrow's challenger: Smart Ovens.
Technology:
Cost tier stratification separates mature connectivity protocols with commoditized component costs from emerging interfaces requiring specialized semiconductor fabrication.
- IoT:2.4 GHz Wi-Fi and Zigbee mesh network architectures enable cloud-based monitoring and predictive maintenance algorithms. EPA WaterSense flow-rate mandates force sensor recalibration that lengthens product development timelines.
- Voice Activation:Amazon Alexa and Google Home ecosystem integration sustains the steepest expansion trajectory as builder-grade specifications increasingly mandate hands-free control.
- Motion Sensing:Touchless infrared sensor technology expands into mid-market faucet replacements stocked by regional home improvement retailers.
- Wireless Connectivity:FCC certification requirements for 2.4 GHz and 5 GHz bands extend product launch windows by 90-120 days.
Current volume anchor: IoT. Emerging disruptor: Voice Activation.
End User:
Application-driven specification requirements create divergent certification burdens and service contract structures across residential and institutional procurement channels.
- Households:Homeowner procurement migrates from showrooms to direct-to-manufacturer digital channels with configuration tools replacing physical sample handling.
- Commercial Kitchens:High-duty-cycle operation demands industrial-grade sensor durability and NSF certification compliance.
- Hotels:Brand standardization across property portfolios favors proprietary ecosystem lock-in with centralized facility management integration.
- Healthcare Facilities:Infection control protocols drive touchless specification mandates with ADA accessibility requirements.
Volume foundation: Households. Margin expansion: Healthcare Facilities.
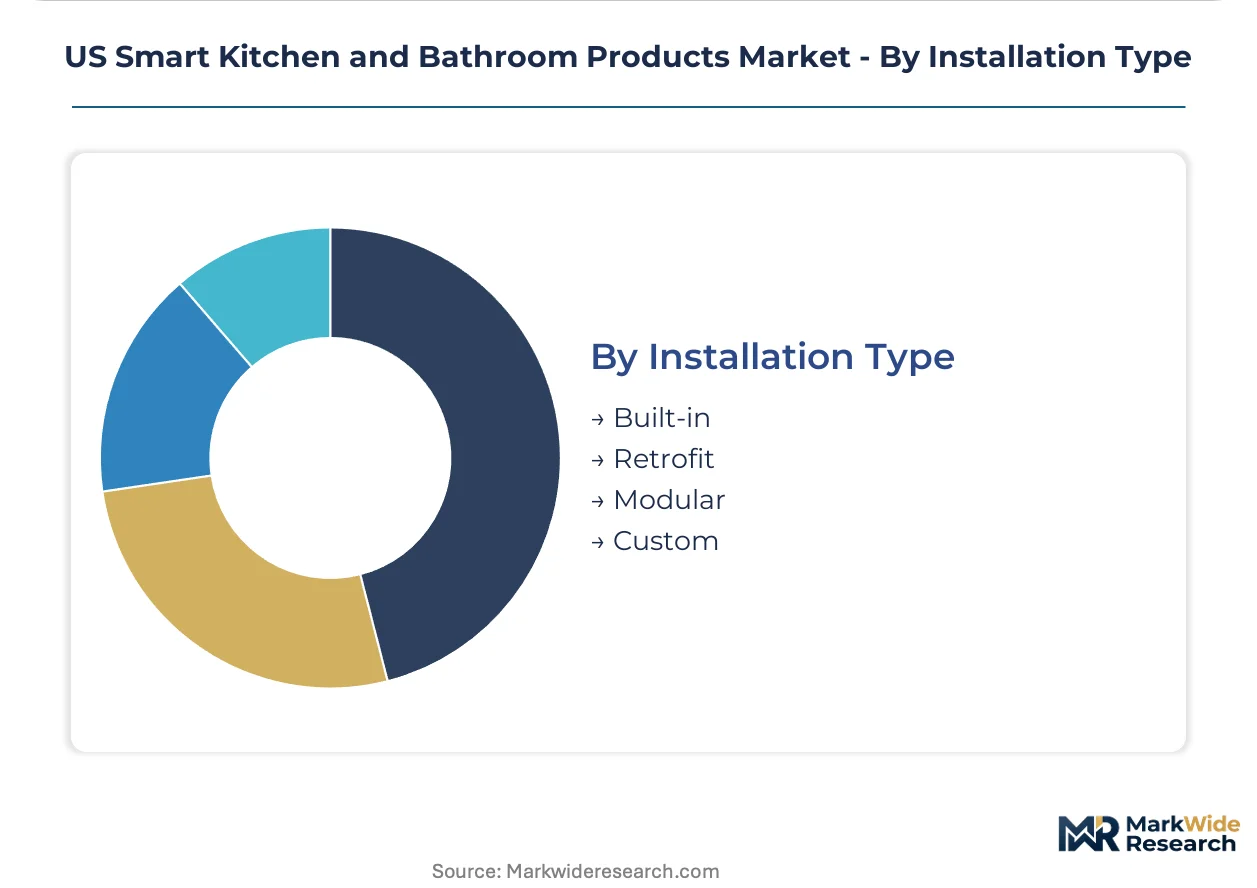
Installation Type:
Customer type segmentation separates new construction specifications with embedded electrical rough-in from renovation projects constrained by existing plumbing infrastructure.
- Built-in:New construction specifications integrate power and network infrastructure during rough-in phase, enabling full feature activation without retrofit constraints.
- Retrofit:Battery-powered and wireless bridge solutions address legacy plumbing infrastructure in Florida retirement community aging-in-place renovations.
- Modular:Component-swappable platforms reduce contractor labor hours and enable field-upgradable feature expansion.
- Custom:Architect-specified finishes and proprietary valve engineering anchor high-rise residential tower projects in Manhattan.
Scale winner: Built-in. Flexibility leader: Modular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas and Florida residential construction corridors concentrate smart fixture demand through new multifamily permitting and hurricane-resistant building code adoption. EPA WaterSense certification requirements and DOE appliance efficiency standards shape product availability across state lines.
Texas
IRA residential energy credits subsidize smart oven replacements in suburban Dallas-Fort Worth and Houston markets. The DOE appliance efficiency standards accelerate replacement of pre-2018 installed base in high-growth counties. San Antonio and Austin metro areas anchor Zigbee mesh protocol adoption through builder-grade smart home packages.
Florida
Aging-in-place retrofit demand concentrates in Tampa and Orlando retirement communities requiring voice-activated temperature control. State-level building codes for hurricane resistance intersect with smart shutoff functionality mandates. Miami luxury multifamily developers specify smart shower systems as standard amenity packages.
California
Water restriction statutes below federal WaterSense floors force SKU fragmentation that elevates inventory carrying costs for Los Angeles and Bay Area distributors. The state's flow-rate prefiguration shapes national efficiency rulemaking timelines. San Diego and Sacramento corridors test predictive maintenance algorithms for drought-responsive irrigation integration.
New York Metro
Manhattan luxury high-rise residential towers face acute EPA WaterSense compliance pressure for municipal permitting. Dual-flush smart toilets and restricted-flow showerheads become mandatory in Brooklyn and Queens new construction. Voice-activated fixture control compresses replacement cycles across residential new construction in the five boroughs.
Arizona
State-level water restriction statutes prefigure national efficiency rulemaking for desert climate fixture specifications. Phoenix and Tucson residential construction corridors prioritize sensor-enabled water delivery systems with pressure-compensating valve design. The Colorado River shortage contingency planning accelerates smart irrigation crossover demand for bathroom fixture suppliers.
US Smart Kitchen and Bathroom Products Market Competitive Landscape
Global majors compete with regional champions across fixture finish portfolios and voice-activation technology integration. The vendor base stratifies into three tiers: full-line plumbing manufacturers with captive ceramic production, specialty sensor technology licensors, and private-label assemblers serving home improvement retail channels. Dominant competitive moves include modular retrofit platform development to reduce contractor labor hours, and proprietary ecosystem lock-in through centralized facility management integration.
Within the full-line manufacturing tier, Moen Incorporated, Kohler Co., and Delta Faucet Company exemplify divergent strategic positioning. Moen occupies a position anchored in voice-activated technology leadership for connected-bath installations. Kohler exemplifies backward integration into captive ceramic production and proprietary valve engineering. Delta represents the modular retrofit platform archetype that reduces contractor labor hours in field installations.
| Leading Market Players |
|---|
| Delta Faucet Company |
| Moen Incorporated |
| Kohler Co. |
| Signature Hardware |
| Pfister |
| American Standard |
| GROHE AMERICA, INC. |
| Kraus USA Plumbing LLC |
| TOTO LTD. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists with multi-generational manufacturing heritage dominate fixture production in Wisconsin and Pennsylvania, anchoring pricing discipline through captive foundry operations and resisting margin erosion despite semiconductor input volatility. Their ownership structure insulates pricing from quarterly earnings pressure while enabling long-term supply contracts with regional home improvement retailers.
Pricing Analysis
Input-cost pass-through from copper and nickel price instability compresses margin predictability for brushed nickel and matte black finish portfolios. Three-tier pricing structure across premium, standard, and economy levels separates WaterSense-certified fixtures from basic mechanical models, with certification grade commanding measurable premiums. Pricing pressure stems from California water restriction statutes below federal floors forcing SKU fragmentation. Renovation contractors in Florida retirement communities exhibit highest price sensitivity, while Manhattan luxury developers demonstrate lowest sensitivity due to amenity packaging economics.
Supply Chain Analysis
Freight cost inflation across Pacific routes elevates landed costs for sensor modules fabricated in Taiwan and South Korea. Wi-Fi and Bluetooth semiconductor dependencies draw from concentrated East Asian foundry capacity, with Zigbee mesh protocol chipsets resting on single-source vulnerability at tier-two suppliers. Distribution runs through regional home improvement retailers in Texas and Florida corridors, bypassing traditional plumbing wholesale channels for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Smart Kitchen and Bathroom Products Market functions as a regulatory compounder where EPA WaterSense certification tightening and DOE appliance efficiency standards generate replacement-cycle demand independent of discretionary renovation spending.
For Market Incumbents: Hedge against semiconductor input volatility through dual-source qualification of Wi-Fi and Zigbee module suppliers in Taiwan and South Korea. Deepen backward integration into sensor calibration and valve engineering to compress EPA-mandated recalibration timelines. Defensive positioning requires modular retrofit platform expansion to capture contractor labor hour reductions in Florida aging-in-place installations. For New Entrants and Emerging Players: Launch via direct-to-manufacturer digital channels with configuration tools targeting seasonal Florida residents completing remote renovation planning. White-space concentration sits in voice-activated temperature control for Tampa and Orlando retirement communities, with battery-powered retrofit solutions addressing legacy plumbing infrastructure. Go-to-market positioning should emphasize Zigbee mesh protocol interoperability to reduce homeowner setup friction. For Investors and Strategic Acquirers: Valuations sit cheapest among private-label assemblers serving home improvement retail channels without captive ceramic production or proprietary valve engineering. Long-term viability across the analysis window favors targets with EPA WaterSense pre-certification and IRA residential energy credit eligibility. The signal to monitor is FCC certification timeline compression for 5 GHz wireless connectivity modules as inflection indicator for product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Retrofit Platform Expansion | Reduces contractor labor hours in Texas and Florida field installations. |
| Voice Activation Technology Integration | Captures builder-grade specifications mandating Amazon Alexa and Google Home compatibility. |
| EPA WaterSense Pre-Certification Investment | Accelerates municipal permitting in Manhattan and Miami high-rise towers. |
| Direct-to-Consumer Digital Channel Buildout | Compresses distributor margins while elevating brand-owned customer data assets. |
| Dual-Source Semiconductor Qualification | Mitigates Wi-Fi and Bluetooth module lead time constraints from Taiwan and South Korea. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with product managers at full-line plumbing manufacturers, procurement leads at regional home improvement retailers, EPA WaterSense program administrators, and electrical contractors in Texas and Florida residential corridors with secondary validation against DOE appliance efficiency standard filings, FCC equipment authorization databases, and municipal permitting records from Manhattan and Miami building departments. Bottom-up SKU-level shipment data triangulated against top-down construction spending forecasts.
Segment-weighting across product type, technology, end user, and installation type dimensions calibrated volume and value outputs throughout the forecast period. Smart faucet replacement-cycle frequency, smart oven AI-driven recipe platform adoption curves, and voice activation technology penetration in builder-grade specifications informed analytical framework construction. CAGRs derived from regression analysis of historical permitting data against efficiency standard implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended semiconductor lead times or accelerated state-level water restriction prefiguration. Forecasts reflect assumptions documented in EPA regulatory dockets and DOE rulemaking timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bathroom Fixtures and Accessories
Toilet Partition Market
Bathroom Fixtures and Accessories
Germany Bathroom Furniture Market
Bathroom Fixtures and Accessories
India Steam Rooms Market
Bathroom Fixtures and Accessories
Automatic Toilet Seat Market
Bathroom Fixtures and Accessories
Shower Tray Market
Bathroom Fixtures and Accessories
North America Plumbing Fixture Market
Bathroom Fixtures and Accessories
US Faucet Market
Bathroom Fixtures and Accessories
Baby Changing Tables and Stations Market
Bathroom Fixtures and Accessories
United Kingdom Bath Fitting Market
Bathroom Fixtures and Accessories
Europe Bath and Shower Products Market
Bathroom Fixtures and Accessories
Bathroom Cabinets Market
Bathroom Fixtures and Accessories
Bathroom Accessories Market
Bathroom Fixtures and Accessories
Shower Curtain Market
Bathroom Fixtures and Accessories
Australia Bathroom Products Market
Bathroom Fixtures and Accessories
Faucet Market
Bathroom Fixtures and Accessories
Bathtub Market