
 Furniture Laminate Market | 2026-2036
Furniture Laminate Market Size, Share, and Industry Trends Forecast 2026-2036
Furniture Laminate Market Insights
CARB Phase 2 certification is unwinding competitive access for laminate producers serving North American furniture OEMs, forcing reformulation investments that smaller resin suppliers cannot absorb. Wilsonart LLC leverages captive thermosetting resin production to sustain margin stability despite volatile phenol pricing. Greenlam Industries Limited anchors South Asian supply through integrated decorative paper printing and pressing operations near Gujarat. Merino Laminates Ltd. differentiates via specialized textured and suede surface finishes targeting premium residential developers.
Furniture laminate denotes a multi-layer composite surface material manufactured by impregnating kraft paper core layers and decorative overlay papers with thermosetting resins, then consolidating under heat and pressure exceeding 1,000 psi for high-pressure grades to achieve wear resistance exceeding 4,000 Taber abrasion cycles. The resulting product provides durable, hygienic, and aesthetically customizable surfaces for desks, cabinetry, wall panels, and retail fixtures subject to heavy use. High-pressure laminate occupies the premium specification tier among architects and commercial contractors demanding superior impact resistance and warranty longevity. Decorative laminate competes aggressively on visual replication of wood grain, stone, and metal textures for hospitality settings where surface finish drives brand perception. Low-pressure laminate dominates volume production among furniture manufacturers prioritizing cost efficiency in standardized office and educational furniture lines.
EPA formaldehyde emissions standards under TSCA Title VI, California Air Resources Board (CARB) Phase 2 limits, and EU REACH chemical restrictions collectively constrain adhesive chemistry choices and elevate third-party verification costs for cross-border suppliers. The US Environmental Protection Agency enforces bonded wood product rules that require accredited laboratory testing and chain-of-custody documentation, while the European Chemicals Agency scrutinizes phenol and melamine derivatives for potential Substance of Very High Concern classification. Stakeholders must monitor evolving bio-based resin performance thresholds and regional certification reciprocity agreements to avoid supply disqualification as procurement specifications harden around health and circularity criteria.
Market Dynamics
Formaldehyde emissions compliance is fragmenting competitive access as CARB Phase 2 and EPA TSCA Title VI force reformulation investments that smaller resin suppliers cannot absorb, concentrating procurement among vertically integrated manufacturers with captive thermosetting resin production.
Growth Catalysts
- Antimicrobial surface specifications:Hospitality designers in hotel and restaurant fit-outs are mandating antimicrobial laminate grades for high-touch surfaces, pulling volume toward specialized HPL manufacturers with certified hygienic performance.
- India's furniture manufacturing cluster expansion:Residential and commercial furniture production around Gujarat and Punjab is concentrating laminate demand, with integrated decorative paper printing and pressing operations anchoring regional supply security.
- EU REACH hazardous substance restrictions:Evolving chemical regulations are redirecting procurement toward bio-based resin platforms and low-emission adhesive systems, rewarding early movers with qualification advantages in European specification channels.
Market Restraints
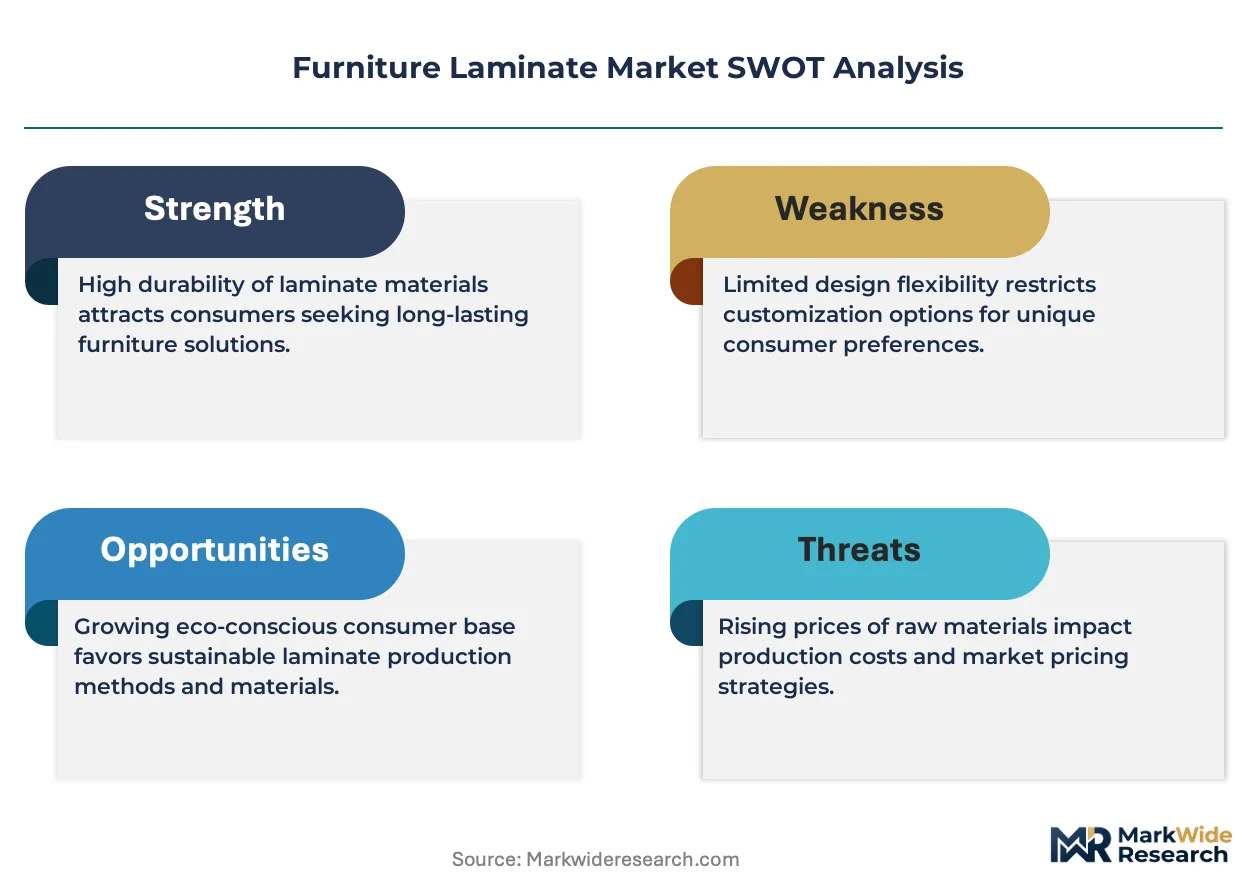
- Phenol input cost volatility:Thermosetting resin production depends on petrochemical feedstock pricing that fluctuates with crude oil and benzene markets, compressing margins for non-integrated laminate producers.
- Supply concentration in decorative paper:Specialty overlay paper manufacturing clusters in specific European and Asian geographies create single-source risk for premium aesthetic grades.
- Technical limitation in fire-rated formulations:Balancing fire resistance with low-emission performance requires proprietary resin chemistry that remains patent-protected by incumbent suppliers.
Strategic Opportunities
- Underpenetrated premium residential retrofit:India's urban housing stock renovation cycle is accelerating specification of textured and suede surface finishes for kitchen and wardrobe applications.
- Circular economy mandates:EU Ecodesign requirements and extended producer responsibility frameworks are creating first-mover advantage for laminate producers with certified recyclable or bio-based content.
- Digital print-on-demand decorative paper:Converging inkjet printing technology with short-run laminate production is enabling mass customization for boutique hospitality brands seeking unique surface aesthetics.
Industry Challenges
- Accredited laboratory testing capacity:EPA TSCA Title VI and CARB Phase 2 require chain-of-custody documentation and third-party verification that creates bottlenecks in certification timelines for new product launches.
- Legacy press reconfiguration:Transitioning from conventional melamine-formaldehyde to bio-based resin platforms requires capital-intensive modifications to multi-daylight hot press equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Furniture Laminate Market |
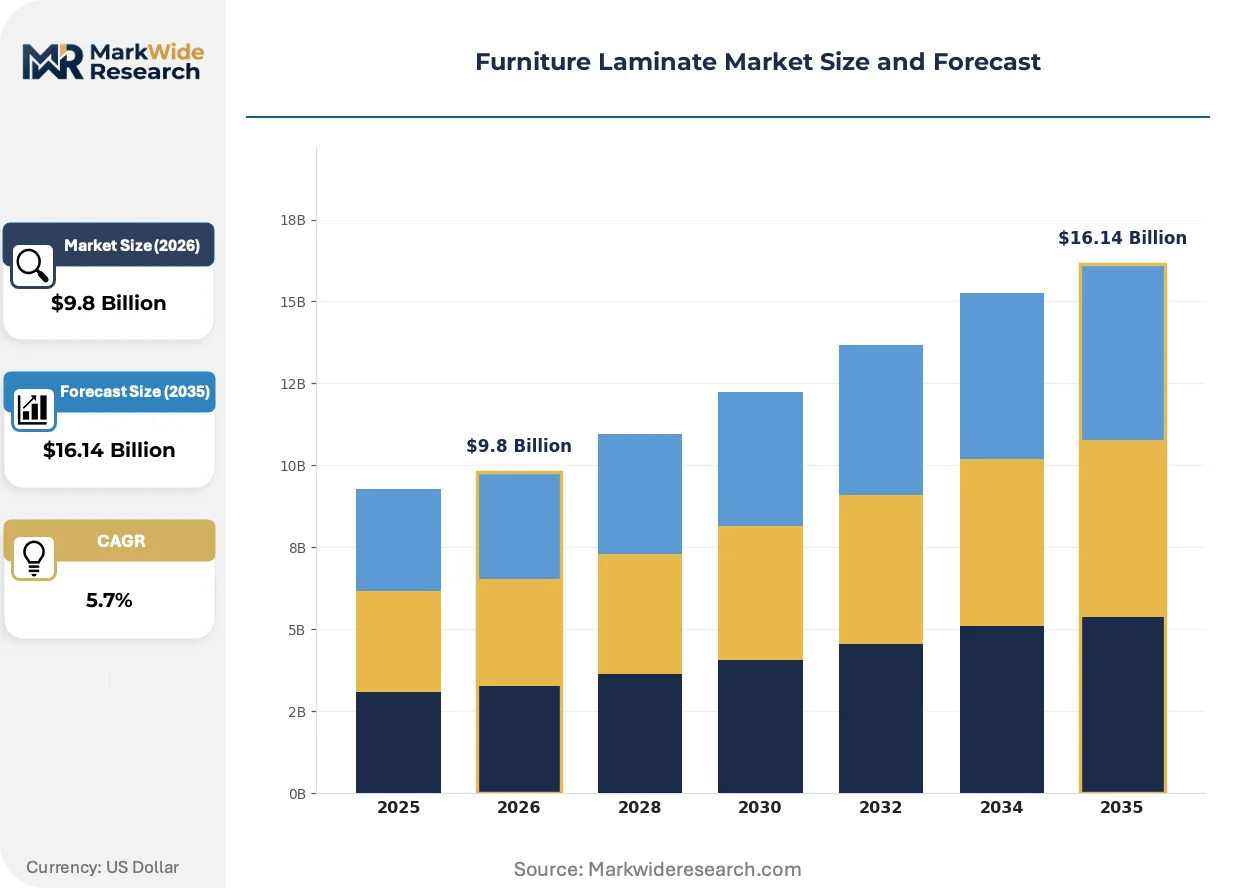
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Laminate, Low-Pressure Laminate, Decorative Laminate, Industrial Laminate, Compact Laminate Application: Office Interiors, Hospitality Settings, Educational Institutions, Healthcare Facilities, Retail Stores Surface Finish: Matte, Glossy, Textured, Embossed, Suede End User: Furniture Manufacturers, Interior Designers, Architects, Commercial Contractors, Residential Developers |
| Companies Covered | Wilsonart LLC, Greenlam Industries Limited, Merino Laminates Ltd., OMNOVA Solutions Inc., Stylam Industries Limited, FunderMax, Abet Laminati S.p.A., Panolam Industries International, Inc., Formica Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Furniture Laminate Market Trends and Innovations
Surface material science and regulatory chemistry are converging to redefine competitive positioning, as durability specifications harden around health criteria and digital manufacturing enables aesthetic differentiation at scale.
Thermosetting bio-resin formulations derived from lignin and plant-based phenol alternatives are decomposing the traditional petroleum-dependent supply structure. Hospitality and healthcare facility managers are piloting these materials for wall panel and cabinetry applications where indoor air quality certification drives procurement. The structural consequence is compressing margin pools for conventional melamine-formaldehyde producers while rewarding integrated resin compounders with backward control over biopolymer feedstocks.
EPA formaldehyde emissions standards under TSCA Title VI are tightening bonded wood product rules with mandatory accredited laboratory testing and documentation requirements. Furniture OEMs serving North American markets must now maintain chain-of-custody verification from resin impregnation through finished panel delivery. Commercial contractors and architectural specifiers are responding by consolidating supplier lists to vertically integrated laminate manufacturers with in-house testing capabilities and established EPA compliance protocols.
Specification-driven procurement is consolidating around certified low-emission and fire-rated product tiers as institutional buyers embed health and safety criteria into master specifications. Distributors serving educational and healthcare furniture channels are displacing generic catalog offerings with curated portfolios of third-party verified laminates. This pattern is most visible in California and EU member states where public procurement mandates reference CARB Phase 2 or CE-marked fire performance classifications.
Furniture Laminate Market Segmentation
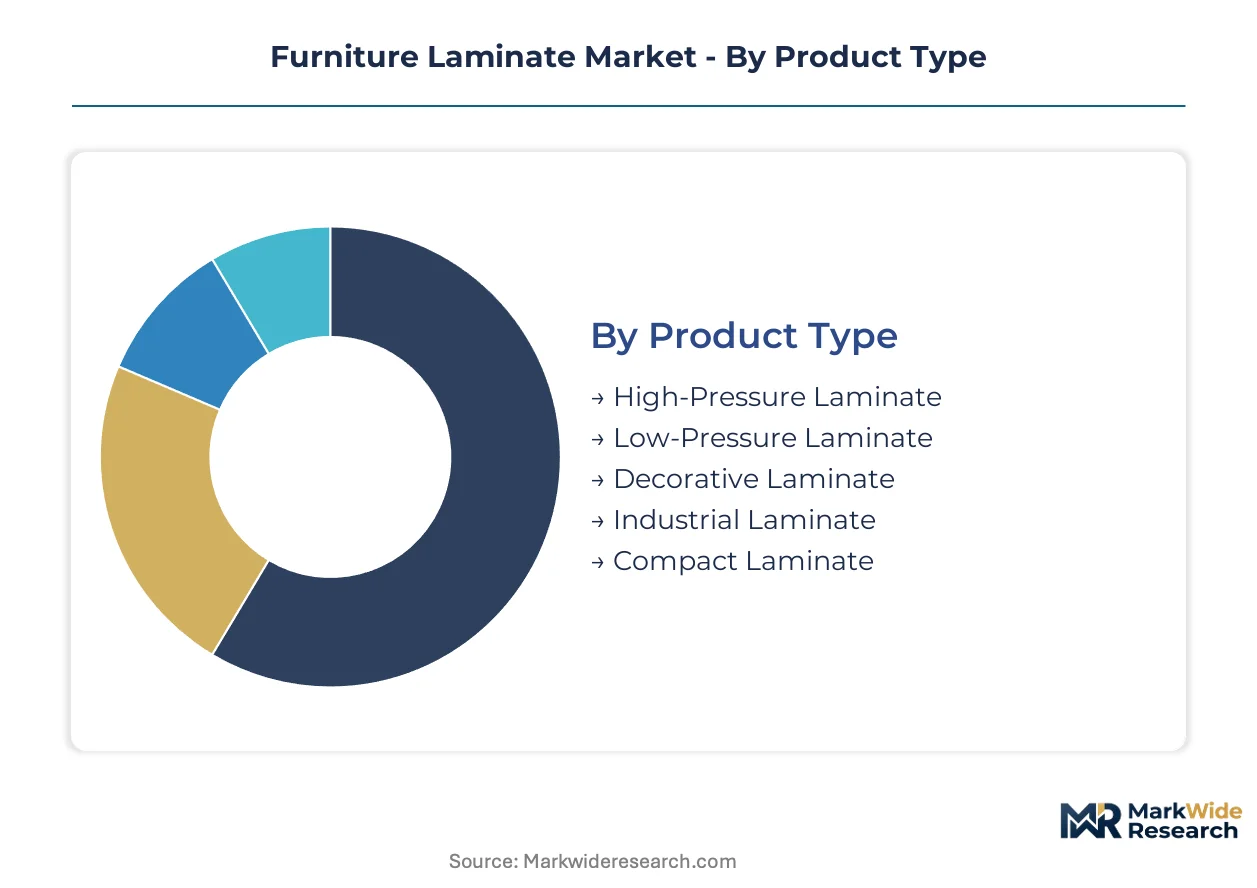
Furniture laminate segmentation reveals how specification authority and manufacturing scale distribute across material grades, installation environments, and aesthetic treatments. Procurement patterns diverge sharply between cost-driven furniture OEMs and design-led architectural specifiers, creating distinct margin architectures within each category.
Product Type:
Margin pools concentrate in thermosetting resin formulations where captive production and certification investments create defensive moats.
- High-Pressure Laminate:Multi-layer kraft paper cores impregnated with phenolic resins and consolidated above 1,000 psi deliver Taber abrasion resistance exceeding 4,000 cycles. Demand concentrates in California hospitality fit-outs where CARB Phase 2 compliance and fire-rated performance are non-negotiable for hotel operators seeking warranty longevity.
- Low-Pressure Laminate:Single-layer decorative paper bonded to particleboard substrates at lower pressure achieves cost efficiency for standardized furniture production. Volume concentrates among Indian furniture manufacturers around Gujarat and Punjab where residential and commercial production lines prioritize throughput over specification depth.
- Decorative Laminate:Visual replication of wood grain, stone, and metal textures for brand-driven surface aesthetics.
- Industrial Laminate:Heavy-duty grades engineered for laboratory and manufacturing environments requiring chemical resistance.
- Compact Laminate:Self-supporting thick grades for washroom partitions and locker systems without substrate backing.
The dominant share belongs to High-Pressure Laminate, while Low-Pressure Laminate is closing the gap fastest.
Application:
Specification intensity varies by setting durability requirements and regulatory exposure, with healthcare and hospitality commanding premium certification tiers.
- Hospitality Settings:Hotels and restaurants mandate antimicrobial surface grades for high-touch reception desks, restaurant tables, and guest room cabinetry. Procurement in EU member states prioritizes REACH-compliant low-emission systems, while California properties require CARB Phase 2 documentation for indoor air quality certification.
- Healthcare Facilities:Hospital and clinic interiors demand hygienic surface performance combined with fire resistance and chemical sterilization tolerance. Specification nurses and facility managers in Germany and France reference CE-marked fire performance classifications alongside ECHA substance restrictions.
- Office Interiors:Corporate furniture systems for workstations and conference rooms.
- Educational Institutions:School and university furniture subject to heavy-use durability requirements.
- Retail Stores:Fixture and display applications where visual impact drives brand presentation.
Hospitality Settings command the highest specification premiums, with Healthcare Facilities expanding most quickly as antimicrobial requirements harden.
Surface Finish:
Aesthetic differentiation and tactile performance create pricing stratification across premium, standard, and economy tiers.
- Textured:Embossed patterns replicating natural wood grain or fabric weaves provide slip resistance and visual depth. Indian premium residential developers in urban renovation cycles specify textured finishes for kitchen cabinetry and wardrobe systems where surface finish signals quality.
- Suede:Ultra-matte soft-touch surfaces target luxury hospitality and residential segments. Merino Laminates Ltd. has built differentiation around specialized suede formulations for boutique hotel brands seeking distinctive tactile identity.
- Matte:Low-sheen finishes reducing glare in office and educational environments.
- Glossy:High-reflectance surfaces for retail and decorative applications.
- Embossed:Three-dimensional surface patterns for enhanced visual and tactile interest.
Textured finishes hold the largest installed base, though Suede is gaining share fastest among premium specification channels.
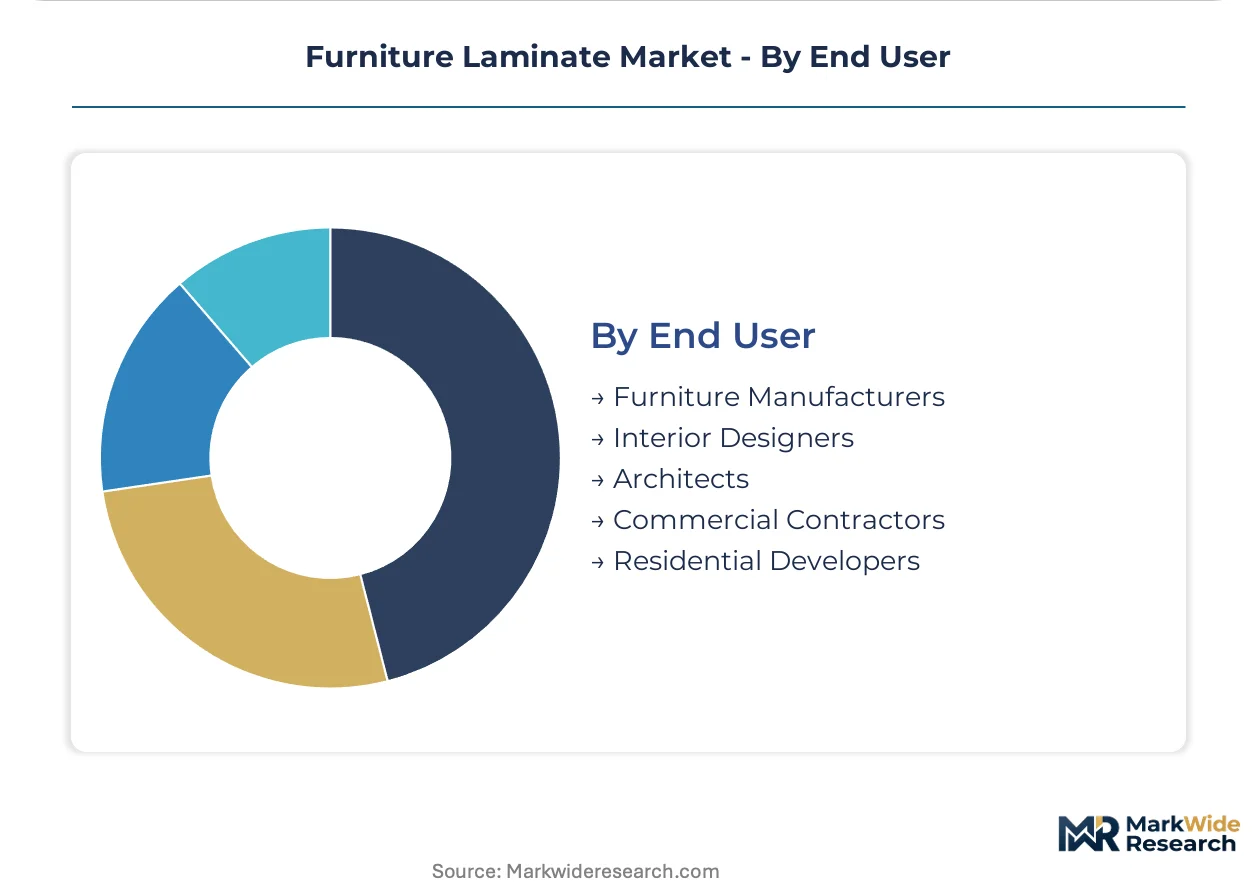
End User:
Procurement authority fragments across manufacturing, design, and construction stakeholders with divergent technical and commercial priorities.
- Architects:Design professionals embedding health, safety, and circularity criteria into master specifications for commercial and institutional projects. EU-based architects increasingly reference Ecodesign requirements and extended producer responsibility frameworks, consolidating supplier lists to vertically integrated manufacturers with certified bio-based content.
- Furniture Manufacturers:OEMs serving North American markets must maintain EPA TSCA Title VI chain-of-custody documentation from resin impregnation through finished panel delivery. Wilsonart LLC leverages captive thermosetting resin production to sustain margin stability despite volatile phenol pricing.
- Interior Designers:Specification consultants curating surface palettes for hospitality and residential projects.
- Commercial Contractors:Construction firms executing institutional builds with certified product mandates.
- Residential Developers:Property developers selecting finishes for multi-unit housing and renovation projects.
Furniture Manufacturers represent the largest volume channel, while Architects are climbing the fastest as specification authority consolidates around health and circularity criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Architects and furniture manufacturers concentrate procurement authority in distinct geographic clusters, with specification intensity varying sharply by regulatory exposure and manufacturing scale. California's CARB Phase 2 standards and the EU's REACH framework are redirecting procurement toward certified low-emission supply chains, while India's furniture manufacturing expansion is reshaping volume distribution.
United States
Hotel operators and commercial contractors drive antimicrobial and fire-rated laminate specifications for hospitality fit-outs. EPA TSCA Title VI enforcement mandates accredited laboratory testing and chain-of-custody documentation from resin impregnation through finished panel delivery. California's CARB Phase 2 formaldehyde emissions standards disqualify uncertified imports, concentrating procurement among domestic manufacturers with captive thermosetting resin production.
Germany
Healthcare facility managers and architectural specifiers demand CE-marked fire performance classifications alongside ECHA substance restrictions for hospital interiors. The EU Green Deal and Ecodesign requirements are embedding circularity criteria into public procurement mandates. Industrial clusters in North Rhine-Westphalia and Bavaria host vertically integrated laminate producers with in-house bio-based resin development capabilities.
India
Residential developers and furniture OEMs in Gujarat and Punjab are scaling production lines for kitchen cabinetry and wardrobe systems. BIS certification requirements and state-level environmental clearances govern formaldehyde emissions in bonded wood products. The Ahmedabad-Surat corridor anchors integrated decorative paper printing and pressing operations serving both domestic and export furniture manufacturing.
China
GB standards for indoor air quality and the country's dual carbon goals are pressuring conventional melamine-formaldehyde producers toward lignin-derived resin alternatives. The Yangtze River Delta and Pearl River Delta manufacturing belts concentrate high-volume laminate production for standardized office furniture exports. MIIT industrial upgrading programs are subsidizing press reconfiguration for bio-based thermosetting formulations.
Italy
Luxury hospitality brands and premium residential developers specify textured and suede surface finishes for distinctive tactile identity. CE marking and EU REACH compliance are baseline requirements for specification access across European markets. The Brianza furniture manufacturing district near Milan coordinates decorative laminate procurement with high-end cabinetry and interior systems production.
Furniture Laminate Market Competitive Landscape
Player mix skews toward vertically integrated specialists with captive resin production and certification infrastructure. The competitive structure concentrates procurement authority among manufacturers with in-house thermosetting compound capabilities and established EPA or CE-marked compliance protocols. Two strategic archetypes dominate: integrated resin-to-laminate producers leveraging backward control over feedstock costs, and decorative surface specialists differentiating through proprietary texture and finish portfolios. Capacity expansion in bio-based resin platforms and strategic partnerships for digital print-on-demand decorative paper represent the dominant competitive moves.
Among North American integrated producers, Wilsonart LLC exemplifies the resin-captive archetype with thermosetting production sustaining margin stability. Greenlam Industries Limited and Merino Laminates Ltd. represent the South Asian manufacturing cluster, with the former anchoring supply through integrated decorative paper operations near Gujarat and the latter occupying a position in specialized textured and suede finishes for premium residential developers. These three companies illustrate how geographic concentration and capability differentiation fragment competitive positioning across regulatory and specification tiers.
| Leading Market Players |
|---|
| Wilsonart LLC |
| Greenlam Industries Limited |
| Merino Laminates Ltd. |
| OMNOVA Solutions Inc. |
| Stylam Industries Limited |
| FunderMax |
| Abet Laminati S.p.A. |
| Panolam Industries International, Inc. |
| Formica Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization above 80% at Gujarat and Punjab pressing facilities compresses margin pools for non-integrated producers while elevating price floors for specialty decorative paper grades. Scale concentration among resin-captive manufacturers in India and the United States enables pricing power through backward control over phenolic compound production, forcing smaller competitors toward commodity low-pressure laminate tiers or exit.
Pricing Analysis
Cost-plus contracts with phenol indexation dominate thermosetting resin procurement, transferring feedstock volatility directly to laminate converters without margin buffers. Three-tier pricing structure across premium, standard, and economy levels separates CARB Phase 2-certified high-pressure grades from uncertified imports and generic low-pressure volumes. Pricing pressure stems from benzene derivative cost swings that compress converter margins during crude upturns. Furniture OEMs in standardized office and educational lines exhibit highest price sensitivity, while hospitality specifiers in California and EU member states absorb premiums for antimicrobial and fire-rated certification tiers.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and port congestion at Nhava Sheva elevate inbound logistics costs for European decorative paper imports into Indian pressing facilities. Manufacturing gravity centers on India, China, and Germany, with specialty overlay paper production concentrated in specific European and Asian geographies that create single-source exposure. Kraft paper cores, phenolic resins, and decorative overlay papers constitute critical input dependencies, with supply chain risk anchored in tariff exposure on Chinese phenol derivatives. Distribution runs through regional distributor networks serving furniture OEM clusters, with specification-driven procurement consolidating around vertically integrated manufacturers with captive resin production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house bio-based resin formulation capabilities have become the scarce asset separating qualified suppliers from disqualified bidders in EU and North American specification channels. The capability gap between integrated compounders and pure-play laminators is widening as EPA and ECHA documentation requirements harden.
For Market Incumbents: Consolidate testing infrastructure investments to secure accredited laboratory capacity for EPA TSCA Title VI and CARB Phase 2 chain-of-custody documentation, defending against emerging bio-resin specialists with faster certification timelines. Deepen backward integration into lignin-derived phenol alternatives to insulate margin pools from petrochemical feedstock volatility and pre-empt REACH substance restriction displacement. For New Entrants and Emerging Players: Digital print-on-demand decorative paper services represent a service-layer gap where incumbents under-serve boutique hospitality brands seeking short-run custom aesthetics. Target India's premium residential retrofit segment in urban kitchen and wardrobe renovation cycles, penetrating through specialized textured and suede finish portfolios that signal quality to developers. Pursue co-development partnerships with regional furniture OEMs for certified low-emission product lines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated resin-to-laminate producers with established EPA and CE-marked compliance protocols over pure-play decorative surface specialists facing regulatory displacement. Long-term viability across the projection horizon rests on bio-based resin platform maturity and circular economy certification depth. Monitor ECHA substance of very high concern classification timelines for phenol derivatives as the inflection signal for conventional melamine-formaldehyde asset stranding.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | Secures feedstock cost stability and REACH qualification advantages in EU specification channels. |
| Accredited Laboratory Certification Investment | Unlocks EPA TSCA Title VI access for North American hospitality and healthcare furniture OEMs. |
| Digital Print-on-Demand Decorative Paper Partnership | Enables mass customization for boutique hotel brands seeking distinctive surface aesthetics. |
| Capacity Expansion in Gujarat-Punjab Corridor | Captures volume concentration in India's residential and commercial furniture manufacturing cluster. |
| Fire-Rated Formulation R&D Collaboration | Addresses technical limitations in balancing fire resistance with low-emission performance. |
Research Methodology
The analysis maps high-pressure laminate, low-pressure laminate, and decorative laminate sub-sectors, each validated through procurement directors at furniture OEMs, specification nurses in healthcare facilities, and hospitality design consultants. Primary interviews with plant managers at integrated resin producers, distribution channel partners serving educational furniture lines, and technical R&D directors at decorative paper manufacturers combined with secondary validation from EPA enforcement databases, ECHA substance restriction filings, BIS certification records, and customs trade data. Bottom-up volume builds triangulated against top-down macroeconomic indicators ensure consistency across the analysis window.
Outputs were validated against external benchmarks including ACC resin production disclosures, Cefic chemical industry reports, and SEC filings from publicly traded building products manufacturers. The analytical framework models product type, application environment, surface finish tier, and end-user procurement authority across the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by pricing stratification across premium, standard, and economy tiers, incorporating phenol feedstock cost assumptions and regulatory compliance cost pass-through rates specific to furniture laminate manufacturing.
Underlying assumptions cover phenol derivative pricing stability, CARB Phase 2 and EPA TSCA Title VI enforcement continuity, and EU REACH substance restriction timelines, with deviation risk concentrated in bio-based resin performance thresholds and certification reciprocity agreement negotiations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Eco-Friendly Furniture Market
Furniture
United States Luxury Furniture Market
Furniture
Europe High-End Furniture Market
Furniture
Study Carrels Market
Furniture
UK Sustainable Office Furniture Market
Furniture
US Contract Furniture and Furnishing Market
Furniture
Global Folding Furniture Market
Furniture
North America Slide Rails Market
Furniture
Wood Furniture Market
Furniture
Indonesia Furniture Market
Furniture
Entryway Furniture Market
Furniture
Indonesia Home Furniture Market
Furniture
Asia Pacific Multifunctional Furniture Market
Furniture
Chaises Longue Market
Furniture
Canada Secondary Wood Products Market
Furniture
Contract Furniture and Furnishing Market