
 India Commercial Vehicles Lubricants Market | 2026-2036
India Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
India Commercial Vehicles Lubricants Market Foresight
API CK-4 and FA-4 specification upgrades is redrawing competitive benchmarks for heavy-duty engine oils. Castrol leverages its technical service network to sustain fleet relationships across India's Golden Quadrilateral corridor. Indian Oil Corporation anchors volume through its extensive fuel-retail footprint and in-house base oil refining. Gulf Oil International differentiates via specialized mining and construction vehicle lubricant portfolios.
Commercial vehicles lubricants are formulated blends of base oils and performance additives engineered to meet SAE viscosity grades and OEM drain-interval specifications, designed to reduce friction, dissipate heat, and extend component life under high-load operating conditions. Engine oil commands the largest value share given drain-interval frequency and sump capacity requirements across truck and bus fleets. Transmission fluid is gaining structural importance as automated manual transmissions penetrate medium and heavy-duty segments. Gear oil maintains stable demand from axle and differential applications in mining and construction equipment.
BIS mandates lubricant performance labeling under IS 13656 standards, while the Automotive Research Association of India enforces emission-parity testing that shapes additive package formulations. The CEA's fuel efficiency norms indirectly tighten lubricant thermal stability requirements for commercial powertrains. Stakeholders must monitor OEM service-fill approvals and drain-interval extension claims as fleet total-cost-of-ownership calculations evolve.
Market Dynamics
API specification upgrades are compressing product lifecycles and forcing reformulation investments across India's heavy-duty engine oil segment. Fleet operators now demand drain-interval documentation that directly feeds total-cost-of-ownership calculations.
Growth Catalysts
- BIS viscosity certification tightening:The Bureau of Indian Standards' evolving IS 13656 labeling mandates are accelerating premium lubricant adoption as fleets seek documented performance parity.
- Long-haul corridor expansion:Golden Quadrilateral highway upgrades are extending duty cycles and increasing oil change frequency across Maharashtra-Gujarat freight routes.
- Automated manual transmission penetration:Transmission fluid demand is structurally rising as AMT systems capture share in medium and heavy-duty truck segments.
Market Restraints
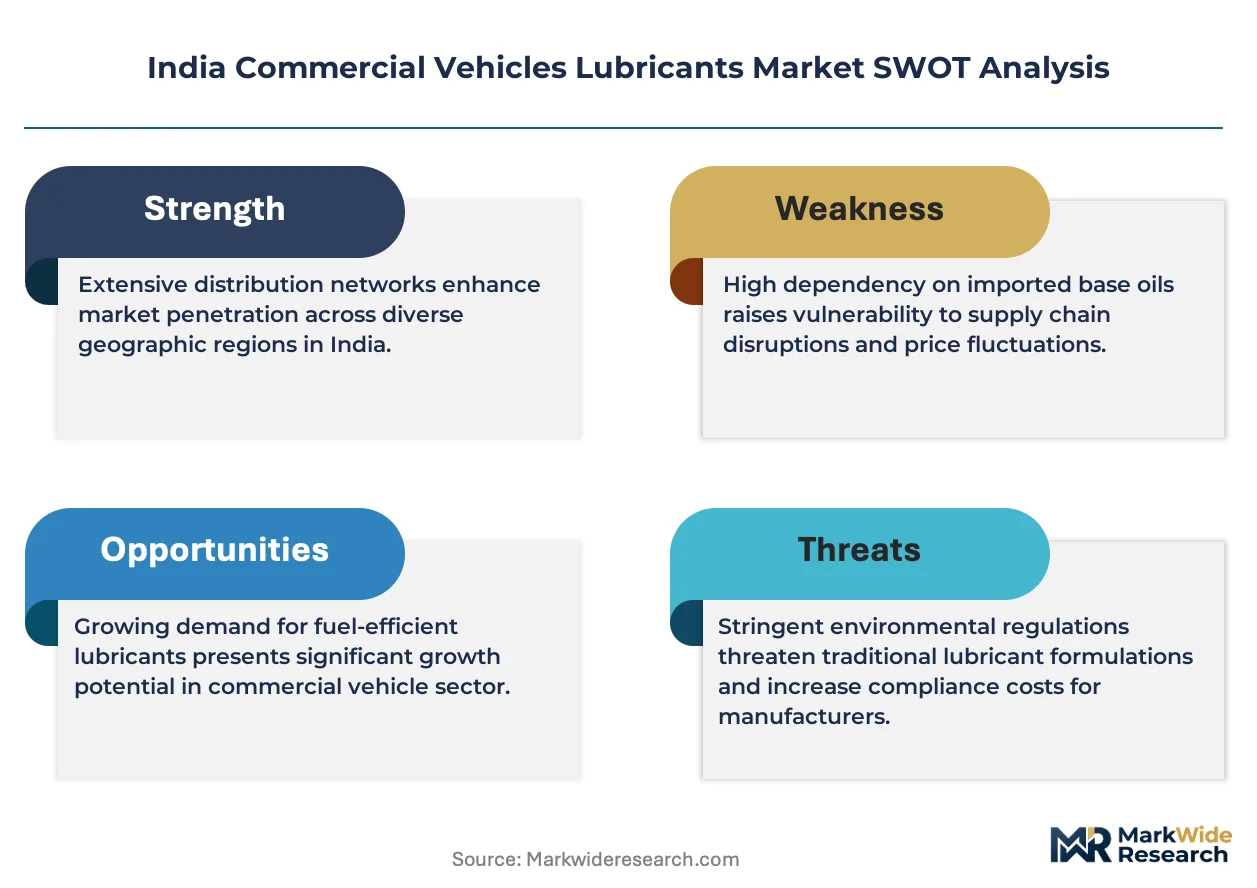
- Group II/III base oil import dependency:India's limited domestic hydrocracker capacity creates exposure to Middle Eastern feedstock pricing volatility.
- Additive package concentration:Four global suppliers control 80 percent of commercial vehicle additive technology, constraining formulation flexibility for domestic blenders.
- Re-refined oil quality perception:Fleet skepticism toward recycled base stocks limits circular economy penetration despite environmental pressure.
Strategic Opportunities
- Mining sector specialization:Odisha and Jharkhand's iron ore belts present underpenetrated demand for high-sulphur ash tolerant lubricants in dump trucks and excavators.
- Electric commercial vehicle pre-positioning:Thermal management fluid development for e-axles and battery packs offers first-mover positioning ahead of Bharat Stage VII implementation.
- Rural last-mile logistics:Three-wheeler and small commercial vehicle lubricant demand is concentrating in tier-3 and tier-4 towns with limited service infrastructure.
Industry Challenges
- OEM approval timeline compression:Accelerated engine platform launches by Ashok Leyland and Tata Motors are shortening lubricant qualification windows.
- Skilled technician scarcity:Diagnostic fluid analysis capability gaps in dealer networks limit predictive maintenance program rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Commercial Vehicles Lubricants Market |
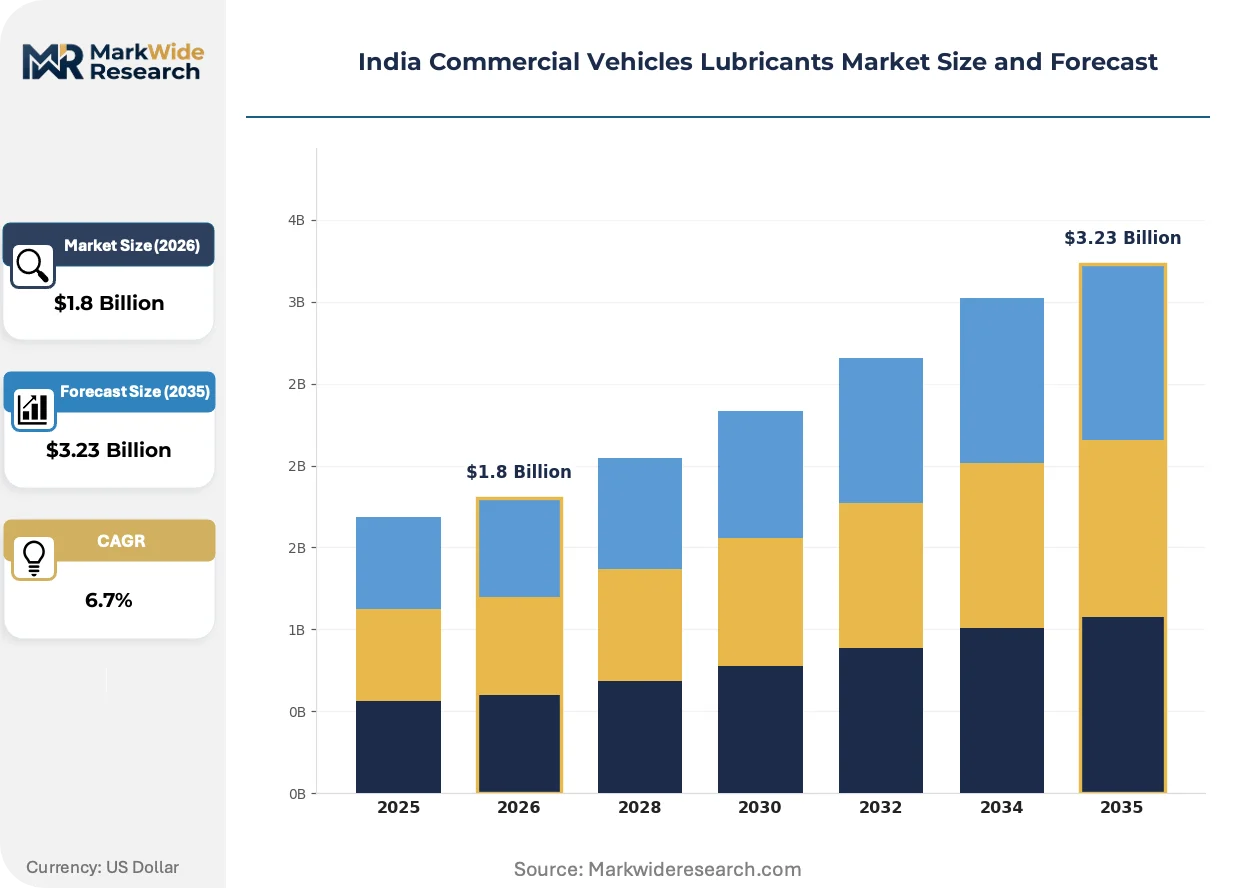
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Gear Oil Application: Trucks, Buses, Vans, Heavy-Duty Vehicles Distribution Channel: Retail, Online, Wholesalers, Service Stations End User: Fleet Operators, Logistics Companies, Individual Owners, Transport Services |
| Companies Covered | BP PLC (Castrol), Royal Dutch Shell Plc, Indian Oil Corporation Limited, TotalEnergies, ExxonMobil Corporation, Bharat Petroleum Corporation Limited, Gulf Oil International, TIDE WATER OIL CO (INDIA) LTD, Hindustan Petroleum Corporation Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Commercial Vehicles Lubricants Market Shifts & Advancements
Reformulation chemistry is pivoting toward lower viscosity grades that preserve hardware protection under higher thermal loads. Three distinct vectors are reshaping competitive positioning in India's commercial vehicle lubricant landscape.
Lower viscosity heavy-duty engine oils are decomposing the traditional trade-off between fuel economy and wear protection. Fleet operators in Gujarat's cement corridor are piloting SAE 5W-30 formulations for long-haul tractors. This viscosity grade compression is decomposing incumbent high-viscosity product margins while demanding additive package investments that domestic blenders struggle to fund.
CEA thermal efficiency norms are indirectly tightening lubricant stability specifications for commercial powertrains. The Central Electricity Authority's fuel consumption benchmarks cascade into engine thermal management requirements. Heavy-duty segment suppliers must now document oxidation resistance under extended drain intervals to maintain OEM service-fill approvals.
Fluid analysis subscriptions are replacing transactional bulk purchases in organized fleet procurement. Large transport operators in Maharashtra's logistics belt now demand real-time wear metal monitoring as a contract condition. This service bundling is most advanced among pharmaceutical cold-chain operators where downtime costs exceed lubricant price differentials by an order of magnitude.
India Commercial Vehicles Lubricants Market Segmentation
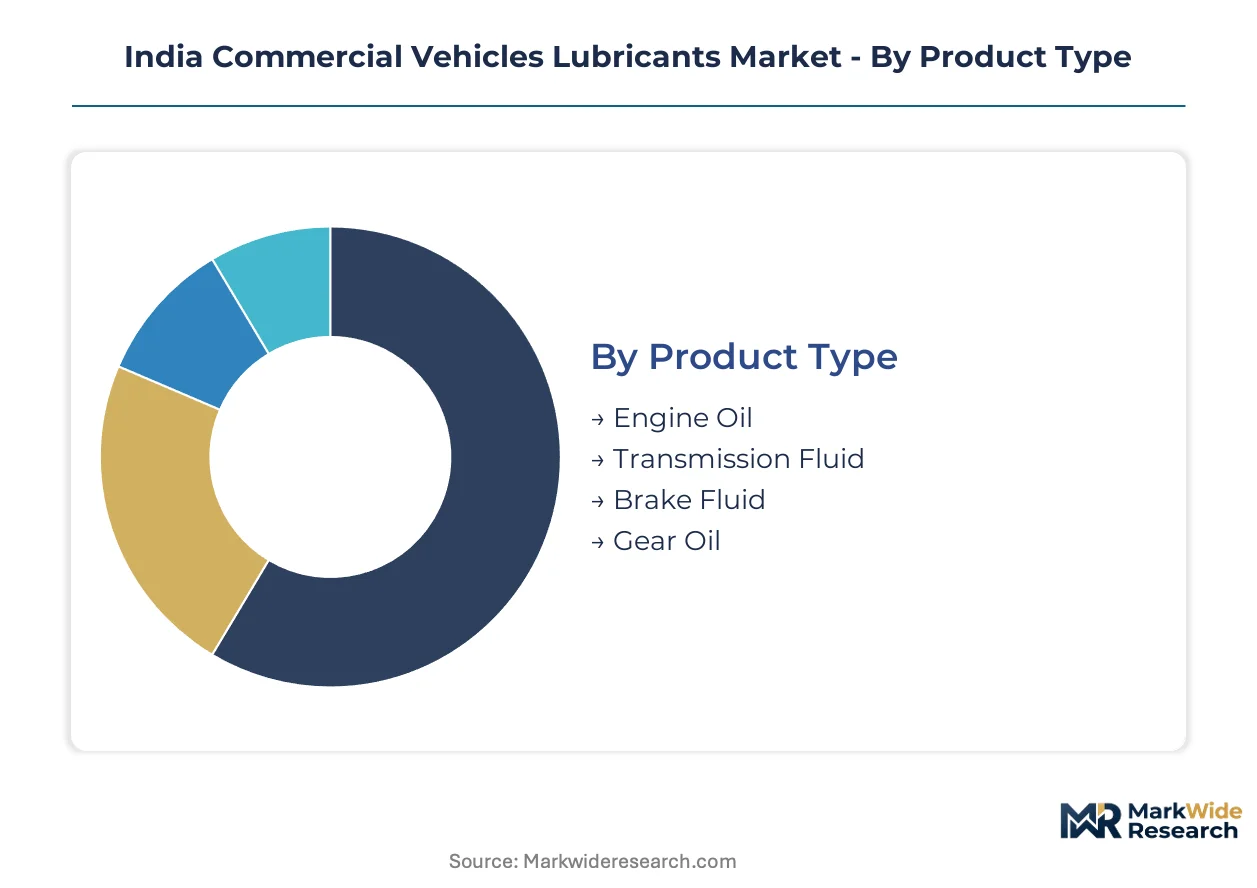
Product specifications in India's commercial vehicle lubricant market diverge sharply between domestic fleet requirements and export-oriented formulations. Segment boundaries are hardening as BIS certification tiers create distinct performance categories that reshape procurement patterns across Maharashtra's logistics corridors and Gujarat's industrial belts.
Product Type:
Domestic consumption dominates engine oil and gear oil categories, while transmission fluid shows emerging export linkages to Southeast Asian markets. Brake fluid demand remains almost entirely captive to India's internal aftermarket.
- Engine Oil:Formulated blends of Group II/III base stocks with detergent-dispersant additive packages meeting API CK-4 and FA-4 specifications. Demand concentrates in long-haul trucking fleets along the Golden Quadrilateral where drain-interval documentation feeds total-cost-of-ownership calculations.
- Transmission Fluid:Synthetic and semi-synthetic formulations engineered for friction stability in automated manual transmissions. Penetration is climbing fastest in medium-duty segments across Pune-Ahmedabad freight routes as AMT adoption accelerates.
- Brake Fluid:Glycol-ether and silicone-based hydraulic fluids meeting DOT 3 and DOT 4 specifications. Replacement cycles tie directly to commercial vehicle inspection schedules mandated by state transport authorities.
- Gear Oil:Extreme-pressure lubricants for axle and differential applications in mining dump trucks and construction excavators. Odisha's iron ore belts generate concentrated demand for high-sulphur ash tolerant formulations.
Engine oil holds the largest share; momentum sits with transmission fluid.
Application:
Volume concentration varies by duty cycle intensity, with heavy-duty vehicles commanding premium formulation margins while vans operate on economy-tier procurement.
- Trucks:Long-haul tractors and rigid cargo vehicles consuming 80% of heavy-duty engine oil volume. Fleet operators in Mumbai's container corridors now mandate real-time fluid analysis subscriptions as contract conditions.
- Buses:Intercity coaches and urban transit fleets with standardized drain intervals tied to state transport corporation maintenance schedules. Thermal stability requirements intensify under CEA fuel efficiency norms.
- Vans:Last-mile delivery vehicles in tier-3 and tier-4 towns with limited service infrastructure. Three-wheeler lubricant demand fragments across unorganized retail channels.
- Heavy-Duty Vehicles:Mining trucks, tippers, and construction equipment operating in high-dust, high-load conditions. Jharkhand's coal belts and Rajasthan's limestone quarries drive specialized high-viscosity demand.
Trucks dominate volume; heavy-duty vehicles claim the steepest expansion trajectory.
Distribution Channel:
Channel selection correlates with fleet scale, with organized operators consolidating procurement through direct wholesaler relationships while individual owners remain tethered to retail.
- Retail:Kirana-format automotive shops and spare parts dealers serving individual truck owners and small fleet operators. Maharashtra's logistics belt surrounding Mumbai and Pune retains dense retail networks despite consolidation pressure.
- Online:B2B procurement platforms and lubricant-aggregator apps penetrating organized fleet segments. Digital channels are expanding most quickly among pharmaceutical cold-chain operators where downtime costs exceed price differentials significantly.
- Wholesalers:Regional distributors supplying bulk volumes to fleet operators and transport contractors. Gujarat's cement corridor relies on wholesaler networks for just-in-time replenishment.
- Service Stations:Indian Oil Corporation and Bharat Petroleum fuel-retail footprints with integrated lubricant dispensing. BIS certification requirements for viscosity grades tighten product specifications available through this channel.
Service stations capture the largest transaction volume; online channels are gaining share fastest.
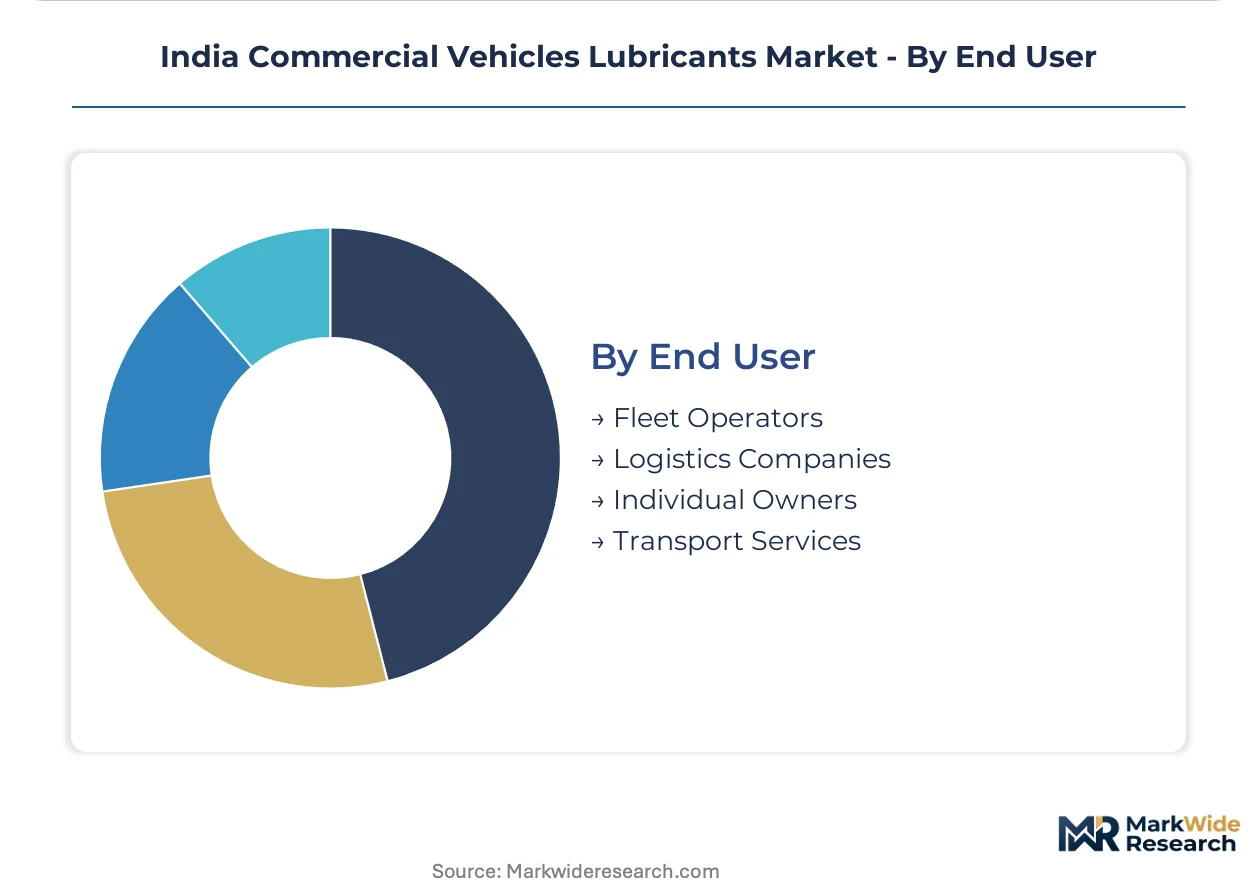
End User:
Procurement sophistication stratifies sharply between organized fleets with technical service requirements and price-sensitive individual operators.
- Fleet Operators:Organized transport companies with 50+ vehicle fleets demanding documented drain-interval performance. Golden Quadrilateral highway upgrades are extending duty cycles and increasing oil change frequency across their networks.
- Logistics Companies:Third-party logistics providers with centralized procurement and predictive maintenance programs. Fluid analysis capability gaps in dealer networks currently limit program rollout.
- Individual Owners:Single-vehicle operators and small contractors prioritizing unit economics over performance documentation. Price sensitivity sustains economy-tier lubricant demand in rural markets.
- Transport Services:State road transport corporations and municipal bus fleets with standardized tender-based procurement. BIS IS 13656 labeling mandates accelerate premium adoption as documented performance parity becomes mandatory.
Fleet operators command the largest value share; logistics companies show the strongest procurement sophistication trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's commercial vehicle lubricant demand tilts toward import-heavy formulations despite domestic blending capacity expansion. Maharashtra and Gujarat absorb disproportionate volume through port-linked logistics infrastructure. Regional specialization follows freight corridor density and mining belt concentration.
Maharashtra
Mumbai-Pune logistics corridors generate concentrated demand for long-haul truck lubricants with documented drain-interval performance. BIS IS 13656 labeling mandates accelerate premium product adoption across fleet procurement contracts. The Jawaharlal Nehru Port hinterland sustains high-throughput service station networks with integrated bulk dispensing.
Gujarat
Cement corridor freight routes extending from Vadodara to Kutch drive heavy-duty engine oil consumption with extended duty cycle requirements. State transport corporation tendering standardizes lubricant specifications for intercity bus fleets. Hazira-Surat industrial clusters anchor wholesale distribution networks serving mining and construction equipment operators.
Karnataka
Bangalore's pharmaceutical cold-chain logistics generate specialized demand for fluid analysis subscriptions and predictive maintenance programs. The state's mining districts in Bellary and Chitradurga concentrate gear oil consumption for iron ore transport tippers. CEA fuel efficiency norms cascade into thermal stability requirements for regional fleet operators.
Odisha
Iron ore mining belts around Keonjhar and Sundargarh present underpenetrated demand for high-sulphur ash tolerant lubricants in dump trucks and excavators. Limited service infrastructure in mineral-rich districts constrains premium product penetration despite load intensity. Domestic blenders face formulation challenges against imported additive packages in this segment.
Tamil Nadu
Chennai's automotive manufacturing ecosystem creates captive demand for OEM service-fill approvals and qualification testing. Sriperumbudur-Ambattur industrial corridors concentrate commercial vehicle assembly and aftermarket service networks. Port-linked container movement to Ennore and Tuticorin sustains long-haul lubricant demand with documented total-cost-of-ownership calculations.
India Commercial Vehicles Lubricants Market Competitive Landscape
Concentration sits with integrated oil majors controlling base oil supply and retail distribution simultaneously. The market structures around three tiers: multinational lubricant specialists with technical service networks, state-owned petroleum corporations leveraging fuel-retail footprints, and domestic blenders competing on price in unorganized channels. Strategic moves center on API specification upgrade timing and fleet contract bundling with fluid analysis services.
Within the multinational tier, BP PLC (Castrol) and Royal Dutch Shell Plc exemplify technical service-intensive positioning across India's Golden Quadrilateral corridor. Indian Oil Corporation Limited anchors volume through captive base oil refining and extensive service station penetration. Gulf Oil International occupies a specialized position in mining and construction segments where high-load formulation requirements differentiate procurement decisions.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| Indian Oil Corporation Limited |
| TotalEnergies |
| ExxonMobil Corporation |
| Bharat Petroleum Corporation Limited |
| Gulf Oil International |
| TIDE WATER OIL CO (INDIA) LTD |
| Hindustan Petroleum Corporation Limited |
| Others |
Supply & Pricing Matrix
BIS IS 13656 certification tiers gate both supplier qualification and price differentiation simultaneously, compressing margins for domestic blenders unable to fund additive package investments while rewarding multinationals with documented OEM approvals. Fleet procurement contracts now bundle fluid analysis subscriptions that decouple lubricant pricing from transactional bulk purchases.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on API certification tier and volume commitment scale, with CK-4 formulations commanding substantial premiums over CJ-4 legacy stocks. Cost compression in the economy tier is intensifying because unorganized retail channels compete on unit price alone. Individual owner-operators in tier-3 towns exhibit highest price sensitivity; pharmaceutical cold-chain fleets show lowest.
Supply Chain Analysis
Container availability constraints on Middle Eastern feedstock routes elevate inbound logistics costs for Group II/III base oil cargoes. Supply concentrates in Saudi Arabia, South Korea, and Singapore, with Indian blenders drawing from these hubs for hydrocracker output. Raw material dependencies span Group II/III base stocks, detergent-dispersant additive packages, and viscosity index improvers. Single-source vulnerability sits with four global additive suppliers controlling formulation technology. Distribution runs through Indian Oil Corporation's fuel-retail footprint alongside regional wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluid analysis subscriptions represent a service-attach opportunity expanding faster than base lubricant volume, as organized fleets demand real-time wear metal monitoring bundled into procurement contracts.
For Market Incumbents: Consolidate technical service networks across the Golden Quadrilateral corridor to defend against emerging digital-native entrants offering predictive maintenance platforms. Deepen backward integration into captive base oil refining to offset Middle Eastern feedstock price volatility. Prioritize API FA-4 qualification investments ahead of Bharat Stage VII implementation.
For New Entrants and Emerging Players: BIS fast-track certification for IS 13656 compliance offers entry into organized fleet procurement previously closed to unapproved suppliers. Odisha's iron ore mining belts present the most penetrable geography, with limited service infrastructure constraining incumbent presence. Lead with specialized high-sulphur ash tolerant formulations for dump truck applications, bypassing direct competition in saturated engine oil segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across additive package formulation capabilities, favoring scaled players with R&D infrastructure. Long-term viability in the five-to-ten year window hinges on electric commercial vehicle thermal management fluid positioning ahead of powertrain electrification. Target domestic blenders with established mining sector relationships and BIS certification infrastructure. Monitor OEM service-fill approval timelines as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| API FA-4 Qualification Investment | Positions suppliers ahead of Bharat Stage VII emission standards tightening thermal stability requirements. |
| Fluid Analysis Platform Development | Captures recurring revenue from pharmaceutical cold-chain operators where downtime costs dominate procurement decisions. |
| Mining Sector Specialization | Odisha and Jharkhand iron ore belts generate premium pricing for high-sulphur ash tolerant formulations. |
| Backward Integration into Base Oil Refining | Reduces exposure to Middle Eastern Group II/III hydrocracker capacity constraints and freight volatility. |
| Electric Vehicle Thermal Management Fluid R&D | First-mover positioning in e-axle and battery pack cooling ahead of commercial EV platform launches. |
Research Methodology
Operator-level perspectives from fleet maintenance managers, Indian Oil Corporation procurement leads, mining equipment operators, and automotive OEM platform engineers anchored the qualitative base. These primary interviews combined with secondary validation from BIS certification registries, Automotive Research Association of India emission test reports, Central Electricity Authority fuel efficiency filings, and customs trade data for base oil imports. Bottom-up volume modeling and top-down market sizing triangulated across these sources.
Sensitivity analysis framed the quantitative approach across the analysis window. Segmentation dimensions modeled include product type, vehicle application class, distribution channel tier, and end-user procurement sophistication. CAGRs derived from trend extrapolation of BIS certification adoption rates, AMT penetration curves, and fleet consolidation patterns. Industry-specific forecast inputs incorporated OEM drain-interval extension claims and Golden Quadrilateral freight volume projections.
Decision-makers should treat outputs as directional under assumptions of continued BIS enforcement tightening and stable Group II/III base oil import flows; material deviation would warrant model refresh. Specific risk factors include abrupt additive supplier consolidation, Bharat Stage VII timeline acceleration, or electric commercial vehicle adoption exceeding powertrain lubricant demand elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Cold Rolling Oils/Lubricants Market
Lubricants
Vietnam Lubricants Market
Lubricants
Canada Lubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Anti-Static Oil Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Argentina Lubricants Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
Open Gear Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
America Lubricants Market
Lubricants
Japan Lubricants Market