
 Spain Commercial Vehicles Lubricants Market | 2026-2036
Spain Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Commercial Vehicles Lubricants Market Analytics
Aftermarket service revenue is tilting toward fluid analysis and condition-based replacement programs rather than fixed-interval changes. Repsol leverages its integrated refining network to secure feedstock cost advantages across Iberian distribution nodes. CEPSA anchors its position through captive supply relationships with major Spanish fleet operators. TotalEnergies competes via specialized heavy-duty engine oil formulations engineered for Euro VI-compliant powertrains.
Commercial vehicles lubricants encompass thermally stable fluid formulations—typically mineral, synthetic, or semi-synthetic base stocks fortified with detergent-dispersant, anti-wear, and viscosity-index improver additive packages—designed to reduce friction, dissipate heat, and suspend combustion byproducts in diesel engines, transmissions, and hydraulic systems operating under severe load cycles. Engine oils command the dominant product category as extended drain intervals and lower-viscosity grades penetrate fleet specifications. Gear oils represent the fastest-expanding segment driven by axle load increases in heavy trucking. Hydraulic fluids maintain steady demand from municipal bus and refuse collection vehicle fleets.
Spain's national implementation of EU REACH chemical registration requirements and the F-Gas Regulation on fluorinated greenhouse gases constrain additive chemistry choices and reformulation timelines for lubricant blenders. The Spanish Ministry for Ecological Transition enforces waste oil recovery quotas that elevate re-refining infrastructure investment. Fleet operators and lubricant suppliers must monitor evolving CO2-based vehicle taxation thresholds and corresponding OEM lubricant specification changes to align procurement with compliance obligations.
Market Dynamics
Spain's Royal Decree on waste oils is compressing reformulation timelines and elevating capital requirements for lubricant blenders, forcing a structural pivot toward re-refined base stocks and circular supply models.
Growth Catalysts
- Fleet electrification readiness programs:Municipal bus operators in Madrid and Barcelona are pre-positioning thermal management fluids for hybrid powertrains, creating pull-through demand for advanced lubricant formulations.
- REACH chemical registration:Spain's national implementation of EU REACH is accelerating additive package standardization, reducing formulation fragmentation and enabling scale economies for compliant blenders.
- Long-haul corridor density:Heavy trucking routes linking the Port of Valencia to Zaragoza and the French border concentrate vehicle-kilometers traveled, anchoring preventive maintenance contract expansion.
Market Restraints
- Group II/III base oil import dependence:Spain lacks domestic hydrocracker capacity for high-quality base stocks, exposing blenders to Rotterdam pricing volatility and euro-dollar hedging costs.
- F-Gas Regulation constraints:The EU F-Gas Regulation on fluorinated greenhouse gases limits certain extreme-pressure additive chemistries used in gear oils, forcing performance trade-offs in high-axle-load applications.
- Re-refining infrastructure gaps:Waste oil collection networks in Galicia and Extremadura remain underdeveloped relative to Madrid and Catalonia, creating geographic supply imbalances for circular feedstocks.
Strategic Opportunities
- Andalusian port logistics expansion:The Algeciras Bay container terminal growth is generating fleet density in southern Spain currently underserved by fluid analysis service networks.
- CO2-based vehicle taxation alignment:Spain's evolving fiscal thresholds for commercial vehicle emissions are creating procurement windows for low-viscosity engine oils that improve fuel economy ratings.
- Condition monitoring convergence:Integration of IoT sensors with lubricant performance data is collapsing the interval between fluid degradation detection and service dispatch, enabling predictive revenue models.
Industry Challenges
- Additive chemist talent scarcity:Spain's technical universities produce fewer lubricant formulation specialists than Germany or France, forcing blenders to recruit from competing industrial sectors.
- Euro VI specification synchronization:OEM lubricant approval timelines for post-2024 engine architectures are compressing, requiring faster certification cycles without compromising thermal stability validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Commercial Vehicles Lubricants Market |
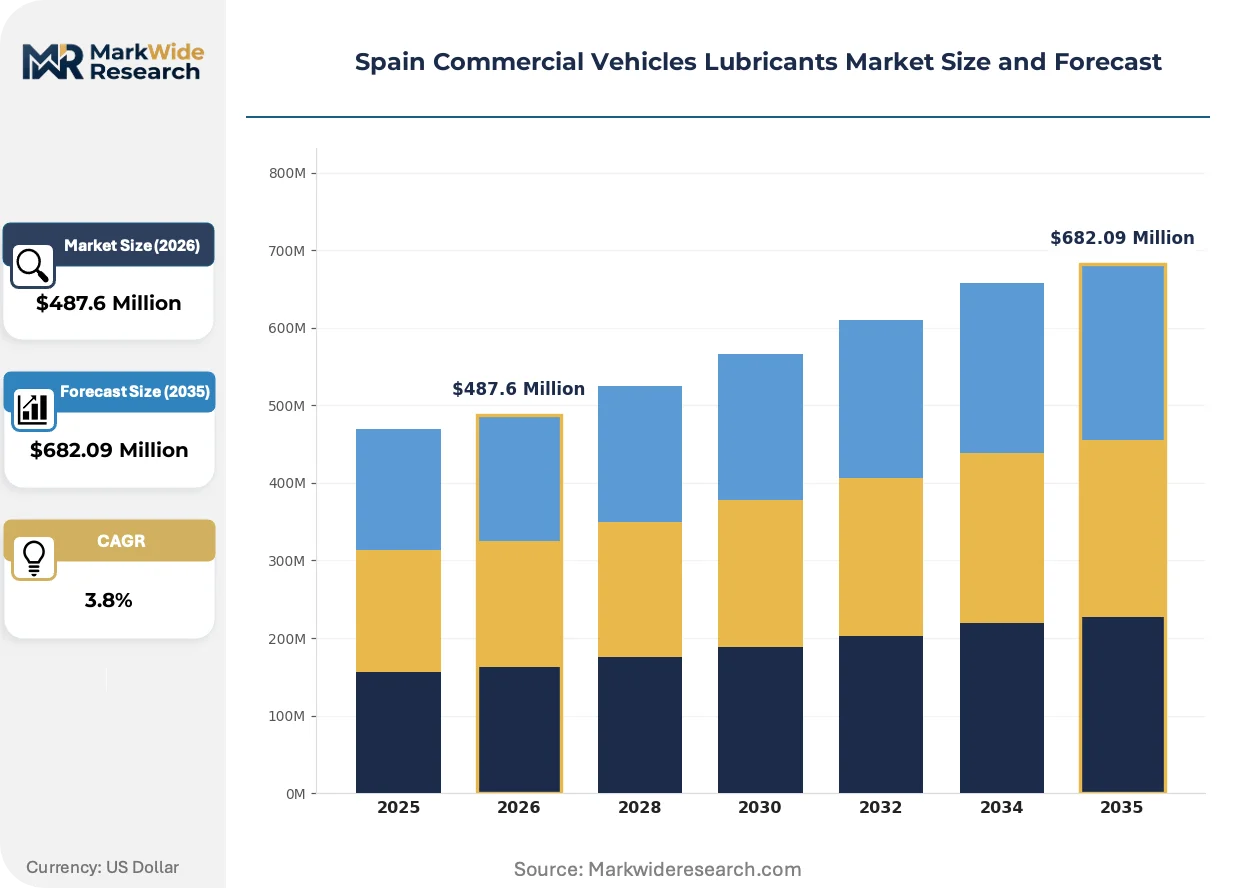
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $682.09 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Gear Oils, Hydraulic Fluids, Greases Vehicle Category: Trucks, Buses, Vans, Light Commercial Vehicles Distribution Channel: Online Retail, Auto Parts Stores, Wholesalers, Service Stations End User: Fleet Operators, Automotive Garages, Transportation Companies, Repair Shops |
| Companies Covered | CEPSA, Repsol, ExxonMobil Corporation, Royal Dutch Shell Plc, TotalEnergies, Castrol, Fuchs, BP, Petronas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Commercial Vehicles Lubricants Market Evolving Landscape
Formulation chemistry and service delivery models are converging around lower-viscosity grades and predictive maintenance platforms, compressing traditional drain intervals and reshaping buyer-supplier relationships.
Low-viscosity 5W-30 and 10W-40 engine oils fortified with advanced polymer technology are collapsing the historical trade-off between fuel economy gains and wear protection durability. Fleet operators operating Euro VI-compliant tractors across the Madrid-Barcelona corridor are adopting these grades at accelerated procurement cycles. The technology is collapsing average drain intervals from 100,000 kilometers toward 150,000 kilometers, compressing lubricant volume demand per vehicle while elevating price-per-liter realization.
Spain's Ministry for Ecological Transition is enforcing waste oil recovery quotas that mandate 85% collection rates from commercial vehicle operators. The industrial consequence is accelerated investment in re-refining capacity at Puertollano and Tarragona. Heavy-duty engine oil blenders are most affected, responding by securing offtake agreements with re-refiners to lock in circular feedstock supply.
Fluid analysis contracts are displacing fixed-interval bulk purchases as the dominant procurement format among mid-size fleet operators. Traditional distributor relationships centered on volume discounts are yielding to technical service partnerships where laboratories certify drain extension eligibility. This behavioral shift is most visible in Catalonia, where refuse collection and urban delivery fleets are unbundling lubricant supply from mechanical service contracts.
Spain Commercial Vehicles Lubricants Market Segmentation
Segmentation in the Spain commercial vehicles lubricants market reveals how procurement behavior diverges across fleet scale, vehicle duty cycles, and channel preferences. Understanding these fault lines enables suppliers to calibrate formulation investment, pricing architecture, and service bundling for distinct buyer clusters.
Product Type:
Cost tier determines margin structure and reformulation frequency across lubricant categories, with premium synthetic grades commanding price multiples over mineral formulations.
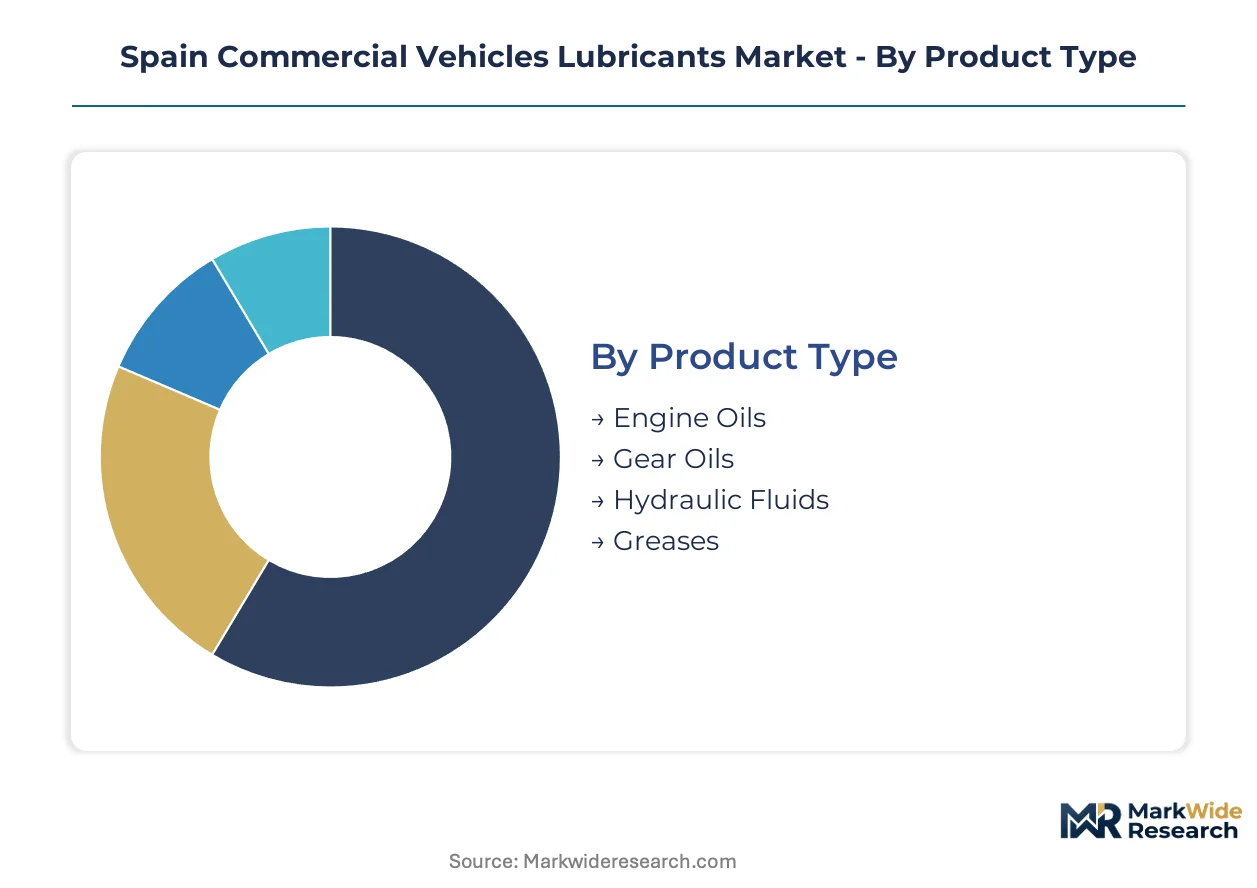
- Engine Oils:Thermally stable formulations—mineral, synthetic, or semi-synthetic base stocks with detergent-dispersant and anti-wear additive packages—reduce friction and suspend combustion byproducts in diesel powertrains. Demand concentrates among long-haul trucking fleets along the Madrid-Barcelona corridor, where extended drain intervals and Euro VI compliance requirements are compressing procurement cycles toward lower-viscosity grades.
- Gear Oils:Extreme-pressure formulations fortified with sulfur-phosphorus additive chemistry protect hypoid gears under elevated axle loads. Heavy trucking operators in the Port of Valencia logistics cluster are expanding preventive maintenance contracts, pulling through advanced formulations as axle weight regulations tighten.
- Hydraulic Fluids:Anti-wear formulations with viscosity index improvers transmit power in municipal bus and refuse collection vehicle systems. Madrid's urban fleet operators anchor steady demand through condition-based replacement programs.
- Greases:Lithium-complex and calcium-sulfonate thickened lubricants seal chassis components and wheel bearings against water ingress and dust contamination. Regional distributors in Andalusia report growing specification complexity as mixed fleet operators consolidate SKU portfolios.
Engine oils hold installed capacity. Gear oils is rotating up the share rankings.
Vehicle Category:
Application severity and annual mileage create divergent lubricant consumption profiles across vehicle classes.
- Trucks:Heavy-duty tractors and rigid trucks operating above 16 tonnes gross vehicle weight consume the highest lubricant volumes per unit, with engine oils representing the dominant cost category. Long-haul operators traversing the Zaragoza-Valencia-French border triangle are adopting 150,000-kilometer drain intervals, compressing volume-per-vehicle while elevating technical service requirements.
- Buses:Urban and intercity coaches with frequent stop-start cycles generate accelerated oil degradation from soot loading and thermal stress. Municipal operators in Barcelona are pre-positioning thermal management fluids for hybrid powertrain transitions, creating formulation pull-through demand.
- Vans:Light commercial vehicles below 3.5 tonnes operate on shorter duty cycles with lower per-unit lubricant consumption. Independent repair shops in Catalonia report growing price sensitivity as fleet operators unbundle lubricant supply from mechanical service contracts.
- Light Commercial Vehicles:Pickups and small vans serving last-mile delivery and construction trades exhibit fragmented procurement patterns. Regional distributors in Galicia note underdeveloped waste oil collection networks relative to Madrid and Catalonia, constraining circular feedstock access.
Trucks dominate volume throughput. Buses is climbing the fastest on reformulation intensity.
Distribution Channel:
Channel configuration determines service bundling economics and customer acquisition cost structures for lubricant suppliers.
- Online Retail:Digital platforms serving small fleet operators and independent mechanics offer price transparency and SKU breadth without technical consultation. The channel is gaining share fastest among van and light commercial vehicle segments where specification complexity remains limited.
- Auto Parts Stores:Regional chains and independent retailers provide same-day availability for standard formulations. Extremadura and rural Castile-La Mancha depend heavily on this channel due to sparse service station density.
- Wholesalers:Bulk distributors supply fleet operators with tankwagon delivery and inventory management services. The Madrid industrial corridor anchors concentration, with lubricant blenders securing captive supply relationships through technical service partnerships.
- Service Stations:Integrated fuel-lubricant retail points along major trucking routes offer convenience but limited formulation specialization. The Algeciras Bay logistics expansion is generating fleet density in southern Spain currently underserved by fluid analysis networks.
Wholesalers hold installed capacity. Online retail is rotating up the share rankings.
End User:
Customer type dictates procurement sophistication, contract structure, and price elasticity in lubricant purchasing decisions.
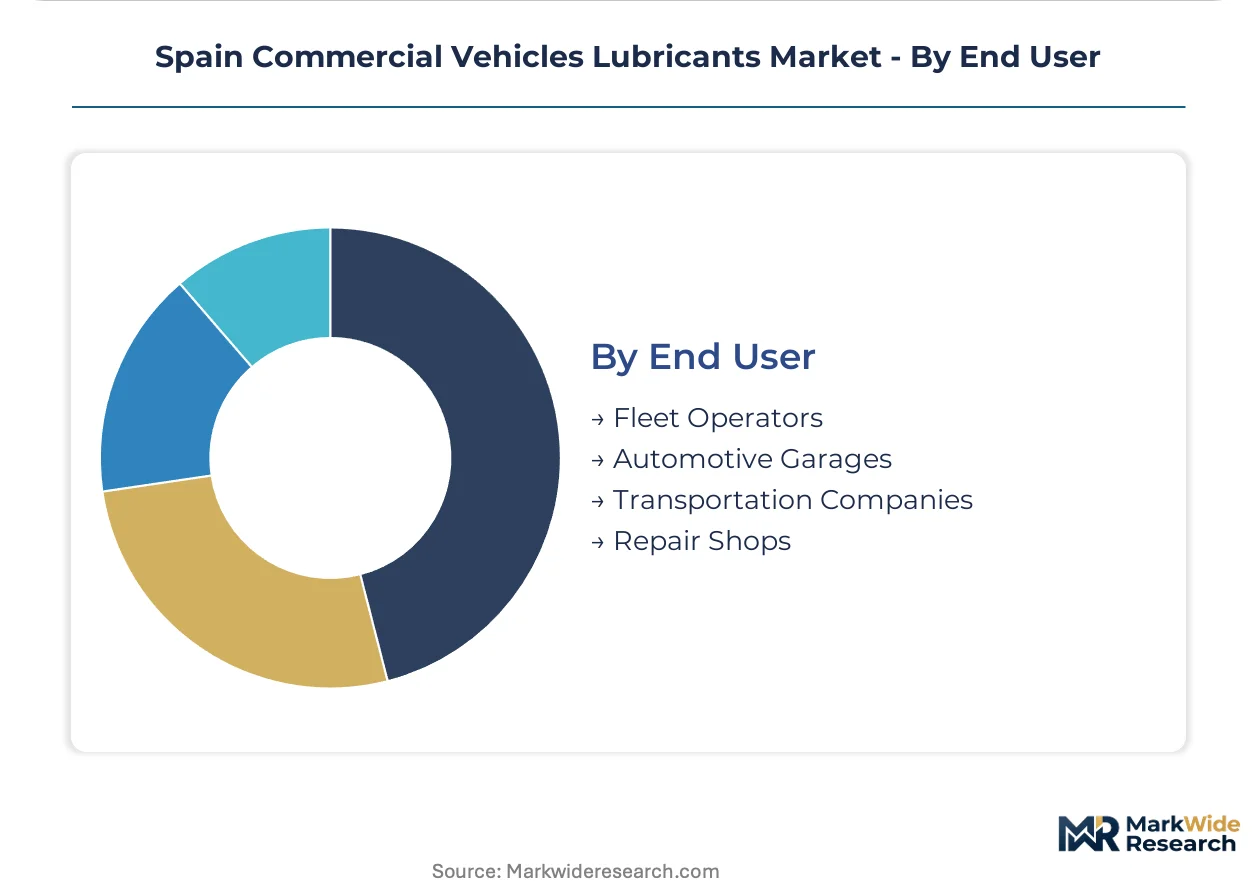
- Fleet Operators:Large-scale commercial vehicle owners operating 50+ units negotiate preventive maintenance contracts with fluid analysis provisions. Repsol and CEPSA anchor positions through integrated refining and captive supply relationships with major Spanish fleet operators.
- Automotive Garages:Independent and franchised repair facilities serve mixed vehicle populations with variable specification requirements. Catalonia's refuse collection and urban delivery fleets are unbundling lubricant supply from mechanical service contracts, shifting procurement toward technical certification models.
- Transportation Companies:Logistics and passenger transport firms with in-house maintenance capabilities balance cost control against OEM warranty compliance. TotalEnergies competes via specialized heavy-duty engine oil formulations engineered for Euro VI-compliant powertrains.
- Repair Shops:Small-scale mechanics serving owner-operators and micro-fleets exhibit high price sensitivity and limited brand loyalty. The segment concentrates in urban peripheries where waste oil recovery quotas under Spain's Royal Decree create compliance cost pressures.
Fleet operators hold installed capacity. Automotive garages is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity in lubricant procurement varies sharply across Spain's industrial geography. Fleet operators in Madrid and Barcelona absorb premium formulations for extended drain intervals, while independent garages in Extremadura and rural Castile-La Mancha prioritize cost minimization over technical service bundling.
Madrid
Heavy-duty trucking fleets along the A-1 and A-2 corridors generate concentrated demand for low-viscosity engine oils. Spain's Ministry for Ecological Transition enforces waste oil recovery quotas that mandate 85% collection rates from commercial operators. The Madrid industrial corridor anchors re-refining infrastructure investment, with blenders securing captive supply relationships through technical service partnerships.
Catalonia
Municipal bus operators in Barcelona are pre-positioning thermal management fluids for hybrid powertrain transitions. The EU F-Gas Regulation constrains extreme-pressure additive chemistries used in gear oils, forcing performance trade-offs in high-axle-load applications. Refuse collection and urban delivery fleets in the Barcelona metropolitan area are unbundling lubricant supply from mechanical service contracts.
Valencia
Port logistics clusters linking Valencia to Zaragoza concentrate vehicle-kilometers traveled and anchor preventive maintenance contract expansion. Spain's Royal Decree on waste oils compresses reformulation timelines for lubricant blenders serving this corridor. Heavy trucking routes to the French border generate pull-through demand for advanced gear oil formulations as axle weight regulations tighten.
Andalusia
The Algeciras Bay container terminal growth is generating fleet density in southern Spain currently underserved by fluid analysis service networks. REACH chemical registration requirements accelerate additive package standardization, reducing formulation fragmentation for compliant blenders. Regional distributors report growing specification complexity as mixed fleet operators consolidate SKU portfolios.
Basque Country
Industrial machinery and automotive component manufacturing anchor steady hydraulic fluid demand from municipal and commercial fleets. Re-refining infrastructure gaps in northern Spain relative to Madrid and Catalonia create geographic supply imbalances for circular feedstocks. Bilbao's port logistics activity is expanding service station density along trucking routes to the French border.
Spain Commercial Vehicles Lubricants Market Competitive Landscape
Capability concentration sits with integrated refiners commanding feedstock cost advantages; scale advantage sits with multinational blenders distributing standardized formulations across Iberian nodes. The market structures around three tiers: captive supply relationships with major fleet operators, technical service partnerships with mid-size distributors, and price-competitive bulk sales to independent garages. Strategic moves center on securing re-refined base stock offtake agreements and collapsing fluid analysis intervals through IoT-enabled condition monitoring.
Within the integrated refiner tier, Repsol and CEPSA exemplify backward integration into captive feedstock supply, while TotalEnergies occupies a position as a formulation specialist competing through Euro VI-compliant powertrain expertise. These three companies anchor the competitive landscape by representing distinct archetypes: Repsol demonstrates Iberian distribution node control, CEPSA illustrates fleet operator captive relationships, and TotalEnergies embodies OEM specification alignment.
| Leading Market Players |
|---|
| CEPSA |
| Repsol |
| ExxonMobil Corporation |
| Royal Dutch Shell Plc |
| TotalEnergies |
| Castrol |
| Fuchs |
| BP |
| Petronas |
| Others |
Value Network & Pricing Analysis
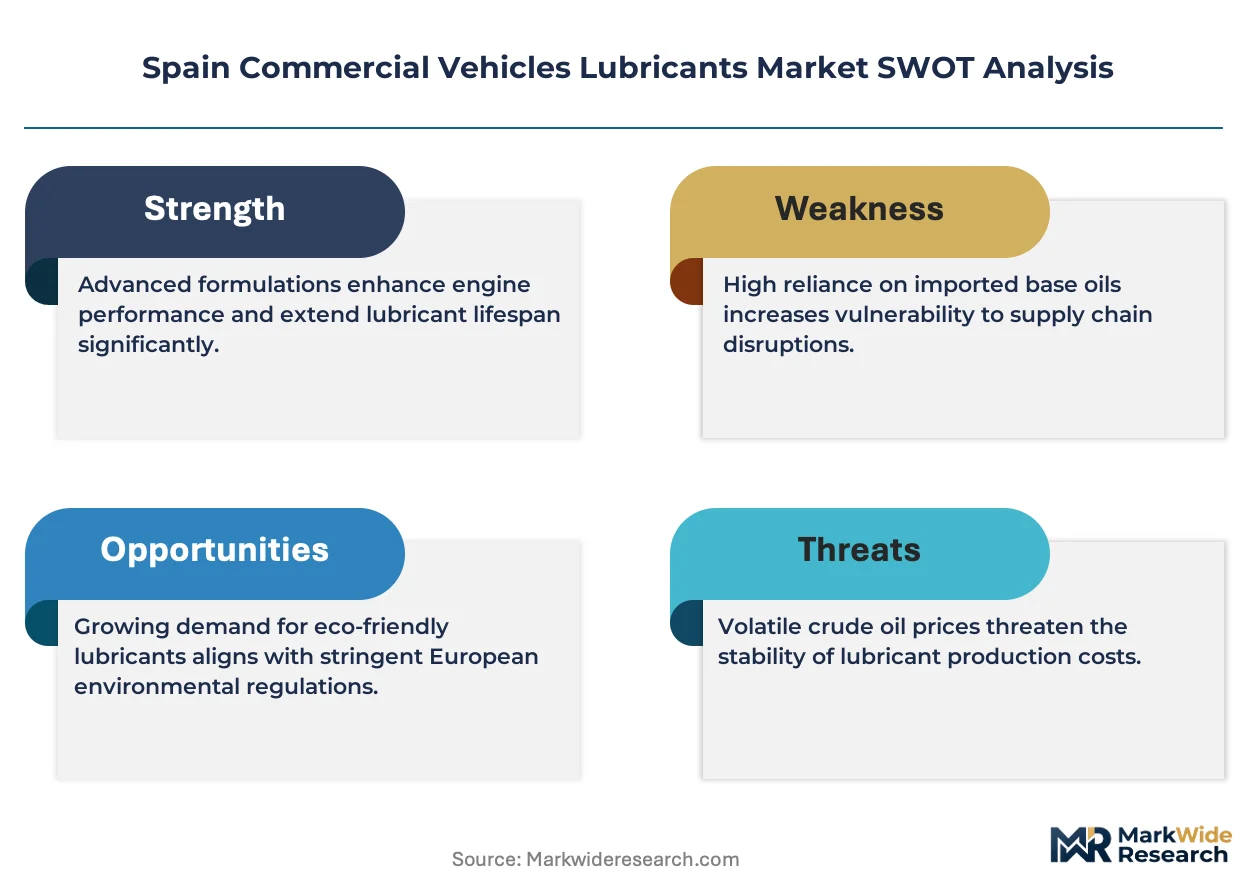
Undercapacity in Spanish hydrocracker facilities for Group II/III base oil production compresses blender margins while elevating Rotterdam import exposure, forcing suppliers to absorb euro-dollar volatility or pass through cost increments to fleet operators locked in long-term preventive maintenance contracts.
Pricing Analysis
After-sales fluid analysis and condition-based replacement programs generate higher lifetime value than transactional bulk sales. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral grades separates Repsol and CEPSA's captive fleet relationships from price-competitive independent garage segments. Cost compression in economy tiers intensifies because Galicia and Extremadura waste oil collection underdevelopment elevates compliance overhead. Independent repair shops exhibit highest price sensitivity; integrated fleet operators absorb premium formulations for extended drain intervals.
Supply Chain Analysis
Extended payment terms from Rotterdam base oil traders strain working capital for Spanish blenders lacking integrated refining capacity. Geographic supply concentrates in the Netherlands, Belgium, and Germany for Group II/III base stocks; additive packages draw from Germany, France, and the United States. Single-source vulnerability runs through Rotterdam-Antwerp corridor logistics chokepoints. Distribution runs through Madrid-Barcelona wholesaler networks with tankwagon delivery, while southern Spain remains underserved by fluid analysis infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's commercial vehicles lubricants market functions as a service-attach opportunity where fluid analysis and predictive maintenance contracts expand faster than commodity lubricant volume. Condition monitoring convergence collapses detection-to-service intervals, elevating recurring-revenue quality.
For Market Incumbents: Build captive feedstock moats through re-refining offtake agreements at Puertollano and Tarragona. Secure additive package standardization advantages under REACH implementation to outpace formulation-fragmented competitors. Defend against TotalEnergies' Euro VI specification expertise by accelerating OEM certification timelines for post-2024 engine architectures. For New Entrants and Emerging Players: Establish a beachhead in Andalusian port logistics where Algeciras Bay fleet density lacks fluid analysis service networks. Target municipal bus operators in Barcelona pre-positioning thermal management fluids for hybrid transitions. Penetrate through IoT-enabled condition monitoring partnerships rather than price-competitive bulk supply. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mid-size fleet operators unbundling lubricant supply from mechanical service contracts in Catalonia. Long-term viability centers on re-refining infrastructure control and circular feedstock access. Acquisition target archetype: regional distributors with laboratory certification capabilities in underserved southern provinces. Watch for inflection when CO2-based vehicle taxation thresholds accelerate low-viscosity procurement windows.| Strategic Initiative | Industry Significance |
|---|---|
| Re-refining Capacity Expansion | Puertollano and Tarragona investments lock in circular feedstock supply under Spain's Royal Decree quotas. |
| Fluid Analysis Service Network Buildout | Andalusian port logistics expansion addresses fleet density currently underserved by condition monitoring infrastructure. |
| Low-Viscosity Formulation Certification | Euro VI-compliant 5W-30 and 10W-40 grades capture CO2 taxation alignment procurement windows. |
| Hybrid Powertrain Fluid Development | Barcelona municipal bus thermal management positioning creates pull-through demand ahead of electrification transitions. |
| Waste Oil Collection Network Extension | Galicia and Extremadura infrastructure closes geographic supply imbalances for circular feedstock access. |
Research Methodology
Cross-validation between primary interviews with lubricant blenders, fleet procurement managers, and aftermarket service directors and secondary sources including customs trade data, Spanish Ministry for Ecological Transition regulatory filings, and SEC disclosures from multinational suppliers anchors the qualitative findings. Bottom-up triangulation across product type, vehicle category, and distribution channel dimensions integrates with top-down macroeconomic calibration.
Calibration against historical volume trends and elasticity assumptions across the projection horizon ensures robustness. Segmentation dimensions modeled include product grade tier, fleet scale archetype, channel configuration, and regional industrial corridor density. CAGRs derive from slope analysis of installed base turnover, drain interval extension rates, and re-refining capacity buildout trajectories. Forecast inputs incorporate REACH compliance cost pass-through assumptions and euro-dollar exchange rate sensitivity bands.
Stress conditions across Rotterdam base oil pricing volatility, REACH additive reformulation timelines, and CO2 taxation threshold adjustments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding fleet electrification readiness pacing and re-refining infrastructure completion. Macroeconomic contraction, regulatory acceleration beyond EU REACH and F-Gas Regulation baselines, or disruptive battery-electric commercial vehicle adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Brazil Lubricants Market
Lubricants
Poland Metalworking Fluids Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Polyurea-Based Greases Market
Lubricants
South America Lubricants Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
Europe Grease Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
Slideway Oil Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
Marine Lubricants Market