
 Textile Machine Lubricants Market | 2026-2036
Textile Machine Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Textile Machine Lubricants Market Outlook
ISO 6743-99 classification for lubricants used in textile machinery is redrawing competitive entry barriers across the supply base. ExxonMobil leverages its integrated base oil network to secure consistent feedstock access for high-viscosity grades. Klüber Lubrication differentiates through application-specific formulations engineered for synthetic fiber spinning lines. FUCHS Lubricants anchors its position with technical service teams embedded inside major European textile clusters.
Textile machine lubricants are formulated lubricating fluids designed to reduce friction, dissipate heat, and prevent corrosion in high-speed spinning frames, looms, and knitting equipment operating at temperatures up to 150°C and speeds exceeding 25,000 rpm. These fluids typically comprise Group II or Group III base stocks fortified with anti-wear, anti-oxidant, and demulsifier additive packages to maintain performance under continuous cyclic loading. Synthetic oils command premium positioning due to extended drain intervals and thermal stability demands from modern texturing machines. Bio-based lubricants represent the fastest-expanding product category as mills face Scope 3 emissions accounting pressure from apparel brand customers. Finishing applications concentrate margin pools because lubricant residues must meet downstream dyeing compatibility standards.
EPA registration requirements under the Toxic Substances Control Act constrain lubricant additive chemistry choices for suppliers serving United States textile mills. REACH substance restrictions and the EU Green Deal's chemical sustainability targets are accelerating reformulation timelines across European formulation houses. India's BIS certification mandates for imported lubricants create compliance gateways for multinational suppliers entering the domestic market. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
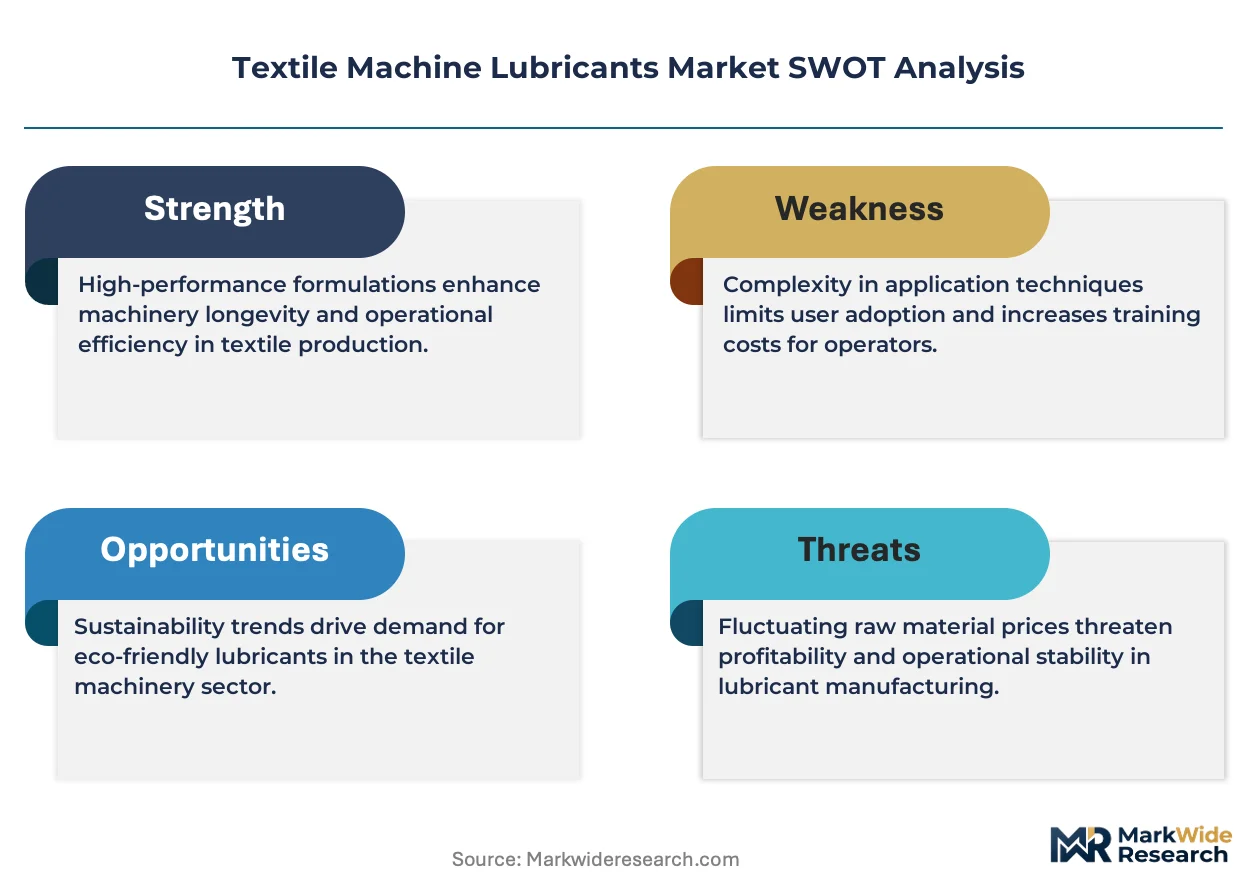
ISO 6743-99 classification requirements are compressing formulation flexibility while accelerating R&D spend among mid-tier suppliers unable to absorb compliance costs through captive base oil production.
Growth Catalysts
- PLI scheme expansion:India's production-linked incentive program for textiles is commissioning new spinning capacity requiring synthetic lubricant volumes. Domestic mills in Gujarat and Tamil Nadu are specifying high-viscosity grades for imported texturing equipment.
- REACH substance restrictions:ECHA's tightening limits on zinc-based anti-wear additives are forcing reformulation toward ashless chemistry. European formulation houses with pre-approved alternative packages are capturing specification upgrades.
- Synthetic fiber spinning speeds:Machinery operating above 25,000 rpm generates thermal loads that mineral oils cannot manage. Nonwoven producers in hygiene applications are mandating polyalphaolefin base stocks to extend drain intervals.
Market Restraints
- Group III base oil supply concentration:Asian refiners control over 60% of high-viscosity Group III capacity. European blenders face feedstock vulnerability when regional cracking margins tighten.
- EPA TSCA registration timelines:New additive chemistry requires 18-24 month pre-manufacture notification review. Suppliers serving US textile mills cannot match European speed-to-market for novel anti-oxidant packages.
- Bio-based ester cost premium:Vegetable oil feedstocks trade at 2-3x paraffinic base oil levels. Mills under apparel brand Scope 3 pressure absorb margin compression or pass costs to undifferentiated commodity yarn.
Strategic Opportunities
- Vietnam textile cluster expansion:FDI-driven fabric and garment capacity is outpacing domestic lubricant blending infrastructure. Multinational suppliers can establish technical service presence ahead of local competitor maturation.
- EU Green Deal chemical sustainability targets:Carbon footprint disclosure requirements for textile inputs create preference for lubricants with certified lifecycle data. Early movers in environmental product declarations capture specification lock-in.
- Digital oil condition monitoring:IoT sensor integration with spinning frames enables predictive drain interval optimization. Lubricant suppliers bundling analytics with fluid supply convert transactional buyers to contracted service relationships.
Industry Challenges
- Tribology specialist scarcity:Formulation chemists with textile machinery friction-wear expertise are concentrated at legacy European and Japanese suppliers. Mid-tier blenders struggle to staff application engineering roles.
- Legacy equipment compatibility:Decades-old looms in South Asian mills operate with mineral oil systems. Synthetic fluid conversion requires seal material upgrades and reservoir cleaning protocols that disrupt production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Textile Machine Lubricants Market |
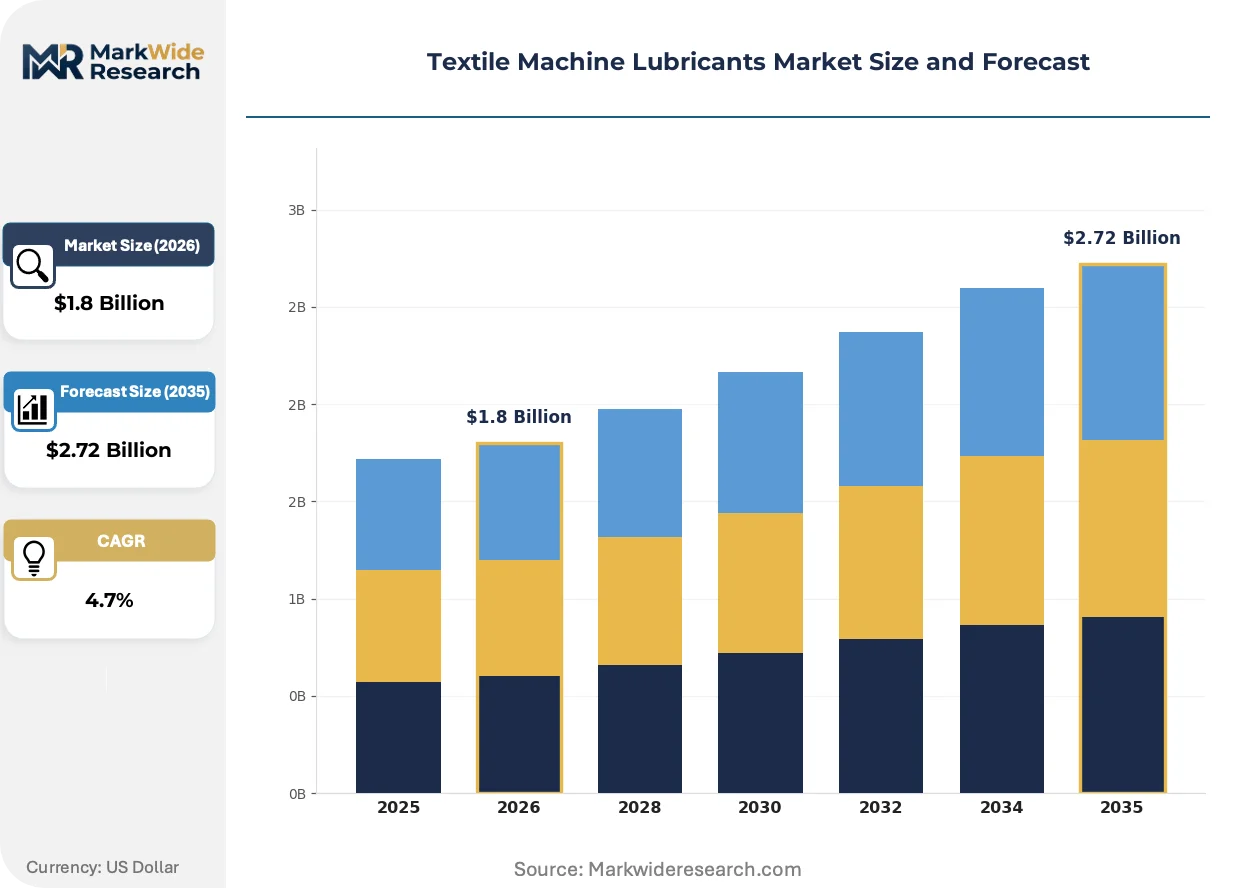
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oils, Mineral Oils, Bio-based Lubricants, Additives Application: Spinning, Weaving, Knitting, Finishing End User: Textile Manufacturers, Apparel Producers, Carpet Mills, Nonwoven Fabric Producers Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores |
| Companies Covered | ExxonMobil, TotalEnergies, Chevron Corporation, Klüber Lubrication, FUCHS Lubricants, Shell Lubricants, BP, Sinopec, Nye Lubricants, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Textile Machine Lubricants Market Strategic Shifts
Reformulation timelines are compressing as regulatory windows narrow and machinery OEMs release lubricant specifications tied to warranty coverage. Suppliers must now validate chemistry across multiple jurisdictions simultaneously.
Soluble polyalkylene glycol base stocks are decomposing the traditional mineral-synthetic binary in textile applications. High-speed texturing machine OEMs in Germany and Japan are specifying PAG fluids for their inherent deposit control and water-miscibility for simplified cleanup. The technology is decomposing aftermarket mineral oil refill cycles by enabling 8,000-hour drain intervals that compress maintenance labor costs.
REACH Annex XIV authorization requirements for medium-chain chlorinated paraffins are eliminating historical extreme-pressure additives from European textile lubricant formulations. Blenders are pivoting to sulfur-phosphorus chemistry or ionic liquid alternatives with equivalent film strength. Synthetic fiber spinning lines in Belgium and Italy are most affected, with mills demanding reformulation certificates before contract renewal.
Consolidated procurement through textile machinery OEMs is displacing mill-direct lubricant purchasing in premium equipment segments. End-users buying complete spinning frames or texturing lines now accept factory-fill and service-fluid packages bundled into equipment financing. This channel compression is most visible in India, where Reliance-backed machinery distributors and European OEM sales subsidiaries are capturing lubricant specification authority from independent mill procurement departments.
Textile Machine Lubricants Market Segmentation
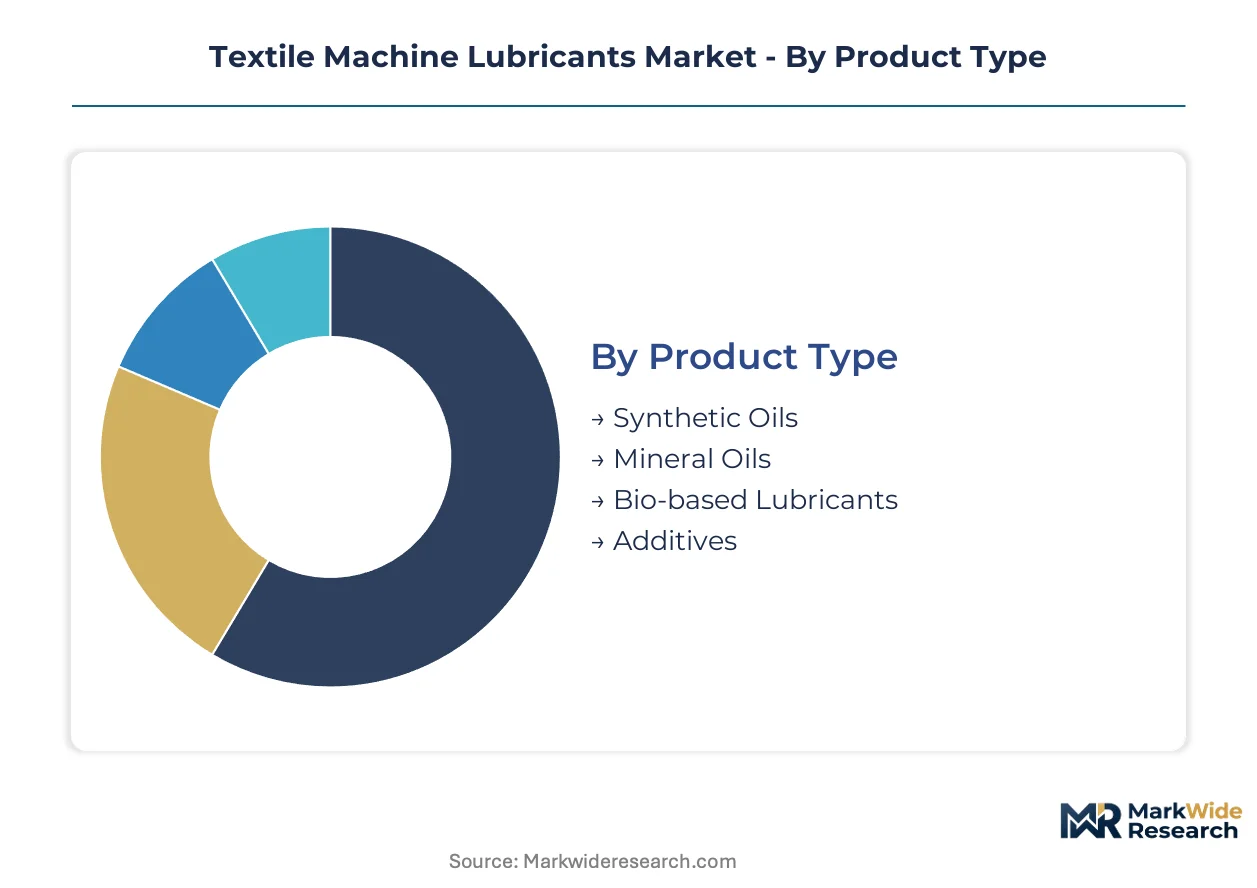
Segmentation in textile machine lubricants reveals how formulation chemistry, machinery type, and procurement channel each impose distinct margin structures and compliance burdens. Suppliers must align R&D investment and distribution footprint against the specific performance thresholds and regulatory exposure of each slice.
Product Type:
REACH substance restrictions and EPA TSCA registration timelines create divergent compliance economics across base stock categories, compressing margins for mineral oil blenders while rewarding synthetic specialists with pre-approved additive packages.
- Synthetic Oils:Polyalphaolefin and ester-based formulations deliver thermal stability above 150°C for texturing machines exceeding 25,000 rpm. Nonwoven fabric producers in hygiene applications specify these grades to extend drain intervals beyond 8,000 hours.
- Mineral Oils:Group II and Group III paraffinic base stocks dominate legacy spinning frames and looms. South Asian mills operating decades-old equipment absorb these fluids for compatibility with existing seal materials and reservoir designs.
- Bio-based Lubricants:Vegetable oil esters and synthetic esters from renewable feedstocks address Scope 3 emissions accounting pressure from apparel brand customers.
- Additives:Ashless anti-wear packages, demulsifiers, and anti-oxidant systems are reformulating rapidly as zinc-based chemistry faces ECHA authorization limits.
Established volume favors mineral oils; emerging adoption favors bio-based lubricants.
Application:
Cost tier differentiation separates premium formulations for high-speed synthetic fiber production from commodity lubricants serving conventional cotton processing.
- Spinning:Ring spinning and open-end rotor systems require viscosity grades between ISO VG 32 and 68 with anti-wear protection for spindle bearings. India's PLI scheme expansion is commissioning imported texturing equipment in Gujarat and Tamil Nadu that specifies synthetic polyalphaolefin fills.
- Weaving:Loom lubrication emphasizes clean-break properties to prevent fabric staining. Water-miscible polyalkylene glycol fluids are displacing mineral oils in high-speed air-jet looms for simplified cleanup and deposit control.
- Knitting:Needle and sinker lubrication demands low-viscosity oils with exceptional oxidation stability for continuous operation. Finishing applications concentrate margin pools because lubricant residues must meet downstream dyeing compatibility standards.
- Finishing:Calendering and heat-setting equipment operates at the highest thermal loads, requiring synthetic formulations with superior thermal conductivity and minimal varnish formation.
Margin concentration sits with finishing; volume expansion centers on spinning.
End User:
Customer type determines specification authority, with machinery OEMs increasingly capturing lubricant procurement decisions through bundled service contracts.
- Textile Manufacturers:Integrated spinning-weaving-knitting operations represent the largest lubricant volume consumers. These facilities specify fluids across multiple machinery platforms, creating demand for product rationalization and consolidated supply agreements.
- Apparel Producers:Brand-owned sustainability mandates are cascading Scope 3 emissions requirements to lubricant suppliers. Mills serving Nike, Inditex, and H&M groups now demand certified lifecycle data and bio-based content verification.
- Carpet Mills:Tufting and backing equipment operates at moderate speeds with heavy grease requirements for needle bar mechanisms.
- Nonwoven Fabric Producers:Spunbond and meltblown lines for hygiene and medical applications run at extreme speeds, mandating synthetic formulations with extended drain intervals.
Procurement consolidation favors textile manufacturers; sustainability pressure intensity favors apparel producers.
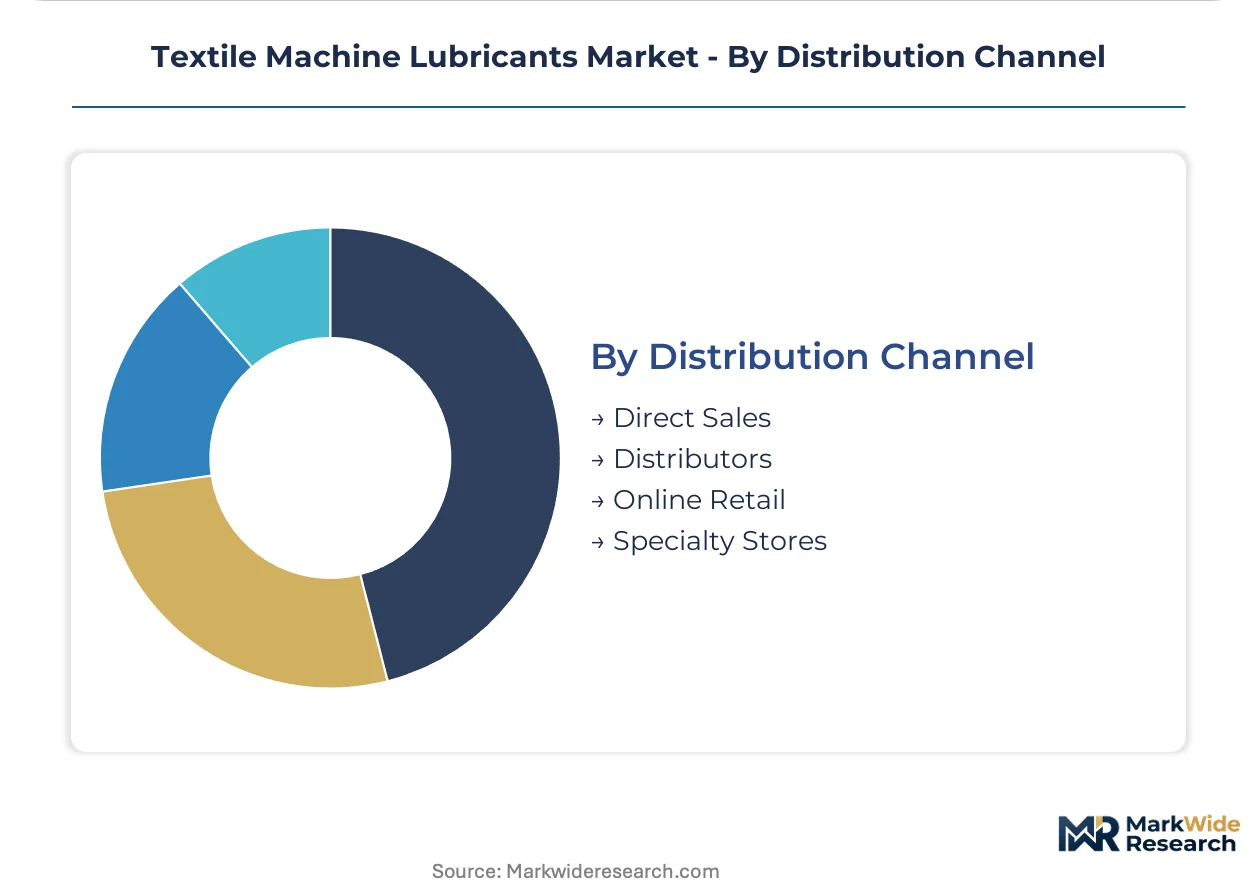
Distribution Channel:
Supply concentration in base oil refining shapes channel economics, with direct sales rewarding integrated suppliers and distributors serving fragmented mill bases.
- Direct Sales:Multinational lubricant suppliers deploy technical service teams embedded inside major European textile clusters and Indian manufacturing belts. These relationships convert transactional fluid supply into contracted performance agreements with predictive maintenance bundling.
- Distributors:Regional blending and warehousing networks serve mid-tier mills without volume justification for direct supplier engagement. Vietnamese textile clusters currently outpace domestic lubricant blending infrastructure, creating distributor expansion opportunities.
- Online Retail:Small maintenance volumes and emergency replenishment for auxiliary equipment migrate to digital procurement platforms.
- Specialty Stores:Local lubricant retailers serve legacy equipment operators in South Asian secondary markets with mineral oil grades and basic additive packages.
Service intensity favors direct sales; geographic coverage favors distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for textiles is commissioning new spinning capacity across Gujarat and Tamil Nadu, drawing synthetic lubricant volumes from multinational suppliers. Germany's REACH enforcement tightens additive chemistry standards. China's dual carbon goals pressure mills toward bio-based formulations.
India
Domestic manufacturing capacity expansion under the PLI scheme drives synthetic lubricant demand for imported texturing equipment. BIS certification mandates for imported lubricants create compliance gateways for multinational suppliers entering the market. Textile clusters in Gujarat and Tamil Nadu specify high-viscosity grades for new spinning capacity.
Germany
High-speed texturing machine OEMs specify polyalkylene glycol fluids for deposit control and extended drain intervals. ECHA's REACH Annex XIV authorization requirements for medium-chain chlorinated paraffins eliminate historical extreme-pressure additives from formulations. Industrial concentration in North Rhine-Westphalia and Baden-Württemberg anchors lubricant technical service deployment.
China
Dual carbon goals and Scope 3 emissions accounting pressure from apparel brand customers accelerate bio-based lubricant adoption. NMPA and MIIT standards govern chemical inputs for textile manufacturing. Yangtze River Delta textile clusters face reformulation timelines as machinery speeds climb and thermal stability demands intensify.
United States
EPA TSCA registration timelines constrain additive chemistry choices for suppliers serving domestic textile mills. Nonwoven fabric producers in hygiene applications mandate synthetic formulations for machinery operating above 25,000 rpm. Southeast textile manufacturing belts absorb compliance costs or pass them through undifferentiated commodity yarn pricing.
Vietnam
FDI-driven fabric and garment capacity expansion outpaces domestic lubricant blending infrastructure. Multinational suppliers establish technical service presence ahead of local competitor maturation. Ho Chi Minh City and Hanoi manufacturing zones concentrate imported texturing equipment requiring synthetic polyalphaolefin fills.
Textile Machine Lubricants Market Competitive Environment
Listed leaders compete with private specialists across formulation chemistry and technical service intensity. The supplier base concentrates around integrated energy majors with captive base oil production and independent lubricant houses with application-specific expertise. Three archetypes dominate: integrated oil majors controlling feedstock access, European formulation specialists embedding technical teams inside textile clusters, and Asian blenders serving cost-sensitive mineral oil demand. Competitive moves center on REACH-compliant additive package pre-approval and predictive maintenance bundling through IoT sensor integration.
Within the integrated major tier, ExxonMobil and Shell Lubricants exemplify feedstock-anchored positioning through global base oil network control. Klüber Lubrication occupies the application engineering specialist archetype, representing the European formulation house model with embedded technical service teams. These three companies illustrate the competitive divergence between scale-driven supply security and expertise-driven specification authority.
| Leading Market Players |
|---|
| ExxonMobil |
| TotalEnergies |
| Chevron Corporation |
| Klüber Lubrication |
| FUCHS Lubricants |
| Shell Lubricants |
| BP |
| Sinopec |
| Nye Lubricants |
| Others |
Value Chain & Pricing Dynamics
Group III base oil refinery scale economies in South Korea and the Middle East compress unit costs for high-viscosity grades while establishing price floors that smaller European blenders cannot match without captive cracking capacity. This feedstock concentration simultaneously shapes procurement strategies and margin structures across synthetic and mineral oil tiers.
Pricing Analysis
Certification level creates the primary spread, with REACH-compliant synthetic formulations commanding substantial premiums over mineral oils lacking ECHA pre-approval. Three-tier pricing structure across premium synthetic, standard mineral, and economy re-refined grades separates specification-locked OEM service contracts from spot-market commodity purchases. Pricing pressure stems from apparel brand Scope 3 accounting mandates forcing mills to absorb bio-based ester cost premiums. Small South Asian legacy operators exhibit highest price sensitivity, while nonwoven hygiene producers prioritize thermal stability over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate synthetic lubricant procurement for high-speed texturing lines, while strategic stockpiling persists for mineral oils serving legacy spinning frames with predictable consumption patterns. Feedstock concentration centers on South Korea, Qatar, and Singapore for Group III base oils, with additive packages sourced from Germany and Japan. Formulation chemistry draws from polyalphaolefin base stocks, ashless anti-wear packages, and demulsifier systems. Single-source vulnerability concentrates in high-viscosity Group III supply when Asian refinery turnarounds coincide. Distribution runs through technical service teams embedded in European clusters and Indian manufacturing belts, supplemented by regional distributors serving fragmented mill bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XIV authorization timelines and machinery OEM specification bundling are compressing competitive windows, creating high-growth disruption for suppliers with pre-approved additive portfolios and embedded technical service infrastructure.
For Market Incumbents: Secure REACH-compliant additive package pre-approval ahead of medium-chain chlorinated paraffin phase-outs to lock specification authority with European textile machinery OEMs. Deepen backward integration into Group III base oil supply through offtake agreements with Asian refiners, mitigating feedstock vulnerability when regional cracking margins tighten. Counter emerging entrant threat from bio-based specialists by certifying lifecycle carbon data for synthetic formulations.
For New Entrants and Emerging Players: BIS certification fast-track for imported lubricants creates entry pathway into India's PLI-driven spinning capacity expansion in Gujarat and Tamil Nadu. Target Vietnam's FDI-driven fabric clusters where domestic blending infrastructure lags equipment installation, establishing technical service presence before local competitor maturation. Pursue digital oil condition monitoring bundling as differentiated go-to-market angle, converting transactional fluid supply into contracted predictive maintenance relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors application engineering specialists with embedded textile cluster relationships over integrated majors dependent on commodity base oil economics. Long-term viability hinges on reformulation agility as regulatory windows narrow across jurisdictions. Acquisition target archetype: European formulation houses with pre-approved REACH additive packages and technical service density in machinery OEM specification channels. Watch ECHA authorization timeline acceleration as inflection indicator for stranded chemistry risk.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Additive Pre-Approval | ECHA authorization timelines compress competitive entry windows for reformulation-ready suppliers. |
| Technical Service Team Embedding | On-site textile cluster presence converts transactional supply into contracted performance agreements. |
| Backward Integration into Group III Feedstock | Captive base oil access secures margin stability when Asian refinery cracking margins tighten. |
| Digital Oil Condition Monitoring Bundling | IoT sensor integration enables predictive drain optimization and recurring service revenue streams. |
| Bio-Based Formulation Certification | Certified lifecycle data addresses apparel brand Scope 3 mandates and specification lock-in. |
Study Parameters
A standing panel of textile mill maintenance directors, lubricant formulation chemists, machinery OEM procurement managers, and regional distribution channel heads provided ongoing calibration against operational realities. Primary fieldwork combined structured interviews with secondary validation through customs trade data, BIS certification registries, ECHA substance restriction notifications, and SEC filings from integrated energy majors. Bottom-up mill consumption estimates triangulated against top-down base oil demand aggregates across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including refinery capacity utilization reports and machinery OEM factory-fill disclosure patterns. The analytical framework modeled segmentation across base stock chemistry, machinery application, end-user procurement authority, and distribution channel intensity throughout the forecast period. CAGRs derived from machinery installation pipelines, PLI scheme capacity commissioning schedules, and regulatory-driven reformulation cycle compression. Industry-specific inputs included texturing machine speed evolution trajectories and REACH authorization timeline probabilities.
Underlying assumptions cover regulatory enforcement consistency, machinery OEM specification bundling persistence, and base oil refinery capacity expansion schedules, with deviation risk concentrated in ECHA authorization acceleration and apparel brand Scope 3 mandate stringency. Forecasts reflect these assumptions with explicit sensitivity bands. Revision becomes warranted when REACH substance restriction scope expands beyond medium-chain chlorinated paraffins or when Indian PLI scheme capacity commissioning diverges from announced timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Poland Industrial Lubricants Market
Lubricants
Global Lubrication Systems Market
Lubricants
Engine Oil and Lubricant Market
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Specialty Lubricants Market
Lubricants
Lubricated Tracks Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Bulgaria Lubricants Market
Lubricants
Bulgaria Passenger Vehicles Lubricants Market
Lubricants
Marine Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Anti-Static Oil Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Global Independent Lubricant Manufacturers Market