
 High Performance Lubricants Market | 2026-2036
High Performance Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Lubricants Market Foresight
Specialty distributor networks for aerospace and precision manufacturing is reshaping how high performance lubricants reach end users. Shell plc leverages its aviation-certified supply chain to dominate turbine oil distribution across European maintenance hubs. Fuchs Petrolub sustains R&D intensity in synthetic ester formulations for wind turbine gearboxes. Klüber Lubrication specializes in application-specific greases for semiconductor cleanroom equipment, occupying a defensible niche against commodity suppliers.
High performance lubricants are formulated base oils and additive packages engineered to operate above 150°C, resist oxidation under extreme pressure, and maintain viscosity stability across broad temperature ranges, serving critical functions in turbines, precision gearboxes, and hydraulic systems where equipment failure carries catastrophic cost. Synthetic formulations command premium positioning due to extended drain intervals and energy efficiency gains in industrial machinery applications. The aerospace segment attracts concentrated R&D investment because airworthiness certification creates steep barriers that lock in supplier relationships. Bio-based products represent the fastest-growing category as OEMs and fleet operators face Scope 3 emissions scrutiny, though mineral oils still anchor volume in emerging market automotive service channels.
The EPA and FAA in the United States, EASA and REACH in Europe, and China's MEE jointly tighten chemical disclosure and biodegradability standards, forcing reformulation investments and culling smaller blenders from approved supplier lists. OEMs now require lubricant partners to pre-certify formulations against multiple regulatory frameworks before contract bidding, raising working capital demands. Stakeholders must monitor how carbon border adjustment mechanisms redefine the cost competitiveness of bio-based versus synthetic supply chains.
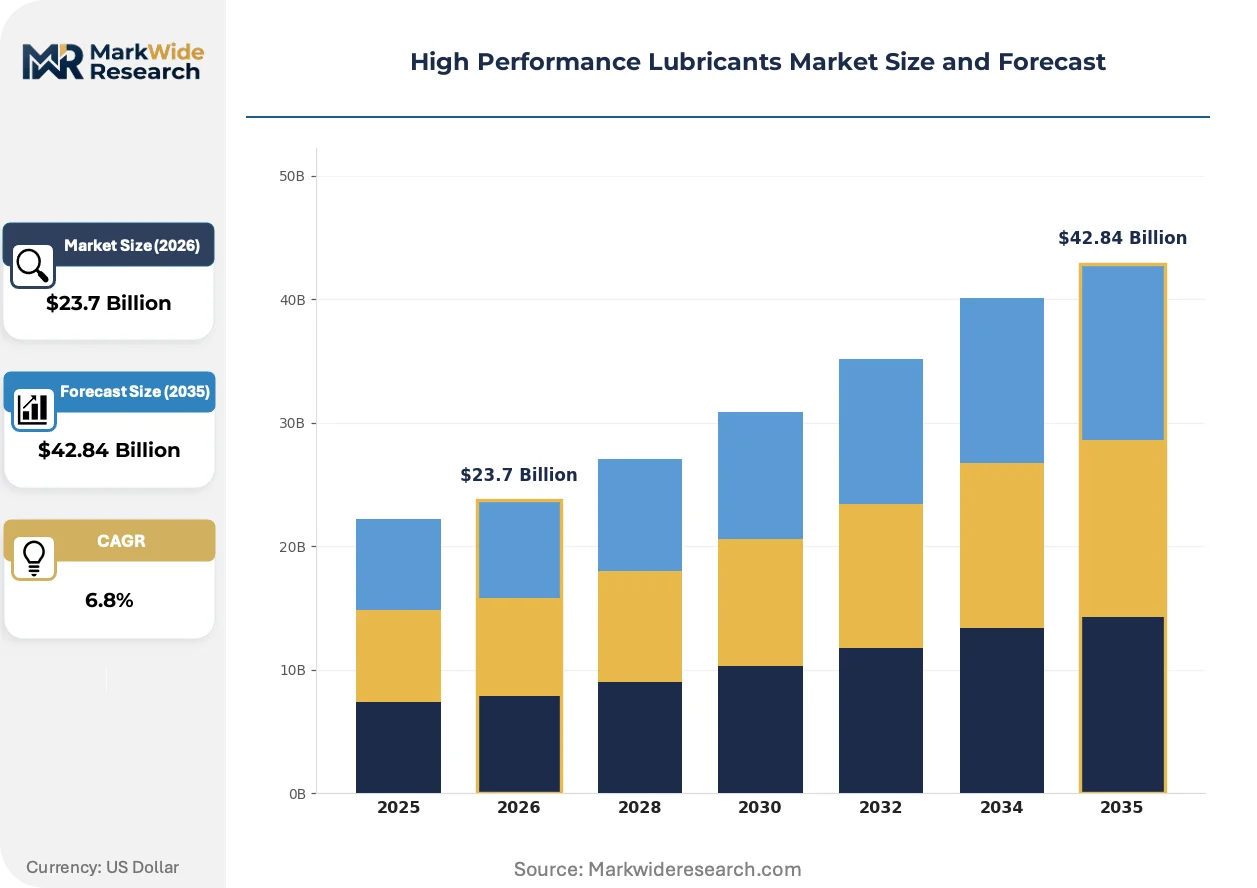
Market Dynamics
Synthetic ester chemistry and bio-based feedstock substitution are compressing formulation cycles as airworthiness certification and carbon accounting simultaneously tighten procurement specifications across aerospace and precision manufacturing.
Growth Catalysts
- Aerospace turbine thermal stability mandates:FAA and EASA airworthiness directives are expanding synthetic lubricant procurement for next-generation engines operating above 180°C.
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases is accelerating low-viscosity synthetic formulation demand in industrial refrigeration and precision cooling systems.
- China's MIIT dual carbon goals:National emissions targets are redirecting state-owned manufacturing procurement toward bio-based hydraulic fluids and biodegradable metalworking lubricants.
Market Restraints
- Group V base oil supply concentration:Polyol ester and polyalkylene glycol feedstock production clusters in Germany and the United States, creating geographic vulnerability for Asian blenders.
- REACH chemical disclosure friction:The European Chemicals Agency's Substance of Very High Concern candidate list expansion is forcing reformulation of corrosion inhibitor packages before contract renewal cycles.
- Mineral oil substitution economics:Extended drain interval claims for synthetics face validation skepticism from cost-sensitive fleet operators in emerging market automotive service channels.
Strategic Opportunities
- Wind turbine gearbox service expansion:Offshore wind installations in the North Sea and Baltic coasts are creating aftermarket demand for synthetic ester formulations with 15-year service life specifications.
- Semiconductor cleanroom grease specialization:Vacuum-compatible, ultra-low outgassing lubricants for wafer handling robotics represent a defensible niche against commodity suppliers.
- India's PLI scheme for precision manufacturing:Production-linked incentives for advanced manufacturing are attracting lubricant technical centers to Pune and Chennai industrial corridors.
Industry Challenges
- Airworthiness certification timeline compression:OEM pre-qualification requirements now demand simultaneous FAA, EASA, and CAAC submission packages, stretching regulatory affairs teams.
- Additive package IP fragmentation:Patent thickets around ashless anti-wear chemistry are forcing smaller blenders into costly licensing negotiations or backward integration into additive synthesis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Lubricants Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, Bio-Based Application: Automotive, Industrial Machinery, Marine, Aerospace End User: OEMs, Maintenance Providers, Fleet Operators, Service Stations Packaging Type: Drum, Pail, Bottle, Bulk |
| Companies Covered | TotalEnergies, Fuchs Petrolub, Shell plc, Sinopec Lubricant Company, PetroChina, ExxonMobil, Chevron, Klüber Lubrication, Castrol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Lubricants Market Shifts & Advancements
Formulation science is pivoting from performance maximization toward carbon intensity verification, with molecular engineering and supply chain traceability converging to redefine product differentiation.
Polyol ester base stocks with tailored branched-chain architectures are rendering obsolete mineral oil formulations in high-temperature hydraulic systems. Aerospace OEMs and industrial turbine operators are specifying these synthetics for continuous operation above 150°C. The technology is compressing drain intervals from annual to biennial cycles while eliminating varnish deposition failures.
REACH Annex XIV authorization requirements for zinc dialkyldithiophosphate compounds are forcing reformulation of anti-wear additive packages across European metalworking and gear oil applications. Blenders are accelerating calcium sulfonate complex grease development as drop-in replacements. The industrial maintenance segment faces the steepest transition costs due to legacy equipment compatibility testing.
Scope 3 emissions auditing is restructuring lubricant procurement contracts toward full lifecycle carbon disclosure. Automotive OEMs and wind farm operators now require feedstock origin documentation and biodegradability certification as bid prerequisites. Germany's precision manufacturing belt exhibits the most advanced buyer concentration around verified low-carbon supply chains.
High Performance Lubricants Market Segmentation
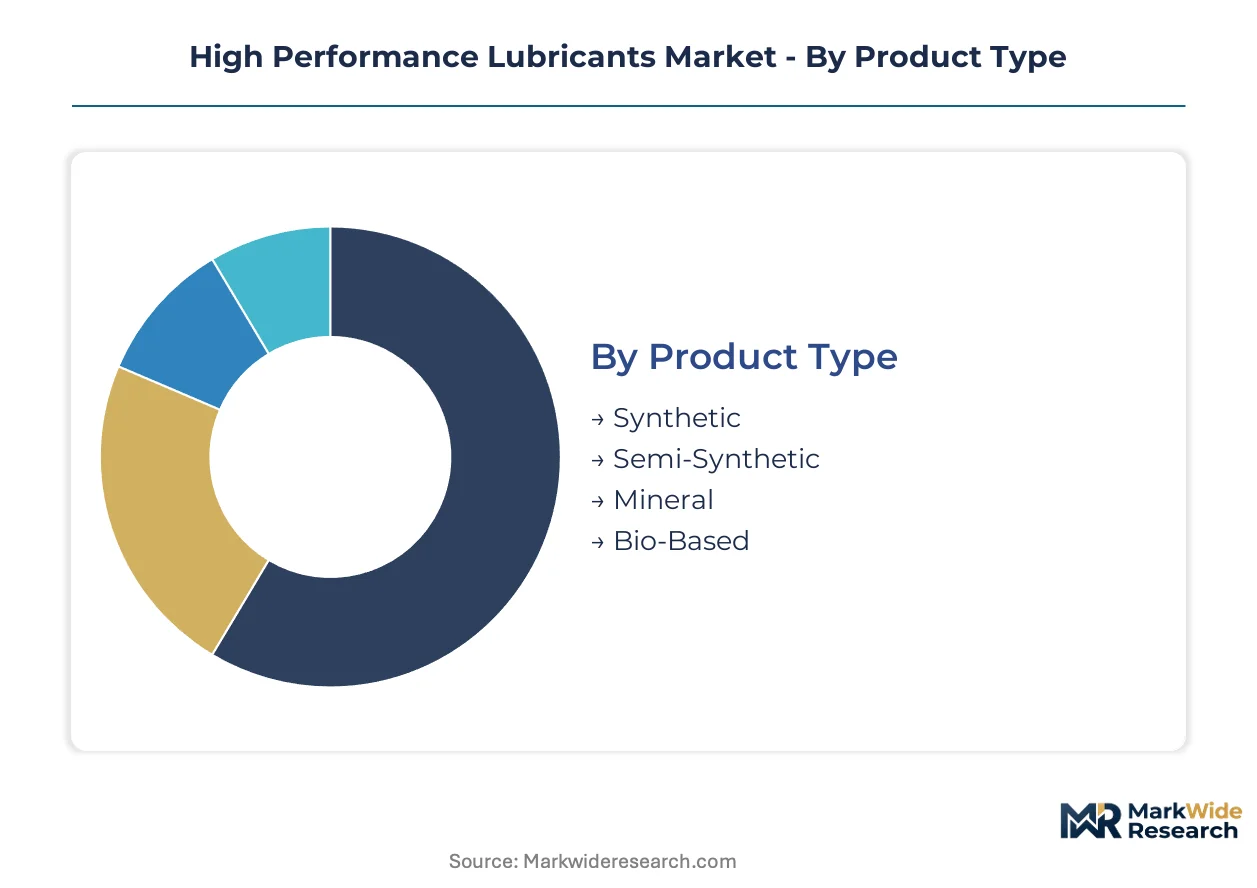
Segmentation in high performance lubricants reveals how formulation chemistry, application severity, and procurement authority split demand across divergent specification regimes. Understanding these fractures exposes where margin concentrates and where certification barriers protect incumbent positions.
Product Type:
Cost tier stratification separates premium synthetic formulations from commodity mineral alternatives, with bio-based products commanding green procurement premiums.
- Synthetic:Polyol ester and polyalkylene glycol base stocks engineered for continuous operation above 150°C. Aerospace turbine manufacturers in Germany and the United States specify these for thermal stability under FAA and EASA directives.
- Bio-Based:Vegetable oil and synthetic ester feedstocks with verified biodegradability certification. Wind farm operators in the North Sea and Baltic coasts prioritize these for Scope 3 emissions compliance.
- Semi-Synthetic:Blended formulations balancing mineral base stocks with synthetic additives for mid-tier industrial applications.
- Mineral:Refined petroleum distillates anchoring volume in emerging market automotive service channels where drain interval economics face validation skepticism.
Synthetic formulations command the established base. The steepest expansion runs through bio-based products.
Application:
Application severity determines formulation complexity, with thermal load and failure cost defining specification stringency.
- Aerospace:Turbine oils and hydraulic fluids requiring simultaneous FAA, EASA, and CAAC airworthiness certification. OEM pre-qualification timelines now demand submission packages across all three regulators, stretching technical resources.
- Industrial Machinery:High-temperature hydraulic systems and precision gearboxes in Germany's manufacturing belt specifying polyol esters for varnish-free operation.
- Automotive:Engine oils and transmission fluids where extended drain claims face cost-sensitive fleet operator scrutiny in emerging markets.
- Marine:Stern tube oils and cylinder lubricants for vessels operating under IMO environmental regulations.
Aerospace commands the established base. The steepest expansion runs through industrial machinery.
End User:
Procurement authority concentration shapes how lubricant suppliers structure technical service and inventory commitments.
- OEMs:Original equipment manufacturers embedding lubricant specifications into design requirements and warranty conditions. These buyers demand pre-certification against multiple regulatory frameworks before contract bidding.
- Fleet Operators:Large-scale vehicle and vessel owners negotiating lifecycle cost contracts with full carbon disclosure requirements.
- Maintenance Providers:Independent service facilities stocking approved lubricants for warranty-compliant repairs.
- Service Stations:Retail outlets serving consumer automotive demand with mineral oil volume.
OEMs command the established base. The steepest expansion runs through fleet operators.
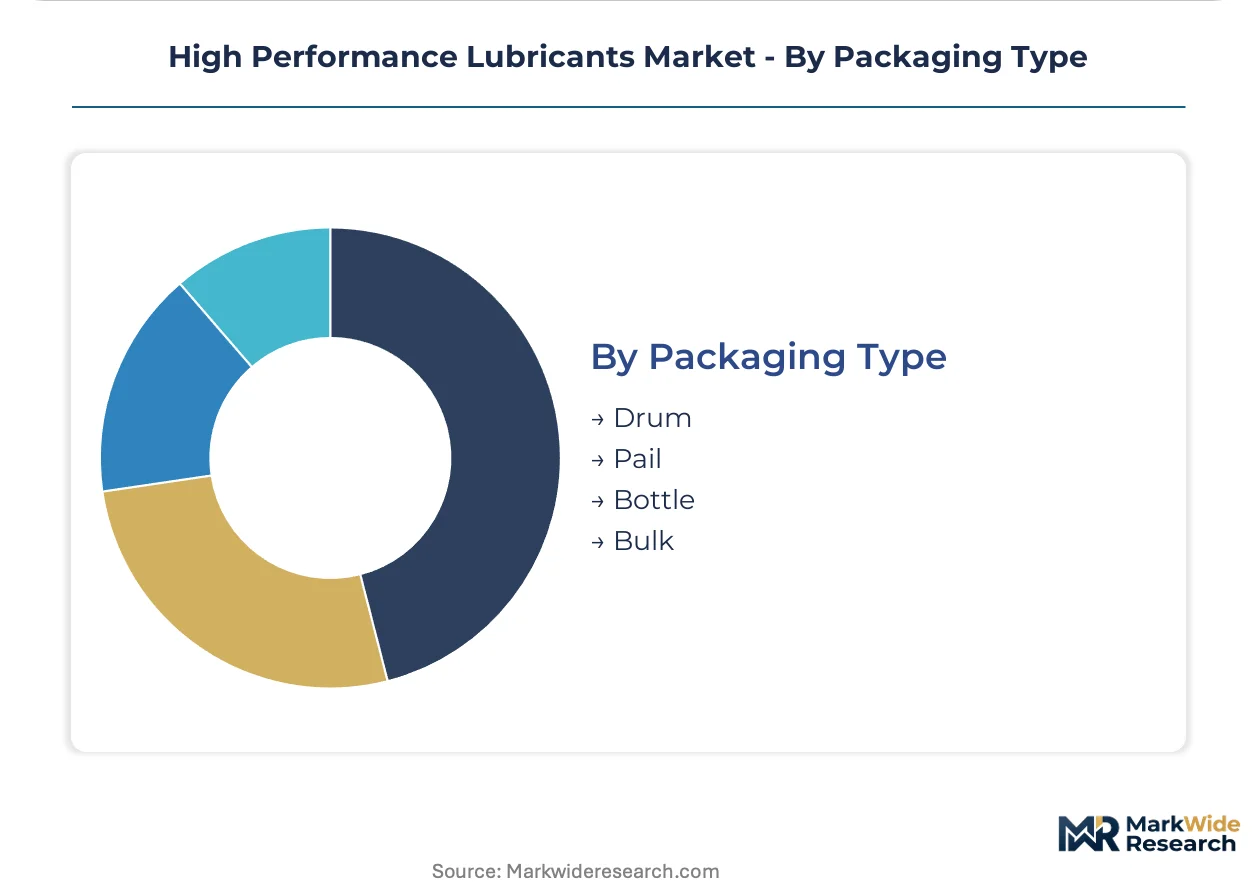
Packaging Type:
Volume scale and handling infrastructure segment logistics economics across the supply chain.
- Bulk:Tanker and railcar deliveries to wind farms and industrial facilities with on-site storage. North Sea offshore installations specify synthetic esters in 20,000-liter batches.
- Drum:200-liter steel containers for manufacturing plants with moderate consumption rates and lifting equipment.
- Pail:20-liter plastic containers for maintenance shops and smaller industrial accounts.
- Bottle:1-5 liter retail formats for automotive service stations and consumer DIY channels.
Bulk commands the established base. The steepest expansion runs through drum formats serving precision manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German blenders extract 30-40% price premiums over Southeast Asian counterparts for identical polyol ester formulations. This asymmetry reflects certification density, regulatory compliance costs, and proximity to aerospace OEM technical centers rather than feedstock economics alone.
United States
FAA airworthiness directives and EPA chemical disclosure rules are expanding synthetic procurement for next-generation turbine engines. The IRA's clean manufacturing provisions accelerate bio-based hydraulic fluid adoption across defense contractors. Houston-Gulf Coast petrochemical corridors anchor Group V base stock production for domestic aerospace supply chains.
Germany
ECHA REACH authorization timelines and the EU F-Gas Regulation are compressing formulation cycles for industrial refrigeration lubricants. Klüber Lubrication and Fuchs Petrolub anchor specialized supply networks in the precision manufacturing belt. Munich-Stuttgart industrial corridors concentrate R&D intensity for high-temperature synthetic esters.
China
MIIT dual carbon goals redirect state-owned manufacturing procurement toward bio-based metalworking fluids. SAMR standard updates tighten biodegradability certification for hydraulic systems in heavy machinery. Yangtze River Delta clusters concentrate domestic blending capacity for wind turbine gearbox service expansion.
Japan
METI energy efficiency mandates accelerate low-viscosity synthetic adoption in precision machine tools. JIS standards for high-temperature hydraulic fluids exceed baseline ISO specifications, creating technical barriers for imported formulations. Nagoya-Tokyo industrial corridors anchor semiconductor equipment grease specialization for wafer handling robotics.
India
PLI scheme incentives for advanced manufacturing attract lubricant technical centers to Pune and Chennai corridors. BIS adoption of REACH-aligned chemical disclosure standards raises compliance costs for European formulation imports. Gujarat petrochemical zones expand Group II/III base oil capacity serving domestic automotive service channels.
High Performance Lubricants Market Competitive Landscape
Integrated energy majors and specialized lubricant formulators split the market along certification-depth and application-breadth axes. Concentration is moderate at the top, with five-to-seven players controlling aerospace and precision manufacturing segments while regional blenders fragment automotive service channels. Two strategic archetypes dominate: vertically integrated petrochemical conglomerates leveraging feedstock control, and application-specific specialists monetizing formulation IP and airworthiness certification relationships. Competitive moves center on additive package backward integration and multi-regulatory pre-certification investments to qualify for OEM bidding.
Among the integrated majors, Shell plc anchors aviation-certified distribution networks across European maintenance hubs. Fuchs Petrolub exemplifies the specialist archetype through concentrated synthetic ester development for industrial machinery applications. Klüber Lubrication occupies a defensible niche in application-specific greases for precision manufacturing environments. These three represent divergent strategic postures within a market where certification density and technical service proximity determine contract capture.
| Leading Market Players |
|---|
| TotalEnergies |
| Fuchs Petrolub |
| Shell plc |
| Sinopec Lubricant Company |
| PetroChina |
| ExxonMobil |
| Chevron |
| Klüber Lubrication |
| Castrol |
| Others |
Supply & Pricing Matrix
REACH chemical disclosure friction and ECHA Substance of Very High Concern candidate list expansion determine both the 30-40% premium spread between German and Southeast Asian polyol ester formulations and the geographic clustering of Group V base stock production around Houston-Gulf Coast and Munich-Stuttgart corridors.
Pricing Analysis
Configured-to-order pricing for FAA-EASA-CAAC pre-certified synthetic turbine oils commands substantial premiums over standard industrial hydraulic fluid catalog pricing. Three-tier pricing structure across aerospace-certified, precision manufacturing-grade, and automotive service mineral tiers separates buyers by certification burden and thermal stability requirements. Price differentiation hinges on airworthiness certification density and feedstock origin documentation for Scope 3 compliance. Cost compression in automotive service mineral oils is intensifying because fleet operators in emerging markets demand validation of extended drain interval claims.
Supply Chain Analysis
Contract manufacturing concentration for polyol ester base stocks rests with integrated petrochemical complexes in Germany, the United States, and select Yangtze River Delta facilities. Raw material dependencies draw from palm-derived fatty acids, petroleum-derived polyols, and specialized additive packages anchored in German and US chemical corridors. Single-source vulnerability concentrates around polyalkylene glycol feedstock production clusters. Distribution runs through specialty distributor networks for aerospace maintenance hubs and direct bulk tanker delivery for North Sea offshore wind installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high performance lubricants market sits in early-cycle expansion as bio-based formulation adoption accelerates under tightening Scope 3 emissions auditing and carbon border adjustment mechanisms.
For Market Incumbents: Insulate aerospace certification relationships by accelerating simultaneous FAA-EASA-CAAC submission package capabilities before OEM pre-qualification timelines compress further. Prioritize backward integration into ashless anti-wear additive synthesis to escape patent thickets forcing costly licensing negotiations on smaller blenders.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme corridors around Pune and Chennai where production-linked incentives for advanced manufacturing are attracting lubricant technical centers absent entrenched incumbent distribution. Target semiconductor cleanroom grease specialization for wafer handling robotics, a defensible niche with vacuum-compatible ultra-low outgassing requirements that commodity suppliers cannot serve.
For Investors and Strategic Acquirers: Application-specific specialists with embedded airworthiness certification relationships and formulation IP in synthetic ester chemistry represent the most attractive acquisition archetype for long-term viability over the next decade. Monitor carbon border adjustment mechanism implementation progress as the critical inflection signal for bio-based versus synthetic supply chain cost competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Synthesis | Escapes patent thickets around ashless anti-wear chemistry that fragment IP for smaller blenders. |
| Multi-Regulatory Pre-Certification Investment | Qualifies suppliers for OEM bidding cycles demanding simultaneous FAA, EASA, and CAAC submission packages. |
| Long-Term Supply Agreement with Wind Farm Operators | Locks in 15-year service life synthetic ester demand for North Sea and Baltic offshore installations. |
| Technical Center Establishment in PLI Corridors | Captures production-linked incentive demand for precision manufacturing in Pune and Chennai industrial belts. |
| Green Manufacturing Transition Certification | Satisfies Scope 3 emissions auditing requirements from automotive OEMs and wind farm operators. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the analysis window, combining structured interviews with aerospace procurement directors, wind farm maintenance heads, semiconductor equipment engineers, and precision manufacturing plant managers with secondary validation from EASA airworthiness directives, EPA chemical disclosure filings, MIIT dual carbon policy documents, and customs trade data for Group V base oil flows. Bottom-up volume modeling triangulated against top-down macroeconomic calibration anchored the forecast framework.
Calibration against historical formulation adoption curves and regulatory implementation timelines shaped projections across the modeling period. Segmentation dimensions modeled include product chemistry tier, application severity class, procurement authority concentration, and regional regulatory cluster intensity. CAGRs were derived from elasticity-adjusted penetration curves for synthetic and bio-based categories. Industry-specific inputs incorporated airworthiness certification queue lengths and carbon border adjustment mechanism implementation phasing.
Sensitivities concentrate around REACH Annex XIV authorization timeline acceleration, CAAC certification reciprocity agreements, and bio-based feedstock crop yield volatility. Forecasts reflect documented assumptions regarding regulatory harmonization and OEM pre-qualification standardization. Quarterly review of ECHA candidate list expansions, FAA airworthiness directive issuance rates, and wind turbine installation commissioning data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Finished Lubricant Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Offshore Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Gun Lubricant Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Global Mineral Oil Market
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
Global Lubricant Antioxidants Market
Lubricants
Thailand Lubricants Market
Lubricants
Africa Lubricants Market
Lubricants
Iran Passenger Vehicles Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
Cutting Fluid Market