
 Aircraft Tube and Duct Assemblies Market | 2026-2036
Aircraft Tube and Duct Assemblies Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Tube and Duct Assemblies Market Analysis
A capital-intensity divergence between full-service aerostructures suppliers and specialized tubing fabricators is redrawing competitive tiers in aircraft fluid conveyance. Safran S.A. leverages integrated engine nacelle programs to bundle high-pressure ducting with propulsion contracts. Triumph Group, Inc. sustains long-term aftermarket revenue through military MRO channel control. Parker-Hannifin Corporation anchors its position via hydraulic line dominance across Boeing and Airbus platforms.
Aircraft tube and duct assemblies are engineered fluid conveyance systems fabricated from titanium alloys, stainless steel, nickel-based superalloys, and thermoset composite matrices, typically operating at pressures from 50 to 5,000 psi and temperatures spanning -65°F to 1,200°F depending on system function; these assemblies distribute air, fuel, hydraulic fluid, and engine bleed air throughout fixed-wing and rotary-wing airframes. Metal tubes retain the largest installed base in fuel and hydraulic applications where fatigue resistance and fire containment remain non-negotiable, while composite ducts are gaining share in air conditioning and engine bleed systems where weight reduction of 30-40 percent versus metallic equivalents justifies higher unit costs. Connector assemblies command disproportionate margin pools due to proprietary quick-disconnect designs and FAA Parts Manufacturer Approval certification barriers.
FAA airworthiness standards under 14 CFR Part 25, EASA CS-25 certification requirements, and ISO 9001/AS9100 quality frameworks collectively govern material selection, fire-smoke-toxicity performance, and traceability across the supply chain. Military procurement through NAVAIR and Defense Logistics Agency specifications adds further compliance layers for defense-oriented suppliers. Stakeholders must monitor how sustainable aviation fuel compatibility requirements and emerging thermal management needs for hybrid-electric propulsion architectures reshape material specifications and qualification timelines.
Market Dynamics
Composite thermoset ducting is displacing titanium and stainless steel in environmental control systems as commercial aviation OEMs pursue 30-40 percent weight reductions on narrow-body platforms, forcing incumbent metal fabricators to requalify legacy product lines.
Growth Catalysts
- 14 CFR Part 25 fire-smoke-toxicity standards:FAA mandates for improved fire containment are accelerating replacement cycles in aging commercial fleets.
- Titanium alloy tubing:Fatigue-resistant hydraulic line demand from expanding narrow-body final assembly lines in the United States, France, and China sustains metal volumes.
- Engine bleed air thermal management:Higher bypass ratio propulsion architectures require upgraded high-temperature ducting specifications across next-generation platforms.
Market Restraints
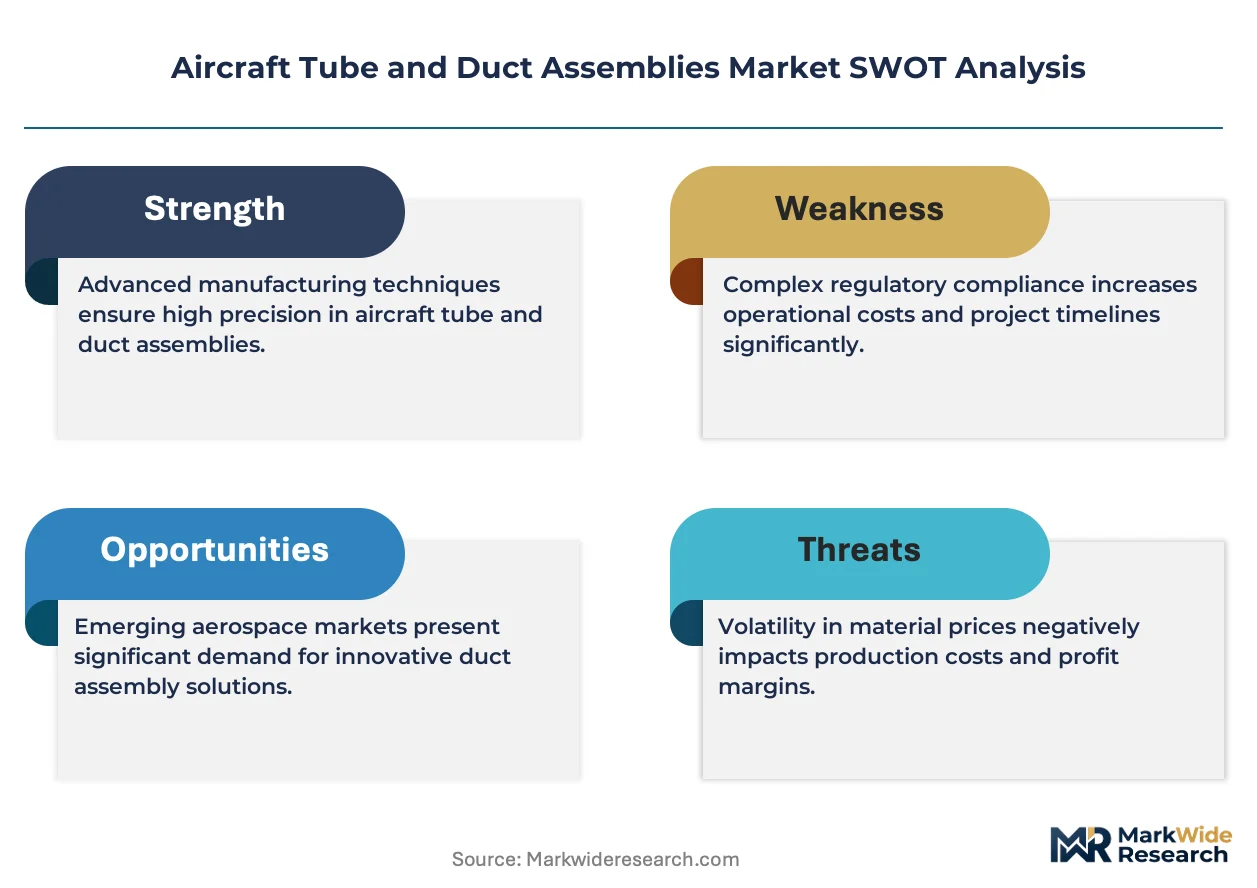
- Titanium sponge price volatility:Aerospace-grade titanium input costs fluctuate with Russian and Chinese export quotas, compressing fabricator margins.
- AS9100 certification concentration:Fewer than twelve North American and European suppliers hold active approvals for FAA Part Manufacturer Approval connector assemblies.
- Metallic fatigue limits:Aluminum tubing substitution remains blocked by 1,200°F temperature ceilings in engine-adjacent applications.
Strategic Opportunities
- Hybrid-electric thermal management:Liquid cooling loops for electric propulsion motors create entirely new ducting specifications without incumbent qualification heritage.
- Sustainable aviation fuel compatibility:EASA and FAA testing protocols for SAF elastomer seal degradation open retrofit markets for fuel line assemblies.
- India defense procurement:Hindustan Aeronautics Limited indigenization mandates under the Ministry of Defence offset policy create local fabrication partnerships.
Industry Challenges
- Composite autoclave capacity scarcity:Large-diameter thermoset curing requires capital-intensive autoclave investment with 18-24 month lead times.
- Dual certification timelines:Simultaneous FAA and EASA qualification for new materials extends time-to-revenue by 36-48 months.
- Legacy hydraulic line integration:New lightweight ducting must interface with existing Boeing and Airbus platform architectures without full system redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Tube and Duct Assemblies Market |
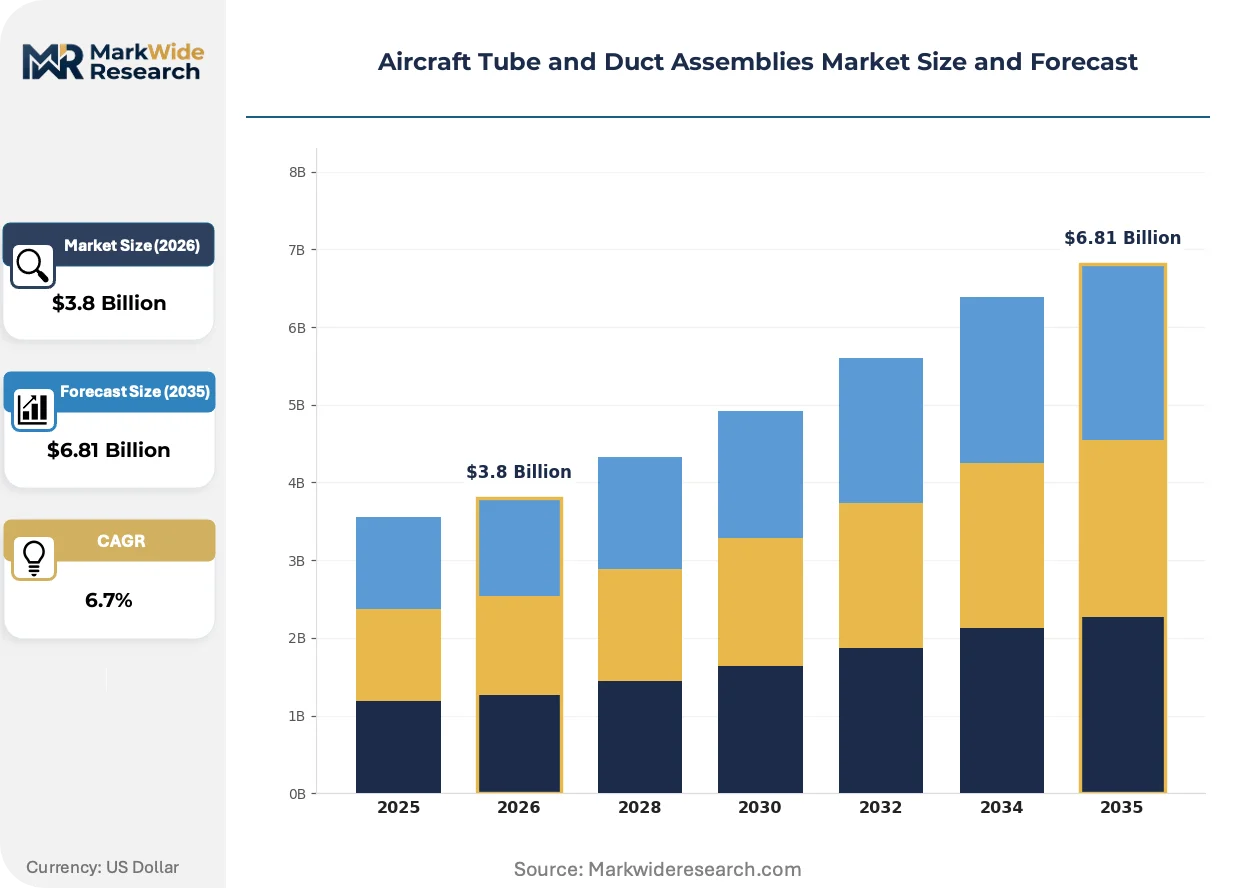
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Tubes, Composite Ducts, Plastic Hoses, Connector Assemblies Application: Air Conditioning Systems, Fuel Systems, Hydraulic Lines, Engine Systems End User: OEMs, MRO Providers, Military Aircraft, Commercial Aviation Installation Type: In-Flight Systems, Ground Support Equipment, Retrofit Installations, Upgrade Projects |
| Companies Covered | Safran S.A., Triumph Group, Inc., Senior plc, Hutchinson SA, GKN Aerospace, Parker-Hannifin Corporation, Ametek Inc., Arrowhead Products, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Tube and Duct Assemblies Market Emerging Trajectories
Thermoplastic composite processing and additive manufacturing are rewriting qualification protocols for fluid conveyance systems, while regulatory pressure on fire performance and supply chain traceability tightens compliance architectures.
Thermoplastic composite ducting is displacing thermoset matrices in non-structural air distribution systems. Safran and Spirit AeroSystems are qualifying polyetherketoneketone ducts for cabin ventilation on single-aisle programs. The shift is compressing fabrication cycle times from hours to minutes and enabling in-situ repair protocols that thermoset autoclave curing cannot match.
EASA CS-25 Amendment 25-146 introduced more stringent fire penetration testing for engine nacelle ducting, effective for type certificates submitted after 2024. European OEMs must now demonstrate 15-minute flame resistance at 2,000°F versus prior 5-minute standards. French and German suppliers are accelerating ceramic matrix composite development to meet these thresholds without weight penalties.
Airline procurement teams are consolidating tube and duct sourcing under airframe OEM direct contracts rather than airline-specified aftermarket purchases. This disintermediation shifts specification control to Boeing and Airbus engineering teams in Everett, Toulouse, and Tianjin. The pattern compresses supplier margins but locks in decade-long production commitments for qualified fabricators.
Aircraft Tube and Duct Assemblies Market Segmentation
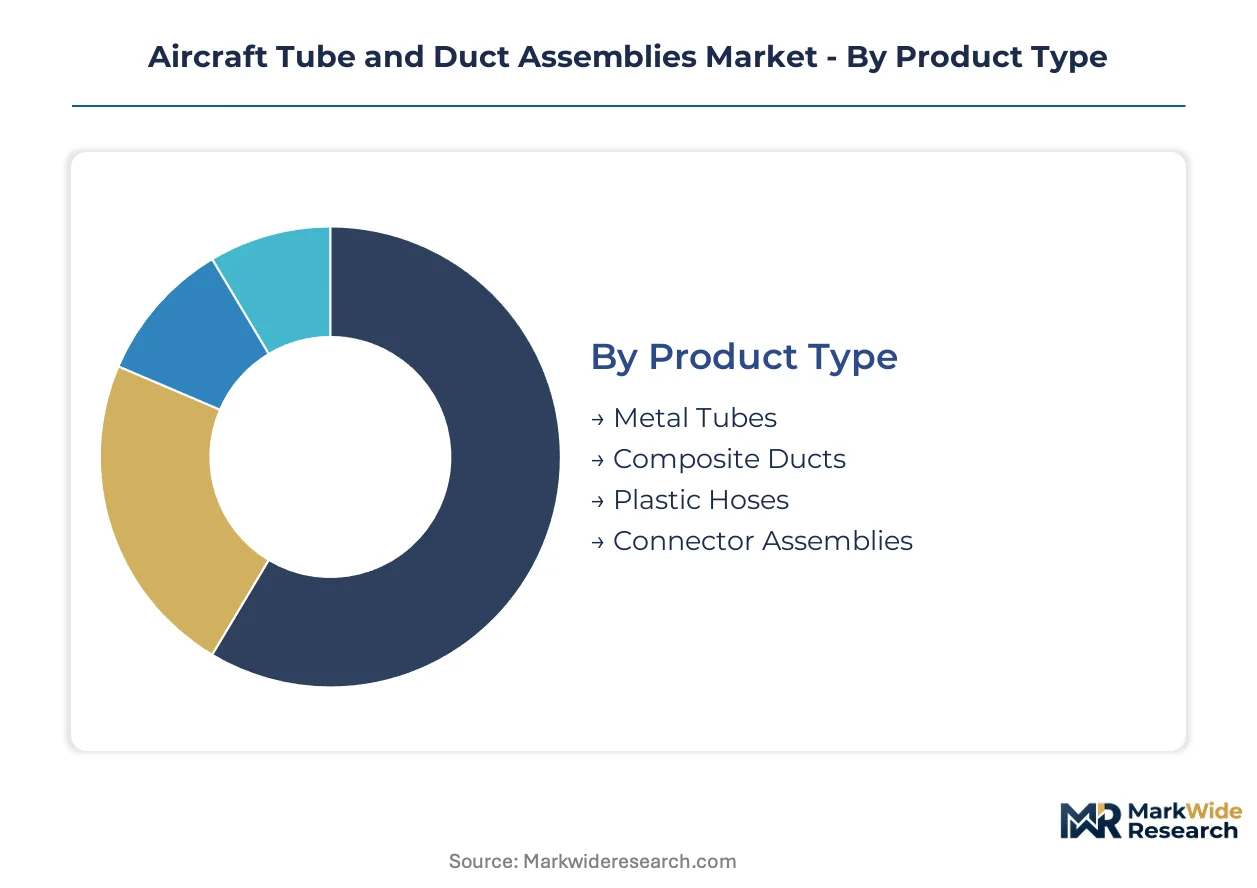
Aircraft tube and duct assemblies fragment across four critical dimensions: material composition dictates qualification pathways, application function determines thermal and pressure specifications, end-user procurement patterns govern contract structures, and installation type shapes aftermarket revenue timing. Understanding these splits reveals where capital deployment concentrates and where margin pools shift.
Product Type:
Metal tubes dominate domestic supply chains in the United States, France, and China where narrow-body final assembly lines cluster, while composite ducts travel farther to serve export-led environmental control retrofits.
- Metal Tubes:Fabricated from titanium alloys, stainless steel, and nickel-based superalloys, these assemblies withstand pressures from 50 to 5,000 psi and temperatures reaching 1,200°F in engine-adjacent applications. Demand concentrates at Boeing's Everett facility and Airbus Toulouse for hydraulic and fuel system integration where fatigue resistance remains non-negotiable.
- Composite Ducts:Thermoset and thermoplastic matrix constructions deliver 30-40 percent weight reduction versus metallic equivalents in air conditioning and engine bleed systems. French suppliers export these to Middle Eastern and Asian carriers pursuing narrow-body fleet modernization under EASA CS-25 Amendment 25-146 fire standards.
- Plastic Hoses:Flexible elastomer constructions serve low-pressure cabin ventilation and drainage applications.
- Connector Assemblies:Proprietary quick-disconnect designs with FAA Part Manufacturer Approval certification command disproportionate margin pools due to qualification barriers.
Metal tubes hold the largest share; momentum sits with composite ducts.
Application:
Application segmentation tracks thermal severity gradients, with cost tiers separating commodity cabin systems from premium engine-adjacent specifications.
- Air Conditioning Systems:Medium-pressure ducting distributes temperature-controlled air throughout passenger cabins and flight decks. Thermoplastic polyetherketoneketone constructions from Safran and Spirit AeroSystems are compressing fabrication cycle times for single-aisle programs in France and Germany.
- Fuel Systems:Fire-resistant tubing and sealing assemblies must contain Jet A and sustainable aviation fuel variants without elastomer degradation. EASA and FAA testing protocols for SAF compatibility are opening retrofit markets for qualified fabricators in the United States.
- Hydraulic Lines:Fatigue-resistant titanium tubing sustains flight control actuation pressures across Boeing and Airbus platforms.
- Engine Systems:High-temperature bleed air management and thermal protection ducting operate at the extreme edge of material capabilities.
Hydraulic lines anchor current procurement volumes; air conditioning systems are climbing the fastest as weight reduction targets tighten.
End User:
Customer type determines contract duration and specification control, with OEM direct procurement displacing airline-specified aftermarket purchases.
- OEMs:Boeing and Airbus engineering teams in Everett, Toulouse, and Tianjin now consolidate tube and duct sourcing under airframe direct contracts rather than airline-specified purchases. This disintermediation locks in decade-long production commitments for qualified fabricators.
- MRO Providers:Aftermarket channel control sustains long-term revenue for specialists like Triumph Group through military and commercial fleet maintenance networks.
- Military Aircraft:NAVAIR and Defense Logistics Agency specifications add compliance layers for defense-oriented suppliers in the United States.
- Commercial Aviation:Airline procurement teams face compressed margins but gain specification certainty through OEM bundling.
OEMs command the dominant share; MRO providers are expanding most quickly as aging fleet replacement cycles accelerate.
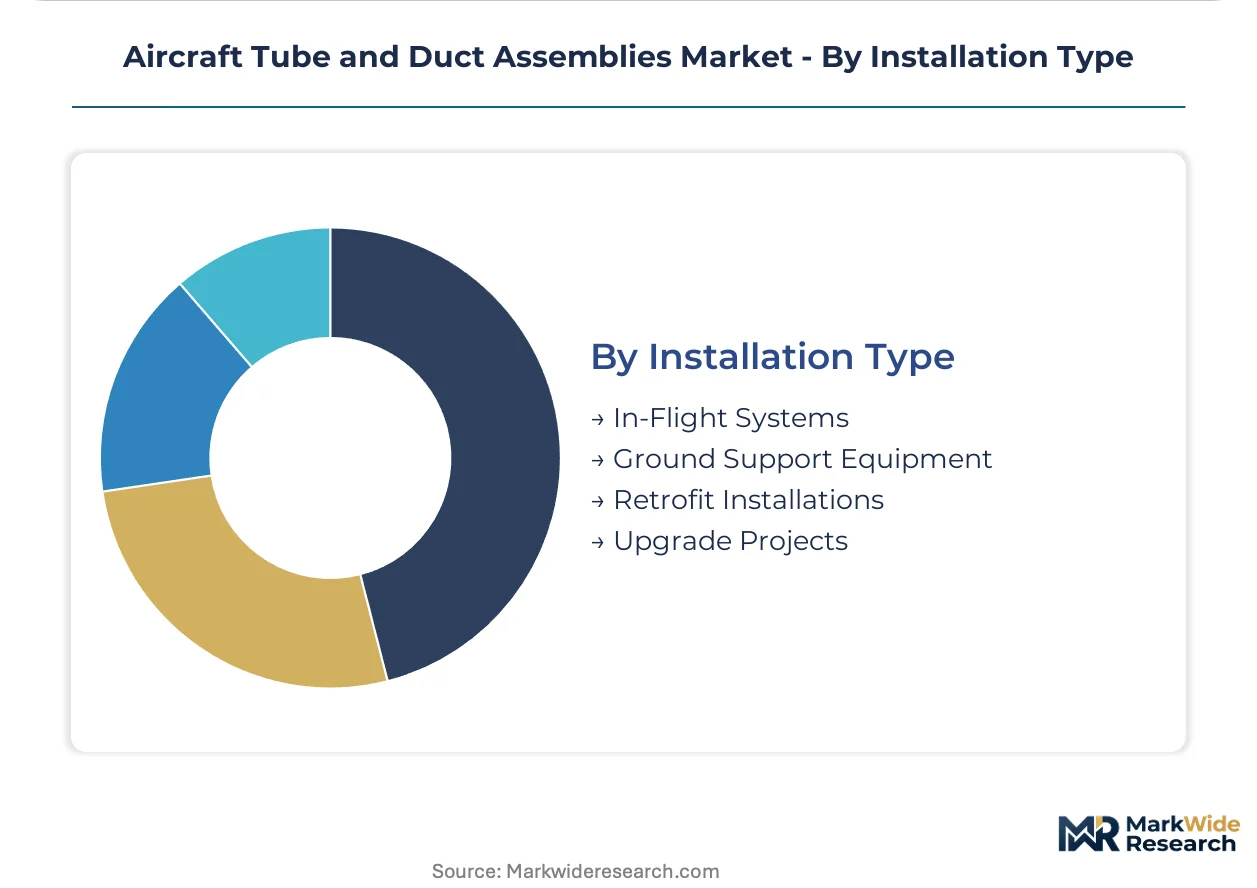
Installation Type:
Installation segmentation separates high-volume production line fit from lower-volume but higher-margin aftermarket and modification work.
- In-Flight Systems:Original equipment installation during airframe assembly represents the highest volume channel with strictest qualification requirements.
- Ground Support Equipment:Mobile pre-conditioned air units and fuel servicing carts utilize standardized hose and duct configurations with shorter certification timelines.
- Retrofit Installations:Fleet upgrades for fire-smoke-toxicity compliance under FAA 14 CFR Part 25 mandates drive replacement demand in aging commercial aircraft.
- Upgrade Projects:Hybrid-electric thermal management retrofits create entirely new ducting specifications for liquid cooling loops without incumbent qualification heritage.
In-flight systems retain the largest installed base; upgrade projects show the steepest expansion trajectory as propulsion architectures evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with French suppliers serving Middle Eastern retrofit demand, while Chinese fabricators compete on volume for narrow-body line-fit contracts. Titanium sponge cost volatility compresses margins in United States-based hydraulic line production. Certification timelines stretch longest for European suppliers navigating simultaneous EASA and FAA qualification pathways.
United States
Boeing's Everett facility and Airbus's Mobile final assembly line sustain titanium hydraulic tubing demand for single-aisle programs. FAA 14 CFR Part 25 fire-smoke-toxicity mandates accelerate replacement cycles in aging domestic fleets. Wichita, Kansas hosts concentrated metal fabrication capacity serving military MRO channels through Defense Logistics Agency specifications.
France
Safran's integrated propulsion contracts bundle high-pressure engine nacelle ducting with narrow-body OEM deliveries. EASA CS-25 Amendment 25-146 imposes 15-minute flame resistance standards effective for type certificates submitted after 2024. Toulouse anchors thermoplastic polyetherketoneketone development for cabin ventilation systems on A320 family programs.
China
COMAC C919 production ramp at Shanghai Pudong drives line-fit procurement of environmental control ducting for indigenous narrow-body platforms. MIIT aerospace certification requirements add domestic qualification layers beyond FAA and EASA benchmarks. Tianjin final assembly operations for Airbus A320 family concentrate import demand for composite bleed air systems.
Germany
Higher bypass ratio propulsion architectures from MTU Aero Engines necessitate upgraded high-temperature ducting specifications. KBA-equivalent aerospace material approvals interface with EASA harmonization protocols for cross-border supply chains. Bavaria's precision tubing clusters specialize in fatigue-resistant hydraulic line integration for legacy platform retrofits.
India
Hindustan Aeronautics Limited indigenization mandates under Ministry of Defence offset policy create local fabrication partnerships for military rotorcraft programs. BIS aerospace material standards are converging with AS9100 quality frameworks for defense procurement eligibility. Bangalore's aerospace engineering corridor attracts joint ventures for composite autoclave capacity expansion.
Aircraft Tube and Duct Assemblies Market Vendor Landscape
Concentration sits with full-service aerostructures suppliers controlling OEM direct contracts, while specialized tubing fabricators defend aftermarket channel positions. Tier-one players leverage integrated propulsion and airframe programs to bundle fluid conveyance with larger system awards. Mid-cap specialists concentrate on FAA Part Manufacturer Approval connector assemblies where certification barriers protect margin pools. Dominant competitive moves include strategic partnerships for hybrid-electric thermal management qualification and geographic expansion into Indian defense offset arrangements.
Among France-based integrated suppliers, Safran S.A. exemplifies the propulsion-bundling archetype through engine nacelle program control. Parker-Hannifin Corporation occupies a position within hydraulic line dominance across Boeing and Airbus platforms. Triumph Group, Inc. represents the aftermarket channel specialist model through military MRO network concentration.
| Leading Market Players |
|---|
| Safran S.A. |
| Triumph Group, Inc. |
| Senior plc |
| Hutchinson SA |
| GKN Aerospace |
| Parker-Hannifin Corporation |
| Ametek Inc. |
| Arrowhead Products |
| Eaton Corporation |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four month autoclave lead times for thermoset composite curing concentrate pricing power with French and German suppliers holding installed capacity, while titanium sponge volatility from Russian and Chinese export quotas compresses margins for United States-based hydraulic line fabricators serving Boeing's Everett narrow-body programs.
Pricing Analysis
The customization-premium spread separates FAA Part Manufacturer Approval-certified connector assemblies from commodity metallic tubing, with proprietary quick-disconnect designs commanding three-tier pricing structure across premium, standard, and economy levels based on certification tier and thermal performance grade. Price differentiation stems from EASA CS-25 Amendment 25-146 fire-resistance qualification status and volume scale of narrow-body OEM line-fit contracts. Cost compression in standard-grade titanium tubing is intensifying because aerospace-grade sponge input costs fluctuate with export quota regimes. Airline procurement teams exhibit highest price sensitivity for aftermarket retrofit volumes, while OEM engineering teams in Toulouse and Tianjin prioritize qualification certainty over unit cost.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for Chinese titanium sponge and Japanese thermoplastic resin shipments to French and German fabrication clusters. Supply concentrates in the United States for hydraulic line integration at Boeing Everett and Airbus Mobile, in France for Safran-bundled engine nacelle ducting, and in China for COMAC C919 environmental control systems. Raw material dependencies rest on Russian and Chinese titanium sponge, Japanese polyetherketoneketone resin, and United States-sourced nickel-based superalloys. Single-source vulnerability in aerospace-grade autoclave capacity creates supply chain risk for large-diameter thermoset curing. Distribution runs through airframe OEM direct contracts rather than airline-specified aftermarket channels, consolidating specification control with Boeing and Airbus engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket connector assembly refurbishment and MRO channel control represent expanding recurring-revenue layers growing faster than original hardware fabrication as aging commercial fleets face FAA 14 CFR Part 25 fire-smoke-toxicity replacement mandates.
For Market Incumbents: Fortify qualification heritage by deepening backward integration into titanium sponge sourcing through long-term offtake agreements with Russian and Chinese suppliers, insulating against export quota volatility. Expand captive composite autoclave capacity in France and Germany to meet EASA CS-25 Amendment 25-146 thermal resistance requirements without subcontracting delays. Channel control through military MRO networks sustains pricing power against emerging thermoplastic ducting substitutes. For New Entrants and Emerging Players: Lead with hybrid-electric thermal management liquid cooling loops for electric propulsion motors, a specification domain lacking incumbent qualification heritage and FAA Parts Manufacturer Approval barriers. India defense procurement under Hindustan Aeronautics Limited indigenization mandates offers the most penetrable geography, with Bangalore aerospace corridors attracting joint ventures for composite autoclave capacity. Pursue AS9100 certification paired with local BIS aerospace material approvals as the go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermoplastic composite processing equipment as Safran and Spirit AeroSystems qualify polyetherketoneketone ducts for single-aisle programs, favoring scaled manufacturers over fabrication job-shops. Acquisition target archetype: mid-cap specialists holding FAA Part Manufacturer Approval for proprietary connector designs with decade-long OEM production commitments. Watch AS9100 certification approval timelines as the signal for supply-constraint inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Autoclave Capacity Expansion | Addresses eighteen-to-twenty-four month equipment lead times constraining thermoset ducting supply for narrow-body programs. |
| Backward Integration into Titanium Sponge | Insulates fabricator margins from Russian and Chinese export quota volatility affecting aerospace-grade input costs. |
| Hybrid-Electric Thermal Management Qualification | Captures liquid cooling loop specifications for electric propulsion motors without incumbent FAA certification heritage. |
| Indian Defense Offset Partnership | Aligns with Hindustan Aeronautics Limited indigenization mandates under Ministry of Defence procurement policy. |
| Thermoplastic Processing Technology Investment | Compresses polyetherketoneketone duct fabrication cycle times from hours to minutes versus thermoset curing. |
Methodological Framework
Cross-validation between primary interviews with airframe OEM procurement directors, MRO channel managers, and composite fabrication engineers and secondary validation through FAA airworthiness directive filings, EASA CS-25 amendment records, and aerospace trade customs data anchors the qualitative findings. Bottom-up triangulation aggregates narrow-body final assembly line procurement volumes at Boeing Everett, Airbus Toulouse, and COMAC Shanghai Pudong with top-down validation against titanium sponge import statistics and thermoset autoclave capacity registrations.
Sensitivity analysis across the projection horizon tests forecast robustness to titanium sponge price volatility bands and composite adoption rate scenarios. The analytical framework models segmentation dimensions spanning material composition, application thermal severity, end-user procurement pattern, and installation type. CAGRs derive from installed base replacement cycles for aging commercial fleets and narrow-body production ramp rates. Industry-specific forecast inputs include EASA CS-25 Amendment 25-146 implementation timelines and sustainable aviation fuel compatibility testing protocols.
Forecasts assume regulatory continuity in FAA 14 CFR Part 25 and EASA CS-25 regimes; material policy shifts in fire-smoke-toxicity standards or SAF elastomer degradation requirements would require re-modeling. Specific risk factors include Russian titanium export restrictions, composite autoclave capacity bottlenecks, and hybrid-electric propulsion architecture delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
Aerostructures Market
Aircraft and Aerospace Components
High-Temperature Composite Exhaust and Thrust Reverser External Panels Market
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Europe Drone Motor Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aircraft Vertical Stabilizer Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market