
 Solenoid Valves in Aerospace Market | 2026-2036
Solenoid Valves in Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
Solenoid Valves in Aerospace Market Insights
The EU Green Deal's emissions targets for aviation is decoupling fleet renewal schedules from pure replacement cycles, forcing OEMs to specify lighter, more efficient valve architectures. Moog leverages its electro-hydraulic expertise to dominate flight control actuation channels. Eaton anchors military aftermarket demand through long-term sustainment contracts with the US Department of Defense. Valcor Engineering specializes in cryogenic and extreme-temperature valve designs for satellite propulsion systems.
Solenoid valves in aerospace are electromechanically operated flow control devices, typically constructed from stainless steel or titanium alloys with coil assemblies rated for continuous duty cycles, designed to manage fluid and gas routing in aircraft subsystems under vibration, thermal cycling, and pressure differentials up to several thousand psi. Pilot operated valves occupy the highest volume tier in fuel management applications where flow capacity exceeds direct acting limitations. Proportional technology variants represent the fastest-expanding segment as fly-by-wire architectures demand modulated flow control rather than binary on-off states. Electric technology leads installed base across commercial platforms, though electro-mechanical hybrids gain share in next-generation landing gear systems.
FAA certification under Part 33 and EASA's CS-E engine standards govern valve qualification timelines, while REACH compliance in Europe constrains material selections for seals and coil insulation. The US EPA and California Air Resources Board indirectly shape demand through emissions rules that accelerate fleet turnover. Stakeholders must monitor how emerging hydrogen propulsion architectures redefine valve sealing requirements and thermal operating envelopes.
Market Dynamics
The aerospace solenoid valve market is being fundamentally restructured by the migration from hydraulic to electromechanical actuation architectures, which compresses component counts while elevating qualification thresholds for surviving suppliers.
Growth Catalysts
- FAA Part 33 Certification Stringency:Tighter airworthiness directives for fuel system integrity are forcing fleet operators into accelerated replacement cycles, generating sustained aftermarket pull for qualified valve manufacturers.
- Commercial Narrow-Body Refresh:Boeing's supply chain ramp for next-generation single-aisle platforms is concentrating procurement volumes among Tier 1 aerostructures suppliers with established flight control integration capabilities.
- Proportional Valve Architectures:Fly-by-wire flight control systems are absorbing modulated flow control demands that binary on-off designs cannot satisfy, expanding addressable content per aircraft.
Market Restraints
- Titanium Alloy Input Volatility:Aerospace-grade Ti-6Al-4V billet pricing swings directly compress margin structures for valve housings and armature assemblies.
- US Supply Concentration:Boeing's Seattle-area procurement gravity and NASA's Marshall Space Flight Center propulsion programs create geographic dependency risk for non-US suppliers seeking qualification.
- Hydrogen Propulsion Uncertainty:Emerging cryogenic sealing requirements for H2 fuel systems threaten technical obsolescence of incumbent elastomer compounds qualified under existing jet-A specifications.
Strategic Opportunities
- EU Green Deal Aviation Mandates:Emissions-based fleet renewal schedules in France and Germany are decoupling replacement cycles from pure mechanical wear, creating regulatory-timed demand windows.
- Satellite Propulsion Cryogenics:Extreme-temperature valve designs for orbital maneuvering systems represent an adjacent application with divergent competitive dynamics from commercial aviation.
- Additive Manufacturing Convergence:Powder-bed fusion of cobalt-chrome coil housings with conventional CNC finishing is collapsing lead times for low-volume prototype qualification.
Industry Challenges
- Electromagnetic Interference Hardening:MIL-STD-461G certification for coil assemblies requires specialized test facilities with 18-month queue times at accredited US laboratories.
- Legacy Platform Documentation Gaps:Sustainment contracts for aging military airframes demand reverse-engineering of obsolete valve specifications where original design authority records have degraded.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solenoid Valves in Aerospace Market |
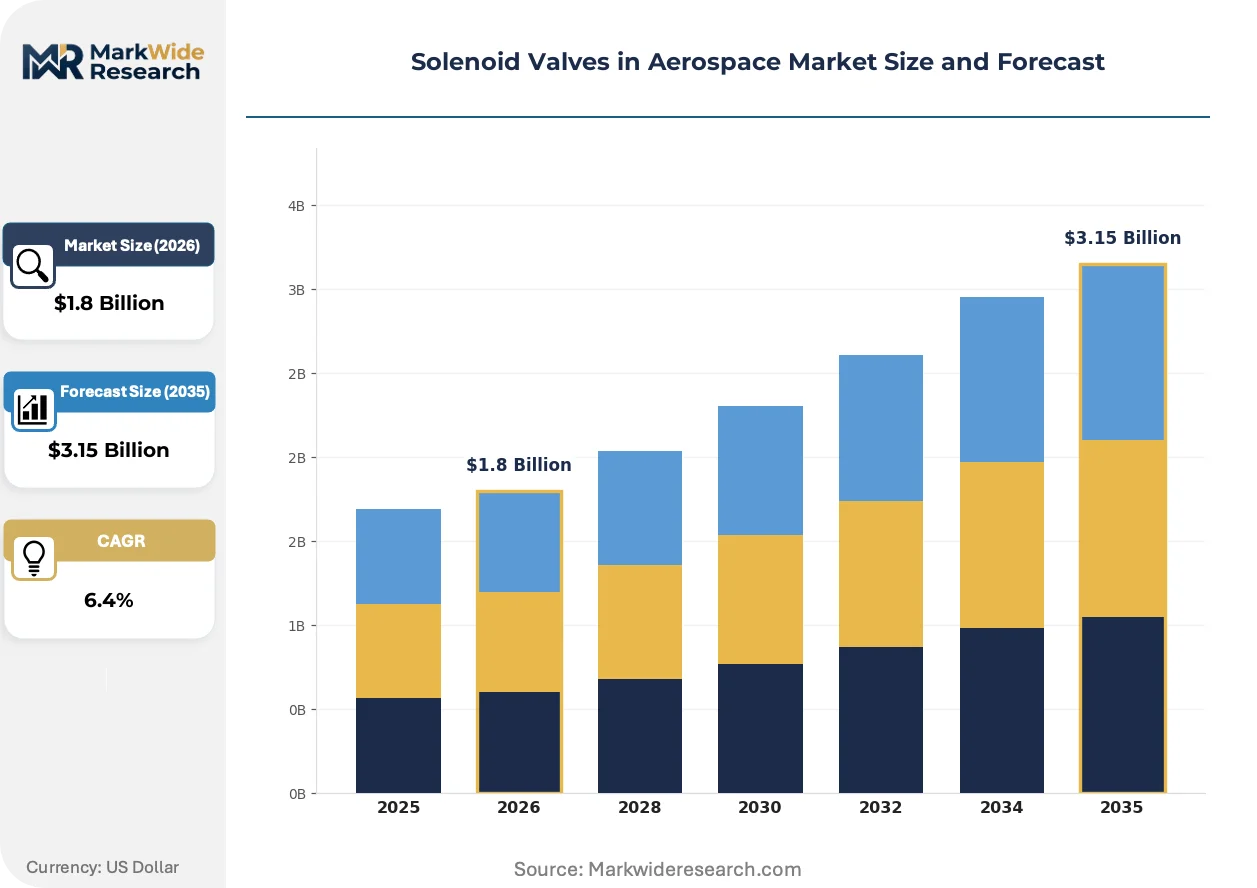
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Acting, Pilot Operated, Two-Way, Three-Way, Proportional Technology: Electric, Pneumatic, Hydraulic, Piezoelectric, Electro-Mechanical Application: Flight Control Systems, Fuel Management, Landing Gear, Cabin Air Management, Fire Suppression End User: Aircraft Manufacturers, Component Suppliers, Maintenance Providers, Defense Contractors |
| Companies Covered | Moog, ITT Aerospace Controls, The Lee Company, Marotta, Circor Aerospace, Valcor Engineering, Honeywell, G.W. Lisk Company, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solenoid Valves in Aerospace Market Trends and Innovations
Electrification of aircraft subsystems is compressing the addressable market for traditional hydraulic components while simultaneously expanding specification complexity for electromechanical replacements. Three interconnected developments are reshaping competitive positioning.
Proportional solenoid technology is absorbing the flow modulation requirements previously met by servo valves in primary flight control surfaces. Airbus and Boeing are specifying these architectures for spoiler actuation and thrust reverser deployment. The shift is compressing supplier margins on legacy binary designs while elevating engineering intensity for survivors.
REACH compliance in Europe is constraining seal compound selections for coil insulation and static face seals, forcing reformulation of qualified materials ahead of sunset dates for legacy phthalate plasticizers. ECHA's SVHC candidate list expansion is accelerating qualification timelines by 8-14 months for European-registered valve variants. Suppliers with captive polymer compounding capabilities are internalizing this regulatory burden as a competitive moat.
Airline procurement departments are consolidating vendor panels around integrated actuator-valve subsystems rather than discrete components. The unbundling of traditional Tier 2 supply relationships is visible most acutely in narrow-body programs where airframers demand single-source accountability for complete electromechanical actuation channels. This concentration is most advanced in US carrier fleet planning, where Southwest and United have pressed OEMs into long-term total cost of ownership contracts.
Solenoid Valves in Aerospace Market Segmentation
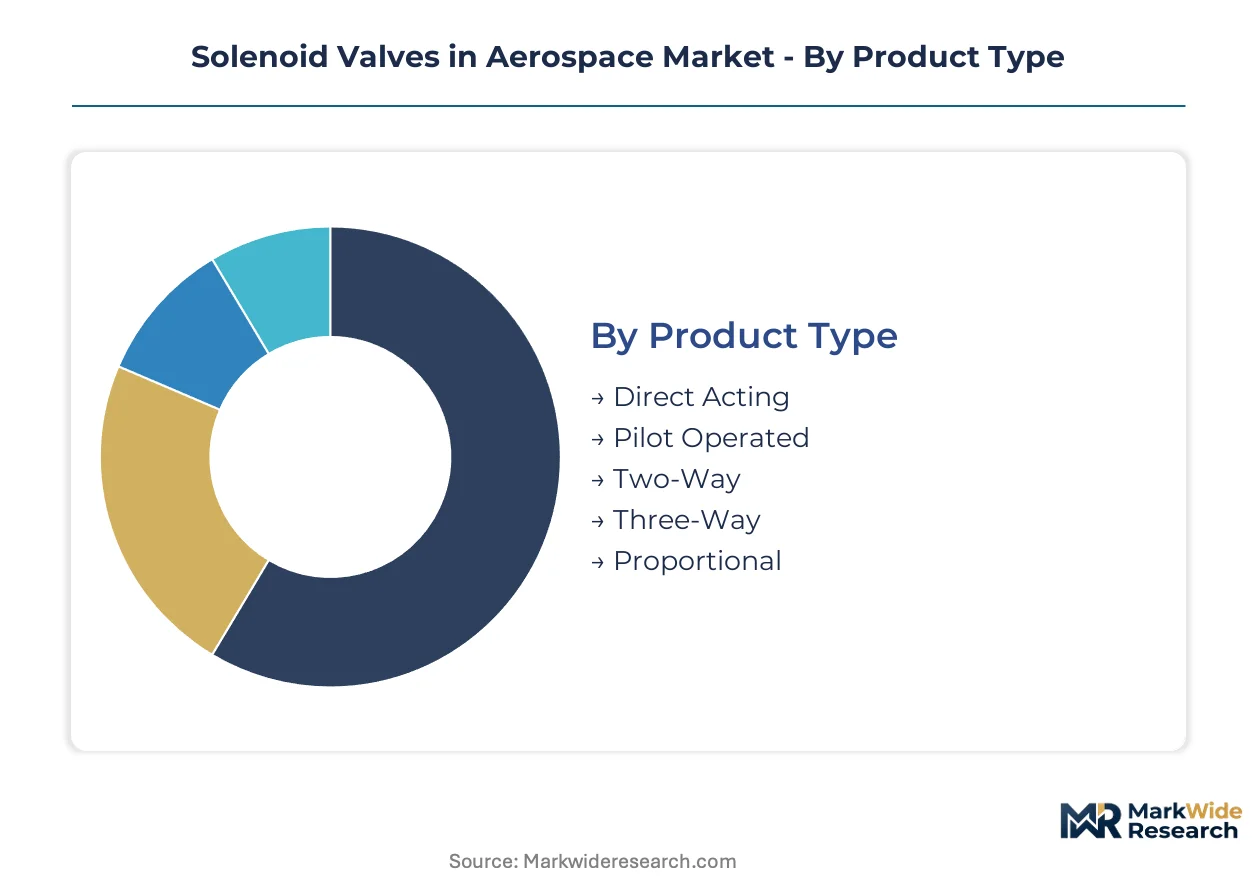
Aerospace solenoid valve procurement splits sharply between high-volume fuel system components and premium flight control architectures. Understanding where specification intensity concentrates versus where unit volumes dominate shapes supplier positioning and capability investments.
Product Type:
Pilot operated variants command the largest unit volumes in fuel management, while proportional designs capture the steepest specification premiums per installation.
- Pilot Operated:These valves use system pressure differentials to amplify solenoid force, enabling flow rates beyond direct-acting limits. Boeing's narrow-body supply chain and Airbus A320 family procurement anchor demand in high-cycle fuel transfer and engine feed applications where pressure ratings exceed 3,000 psi.
- Proportional:Continuous-position control replaces binary on-off states, delivering modulated flow for fly-by-wire surfaces. Thrust reverser actuation and spoiler deployment on next-generation platforms absorb these units as servo valve replacements, with FAA Part 33 certification timelines stretching 18-24 months.
- Direct Acting:Compact coil-armature assemblies suit low-flow, high-reliability niches in fire suppression and emergency shutoff circuits.
- Two-Way:Simple inlet-outlet configurations dominate cabin air management and auxiliary power unit fuel lines.
- Three-Way:Directional switching capability serves landing gear selector valves and hydraulic system mode transitions.
Today's leader: Pilot Operated. Tomorrow's challenger: Proportional.
Technology:
Electric architectures anchor installed base across commercial fleets, though hybrid electro-mechanical designs gain traction in weight-critical landing gear applications.
- Electric:Coil-driven armature movement delivers millisecond response times with no pneumatic or hydraulic infrastructure. Narrow-body OEM specifications favor these for fuel metering and bleed air control, with EASA CS-E engine standards governing electromagnetic compatibility hardening.
- Electro-Mechanical:Integrated motor-screw mechanisms replace hydraulic cylinders in brake and steering actuators. Boeing's 787 program pioneered these for primary flight controls, and next-generation single-aisle platforms are expanding specification.
- Hydraulic:Pressure-assisted actuation persists in heavy-lift military transports and legacy wide-body platforms where retrofit economics delay electrification.
- Pneumatic:Compressed air power suits engine anti-ice and environmental control systems with available bleed air.
- Piezoelectric:Ceramic stack actuation enables nanometer-precision positioning for fuel injector timing in small-engine propulsion.
Electric technology retains volume dominance. Electro-mechanical variants are climbing the fastest as airframers delete hydraulic distribution systems.
Application:
Fuel management absorbs the highest unit volumes, while flight control systems concentrate the most demanding qualification requirements.
- Fuel Management:Tank transfer, engine feed, and refuel/defuel circuits demand fire-resistant sealing and FAA-certified fail-safe positions. Commercial fleet refresh cycles in the United States drive replacement demand as airlines comply with updated airworthiness directives on fuel system integrity.
- Flight Control Systems:Primary surface actuation and autopilot servo loops require MIL-STD-461G electromagnetic interference certification. Proportional valve content per aircraft is expanding as spoiler and slat mechanisms convert from hydraulic to electromechanical architectures.
- Landing Gear:Brake control, steering, and door sequencing favor electro-mechanical hybrids for weight reduction on extended-range platforms.
- Cabin Air Management:Temperature control and pressurization valves prioritize compact envelope dimensions over extreme pressure ratings.
- Fire Suppression:Rapid-discharge halon and successor agent systems use specialized high-speed direct-acting designs with explosive actuator backups.
Fuel Management generates the most units. Flight Control Systems deliver the highest content value per shipset.
End User:
Aircraft manufacturers concentrate specification authority, while maintenance providers fragment into airline-operated shops and independent MRO networks.
- Aircraft Manufacturers:Boeing, Airbus, and emerging regional jet programs hold design authority and vendor qualification gates. Their supply chain consolidation around integrated actuator-valve subsystems is compressing Tier 2 supplier margins while elevating engineering accountability requirements.
- Defense Contractors:Long-term sustainment contracts with the US Department of Defense anchor aftermarket demand for legacy military airframes. Reverse-engineering of obsolete specifications dominates procurement where original design records have degraded.
- Component Suppliers:Tier 2 aerostructures integrators source discrete valves for assembly into larger hydraulic or fuel system modules.
- Maintenance Providers:FAA-certified repair stations and airline technical operations execute fleet replacement cycles driven by airworthiness directive compliance timelines.
Aircraft Manufacturers control specification. Defense Contractors secure the most predictable long-term revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace solenoid valve manufacturing traces its industrial lineage to post-war American aviation clusters, where precision hydraulics expertise migrated from military aircraft programs into commercial supply chains. This foundation established qualification protocols and metallurgical standards that persist across global procurement networks today. Contemporary demand distributes across manufacturing centers in North America, Europe, and Asia-Pacific, each shaped by distinct regulatory frameworks and OEM supply chain configurations.
United States
Boeing's Seattle-area procurement gravity and NASA's Marshall Space Flight Center propulsion programs concentrate specification authority and qualification testing capacity. FAA Part 33 certification timelines govern valve approval for fuel system integrity, with airworthiness directives driving fleet replacement cycles among domestic carriers. The aerospace corridor spanning Washington state and southern California hosts Tier 1 integrators with established flight control system partnerships.
France
Airbus Toulouse operations anchor European narrow-body and wide-body assembly, with procurement specifications cascading to valve suppliers through aerostructures integrators. EASA CS-E engine standards and REACH compliance constrain material selections for seals and coil insulation, extending qualification timelines for European-registered variants. The Occitanie region maintains specialized test facilities for electromagnetic interference hardening under MIL-STD-461G protocols.
Germany
EU Green Deal aviation mandates are decoupling fleet renewal schedules from pure mechanical wear, creating regulatory-timed demand windows for emissions-compliant valve architectures. The country's national aerospace regulator enforces EASA certification requirements while federal economic programs support additive manufacturing convergence for prototype qualification. Bavaria's precision engineering clusters supply CNC finishing capabilities for powder-bed fusion components.
United Kingdom
Rolls-Royce Derby operations and BAE Systems military programs sustain demand for cryogenic and extreme-temperature valve designs in satellite propulsion applications. The Civil Aviation Authority implements EASA-aligned certification standards with additional national requirements for defense export controls. Midlands-based aerostructures suppliers maintain legacy platform documentation for sustainment contracts where original design authority records have degraded.
Japan
METI industrial policy directs aerospace supply chain development through partnerships with Boeing and Airbus Tier 2 networks, emphasizing weight-reduction technologies for next-generation single-aisle platforms. JIS standards govern material specifications for titanium alloy valve housings, with domestic chemical processors supplying aerospace-grade Ti-6Al-4V billet. The Nagoya aerospace cluster integrates valve procurement into regional composite wing and fuselage assembly operations.
Solenoid Valves in Aerospace Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and integration depth, with qualification timelines creating structural barriers that protect incumbent positions. The supplier base concentrates around electromechanical system integrators with captive valve design capabilities, while discrete component manufacturers face margin compression from OEM vendor panel consolidation. Three archetypes dominate: flight control system integrators with electro-hydraulic expertise, military sustainment contractors with long-term service agreements, and cryogenic specialists for satellite propulsion niches. Competitive dynamics center on strategic partnerships for fly-by-wire program qualification and backward integration into polymer compounding for REACH-compliant seal materials.
Among American-based suppliers, Moog and Eaton occupy positions within the flight control and military aftermarket archetypes respectively, while Valcor Engineering exemplifies the cryogenic specialization tier. ITT Aerospace Controls and Circor Aerospace represent diversified industrial conglomerates with aerospace valve portfolios, sitting within scale-driven competitive segments. The Lee Company and Marotta anchor precision miniature valve supply for fuel management applications, with Honeywell spanning multiple archetypes through integrated avionics and actuation system offerings. G.W. Lisk Company maintains a position within electromagnetic component supply for coil assembly subsystems.
| Leading Market Players |
|---|
| Moog |
| ITT Aerospace Controls |
| The Lee Company |
| Marotta |
| Circor Aerospace |
| Valcor Engineering |
| Honeywell |
| G.W. Lisk Company |
| Eaton |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's aviation emissions mandates gate both qualified supply and premium-tier pricing access, as REACH-compliant seal compounds and EASA-certified electromagnetic hardening create dual qualification barriers that only incumbent suppliers with captive polymer compounding can clear. OEM procurement consolidation around integrated actuator-valve subsystems compresses Tier 2 margins while elevating engineering accountability premiums for survivors with flight control integration capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates flight control system integrators from fuel management component suppliers from aftermarket sustainment contractors. Price differentiation rests on FAA Part 33 certification grade and volume scale, with proportional valve architectures commanding specification premiums over binary on-off designs. Cost compression in standard-tier fuel system components is intensifying because Boeing's vendor panel consolidation forces discrete valve manufacturers into price-competitive bidding for narrow-body platform content. Airline procurement departments exhibit the highest price sensitivity, while defense sustainment contractors accept cost-plus structures for reverse-engineered legacy platform documentation.
Supply Chain Analysis
Freight cost volatility for aerospace-grade Ti-6Al-4V billet from US and Japanese titanium processors amplifies margin pressure on valve housing and armature assembly production. Supply concentration in the United States, France, and Germany draws from precision machining clusters with legacy military aviation heritage, with raw material dependencies on titanium alloy feedstock, cobalt-chrome powder for additive manufacturing, and REACH-compliant fluorocarbon seal compounds. Single-source vulnerability persists in electromagnetic interference test facilities, where MIL-STD-461G certification queues at accredited US laboratories create 18-month bottlenecks. Distribution runs through Boeing's Seattle-area procurement gravity and Airbus Toulouse aerostructures integrators, with Tier 1 system houses consolidating discrete component sourcing into integrated actuator-valve subsystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story, as the migration from hydraulic to electromechanical actuation architectures forces fleet operators toward premium-specification proportional valves that binary designs cannot satisfy. The addressable content per aircraft is expanding for qualified suppliers while compressing for commodity component manufacturers.
For Market Incumbents: Lock in long-term sustainment contracts with the US Department of Defense before reverse-engineering capabilities degrade further, and deepen backward integration into REACH-compliant polymer compounding to internalize regulatory burden as competitive moat against emerging entrants lacking captive seal material qualification. Hydrogen propulsion uncertainty threatens technical obsolescence of incumbent elastomer compounds, making cryogenic sealing R&D investment the critical defensive lever. For New Entrants and Emerging Players: Begin with satellite propulsion cryogenics, where extreme-temperature valve designs for orbital maneuvering systems present divergent competitive dynamics from the consolidated commercial aviation supply chain dominated by Moog and Eaton. Additive manufacturing convergence for powder-bed fusion coil housings offers a go-to-market angle to collapse prototype qualification lead times against incumbent CNC-dependent workflows. For Investors and Strategic Acquirers: Roll-up economics work for cryogenic specialization archetypes because satellite propulsion and emerging hydrogen fuel system architectures demand valve sealing capabilities that sit outside incumbent commercial aviation competency centers. The five-to-ten year viability window favors targets with MIL-STD-461G test facility access or captive electromagnetic hardening capabilities. Watch FAA airworthiness directive acceleration timelines as the inflection signal indicating aftermarket replacement cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH-compliant seal formulation internalizes ECHA regulatory burden as competitive moat. |
| Electromagnetic Interference Test Facility Accreditation | MIL-STD-461G certification capacity captures 18-month queue bottleneck value. |
| Cryogenic Valve Architecture Development | Hydrogen propulsion and satellite propulsion open adjacent premium-margin application tiers. |
| Long-term Sustainment Contract Structuring | US Department of Defense agreements anchor predictable revenue through fleet lifecycle. |
| Additive Manufacturing Process Qualification | Powder-bed fusion of cobalt-chrome coil housings collapses prototype lead times. |
Research Methodology
Multiple input streams — primary interviews with flight control system engineers, procurement directors at Tier 1 aerostructures integrators, and aftermarket sustainment managers at FAA-certified repair stations; secondary validation through EASA CS-E engine standards documentation, FAA Part 33 certification databases, and REACH compliance filings — were reconciled through bottom-up unit-volume modeling and top-down market sizing triangulation.
Data-stream reconciliation across the projection horizon applied analytical frameworks segmented by valve architecture type, technology platform, application subsystem, and end-user procurement authority, with CAGRs derived from fleet refresh cycle modeling and airworthiness directive compliance timelines. Boeing narrow-body supply chain ramp rates and NASA Marshall Space Flight Center propulsion program procurement disclosures informed aerospace-specific forecast inputs.
Caveats apply where titanium alloy input volatility, hydrogen propulsion architecture shifts, or electromagnetic interference test facility capacity constraints could materially shift the outlook for qualified supplier margins and replacement cycle timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Aircraft Gearbox Market
Aircraft and Aerospace Components
Aerostructures Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Liquid Rocket Engine Market
Aircraft and Aerospace Components
Commercial Aircraft Turbine Blades and Vanes Market