
 Aerospace Pressure Bulkheads Market | 2026-2036
Aerospace Pressure Bulkheads Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Pressure Bulkheads Market Analysis
Composite-to-metal hybrid fabrication is tilting how pressure bulkheads achieve weight reduction without sacrificing fatigue performance. Airbus Group leverages its integrated aerostructures capability to control composite bulkhead design cycles from concept to certification. Spirit AeroSystems anchors North American supply for large commercial programs through dedicated tooling and long-term OEM contracts. Triumph Group differentiates in aftermarket conversion and repair, sustaining revenue through MRO service partnerships.
Aerospace pressure bulkheads are reinforced structural barriers sealed to maintain cabin pressurization differential, typically fabricated from aluminum alloys, carbon fiber-reinforced polymers, or titanium depending on aircraft size and mission profile. Metal bulkheads retain dominance in narrow-body retrofits and military platforms where impact resistance and repairability outweigh weight penalties. Composite bulkheads command expanding share in next-generation wide-bodies, where carbon fiber layups deliver specific strength advantages that translate directly into fuel burn reduction. Hybrid bulkheads occupy an emerging niche, blending metallic frames with composite skins to balance certification familiarity with performance gains.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements govern damage tolerance, lightning strike protection, and fatigue life validation for pressure bulkhead installations. ISO 9100 quality management and NADCAP accreditation for special processes constrain supplier qualification, filtering market access toward vertically capable manufacturers. OEMs and tier-one suppliers must monitor evolving EPA and REACH restrictions on hexavalent chromium surface treatments and certain resin chemistries. Stakeholders should weigh material substitution timelines against requalification costs as sustainability mandates penetrate aerospace supply chain contracting.
Market Dynamics
Composite-intensive pressure bulkhead designs are compressing qualification cycles as FAA and EASA tighten damage tolerance protocols, forcing suppliers to front-load certification investment before production contracts materialize.
Growth Catalysts
- FAA Part 25 Damage Tolerance Standards:Stricter fatigue life validation requirements are filtering supplier pools toward vertically integrated manufacturers with captive NADCAP-accredited testing facilities.
- Narrow-Body Fleet Renewal:Airlines retiring aging Boeing 737NG and Airbus A320ceo aircraft are specifying lighter composite bulkhead configurations for replacement programs.
- Carbon Fiber Layup Automation:Fiber placement robotics are reducing unit labor hours and improving ply consistency for complex double-curvature bulkhead geometries.
Market Restraints
- Titanium Input Cost Volatility:Sponge titanium price swings are compressing margins on legacy metallic bulkhead programs that retain military platform specifications.
- Hexavalent Chromium REACH Restrictions:ECHA's tightening limits on chromate conversion coatings are forcing surface treatment requalification across European supply chains.
- Aluminum-Lithium Substitution Ceiling:Third-generation Al-Li alloys have plateaued in specific strength gains, limiting further metal bulkhead weight reduction without hybrid architectures.
Strategic Opportunities
- Urban Air Mobility Pressurized Cabins:eVTOL developers are specifying miniaturized bulkhead designs that leverage transferrable composite expertise from commercial aviation.
- India PLI Scheme for Aerostructures:Domestic content requirements for Boeing and Airbus offset programs are creating greenfield manufacturing incentives for tier-one suppliers.
- Digital Thread Certification:Model-based definition and virtual testing protocols are collapsing physical prototype iterations for damage tolerance demonstrations.
Industry Challenges
- Composite Repair Technician Scarcity:Airlines and MRO providers face shortages of inspectors qualified to SRM-compliant scarf repair procedures for CFRP bulkhead damage.
- Lightning Strike Protection Integration:Embedding conductive mesh without compromising fatigue performance requires iterative testing that extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Pressure Bulkheads Market |
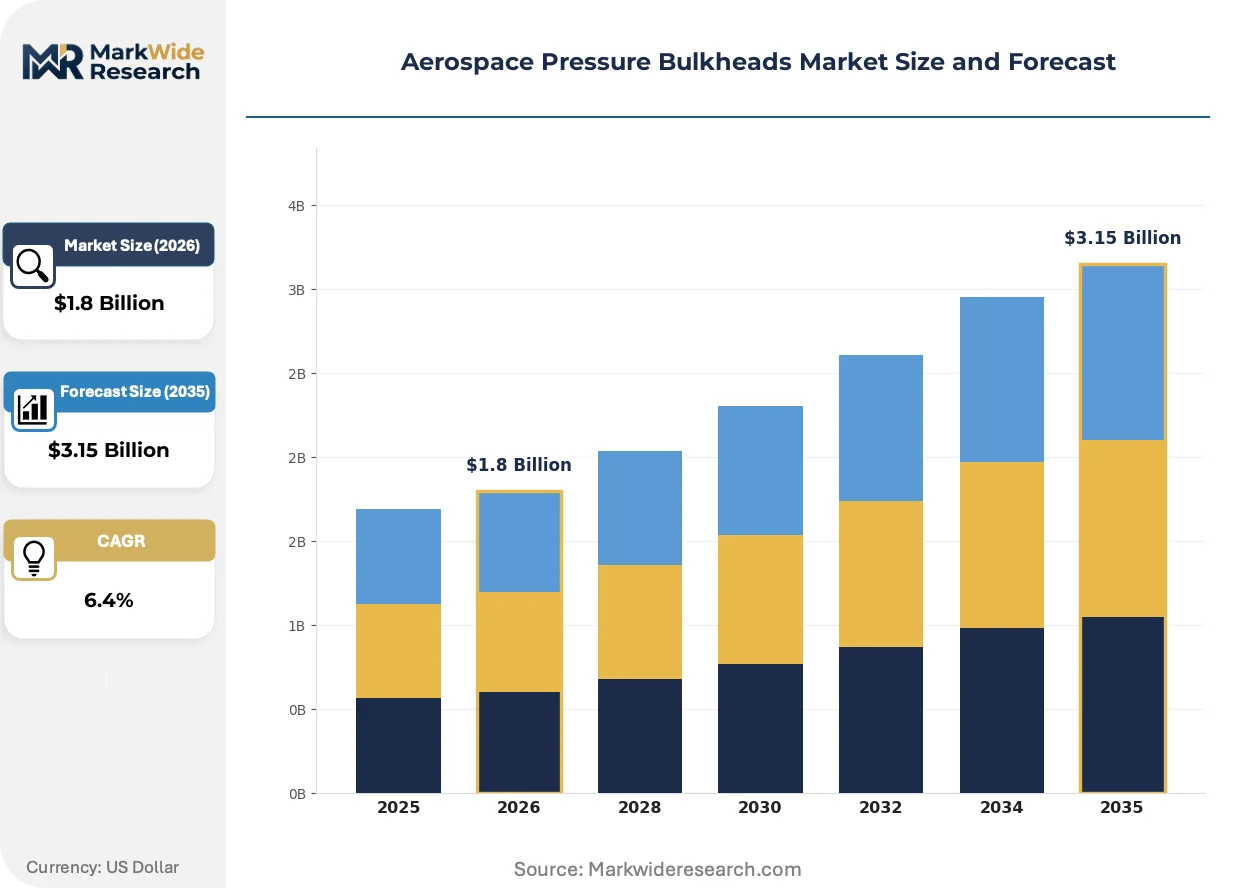
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Bulkheads, Composite Bulkheads, Hybrid Bulkheads, Transparent Bulkheads Application: Commercial Aircraft, Military Aircraft, Spacecraft, UAVs Material: Aluminum, Carbon Fiber, Steel, Titanium End User: Aerospace Manufacturers, Defense Contractors, MRO Service Providers, OEMs |
| Companies Covered | Aernnova Aerospace, Airbus Group, Spirit AeroSystems, Kawasaki Heavy Industries, Bombardier Inc., RUAG Holding AG, The Boeing Company, Triumph Group, Premium AEROTEC GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Pressure Bulkheads Market Emerging Trajectories
Automated fiber placement and out-of-autoclave curing are collapsing traditional manufacturing bottlenecks while regulatory digitization compresses certification timelines for novel material systems.
Thermoplastic composite bulkheads are collapsing the processing cost gap with thermoset alternatives. Airbus A350 follow-on programs are evaluating PEEK and PPS matrices for improved damage tolerance and weldability. The shift is collapsing repair cycle times and enabling in-service thermoplastic welding rather than bolted repairs.
EASA's evolving CS-25 Special Condition framework for novel materials is accelerating qualified alternative pathways. Manufacturers can now pursue equivalent safety demonstrations through analysis rather than full-scale fatigue testing. European wide-body programs are exploiting this regulatory latitude to compress certification schedules for hybrid bulkhead architectures.
Airline procurement teams are consolidating supplier relationships around full aerostructure modules rather than discrete bulkhead components. Boeing's 787 and 777X programs have normalized shipset contracting that bundles pressure bulkheads with adjacent barrel sections. North American carriers are driving this consolidation furthest, pressuring tier-two specialists to integrate into larger aerostructure packages or exit the market.
Aerospace Pressure Bulkheads Market Segmentation
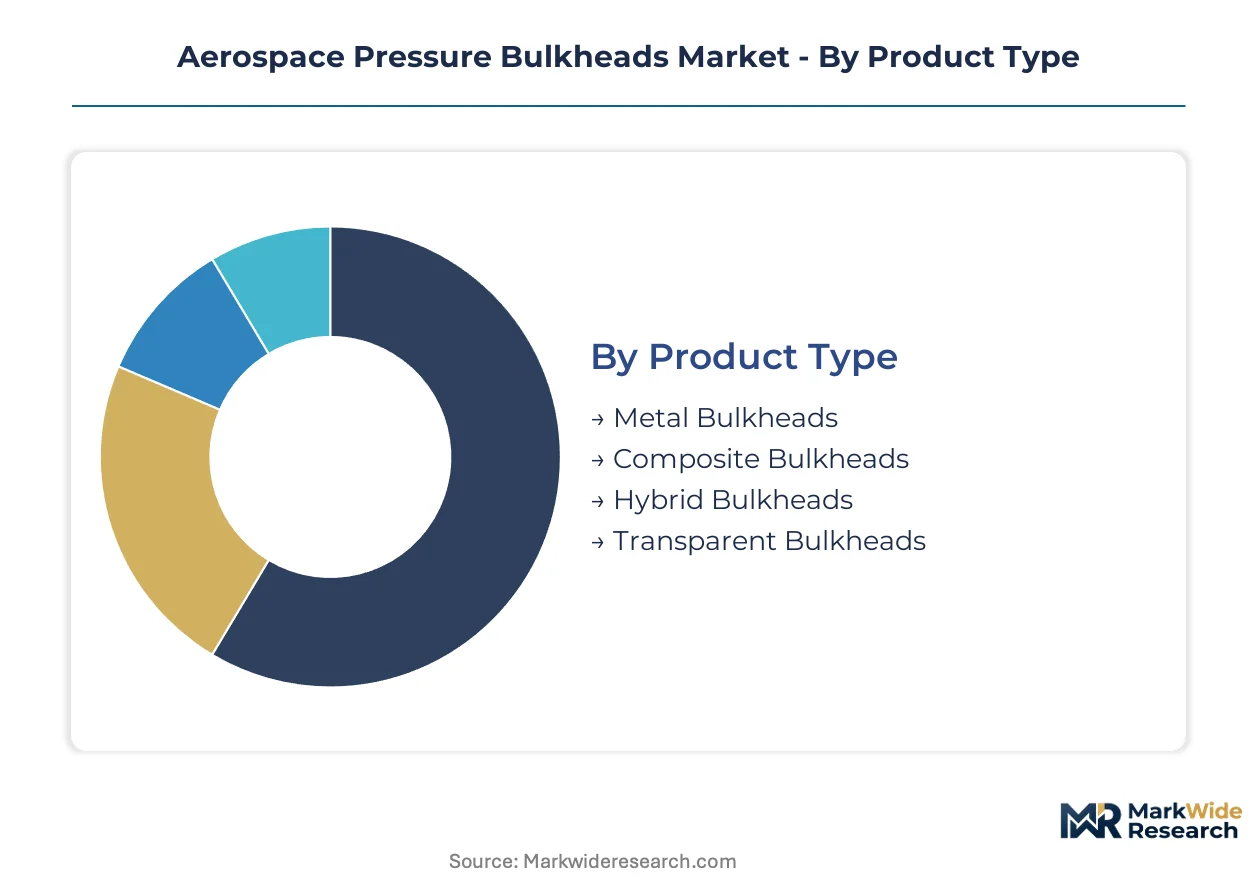
Pressure bulkhead segmentation reveals how material choices, platform requirements, and supply chain roles fragment procurement strategies across aerospace programs. Each dimension carries distinct certification burdens and margin structures that shape supplier positioning.
Product Type:
Cost tier separates legacy metallic fabrication from advanced composite systems and emerging hybrid architectures.
- Metal Bulkheads:Aluminum alloy and titanium stampings dominate narrow-body retrofits and military platforms where impact resistance and field repairability outweigh weight penalties. Boeing 737MAX and Airbus A320neo line-fit programs in the United States absorb substantial volumes as airlines prioritize proven damage tolerance over marginal fuel savings.
- Composite Bulkheads:Carbon fiber-reinforced polymer layups deliver specific strength advantages that translate directly into fuel burn reduction for wide-body programs. Airbus A350 and Boeing 787 shipsets specify these configurations, with automated fiber placement collapsing unit labor hours for complex double-curvature geometries.
- Hybrid Bulkheads:Metallic frames bonded to composite skins balance certification familiarity with performance gains, occupying an emerging niche in next-generation narrow-body development.
- Transparent Bulkheads:Polycarbonate and acrylic pressure barriers serve specialized observation and VIP cabin applications in business jets.
Metal bulkheads hold installed capacity across the in-service fleet. Composite bulkheads are rotating up the share rankings in new program specifications.
Application:
Platform mission profiles dictate pressure differential requirements, cycle counts, and crashworthiness standards that cascade into material selection.
- Commercial Aircraft:Narrow-body and wide-body programs generate volume concentration, with fleet renewal cycles in the United States driving specification shifts toward lighter configurations. FAA Part 25 damage tolerance protocols filter supplier pools toward vertically capable manufacturers.
- Military Aircraft:Fighter and transport platforms retain metallic bulkhead specifications where ballistic tolerance and battle damage repairability override weight optimization. Titanium input cost volatility compresses margins on legacy programs.
- Spacecraft:Crew and cargo modules require ultra-high reliability seals with minimal outgassing, commanding premium qualification cycles.
- UAVs:Unmanned platforms tolerate higher risk profiles, enabling faster adoption of thermoplastic composite alternatives.
Commercial aircraft anchors procurement volume. Spacecraft applications are climbing the fastest on a percentage basis from low bases.
Material:
Specific strength and processing economics divide the supply base between mature metal systems and advancing polymer matrices.
- Aluminum:Third-generation aluminum-lithium alloys have plateaued in weight reduction gains, limiting further metal bulkhead optimization without hybrid architectures. Narrow-body retrofits in the United States sustain demand.
- Carbon Fiber:Automated layup and out-of-autoclave curing are collapsing processing cost gaps with metallic alternatives, expanding addressable market share.
- Steel:High-strength alloys serve specialized military and space applications requiring extreme toughness.
- Titanium:Sponge price swings compress margins on legacy programs; REACH restrictions on hexavalent chromium surface treatments force European supply chain requalification.
Aluminum retains broadest installed base. Carbon fiber is gaining share fastest in new program awards.
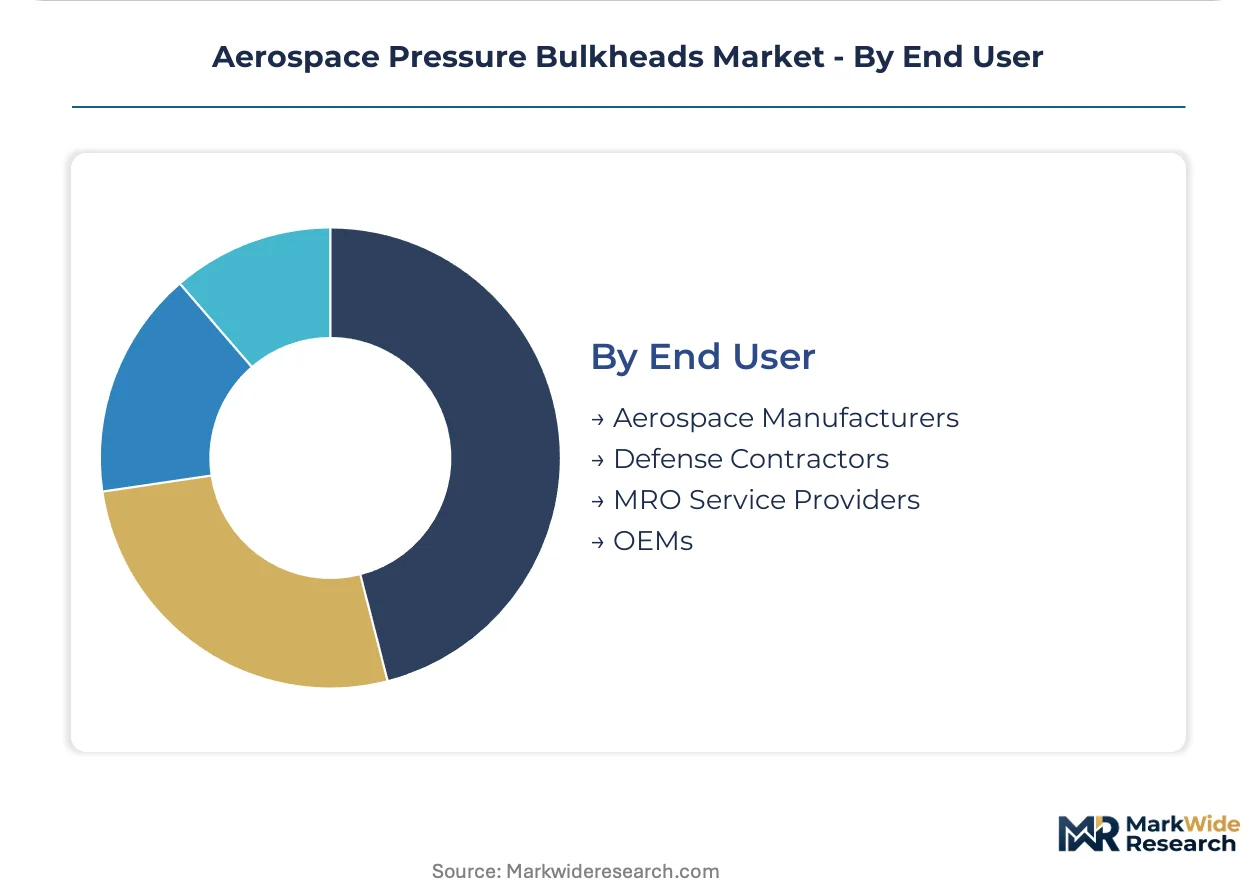
End User:
Customer type determines contract structure, from long-term OEM shipset agreements to spot MRO procurement.
- Aerospace Manufacturers:Boeing and Airbus anchor demand through shipset contracting that bundles bulkheads with adjacent barrel sections, consolidating supplier relationships around full aerostructure modules.
- Defense Contractors:Lockheed Martin and Northrop Grumman specify military-grade metallic configurations with extended qualification horizons.
- MRO Service Providers:Airlines and independent repair stations face composite technician scarcity, sustaining revenue for specialists with SRM-compliant scarf repair capabilities.
- OEMs:Tier-one aerostructure suppliers pursue backward integration into bulkhead fabrication to defend margin position in consolidated procurement.
Aerospace manufacturers concentrate forward demand. MRO service providers are rotating up the share rankings as fleet age extends retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airlines and defense procurement offices concentrate bulkhead demand in manufacturing clusters anchored by final assembly lines and tier-one aerostructure facilities. Boeing and Airbus anchor regional procurement patterns through shipset contracting that bundles pressure bulkheads with adjacent fuselage sections.
United States
Boeing's 737MAX and 777X programs in Renton and Everett absorb substantial composite and metallic bulkhead volumes through long-term supplier agreements. FAA Part 25 damage tolerance protocols filter supplier pools toward vertically capable manufacturers with captive NADCAP-accredited testing facilities. Wichita, Kansas anchors Spirit AeroSystems fabrication activity for large commercial programs.
Germany
Airbus Group's integrated aerostructures capability in Hamburg and Bremen controls composite bulkhead design cycles from concept to EASA CS-25 certification. REACH restrictions on hexavalent chromium surface treatments force supply chain requalification across Bavarian and North Rhine-Westphalian manufacturing networks. Premium AEROTEC GmbH exemplifies the tier-one positioning of German fabricators.
France
Airbus final assembly in Toulouse drives specification shifts toward carbon fiber-reinforced polymer layups for A350 wide-body programs. EASA's evolving CS-25 Special Condition framework accelerates qualified alternative pathways for novel material systems. The Occitanie region concentrates composite research activity linked to university engineering clusters.
Japan
Kawasaki Heavy Industries anchors domestic supply for Boeing 787 shipsets through technology licensing and joint development agreements. METI industrial policy supports carbon fiber precursor manufacturing in the Chubu region around Nagoya. Japanese suppliers occupy specialized positions in automated fiber placement equipment and quality systems.
United Kingdom
BAE Systems and Airbus UK operations in Bristol and Broughton sustain metallic bulkhead demand for military platforms and narrow-body retrofits where impact resistance outweighs weight optimization. The UK's national aerospace regulator enforces damage tolerance validation aligned with EASA frameworks. Northern England maintains legacy aluminum fabrication capacity for defense programs.
Aerospace Pressure Bulkheads Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply positions. OEMs with captive aerostructures divisions consolidate procurement around full shipset modules, filtering tier-two specialists toward integration or exit. Three archetypes dominate: integrated OEM divisions, tier-one aerostructure suppliers with backward integration into bulkhead fabrication, and aftermarket repair specialists with SRM-compliant capabilities. Competitive moves center on long-term shipset contracting and qualification investment pre-production.
Among integrated OEM divisions, Airbus Group and The Boeing Company represent the channel-controlling archetype through bundled procurement. Spirit AeroSystems and Triumph Group exemplify tier-one positioning—Spirit through dedicated tooling for large commercial programs, Triumph through MRO service partnerships sustaining retrofit revenue. Aernnova Aerospace and RUAG Holding AG occupy specialized fabrication positions serving regional programs and military platforms respectively.
| Leading Market Players |
|---|
| Aernnova Aerospace |
| Airbus Group |
| Spirit AeroSystems |
| Kawasaki Heavy Industries |
| Bombardier Inc. |
| RUAG Holding AG |
| The Boeing Company |
| Triumph Group |
| Premium AEROTEC GmbH |
| Others |
Supply Flow & Price Mechanics
The Trans-Pacific air freight corridor's rate volatility directly shapes how tier-one suppliers calibrate cost-plus indexation clauses for Boeing and Airbus shipset contracts, concentrating pricing power among vertically capable manufacturers while fragmenting tier-two margins across certification-grade tiers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation dominate narrow-body retrofits, while carbon fiber prepreg agreements tether to Toray and Hexcel pricing schedules. Price differentiation separates FAA-certified composite configurations from metallic alternatives lacking damage tolerance documentation. Pricing pressure stems from titanium sponge volatility on legacy military programs, compressing margins for suppliers without backward integration into raw material sourcing. Defense contractors exhibit lowest price sensitivity due to extended qualification horizons, whereas regional airline MRO procurement teams drive hardest bargain negotiations on spot repair contracts.
Supply Chain Analysis
Upstream feedstock concentration in Japanese carbon fiber precursor manufacturing and Russian sponge titanium extraction anchors tier-one supplier cost structures. Raw material dependencies span Toray T800S intermediate modulus fiber, Huntsman aerospace-grade epoxy resin systems, and Allegheny Technologies titanium billet. Single-source vulnerability permeates the qualified supplier base for NADCAP-accredited heat treatment processes. Distribution runs through Boeing's shipset contracting model that bundles pressure bulkheads with Spirit AeroSystems fuselage barrel sections, filtering tier-two specialists toward integration or exit.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity defines this market as eVTOL cabin pressurization requirements proliferate, creating specialized niches for miniaturized bulkhead configurations that transfer composite expertise from commercial aviation platforms.
For Market Incumbents: Harden qualification investment moats by accelerating NADCAP accreditation for out-of-autoclave thermoplastic processing before EASA CS-25 Special Condition pathways mature. Deepen captive supply of carbon fiber layup robotics to offset labor hour compression from automated fiber placement adoption. Threats from urban air mobility entrants with clean-sheet thermoplastic designs demand preemptive certification lock-in on next-generation narrow-body programs.
For New Entrants and Emerging Players: India's underpenetrated aerostructure fabrication base offers white-space positioning through Boeing and Airbus offset program localization under the PLI scheme. Target thermoplastic composite repair capabilities where SRM-compliant technician scarcity sustains premium pricing. Go-to-market leverage rests on digital thread certification partnerships that collapse physical prototype iterations for damage tolerance demonstrations.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors tier-one aerostructure suppliers with backward integration into bulkhead fabrication and captive NADCAP testing facilities. Long-term viability across the projection horizon hinges on qualification asset ownership rather than discrete component manufacturing. Acquisition archetype: European fabricators with EASA CS-25 certification track records and thermoplastic welding IP. Signal to watch: Airbus A350 follow-on program material specifications for PEEK and PPS matrix adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Composite Qualification | EASA CS-25 Special Condition pathways enable equivalent safety demonstrations through analysis rather than full-scale fatigue testing. |
| Automated Fiber Placement Scale-Up | Robotics adoption collapses unit labor hours for complex double-curvature bulkhead geometries on Boeing 787 and A350 programs. |
| Digital Thread Certification Investment | Model-based definition protocols reduce physical prototype iterations for FAA Part 25 damage tolerance demonstrations. |
| Urban Air Mobility Cabin Partnership | eVTOL developers leverage transferrable composite expertise from commercial aviation for miniaturized pressurized cabin designs. |
| India Manufacturing Localization | PLI scheme incentives create greenfield capacity for Boeing and Airbus offset program domestic content requirements. |
Methodological Framework
Initial hypotheses were tested against primary input from aerostructure procurement executives, FAA certification engineers, airline fleet planning directors, and composite repair station managers, then refined against secondary validation from FAA Part 25 airworthiness directive filings, EASA CS-25 certification databases, NADCAP special process audit records, and OEM shipset contracting disclosures. Bottom-up build-ups from individual program specifications triangulated against top-down aerospace production forecasts.
Demand-supply balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions spanning material type, platform application, end-user contract structure, and regional regulatory cluster. CAGRs derived from production rate assumptions for Boeing 737MAX, 777X, and Airbus A320neo, A350 programs, cross-referenced against fleet age demographics driving retrofit cycle timing. Industry-specific inputs incorporated titanium sponge price index trajectories and carbon fiber capacity expansion announcements from Toray and Hexcel.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed aerostructure entrants or accelerated thermoplastic adoption by Airbus would shift outcomes beyond modeled ranges. Cross-checking against Boeing and Airbus published production rate guidance is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Altimeter Market