
 Altimeter Market | 2026-2036
Altimeter Market Size, Share, and Industry Trends Forecast 2026-2036
Altimeter Market Analysis
China is reconfiguring altimeter supply chains through expanded avionics manufacturing clusters in Shanghai and Xi'an. Honeywell International leverages its integrated flight deck portfolios to sustain long-term contracts with Boeing and Airbus. Collins Aerospace anchors its position through proprietary radar altimeter architectures deployed across military and commercial platforms. Thales Group competes in the European defense segment with software-integrated altimeter systems for fighter aircraft upgrades.
An altimeter measures vertical distance above a reference point, typically employing barometric pressure differentials, radio wave reflection, laser time-of-flight, or satellite triangulation with precision thresholds ranging from feet to centimeters depending on application. The device serves as critical flight instrumentation for terrain clearance, approach guidance, and autopilot coupling in aviation operations. Radar altimeters command the premium product tier due to mandatory fitment on transport-category aircraft and helicopter terrain awareness systems, while GPS altimeters gain traction in land surveying and unmanned aerial vehicle navigation where cost sensitivity outweighs aviation-grade certification burdens. Digital technology architectures now dominate new installations as analog systems face obsolescence in regulated aviation environments, though hybrid configurations persist in marine applications where redundancy requirements favor dual-mode instrumentation.
FAA airworthiness directives on radar altimeter susceptibility to wireless interference have reshaped certification timelines and retrofit obligations for US-registered fleets. EASA parallel guidance under the EU AI Act and MDR frameworks extends similar technical scrutiny to European operators and equipment suppliers. China's NMPA and CAAC coordinate type validation for domestically produced altimeters supporting COMAC platform certification. Stakeholders must monitor spectrum allocation rulings and cross-border mutual recognition agreements to anticipate compliance cost shifts and qualification pathway changes.
Market Dynamics
Radar altimeter resilience mandates against 5G C-band interference are forcing certification pathway redesigns across aviation supply chains. FAA and EASA directives compress retrofit timelines while COMAC's C919 production ramp accelerates domestic sourcing requirements in China.
Growth Catalysts
- Next-Generation Narrow-Body Aircraft:Commercial aviation fleets in Asia-Pacific are expanding altimeter procurement. Airlines prioritize terrain awareness systems for new deliveries.
- FAA Resilience Mandates:Airworthiness directives on radar altimeter susceptibility to wireless interference tighten certification requirements. US-registered fleets face accelerated retrofit obligations.
- COMAC Production Scaling:China's domestic airline operators retrofit existing fleets while supporting C919 platform certification. NMPA and CAAC coordinate type validation for locally produced instruments.
Market Restraints
- Aviation-Grade Certification Burden:GPS altimeters face prohibitive qualification costs for transport-category fitment. Certification timelines stretch 18-24 months for new entrants.
- Shanghai-Xi'an Supply Concentration:China's avionics manufacturing clusters create geographic dependency risk. Disruption to either hub strains global radar altimeter component flows.
- Hybrid Analog-Digital Persistence:Marine applications favor dual-mode instrumentation redundancy. This technical limitation slows full digital architecture penetration in adjacent verticals.
Strategic Opportunities
- Unmanned Aerial Vehicle Navigation:GPS altimeters gain traction where cost sensitivity outweighs aviation-grade certification. Precision agriculture and survey operators drive volume demand.
- EU AI Act Integration:Software-integrated altimeter systems for fighter aircraft upgrades benefit from MDR framework alignment. Thales Group anchors European defense positioning through this regulatory tailwind.
- Laser Time-of-Flight Convergence:Lidar altimetry merges with satellite triangulation for centimeter-grade surveying. Construction and mining verticals adopt hybrid optical-GPS configurations.
Industry Challenges
- RF Engineering Talent Scarcity:Radar altimeter architecture expertise concentrates within legacy defense contractors. Commercial aviation suppliers compete for limited microwave design specialists.
- Cross-Border Mutual Recognition Delays:EASA and FAA spectrum allocation rulings diverge on 5G C-band mitigation standards. Dual certification adds 8-12 months to product qualification.
- Legacy Flight Deck Integration Complexity:Analog-to-digital interface conversion requires airframe-specific software adaptation. Retrofit programs face airworthiness recertification cascades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Altimeter Market |
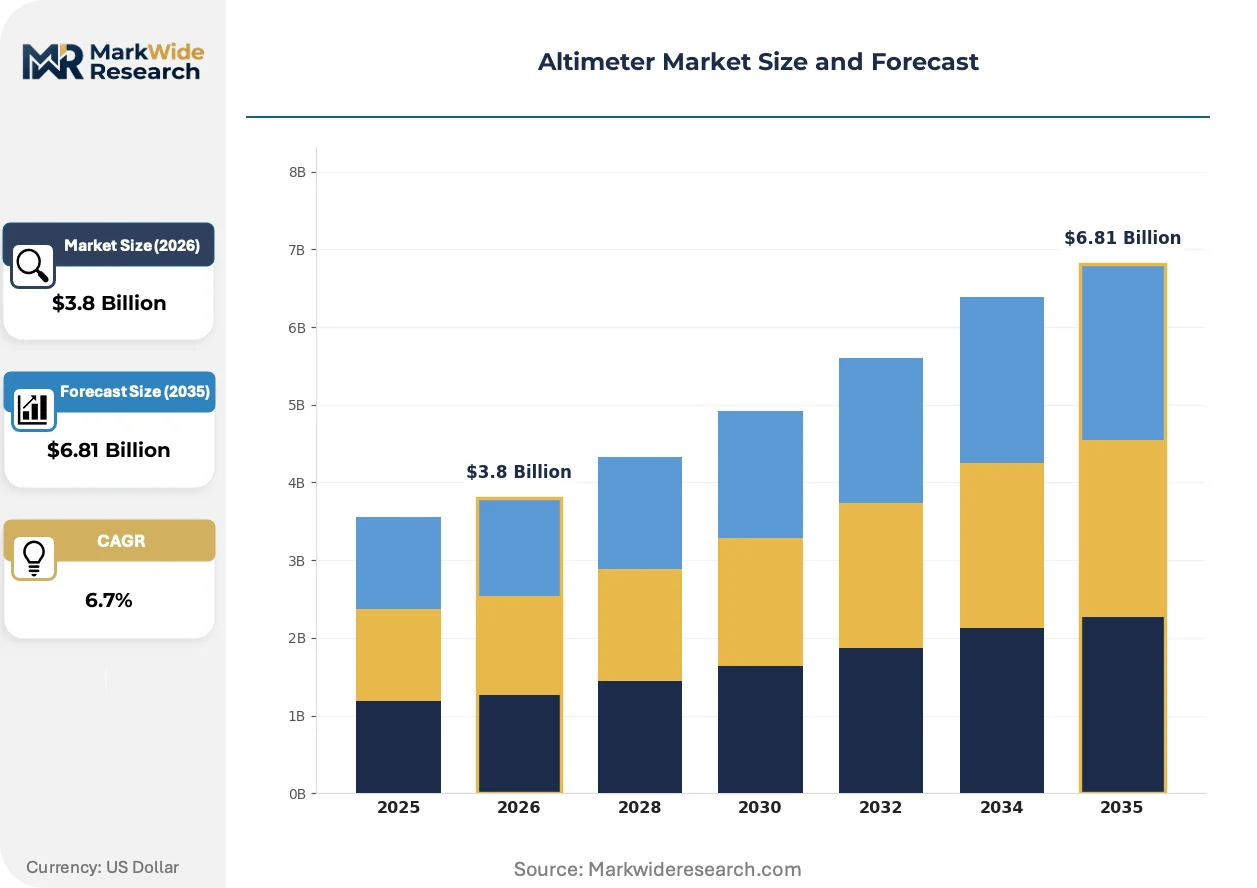
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Barometric Altimeter, Laser Altimeter, GPS Altimeter, Radar Altimeter End User: Aerospace, Marine, Automotive, Land Surveying Technology: Digital, Analog, Hybrid, Software-Integrated Installation: Fixed, Portable, Embedded, Handheld |
| Companies Covered | Honeywell International, Collins Aerospace, Thales Group, Garmin Ltd., Safran, BAE Systems, Northrop Grumman, L3Harris Technologies, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Altimeter Market Emerging Trajectories
Digital technology architectures are displacing analog instrumentation across regulated aviation environments. Three interconnected developments are compressing product lifecycles and reshaping competitive positioning.
Solid-state radar altimeter transceivers are digitizing signal processing chains previously handled by discrete analog components. Helicopter terrain awareness system manufacturers adopt these architectures fastest, driven by weight and power constraints. This compression of component count is digitizing maintenance protocols and reducing mean-time-between-failure metrics by eliminating drift-prone analog stages.
EASA's MDR framework extends technical scrutiny to software-integrated altimeter systems under parallel FAA guidance on wireless interference susceptibility. Equipment suppliers face expanded documentation requirements for artificial intelligence-enabled signal processing. Fighter aircraft upgrade programs in Europe absorb the most severe compliance cost impacts, with OEMs embedding regulatory specialists within design teams.
Airline procurement departments are consolidating avionics purchasing through integrated flight deck contracts rather than standalone altimeter transactions. This channel consolidation displaces component-level distributors from transport-category deals. China and Southeast Asia exhibit the most pronounced concentration, where COMAC and Airbus A320 family operators negotiate fleet-scale instrumentation packages.
Altimeter Market Segmentation
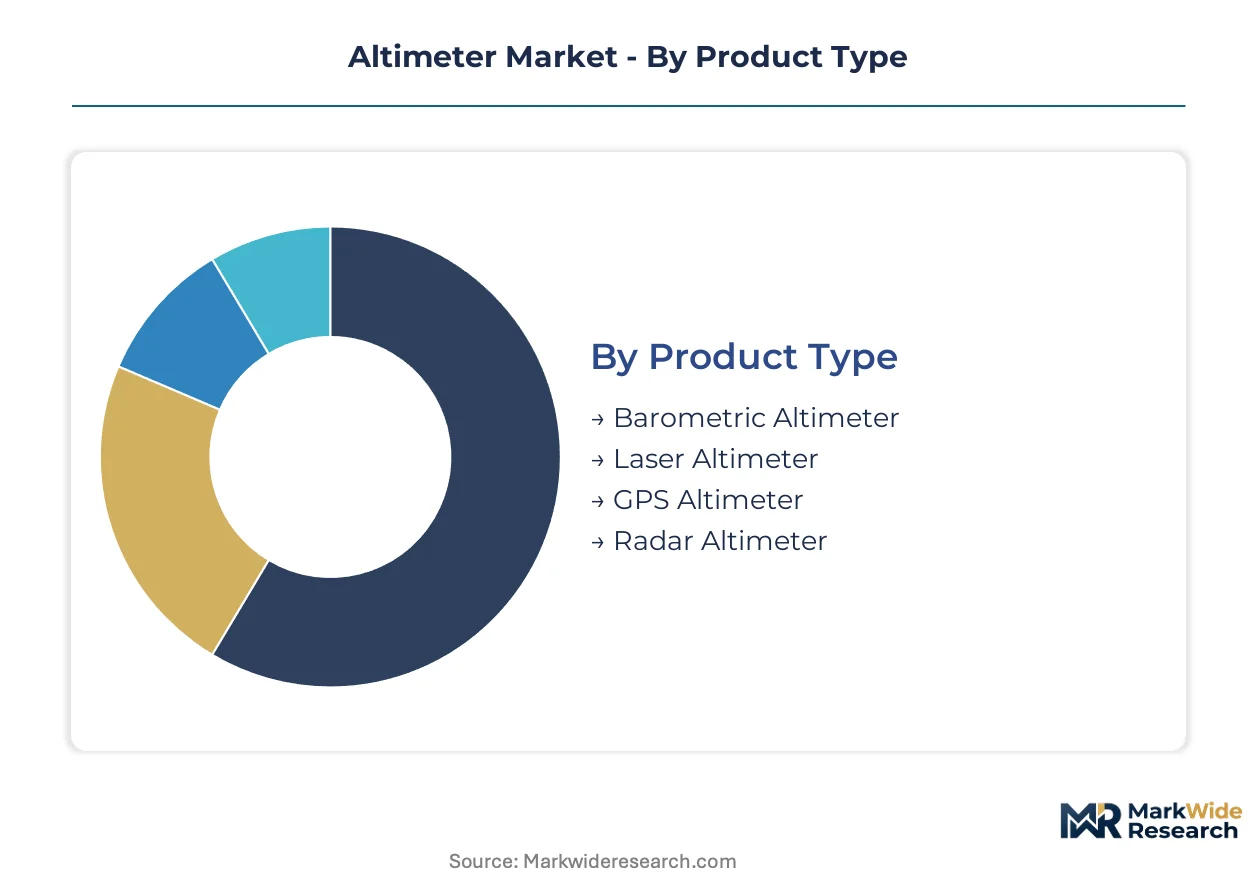
Altimeter procurement patterns diverge sharply across aviation, marine, and terrestrial applications. Each segment demands distinct precision thresholds, certification burdens, and integration architectures that reshape supplier strategies and pricing models.
Product Type:
Measurement principles range from atmospheric pressure differentials to radio wave reflection and laser time-of-flight, with each technology commanding distinct cost tiers and regulatory pathways.
- Barometric Altimeter:Relies on atmospheric pressure calibration against sea-level reference points. General aviation operators in the United States favor these instruments for cost-sensitive retrofit programs under FAA Part 23 certification.
- Laser Altimeter:Emits pulsed light beams and measures return time for centimeter-grade elevation mapping. Survey contractors in Canada and Australia deploy these systems for mining terrain modeling where satellite occlusion limits GPS reliability.
- GPS Altimeter:Triangulates elevation through satellite constellation geometry. Precision agriculture drone fleets in Brazil absorb volume demand where aviation-grade certification is not required.
- Radar Altimeter:Transmits radio frequency pulses toward terrain and calculates altitude from echo return time. Transport-category aircraft mandates under FAA and EASA airworthiness directives sustain premium pricing for these systems.
The dominant share belongs to Radar Altimeter, while Laser Altimeter is closing the gap fastest.
End User:
Customer archetypes span regulated transportation modes to uncrewed commercial applications, each imposing distinct performance floors and procurement volumes.
- Aerospace:Encompasses commercial air transport, business aviation, and military platforms. Airlines in China retrofit narrow-body fleets for terrain awareness compliance as COMAC C919 production scales.
- Marine:Covers commercial shipping, naval vessels, and recreational craft. Dual-mode barometric-digital redundancy persists here due to salt-air corrosion resistance requirements.
- Automotive:Includes autonomous vehicle perception stacks and off-road navigation systems. German automotive suppliers integrate GPS altimeters for elevation-aware powertrain calibration in Alpine driving conditions.
- Land Surveying:Captures construction, mining, and geodetic measurement applications. Japanese survey equipment manufacturers combine lidar altimetry with satellite triangulation for infrastructure monitoring contracts.
Aerospace commands the revenue concentration, though Land Surveying is expanding most quickly through optical-GPS hybrid adoption.
Technology:
Signal processing architectures determine maintenance protocols, failure modes, and regulatory documentation burdens across installation bases.
- Digital:Employs solid-state transceivers with software-defined signal processing. Helicopter terrain awareness manufacturers in France prioritize these architectures for weight and power optimization.
- Analog:Utilizes discrete electronic components with drift-prone calibration requirements. Legacy marine installations retain these systems where operators prioritize familiar maintenance procedures.
- Hybrid:Combines analog sensors with digital display and logging functions. Coastal fishing fleets in Spain favor this configuration for redundancy without full digital complexity.
- Software-Integrated:Embeds artificial intelligence-enabled signal filtering and fault detection. Thales Group deploys these systems for European fighter aircraft upgrade programs under EASA MDR framework alignment.
Digital architectures hold the installed base majority, yet Software-Integrated is gaining share fastest through defense procurement shifts.
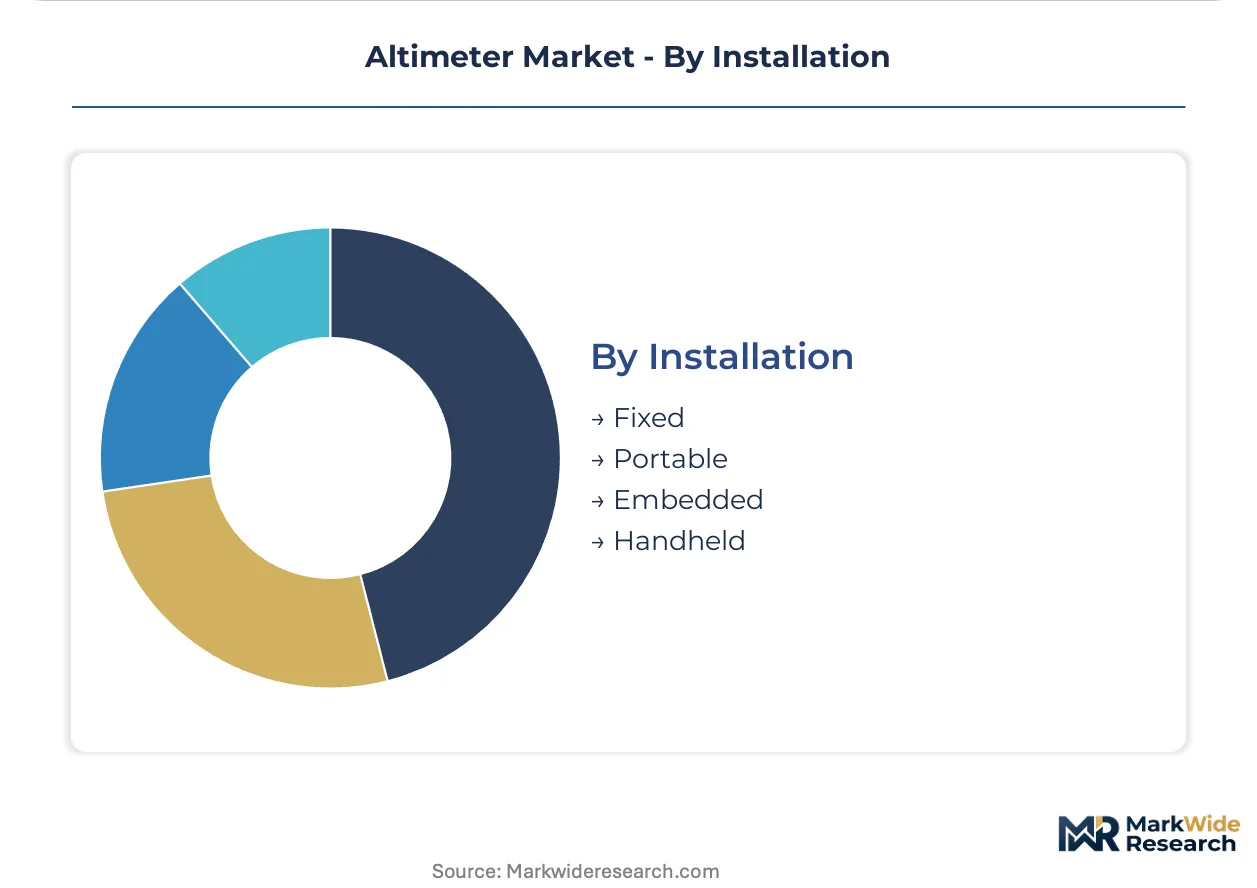
Installation:
Physical integration modes reflect mobility requirements, calibration frequency, and airworthiness permanence across operating environments.
- Fixed:Permanently mounted instrumentation with hardwired power and data interfaces. Commercial aviation mandates this configuration for primary flight display integration.
- Portable:Battery-operated units with temporary mounting provisions. Search-and-rescue operators in Switzerland deploy these for alpine helicopter missions requiring rapid aircraft reconfiguration.
- Embedded:Chip-scale modules integrated within larger avionics or vehicle systems. Autonomous vehicle developers in California source these for perception stack miniaturization.
- Handheld:Standalone devices for field personnel without vehicle integration. Forestry survey crews in Finland utilize these for timber volume estimation in remote terrain.
Fixed installations generate the revenue core, while Embedded is climbing the fastest through automotive and unmanned system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA mandates on radar altimeter resilience against 5G C-band interference anchor the United States as the dominant regulatory geography shaping certification timelines and retrofit obligations across aviation supply chains.
United States
Commercial airlines retrofit narrow-body fleets for terrain awareness compliance while defense contractors upgrade military platforms. FAA airworthiness directives compress qualification pathways for new radar altimeter installations. Wichita's aviation manufacturing cluster hosts avionics integration facilities serving Boeing and regional jet programs.
China
COMAC C919 production scaling drives altimeter procurement for new deliveries and existing fleet retrofits. NMPA and CAAC coordinate type validation for domestically produced instruments supporting platform certification. Shanghai and Xi'an manufacturing clusters concentrate avionics component flows and radar altimeter assembly capacity.
France
Thales Group anchors European defense positioning through software-integrated altimeter systems for fighter aircraft upgrade programs. EASA MDR framework alignment extends technical scrutiny to artificial intelligence-enabled signal processing. Paris-Saclay aerospace corridor hosts design teams embedding regulatory specialists within development workflows.
Germany
German automotive suppliers integrate GPS altimeters for elevation-aware powertrain calibration in Alpine driving conditions. EU AI Act integration creates compliance tailwinds for software-defined instrumentation. Bavaria's automotive electronics cluster adapts aviation-grade signal processing for autonomous vehicle perception stacks.
United Kingdom
BAE Systems sustains military altimeter procurement for rotorcraft and fixed-wing platforms under UK Ministry of Defense modernization programs. CAA alignment with EASA spectrum allocation rulings shapes dual certification requirements. Bristol's aerospace engineering hub concentrates microwave design specialists for radar altimeter architecture development.
Altimeter Market Vendor Landscape
Diversified avionics conglomerates and defense-focused electronics specialists split the market through divergent certification strategies and customer access patterns. The vendor base concentrates around integrated flight deck providers and standalone radar altimeter architects. Tier-one suppliers leverage long-term OEM contracts while mid-scale specialists capture retrofit and upgrade cycles. Competitive moves center on strategic partnerships for regulatory compliance and portfolio diversification into adjacent unmanned platforms.
Among diversified conglomerates, Honeywell International and Collins Aerospace exemplify archetypes anchored in integrated flight deck portfolios. Thales Group occupies a position representing European defense-focused specialization under EASA regulatory alignment. These three entities sit within distinct competitive vectors—Honeywell and Collins exemplifying scale-driven commercial aviation dominance, Thales representing software-integrated military positioning—while Garmin Ltd. anchors consumer and general aviation accessibility at lower certification tiers.
| Leading Market Players |
|---|
| Honeywell International |
| Collins Aerospace |
| Thales Group |
| Garmin Ltd. |
| Safran |
| BAE Systems |
| Northrop Grumman |
| L3Harris Technologies |
| Leonardo S.p.A. |
| Others |
Supply Flow & Price Mechanics
Shanghai and Xi'an manufacturing clusters concentrate radar altimeter assembly capacity and component flows, concentrating pricing power among integrated flight deck providers who negotiate fleet-scale contracts with COMAC and Airbus operators. This geographic concentration amplifies margin pressure on standalone component suppliers excluded from consolidated procurement channels.
Pricing Analysis
Price spreads between US and Chinese-sourced radar altimeters reflect certification tier differentiation, with FAA-validated units commanding substantial premiums over NMPA-certified alternatives. Three-tier pricing structure across aviation-grade, industrial-grade, and uncertified levels separates transport-category mandates from precision agriculture applications. Pricing pressure stems from COMAC's domestic sourcing requirements accelerating local production scale. GPS altimeter buyers in surveying and drone navigation exhibit highest price sensitivity, while commercial airlines accept premium positioning for terrain awareness compliance.
Supply Chain Analysis
Export control regimes under US EAR and EU dual-use regulations restrict solid-state radar transceiver technology flows to Chinese avionics manufacturers, fragmenting component sourcing strategies. Manufacturing concentrates in the United States, France, and China, with microwave design expertise anchored in legacy defense contractors. Supply chains draw from specialized RF semiconductor foundries, precision antenna fabricators, and aviation-grade PCB substrate suppliers. Single-source vulnerability concentrates in GaN transistor procurement for next-generation transceivers. Distribution runs through integrated flight deck OEMs rather than component-level channels for transport-category fitment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPS altimeter encroachment on aviation-adjacent applications threatens radar altimeter incumbents who must defend certification moats against cost-disruptive substitutes. Substitution defense requires strategic repositioning across three stakeholder archetypes.
For Market Incumbents: Insulate certification portfolios through accelerated FAA-EASA dual qualification investments, particularly for 5G C-band resilience architectures. Deepen backward integration into solid-state transceiver production to capture margin erosion from RF component suppliers. Lock long-term flight deck integration contracts with COMAC and Airbus A320 family operators before procurement consolidation hardens. For New Entrants and Emerging Players: Pursue uncertified GPS altimeter volume in precision agriculture drone fleets across Brazil and Southeast Asia where aviation-grade burden is absent. Target handheld and portable configurations for forestry and alpine search-and-rescue operators underserved by fixed-installation incumbents. Lead with embedded chip-scale modules for autonomous vehicle perception stack suppliers seeking elevation-aware powertrain calibration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified defense conglomerates spinning off non-core radar altimeter divisions under portfolio rationalization pressures. Long-term viability hinges on regulatory compliance capability rather than manufacturing scale alone. Monitor EASA-FAA spectrum allocation convergence as inflection signal for dual certification cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | FAA-EASA alignment compresses qualification timelines for radar altimeter resilience mandates. |
| Backward Integration into RF Semiconductors | Captive GaN transistor production secures supply against export control fragmentation. |
| Software-Integrated Architecture Development | EASA MDR framework alignment opens European fighter upgrade procurement channels. |
| Embedded Module Miniaturization | Chip-scale formats penetrate automotive and UAV perception stack integration. |
| COMAC Supply Chain Localization | NMPA-CAAC coordination creates captive demand for domestically validated instruments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directives, EASA MDR framework documentation, and COMAC supplier qualification records. Primary interviews engaged radar altimeter engineering directors at tier-one avionics suppliers, CAAC certification specialists, airline procurement managers at Asia-Pacific carriers, and RF component sourcing leads at defense contractors. Secondary validation drew from FCC spectrum allocation rulings, NMPA type validation databases, and customs trade flow records for avionics components. Bottom-up segment sizing triangulated against top-down fleet retrofit obligation estimates across US and Chinese-registered commercial aircraft.
Forecast inputs incorporate equipment replacement cycles, regulatory compliance deadlines, and platform production schedules across the projection horizon. Segmentation modeling spans measurement principle, end-user vertical, signal processing architecture, and physical integration mode. CAGRs derive from installed base evolution and new delivery penetration rates calibrated against airframe manufacturer output projections. Industry-specific inputs include 5G C-band interference mitigation timelines and COMAC C919 production ramp assumptions.
Sensitivities concentrate around spectrum allocation rulings, export control expansion, and mutual recognition agreement negotiations between FAA and CAAC. Forecasts reflect documented assumptions on certification pathway durations and retrofit compliance adoption curves. Material shifts in cross-border validation reciprocity or 5G C-band mitigation standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Global Aircraft Seat Actuation System Market
Aircraft and Aerospace Components
Europe Drone Motor Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market
Aircraft and Aerospace Components
Composite Winglet and Sharklet Structures Market
Aircraft and Aerospace Components
Aircraft Hose Fittings Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Europe Aerospace and Defense Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Europe Rotor Blade Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market