
 On-Demand Wellness Software Market | 2026-2036
On-Demand Wellness Software Market Size, Share, and Industry Trends Forecast 2026-2036
On-Demand Wellness Software Market Intelligence
Workforce health coaching capacity is unwinding across employer wellness programs as certified behavioral specialists remain scarce relative to platform scale. Wellable leverages its corporate channel control to sustain recurring contracts with Fortune 500 benefits administrators. Personify Health anchors its position through integrated medical and wellness data streams. Sprout competes on geographic dominance in the Canadian employer market.
On-demand wellness software denotes cloud-native applications delivering real-time health interventions through biometric ingestion, algorithmic personalization, and synchronous provider connectivity, typically architected on RESTful APIs with sub-200-millisecond response thresholds for live coaching sessions. SaaS Platforms lead structural deployment as employers favor centralized administrative dashboards over fragmented mobile-only experiences. Mental Health Support services capture expanding margin pools as reimbursement pathways for digital therapeutics mature. Wearable Devices represent the fastest-growing product attachment as IoT sensor fidelity improves.
FDA oversight of software-as-medical-device classifications and HIPAA privacy safeguards in the United States constrain feature development timelines while elevating compliance costs for market entry. EMA's evolving digital health framework in Europe and India's CDSCO guidance on wellness-versus-drug claims create additional jurisdictional complexity for multi-territory operators. Stakeholders must weigh regulatory pre-certification investments against the pace of AI-driven personalization capabilities.
Market Dynamics
Enterprise HR departments are consolidating vendor relationships around platforms that unify biometric data ingestion, synchronous coaching, and benefits administration into single administrative dashboards. This procurement compression favors SaaS architectures with sub-200-millisecond API response thresholds over fragmented mobile-only point solutions.
Growth Catalysts
- HIPAA Compliance Infrastructure:Cloud-native vendors investing in United States privacy safeguards capture recurring contracts from Fortune 500 benefits administrators who cannot tolerate audit risk.
- Biometric Sensor Fidelity:Wearable device manufacturers delivering continuous glucose monitoring and heart rate variability data unlock algorithmic personalization engines for metabolic health interventions.
- German Occupational Health Mandates:Betriebsärzte integration requirements push employers toward platforms with integrated medical and wellness data streams for statutory reporting.
Market Restraints
- FDA Software-as-Medical-Device Classification:Pre-submission pathways for digital therapeutics extend feature development timelines by twelve to eighteen months for algorithmic coaching modules.
- Certified Behavioral Specialist Scarcity:Workforce health coaching capacity remains concentrated in United States metropolitan clusters, constraining platform scale in secondary markets.
- Cloud Infrastructure Concentration:HIPAA-compliant hosting providers cluster in Virginia and Oregon data center corridors, creating geographic single points of failure for live session continuity.
Strategic Opportunities
- EMA Digital Health Framework Evolution:Pre-certification investments in European conformity assessment procedures open reimbursement pathways for mental health support services in Germany and France.
- India CDSCO Wellness-versus-Drug Guidance:Clarified claim boundaries enable platform localization for corporate campuses in Bangalore and Hyderabad without pharmaceutical licensing requirements.
- IoT Sensor Convergence:Integration of continuous blood pressure monitoring with sleep architecture analysis creates new product attachment categories for cardiovascular risk stratification.
Industry Challenges
- RESTful API Latency Engineering:Maintaining sub-200-millisecond response thresholds for synchronous coaching sessions requires specialized edge computing deployments that strain DevOps capacity.
- Multi-Jurisdictional Privacy Architecture:Reconciling HIPAA safeguards with GDPR data localization and India's proposed digital health data protection framework demands redundant consent management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On-Demand Wellness Software Market |
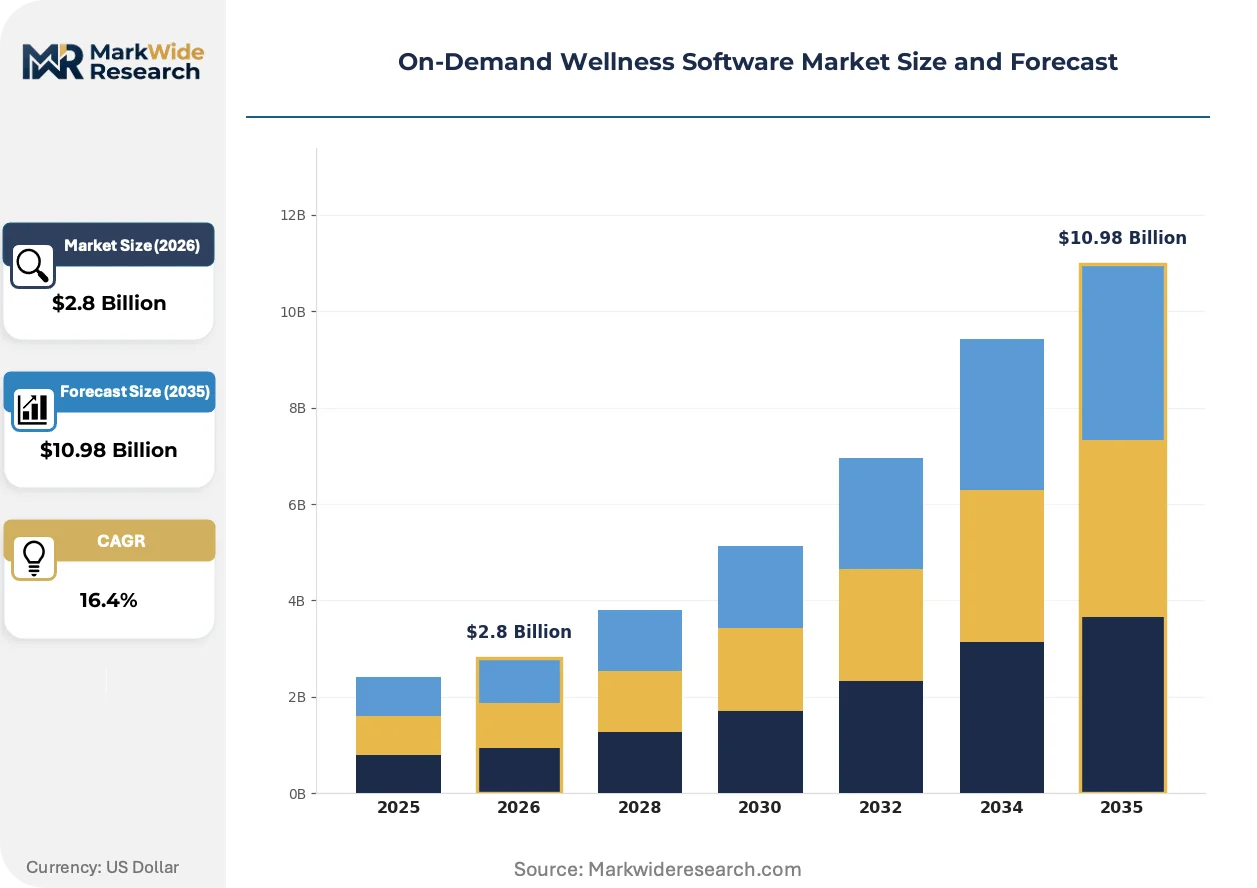
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, SaaS Platforms, Web Portals, Wearable Devices Service Type: Consultation, Fitness Tracking, Nutrition Planning, Mental Health Support End User: Individuals, Corporates, Healthcare Providers, Wellness Centers Technology: AI, Machine Learning, Cloud Computing, IoT |
| Companies Covered | Vantage Fit, IncentFit, Wellness360, GoJoe, WellRight, Wellable, Sprout, YuMuuv, Personify Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On-Demand Wellness Software Market Strategic Shifts & Innovations
Algorithmic personalization engines are compressing the role of generalized wellness content libraries in employer benefit programs. Three developments are restructuring how interventions are delivered, regulated, and purchased.
Continuous glucose monitoring integration is supplanting episodic biometric screening as the primary metabolic health intervention modality. Large self-insured employers in the United States are deploying these sensors to prediabetic employee cohorts within ninety-day implementation windows. This sensor architecture is compressing annual wellness program design cycles into real-time feedback loops that demand constant algorithmic recalibration.
EMA's evolving digital health framework is mandating clinical evidence standards for software delivering therapeutic interventions. European platform operators must now submit randomized controlled trial data for mental health coaching modules seeking national reimbursement eligibility. German occupational health insurers are responding by pre-qualifying vendors with notified body certifications, excluding smaller competitors without conformity assessment resources.
Benefits administrators are consolidating vendor relationships around platforms offering unified administrative dashboards rather than assembling point solutions. This procurement compression displaces standalone meditation applications and step-counting programs from employer technology stacks. The pattern is most visible among United States Fortune 500 companies with centralized HR information systems requiring single sign-on integration and consolidated utilization reporting.
On-Demand Wellness Software Market Segmentation
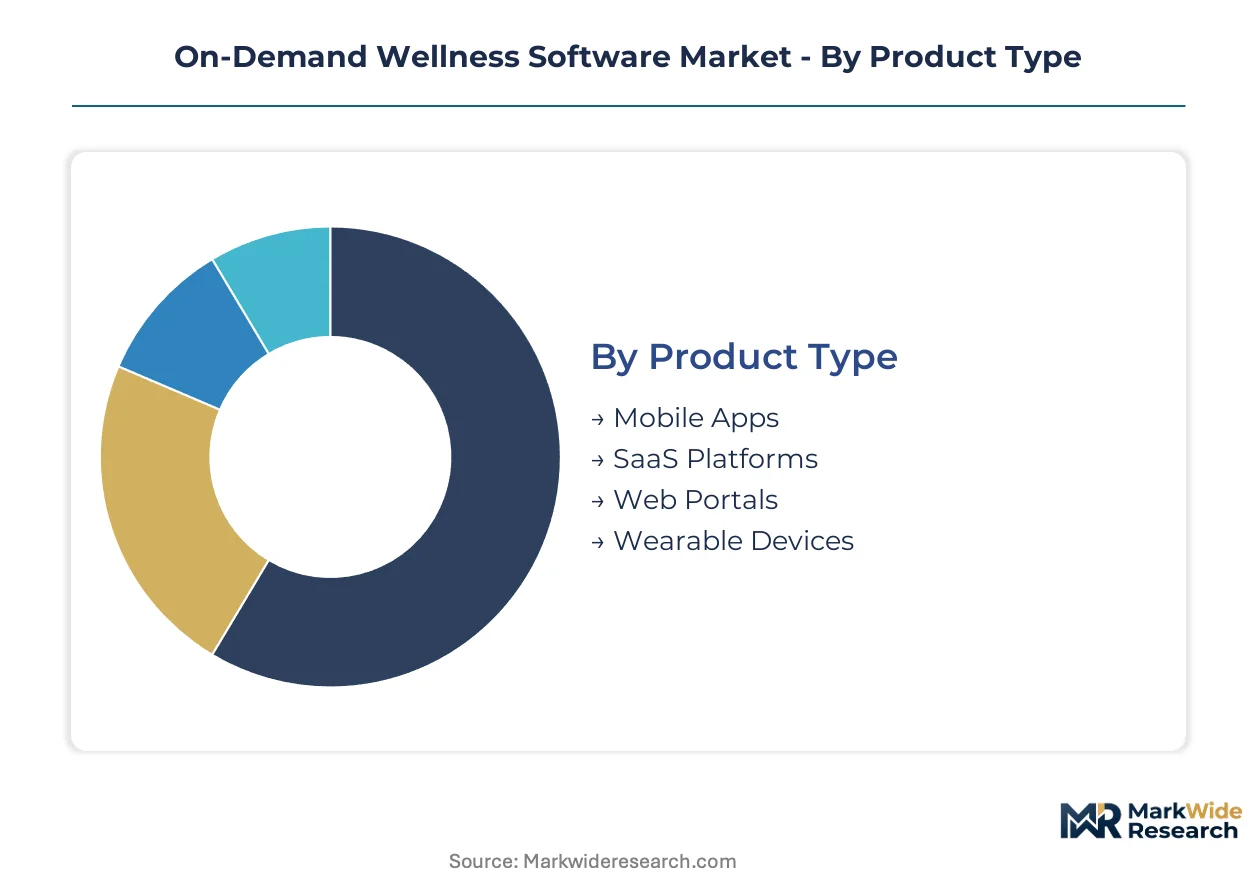
Segmentation in on-demand wellness software reveals how procurement channels filter product and service categories differently. Enterprise HR departments, individual consumers, and clinical settings each activate distinct technology stacks and compliance requirements.
Product Type:
Channel architecture splits sharply between direct-to-consumer mobile distribution and enterprise SaaS procurement through benefits administrators.
- SaaS Platforms:Cloud-native architectures deliver centralized administrative dashboards with RESTful API integration for HR information systems. Fortune 500 benefits administrators in the United States demand sub-200-millisecond response thresholds and single sign-on capabilities that mobile-only solutions cannot satisfy.
- Wearable Devices:Continuous biometric sensors with heart rate variability and glucose monitoring capabilities feed algorithmic personalization engines. Large self-insured employers deploy these to prediabotic employee cohorts within compressed implementation windows.
- Mobile Apps:Standalone applications serve individual consumers and small employers lacking centralized IT infrastructure.
- Web Portals:Browser-based interfaces persist in wellness center and clinical settings requiring workstation access.
SaaS Platforms dominate installed base. Wearable Devices is where expansion concentrates.
Service Type:
Margin structure varies by reimbursement pathway maturity and regulatory classification burden.
- Mental Health Support:Digital therapeutics with cognitive behavioral therapy modules command premium pricing where FDA software-as-medical-device pathways and EMA clinical evidence standards unlock national reimbursement. German occupational health insurers pre-qualify vendors with notified body certifications.
- Consultation:Synchronous coaching sessions with certified behavioral specialists concentrate in United States metropolitan clusters, constraining platform scale.
- Fitness Tracking:Step counting and activity monitoring face displacement from benefits technology stacks as procurement consolidates around unified platforms.
- Nutrition Planning:Meal logging and dietary guidance remain secondary to metabolic sensor integration in employer program design.
Consultation services anchor recurring revenue. Mental Health Support climbs the fastest.
End User:
Customer type determines compliance architecture and sales cycle length.
- Corporates:Enterprise HR departments consolidate vendor relationships around platforms unifying biometric ingestion, synchronous coaching, and benefits administration. HIPAA compliance infrastructure and audit tolerance requirements favor established cloud-native vendors.
- Healthcare Providers:Clinical integration demands EHR connectivity and FDA oversight alignment for algorithmic coaching modules.
- Individuals:Direct-to-consumer subscriptions face churn pressure from fragmented point solutions.
- Wellness Centers:Facility-based operators seek hardware-software bundles with staff training components.
Corporates dominate installed base. Healthcare Providers is where expansion concentrates.
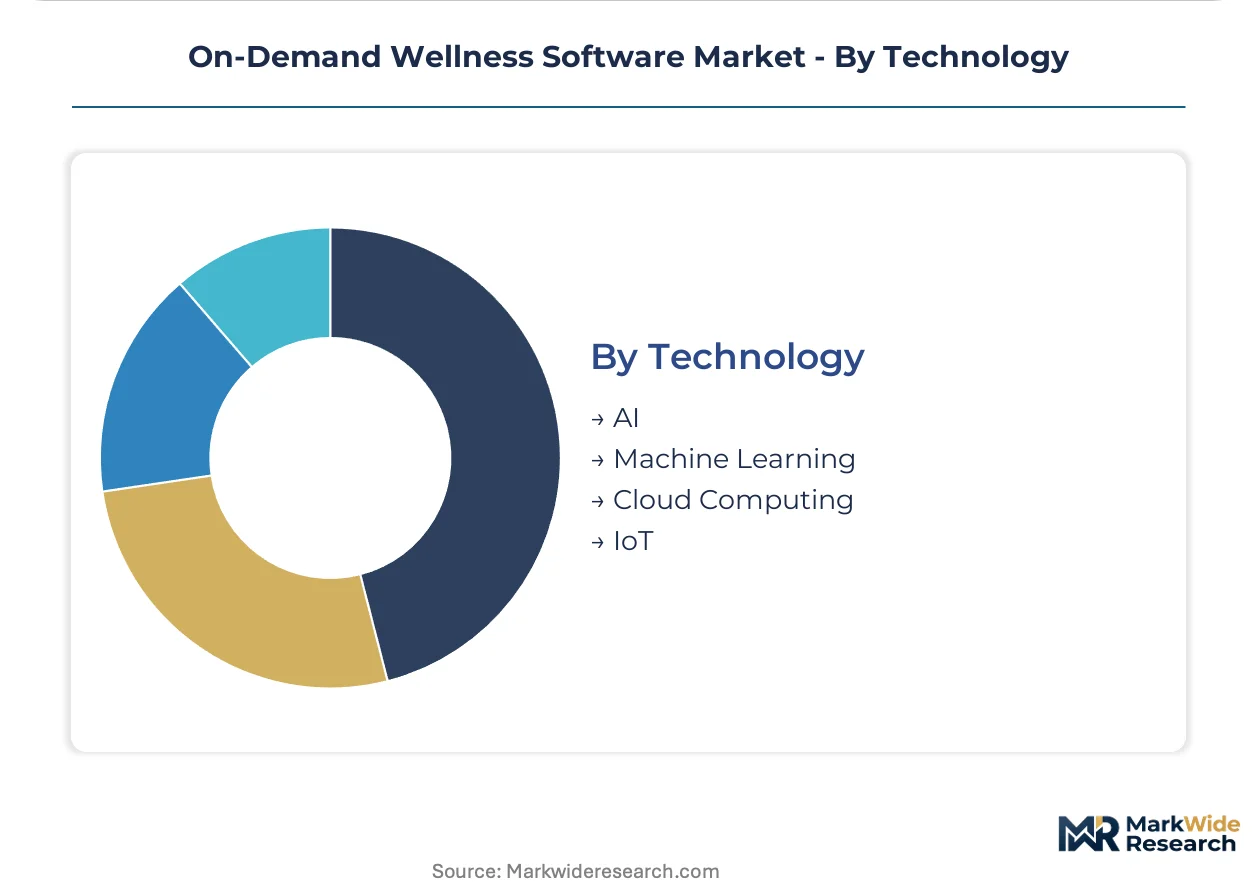
Technology:
Underlying technology layers determine personalization fidelity and infrastructure cost structure.
- AI:Algorithmic personalization engines compress generalized content libraries by processing continuous glucose monitoring and sleep architecture data for real-time metabolic intervention recalibration.
- Cloud Computing:HIPAA-compliant hosting clusters in Virginia and Oregon data center corridors create geographic concentration risk for live session continuity.
- Machine Learning:Predictive models for cardiovascular risk stratification require training data from diverse biometric streams.
- IoT:Sensor convergence enables new product attachment categories integrating continuous blood pressure monitoring with existing wearable architectures.
Cloud Computing dominates installed base. AI is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
HIPAA compliance infrastructure in the United States anchors regulatory investment priorities for cloud-native wellness platforms. Fortune 500 employers in Virginia and Oregon data center corridors drive procurement volume for sub-200-millisecond API architectures.
United States
Large self-insured employers deploy continuous glucose monitoring sensors to prediabetic employee cohorts within ninety-day windows. FDA software-as-medical-device classification pathways extend feature development timelines for algorithmic coaching modules. Virginia and Oregon hosting clusters concentrate HIPAA-compliant infrastructure for live session continuity.
Germany
Betriebsärzte integration requirements push employers toward platforms with unified medical and wellness data streams for statutory reporting. EMA digital health framework evolution mandates clinical evidence standards for mental health coaching modules seeking national reimbursement. Berlin and Munich occupational health insurers pre-qualify vendors with notified body certifications.
India
Corporate campuses in Bangalore and Hyderabad activate demand for localized wellness platforms serving technology sector workforces. CDSCO guidance on wellness-versus-drug claims clarifies regulatory boundaries without pharmaceutical licensing requirements. Hyderabad data centers host emerging cloud infrastructure for regional platform delivery.
Canada
Employer wellness programs in Toronto and Vancouver consolidate procurement around unified administrative dashboards with single sign-on integration. Provincial privacy statutes layer compliance requirements atop federal PIPEDA frameworks for biometric data handling. Toronto benefits administrators favor SaaS architectures over fragmented mobile-only point solutions.
United Kingdom
NHS digital health initiatives create procurement pathways for wellness platforms integrating with primary care referral systems. GDPR data localization requirements demand redundant consent management systems for multi-territory operators. London-based benefits consultants advise FTSE 100 employers on platform consolidation strategies.
On-Demand Wellness Software Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the vendor base. Established cloud-native platforms with HIPAA-compliant infrastructure capture recurring Fortune 500 contracts, while specialized coaching networks compete on behavioral specialist density. Three archetypes dominate: integrated health data platforms, geographic market specialists, and corporate channel controllers. M&A activity concentrates on biometric data ingestion capabilities, while strategic partnerships target EHR connectivity for clinical settings.
Among corporate channel controllers, Wellable leverages its benefits administrator relationships to sustain recurring contracts with large employers. Personify Health exemplifies the integrated health data archetype through its unified medical and wellness stream architecture. Sprout occupies a position as the geographic specialist anchoring Canadian employer market penetration. These three represent distinct competitive vectors rather than overlapping positioning.
| Leading Market Players |
|---|
| Vantage Fit |
| IncentFit |
| Wellness360 |
| GoJoe |
| WellRight |
| Wellable |
| Sprout |
| YuMuuv |
| Personify Health |
| Others |
Cost & Logistics Intelligence
FDA software-as-medical-device classification gates both vendor qualification and pricing stratification simultaneously. HIPAA compliance infrastructure in Virginia and Oregon data center corridors creates tiered supply access that vendors translate into subscription premiums for Fortune 500 benefits administrators.
Pricing Analysis
United States enterprise contracts command three-to-five-fold premiums over Indian corporate campus deployments. SaaS subscription tiers stratify across premium, standard, and economy levels based on API response thresholds and biometric data integration depth. Price differentiation rests on HIPAA audit certification and single sign-on complexity. Cost compression in standard tiers is intensifying as cloud-native entrants replicate core dashboard functionality. Small employers lacking centralized IT infrastructure exhibit highest price sensitivity; self-insured Fortune 500 buyers prioritize audit tolerance over unit cost.
Supply Chain Analysis
United States and Germany anchor cloud infrastructure and regulatory consulting capacity for wellness platform delivery. India and Ireland feed software engineering talent and customer success operations. Raw material dependencies center on continuous glucose monitoring sensors from medical device manufacturers, edge computing hardware for sub-200-millisecond latency, and certified behavioral specialist labor pools concentrated in metropolitan clusters. Single-source vulnerability runs through HIPAA-compliant hosting corridors in Virginia and Oregon. Distribution runs through benefits administrator channel partnerships rather than direct enterprise sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. HIPAA compliance infrastructure and FDA pre-certification pathways create switching costs that cement incumbent positions.
For Market Incumbents: Compound channel control through deeper benefits administrator integration and exclusive biometric data partnerships. Wellable-style corporate relationships resist point-solution disintermediation. FDA software-as-medical-device pathway investments block algorithmic coaching module replication. Vertical integration into continuous glucose monitoring sensor distribution locks metabolic health intervention workflows. For New Entrants and Emerging Players: Lead with white-space exploitation in Indian corporate campuses and German mid-market employers below Betriebsärchte reporting thresholds. CDSCO wellness-versus-drug claim clarity enables platform localization without pharmaceutical licensing. EMA digital health framework pre-certification investments open reimbursement pathways for mental health support services. Channel partnership with regional occupational health insurers bypasses direct Fortune 500 procurement compression. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-driven personalization engine development. Long-term viability favors platforms with unified medical and wellness data stream architecture and notified body certifications for European market access. Target acquisition archetype: geographic specialists with dense certified behavioral specialist networks. Signal to watch: EMA randomized controlled trial data submission rates for mental health coaching modules.| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA Compliance Infrastructure Expansion | Fortune 500 benefits administrators demand audit-ready cloud architectures with Virginia and Oregon data center presence. |
| Continuous Glucose Monitoring Integration | Metabolic health intervention workflows lock in prediabetic employee cohorts through real-time sensor data feeds. |
| FDA Software-as-Medical-Device Pathway Investment | Pre-submission timelines extend competitive moats for algorithmic coaching modules in digital therapeutics. |
| EMA Notified Body Certification Pursuit | German occupational health insurers pre-qualify vendors for national reimbursement eligibility in mental health support. |
| Certified Behavioral Specialist Network Density | Synchronous coaching capacity constraints platform scale in secondary markets beyond United States metropolitan clusters. |
Research Approach
A spread of perspectives from enterprise HR benefits administrators, cloud platform engineers, FDA regulatory consultants, and occupational health insurers converged on the working assumptions. Primary interviews with Fortune 500 procurement officers and German Betriebsärzte integration specialists combined with secondary validation from FDA 510(k) filings, EMA digital health framework guidance documents, CDSCO wellness claim circulars, and SEC SaaS company disclosures. Bottom-up triangulation across deployment scale estimates and top-down reconciliation against employer benefits spending patterns anchored the analytical framework.
Segmentation dimensions modeled include deployment architecture, organization size tier, service reimbursement pathway, biometric sensor attachment category, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to enterprise SaaS procurement cycles and wearable device penetration trajectories. Forecast inputs incorporated HIPAA compliance cost inflation and EMA clinical evidence standard evolution across the projection horizon.
The analysis sits within stated boundaries; outcomes outside FDA classification pathway stability or EMA framework finalization would require recalibration. Forecasts reflect documented assumptions regarding certified behavioral specialist supply elasticity and cloud infrastructure geographic concentration. Recalibration cycles align with material shifts in digital therapeutic reimbursement policy and biometric sensor fidelity breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software Consulting Market
Software & Services
Movie Editing Software Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Global Saas Backup Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
Global Server Management Software Market
Software & Services
Photo Editor App Market
Software & Services
Global Catalog Management Software Market
Software & Services
Global Application Platform Market
Software & Services
Global Automotive Software Market
Software & Services
Application Platform As a Service Market
Software & Services
Software-Defined Machine Market
Software & Services
Procure to Pay Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Global Application Performance Monitoring (APM) Market