
 Cemetery Software Market | 2026-2036
Cemetery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Cemetery Software Market Analysis
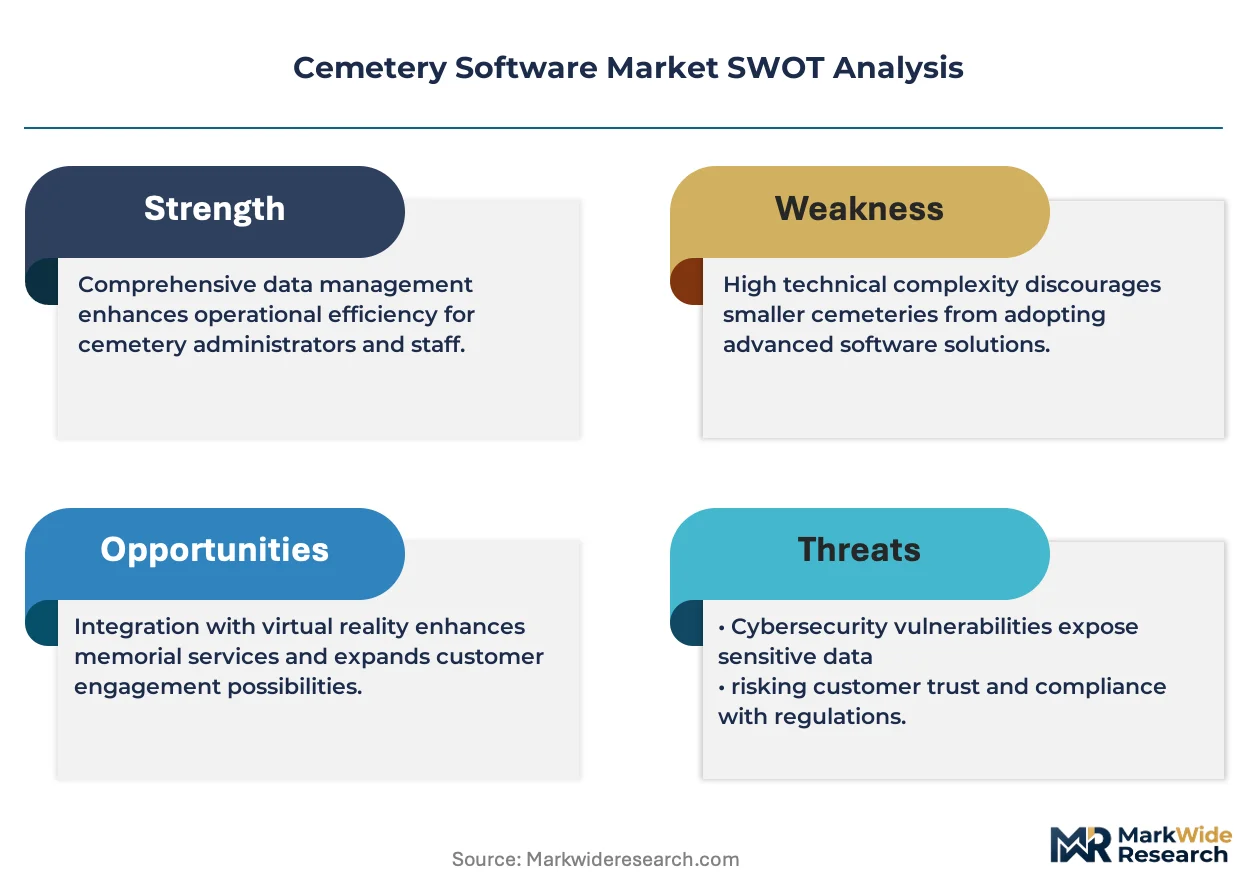
North American cloud infrastructure expansion is reshaping how cemetery software vendors architect their platforms. PlotBox leverages extensive geographic coverage across the United States and Canada to sustain competitive positioning in cloud-based burial management. CemeterySoft specializes in on-premises legacy migration tools, occupying a distinct niche among municipalities with strict data sovereignty requirements. GraveTrac differentiates through mobile-first grave locator interfaces, extending its reach into smaller religious cemeteries with limited IT staff.
Cemetery software encompasses digital platforms that automate burial plot inventory, interment scheduling, deed management, and genealogical record retrieval through centralized databases with geospatial mapping capabilities. These systems replace paper-based ledger systems and fragmented spreadsheets, enabling real-time plot availability verification and compliance with public records retention mandates. Cloud-Based deployment leads segment momentum as funeral homes and cemetery authorities prioritize remote accessibility and reduced hardware maintenance overhead, while On-Premises solutions retain strength among institutional buyers with stringent data control protocols. Grave Locator functionality represents the fastest-expanding feature category, driven by consumer genealogy research demand and municipal transparency initiatives.
HIPAA privacy provisions influence how cemetery software vendors handle decedent medical information linked to burial records, particularly when funeral homes integrate with hospital systems. The FTC Funeral Rule shapes pricing transparency requirements that software platforms must embed in their financial management modules. Municipal procurement officers and cemetery administrators need to evaluate vendor compliance with evolving public records standards and cloud security certifications before committing to long-term platform contracts.
Market Dynamics
Municipal cemetery authorities across North America are accelerating cloud migration timelines as HIPAA-compliant data handling requirements intersect with remote workforce mandates, forcing vendors to rearchitect platforms for hybrid deployment models.
Growth Catalysts
- FTC Funeral Rule compliance automation:Cemetery software platforms embed transparent pricing modules that satisfy federal disclosure mandates, reducing administrative penalties for funeral home operators.
- Genealogy research demand:Consumer interest in ancestral burial records drives municipal investment in digitized plot databases with public-facing grave locator portals.
- Cloud infrastructure expansion:Reduced hardware maintenance overhead and real-time remote access capabilities pull cemetery authorities away from legacy on-premises systems.
Market Restraints
- Data sovereignty requirements:Strict municipal protocols for burial record custody limit cloud adoption among institutional buyers with legacy compliance frameworks.
- Legacy system integration friction:Decades-old paper ledger archives require expensive manual digitization before software deployment can proceed.
- Specialized IT talent scarcity:Cemetery administrators lack technical staff capable of managing geospatial database configurations or API integrations.
Strategic Opportunities
- Mobile-first grave locator interfaces:Religious cemeteries with minimal IT infrastructure represent an underserved segment for simplified consumer-facing applications.
- Interoperability with hospital systems:Funeral home software that seamlessly exchanges decedent medical data with healthcare networks captures workflow efficiency premiums.
- Municipal transparency initiatives:Open data mandates in select jurisdictions create procurement windows for vendors offering public record retrieval capabilities.
Industry Challenges
- Geospatial data accuracy verification:Historical plot boundary disputes and incomplete survey records complicate digital mapping rollouts.
- Cross-platform record standardization:Fragmented data formats between competing software systems impede municipal consolidation efforts.
- Long sales cycle compression:Public procurement timelines for cemetery authorities extend 18-24 months, straining vendor cash flow management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cemetery Software Market |
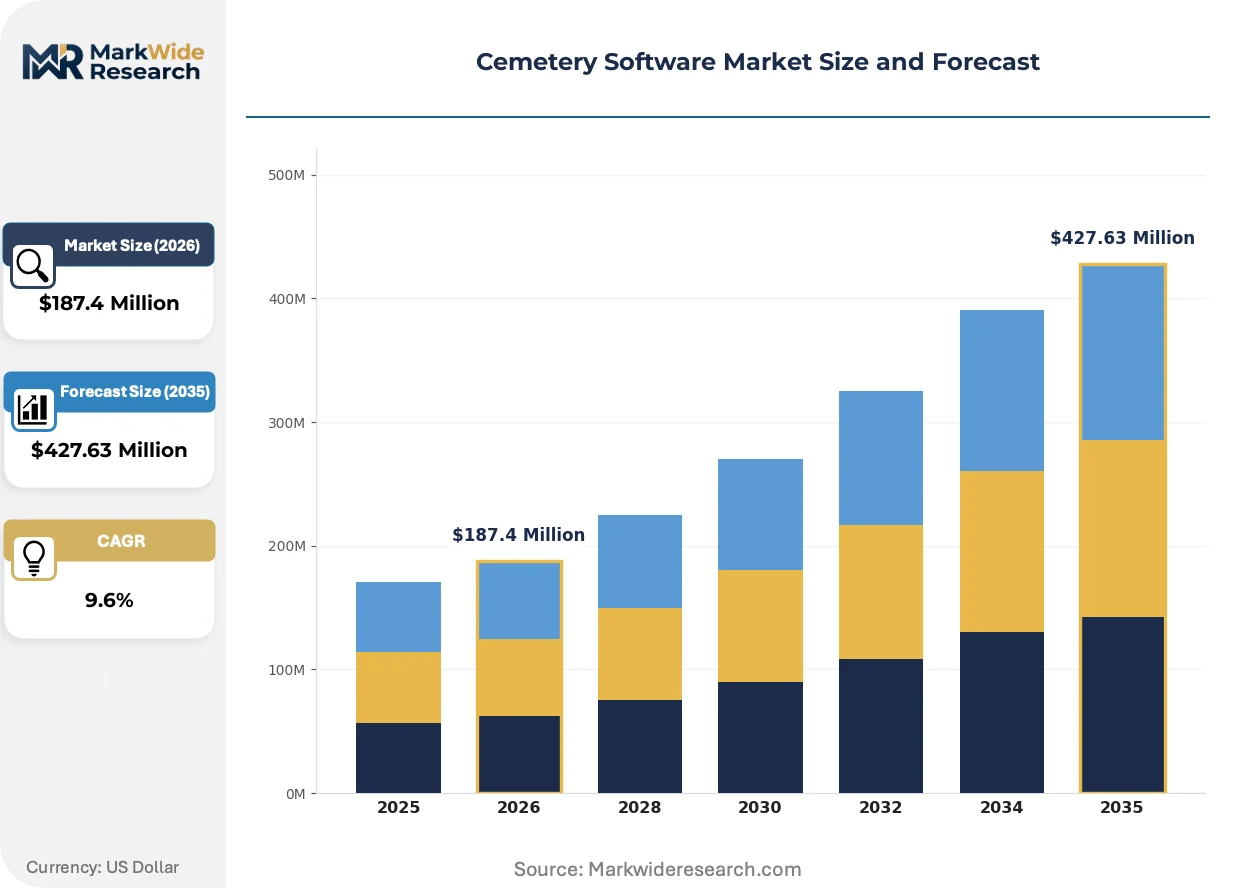
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Feature: Inventory Management, Financial Management, Reporting Tools, Grave Locator End User: Funeral Homes, Cemetery Authorities, Municipalities, Religious Organizations Customer Type: Private, Public, Non-Profit, Institutional |
| Companies Covered | CemeterySoft, Cemetery Workstation, PlotBox, CemeteryFind, Cemify, Memoris, Section8, EverArk, GraveTrac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cemetery Software Market Emerging Trajectories
Cloud-native architectures are rewriting competitive requirements as cemetery software vendors race to deliver HIPAA-compliant remote access without sacrificing municipal data control preferences.
Serverless computing is collapsing the cost structure for multi-tenant cemetery management platforms, allowing vendors to provision geospatial databases on demand. Mid-sized municipal cemetery authorities in the United States are adopting these elastic infrastructure models fastest, eliminating capital expenditure for on-site server hardware. The technology is collapsing barriers to entry for regional software providers previously locked out by enterprise infrastructure requirements.
HIPAA privacy provisions are tightening data handling protocols for decedent medical information linked to burial records, particularly when funeral homes integrate with hospital discharge systems. Vendors must now embed granular access controls and audit trails that satisfy federal health privacy mandates. Cemetery software platforms serving integrated funeral home networks face the steepest compliance engineering costs.
Consumer genealogy researchers are reshaping feature prioritization as cemetery authorities face pressure to publish searchable burial records online. Municipal transparency mandates in select jurisdictions accelerate public portal deployment, displacing traditional record request workflows. This demand rotation concentrates procurement attention on vendors with native web-based grave locator modules rather than back-office administrative tools.
Cemetery Software Market Segmentation
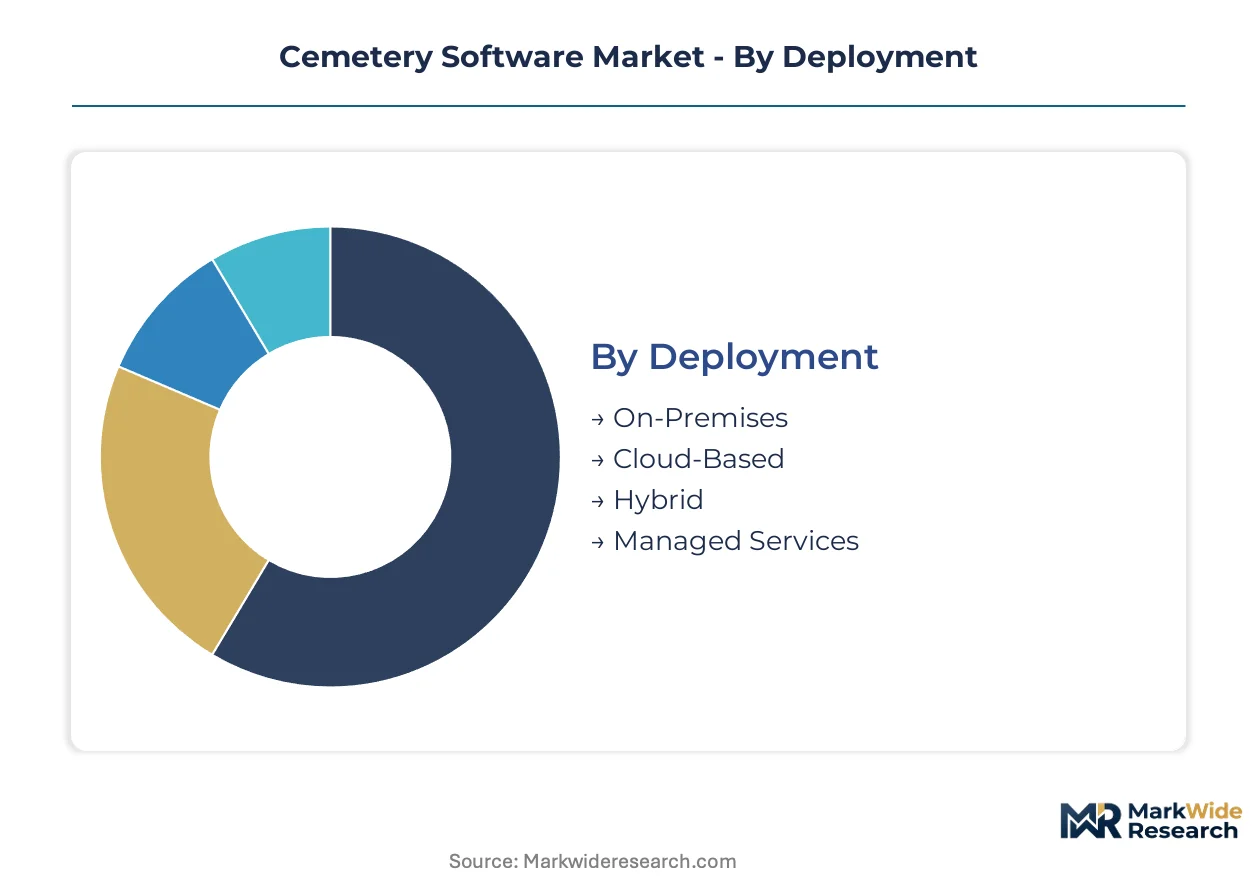
Cemetery software procurement cycles vary dramatically by deployment complexity and institutional risk tolerance. Municipal buyers with 18-24 month procurement timelines favor different architectures than funeral homes replacing legacy systems quarterly.
Deployment:
Replacement velocity separates these segments, with cloud platforms refreshing every 3-4 years while on-premises installations persist for 8-12 year cycles.
- Cloud-Based:Multi-tenant architectures provision geospatial databases on demand through serverless computing, eliminating capital expenditure for on-site server hardware. Municipal cemetery authorities in the United States adopt these elastic infrastructure models fastest as remote workforce mandates intersect with HIPAA-compliant data handling requirements.
- On-Premises:Legacy server installations within municipal data centers satisfy strict burial record custody protocols and data sovereignty frameworks. Institutional buyers with decades-old compliance architectures resist cloud migration despite higher maintenance overhead.
- Hybrid:Split architectures maintain sensitive burial records locally while pushing public-facing grave locator functions to cloud edge nodes.
- Managed Services:Outsourced infrastructure operations where vendors retain full responsibility for server maintenance, backup protocols, and security patching.
Cloud-Based deployment anchors the volume base while Managed Services gains share at the steepest rate.
Feature:
Development resource allocation tracks directly to which functions drive procurement decisions versus routine administrative automation.
- Grave Locator:Consumer-facing geospatial interfaces enable real-time burial plot discovery through web portals and mobile applications. Municipal transparency initiatives in select jurisdictions accelerate public portal deployment, displacing traditional record request workflows.
- Inventory Management:Digital plot tracking replaces paper ledgers with centralized databases mapping burial space availability, deed status, and interment history. Cemetery administrators rely on these modules for daily operational decisions.
- Financial Management:Automated billing, payment processing, and FTC Funeral Rule compliance modules embed transparent pricing disclosures.
- Reporting Tools:Regulatory compliance dashboards and genealogical record extraction utilities for public records retention mandates.
Inventory Management anchors the volume base while Grave Locator climbs the fastest as consumer genealogy demand reshapes feature prioritization.
End User:
Technical sophistication and integration requirements create distinct purchasing patterns across buyer categories.
- Municipalities:Public cemetery authorities manage multiple burial grounds with centralized procurement through municipal IT departments. HIPAA privacy provisions and public records retention mandates dominate their vendor evaluation criteria.
- Funeral Homes:Death care operators require seamless data exchange with hospital discharge systems for decedent medical information handling. These buyers prioritize interoperability over standalone feature depth.
- Cemetery Authorities:Standalone cemetery management entities operating independent of municipal structures.
- Religious Organizations:Church-affiliated cemeteries with minimal IT infrastructure and limited technical staff capacity.
Municipalities anchor the volume base while Funeral Homes expand most quickly through hospital system integration requirements.
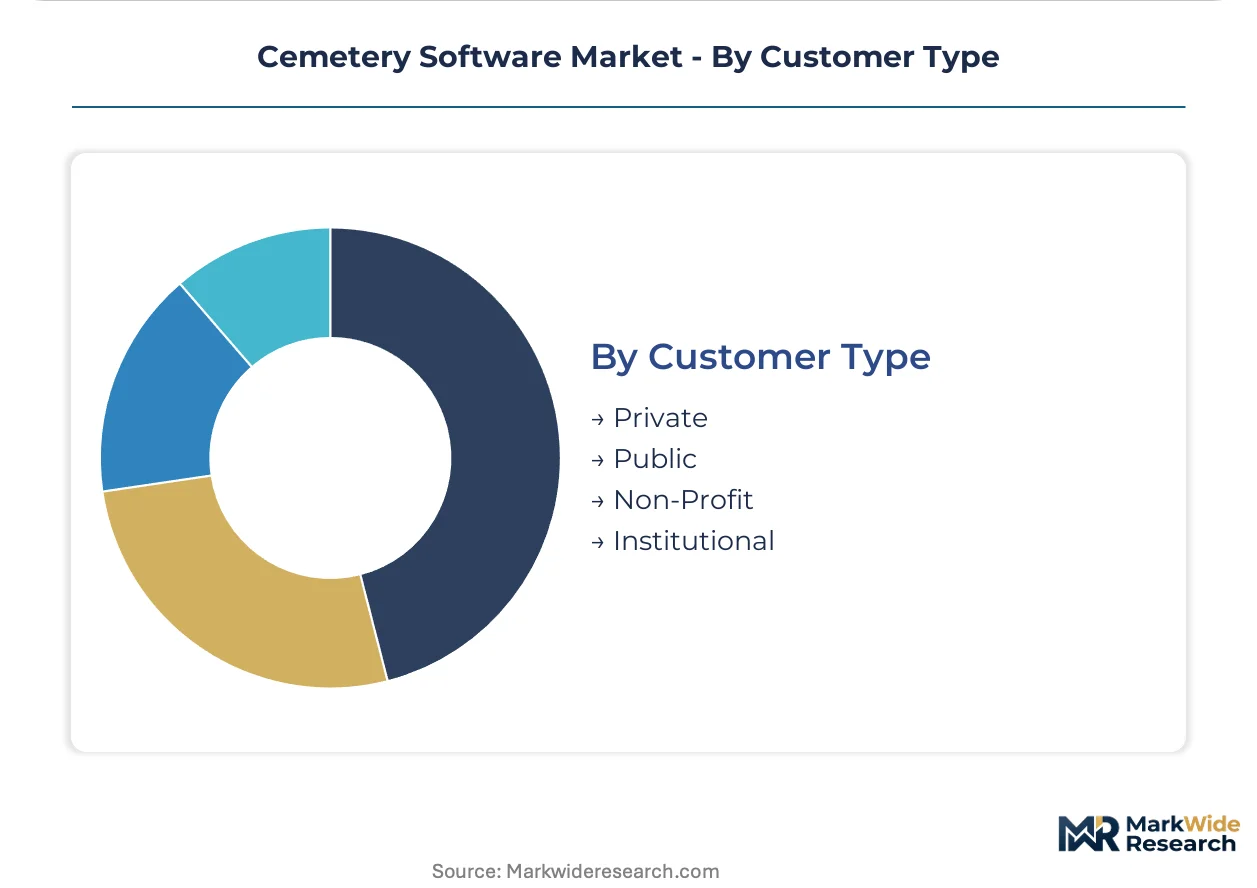
Customer Type:
Budget authority and decision-making velocity differ sharply between taxpayer-funded and privately capitalized operations.
- Public:Government-owned cemetery operations subject to municipal procurement regulations, open records laws, and elected official oversight. These buyers face extended sales cycles and strict vendor qualification requirements.
- Private:Commercial cemetery operators and corporate funeral home chains with centralized technology budgets and faster approval workflows.
- Non-Profit:Charitable cemetery trusts and memorial associations with donor-funded technology investments.
- Institutional:University, military, and hospital-affiliated burial grounds with specialized compliance frameworks.
Public customers anchor the volume base while Private operators gain share fastest through consolidated purchasing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development for cemetery management concentrates heavily in the United States, where municipal digitization mandates and consumer genealogy demand create concentrated procurement activity. Cloud infrastructure expansion and HIPAA compliance requirements pull development resources toward North American markets.
United States
Municipal cemetery authorities in California, Texas, and Florida drive cloud migration timelines as aging paper record systems require replacement. The FTC Funeral Rule shapes pricing transparency modules that vendors must embed for funeral home integration. Boston and Chicago metropolitan areas host clusters of legacy system migration projects targeting hybrid deployment architectures.
Canada
Provincial cemetery boards in Ontario and Quebec accelerate digitization of burial plot inventories following municipal transparency initiatives. Health Canada guidelines intersect with provincial privacy statutes to govern decedent medical data handling in integrated funeral home networks. Toronto-based software deployments emphasize French-English bilingual grave locator interfaces for public portal compliance.
United Kingdom
Church of England diocesan authorities and municipal burial boards in England and Wales digitize parish cemetery records under genealogical research pressure. GDPR provisions constrain cloud data residency choices for burial record custodians. London and Manchester clusters concentrate vendor development resources for Commonwealth cemetery management protocols.
Germany
Stadtverwaltung cemetery departments in Bavaria and North Rhine-Westphalia modernize burial ground administration through municipal IT procurement frameworks. Bundesdatenschutzgesetz data protection requirements limit cross-border cloud hosting for sensitive interment records. Munich and Cologne represent focal points for cemetery software localization to German municipal accounting standards.
Australia
State cemetery trusts in New South Wales and Victoria deploy digital plot management following public records modernization programs. The Privacy Act 1988 and state-based information commissioner directives govern online publication of burial records. Sydney and Melbourne concentrate vendor partnerships with municipal cemetery authorities managing coastal burial ground expansion.
Cemetery Software Market Vendor Landscape
Cloud-native specialists and legacy migration vendors split the market along deployment architecture lines. Consolidation pressure remains moderate given the specialized compliance knowledge required for municipal procurement cycles. Two strategic archetypes dominate: multi-tenant platform operators serving scaled cemetery authorities, and niche consultants handling paper-to-digital transitions for religious cemeteries. Competitive moves concentrate on geographic expansion through municipal framework contracts and technology licensing partnerships with funeral home networks.
Within the cloud-native tier, PlotBox and Cemify exemplify platform operators leveraging serverless infrastructure for elastic geospatial database provisioning. CemeterySoft occupies a distinct position among vendors specializing in on-premises legacy migration tools for data-sovereignty-constrained buyers. GraveTrac anchors the mobile-first specialization vector, representing simplified consumer-facing grave locator development for minimally staffed religious cemetery operations.
| Leading Market Players |
|---|
| CemeterySoft |
| Cemetery Workstation |
| PlotBox |
| CemeteryFind |
| Cemify |
| Memoris |
| Section8 |
| EverArk |
| GraveTrac |
| Others |
Supply Flow & Price Mechanics
Boston's municipal software development cluster concentrates HIPAA-compliant engineering capacity, translating into tiered SaaS pricing power for vendors serving cemetery authorities with strict data sovereignty requirements. Cloud-native platforms command subscription premiums where serverless infrastructure collapses delivery costs, while on-premises legacy migration specialists extract value from data-center-bound buyers facing decades-old compliance architectures.
Pricing Analysis
The FTC Funeral Rule dictates the pricing tier structure for cemetery software platforms, mandating transparent disclosure modules that separate premium compliance-automation tiers from standard administrative tools. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by integration depth with hospital discharge systems and genealogical portal sophistication. Cost compression in the standard tier intensifies as municipal procurement officers consolidate vendor lists through framework contracts. Religious cemeteries with minimal IT infrastructure exhibit highest price sensitivity, while integrated funeral home networks absorbing HIPAA engineering costs prove least elastic.
Supply Chain Analysis
Extended payment terms from municipal cemetery authorities strain vendor cash flow, forcing software providers to secure supply-chain finance facilities against multi-year framework receivables. Engineering talent concentrates in the United States, Canada, and the United Kingdom, with cloud infrastructure provisioning drawing from hyperscaler data centers in Virginia, Oregon, and Frankfurt. Single-source vulnerability runs through specialized geospatial database providers serving plot mapping functions. Distribution runs through direct municipal procurement channels and funeral home network partnerships, bypassing traditional software reseller structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architecture disruption is accelerating cemetery software procurement cycles, with HIPAA-compliant remote access mandates compressing legacy system replacement timelines. Serverless computing collapses infrastructure barriers, enabling mid-sized vendors to challenge entrenched platform operators.
For Market Incumbents: Build switching-cost moats through deep integration with hospital discharge systems and municipal records retention frameworks. Incumbents should anchor municipal framework contracts in California, Texas, and Florida before emerging cloud-native competitors achieve critical mass. Vertical integration into geospatial survey services captures plot boundary verification workflows that third-party mapping vendors currently fragment. For New Entrants and Emerging Players: Establish a beachhead in religious cemetery segments where mobile-first grave locator interfaces displace paper-based systems with minimal IT staff requirements. Target church-affiliated burial grounds in the Midwest and Southeast United States, where procurement bypasses municipal bureaucracy. A direct-to-cemetery sales model with simplified onboarding protocols outmaneuvers enterprise-focused incumbents burdened by 18-24 month sales cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native specialists with serverless infrastructure and HIPAA compliance engineering already deployed. Acquisition targets should demonstrate live municipal framework contracts and funeral home network integrations rather than pipeline promises. Watch for inflection when municipal transparency mandates in additional jurisdictions mandate public-facing grave locator portals, accelerating replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with Hospital Systems | Seamless decedent data exchange with discharge networks captures workflow efficiency premiums for funeral home operators. |
| Geographic Expansion through Municipal Frameworks | Multi-state procurement contracts in California, Texas, and Florida lock out competitors for 3-5 year renewal cycles. |
| Acquisition of Geospatial Survey Specialists | In-house plot boundary verification eliminates third-party mapping dependencies that delay digital rollout timelines. |
| Mobile-First Grave Locator Development | Consumer-facing genealogy portals satisfy municipal transparency mandates while generating direct subscription revenue. |
| Strategic Partnership with Hyperscaler Cloud Providers | Serverless infrastructure provisioning collapses capital requirements for mid-sized cemetery authority deployments. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of municipal procurement databases, funeral home operator disclosures, HIPAA compliance filings, and cloud infrastructure spending reports. Cemetery administrators, municipal IT procurement officers, funeral home operations directors, and geospatial software engineers provided structured input across North American markets. Bottom-up deployment counts triangulate against top-down vendor revenue segmentation across cloud-based, on-premises, and hybrid architectures.
Forecast inputs incorporate deployment model adoption curves, municipal digitization mandate timelines, and genealogical research demand indices across the analysis window. Segmentation dimensions model deployment complexity, end-user technical sophistication, feature prioritization, and regional regulatory cluster. CAGRs derive from elasticity-adjusted replacement cycle compression and cloud infrastructure cost trajectory assumptions. Hospital system integration requirements and FTC Funeral Rule compliance automation intensity serve as industry-specific demand drivers.
Sensitivities concentrate around municipal budget volatility, HIPAA enforcement escalation, and cloud data residency regulation expansion. Forecasts assume continued cloud infrastructure cost decline and stable municipal procurement officer staffing levels. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Association Management Software Market
Software & Services
Embroidery Design Software Market
Software & Services
Middle-East Virtual Data Room Market
Software & Services
Contract Lifecycle Management (CLM) Solution Market
Software & Services
Business Activity Monitoring Software (BAM) Market
Software & Services
Referral Marketing Software Market
Software & Services
Statistics Software Market
Software & Services
Productivity Management Software Market
Software & Services
Software Consulting Market
Software & Services
Global Data Governance Software Market
Software & Services
Global Printing Software Market
Software & Services
Computer Assisted Translation Software Market
Software & Services
Global Legal Case Management Software Market
Software & Services
Bridge Analysis Software Market
Software & Services
Laser Engraving Software Market
Software & Services
Advanced Mobile UX Design Services Market