
 Laboratory Management Software Market | 2026-2036
Laboratory Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Laboratory Management Software Market Insights
A shortage of informatics-trained laboratory scientists is bifurcating the market between turnkey SaaS platforms and configurable enterprise suites. Thermo Fisher Scientific Inc. leverages its instrument-to-software integration to anchor large pharmaceutical accounts. LabVantage Solutions Inc. competes through modular architecture that sustains multi-site deployments across contract research organizations. Benchling Inc. differentiates via cloud-native molecular biology workflows that dominate emerging biotech segments.
Laboratory management software encompasses applications that automate sample tracking, protocol execution, instrument integration, and regulatory reporting across research and quality-control environments. These systems typically interface with analytical instruments through standardized communication protocols such as ASTM E1381 or HL7 FHIR to ensure data integrity and real-time capture. Cloud-based deployments are capturing the fastest expansion as pharmaceutical companies and clinical labs prioritize remote accessibility and reduced IT overhead, while on-premise installations retain stronger margins in defense and government laboratories with stringent data-sovereignty requirements. Academic institutions represent a growing adoption segment as grant-funded research centers modernize legacy spreadsheet-dependent operations.
FDA 21 CFR Part 11 and EU Annex 11 together establish electronic record and signature standards that determine software qualification requirements for GxP-regulated laboratories. ISO 17025 accreditation frameworks further shape functional specifications for calibration and testing labs in the United States, Germany, and Japan. EPA Good Automated Laboratory Practice standards influence environmental testing workflows and vendor selection criteria. Stakeholders must weigh interoperability investments against the risk of proprietary data lock-in as instrument manufacturers deepen their software ecosystems.
Market Dynamics
Biopharmaceutical R&D pipelines are compressing discovery timelines through cloud-native laboratory platforms that integrate instrument control with AI-driven protocol optimization, forcing legacy vendors to rearchitect monolithic codebases.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature mandates in GxP environments are accelerating replacement of paper-based systems in United States pharmaceutical quality-control labs.
- Cloud infrastructure:Remote accessibility requirements from distributed research teams are pulling SaaS deployments ahead of on-premise installations in contract research organizations.
- Germany:Academic-industrial research clusters in Baden-Württemberg and Bavaria are digitizing core laboratory infrastructure through coordinated federal funding programs.
Market Restraints
- Data sovereignty requirements:Defense and government laboratories in the United States enforce strict on-premise hosting, limiting cloud vendor addressable market.
- Integration complexity:Proprietary instrument communication protocols from dominant analytical equipment manufacturers create technical lock-in and switching costs.
- Informatics talent scarcity:Shortage of laboratory scientists trained in computational methods constrains deployment velocity across mid-sized research institutions.
Strategic Opportunities
- Cell and gene therapy workflows:Emerging biotech segments require specialized molecular biology modules that incumbent enterprise suites have not optimized.
- India:CDSCO regulatory harmonization with ICH guidelines is creating validated electronic system requirements in domestic pharmaceutical manufacturing.
- AI-ELN convergence:Integration of predictive analytics with electronic lab notebooks is opening new pricing tiers for intelligent protocol recommendation engines.
Industry Challenges
- LIMS-SDMS integration:Bridging laboratory information management with scientific data management systems requires complex data lake architectures that strain IT departments.
- ISO 17025 accreditation timelines:Calibration and testing labs face extended validation periods when migrating from legacy spreadsheet-dependent operations to automated platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laboratory Management Software Market |
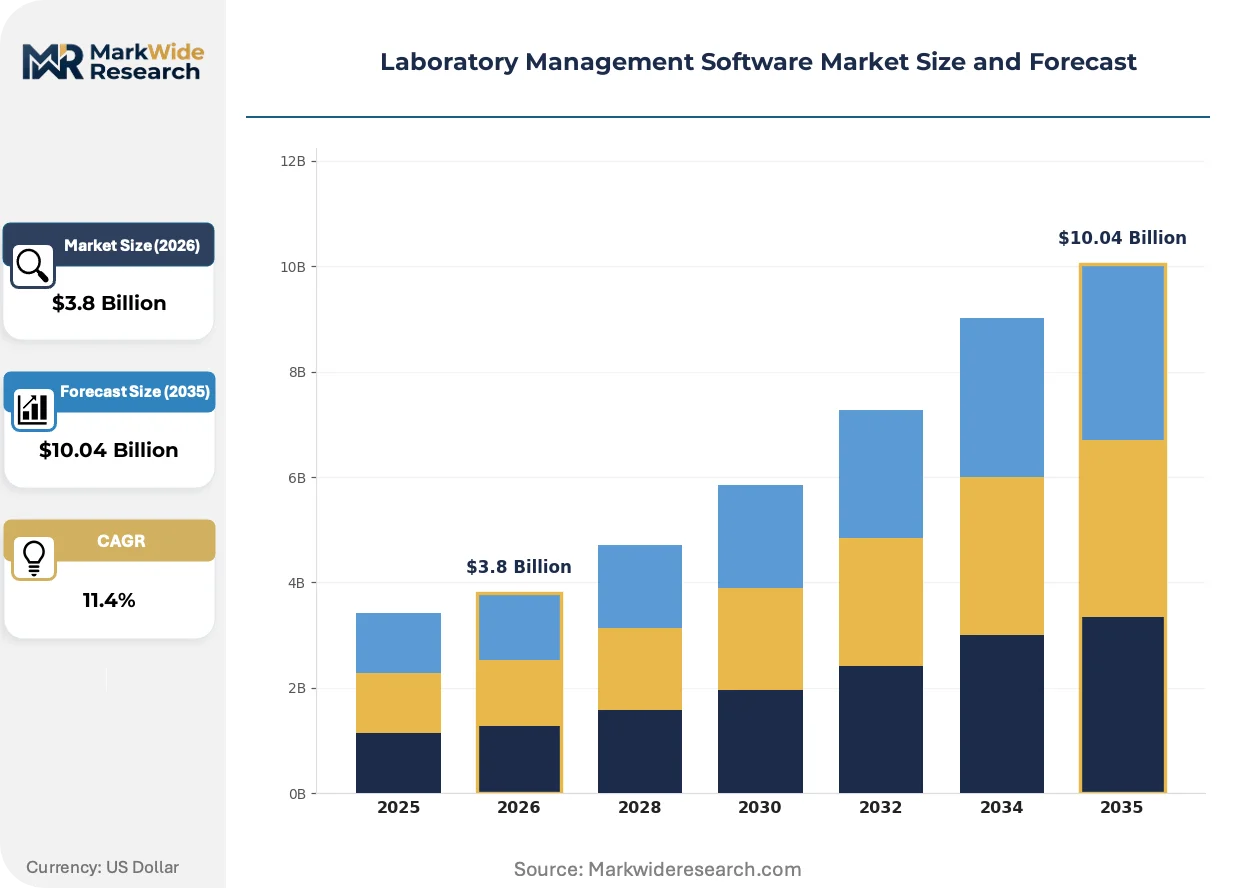
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Integrated Systems, Standalone Solutions End User: Pharmaceutical Companies, Academic Institutions, Clinical Labs, Research Organizations Application: Inventory Management, Sample Tracking, Compliance Management, Data Analysis Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-site |
| Companies Covered | Thermo Fisher Scientific Inc., LabVantage Solutions Inc., LabWare Inc., LabLynx Inc., Abbott Laboratories, STARLIMS Corporation, Autoscribe Informatics, Agilent Technologies Inc., Benchling Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laboratory Management Software Market Trends and Innovations
Edge computing architectures are redistributing data processing from centralized cloud instances to instrument-adjacent nodes, reducing latency for time-sensitive analytical workflows while complicating vendor platform strategies.
Microfluidic control software is miniaturizing experimental throughput by embedding protocol execution directly on chip-scale laboratory devices. Biotechnology startups in Boston and Basel are adopting these integrated systems for high-content screening applications. This convergence is miniaturizing the physical footprint required for equivalent experimental output, compressing facility capital requirements for emerging therapeutic developers.
EU Annex 11 updates are mandating enhanced audit trail integrity for cloud-hosted systems used in pharmaceutical manufacturing across European member states. German and French regulators are enforcing stricter vendor qualification documentation for software-as-a-service platforms handling GxP data. Contract manufacturing organizations in Ireland and the Netherlands are responding by demanding single-tenant hosting options with dedicated infrastructure isolation.
Research procurement teams are consolidating vendor relationships through enterprise-wide licensing agreements that bundle instrument, software, and service contracts. Academic medical centers and national research institutes are displacing point solutions with platform subscriptions spanning multiple laboratory sites. This pattern is most pronounced in United States research universities managing distributed core facilities across multiple campuses.
Laboratory Management Software Market Segmentation
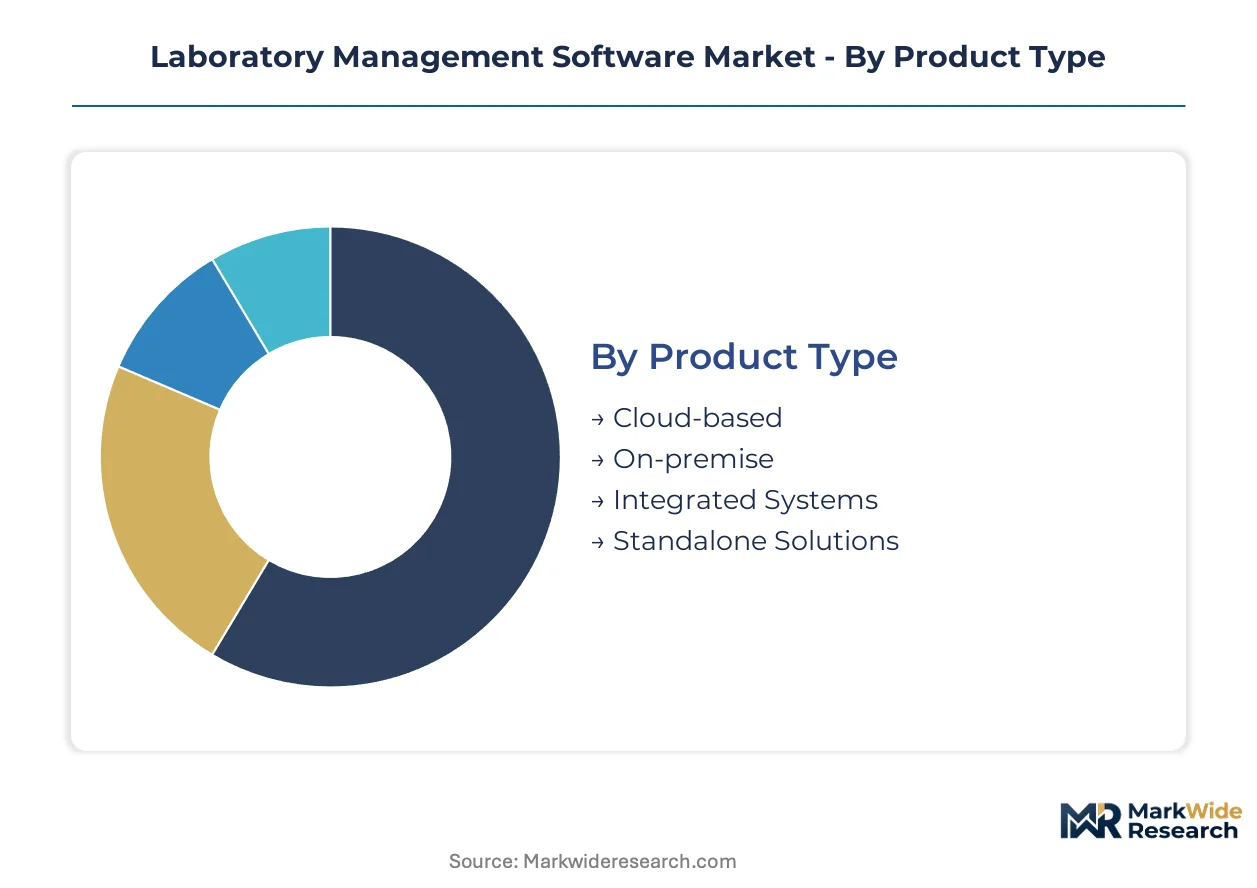
Laboratory management software vendors architect product portfolios around distinct operational requirements. Deployment preferences vary sharply between regulated pharmaceutical quality-control environments and academic research settings with lighter compliance burdens.
Product Type:
Cloud-based platforms flow through SaaS subscription channels with monthly recurring revenue models, while on-premise installations rely on perpetual licensing with annual maintenance contracts.
- Cloud-based:Multi-tenant architectures deliver remote accessibility through browser interfaces. Pharmaceutical contract research organizations in Germany and the United States prioritize these deployments for distributed team coordination.
- On-premise:Single-tenant installations run on customer-managed servers behind institutional firewalls. United States defense laboratories and government facilities mandate this architecture for data sovereignty compliance.
- Integrated Systems:Bundled instrument control and data management suites from analytical equipment manufacturers.
- Standalone Solutions:Point applications addressing specific workflows without broader enterprise connectivity.
On-premise systems dominate installed base in regulated industries. Cloud-based deployments are where expansion concentrates.
End User:
Customer type determines pricing tier and sales cycle length, with enterprise pharmaceutical accounts commanding dedicated implementation teams.
- Pharmaceutical Companies:GxP-validated environments require FDA 21 CFR Part 11 compliant electronic signatures and audit trails. United States and European quality-control labs drive premium module adoption for batch release documentation.
- Academic Institutions:Grant-funded research centers prioritize cost efficiency and multi-instrument compatibility. German universities in Baden-Württemberg and Bavaria are modernizing legacy spreadsheet operations through coordinated federal digitization programs.
- Clinical Labs:Diagnostic testing facilities processing patient samples under CLIA or ISO 15189 standards.
- Research Organizations:Non-profit institutes and government laboratories with heterogeneous instrument fleets.
Pharmaceutical companies anchor vendor revenue. Academic institutions are climbing the fastest as digitization funding expands.
Application:
Functional module selection correlates with laboratory maturity, with basic inventory management preceding advanced analytics adoption.
- Sample Tracking:Barcode and RFID-enabled chain-of-custody systems prevent misidentification in high-throughput screening facilities. Biopharmaceutical discovery labs in Boston and Basel deploy these modules to compress compound library management cycles.
- Compliance Management:Automated audit trail generation and electronic signature capture for regulatory inspections. FDA and EMA inspection readiness drives replacement of paper-based systems in United States and European manufacturing quality labs.
- Inventory Management:Reagent lot tracking and expiration alerting for consumables control.
- Data Analysis:Statistical process control and visualization tools integrated with instrument data streams.
Sample tracking commands the largest module footprint. Compliance management is gaining share fastest as regulatory enforcement intensifies.
Deployment:
Infrastructure configuration shapes total cost of ownership calculations and IT staffing requirements.
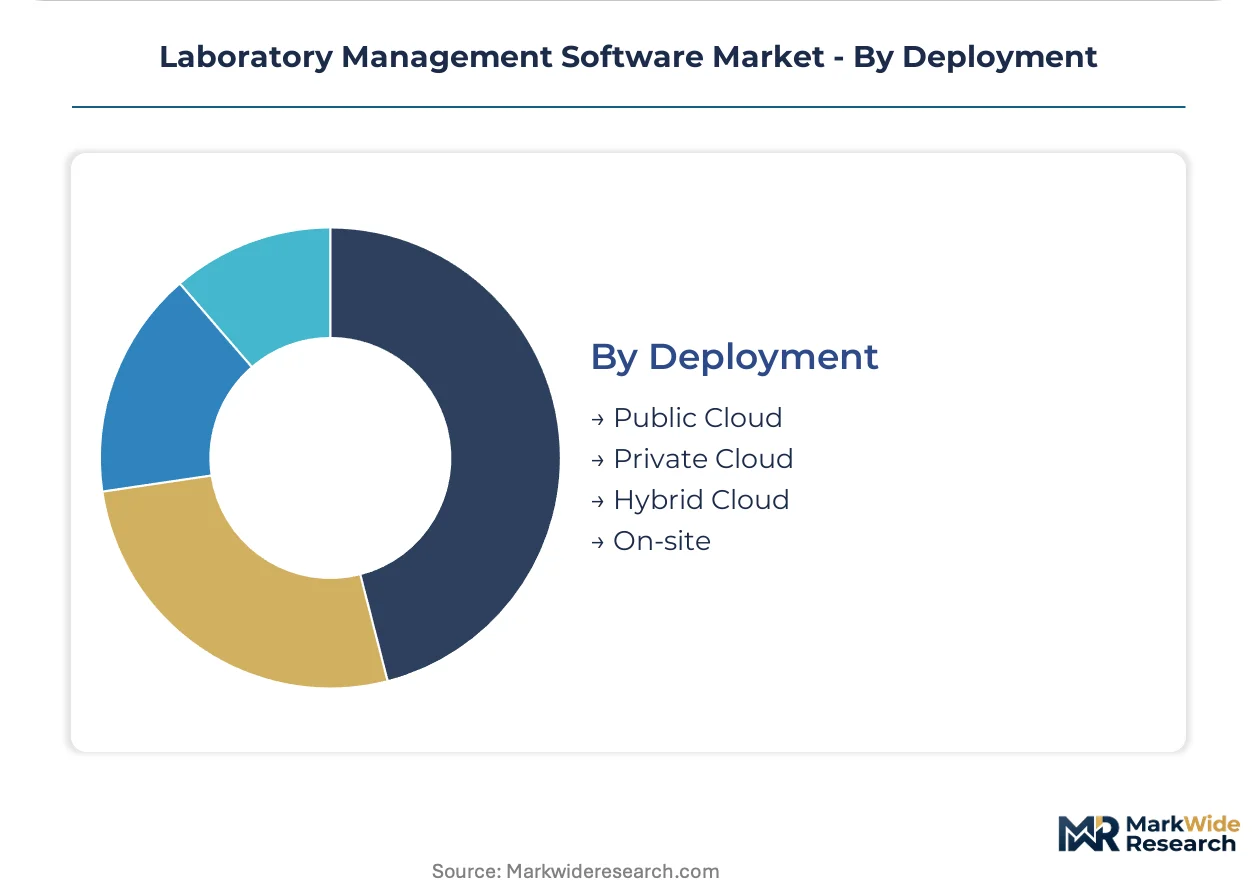
- Public Cloud:Shared infrastructure with vendor-managed security patching and scalability. Contract manufacturing organizations in Ireland and the Netherlands are adopting single-tenant isolation variants to satisfy EU Annex 11 vendor qualification demands.
- Private Cloud:Dedicated virtual environments within third-party data centers. German pharmaceutical manufacturers prefer this model for GDPR-aligned data residency.
- Hybrid Cloud:Sensitive data remains on-premise while compute-intensive analytics burst to cloud resources.
- On-site:Physical servers within laboratory facilities requiring internal IT maintenance.
On-site infrastructure retains strongest margins in defense applications. Public cloud is expanding most quickly as remote accessibility becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 compliance mandates in the United States anchor the dominant geography, while coordinated digitization programs in Germany and emerging regulatory harmonization in India reshape procurement patterns across three continents.
United States
Pharmaceutical quality-control labs in Boston and Research Triangle Park drive replacement of paper-based systems with validated electronic platforms. FDA inspection readiness requirements compress vendor selection cycles for GxP-validated deployments. The National Institutes of Health's intramural research program modernizes legacy spreadsheet operations across Maryland and Bethesda facilities.
Germany
Academic-industrial clusters in Baden-Württemberg and Bavaria digitize core laboratory infrastructure through coordinated federal funding. EU Annex 11 updates mandate enhanced audit trail integrity for cloud-hosted pharmaceutical manufacturing systems. Contract manufacturing organizations in Frankfurt-Rhine-Main demand single-tenant hosting with dedicated infrastructure isolation.
India
Domestic pharmaceutical manufacturers in Hyderabad and Ahmedabad adopt validated electronic systems as CDSCO regulatory harmonization with ICH guidelines advances. The country's national pharmaceutical regulator tightens documentation standards for active pharmaceutical ingredient exports. Research institutions in Bangalore and Pune modernize grant-funded operations through cloud-native platform adoption.
United Kingdom
Academic medical centers in London and Cambridge consolidate vendor relationships through enterprise-wide licensing agreements spanning distributed core facilities. MHRA alignment with FDA electronic record standards shapes qualification requirements for biopharmaceutical quality labs. The Oxford-Cambridge arc attracts molecular biology software specialists serving emerging therapeutic developers.
Japan
PMDA guidance on computerized systems in GxP environments accelerates migration from legacy laboratory data management. Pharmaceutical manufacturers in Osaka and Tokyo prioritize instrument-to-software integration for high-throughput screening facilities. METI-funded smart factory initiatives extend to analytical laboratory automation in the Kansai industrial corridor.
Laboratory Management Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with instrument manufacturers leveraging hardware-software bundling against pure-play SaaS vendors. The market structure rewards vertical integration in regulated pharmaceutical accounts while favoring modular architectures in contract research organizations. Three archetypes dominate: instrument-anchored suites, cloud-native molecular biology platforms, and configurable enterprise systems. Consolidation pressures intensify as biopharmaceutical R&D timelines compress and AI-driven protocol optimization becomes table stakes.
Within the instrument-anchored tier, Thermo Fisher Scientific Inc. and Agilent Technologies Inc. exemplify the integration advantage, while Benchling Inc. occupies a distinct position among cloud-native specialists serving emerging biotech segments. LabVantage Solutions Inc. represents the modular enterprise archetype sustaining multi-site contract research organization deployments. These three patterns illustrate how vendor strategies diverge based on customer scale, regulatory burden, and workflow complexity rather than converging on a single dominant model.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| LabVantage Solutions Inc. |
| LabWare Inc. |
| LabLynx Inc. |
| Abbott Laboratories |
| STARLIMS Corporation |
| Autoscribe Informatics |
| Agilent Technologies Inc. |
| Benchling Inc. |
| Others |
Pricing and Supply Chain Analysis
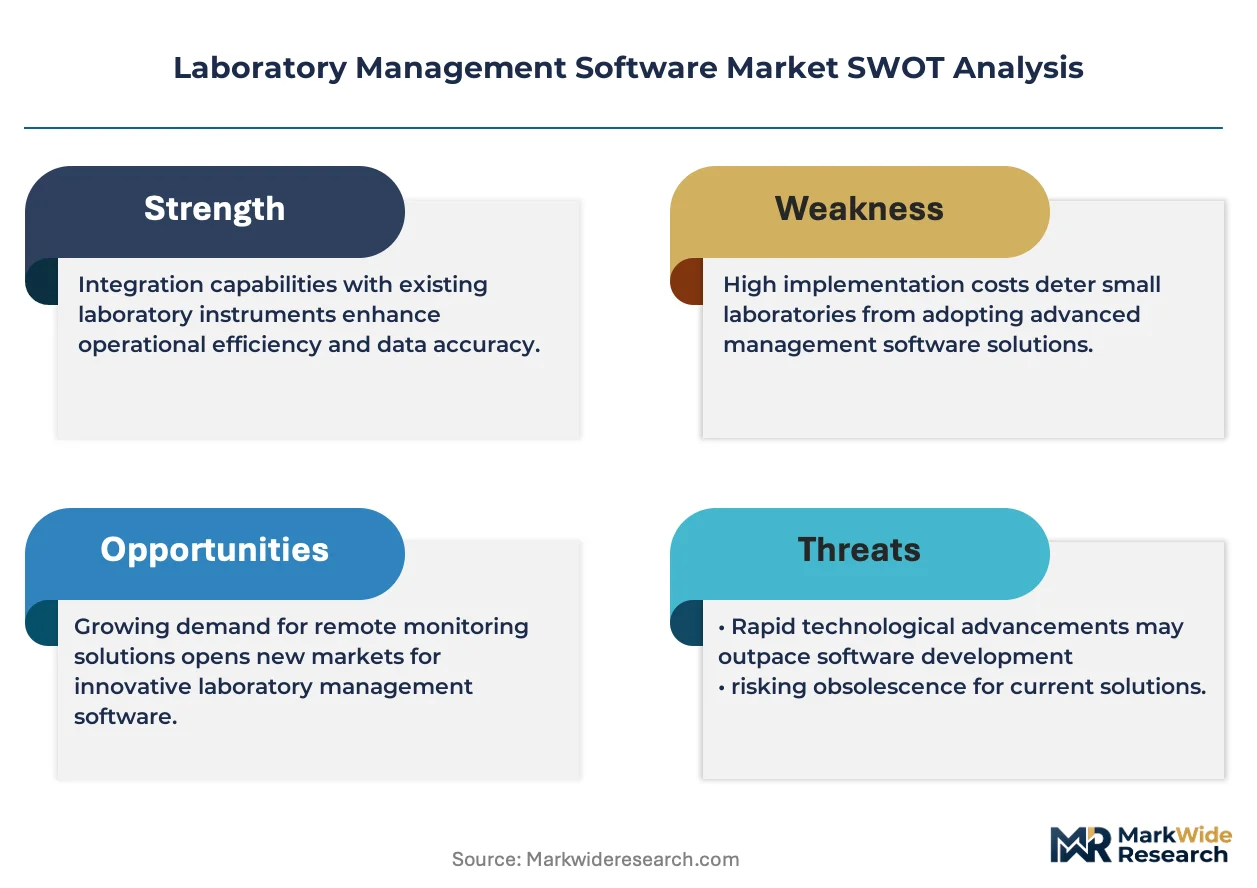
Server farm utilization rates above 85% in hyperscale cloud regions generate substantial economies of scale for SaaS vendors, compressing per-seat delivery costs while concentrating pricing power among platform operators with multi-tenant infrastructure in Germany and the United States. This scale dynamic simultaneously elevates price floors for smaller competitors lacking comparable capacity and rewards vertical integration by instrument manufacturers seeking to bundle hardware-software margins.
Pricing Analysis
Annual subscription spreads between German pharmaceutical quality-control deployments and Indian academic installations exceed 4x, reflecting divergent compliance overhead and customization depth. Pricing stratifies across GxP-validated enterprise suites, configurable mid-market platforms, and lightweight SaaS tiers for emerging biotech. Cost compression in the mid-market tier is intensifying as Benchling and cloud-native entrants compete on implementation speed. Academic institutions exhibit highest price sensitivity; FDA-regulated pharmaceutical manufacturers prioritize audit trail integrity over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for analytical instrument components sourced from Japan and South Korea. Software development capacity concentrates in the United States, Germany, and India, with Bangalore and Pune emerging as delivery hubs for cloud-native platform engineering. Single-source vulnerability persists for specialized chromatography data systems tethered to proprietary instrument protocols. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and channel partners for academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across deployment models, compliance tiers, and scientific workflows creates multiple specialization opportunities. Cell and gene therapy digitization demands are fragmenting demand into molecular-biology-specific niches underserved by incumbent enterprise suites.
For Market Incumbents:Fortify instrument-to-software integration moats through deeper ASTM E1381 protocol support and embedded AI-driven protocol optimization. Prioritize FDA 21 CFR Part 11 pre-validation investments to accelerate pharmaceutical procurement cycles. Acquire cloud-native specialists in Boston and Basel to neutralize Benchling's emerging biotech penetration before cell therapy workflows standardize.
For New Entrants and Emerging Players:ISO 17025 fast-track certification for calibration and testing lab segments offers the most penetrable entry vector, as incumbent suites over-serve these lighter compliance environments. Target contract research organizations in Ireland and the Netherlands demanding single-tenant cloud isolation under EU Annex 11. Lead with API-first architecture enabling rapid LIMS-SDMS integration without legacy data lake complexity.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors modular enterprise platforms with multi-site deployment track records over monolithic suites requiring rearchitecture. Five-to-ten year viability hinges on AI-ELN convergence capabilities and cell therapy workflow coverage. Watch CDSCO regulatory harmonization progress in India as inflection signal for validated system demand acceleration in domestic pharmaceutical manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded AI protocol optimization compresses biopharmaceutical discovery timelines for competitive advantage. |
| Acquisition of Specialist Firm | Cell therapy workflow expertise addresses white-space segments beyond incumbent enterprise suite coverage. |
| Regulatory Approval Pathway | FDA 21 CFR Part 11 pre-validation accelerates pharmaceutical quality-control procurement decisions. |
| Strategic Partnership | Single-tenant cloud hosting partnerships satisfy EU Annex 11 vendor qualification demands in Ireland. |
| Geographic Expansion | CDSCO-aligned validation investments capture emerging electronic system requirements in Hyderabad manufacturing. |
Research Methodology
Operator-level perspectives from laboratory informatics directors, GxP compliance officers, pharmaceutical procurement managers, and academic core facility administrators anchored the qualitative base. Primary interview findings triangulated against secondary sources including FDA 483 inspection observations, EMA GMP inspection databases, ISO 17025 accreditation registries, and vendor SEC filings. Bottom-up deployment counts across cloud and on-premise installations reconciled with top-down pharmaceutical R&D spending allocations.
Sensitivity analysis tested forecast robustness across cloud adoption acceleration scenarios and regulatory enforcement intensity variations over the projection horizon. Segmentation modeling incorporated deployment architecture, organization scale, scientific workflow complexity, vertical industry, and regional regulatory cluster dimensions. CAGRs derived from instrument shipment correlations, SaaS booking disclosures, and grant funding trajectories in German academic clusters.
Decision-makers should treat outputs as directional under assumptions of sustained FDA 21 CFR Part 11 enforcement and stable cloud infrastructure pricing; material deviation in regulatory harmonization timelines or hyperscale cost structures would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Email Optimization Software Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Radio Propagation Software Market
Software & Services
Stock Footage Software Market
Software & Services
Talent Management Software Market
Software & Services
Dealer Management System Market
Software & Services
Software Market
Software & Services
Royalty Management Software and Services Market
Software & Services
RIP Software Market
Software & Services
Intellectual Property Software Market
Software & Services
Over-The-Air Software Update Market
Software & Services
Global CMDB Software Market
Software & Services
Artwork Management Software Market
Software & Services
Document-Centric Collaboration Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Global Content Management Software Market