
 Dental Practice Management Software Market | 2026-2036
Dental Practice Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Practice Management Software Market Analysis
North American software development capacity is reshaping competitive dynamics in dental practice technology. CareStack leverages cloud-native architecture to anchor multi-location deployment contracts across large dental service organizations. Dentrix sustains deep integration with imaging hardware and payer networks, occupying a dominant position in established private practices. Tebra differentiates through combined practice management and patient engagement tools, competing aggressively for mid-market group practices.
Dental practice management software comprises integrated digital platforms that coordinate administrative, clinical, and financial operations within oral healthcare delivery settings. These systems typically incorporate HL7 FHIR interoperability standards, encrypted patient data repositories, and real-time scheduling algorithms to streamline practice workflows and ensure regulatory compliance. Cloud-based solutions now lead deployment preferences due to lower capital requirements and automatic security patching, while hybrid solutions capture practices transitioning legacy on-premises infrastructure. Patient records functionality commands concentrated investment as interoperability mandates intensify, and billing management modules attract margin focus from group practices navigating complex payer environments.
FDA oversight of software-as-medical-device classifications and HIPAA security rule enforcement directly shape product development roadmaps and customer procurement criteria in the United States market. State dental boards impose additional operational requirements that vendors must accommodate through configurable compliance templates. Stakeholders should monitor evolving federal cybersecurity certification programs and state-level data breach notification laws that will determine platform viability and customer retention trajectories.
Market Dynamics
Cloud migration pressure from dental service organizations is compressing deployment cycles and forcing vendors to rearchitect legacy platforms for multi-tenancy. HIPAA security rule enforcement and state-level breach notification laws are accelerating replacement demand among practices still operating on-premises infrastructure.
Growth Catalysts
- HIPAA Security Rule:Enforcement actions against dental practices with inadequate data safeguards are driving mandatory platform upgrades and cloud migration decisions.
- Dental service organizations:Consolidation of independent practices into multi-location networks creates concentrated demand for centralized scheduling and unified billing systems.
- HL7 FHIR interoperability:Federal mandates for seamless health data exchange are compelling vendors to invest in standardized APIs that connect practice management systems with hospital EHRs and payer networks.
Market Restraints
- Legacy data migration costs:Practices with decades of patient records face substantial extraction and validation expenses when transitioning from on-premises servers to cloud environments.
- Specialized dental IT talent scarcity:Limited supply of technicians trained in both clinical workflows and cybersecurity protocols constrains implementation velocity.
- State dental board variability:Inconsistent operational requirements across jurisdictions force vendors to maintain costly configurable compliance templates rather than standardized deployments.
Strategic Opportunities
- Teledentistry integration:Regulatory recognition of remote oral health consultations creates white space for platforms embedding synchronous video and asynchronous imaging workflows.
- Artificial intelligence convergence:Machine learning models for radiographic interpretation are hybridizing with practice management systems to automate diagnostic coding and treatment planning.
- Patient engagement channels:Two-way texting and automated recall systems represent underpenetrated modules that reduce no-show rates and accelerate revenue cycle velocity.
Industry Challenges
- Cybersecurity certification timelines:Federal programs evaluating healthcare software security are creating procurement delays as practices await vendor compliance verification.
- Interoperability implementation complexity:Mapping proprietary data schemas to HL7 FHIR standards requires specialized engineering resources that stretch vendor development capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Practice Management Software Market |
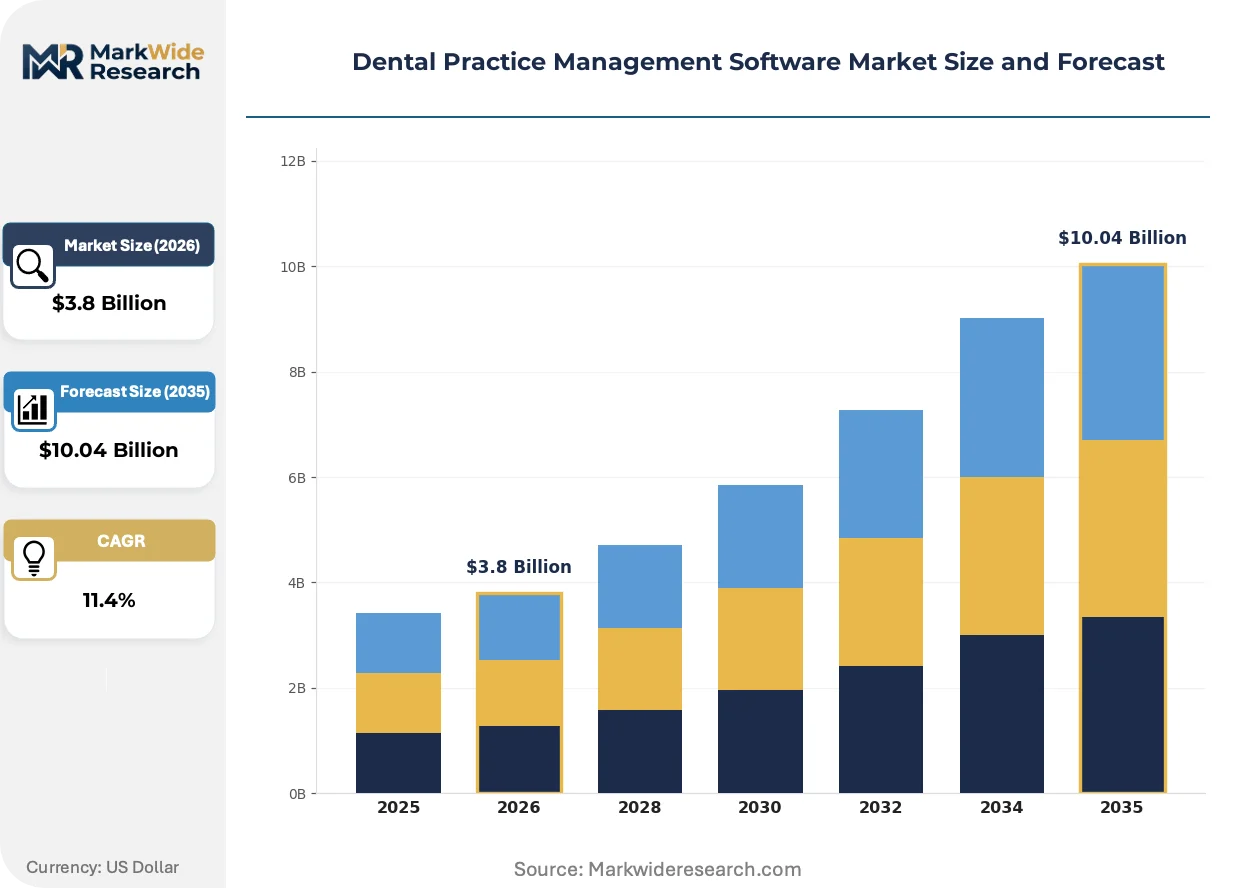
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Mobile Applications End User: Private Practices, Dental Clinics, Group Practices, Orthodontic Offices Functionality: Appointment Scheduling, Billing Management, Patient Records, Inventory Control Deployment: Single-Location Deployment, Multi-Location Deployment, Remote Setup, In-House Installation |
| Companies Covered | CareStack, NextGen Healthcare, Dentrix, DentiMax, Tebra, Open Dental, Denticon, AdvancedMD, Curve Dental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Practice Management Software Market Emerging Trajectories
Artificial intelligence and automation are penetrating core clinical workflows, while regulatory pressure intensifies around data security and interoperability standards. Vendors are racing to embed predictive capabilities that reduce administrative burden and improve patient retention metrics.
Natural language processing for clinical documentation is hybridizing voice-to-text capture with structured data entry, allowing dentists to generate compliant notes without keyboard interaction. Solo practitioners and small group practices are adopting these tools fastest, driven by staffing constraints and documentation burden. The technology is compressing the gap between clinical encounter completion and claim submission, reducing accounts receivable cycles by eliminating transcription delays.
FDA software-as-medical-device classifications are tightening oversight of diagnostic algorithms embedded within practice management platforms, requiring premarket submissions for AI-powered radiographic analysis tools. Vendors must now maintain quality management systems and clinical validation datasets previously unnecessary for administrative software. Large dental service organizations are responding by centralizing procurement through dedicated compliance teams that evaluate regulatory documentation before contract execution.
Subscription pricing models are displacing perpetual licenses across the mid-market, with practices prioritizing predictable operating expenditures over capital-intensive server purchases. Vendor financing arrangements and usage-based tiers are replacing upfront implementation fees, particularly among newly established practices and recent dental school graduates. This shift is most visible in metropolitan markets with high practice turnover and competitive patient acquisition environments.
Dental Practice Management Software Market Segmentation
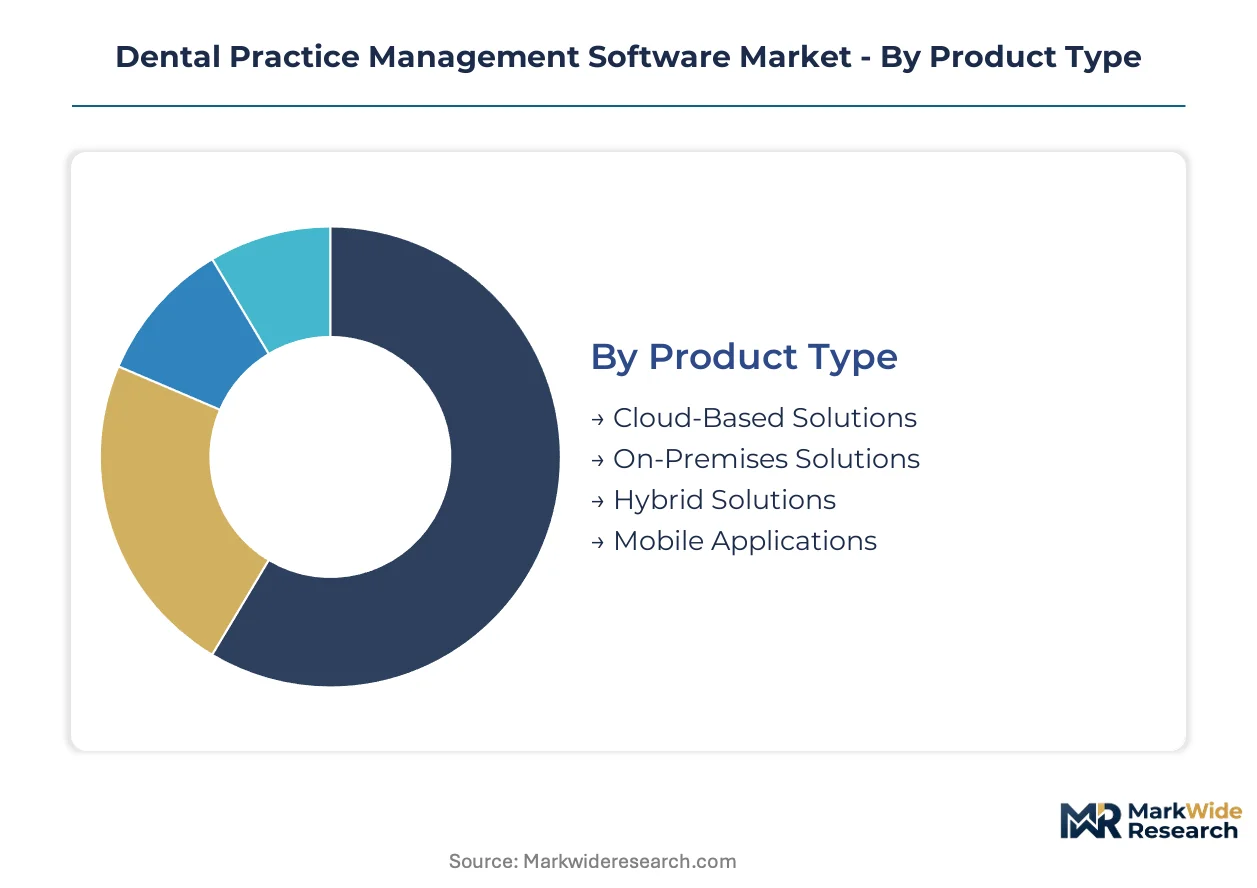
Dental practice management software segments reflect divergent technology maturity and procurement priorities across practice types. Cloud migration patterns and regulatory compliance requirements reshape how vendors architect solutions for distinct operational scales.
Product Type:
Cost tier differentiation separates capital-intensive perpetual licenses from subscription-based operational expenditure models.
- Cloud-Based Solutions:Multi-tenant SaaS architectures deliver automatic security patching and remote accessibility. Dental service organizations in the United States concentrate procurement here, driven by HIPAA enforcement actions mandating off-premises data protection with vendor-managed encryption.
- On-Premises Solutions:Local server installations maintain full data custody within practice walls. Established private practices with decades of patient records retain these systems, constrained by legacy data migration costs and specialized dental IT talent scarcity during transition planning.
- Hybrid Solutions:Bridging architectures accommodate phased cloud migration for mid-size group practices.
- Mobile Applications:Native iOS and Android interfaces extend core functionality for chairside documentation and patient communication.
Cloud-based solutions command the established base. The steepest expansion runs through hybrid deployments.
End User:
Customer type determines feature complexity and integration depth requirements across the care delivery spectrum.
- Group Practices:Multi-location networks require centralized scheduling, unified billing, and consolidated reporting dashboards. These organizations in North America drive concentrated demand for HL7 FHIR interoperability to connect with hospital EHRs and payer networks under federal mandates.
- Private Practices:Solo and small-group operators prioritize intuitive interfaces and minimal IT overhead. Practices across the United States select streamlined cloud packages, responding to staffing constraints and documentation burden through natural language processing tools.
- Dental Clinics:High-volume community health centers need Medicaid billing specialization and sliding-scale fee management.
- Orthodontic Offices:Extended treatment timelines demand specialized recall systems and progress tracking modules.
Private practices anchor volume share. Group practices are gaining share fastest through consolidation waves.
Functionality:
Application criticality varies by regulatory pressure and revenue cycle proximity.
- Patient Records:Encrypted repositories with HL7 FHIR standardization form the compliance core. Investment concentrates here as interoperability mandates intensify across United States dental networks requiring seamless health data exchange.
- Billing Management:Claims scrubbing, electronic submission, and denial management modules attract margin focus. Group practices navigating complex payer environments prioritize these tools to accelerate revenue cycle velocity.
- Appointment Scheduling:Real-time algorithms optimize chair utilization and reduce no-show rates.
- Inventory Control:Supply tracking and automated reorder points manage consumable costs for high-volume operators.
Patient records functionality commands the established base. The steepest expansion runs through billing management.
Deployment:
Volume scale and geographic distribution dictate infrastructure architecture choices.
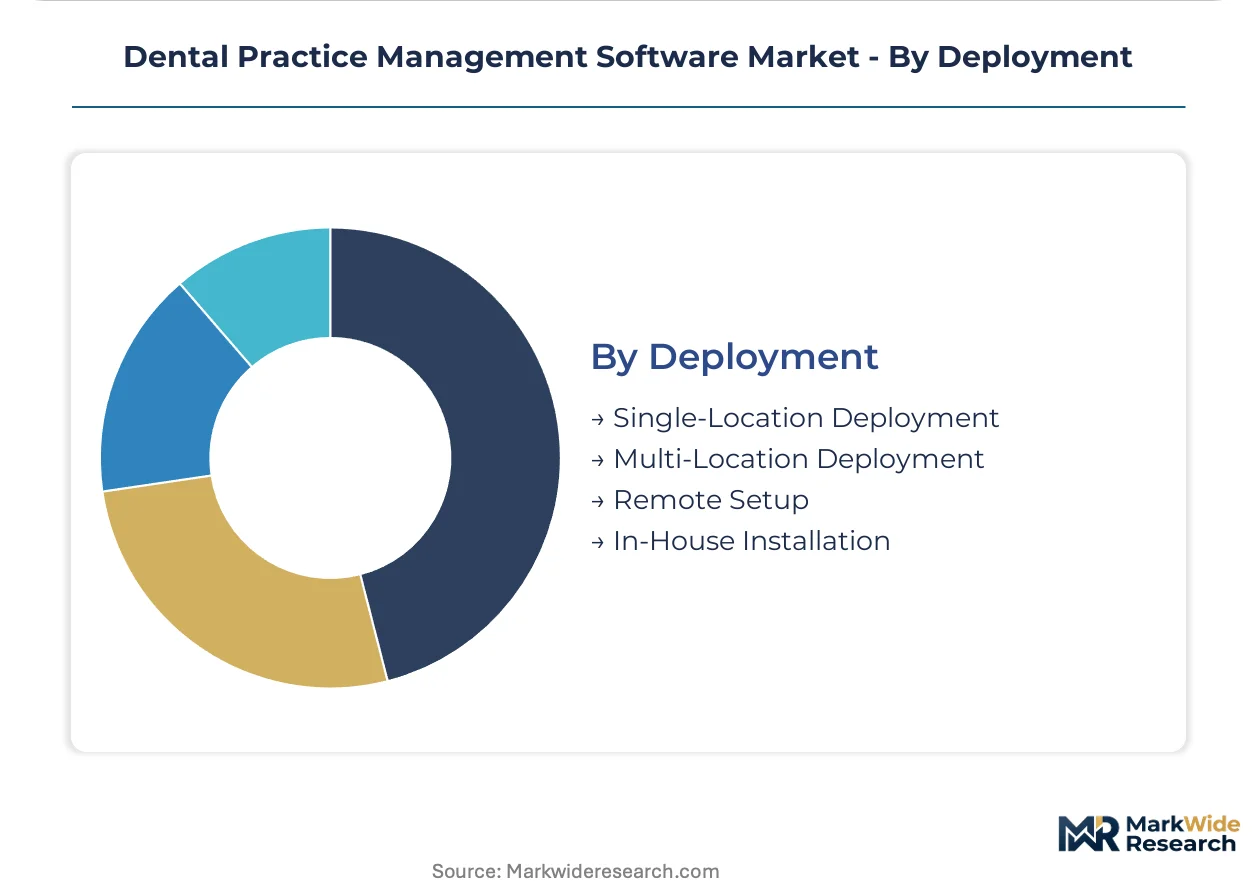
- Multi-Location Deployment:Centralized data repositories with distributed access points serve expanding dental service organizations. These implementations in the United States require configurable compliance templates accommodating state dental board variability across jurisdictions.
- Single-Location Deployment:Standalone instances suit independent practitioners with localized operational needs. Solo operators favor these streamlined configurations to minimize cybersecurity certification timeline delays affecting procurement decisions.
- Remote Setup:Zero-touch provisioning enables rapid activation without on-site technical presence.
- In-House Installation:On-premise server configuration with direct vendor technician support.
Single-location deployment commands the established base. The steepest expansion runs through multi-location deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
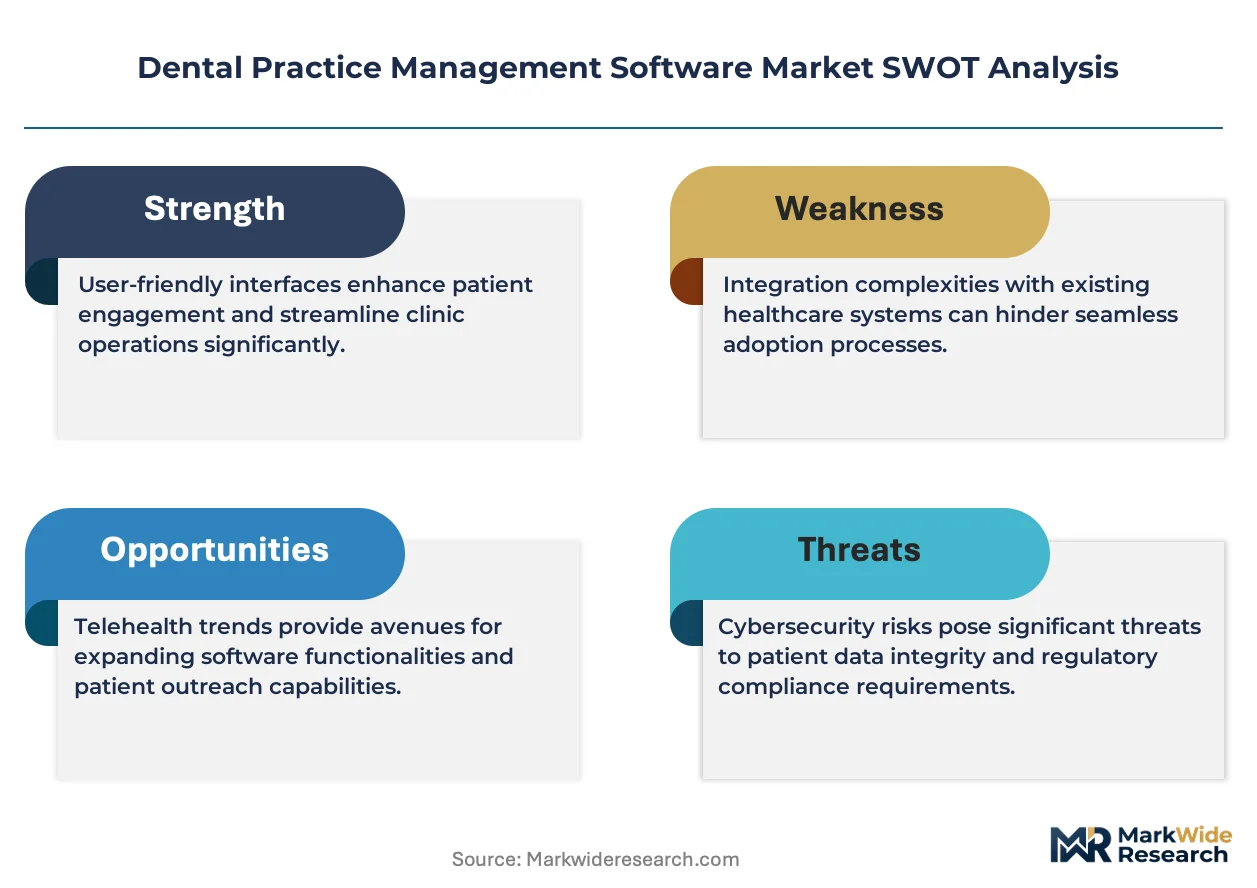
FDA software-as-medical-device classifications and HIPAA enforcement actions anchor the United States as the dominant geography for dental practice management software procurement and platform development.
United States
Dental service organizations in Texas and Florida drive concentrated demand for multi-tenant cloud architectures capable of centralized scheduling across dozens of locations. HIPAA Security Rule enforcement actions from the Office for Civil Rights accelerated replacement cycles among practices operating legacy on-premises servers through 2023 and 2024. The Dallas-Fort Worth metroplex hosts a cluster of dental support organizations actively consolidating independent practices into unified technology platforms.
Germany
Mid-size group practices in Bavaria and North Rhine-Westphalia prioritize HL7 FHIR interoperability to connect with hospital EHR networks under the European Health Data Space implementation timeline. The country's national pharmaceutical regulator, BfArM, maintains oversight of software with diagnostic algorithms, creating compliance documentation requirements for vendors embedding AI-powered radiographic tools. Berlin's dental technology corridor attracts platform developers seeking proximity to European payer standardization bodies.
United Kingdom
NHS dental contract reform pressures practice owners in Greater London and the Midlands toward automated reporting and unified billing systems that reduce administrative overhead. The Medicines and Healthcare products Regulatory Agency evaluates software-as-medical-device classifications for diagnostic modules, influencing procurement criteria among corporate dental chains. Manchester's health innovation district hosts pilot programs testing teledentistry integrations with primary care networks.
India
Cloud-native deployments accelerate among multi-location dental chains in Maharashtra and Karnataka seeking to bypass capital-intensive server infrastructure. The Central Drugs Standard Control Organization under the Ministry of Health and Family Welfare establishes software oversight frameworks for diagnostic algorithms, shaping vendor entry strategies. Hyderabad's health technology cluster incubates practice management platforms targeting price-sensitive solo practitioners across tier-2 and tier-3 cities.
Japan
Metropolitan Tokyo and Osaka dental clinics adopt patient engagement modules featuring automated recall systems and two-way texting to address persistent staffing shortages. The Ministry of Economy, Trade and Industry promotes healthcare software standardization through JIS certification programs that influence procurement decisions among large group practices. Yokohama's medical device corridor hosts integration specialists connecting practice management systems with national health insurance claim submission protocols.
Dental Practice Management Software Market Vendor Landscape
Cloud-native specialists and legacy platform incumbents split the market between rapid-deployment SaaS architectures and deeply integrated on-premises ecosystems. Consolidation pressures from dental service organizations favor vendors with proven multi-tenancy capabilities, while independent practices sustain demand for streamlined interfaces with minimal IT overhead. Two strategic archetypes dominate: vertically integrated health technology conglomerates and focused dental software pure-plays. Competitive intensity manifests through M&A activity targeting regional cloud providers and strategic partnerships bridging practice management with payer networks.
Within the cloud-native tier, CareStack and Tebra exemplify architectures designed for dental service organization scale, while Dentrix occupies a position representing legacy incumbents with deep imaging hardware integration. Henry Schein One's Dentrix platform anchors the established private practice segment through decades of payer network relationships. These three companies illustrate the strategic divergence between rapid cloud migration and incremental modernization paths.
| Leading Market Players |
|---|
| CareStack |
| NextGen Healthcare |
| Dentrix |
| DentiMax |
| Tebra |
| Open Dental |
| Denticon |
| AdvancedMD |
| Curve Dental |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific data corridor costs are compressing margins for cloud-native vendors serving multi-location dental service organizations, concentrating pricing power among platforms with vendor-managed encryption and automatic security patching while forcing tiered differentiation between premium HIPAA-compliant tiers and stripped-down economy packages for solo practitioners.
Pricing Analysis
Metropolitan markets in Texas and Florida command subscription premiums against tier-2 city benchmarks. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in HL7 FHIR interoperability depth and AI-powered radiographic module inclusion. Cost compression in the economy tier intensifies because newly graduated dentists prioritize predictable operating expenditures. Solo practitioners exhibit highest price sensitivity, while dental service organizations absorb premium tiers for centralized compliance management.
Supply Chain Analysis
Tariff exposure between the United States and China dominates hardware component sourcing for on-premises server installations. Software development concentrates in the United States, India, and Germany, with cloud infrastructure drawing from hyperscaler data centers in Virginia, Oregon, and Frankfurt. Single-source vulnerability persists in specialized dental IT talent pipelines. Distribution runs through direct vendor sales teams for enterprise contracts and value-added resellers for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dental practice management software sits in early-cycle expansion, with cloud migration penetration among independent practices still below saturation and HIPAA enforcement creating forced replacement waves that expand the addressable base beyond organic growth.
For Market Incumbents: Pre-empt cloud-native challengers by embedding teledentistry modules and AI diagnostic workflows before FDA software-as-medical-device classifications tighten compliance documentation requirements. Acquire regional cloud providers with proven multi-tenancy architectures to accelerate dental service organization contract velocity. Deepen vertical integration into patient engagement channels through in-house development of two-way texting and automated recall systems.
For New Entrants and Emerging Players: Tier-2 and tier-3 cities in India and Southeast Asia present underpenetration white space where capital-intensive server infrastructure barriers deter legacy incumbents. Target solo practitioners with mobile-first documentation tools that bypass keyboard interaction through natural language processing. Pursue channel partnerships with dental schools and recent graduate financing programs to establish early workflow habits.
For Investors and Strategic Acquirers: Cloud-native mid-cap specialists with HL7 FHIR certification and proven multi-location deployment contracts represent the most defensible acquisition archetype. Long-term viability hinges on regulatory moats around FDA diagnostic algorithm oversight and cybersecurity certification programs. Monitor federal cybersecurity verification timelines as the critical inflection signal for vendor procurement delays and customer retention trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | HL7 FHIR interoperability connects practice management systems with hospital EHRs under federal mandates. |
| Acquisition of Specialist Firm | Regional cloud providers with multi-tenancy expertise accelerate dental service organization contract penetration. |
| Product Launch | Teledentistry modules embedding synchronous video capture regulatory-recognized remote consultation revenue. |
| Strategic Partnership | Payer network alliances streamline electronic claims submission and denial management for group practices. |
| Geographic Expansion | Zero-touch provisioning in tier-2 Indian cities bypasses capital barriers for price-sensitive solo practitioners. |
Methodological Framework
Cross-validation between primary fieldwork with dental practice owners and secondary analysis of HIPAA enforcement actions anchors the qualitative findings. Interviews with dental service organization technology officers, private practice administrators, dental school clinic directors, and payer network integration specialists combined with FDA software-as-medical-device filings, CMS Medicare reimbursement data, state dental board operational requirement databases, and cloud vendor security certification disclosures. Bottom-up practice-level deployment estimates and top-down vendor revenue triangulation produced segment-level market sizing.
Calibration against historical cloud migration velocity in adjacent healthcare verticals shaped the projection framework. Modeled dimensions span deployment architecture, practice scale, functionality module penetration, and regional regulatory enforcement intensity. CAGRs derived from segment-level growth rate synthesis weighted by procurement cycle timing. Forecast inputs include dental service organization consolidation pace and federal cybersecurity certification program rollout schedules across the analysis window.
Practitioners should monitor HIPAA Security Rule enforcement action frequency and FDA diagnostic algorithm classification timelines for early signals of replacement demand acceleration. Forecasts reflect assumptions around cloud migration cost curves and interoperability mandate implementation pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Strategy Management Software Market
Software & Services
Runtime Software Market
Software & Services
Global Recipe Apps Market
Software & Services
Skills Management Software Market
Software & Services
Ad Creation Software Market
Software & Services
Metal Recycling Software Market
Software & Services
India Software Services Export Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Global Guidewire Market
Software & Services
Time Series Databases Software Market
Software & Services
Global Personalisation Software Market
Software & Services
Software-Defined Machine Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Global Webinar Software Market
Software & Services
Global PPC Software Market
Software & Services
Russian IT Software and Services Market