
 Association Management Software Market | 2026-2036
Association Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Association Management Software Market Analysis
North American SaaS infrastructure expansion is reshaping how association management software reaches end users. Fonteva leverages native Salesforce architecture to anchor enterprise-scale deployments for professional associations. Protech specializes in Microsoft Dynamics integration, competing directly in the mid-market trade association segment. Wild Apricot sustains a low-code positioning that dominates small membership organizations with limited IT staff.
Association management software integrates constituent relationship management, event orchestration, financial processing, and communication workflows into unified platforms, typically delivered through multi-tenant cloud architectures with API-first design for third-party connectivity. Its primary commercial purpose is reducing administrative overhead while improving member retention through automated engagement tracking. Cloud-based deployment leads segment value generation due to recurring revenue predictability and lower total cost of ownership for non-profits with constrained capital budgets. Member engagement features represent the fastest-expanding capability cluster as associations prioritize personalized communication portals over traditional broadcast tools. On-premises licensed software occupies a shrinking but margin-rich niche among organizations with stringent data residency requirements.
GDPR enforcement by European national regulators shapes product development roadmaps, forcing vendors to implement granular consent management and cross-border data transfer protocols. The EU AI Act introduces additional compliance layers for automated member scoring and predictive churn algorithms. In the United States, state-level privacy legislation in California and Virginia fragments the regulatory landscape, creating patchwork compliance obligations for SaaS providers. Stakeholders must monitor how emerging AI governance frameworks redefine permissible automation in member-facing workflows.
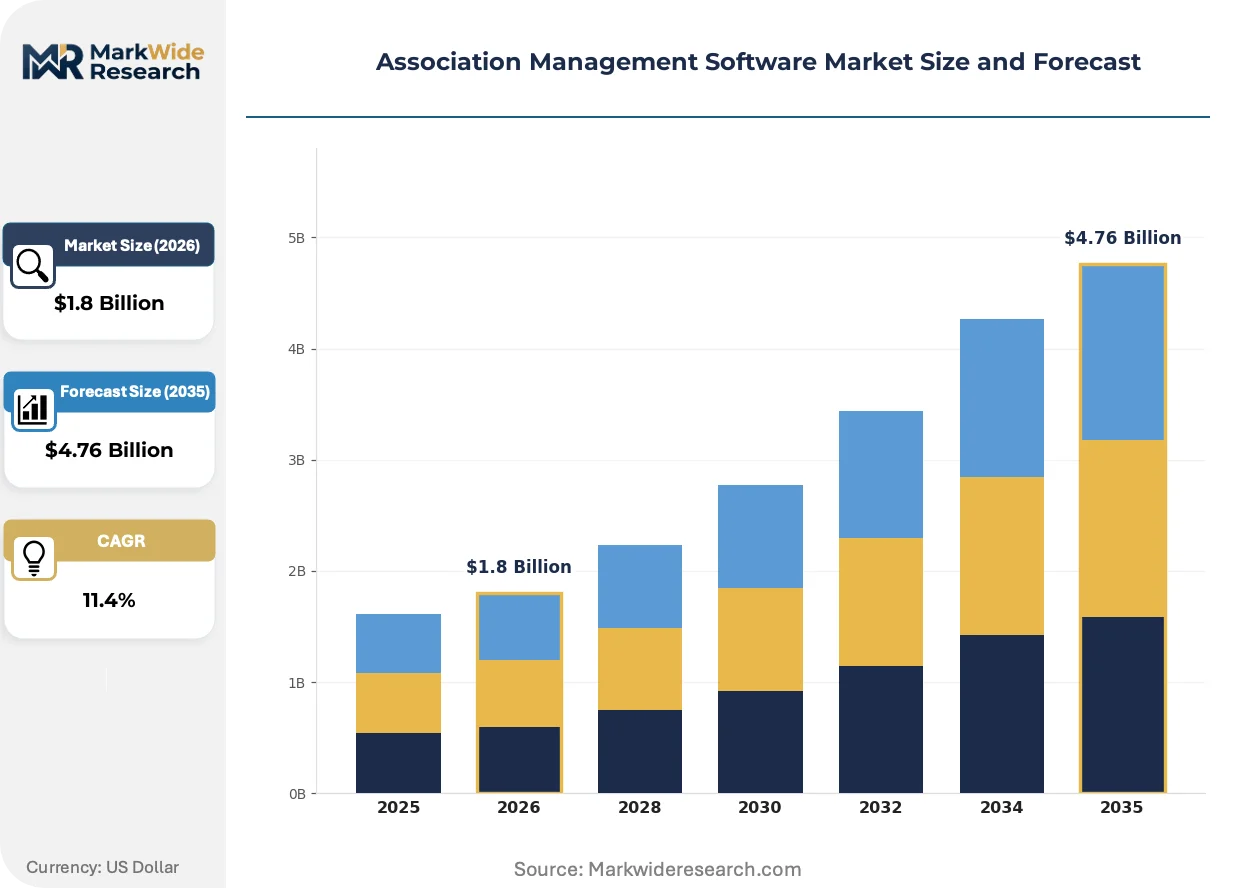
Market Dynamics
Cloud migration mandates under Europe's GDPR and the EU AI Act are compelling vendors to re-architect data governance layers, while professional associations in the United States accelerate replacement of legacy on-premises systems with API-first SaaS platforms.
Growth Catalysts
- GDPR Enforcement:European national regulators mandate granular consent management, forcing vendors to develop compliant cross-border data transfer protocols that unlock enterprise adoption.
- Professional Association Modernization:Trade associations prioritize member engagement platforms over traditional broadcast tools, driving subscription renewals through automated churn prediction.
- API-First Architecture:Multi-tenant cloud designs with native third-party connectivity reduce integration costs for non-profits with constrained capital budgets.
Market Restraints
- Data Residency Requirements:Stringent localization mandates in Germany and France sustain margin-rich on-premises niches, fragmenting vendor R&D investment.
- State-Level Privacy Fragmentation:California Consumer Privacy Act and Virginia Consumer Data Protection Act create patchwork compliance obligations for SaaS providers operating across multiple US jurisdictions.
- Legacy System Lock-In:Decades-old custom databases in established professional associations impose prohibitive switching costs and extended migration timelines.
Strategic Opportunities
- EU AI Act Compliance Services:Automated member scoring and predictive churn algorithms require new governance frameworks, creating premium advisory revenue streams.
- Small Membership Organization Penetration:Low-code deployment models address IT staff limitations in volunteer-run trade groups and regional chapters.
- Event-Finance Integration:Converging event orchestration and financial processing workflows into unified platforms eliminates point-solution fragmentation.
Industry Challenges
- Embedded Database Migration:Extracting historical member records from proprietary formats without data loss demands specialized engineering talent scarce outside major metropolitan tech clusters.
- Certification Timeline Compression:ISO 27001 and SOC 2 Type II audits for cloud infrastructure require 12-18 month cycles that delay market entry for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Association Management Software Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premises, Hybrid, Mobile End User: Professional Associations, Trade Associations, Non-Profits, Membership Organizations Feature: Event Management, Member Engagement, Fundraising Tools, Communication Portal Deployment: Public Cloud, Private Cloud, SaaS, Licensed Software |
| Companies Covered | Fonteva, Protech, Wild Apricot, Nimble AMS, iMIS, MemberClicks, MemberLeap, NetForum, GrowthZone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Association Management Software Market Emerging Trajectories
Native Salesforce and Microsoft Dynamics architectures are consolidating competitive positioning around enterprise-scale deployments, while predictive analytics and automated engagement tracking compress traditional renewal cycles.
Composable microservices architecture is rendering obsolete monolithic association management suites that bundled CRM, events, and finance into inseparable codebases. Mid-market trade associations now adopt best-of-breed components integrated through standardized APIs, compressing implementation timelines from years to quarters. This modularity is rendering obsolete the multi-year customization projects that previously dominated professional association procurement.
The EU AI Act introduces mandatory risk classification for automated decision systems processing member data, forcing vendors to document algorithmic transparency and human oversight protocols. European national regulators coordinate enforcement through the European Artificial Intelligence Board, creating uniform compliance thresholds across member states. Vendors serving predictive churn and engagement scoring segments must now maintain technical documentation and conformity assessments previously absent from SaaS development cycles.
Subscription-based pricing models displace perpetual licensing arrangements that dominated association software procurement for two decades. Finance committees in professional associations now prioritize operational expenditure predictability over capital asset ownership, favoring vendors with transparent usage-based tiers. This preference shift is most visible in United States healthcare and legal professional associations, where constrained annual budgets align with recurring revenue structures.
Association Management Software Market Segmentation
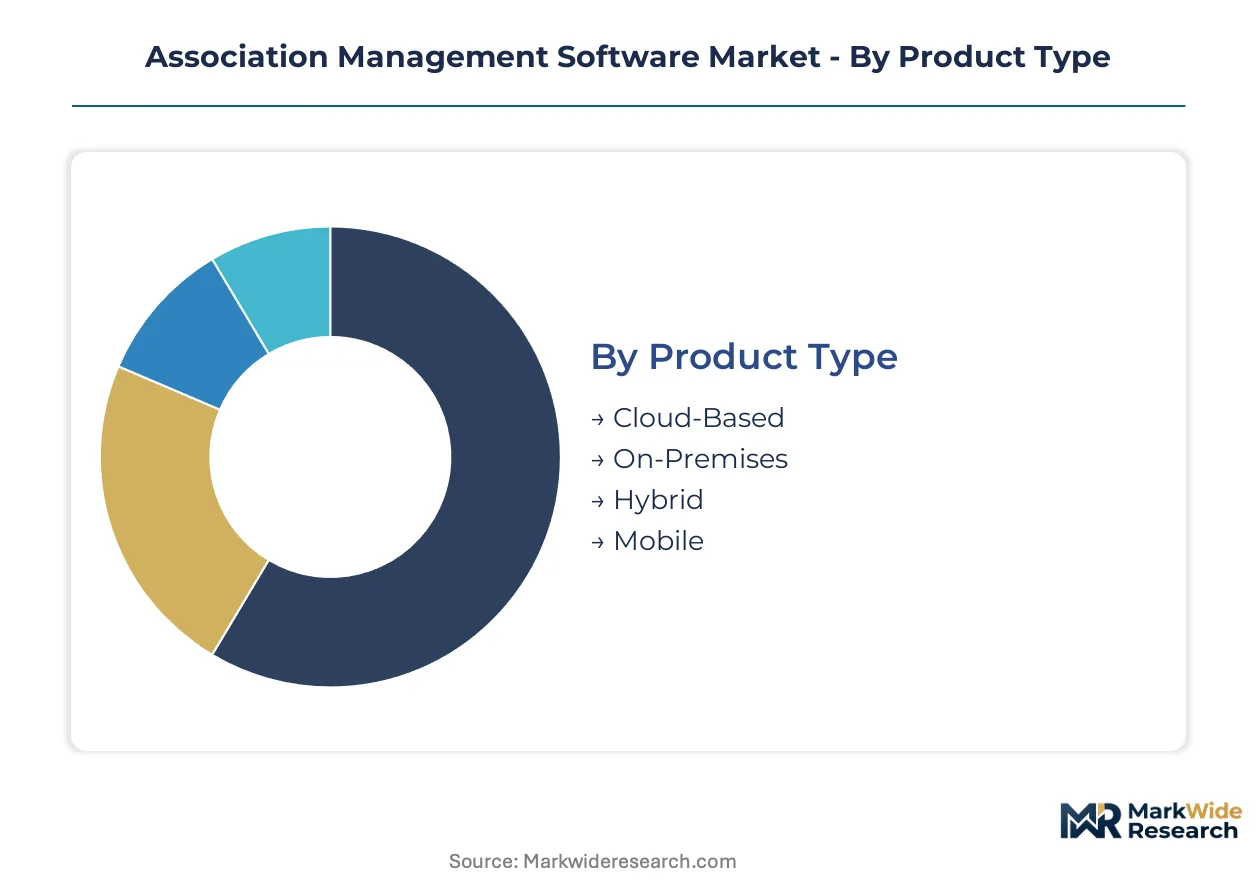
Association management software segments reflect divergent IT maturity levels across member-based organizations. Deployment preferences split between capital-constrained non-profits favoring operational expenditure models and regulated industries requiring data sovereignty controls.
Product Type:
Use-case spectrum spans volunteer-run regional chapters with no technical staff to enterprise professional associations with dedicated engineering teams.
- Cloud-Based:Multi-tenant architectures deliver constituent relationship management, event orchestration, and financial processing through browser-based interfaces. Professional associations in the United States with constrained capital budgets concentrate demand here, driven by finance committee preference for predictable operational expenditure over asset ownership.
- On-Premises:Licensed software installed on organization-controlled servers maintains data residency for stringent regulatory environments. German and French trade associations sustain this segment through national data localization mandates that prohibit cross-border member record storage.
- Hybrid:Split deployments keep sensitive member financial data on-premises while routing engagement tools through cloud infrastructure. Mid-market membership organizations adopt this configuration to balance GDPR compliance with marketing automation capabilities.
- Mobile:Native iOS and Android applications extend member portal access to field-based volunteer leadership. Regional chapters with distributed geographic coverage drive adoption for real-time event check-in and dues payment.
Established volume favors cloud-based deployment; emerging adoption favors hybrid configurations bridging compliance and functionality requirements.
End User:
Customer-type concentration determines feature prioritization, with dues-collection automation dominating some segments and donor stewardship tools commanding others.
- Professional Associations:Medical, legal, and engineering societies require continuing education tracking integrated with certification workflows. These organizations in the United States command the largest installed base of legacy systems requiring modernization, creating sustained replacement demand.
- Trade Associations:Industry groups prioritize government relations tracking and committee management for policy advocacy. GDPR enforcement by European national regulators shapes procurement decisions, forcing granular consent management for lobbyist contact databases.
- Non-Profits:Charitable organizations emphasize donor management and grant reporting over member-centric features. Volunteer-run operations with zero IT staff favor low-code deployment models that eliminate implementation complexity.
- Membership Organizations:Alumni associations and recreational clubs balance social networking tools with traditional dues administration. Constrained annual budgets align these buyers with subscription-based pricing tiers.
Professional associations anchor current revenue concentration; non-profits represent the steepest expansion trajectory as low-code tools democratize access.
Feature:
Application maturity varies sharply, with some capabilities reaching commodity status while predictive analytics commands premium pricing.
- Event Management:Comprehensive registration, venue logistics, and attendee tracking modules now serve as table stakes. Trade associations recovering from pandemic-era virtual pivots concentrate demand here, requiring hybrid event support for simultaneous in-person and streaming audiences.
- Member Engagement:Personalized communication portals with behavioral tracking and automated nurture campaigns represent the capability cluster gaining share fastest. Professional associations prioritize these tools over traditional broadcast email to improve retention metrics.
- Fundraising Tools:Recurring donation processing, campaign thermometers, and major donor pipelines address non-profit revenue diversification. PCI-DSS compliance requirements create vendor consolidation pressure around established payment processors.
- Communication Portal:Discussion forums, document libraries, and directory search functionality sustain member community interaction. Regional chapters with aging volunteer leadership favor simplified interfaces that reduce training burden.
Communication portals represent mature installed base; member engagement capabilities command fastest-growing implementation timelines.
Deployment:
Supply concentration clusters around hyperscaler infrastructure, with vendor differentiation shifting to data governance layers rather than raw compute.
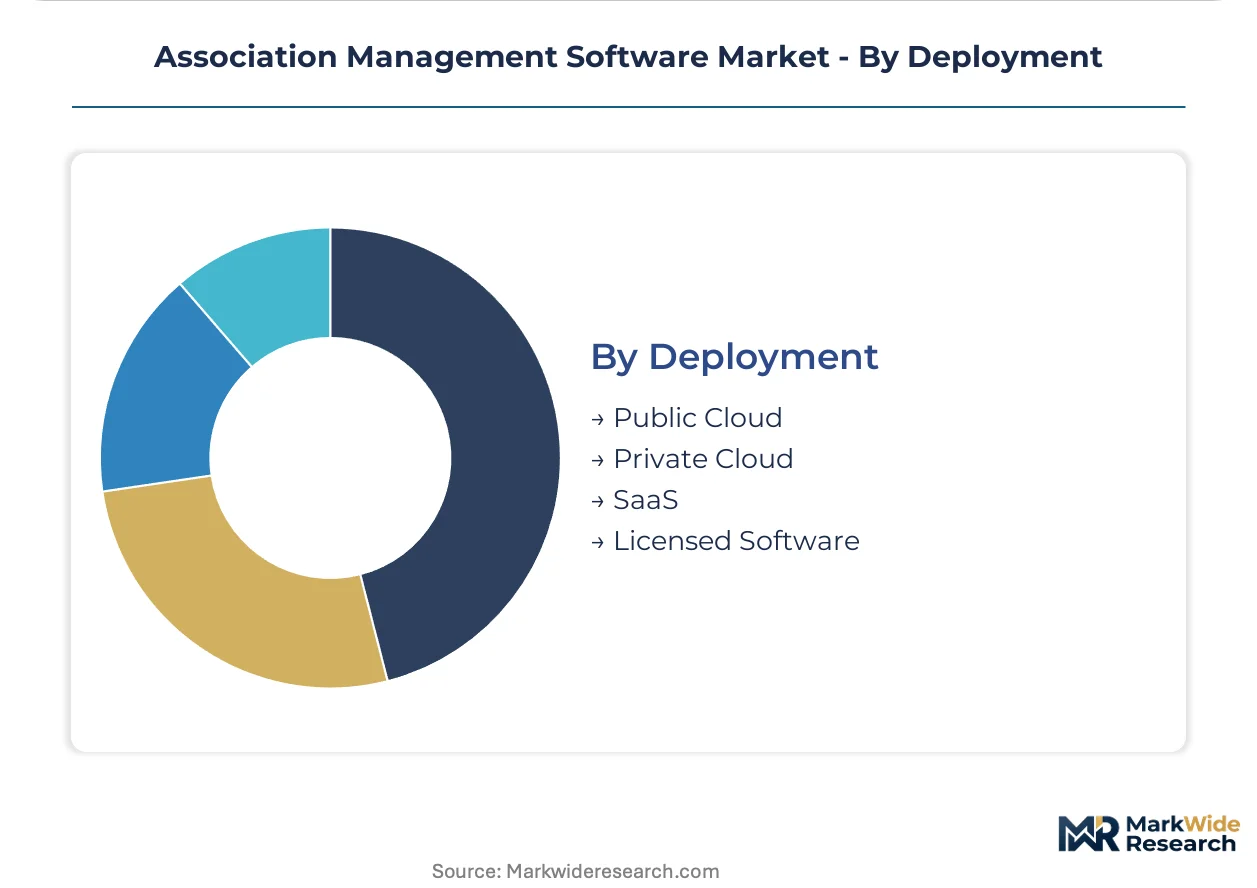
- Public Cloud:Shared infrastructure from Amazon Web Services, Microsoft Azure, and Google Cloud Platform delivers elastic scaling for seasonal membership renewal peaks. United States-based professional associations dominate consumption, benefiting from domestic data center density.
- Private Cloud:Dedicated single-tenant environments isolate member records for organizations with stringent security requirements. German healthcare professional associations mandate this deployment mode under national data protection authority guidance.
- SaaS:Subscription delivery with automatic feature updates eliminates version fragmentation and security patching responsibility. Finance committees across all end-user categories now mandate this procurement model.
- Licensed Software:Perpetual ownership with annual maintenance contracts persists in organizations with capital budget cycles and internal IT operations. Margin-rich niche sustains despite shrinking addressable market.
SaaS delivery captures emerging procurement preference; licensed software retains entrenched positions in regulated European jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor engineering talent clusters in metropolitan tech hubs across the United States, Germany, and United Kingdom, with regulatory compliance costs diverging sharply between GDPR-governed European jurisdictions and the fragmented US state-level privacy landscape.
United States
Professional associations in healthcare and legal sectors drive replacement demand for legacy on-premises systems. State-level privacy fragmentation through CCPA and Virginia CDPA creates patchwork compliance obligations for SaaS providers. Finance committees in Chicago and New York-based medical societies prioritize operational expenditure predictability over capital asset ownership.
Germany
Trade associations mandate data residency controls under national data protection authority guidance. GDPR enforcement by CNIL-coordinated regulators shapes procurement decisions for cross-border member record management. Bavarian healthcare professional associations sustain private cloud deployment demand through stringent localization requirements.
United Kingdom
Post-Brexit regulatory divergence complicates data transfer protocols for associations with EU member operations. The Information Commissioner's Office maintains GDPR-aligned enforcement thresholds with sector-specific guidance for membership organizations. London-based professional bodies anchor enterprise-scale SaaS adoption for continuing education tracking.
France
ANSM and CNIL coordinate oversight of automated member scoring systems under emerging AI governance frameworks. Trade associations prioritize granular consent management for lobbyist contact databases. Parisian industry groups concentrate demand for hybrid deployments balancing compliance with marketing automation capabilities.
Canada
Health Canada guidance influences data governance standards for medical professional associations. PIPEDA and provincial privacy statutes create layered compliance obligations for SaaS vendors. Toronto-based engineering societies exemplify mid-market migration toward API-first cloud architectures.
Association Management Software Market Vendor Landscape
Platform-native specialists and independent software vendors split the market into distinct competitive spheres. Enterprise-scale deployments concentrate around hyperscaler-integrated architectures, while volunteer-run organizations sustain demand for low-code alternatives. Three archetypes dominate: Salesforce-native platforms, Microsoft Dynamics-anchored solutions, and standalone SaaS specialists. Competitive moves center on API ecosystem expansion and vertical feature specialization for regulated professional sectors.
Within the hyperscaler-native tier, Fonteva and Protech exemplify divergent platform strategies, while Wild Apricot occupies a position serving capital-constrained membership organizations. These three companies represent the archetype spectrum from enterprise-scale system integration to accessible deployment models, anchoring competitive dynamics without direct feature overlap.
| Leading Market Players |
|---|
| Fonteva |
| Protech |
| Wild Apricot |
| Nimble AMS |
| iMIS |
| MemberClicks |
| MemberLeap |
| NetForum |
| GrowthZone |
| Others |
Supply Flow & Price Mechanics
Transatlantic data center fiber routes between Frankfurt and Northern Virginia transmit the compliance documentation and API traffic that underpin SaaS delivery economics, with bandwidth cost fluctuations cascading through hyperscaler pricing tiers and forcing differentiation between GDPR-certified private cloud deployments and standard multi-tenant subscriptions.
Pricing Analysis
GDPR and the EU AI Act dictate the pricing tier structure across the association management software landscape. Three-tier pricing structure across enterprise compliance, professional standard, and volunteer economy levels segments buyers by data governance complexity and automation depth. Price differentiation centers on ISO 27001 certification status and SOC 2 Type II audit completion, with German healthcare associations paying premiums for private cloud isolation. Cost compression in the mid-market tier is intensifying because Microsoft Dynamics and Salesforce native platforms commoditize integration capabilities. Volunteer-run regional chapters exhibit highest price sensitivity, while legal professional societies in New York and Chicago show lowest sensitivity due to constrained IT staffing.
Supply Chain Analysis
Tariff exposure between China and the United States dominates hardware procurement risk for on-premises deployment components. Engineering talent clusters in the United States, Germany, and the United Kingdom, with vendor R&D concentrated in San Francisco, London, and Berlin metropolitan tech corridors. Cloud infrastructure draws from Amazon Web Services, Microsoft Azure, and Google Cloud Platform data center networks spanning Dublin, Frankfurt, and Amsterdam. Single-source vulnerability rests on hyperscaler concentration for elastic compute during seasonal membership renewal peaks. Distribution runs through direct enterprise sales teams for professional associations and self-service digital channels for small membership organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Association management software sits in early-cycle expansion as low-code deployment models unlock penetration among volunteer-run trade groups previously excluded by implementation complexity. Cloud migration mandates across European jurisdictions accelerate replacement timelines for legacy on-premises systems.
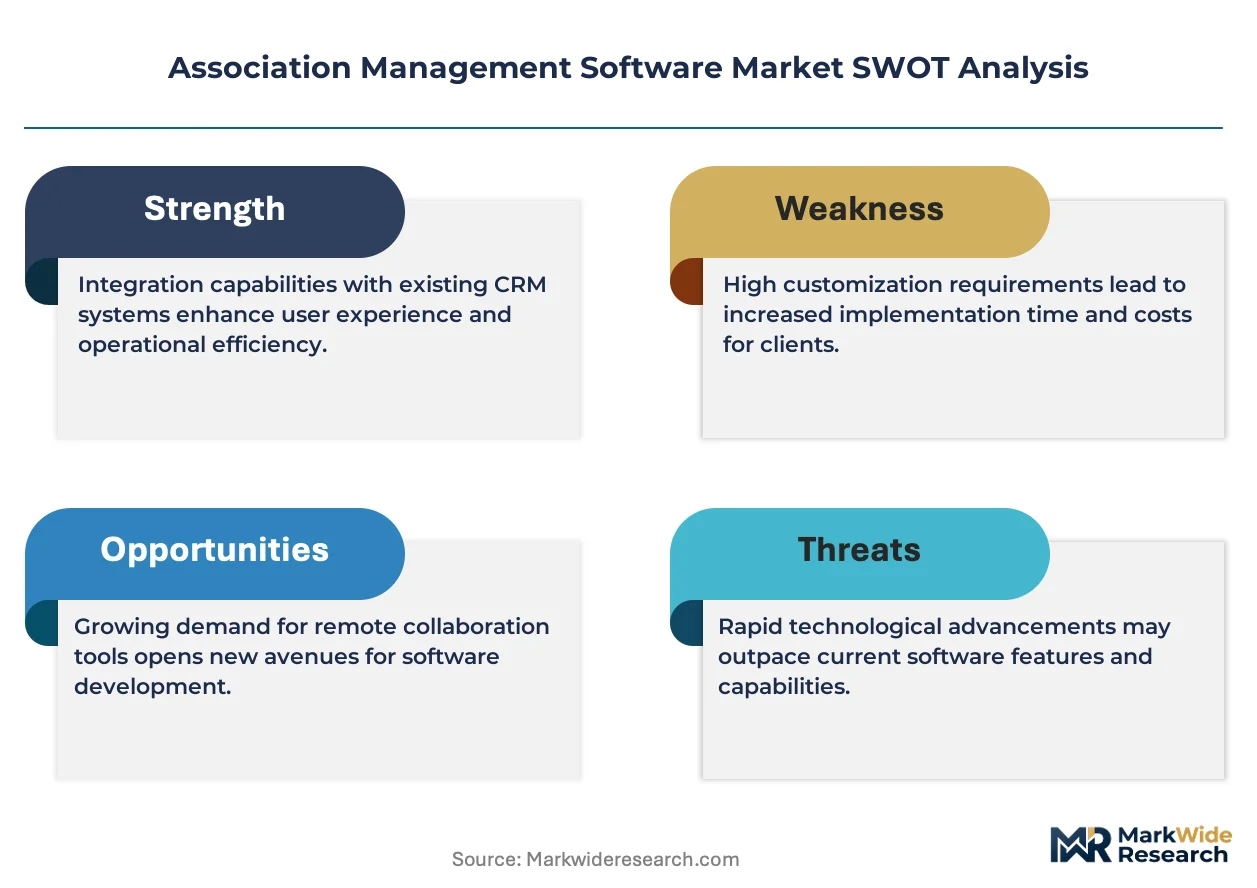
For Market Incumbents: Pre-empt composable architecture disruption by acquiring API-first specialist vendors before mid-market trade associations fragment their procurement across best-of-breed components. Fortify Salesforce and Microsoft Dynamics native positions through deeper vertical integration into continuing education certification workflows. Defend against low-code entrants by embedding implementation services into subscription tiers.
For New Entrants and Emerging Players: Build out hybrid deployment expertise targeting French and German trade associations navigating GDPR cross-border data transfer requirements. White-space concentration sits in regional chapters with zero IT staff and sub-five-hundred-member bases. Pursue channel partnerships with accounting firms serving non-profit finance committees as primary go-to-market mechanism.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-native specialists with established hyperscaler integrations over standalone SaaS vendors facing R&D fragmentation. Five-to-ten-year viability hinges on AI governance compliance capabilities as the EU AI Act enforcement matures. Target acquisition archetype: ISO 27001-certified vendors with private cloud deployment track records. Signal to monitor: European national regulator coordination through the European Artificial Intelligence Board as inflection indicator for compliance service premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce and Microsoft Dynamics architectures reduce implementation timelines from years to quarters for enterprise professional associations. |
| Compliance Service Development | EU AI Act documentation and conformity assessment capabilities unlock premium advisory revenue from predictive churn algorithm deployments. |
| Low-Code Deployment Expansion | Self-service configuration tools address IT staff limitations in volunteer-run regional chapters and trade groups. |
| Hybrid Cloud Infrastructure Investment | Split deployments balance GDPR data residency requirements with marketing automation functionality for mid-market membership organizations. |
| API Ecosystem Partnership | Standardized third-party connectivity eliminates point-solution fragmentation in event orchestration and financial processing workflows. |
Methodological Framework
A spread of perspectives from association CIOs, non-profit finance directors, hyperscaler partnership leads, and regulatory compliance officers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings of publicly traded parent companies, GDPR enforcement actions documented by European national regulators, and hyperscaler capex disclosures revealing infrastructure expansion patterns. Bottom-up sizing of member organization counts and dues structures triangulated against top-down SaaS revenue estimates from cloud ecosystem marketplaces.
Demand-supply balance across the analysis window anchored the quantitative framework, with segmentation modeled across deployment mode, organization size tier, vertical regulatory intensity, and regional adoption pattern. CAGRs were derived from cohort-based renewal rate analysis and replacement demand curves for legacy on-premises installations. Forecast inputs included GDPR fine trajectory data and EU AI Act implementation timelines from coordinated regulator guidance.
Stress conditions across hyperscaler pricing volatility, European regulatory enforcement intensity, and US state-level privacy fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about cloud migration velocity and AI governance compliance cost pass-through. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
3PL Software Market
Software & Services
Global Catalog Management Software Market
Software & Services
Machine Translation Software Market
Software & Services
Urban Planning Software and Services Market
Software & Services
Classified Platform Market
Software & Services
Supplier Relationship Management Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Dropshipping Software Solutions Market
Software & Services
PLM Software Market
Software & Services
Creative Software Market
Software & Services
Plant Design Software Market
Software & Services
Integration Brokerage Software Market
Software & Services
Predictive Dialer Software Market
Software & Services
Grant Management Software Market
Software & Services
UK Applicant Tracking System Market