
 ITSM Market | 2026-2036
ITSM Market Size, Share, and Industry Trends Forecast 2026-2036
ITSM Market Analysis
India's software services corridor is fragmenting as domestic ITSM development accelerates alongside cloud infrastructure build-outs. ServiceNow dominates the enterprise workflow layer with extensive IT operations management integration. Freshworks competes aggressively in the mid-market segment through localized pricing and regional data residency options. Atlassian extends its developer-centric platform into service management through Jira Service Management, leveraging existing user bases.
IT service management encompasses the policies, processes, and software platforms that organizations use to design, deliver, manage, and improve IT services to internal and external customers, typically structured around ITIL frameworks with service level agreements defining performance thresholds. Its primary purpose is ensuring alignment between IT capabilities and business objectives while minimizing service disruption. Cloud deployment models now lead adoption as enterprises prioritize scalability and remote accessibility over capital-intensive on-premises infrastructure. SaaS delivery within the deployment model segment captures the fastest expansion trajectory, particularly among small and mid-sized organizations seeking subscription-based consumption without dedicated infrastructure teams.
The EU AI Act, GDPR, and ISO/IEC 20000 standards collectively shape ITSM product requirements across European markets, mandating explainable automation logic and cross-border data governance capabilities that vendors must embed natively. In the United States, HIPAA and SEC cybersecurity disclosure rules extend compliance burdens to healthcare and publicly traded ITSM adopters respectively. Stakeholders must evaluate whether their platform architectures can accommodate emerging algorithmic accountability mandates without fragmenting operational workflows.
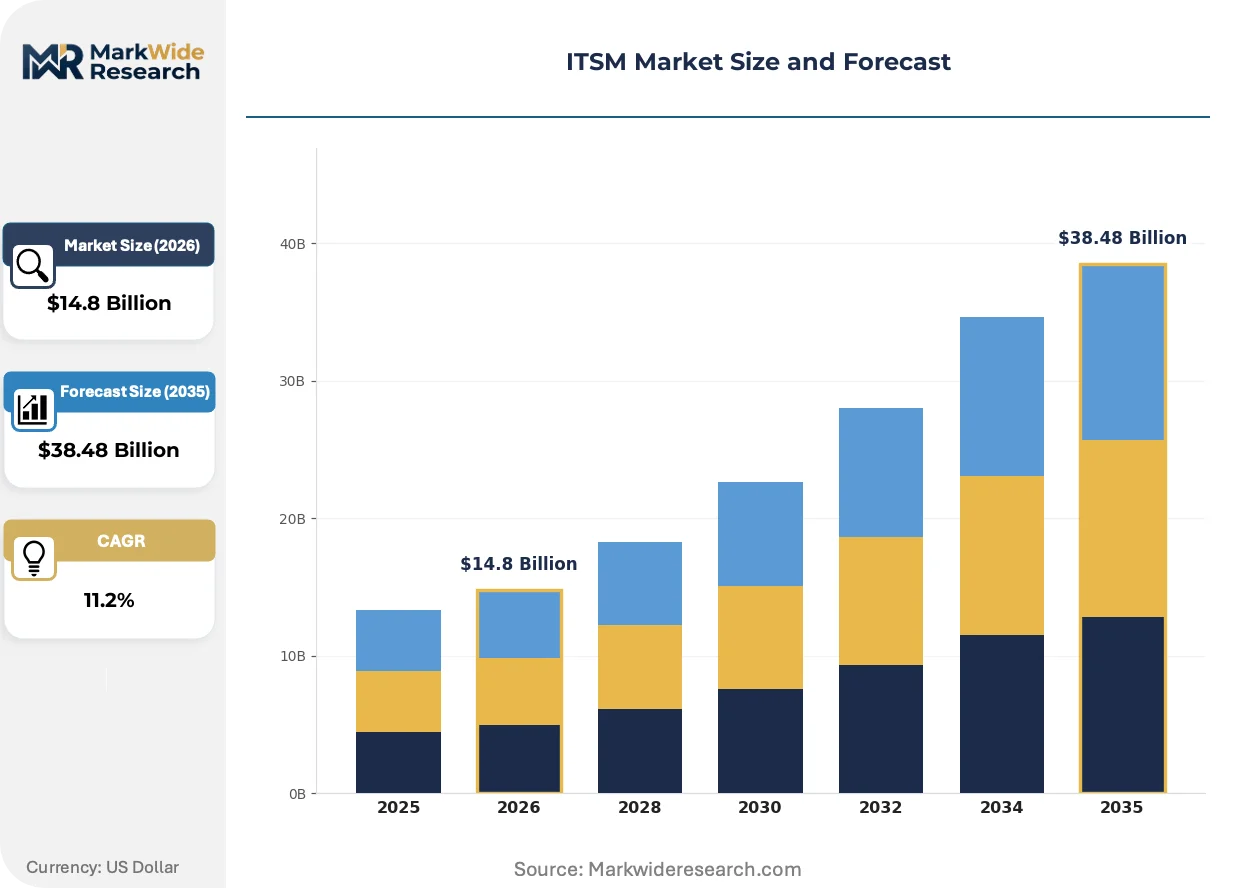
Market Dynamics
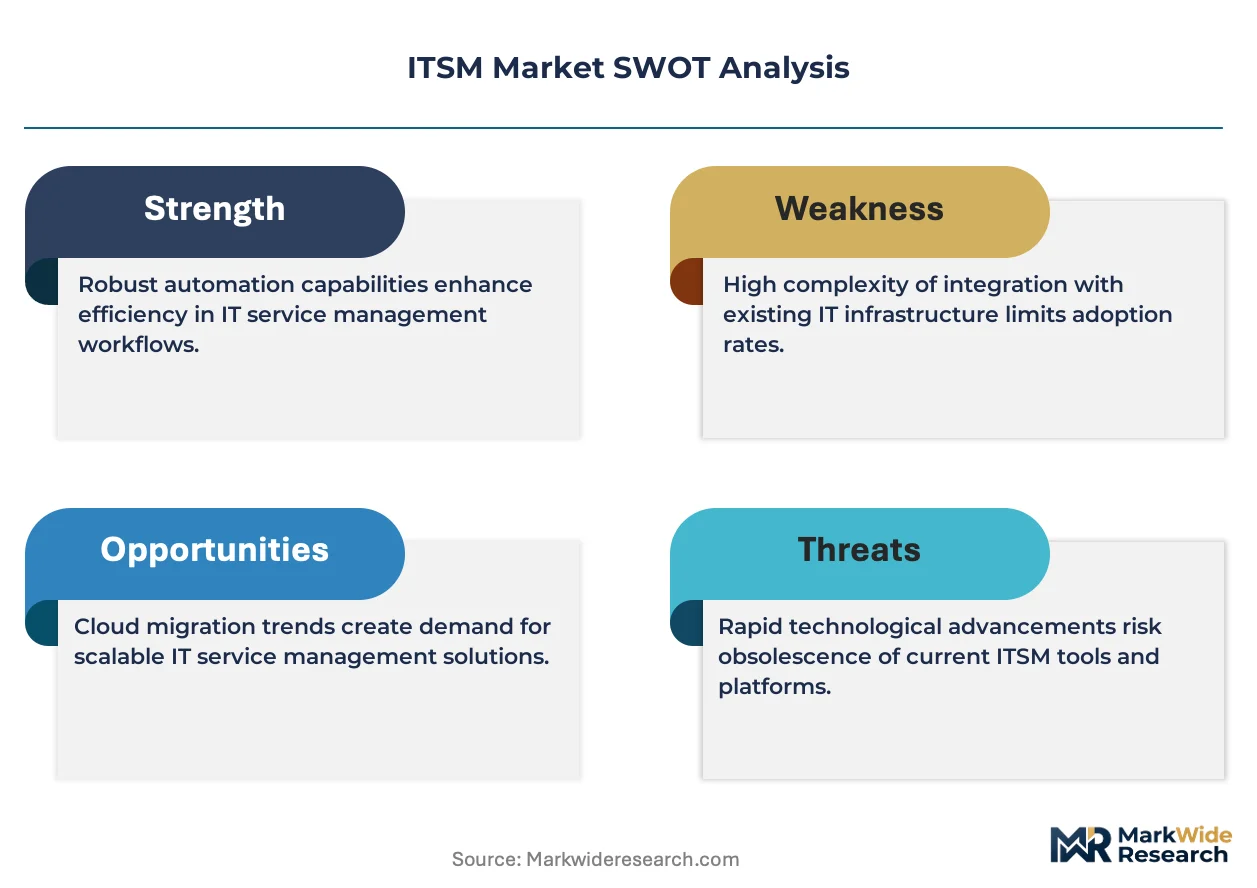
The ITSM market is experiencing structural compression as compliance mandates from the EU AI Act and GDPR force vendors to rebuild automation logic for auditable transparency, while hybrid cloud migration creates parallel demand for unified workflow orchestration across fragmented infrastructure estates.
Growth Catalysts
- EU AI Act:Mandatory explainability requirements for automated decision systems are compelling enterprises to replace opaque legacy tools with auditable ITSM platforms that embed compliance-by-design architectures.
- Financial services automation:Banks and insurers are deploying incident management platforms to reduce mean-time-to-resolution for critical system outages, driven by operational resilience mandates from national regulators.
- Cloud infrastructure build-outs:India's domestic data center expansion is accelerating localized ITSM adoption as enterprises seek SaaS alternatives to foreign-hosted platforms with data residency constraints.
Market Restraints
- Specialized talent scarcity:Shortages of ITIL-certified architects and platform engineers are inflating implementation costs and extending deployment timelines for complex workflow transformations.
- Input cost volatility:Cloud compute and storage pricing fluctuations are compressing margins for SaaS vendors operating multi-tenant architectures with fixed subscription rates.
- Legacy system entrenchment:Deep integration of on-premises ITSM tools with custom-built CMDBs and change management databases creates switching friction that delays platform consolidation.
Strategic Opportunities
- Germany's hybrid migration wave:Industrial manufacturers in Baden-Württemberg and Bavaria are seeking bridge solutions that synchronize on-premises service desks with cloud-native capabilities.
- Developer-centric convergence:Integration between ITSM platforms and CI/CD pipelines is opening new revenue streams as platform engineering teams demand unified visibility across infrastructure and application lifecycles.
- ISO/IEC 20000 certification tailwind:Service providers pursuing this international standard are driving demand for native compliance reporting and automated evidence collection capabilities.
Industry Challenges
- Multi-framework orchestration:Enterprises must simultaneously satisfy ITIL 4, DevOps, and SRE methodologies, forcing vendors to support conflicting workflow paradigms within single platforms.
- Cross-border data governance:Schrems II rulings and divergent national implementations of GDPR are complicating SaaS architectures that must route tickets and attachments across jurisdictions without violating transfer restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ITSM Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $38.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Incident Management, Change Management, Problem Management, Configuration Management Deployment Model: Cloud, On-Premises, Hybrid, SaaS End User: IT Departments, Managed Service Providers, Enterprises, Government Agencies Solution: Service Desk Software, Automation Tools, Reporting Solutions, Integration Platforms |
| Companies Covered | Ivanti, Freshworks, ServiceNow, Broadcom, ManageEngine (Zoho Corp.), Atlassian, Microsoft, GoTo, BMC Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ITSM Market Emerging Trajectories
Automation architectures are undergoing fundamental restructuring as rule-based engines give way to adaptive systems, while regulatory pressure and procurement evolution reshape how ITSM capabilities are sourced and deployed across enterprise technology estates.
Predictive analytics engines are migrating from standalone AIOps point solutions to embedded capabilities within core ITSM platforms. Mid-market enterprises in healthcare and retail are adopting these integrated modules faster than large financial institutions constrained by model risk management requirements. This consolidation is compressing the addressable market for specialized anomaly detection vendors while elevating platform stickiness for incumbent workflow providers.
The EU AI Act's risk classification framework is forcing vendors to redesign automation logic for high-risk use cases such as change approval and incident prioritization. Product teams must now document decision pathways and maintain human-in-the-loop checkpoints that were previously optional. German industrial enterprises and French public sector agencies are the most advanced in demanding these capabilities, creating a two-tier market between compliance-ready and legacy platforms.
Subscription consumption patterns are fragmenting as buyers resist long-term platform commitments. Procurement teams increasingly favor modular pricing that separates service desk, asset management, and workflow automation into independently scalable components. This unbundling is most pronounced among technology and professional services firms in the United States, where finance departments prioritize operational expenditure flexibility over total-cost-of-ownership calculations.
ITSM Market Segmentation
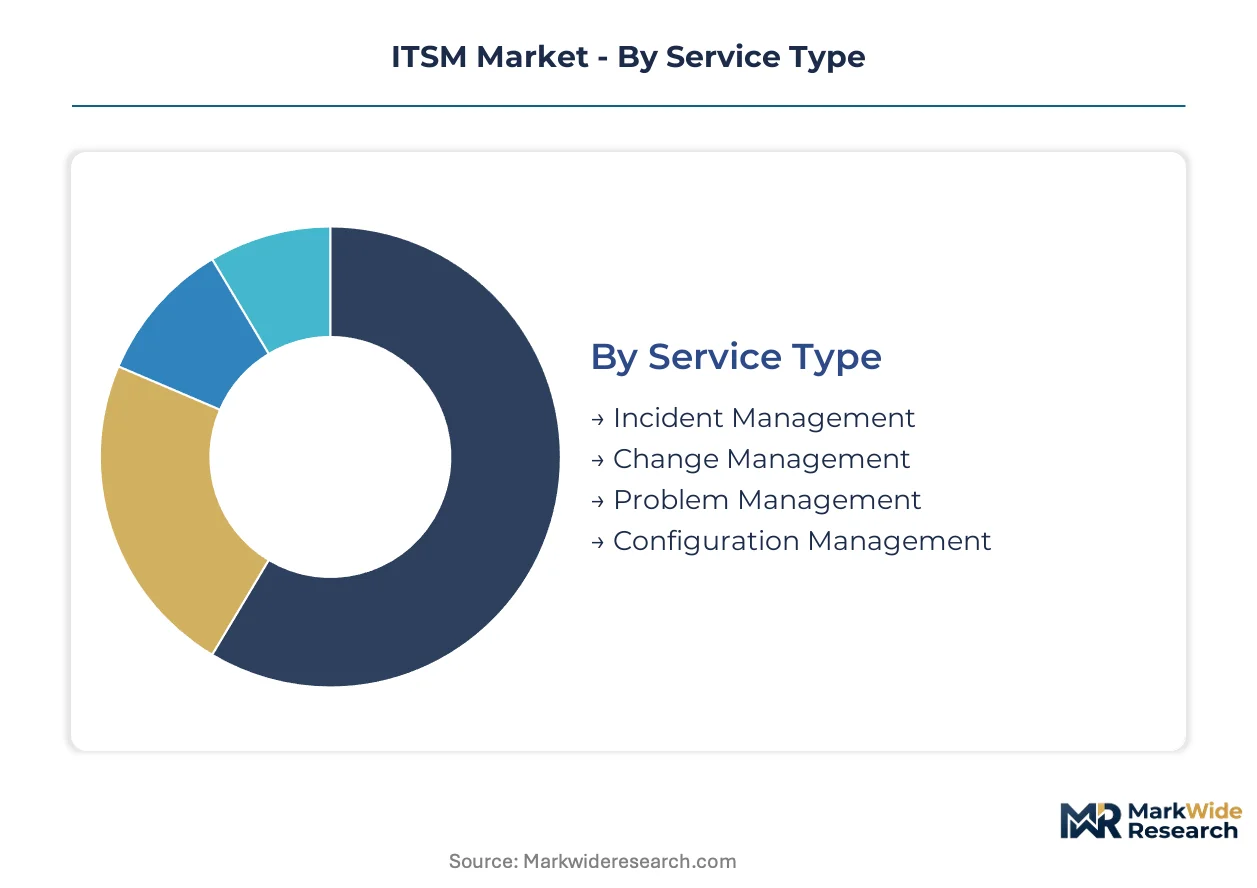
ITSM procurement patterns diverge sharply across service types and deployment architectures, with compliance mandates and infrastructure legacy dictating platform selection criteria. Vendors must architect modular offerings that align with distinct operational maturity levels and regulatory exposure profiles.
Service Type:
After-sales-service intensity varies dramatically across ITSM service categories, with incident response demanding 24/7 operational coverage while configuration management requires intermittent but highly specialized architectural intervention.
- Incident Management:Real-time ticket routing and escalation protocols form the operational core, with automated classification reducing manual triage overhead. Financial services firms in Frankfurt and Singapore are consolidating fragmented alert channels into unified response workflows driven by operational resilience mandates from BaFin and MAS. Service level agreements here carry the steepest penalty clauses, elevating platform reliability above feature breadth in vendor selection.
- Change Management:Structured approval gates and risk assessment matrices govern system modifications, with embedded audit trails satisfying EU AI Act explainability requirements for automated decision systems. German automotive manufacturers and French public sector agencies are demanding human-in-the-loop checkpoints that legacy rule-based engines cannot accommodate, forcing platform replacements.
- Problem Management:Root cause analysis capabilities integrate with knowledge bases to prevent recurrence patterns, with diagnostic depth determining value capture for ITIL-mature organizations.
- Configuration Management:CMDB accuracy underpins dependency mapping for impact analysis, with data federation challenges multiplying in hybrid infrastructure estates spanning on-premises and cloud-native assets.
Incident Management holds the largest share; momentum sits with Change Management as regulatory pressure intensifies.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises implementations from subscription-based consumption models, with hybrid architectures commanding premium pricing for synchronization complexity.
- Cloud:Multi-tenant architectures deliver scalability without infrastructure ownership, with AWS, Azure, and GCP hosting options enabling geographic distribution for latency-sensitive operations. India's domestic data center expansion is accelerating localized cloud ITSM adoption as enterprises seek alternatives to foreign-hosted platforms with data residency constraints under RBI guidelines.
- On-Premises:Dedicated infrastructure maintains full data sovereignty and customization latitude, with air-gapped deployments persisting in defense and classified government environments where external connectivity is prohibited.
- Hybrid:Synchronized on-premises and cloud-native capabilities bridge migration phases, with workload portability becoming critical for industrial manufacturers in Baden-Württemberg modernizing legacy service desks without operational disruption.
- SaaS:Subscription delivery eliminates infrastructure teams entirely, with modular pricing separating service desk, asset management, and workflow automation into independently scalable components that finance departments prioritize for operational expenditure flexibility.
Cloud captures the dominant position; SaaS is climbing the fastest as mid-market procurement patterns shift toward consumption-based models.
End User:
Customer type determines feature prioritization, with managed service providers demanding multi-tenant efficiency while government agencies mandate certified compliance architectures.
- IT Departments:Internal technology organizations balance standardization against shadow IT proliferation, with enterprise service management extending beyond traditional boundaries into HR and facilities workflows.
- Managed Service Providers:Multi-client orchestration requires tenant isolation and consolidated billing engines, with margin compression driving automation investment to maintain profitability at scale.
- Enterprises:Complex organizational matrices demand role-based access controls and federated identity integration, with platform consolidation initiatives reducing vendor sprawl across acquired subsidiaries.
- Government Agencies:Public sector procurement imposes stringent certification requirements, with FedRAMP in the United States and ISO/IEC 20000 internationally forming mandatory gating criteria for vendor eligibility.
Enterprises command the greatest volume; Managed Service Providers are gaining share fastest as outsourcing accelerates.
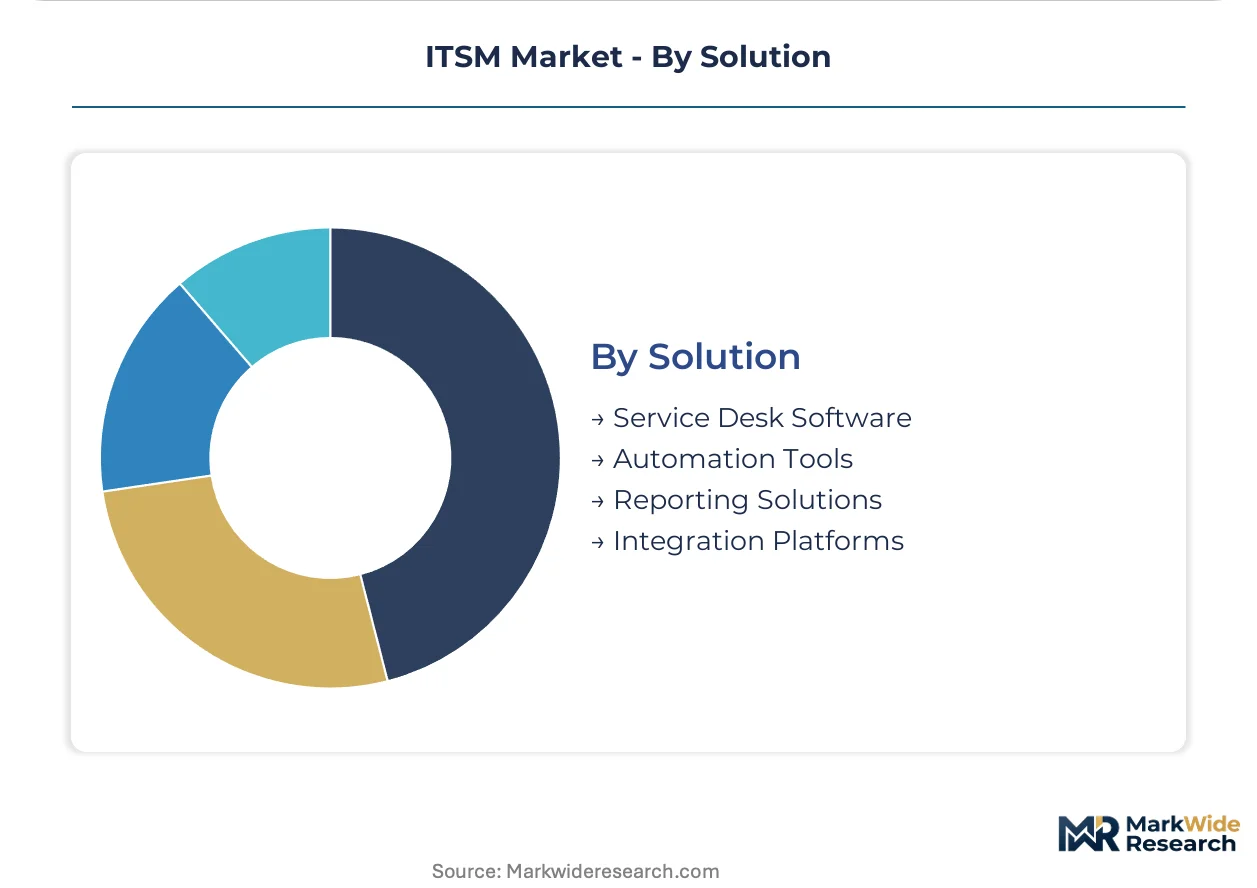
Solution:
Application maturity separates established service desk functionality from emerging automation layers, with integration depth becoming the primary competitive differentiator.
- Service Desk Software:Ticket intake, routing, and resolution tracking constitute foundational capability, with omnichannel support spanning email, chat, voice, and self-service portals now table stakes for competitive positioning.
- Automation Tools:Robotic process automation and AI-driven classification reduce manual intervention, with predictive analytics engines migrating from standalone AIOps point solutions into embedded platform capabilities.
- Reporting Solutions:Compliance dashboards and operational metrics satisfy governance requirements, with real-time visualization replacing static periodic reviews for agile management cadences.
- Integration Platforms:API ecosystems and pre-built connectors unify disparate tools, with CI/CD pipeline integration opening new revenue streams as platform engineering teams demand visibility across infrastructure and application lifecycles.
Service Desk Software retains the largest footprint; Integration Platforms are expanding most quickly as architectural fragmentation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ITSM platform development clusters in the United States, Germany, and India, with each geography shaping distinct deployment preferences and compliance architectures. Vendor R&D investment concentrates where enterprise density and regulatory complexity intersect.
United States
Financial services firms in New York and San Francisco are consolidating fragmented alert channels into unified response workflows. SEC cybersecurity disclosure rules and HIPAA extend compliance burdens to publicly traded and healthcare ITSM adopters. The Northeast corridor hosts the densest concentration of enterprise platform engineering teams demanding CI/CD pipeline integration.
Germany
Industrial manufacturers in Baden-Württemberg and Bavaria are synchronizing on-premises service desks with cloud-native capabilities. The EU AI Act and GDPR mandate explainable automation logic and cross-border data governance that vendors must embed natively. Frankfurt's financial services cluster drives demand for operational resilience tooling under BaFin supervision.
India
Domestic data center expansion in Maharashtra and Karnataka is accelerating localized ITSM adoption. RBI guidelines on data residency push enterprises toward SaaS alternatives to foreign-hosted platforms. Bangalore's technology corridor fragments software services as domestic ITSM development accelerates alongside cloud infrastructure build-outs.
United Kingdom
Enterprise service management extensions into HR and facilities workflows are gaining traction in London and the Southeast. ISO/IEC 20000 certification requirements shape procurement criteria for service providers. The Midlands manufacturing belt is modernizing legacy service desks with hybrid deployment models.
Japan
Platform engineering teams in Tokyo and Osaka are demanding unified visibility across infrastructure and application lifecycles. METI industrial policy encourages operational technology integration with IT service management. The Nagoya automotive cluster is adopting predictive analytics modules for supply chain incident response.
ITSM Market Vendor Landscape
Enterprise workflow platforms and developer-centric toolchains split the market into competing gravitational centers. The vendor base organizes around three strategic archetypes: integrated suite providers, specialized service desk vendors, and platform engineering-native solutions. Consolidation pressure intensifies as buyers resist long-term commitments and favor modular consumption. M&A activity targets API ecosystem capabilities, while organic investment flows toward predictive analytics embedding.
Within the integrated suite tier, ServiceNow and Microsoft exemplify platform consolidation strategies that extend beyond traditional IT boundaries. Freshworks occupies a position in the mid-market segment through regional data residency options. Atlassian anchors the developer-centric convergence vector, leveraging existing user bases to extend into service management workflows.
| Leading Market Players |
|---|
| Ivanti |
| Freshworks |
| ServiceNow |
| Broadcom |
| ManageEngine (Zoho Corp.) |
| Atlassian |
| Microsoft |
| GoTo |
| BMC Software |
| Others |
Supply Flow & Price Mechanics
Frankfurt-to-Mumbai cloud infrastructure corridors carry escalating data transfer and compute provisioning costs that compress margins for SaaS vendors while amplifying price differentiation between compliance-ready platforms and legacy alternatives. Supply concentration among hyperscale providers in these nodes directly shapes downstream procurement flexibility for enterprise buyers.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across ITSM platforms, separating vendors into premium compliance-ready tiers with embedded explainability architectures from standard tiers lacking automated audit trails. Price differentiation hinges on certification grade—ISO/IEC 20000 and FedRAMP authorization command substantial premiums—and geographic delivery cost, with on-premises-to-hybrid synchronization in Germany attracting the steepest service premiums. Cost compression in mid-market SaaS tiers is intensifying because cloud compute pricing volatility strains fixed-rate subscription models. Managed service providers exhibit the highest price sensitivity due to margin compression across multi-tenant operations, while government agencies demonstrate the least sensitivity given mandatory certification requirements.
Supply Chain Analysis
Upstream cloud infrastructure feeds from concentrated hyperscale capacity in the United States, Germany, and India, with AWS, Azure, and GCP data center expansion determining regional platform availability. Software development draws from specialized engineering talent pools in Bangalore, Berlin, and the US Northeast Corridor, while compliance consulting and implementation services rest on ITIL-certified architect networks concentrated in London and Singapore. Single-source vulnerability in hyperscale compute provisioning creates exposure for SaaS vendors locked into specific cloud ecosystems. Distribution runs through direct enterprise sales teams and channel partners serving mid-market segments, with managed service providers acting as consolidated procurement intermediaries for fragmented end-user bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as enterprise procurement teams consolidate vendor relationships and resist long-term platform commitments, fragmenting ITSM spending across modular, independently scalable components rather than integrated suites.
For Market Incumbents: Harden platform stickiness through native predictive analytics embedding that displaces standalone AIOps point solutions, while deepening API ecosystem capabilities to capture CI/CD pipeline integration demand from platform engineering teams. Threat substitution from developer-centric toolchains extending into service management workflows demands defensive certification investment in ISO/IEC 20000 and FedRAMP to maintain government and regulated industry eligibility. Vertical integration into specialized compliance consulting services represents a critical lever for margin defense against modular unbundling pressures. For New Entrants and Emerging Players: Mid-market healthcare and retail organizations in India and Southeast Asia represent the most penetrable entry point, as these segments adopt integrated predictive analytics modules faster than constrained financial institutions and seek alternatives to foreign-hosted platforms with data residency limitations. German industrial manufacturers in Baden-Württemberg modernizing legacy service desks without operational disruption present a second white-space target for bridge hybrid solutions. A developer-native go-to-market angle leveraging existing DevOps toolchain relationships offers the cleanest path to service management workflow penetration. For Investors and Strategic Acquirers: The EU AI Act's full enforcement reshapes the acquisition landscape toward platforms with pre-built explainable automation logic and human-in-the-loop checkpoint architectures. Long-term viability over the next decade centers on compliance-ready infrastructure rather than feature breadth, positioning API ecosystem specialists and predictive analytics module developers as prime consolidation targets. The signal to watch is procurement pattern fragmentation toward modular consumption, which accelerates platform unbundling and elevates standalone automation and integration capabilities above monolithic suite valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fragmented alert channels for BaFin-supervised financial services firms in Frankfurt. |
| Acquisition of Specialist Firm | Captures API ecosystem capabilities demanded by platform engineering teams in US Northeast corridor. |
| Geographic Expansion | Establishes localized data center presence for RBI-compliant SaaS alternatives in Maharashtra. |
| Product Launch | Introduces embedded predictive analytics compressing standalone AIOps vendor addressable markets. |
| Strategic Partnership | Secures CI/CD pipeline visibility for developer-centric convergence into service management workflows. |
Methodological Framework
A standing panel of IT procurement officers, platform engineering leads, managed service provider operations directors, and compliance architects provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC cybersecurity disclosure filings, RBI data residency guidelines, EU AI Act implementation documents, and hyperscaler capex disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing from enterprise platform adoption surveys.
Scenario-bracketing framed the analytical approach across the projection horizon, with deployment model, organization size, vertical industry, and integration complexity serving as core segmentation dimensions. CAGRs derived from trend extrapolation of SaaS subscription growth patterns, cloud infrastructure build-out trajectories, and regulatory compliance investment cycles. Forecast inputs incorporated ITIL 4 adoption velocity, DevOps toolchain penetration rates, and operational resilience mandate implementation timelines.
Practitioners should monitor EU AI Act enforcement intensity, Schrems II ruling evolution, and hyperscale pricing volatility for early signals requiring forecast revision. Quarterly review of enterprise procurement pattern fragmentation, managed service provider margin compression indicators, and compliance certification backlog lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Ad Creation Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Testing As a Service (Taas) Market
Software & Services
Global Thermal Analysis Software Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
Global Policy Management Software Market
Software & Services
Cloud-Based ERP Software Market
Software & Services
Tenant Billing System Market
Software & Services
Global Building Information Modeling (BIM) Software Market
Software & Services
Radio Propagation Software Market
Software & Services
Logistics Services Software Market
Software & Services
Canada HR Payroll Software Market
Software & Services
Customer Advocacy Software Market
Software & Services
Intelligent Enterprise Data Capture Software Market
Software & Services
Global Student Information System Market
Software & Services
Family Law Software Market